
 Sweden Data Center Construction Market | 2026-2036
Sweden Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Data Center Construction Market Insights
Cloud service provider demand is pivoting Sweden's data center construction pipeline toward hyperscale campuses. Skanska Sverige AB leverages its domestic civil engineering scale to secure foundation and shell contracts across Stockholm's northern corridor. DPR Construction competes on modular delivery speed, while Bravida Holding AB specializes in mechanical and electrical installations that compress commissioning timelines.
Data center construction encompasses the design, engineering, and physical build-out of facilities housing compute, storage, and networking infrastructure, typically requiring power densities exceeding 50 kilowatts per rack and precision cooling systems to maintain operational thresholds. Modular data centers are gaining share among time-constrained deployers who need incremental capacity without full ground-up builds, while traditional data centers still dominate total value where custom redundancy tiers and wholesale leasing structures command premium construction budgets. Pre-fabricated components are displacing on-site concrete pours as developers compress schedules amid labor constraints.
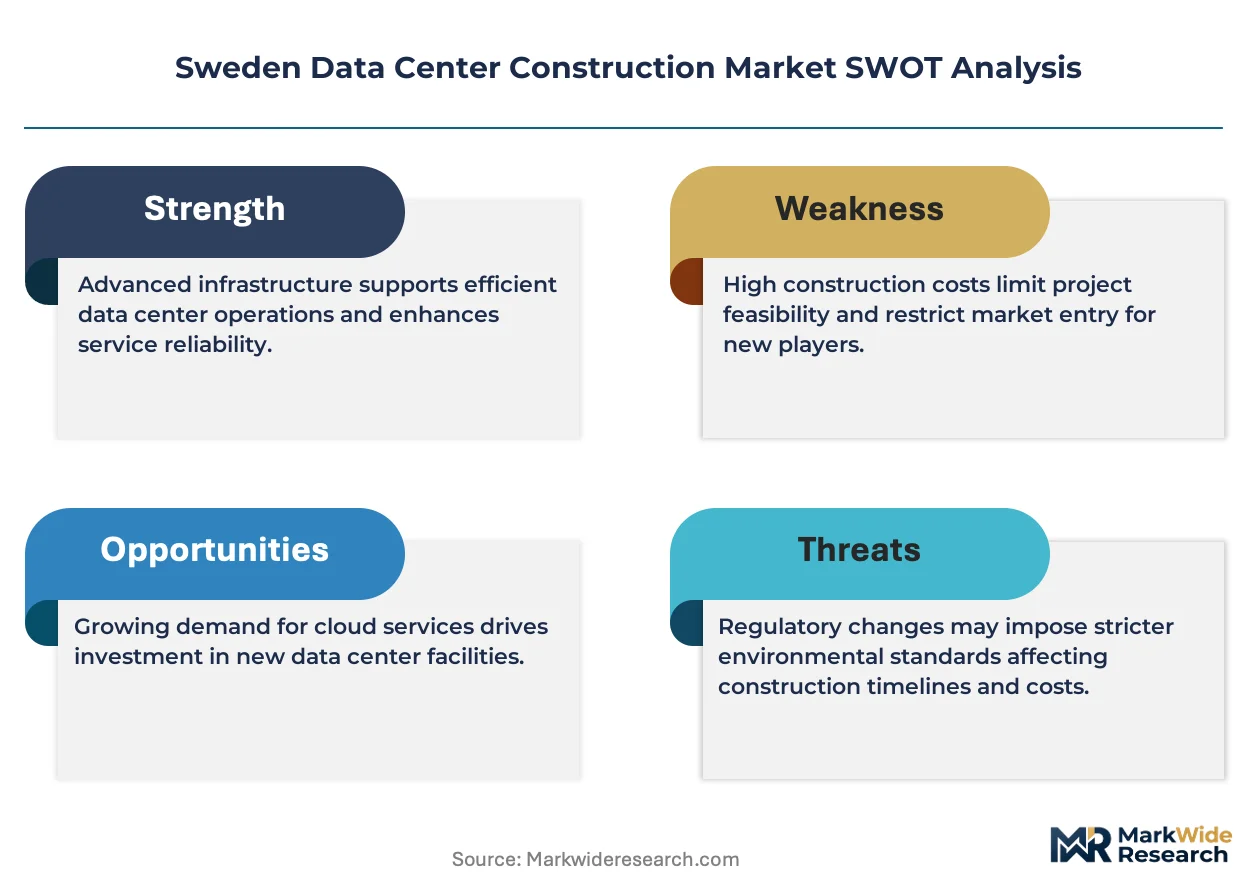
The Swedish Energy Agency administers tax structures that directly affect facility operating economics, while Boverket's building codes shape fire suppression and structural requirements for high-density electrical installations. The EU Green Deal's decarbonization benchmarks filter into procurement criteria, pushing developers toward renewable power supply configurations and heat recovery integration. Stakeholders must weigh location decisions against grid interconnection queues and municipal planning permissions that now scrutinize water usage for evaporative cooling systems.
Market Dynamics
Hyperscale cloud providers are compressing construction timelines across Sweden's Mälardalen corridor, forcing developers to modularize delivery methods and pre-fabricate electrical-mechanical assemblies off-site.
Growth Catalysts
- Swedish Energy Agency tax relief:Energy consumption exemptions under the national framework reduce operational expenditure burdens for facilities exceeding 0.5 megawatt installed capacity, redirecting capital toward expansion.
- Liquid cooling adoption:Direct-to-chip and immersion systems enable power densities above 100 kilowatts per rack, unlocking rack economics that air-cooled designs cannot sustain.
- Stockholm metropolitan cluster:Proximity to Norrtälje and Gävle grid interconnectors combines with Baltic Sea cooling water access to concentrate developer site selection.
Market Restraints
- Grid interconnection queues:Svenska Kraftnät processing delays for high-voltage substation upgrades extend commissioning timelines by 18-36 months in high-demand zones.
- Steel and copper input volatility:Busbar and structural steel pricing fluctuations compress fixed-price contract margins for general contractors.
- Evaporative cooling scrutiny:Boverket municipal planning permissions now mandate closed-loop water systems, eliminating once-standard open cooling tower designs.
Strategic Opportunities
- Norrbotten renewable surplus:Excess hydroelectric and wind generation capacity in Luleå and Piteå offers power purchase agreements below Stockholm pricing tiers.
- Heat recovery integration:District heating network interconnection allows facilities to monetize waste heat, converting thermal load into revenue streams under municipal utility contracts.
- Prefabricated electrical skids:Factory-integrated switchgear and UPS modules compress on-site mechanical completion from months to weeks.
Industry Challenges
- High-voltage technician scarcity:Specialized competence in 400 kilovolt substation commissioning commands premium wages and extends recruitment cycles.
- CE marking complexity for imported modules:Non-EU manufactured prefabricated data center components face extended conformity assessment timelines under EU construction product regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Data Center Construction Market |
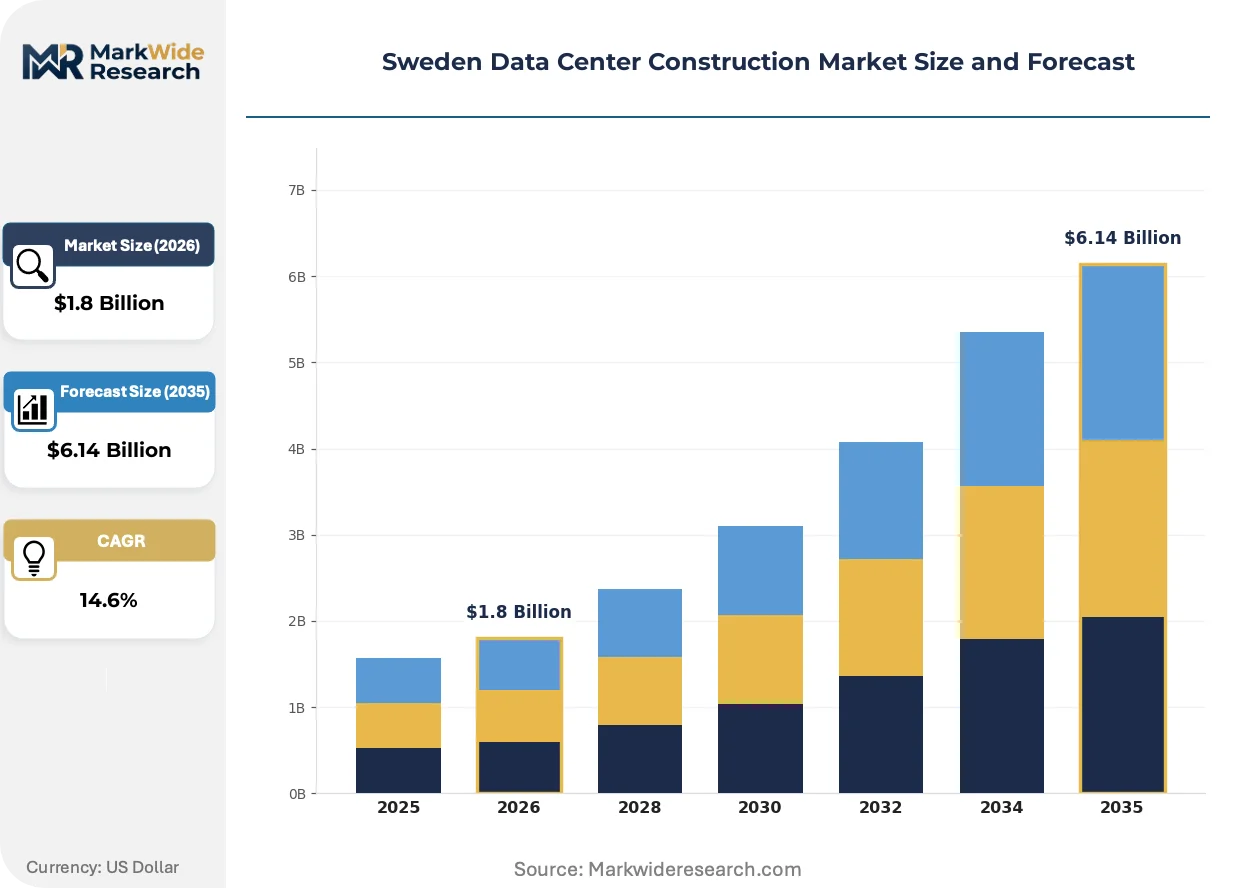
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Traditional Data Centers, Containerized Data Centers, Edge Data Centers Construction Material: Steel, Concrete, Glass, Pre-fabricated Components End User: Cloud Service Providers, Telecom Companies, Enterprises, Government Agencies Power Supply: Renewable Sources, Diesel Generators, Grid Power, Hybrid Systems |
| Companies Covered | DPR Construction, Collen Construction Limited, Skanska Sverige AB, Winthrop Technologies Ltd, Kirby Group Engineering, Bravida Holding AB, Coromatic AB, NCC, AECOM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Data Center Construction Market Trends and Innovations
Construction methodology is fragmenting across two parallel tracks: hyperscale campuses demanding bespoke redundancy tiers and edge deployers requiring rapid, repeatable modular units.
Prefabricated modular data centers are decentralizing site selection across Sweden's secondary markets. These factory-built units integrate power distribution, cooling, and fire suppression into transportable enclosures. Regional cloud providers and content delivery networks are deploying them in 12-16 week cycles. The technology is decentralizing construction activity away from Stockholm's saturated land corridor toward Västerås and Örebro where municipal permitting moves faster.
The EU Green Deal's decarbonization benchmarks are filtering into Swedish procurement criteria through the Swedish Energy Agency's reporting requirements. Developers must now document renewable power supply configurations and embodied carbon in structural materials. Hyperscale lease agreements increasingly mandate third-party verified sustainability metrics, pressuring general contractors to source low-carbon concrete and steel.
Buyers are consolidating procurement under design-build contracts that transfer performance risk to single-source contractors. Traditional bid-build arrangements are retreating as cloud operators seek guaranteed power usage effectiveness and construction cost ceilings. This consolidation is most visible among Stockholm-based financial services tenants who lack internal construction management capabilities.
Sweden Data Center Construction Market Segmentation
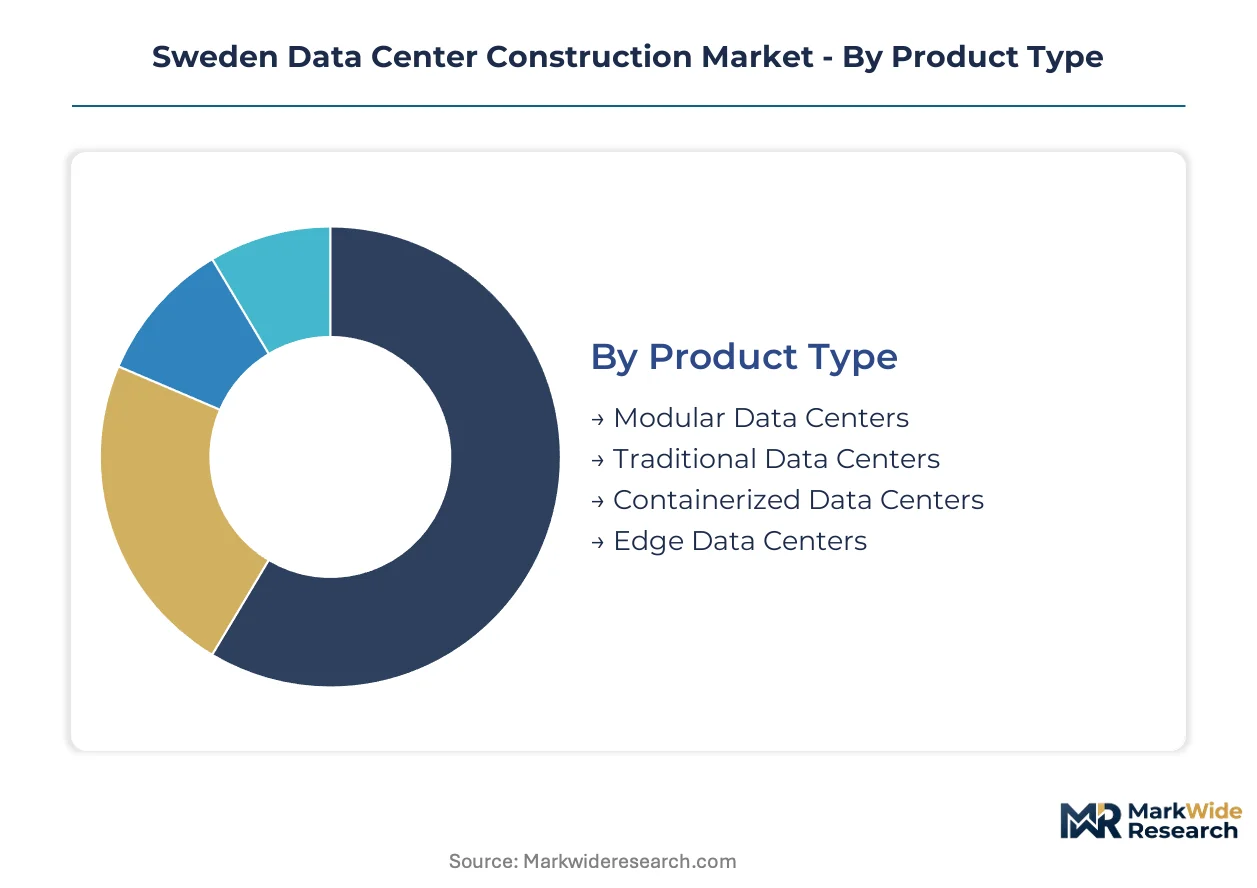
Segmentation in Sweden's data center construction market reveals how procurement patterns split between standardized modular solutions and bespoke hyperscale builds. Developers must align construction methodologies with tenant risk profiles, power density requirements, and municipal permitting constraints across the Mälardalen corridor.
Product Type:
Customization intensity varies dramatically across this category, from fully bespoke traditional facilities to factory-standardized containerized units that compress deployment timelines.
- Modular Data Centers:Factory-integrated power, cooling, and fire suppression systems ship as transportable enclosures. Cloud service providers in Stockholm's northern corridor deploy these in 12-16 week cycles when grid interconnection delays compress commissioning windows.
- Traditional Data Centers:Ground-up concrete and steel construction enables custom redundancy tiers, wholesale leasing structures, and power densities exceeding 100 kilowatts per rack. Financial services tenants in Stockholm metropolitan clusters favor these for guaranteed operational thresholds.
- Containerized Data Centers:ISO-standard shipping containers house compute infrastructure for rapid edge deployment.
- Edge Data Centers:Compact facilities serve latency-sensitive applications in secondary Swedish markets like Västerås and Örebro.
Leading the category by volume: Traditional Data Centers. Expanding most quickly: Modular Data Centers.
Construction Material:
Material selection tracks the tension between speed-to-market and structural permanence, with pre-fabrication gaining ground amid labor constraints.
- Steel:Structural steel framing dominates hyperscale campuses for seismic resilience and rapid erection. Norrtälje and Gävle developments source Swedish-produced sections to minimize embodied carbon under EU Green Deal procurement criteria.
- Pre-fabricated Components:Factory-cast wall panels, electrical skids, and mechanical modules displace on-site concrete pours. These compress mechanical completion from months to weeks where Svenska Kraftnät grid queues already extend timelines.
- Concrete:Cast-in-place foundations and structural cores anchor traditional builds requiring multi-decade asset lifespans.
- Glass:Curtain wall systems appear in corporate showcase facilities and mixed-use developments.
Steel commands the largest procurement volumes. Pre-fabricated Components are climbing the fastest as developers modularize delivery.
End User:
Tenant sophistication determines whether projects proceed under design-build risk transfer or traditional bid-build arrangements.
- Cloud Service Providers:Hyperscale operators demand guaranteed power usage effectiveness and construction cost ceilings, consolidating procurement under single-source design-build contracts. These tenants concentrate in Stockholm's Mälardalen corridor where land, cooling water, and grid capacity align.
- Enterprises:Financial services and industrial firms lacking internal construction management capabilities seek turnkey solutions with defined operational handover criteria.
- Telecom Companies:National carriers deploy edge infrastructure for 5G core network functions.
- Government Agencies:Public sector data sovereignty requirements drive sovereign facility construction with enhanced security specifications.
Cloud Service Providers dominate committed pipeline capacity. Enterprises represent the fastest-expanding tenant category as colocation demand broadens.
Power Supply:
Configuration choices reflect the Swedish Energy Agency's tax relief framework and EU Green Deal decarbonization mandates.
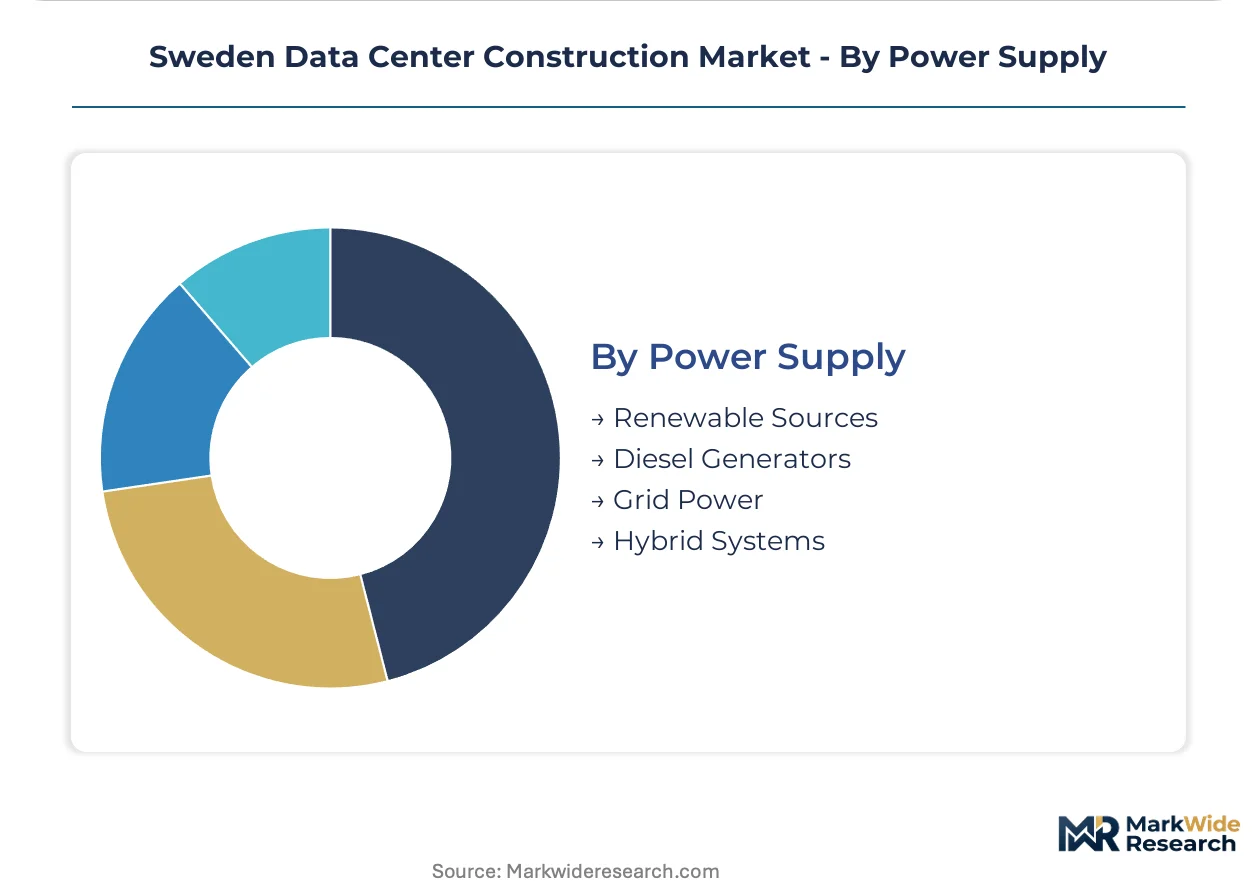
- Renewable Sources:Hydroelectric and wind power purchase agreements dominate new developments, particularly in Norrbotten where excess generation capacity offers pricing below Stockholm tiers. Lease agreements increasingly mandate third-party verified renewable supply configurations.
- Hybrid Systems:Grid power paired with on-site battery storage and diesel backup balances cost with resilience requirements where Svenska Kraftnät interconnection queues extend 18-36 months.
- Grid Power:Direct utility connection remains standard where substation capacity permits.
- Diesel Generators:Backup-only deployment faces tightening Boverket emissions scrutiny.
Renewable Sources lead procurement by committed megawatts. Hybrid Systems are gaining share fastest amid grid interconnection bottlenecks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden's data center construction pipeline concentrates capacity build-out in the Mälardalen corridor while regional developers scout secondary Nordic markets for stranded renewable generation and faster municipal permitting.
Stockholm Metropolitan Cluster
Hyperscale cloud providers anchor committed capacity in Stockholm's northern corridor where Norrtälje and Gävle grid interconnectors align with Baltic Sea cooling water access. Boverket's building codes shape fire suppression requirements for high-density electrical installations. The Mälardalen region dominates developer site selection as land scarcity and grid queues intensify competition for viable parcels.
Norrbotten
Excess hydroelectric and wind generation capacity in Luleå and Piteå offers power purchase agreements below Stockholm pricing tiers. The Swedish Energy Agency's tax relief framework extends to facilities exceeding 0.5 megawatt installed capacity regardless of location. Data center developers are negotiating heat recovery integration with municipal district heating networks to monetize waste heat streams.
Finland
Helsinki and Espoo attract Nordic hyperscale investment through competitive land costs and direct submarine cable connectivity to continental Europe. Finland's national energy regulator oversees grid interconnection queues that currently process faster than Sweden's Svenska Kraftnät timelines. The Helsinki metropolitan cluster positions itself as an alternative to Stockholm's saturated development corridor.
Denmark
Copenhagen and Fredericia emerge as data center construction targets where Danish grid stability and renewable energy certificates satisfy EU Green Deal procurement criteria. The Danish Energy Agency administers streamlined permitting for facilities committing to carbon-neutral operations. Facebook's existing Odense campus demonstrates the viability of large-scale heat recovery into municipal district heating systems.
Norway
Stavanger and Oslo regions leverage surplus hydropower generation to attract power-intensive computing facilities seeking below-market electricity rates. Norway's water resources and energy directorate regulates cooling water discharge more permissively than Sweden's evaporative cooling scrutiny. Developers are evaluating submarine cable routes that position Norwegian facilities as latency-competitive alternatives to Stockholm.
Sweden Data Center Construction Market Competitive Landscape
Top-tier vendors anchor hyperscale foundation and shell contracts across Stockholm's northern corridor, while mid-tier specialists compete on modular delivery speed and mechanical-electrical installation compression. The vendor base stratifies across three archetypes: domestic civil engineering conglomerates with scale advantages, international modular construction specialists, and regional mechanical-electrical integrators. Consolidation pressures favor design-build contracts that transfer performance risk to single-source contractors, while procurement fragmentation persists among enterprise tenants lacking internal construction management capabilities.
Within the domestic engineering tier, Skanska Sverige AB and NCC occupy positions as anchor contractors for ground-up concrete and steel construction requiring seismic resilience and multi-decade asset lifespans. DPR Construction exemplifies the international modular specialist archetype competing on factory-integrated delivery timelines. Bravida Holding AB represents the mechanical-electrical integration specialist segment where compressed commissioning windows command premium contracting margins.
| Leading Market Players |
|---|
| DPR Construction |
| Collen Construction Limited |
| Skanska Sverige AB |
| Winthrop Technologies Ltd |
| Kirby Group Engineering |
| Bravida Holding AB |
| Coromatic AB |
| NCC |
| AECOM |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up mechanical-electrical specialists dominate Sweden's data center construction tier, compressing subcontractor margins while enforcing fixed-price discipline on steel and copper inputs. This ownership concentration feeds pricing power upstream toward factory-integrated skid manufacturers and squeezes general contractors facing Svenska Kraftnät grid interconnection delays.
Pricing Analysis
Margin tightening in traditional ground-up construction reflects steel and copper input volatility that erodes fixed-price contract buffers. Three-tier pricing structure across premium redundancy tiers, standard colocation builds, and economy modular deployments tracks tenant risk profiles and certification requirements. Cost-down pressure on electrical-mechanical packages accelerates because hyperscale cloud providers consolidate procurement under single-source design-build contracts. Financial services tenants in Stockholm exhibit lowest price sensitivity due to operational threshold guarantees, while regional edge deployers in Västerås and Örebro prioritize speed-to-market over specification.
Supply Chain Analysis
Refurbishment flows for decommissioned switchgear and UPS modules create secondary supply channels that moderate new equipment pricing in Stockholm's northern corridor. Factory-integrated electrical skids and pre-cast concrete panels draw from manufacturing concentrations in Germany, Poland, and domestic Swedish production hubs. Busbar and structural steel sourcing rests on Nordic mill capacity and import flows from continental Europe. Single-source vulnerability concentrates in high-voltage transformer supply where 400 kilovolt commissioning competence is scarce. Distribution runs through design-build contractors who warehouse prefabricated components to compress on-site mechanical completion timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Swedish data center construction market operates as a cost-of-compliance story where Boverket building codes and Swedish Energy Agency tax frameworks erect barrier-to-entry moats. EU Green Deal procurement criteria now mandate third-party verified sustainability metrics that only capitalized incumbents can satisfy.
For Market Incumbents: Deepen backward integration into pre-fabricated electrical skid manufacturing to capture margins currently flowing to German and Polish suppliers. Anchor capacity addition in Norrbotten's Luleå and Piteå corridor where excess hydroelectric generation supports below-market power purchase agreements. Defend against modular construction specialists by compressing commissioning timelines through in-house mechanical-electrical integration. For New Entrants and Emerging Players: Digital-channel specification tools offer low-friction entry into enterprise tenant segments lacking internal construction management capabilities. Target heat recovery integration services as the most penetrable niche, where municipal district heating network interconnection contracts convert waste heat into revenue streams. Pursue go-to-market positioning as sustainability compliance specialists who navigate EU Green Deal embodied carbon documentation for financial services tenants. For Investors and Strategic Acquirers: Distressed-cycle entries favor mechanical-electrical integration specialists with compressed commissioning capabilities in Stockholm's saturated Mälardalen corridor. Long-term viability hinges on positioning for heat recovery monetization and renewable power supply configuration mandates. Watch Svenska Kraftnät grid interconnection queue clearance rates as the inflection signal for construction activity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Electrical Skid Manufacturing | Factory-integrated switchgear compresses on-site completion from months to weeks amid labor constraints. |
| Heat Recovery Network Integration | District heating interconnection monetizes waste heat under municipal utility contracts in Norrbotten. |
| Renewable Power Purchase Agreements | Hydroelectric and wind supply configurations satisfy EU Green Deal procurement criteria for hyperscale leases. |
| Design-Build Contract Consolidation | Single-source risk transfer aligns contractor incentives with cloud provider power usage effectiveness guarantees. |
| Liquid Cooling Infrastructure Deployment | Direct-to-chip systems enable rack economics above 100 kilowatts that air-cooled designs cannot sustain. |
Research Methodology
Multi-period observation of construction permit filings, grid interconnection queues, and hyperscale lease announcements anchored the trend analysis, supplemented by interviews with data center developers, EPC contractors, municipal planning officers, and electrical-mechanical subcontractors. Secondary validation drew from Boverket building code amendments, Swedish Energy Agency tax relief documentation, Svenska Kraftnät transmission data, EU Green Deal procurement guidelines, and hyperscaler capital expenditure disclosures. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates across modular and traditional construction categories.
Segment-weighting approaches distributed value across product type, construction material, end user, and power supply configurations throughout the forecast period. CAGRs derived from capacity deployment trajectories, tenant commitment timelines, and municipal permitting velocity. Industry-specific inputs included Svenska Kraftnät substation upgrade schedules, Baltic Sea cooling water access constraints, and Norrbotten renewable surplus absorption rates.
The model holds under sustained hyperscale cloud demand and stable Swedish Energy Agency tax frameworks; deviation in grid interconnection processing timelines or Boverket evaporative cooling restrictions would shift regional deployment patterns. Practitioners should monitor Svenska Kraftnät queue clearance rates and municipal closed-loop water system mandates for early signals of construction timeline compression or extension.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Public Cloud System Infrastructure Service Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
Vietnam Data Center Physical Security Market
Data Center Infrastructure
New Jersey Data Center Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
Germany Data Center Market
Data Center Infrastructure
Global Edge Data Center Market
Data Center Infrastructure
Austria Data Center Market
Data Center Infrastructure
Asia-Pacific Data Center Power Market
Data Center Infrastructure
Italy Data Center Server Market
Data Center Infrastructure
Mexico Data Center Power Market