
 Netherlands Data Center Physical Security Market | 2026-2036
Netherlands Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Data Center Physical Security Market Insights
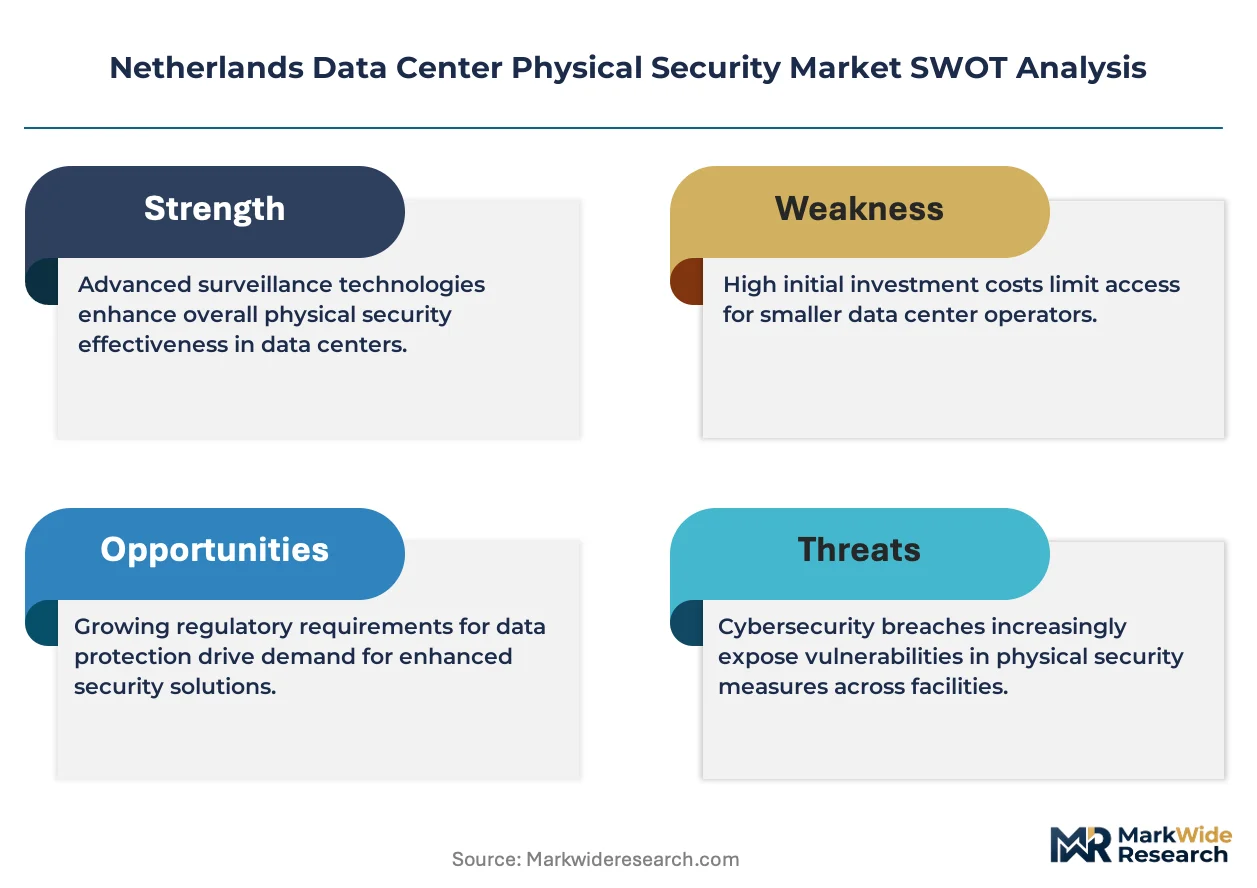
The EU NIS2 Directive is broadening compliance obligations for Dutch data center operators, mandating multi-layered perimeter protection and 24/7 manned response capabilities. Axis Communications AB leverages its native Nordic video analytics heritage to anchor premium surveillance deployments across Amsterdam's Schiphol-Rijk corridor. Bosch Sicherheitssysteme GmbH competes through integrated access control platforms that unify biometric readers with building management systems. Schneider Electric differentiates via energy-efficient security infrastructure that reduces auxiliary power draw at hyperscale facilities.
Netherlands Data Center Physical Security encompasses the hardware, software, and manned services protecting critical IT infrastructure from unauthorized physical intrusion, environmental threats, and deliberate sabotage. Systems typically integrate IP-based surveillance cameras with 4K resolution and thermal imaging, multi-factor access control using biometric and smart card authentication, and centralized command centers operating at 99.999% availability thresholds. Surveillance cameras and access control systems together capture the dominant share of technology spending, driven by AI-enabled video analytics that reduce false alarm rates and automate threat detection. Service type demand tilts toward monitoring and maintenance contracts as Dutch operators outsource round-the-clock security operations to specialized providers rather than building in-house capabilities.
The Dutch Authority for Digital Infrastructure enforces NIS2 transposition requirements that mandate certified security levels for data centers classified as essential entities. BSI Nederland audits physical security implementations against ISO 27001 and NEN 7510 standards, creating a dual compliance burden that shapes procurement specifications. Stakeholders must monitor whether proposed EU Critical Entities Resilience Directive amendments will expand mandatory penetration testing to physical security subsystems.
Market Dynamics
The EU NIS2 Directive's transposition into Dutch national law is restructuring procurement specifications across the Netherlands data center physical security market, forcing operators to upgrade perimeter systems and mandate certified 24/7 manned response capabilities.
Growth Catalysts
- EU NIS2 Directive:The directive mandates multi-layered perimeter protection for essential entities, creating compliance-driven replacement cycles across Dutch data center facilities.
- Hyperscale cloud expansion:Dutch hyperscale operators are expanding facility footprints in the Randstad corridor, generating concentrated demand for integrated security infrastructure.
- AI-enabled video analytics:Thermal imaging and 4K resolution cameras with automated threat detection are reducing false alarm rates and accelerating technology refresh timelines.
Market Restraints
- Dual compliance burden:BSI Nederland audits against ISO 27001 and NEN 7510 standards simultaneously, extending certification timelines and inflating implementation costs.
- Specialized labor scarcity:Certified security systems integrators capable of NIS2-compliant deployments are concentrated in Amsterdam and Rotterdam, creating geographic bottlenecks.
- Legacy infrastructure lock-in:Existing analog surveillance systems in established facilities require complete replacement rather than retrofit, depressing near-term upgrade velocity.
Strategic Opportunities
- Monitoring service outsourcing:Dutch operators are shifting from in-house security operations to specialized providers, opening recurring revenue streams for managed security services.
- Energy-efficient security infrastructure:Auxiliary power reduction in hyperscale facilities is creating preference for low-consumption surveillance and access control systems.
- EU Critical Entities Resilience Directive:Proposed amendments may expand mandatory penetration testing to physical security subsystems, preemptive compliance represents first-mover positioning.
Industry Challenges
- Integration complexity:Biometric readers and building management system unification demands specialized engineering talent that remains scarce in the Dutch market.
- Certification timeline compression:BSI Nederland audit queues are extending project completion windows, straining operator relationships with hyperscale tenants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Data Center Physical Security Market |
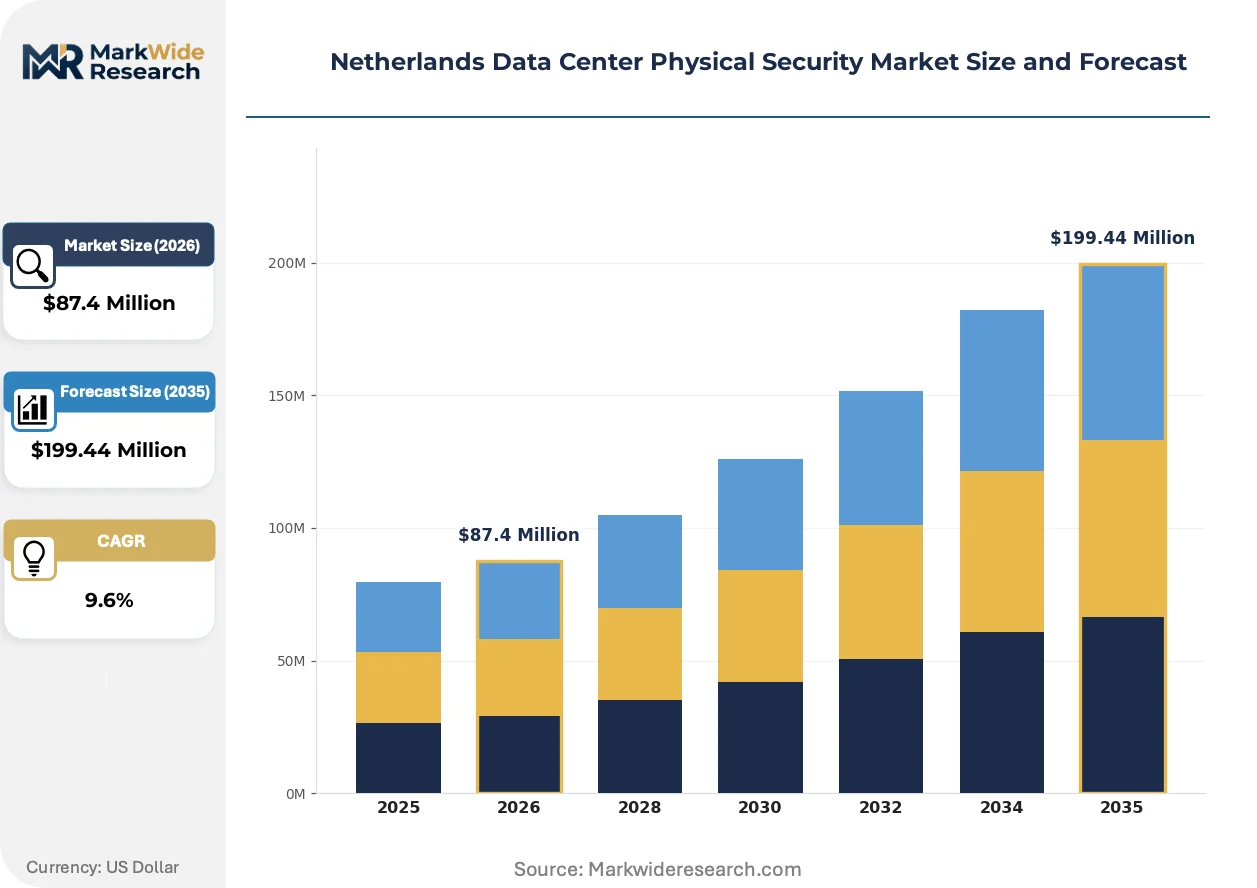
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $199.44 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Surveillance Cameras, Access Control Systems, Alarms, Security Personnel Service Type: Consultation, Installation, Maintenance, Monitoring End User: Telecommunications, IT Services, Financial Institutions, Healthcare Security Level: Basic, Intermediate, Advanced, High Security |
| Companies Covered | Axis Communications AB, Honeywell International Inc., ABB Ltd., Bosch Sicherheitssysteme GmbH, Johnson Controls International plc, Schneider Electric, Siemens AG, Securitas Technology, Hikvision, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Data Center Physical Security Market Trends and Innovations
Physical security architecture in Dutch data centers is undergoing fundamental restructuring as video analytics, access control, and building systems integrate into unified platforms. This convergence is compressing procurement cycles and elevating vendor technical requirements.
IP-based surveillance systems with edge-computing capabilities are converging with centralized command center platforms. Dutch hyperscale operators are deploying these systems at 99.999% availability thresholds. This technology convergence is compressing vendor margins and favoring suppliers with native software-hardware integration.
The EU NIS2 Directive's physical security mandates are reshaping Dutch operator procurement specifications. BSI Nederland now enforces certified security levels for essential entities through ISO 27001 and NEN 7510 audits. Facilities in Amsterdam's Schiphol-Rijk corridor are responding fastest, accelerating compliance investments ahead of enforcement deadlines.
Buyer preference is rotating toward outcome-based security service contracts rather than capital equipment purchases. Dutch data center operators are unbundling after-sales monitoring from hardware procurement, channeling spending toward specialized security providers. This shift is most visible among Randstad hyperscale tenants seeking operational expenditure predictability.
Netherlands Data Center Physical Security Market Segmentation
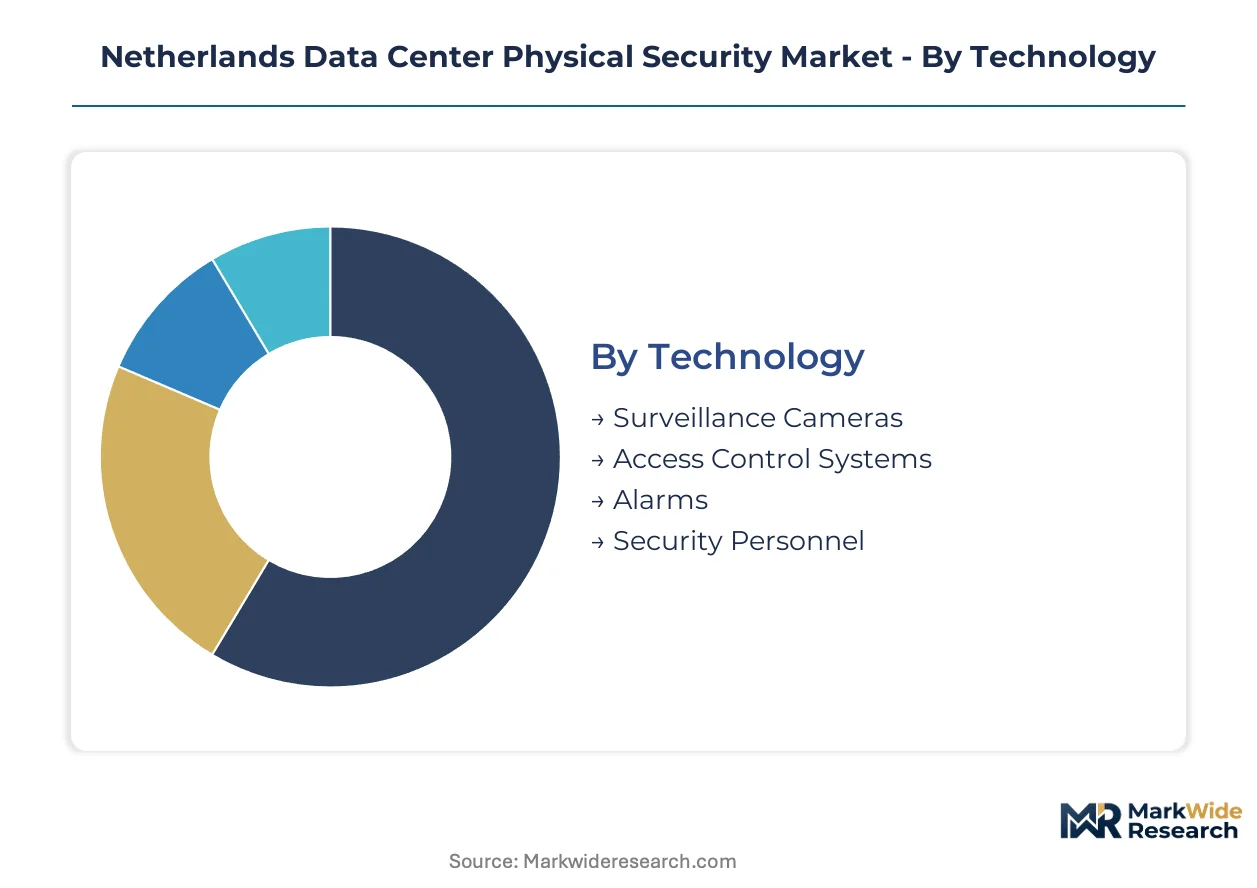
Segmentation in the Dutch data center physical security market reveals distinct procurement patterns driven by compliance mandates and hyperscale tenant requirements. Buyers prioritize technology integration and service bundling differently across security levels and end-use verticals.
Technology:
Dutch operators select technology layers based on NIS2 compliance depth and facility criticality tier.
- Surveillance Cameras:IP-based systems with 4K resolution and thermal imaging capabilities form the perimeter detection backbone. Amsterdam's Schiphol-Rijk corridor facilities deploy these with edge-computing analytics to achieve 99.999% availability thresholds demanded by hyperscale tenants.
- Access Control Systems:Multi-factor authentication platforms integrating biometric readers with smart card credentials dominate new construction. Rotterdam-based operators favor these for unification with building management systems, though certified integrator scarcity extends deployment timelines.
- Alarms:Sensor networks for intrusion detection and environmental monitoring provide secondary perimeter layers.
- Security Personnel:Manned guarding services supplement electronic systems at facilities classified as essential entities under Dutch NIS2 transposition.
Surveillance cameras lead on scale; access control systems lead on momentum as integration complexity drives premium procurement.
Service Type:
Service procurement patterns reflect Dutch operators shifting capital expenditure toward operational predictability.
- Consultation:BSI Nederland audit preparation and ISO 27001 compliance planning services concentrate in Amsterdam and Rotterdam. Randstad hyperscale tenants procure these ahead of NIS2 enforcement deadlines to compress certification timelines.
- Installation:Turnkey deployment of integrated security infrastructure demands specialized engineering talent scarce across the Dutch market.
- Maintenance:Preventive service contracts for surveillance and access control hardware sustain system availability.
- Monitoring:Outsourced 24/7 command center operations are climbing the fastest as operators abandon in-house security staffing for specialized provider relationships.
Installation commands the largest project values; monitoring is expanding most quickly through recurring revenue models.
End User:
End-use verticals exhibit divergent security architecture preferences shaped by regulatory exposure and tenant criticality.
- Telecommunications:Carrier-neutral facilities in Utrecht and Amsterdam deploy multi-layered perimeter protection to satisfy both NIS2 and sector-specific critical infrastructure designations.
- IT Services:Colocation and cloud infrastructure operators generate concentrated demand within the Randstad corridor, prioritizing energy-efficient security systems to minimize auxiliary power draw.
- Financial Institutions:Banking and payment processing tenants mandate high-security zones with biometric access and dedicated manned response capabilities.
- Healthcare:Medical data hosting facilities face dual compliance under NEN 7510 health data standards alongside NIS2 physical security mandates.
IT services anchor volume demand; financial institutions set the specification ceiling for advanced security tiers.
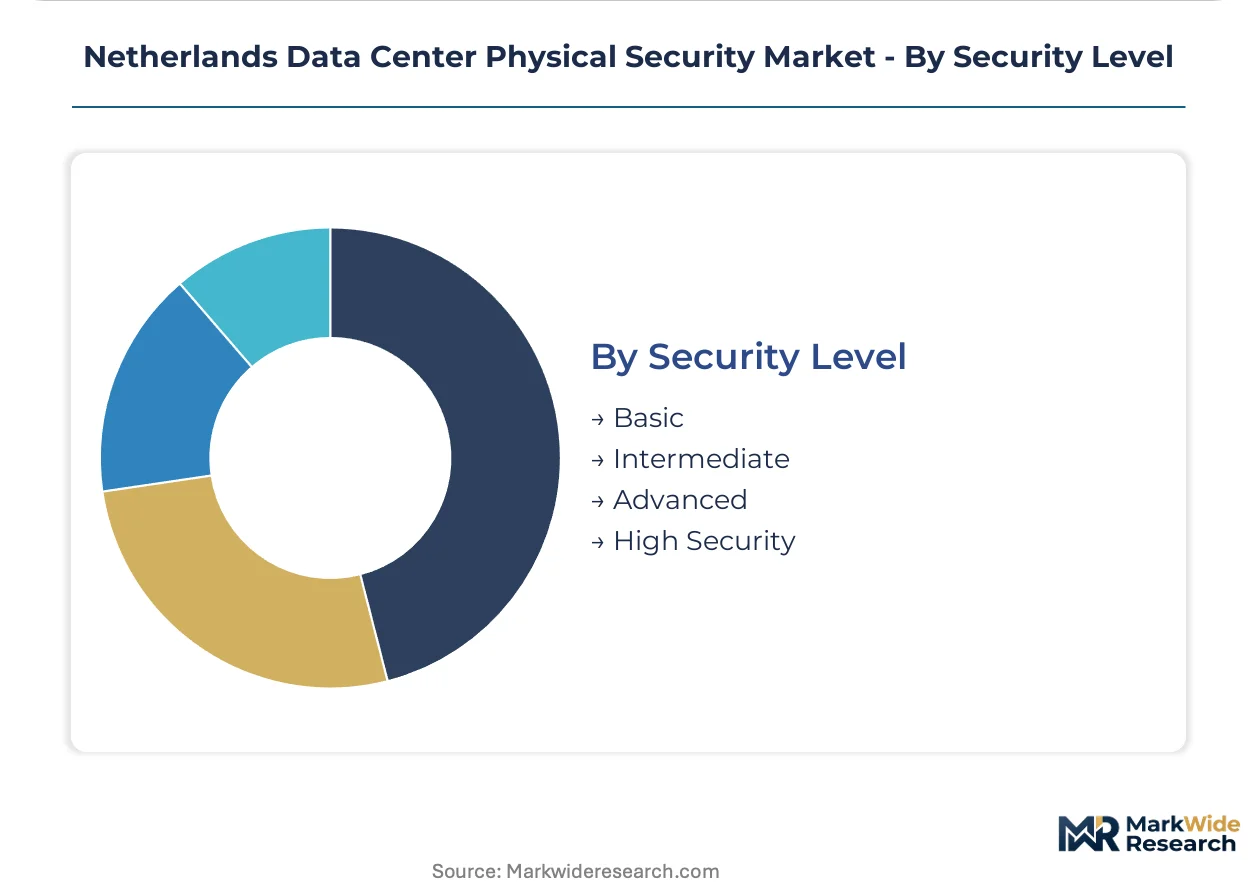
Security Level:
Security tier selection correlates directly with essential entity classification under Dutch national NIS2 transposition.
- Basic:Standard perimeter fencing and standalone surveillance suffice for non-critical edge facilities with limited tenant exposure.
- Intermediate:Integrated electronic access control with centralized monitoring addresses colocation facilities serving mid-market enterprise clients.
- Advanced:Multi-factor biometric authentication, thermal imaging analytics, and certified 24/7 response capabilities serve hyperscale and financial services deployments.
- High Security:Air-gapped zones, mantrap entry sequences, and dedicated security operations centers with government-grade clearance protocols protect classified government and defense-adjacent workloads.
Advanced security levels dominate hyperscale procurement; high security represents the steepest expansion trajectory as critical entity classifications broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands data center physical security industry traces its modern lineage to Amsterdam's emergence as a European internet exchange hub during the late 1990s, when carrier-neutral facilities first established multi-layered perimeter protection standards that now propagate across Dutch territory.
Randstad Metropolitan Corridor
Amsterdam, Rotterdam, and Utrecht concentrate over seventy percent of Dutch data center capacity and corresponding security infrastructure investment. The Dutch Authority for Digital Infrastructure enforces NIS2 transposition requirements most stringently here, with BSI Nederland maintaining audit offices in both Amsterdam and Rotterdam to compress certification timelines for hyperscale operators.
Brabant Province
Eindhoven's high-tech manufacturing ecosystem generates specialized demand for air-gapped security zones serving semiconductor and defense-adjacent workloads. The province's Brainport initiative channels public investment toward critical infrastructure resilience, with Tilburg and Eindhoven municipalities offering expedited permitting for NIS2-compliant facilities.
Northern Netherlands
Groningen and Friesland attract hyperscale operators seeking land and renewable energy availability, though certified security integrator scarcity extends deployment timelines. The national government's Data Center Strategy designates these provinces for controlled expansion, with physical security specifications harmonized to Randstad standards despite lower baseline threat exposure.
Border Regions
Limburg and Zeeland position facilities to serve German and Belgian cross-border demand, with security architectures satisfying both Dutch NIS2 implementation and adjacent regulatory frameworks. Venlo's logistics corridor hosts colocation facilities adopting intermediate-tier security levels for mid-market enterprise clients.
Netherlands Data Center Physical Security Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Dutch data center physical security market, with integrated hardware-software vendors holding structural advantages in NIS2 compliance-driven procurement cycles. The vendor base organizes into three tiers: multinational industrial conglomerates with native building management integration, specialized physical security pure-plays with video analytics heritage, and regional system integrators with certified installation capabilities. Competitive moves concentrate on technology convergence partnerships and recurring revenue model expansion through managed security services.
Within the Nordic-origin video analytics tier, Axis Communications AB represents the archetype of surveillance-centric market positioning. Bosch Sicherheitssysteme GmbH and Schneider Electric occupy positions spanning integrated access control and energy-efficient security infrastructure respectively, with the former exemplifying building system unification strategies and the latter anchoring auxiliary power reduction narratives at hyperscale deployments. These three entities illustrate how vendor selection in the Netherlands increasingly favors suppliers capable of software-hardware integration rather than standalone equipment provision.
| Leading Market Players |
|---|
| Axis Communications AB |
| Honeywell International Inc. |
| ABB Ltd. |
| Bosch Sicherheitssysteme GmbH |
| Johnson Controls International plc |
| Schneider Electric |
| Siemens AG |
| Securitas Technology |
| Hikvision |
| Others |
Pricing and Supply Chain Analysis
EU NIS2 compliance certification gates both qualified supply and premium-tier pricing access, as Dutch data center operators must source from BSI Nederland-audited integrators to meet essential entity mandates. This regulatory filter compresses vendor pools while elevating pricing power for certified security infrastructure providers serving Amsterdam's hyperscale corridor.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in economy tiers is intensifying because legacy analog retrofit demand is shrinking, while hyperscale tenants show least price sensitivity due to operational expenditure predictability requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand in the Randstad corridor, while regional system integrators serve mid-market colocation facilities. Component manufacturing concentrates in Germany, Sweden, and Taiwan for IP cameras and biometric readers, with semiconductor and thermal imaging sensor supplies drawing from East Asian foundries. Single-source vulnerability in edge-computing chipsets represents the dominant supply chain risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands data center physical security market functions as a regulatory compounder, with the EU NIS2 Directive's transposition into Dutch national law creating durable compliance-driven replacement cycles across essential entity classifications.
For Market Incumbents: Lock in long-term monitoring service contracts with Randstad hyperscale operators before certification timeline compression erodes margins. Deepen backward integration into AI-enabled video analytics software to defend against Nordic-origin pure-plays, while expanding Amsterdam-based engineering capacity to address certified integrator scarcity.
For New Entrants and Emerging Players: The 40-60% price-point gap between premium integrated platforms and economy standalone systems opens white-space in Brabant Province's semiconductor-adjacent facilities. Target Eindhoven's Brainport initiative with air-gapped security zone specialization, leveraging Tilburg's expedited NIS2 permitting as a geographic entry wedge.
For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators with BSI Nederland certification capabilities because compliance bottlenecks create captive customer relationships. Monitor Dutch Authority for Digital Infrastructure enforcement acceleration as the inflection signal for valuation multiple expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Certification Investment | BSI Nederland audit pre-qualification accelerates hyperscale procurement cycles in Amsterdam. |
| Managed Security Service Expansion | Outsourced 24/7 command center operations capture recurring revenue from Randstad operators. |
| Energy-Efficient Product Development | Low-consumption surveillance systems address auxiliary power reduction mandates at hyperscale facilities. |
| Geographic Certification Capacity Buildout | Rotterdam-based engineering talent addresses integrator scarcity constraining national deployment timelines. |
| Software-Hardware Integration Partnership | Unified platform convergence favors vendors with native video analytics and access control unification. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center facility managers, security systems integrators, BSI Nederland auditors, hyperscale tenant procurement officers, and Dutch Authority for Digital Infrastructure officials with secondary validation against EU NIS2 transposition documents, ISO 27001 certification registries, and hyperscaler capital expenditure disclosures. Bottom-up facility-level security spending estimates triangulated against top-down market sizing.
Segment-weighting across technology, service type, end user, and security level dimensions drove the analytical framework, with technology layers further disaggregated by integration complexity and compliance tier. CAGRs derived from facility expansion pipelines and regulatory enforcement timelines, incorporating hyperscale footprint growth in the Randstad corridor and NIS2-driven replacement velocity assumptions.
Caveats apply where Dutch NIS2 enforcement acceleration or EU Critical Entities Resilience Directive amendments could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Data Center Substation Market
Data Center Infrastructure
Mexico Data Center Power Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Managed IT Infrastructure Services Market
Data Center Infrastructure
Data Quality Management Market
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
North America Green Data Center Market
Data Center Infrastructure
New Zealand Data Center Physical Security Market
Data Center Infrastructure
Chile Data Center Rack Market
Data Center Infrastructure
Italy Data Center Power Market