
 Pandemic Analytics Market | 2026-2036
Pandemic Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Pandemic Analytics Market Analysis
Data science talent scarcity is reorganizing how vendors build pandemic analytics platforms, forcing cloud providers to retrain epidemiologists as platform architects. Microsoft Corporation leverages its Azure health data services to anchor large-scale outbreak modeling contracts with federal agencies. Oracle Corporation sustains dominance in hospital network deployments through integrated electronic health record pipelines that feed real-time surveillance dashboards.
Pandemic analytics encompasses computational systems that ingest multi-source health data—case reports, genomic sequencing, mobility patterns, and supply chain signals—to generate predictive intelligence on disease trajectory and healthcare system stress. These platforms employ machine learning classifiers and agent-based simulation engines to forecast infection peaks with geographic granularity down to hospital catchment areas. Predictive modeling software captures the largest margin pool among product types, as proprietary epidemiological algorithms command premium licensing fees from government buyers. Cloud-based deployment is expanding fastest among end-user segments, since health agencies now prioritize elastic compute capacity over capital-intensive on-premise infrastructure.
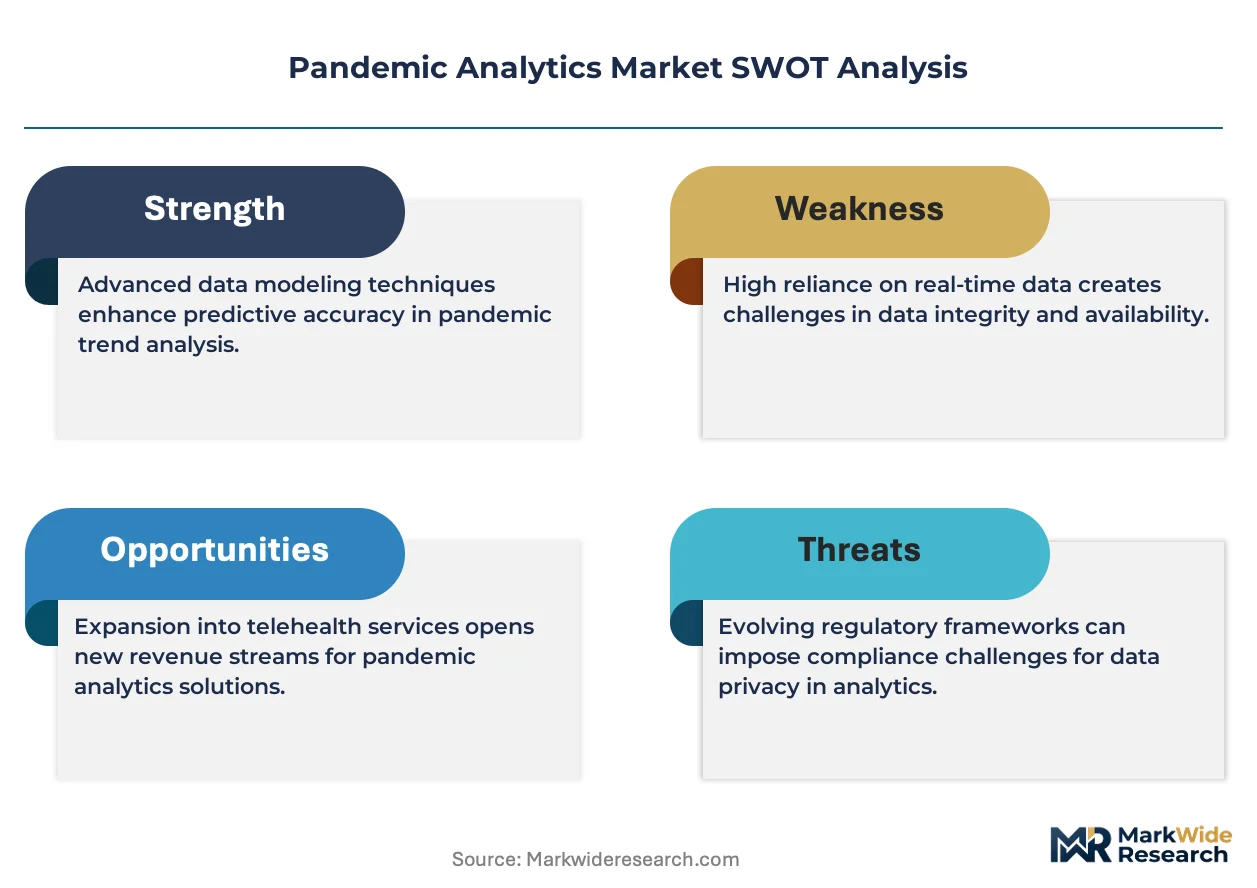
The FDA governs clinical decision-support modules embedded in pandemic analytics suites, requiring algorithmic transparency documentation for tools influencing patient triage protocols. HIPAA compliance obligations shape data architecture choices, particularly for platforms processing identifiable patient records across state jurisdictions. The CDC's data interoperability mandates drive standardization of API formats for interstate case reporting. Stakeholders must weigh algorithmic explainability requirements against predictive accuracy trade-offs as regulators scrutinize black-box models deployed in emergency response settings.
Market Dynamics
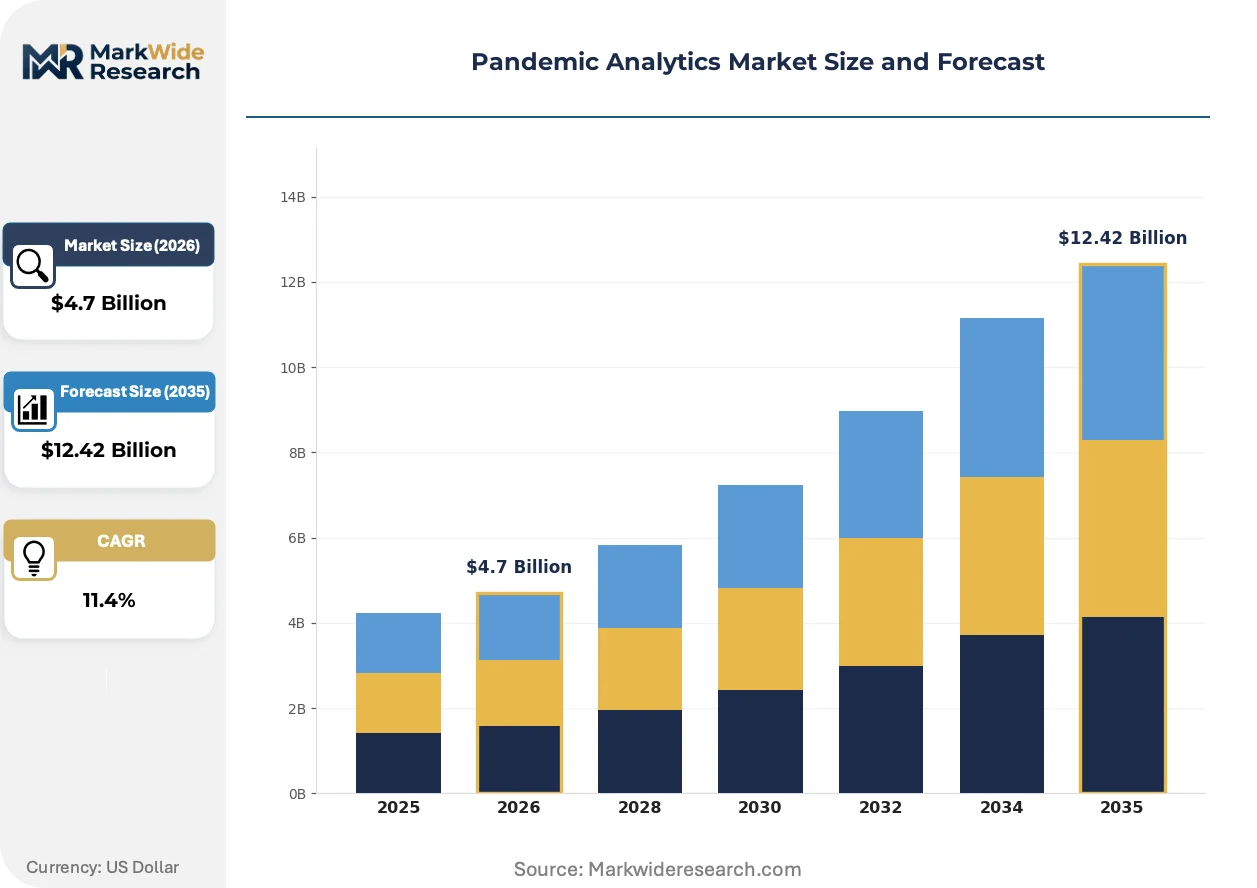
Federal pandemic preparedness budgets are compressing procurement cycles for predictive modeling platforms while HIPAA compliance obligations reshape data architecture investments across health agencies.
Growth Catalysts
- FDA Emergency Use Authorization:Accelerated software validation timelines during health emergencies reduce deployment barriers for real-time surveillance tools. Federal agencies fast-track contracts under this pathway.
- Cloud Elasticity:Health agencies prioritize elastic compute capacity over capital-intensive on-premise infrastructure, expanding subscription-based platform adoption.
- Hospital Network Integration:Electronic health record pipelines feeding real-time surveillance dashboards create captive demand for interoperable analytics modules.
Market Restraints
- Data Science Talent Scarcity:Cloud providers must retrain epidemiologists as platform architects, inflating implementation costs and extending deployment timelines.
- Algorithmic Transparency Requirements:FDA mandates for clinical decision-support documentation create compliance friction for proprietary black-box models.
- State Jurisdiction Fragmentation:HIPAA obligations multiply across interstate data flows, complicating multi-state health system deployments.
Strategic Opportunities
- Genomic Sequencing Convergence:Integration of pathogen genomic data with mobility pattern analytics opens new predictive accuracy tiers for outbreak origin tracing.
- API Standardization:CDC data interoperability mandates create first-mover advantage for vendors adopting standardized case reporting formats.
- Agent-Based Simulation:Hospital catchment-level forecasting capabilities remain underpenetrated in mid-tier metropolitan health departments.
Industry Challenges
- Epidemiological Modeling Expertise Gap:Platform vendors struggle to staff teams combining machine learning engineering with infectious disease domain knowledge.
- Legacy System Integration Complexity:State health department IT infrastructure requires custom middleware development for real-time data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pandemic Analytics Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Visualization Tools, Predictive Modeling Software, Dashboard Applications, Reporting Solutions End User: Government Agencies, Healthcare Providers, Research Institutions, Corporations Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Applications Application: Forecasting, Resource Allocation, Risk Assessment, Trend Analysis |
| Companies Covered | IBM Corporation, Oracle Corporation, Microsoft Corporation, Amazon Web Services, Inc., IQVIA Holdings, Inc., McKesson Corporation, Health Catalyst, Inc., Optum Inc., Cerner Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pandemic Analytics Market Emerging Trajectories
Machine learning classifiers are fragmenting traditional epidemiological forecasting methodologies while regulatory pressure on algorithmic explainability reshapes product development roadmaps.
Agent-based simulation engines are fragmenting the dominance of compartmental models in outbreak forecasting. State health departments are adopting these tools for hospital surge capacity planning. The technology is fragmenting vendor market share as specialized simulation providers capture niche geographic forecasting contracts.
The EU AI Act's risk classification framework for health-critical algorithms is reshaping export compliance strategies for US-based platform vendors. High-risk system documentation requirements are extending product development cycles. European health agencies are prioritizing vendors with pre-established algorithmic audit trails.
Subscription-based platform licensing is displacing perpetual software licenses in federal procurement. State and local health departments favor operational expenditure models that align analytics costs with emergency funding cycles. This shift is most visible in CDC cooperative agreement-funded jurisdictions.
Pandemic Analytics Market Segmentation
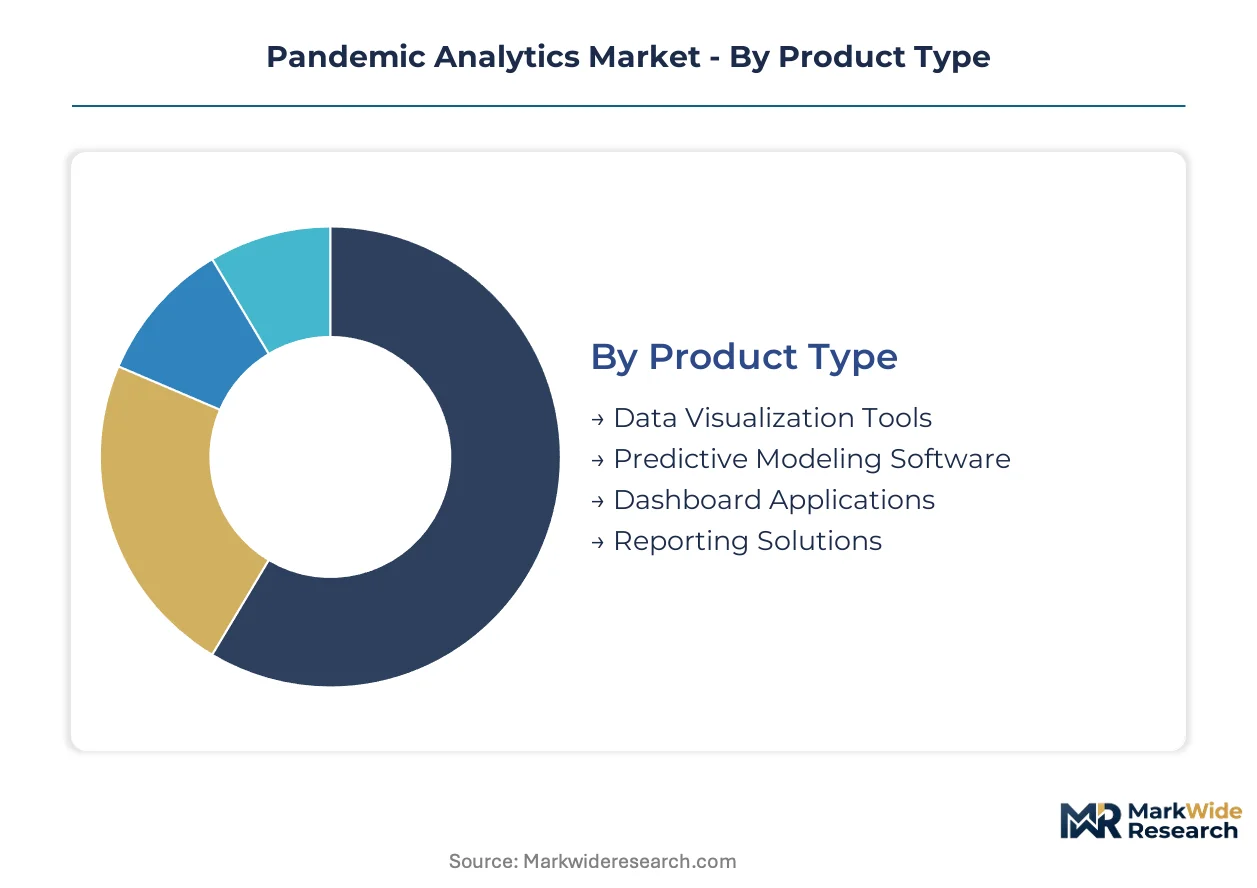
Pandemic analytics platforms fragment across product architectures, user workflows, and infrastructure models. Segment boundaries determine procurement pathways, pricing tiers, and integration complexity for health system buyers.
Product Type:
Predictive modeling software flows through federal emergency procurement channels, while visualization tools distribute via SaaS marketplaces and direct hospital sales.
- Predictive Modeling Software:Proprietary epidemiological algorithms employing machine learning classifiers and agent-based simulation engines. Federal agencies in the United States sustain premium licensing demand for tools forecasting infection peaks at hospital catchment granularity. FDA emergency use authorization pathways compress validation timelines for these modules.
- Data Visualization Tools:Interactive mapping interfaces and temporal trend displays processing multi-source health data streams. State health departments prioritize these for public communication dashboards during outbreak events. Cloud elasticity requirements favor subscription-based distribution models.
- Dashboard Applications:Real-time surveillance interfaces integrating electronic health record pipelines with case reporting feeds.
- Reporting Solutions:Automated compliance documentation generators for HIPAA audit trails and CDC interoperability mandates.
By volume, data visualization tools lead. By growth pace, predictive modeling software is gaining share fastest.
End User:
Government agencies concentrate procurement in the United States through CDC cooperative agreements, while healthcare providers distribute demand across integrated delivery networks and standalone hospitals.
- Government Agencies:Federal, state, and local public health departments operating surveillance infrastructure. United States pandemic preparedness budgets sustain advanced analytics procurement for CDC-funded jurisdictions. API standardization mandates reshape vendor selection criteria.
- Healthcare Providers:Hospital networks and health systems managing surge capacity and intensive care resource allocation. Oracle Corporation anchors this segment through electronic health record integration pipelines. Real-time surveillance dashboard demand concentrates in large metropolitan catchment areas.
- Research Institutions:Academic medical centers and epidemiological research organizations conducting outbreak origin studies.
- Corporations:Employers and insurers deploying workforce health monitoring and supply chain risk analytics.
Healthcare providers dominate current spending. Government agencies show the steepest expansion trajectory as federal funding cycles align with platform subscription models.
Deployment:
Cloud-based architectures command the fastest uptake among health agencies prioritizing operational expenditure flexibility over capital commitments.
- Cloud-Based:Elastic compute platforms hosted on Microsoft Azure and competing infrastructure services. State and local health departments favor subscription licensing that aligns costs with emergency funding availability. HIPAA compliance obligations shape multi-tenant data architecture decisions.
- On-Premise:Capital-intensive server installations maintaining physical data sovereignty. Legacy state health department IT infrastructure perpetuates demand for custom middleware development.
- Hybrid:Split architectures processing sensitive patient records on-premise while leveraging cloud burst capacity for simulation workloads.
- Mobile Applications:Field-deployable interfaces for contact tracers and rapid response teams requiring offline synchronization capabilities.
Cloud-based deployment leads by new contract volume. Hybrid models are climbing fastest as jurisdictions balance sovereignty requirements with compute scalability.
Application:
Forecasting applications capture the largest margin pool through proprietary algorithm licensing, while resource allocation modules penetrate fastest among hospital network buyers.
- Forecasting:Machine learning classifiers predicting disease trajectory with geographic and temporal granularity. Agent-based simulation engines fragment traditional compartmental model dominance in outbreak projection. Federal contracts sustain premium pricing for hospital catchment-level capabilities.
- Resource Allocation:Intensive care capacity planning and supply chain signal integration for medical countermeasure distribution. Hospital networks deploy these modules for surge capacity management during case peaks.
- Risk Assessment:Pathogen genomic sequencing convergence with mobility pattern analytics for outbreak origin tracing.
- Trend Analysis:Historical case pattern mining and comparative epidemiological study tools for research workflows.
Resource allocation leads by deployment count across hospital networks. Forecasting commands the highest revenue per contract.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes pandemic analytics platforms through federal emergency procurement channels, while European health agencies prioritize algorithmic audit trails under the EU AI Act's risk classification framework. This consumption-mix differential shapes vendor compliance strategies and product roadmaps across Atlantic markets.
United States
Federal pandemic preparedness budgets sustain procurement of predictive modeling platforms through CDC cooperative agreements and ASPR emergency funding cycles. The FDA's emergency use authorization pathway compresses software validation timelines for real-time surveillance tools during declared health emergencies. Health agencies in the Washington DC metro area anchor federal contracting concentration, while state health departments in California and New York drive demand for cloud-based deployment with HIPAA-compliant multi-tenant architectures.
Germany
The Robert Koch Institute coordinates national surveillance infrastructure procurement, with federal states competing for analytics platform contracts through centralized health IT frameworks. The EU AI Act's high-risk system documentation requirements extend product development cycles for clinical decision-support modules exported from US vendors. Berlin and Munich host the densest concentration of health data interoperability specialists, where regional health ministries pilot API standardization for interstate case reporting.
United Kingdom
NHS England's pandemic preparedness directorate funds predictive modeling capabilities through integrated care system procurement frameworks, with surge capacity planning driving hospital network adoption. The UK Health Security Agency mandates algorithmic transparency for outbreak forecasting tools influencing patient triage protocols. London's academic medical centers cluster genomic sequencing analytics expertise, where pathogen origin tracing capabilities converge with mobility pattern data.
France
Santé publique France operates centralized surveillance infrastructure with regional health agencies deploying catchment-level forecasting tools for hospital capacity management. ANSM and CNIL jointly regulate clinical decision-support algorithms and health data processing, creating dual compliance obligations for platform vendors. The Paris-Saclay research cluster concentrates epidemiological modeling expertise, where academic partnerships with hospital networks accelerate agent-based simulation adoption.
Japan
METI's health technology procurement programs subsidize predictive analytics platform adoption for prefectural health departments managing aging-population disease surveillance. PMDA guidelines for software as a medical device shape validation requirements for outbreak forecasting tools with patient-facing outputs. Tokyo and Osaka metropolitan governments lead deployment of real-time surveillance dashboards integrated with electronic health record pipelines from dominant hospital network vendors.
Pandemic Analytics Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with cloud infrastructure providers and health IT incumbents commanding distinct procurement channels. The market structure concentrates around vendors with pre-established federal contracting relationships and hospital network integration capabilities. Three archetypes dominate: hyperscale cloud platforms with health data services, electronic health record vendors with embedded analytics modules, and specialized epidemiological software providers with proprietary simulation engines. Competitive moves center on strategic partnerships linking genomic sequencing databases to mobility analytics, and portfolio diversification into workforce health monitoring for corporate buyers.
Within the integrated platform tier, Microsoft Corporation and Oracle Corporation exemplify divergent market positions. Microsoft anchors federal outbreak modeling contracts through Azure health data services, leveraging existing government cloud procurement vehicles. Oracle sustains hospital network dominance through electronic health record pipelines that feed real-time surveillance dashboards, creating captive demand for interoperable analytics modules. Amazon Web Services, Inc. occupies a position between these archetypes, with health agency cloud infrastructure contracts supporting third-party epidemiological software deployments.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| Microsoft Corporation |
| Amazon Web Services, Inc. |
| IQVIA Holdings, Inc. |
| McKesson Corporation |
| Health Catalyst, Inc. |
| Optum Inc. |
| Cerner Corporation |
| Others |
Supply Flow & Price Mechanics
Azure's hyperscale compute capacity anchors pricing power for federal outbreak modeling contracts, compressing unit economics for competing cloud providers while elevating price floors for specialized epidemiological software vendors serving state health departments.
Pricing Analysis
Long-term subscription contracts dominate federal procurement through CDC cooperative agreements, displacing perpetual licenses as health agencies prioritize operational expenditure alignment with emergency funding cycles. Price differentiation separates FDA-validated predictive modeling modules from visualization-only tools, with algorithmic transparency documentation commanding premiums from government buyers. Pricing pressure stems from cloud provider competition for health agency infrastructure contracts, compressing margins for mid-tier platform vendors. State health departments exhibit highest price sensitivity due to fragmented budget authority, while federal agencies absorb premium licensing for hospital catchment-level forecasting capabilities.
Supply Chain Analysis
Strategic stockpiles of epidemiological talent concentrate in the United States, Germany, and the United Kingdom, where academic medical centers feed specialized workforce pipelines into platform vendors. Raw material dependencies include genomic sequencing databases, mobility pattern feeds from telecommunications providers, and electronic health record interoperability middleware. Supply chain risk centers on single-source vulnerability for cloud compute infrastructure serving federal health agencies. Distribution runs through direct enterprise sales teams for hospital network deployments and public sector contracting vehicles for government agency procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pandemic analytics sits in early-cycle expansion as federal pandemic preparedness budgets institutionalize predictive modeling procurement beyond emergency response periods.
For Market Incumbents: Consolidate federal contracting relationships through Azure and Oracle health data services to defend against specialized simulation vendors capturing niche geographic forecasting contracts. Deepen electronic health record integration pipelines to create switching costs for hospital network buyers. Prioritize algorithmic audit trail investments to preempt EU AI Act compliance friction in European export markets. For New Entrants and Emerging Players: Anchor in mid-tier metropolitan health departments where agent-based simulation capabilities remain underpenetrated for hospital surge capacity planning. Target state jurisdictions with CDC cooperative agreement funding but limited in-house epidemiological expertise. Pursue channel partnerships with existing electronic health record vendors to bypass direct procurement barriers. For Investors and Strategic Acquirers: Specialized epidemiological software providers with proprietary simulation engines and pre-established FDA emergency use authorization pathways represent the highest-conviction acquisition archetype. Long-term viability hinges on sustained federal health IT modernization budgets and cloud migration tailwinds across state health departments. Watch for inflection when hospital network consolidation accelerates demand for interoperable analytics modules across integrated delivery systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Emergency Use Authorization Pathway | Accelerated validation timelines compress competitive moats for real-time surveillance tools during health emergencies. |
| Genomic Sequencing Database Integration | Pathogen origin tracing capabilities differentiate forecasting platforms for federal outbreak modeling contracts. |
| Cloud Infrastructure Partnership | Azure and AWS health data services anchor elastic compute procurement for state health department subscriptions. |
| Electronic Health Record Pipeline Development | Oracle's integrated data feeds create captive demand for interoperable surveillance dashboard modules. |
| Algorithmic Transparency Investment | Pre-established audit trails preempt EU AI Act compliance costs for European health agency exports. |
Methodological Framework
The analysis maps predictive modeling software, data visualization tools, dashboard applications, and reporting solutions, each validated through health agency IT directors, hospital chief medical informatics officers, epidemiological research leads, and federal procurement specialists. Primary intelligence combines structured interviews with secondary validation against FDA 510(k) filings, CDC cooperative agreement databases, HHS procurement records, and cloud provider health sector revenue disclosures. Bottom-up segment sizing triangulates with top-down federal budget allocation analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture, end-user workflow, deployment infrastructure, and application purpose. CAGRs derive from trend extrapolation of federal pandemic preparedness appropriations, health agency cloud migration rates, and hospital network consolidation patterns. Industry-specific inputs incorporate CDC data interoperability mandate implementation timelines and FDA emergency use authorization pathway utilization frequencies.
Decision-makers should treat outputs as directional under assumptions of sustained federal health IT funding and stable HIPAA regulatory frameworks; material deviation in either would warrant model refresh. Revision becomes warranted when health agency cloud procurement velocity or genomic sequencing data availability crosses threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Web Analytics Market
Analytics
Behavior Analytics Market
Analytics
Asia-Pacific Crowd Analytics Market
Analytics
Drone Analytics Software Market
Analytics
Content Analytics and Search Software Market
Analytics
Global Hadoop Big Data Analytics Market
Analytics
Voice Analytics Market
Analytics
North America HR Analytics Market
Analytics
Customer Journey Analytics Market
Analytics
Practice Analytics Market
Analytics
Capacity Management Analytics Market
Analytics
Data Wrangling Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Audio and Video Analytics Software Market
Analytics
Europe Predictive Analytics Market
Analytics
Data Mining Tools Market