
 Vietnam Data Center Power Market | 2026-2036
Vietnam Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Data Center Power Market Insights
Software-defined power management is shifting how facility operators procure and optimize electrical infrastructure across Vietnamese data centers. Schneider Electric SE leverages its integrated microgrid and energy management portfolio to anchor large-scale deployments in the north. Vertiv Group Corp competes through thermal-electrical co-design capabilities that reduce stranded capacity. Viettel IDC sustains state-backed project pipelines through captive construction and direct grid interconnection agreements.
Vietnam data center power encompasses the generation, conditioning, distribution, and backup electrical systems purpose-built to sustain continuous operations of server and storage facilities, typically requiring redundancy from N+1 to 2N configurations and operating at voltages from 380V to 480V three-phase. Uninterruptible power supply systems dominate capital allocation among power source categories due to their role in bridging generator startup intervals during grid instability. Liquid cooling is displacing conventional air cooling in high capacity deployments where rack densities exceed 30kW, creating concentrated margin pools for integrated power-thermal vendors.
Vietnam's Ministry of Information and Communications and the state utility Vietnam Electricity (EVN) shape market access through data center licensing and power allocation frameworks that prioritize projects with renewable energy offtake commitments. National technical standards on energy efficiency for information technology equipment, aligned with ISO 50001 principles, are tightening procurement specifications for imported power infrastructure. Stakeholders must monitor regulatory evolution around direct power purchase agreements and carbon accounting rules that will determine project economics and vendor selection criteria.
Market Dynamics
Software-defined power management is compressing procurement cycles and forcing facility operators to reconfigure electrical infrastructure around real-time optimization rather than static redundancy tiers. This shift is redistributing margin pools from hardware vendors toward integrated platform providers capable of orchestrating generation, storage, and distribution through unified control layers.
Growth Catalysts
- Data localization mandates:Vietnam's Ministry of Information and Communications directives require domestic data storage for specific digital service categories, compelling foreign cloud providers to establish certified facilities with compliant power architectures.
- Liquid cooling adoption:Rack densities exceeding 30kW in AI training clusters are forcing thermal-electrical co-design investments that upgrade legacy power distribution to match coolant flow rates and heat rejection capacity.
- Ho Chi Minh City demand concentration:Hyperscale commitments cluster near submarine cable landing stations and renewable energy zones, creating anchor loads that justify dedicated substations and transmission upgrades.
Market Restraints
- Generator set supply concentration:Vietnamese projects depend on imported diesel and gas turbine units from concentrated European and East Asian manufacturing bases, exposing timelines to shipping bottlenecks and currency volatility.
- Copper and silicon carbide cost exposure:Power distribution busway and wide-bandgap semiconductor prices fluctuate with commodity markets, squeezing margins on fixed-price construction contracts.
- Grid interconnection queuing:Vietnam Electricity's approval timelines for high-voltage connections extend project development cycles and delay revenue recognition for independent facility operators.
Strategic Opportunities
- Direct power purchase agreements:Regulatory evolution toward corporate renewable energy procurement would enable off-grid solar and wind integration, bypassing EVN tariff structures and improving carbon accounting.
- Northern Vietnam expansion:Bac Ninh and Hai Phong provinces offer cooler ambient temperatures and proximity to China-border fiber routes, attracting latency-sensitive workloads underserved by southern capacity.
- Modular UPS integration:Containerized uninterruptible power systems allow phased capacity deployment that matches tenant ramp schedules, reducing stranded capital in speculative builds.
Industry Challenges
- Electrical commissioning specialist scarcity:Vietnam's technical workforce lacks depth in 480V three-phase synchronization and protective relay programming for 2N redundant configurations, extending handover timelines.
- ISO 50001 certification complexity:Energy management system documentation requirements for imported power infrastructure create procurement specification mismatches between European vendors and Vietnamese integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Data Center Power Market |
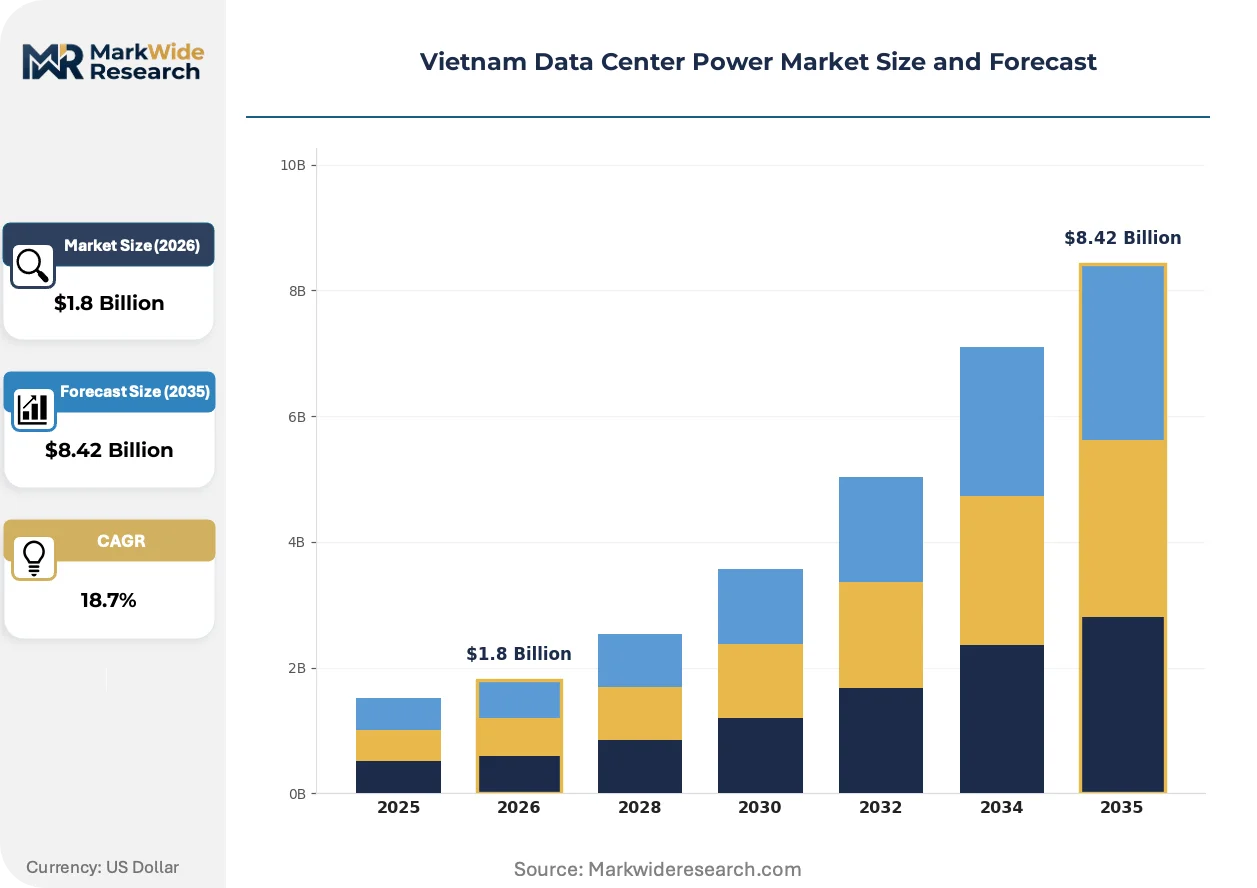
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable Energy, Diesel Generators, Grid Power, Uninterruptible Power Supply Cooling Technology: Liquid Cooling, Air Cooling, Immersion Cooling, Evaporative Cooling End User: Telecommunications, IT Services, Cloud Providers, E-commerce Capacity: Low Capacity, Medium Capacity, High Capacity, Critical Capacity |
| Companies Covered | Schneider Electric SE, ABB Ltd, Vertiv Group Corp, Eaton Corporation plc, Caterpillar Inc., Viettel IDC, VNPT, FPT Telecom, CMC Telecom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Data Center Power Market Trends and Innovations
Intelligent power infrastructure is converging with thermal management and energy storage into unified control platforms that optimize facility-level efficiency rather than subsystem performance in isolation.
Wide-bandgap semiconductors based on silicon carbide are reducing switching losses in uninterruptible power supply inverters and enabling higher power density in distribution units. Hyperscale operators in Hanoi and Ho Chi Minh City are specifying these materials for new builds to minimize cooling loads and footprint. The technology is expanding into medium-voltage power conversion for campus-scale microgrids that integrate on-site generation with utility interconnection.
Vietnam's Ministry of Information and Communications is tightening energy efficiency standards for information technology equipment through technical regulations aligned with ISO 50001 principles. These rules are elevating procurement specifications for imported power infrastructure and disqualifying legacy transformer and UPS designs that fail efficiency thresholds. Domestic facility operators are responding by pre-qualifying vendors against draft standards before final compliance deadlines.
Colocation buyers are unbundling power infrastructure procurement from facility lease agreements, negotiating direct supply contracts with electrical equipment vendors and charging infrastructure as separate service lines. This pattern fragments the traditional integrated offering of Vietnamese data center developers and transfers capex risk to tenants with specific redundancy requirements. The shift is most visible among financial services tenants in Ho Chi Minh City demanding transparent cost allocation between space, power, and cross-connect services.
Vietnam Data Center Power Market Segmentation
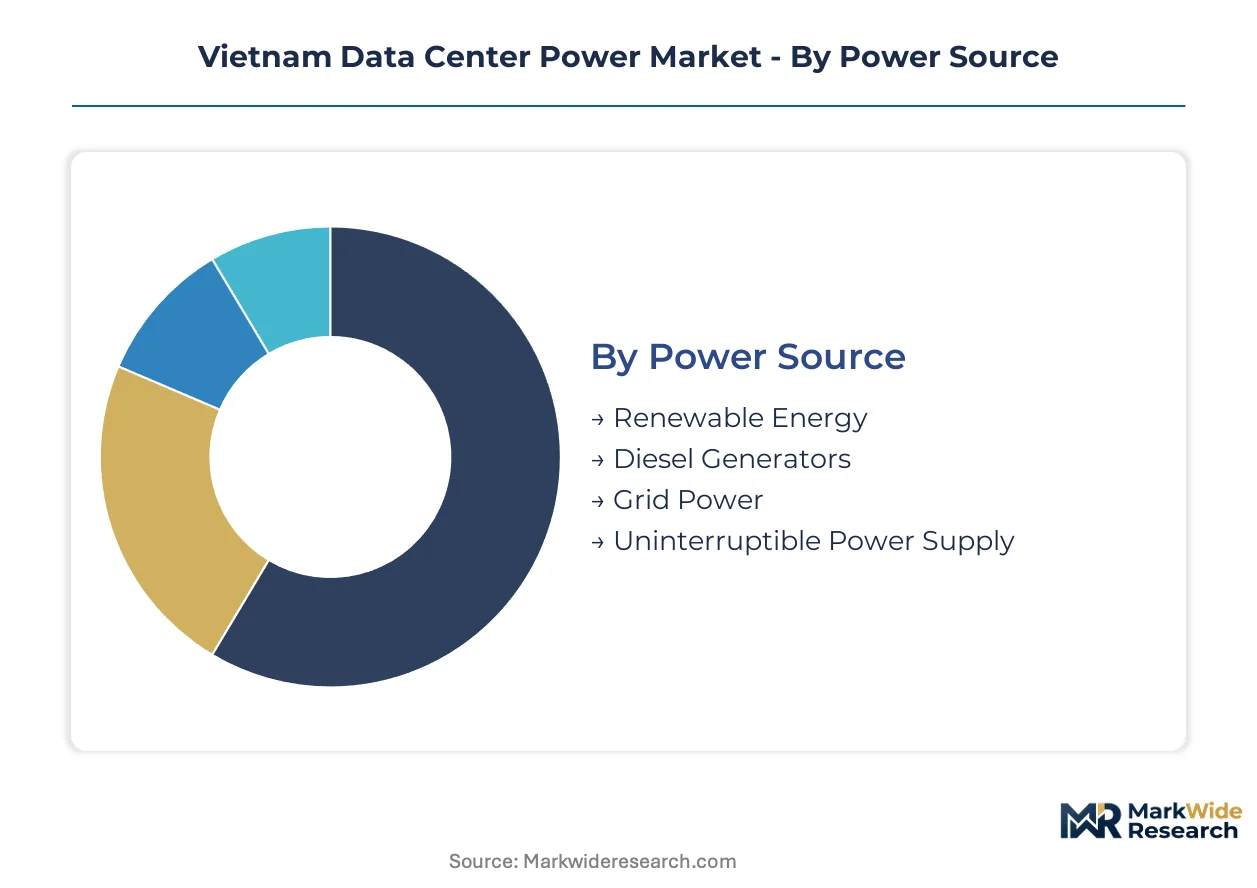
Power infrastructure procurement in Vietnamese data centers varies sharply by deployment scale and operational criticality. Segment-specific requirements determine whether operators prioritize renewable integration, thermal-electrical co-design, or modular redundancy architectures.
Power Source:
Capital intensity peaks in on-site generation assets that must bridge grid instability during tropical storm seasons.
- Uninterruptible Power Supply:Double-conversion online UPS systems dominate facility electrical rooms, conditioning power from 380V to 480V three-phase for server racks. Ho Chi Minh City hyperscale projects specify silicon carbide inverters to minimize switching losses and cooling loads during generator startup intervals.
- Renewable Energy:Solar photovoltaic and wind power purchase agreements anchor new builds near EVN transmission corridors in Binh Duong and Bac Ninh provinces. Direct corporate procurement frameworks remain under regulatory development, constraining off-grid deployment at scale.
- Grid Power:Vietnam Electricity allocates high-voltage connections based on project certification status and localization compliance timelines.
- Diesel Generators:European and East Asian manufactured gensets provide N+1 to 2N redundancy, though shipping bottlenecks extend commissioning schedules.
Most installed capacity flows through Uninterruptible Power Supply systems. Expansion is steepest in Renewable Energy procurement as carbon accounting rules tighten.
Cooling Technology:
Rack density thresholds determine whether operators deploy air-based or liquid-based heat rejection, with direct implications for power distribution sizing.
- Liquid Cooling:Cold plate and rear-door heat exchanger configurations match 30kW-plus rack densities in AI training clusters. Bac Ninh province facilities leverage cooler ambient temperatures to reduce chiller energy consumption.
- Air Cooling:Computer room air handlers and in-row cooling units serve legacy enterprise deployments below 15kW per rack, dominating Hanoi colocation stock.
- Immersion Cooling:Dielectric fluid baths enable extreme density for cryptocurrency mining and specialized compute, though chemical handling regulations limit adoption.
- Evaporative Cooling:Adiabatic systems supplement mechanical cooling in coastal zones where water availability constrains traditional tower operation.
Air Cooling retains the largest installed base. Liquid Cooling is climbing the fastest as hyperscale operators commit to high-density AI infrastructure.
End User:
Customer type dictates redundancy tiering, with financial and cloud workloads demanding 2N configurations that double electrical infrastructure capital.
- Cloud Providers:Hyperscale operators negotiate direct equipment procurement and custom substation design, unbundling power from facility leases in Ho Chi Minh City.
- Telecommunications:Viettel IDC and state-backed carriers drive northern Vietnam expansion through captive construction and direct EVN interconnection agreements.
- IT Services:Systems integrators and managed hosting providers occupy mid-tier colocation, prioritizing modular UPS for phased tenant ramp.
- E-commerce:Peak-load volatility during promotional cycles drives demand for burst capacity and rapid provisioning in southern logistics corridors.
Telecommunications accounts for the most megawatts under construction. Cloud Providers are gaining share fastest through certified facility commitments.
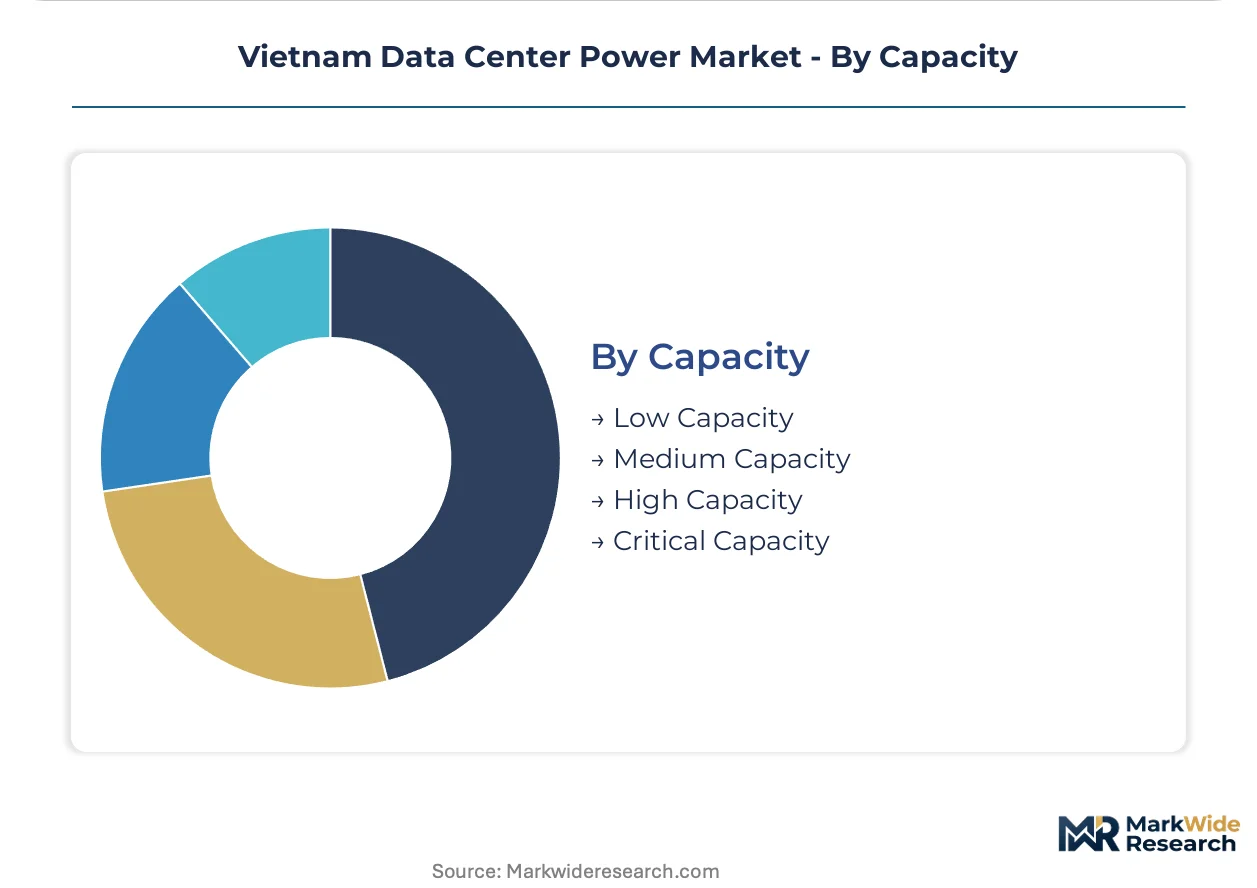
Capacity:
Scale tiering determines whether projects qualify for dedicated substations or must share grid infrastructure with industrial neighbors.
- High Capacity:Campus-scale deployments exceeding 20MW anchor near submarine cable landing stations and renewable energy zones, justifying transmission upgrades.
- Critical Capacity:Financial services and government workloads demand 2N electrical paths with isolated medium-voltage switchgear, extending commissioning timelines.
- Medium Capacity:Regional enterprise and secondary cloud nodes cluster in Da Nang and Can Tho, balancing latency against land cost.
- Low Capacity:Edge micro data centers and 5G base station aggregation points distribute across provincial cities with limited local technical workforce.
High Capacity deployments absorb the majority of 2024-2025 power equipment orders. Critical Capacity shows the steepest expansion trajectory as compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Vietnam's emerging compliance framework and mature Asian markets is redirecting hyperscale investment toward northern provinces with cooler ambient temperatures and streamlined permitting. The Ministry of Information and Communications' localization mandates create cost-of-compliance gaps that favor domestic facility construction over cross-border data residency.
Ho Chi Minh City
Hyperscale cloud commitments concentrate near submarine cable landing stations in Thu Duc City and Binh Chanh district. Vietnam Electricity allocates dedicated 110kV substations to certified facilities meeting MIC localization timelines. Renewable energy zones in neighboring Binh Duong province anchor corporate power purchase agreement negotiations for southern campus deployments.
Hanoi
Northern Vietnam's cooler climate reduces mechanical cooling loads for AI training clusters exceeding 30kW per rack. Bac Ninh province hosts Viettel IDC state-backed construction with direct EVN interconnection agreements. The Ministry of Information and Communications prioritizes licensing for facilities with ISO 50001-aligned energy management documentation.
Hai Phong
Proximity to China-border fiber routes attracts latency-sensitive financial services workloads underserved by southern capacity. Hai Phong Economic Zone offers streamlined land allocation for data center power infrastructure with 220kV grid access. EVN transmission upgrades along the Hanoi-Hai Phong corridor reduce interconnection queuing for campus-scale projects.
Da Nang
Central Vietnam's geographic position balances latency between Hanoi and Ho Chi Minh City for secondary cloud nodes and disaster recovery deployments. Da Nang High-Tech Park provides tax incentives for imported electrical equipment meeting national efficiency standards. The city's cooler coastal climate supports evaporative cooling supplementation for medium-capacity facilities.
Can Tho
Mekong Delta logistics corridors drive e-commerce edge computing demand with rapid provisioning requirements during promotional cycles. Can Tho City People's Committee fast-tracks permits for 5G base station aggregation points with modular UPS specifications. Limited local technical workforce extends electrical commissioning timelines for low-capacity distributed deployments.
Vietnam Data Center Power Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers capturing margin from hardware vendors through software-defined orchestration layers. The vendor base concentrates around electrical infrastructure multinationals with Vietnamese distribution partnerships and state-affiliated domestic operators with captive construction capabilities. Three archetypes dominate: global equipment suppliers with localized service networks, regional system integrators with EVN relationship depth, and state-backed facility operators with direct grid interconnection privileges. Competitive moves center on thermal-electrical co-design partnerships and modular UPS leasing structures that transfer capex risk to tenants.
Among global electrical infrastructure suppliers, Schneider Electric SE and Vertiv Group Corp anchor the premium equipment tier through integrated microgrid and energy management portfolios. Viettel IDC occupies a distinct position as a state-backed facility operator with direct EVN interconnection agreements and captive construction pipelines in northern provinces. Eaton Corporation plc and ABB Ltd represent the diversified industrial conglomerate archetype with broad power distribution and automation portfolios serving multinational cloud provider specifications.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd |
| Vertiv Group Corp |
| Eaton Corporation plc |
| Caterpillar Inc. |
| Viettel IDC |
| VNPT |
| FPT Telecom |
| CMC Telecom |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide inverter adoption in Vietnamese hyperscale facilities is simultaneously compressing switching losses and concentrating procurement power among integrated platform vendors capable of thermal-electrical co-design. This technology transition elevates capital efficiency for operators while squeezing margins on legacy transformer and UPS hardware that fails tightening ISO 50001-aligned efficiency thresholds.
Pricing Analysis
Distributor margins on imported electrical equipment absorb 12-18 percent of landed cost for European and East Asian manufacturers serving Vietnamese projects. Project-based contract pricing dominates facility-scale deployments, with differentiation driven by certification tier and after-sales service bundling rather than base hardware specifications. Cost compression in standard-efficiency UPS tiers is intensifying because domestic integrators face procurement specification mismatches with draft national standards. Cloud providers demonstrate lowest price sensitivity, prioritizing silicon carbide-enabled density and guaranteed availability over per-kW capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for custom substation design and containerized UPS systems, bypassing traditional electrical distribution networks. Manufacturing concentrates in Germany, Japan, and South Korea for diesel generator sets and wide-bandgap semiconductor components. Vietnamese projects draw from copper busway suppliers in China and transformer winding specialists in Taiwan. Single-source vulnerability in silicon carbide substrate supply creates commissioning timeline exposure for northern province deployments. Distribution runs through state-affiliated procurement frameworks for EVN-interconnected projects and multinational vendor direct sales for cloud provider specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam data center power infrastructure has entered a late-cycle quality phase where ISO 50001-aligned efficiency certification and silicon carbide-enabled density specifications command premium positioning. Buyers now unbundle power procurement from facility leases, transferring capex risk to tenants with specific redundancy requirements.
For Market Incumbents: Acquire electrical commissioning specialist capabilities to address workforce scarcity in 480V three-phase synchronization and protective relay programming. Secure captive supply agreements for silicon carbide substrates to mitigate single-source exposure from East Asian manufacturing concentration. Expand modular UPS leasing structures that match tenant ramp schedules and reduce stranded capital risk in speculative builds. For New Entrants and Emerging Players: Financial services tenants in Hai Phong represent an underserved buyer archetype demanding 2N configurations with transparent cost allocation between space, power, and cross-connect services. Bac Ninh province offers white-space for latency-sensitive AI training clusters leveraging cooler ambient temperatures and China-border fiber proximity. Target direct power purchase agreement facilitation as regulatory evolution enables corporate renewable energy procurement bypassing EVN tariff structures. For Investors and Strategic Acquirers: Valuations sit cheapest among regional system integrators with EVN relationship depth and ISO 50001 documentation capabilities. Long-term viability hinges on positioning for direct corporate renewable procurement frameworks and carbon accounting rule tightening. Monitor regulatory evolution around direct power purchase agreements as the inflection signal for project economics and vendor selection criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal-Electrical Co-Design Partnership | Schneider Electric and Vertiv capture margin pools from hardware vendors through integrated platform orchestration. |
| Modular UPS Leasing Structure | Containerized systems transfer capex risk to tenants while matching phased capacity deployment to ramp schedules. |
| Direct Power Purchase Agreement | Corporate renewable procurement bypasses EVN tariff structures and improves carbon accounting for hyperscale operators. |
| ISO 50001 Certification Investment | Energy management documentation secures Ministry of Information and Communications licensing priority for facility operators. |
| Northern Province Expansion | Bac Ninh and Hai Phong proximity to China-border fiber routes attracts latency-sensitive financial services workloads. |
Research Methodology
Direct dialogue with data center facility operators, electrical infrastructure procurement managers, EVN grid interconnection officers, and EPC contractors grounded qualitative findings in operational reality. Secondary validation drew from Vietnam Electricity transmission planning documents, Ministry of Information and Communications technical regulations, SEC filings of listed electrical equipment multinationals, and customs records of generator set imports. Bottom-up capacity aggregation across certified facility pipelines triangulated against top-down power equipment order flow analysis.
Bottom-up modeling segmented deployments by capacity tier, cooling technology, and end-user criticality, while top-down analysis tracked import volumes of UPS systems and diesel generator sets. Analytical lenses across the projection horizon incorporated power source mix evolution, renewable energy offtake commitment trends, and regulatory timeline assumptions for direct corporate procurement frameworks. CAGRs derived from facility pipeline aggregation and equipment order backlogs, with sensitivity testing around EVN interconnection queuing durations and silicon carbide supply availability.
Inputs from EVN planning documents and MIC regulatory drafts were available through the study window; gaps in proprietary hyperscale operator capex disclosures introduce uncertainty bands around capacity timing assumptions. Forecasts reflect documented assumptions regarding localization compliance deadlines and renewable energy zone transmission upgrade schedules. Periodic stress-testing of base assumptions is recommended as carbon accounting rules and direct power purchase agreement frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
Nigeria Data Center Power Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
Hong Kong Data Center Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Indonesia Data Center Construction Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
Asia-Pacific Data Center Power Market
Data Center Infrastructure
Dedicated Server Hosting Market
Data Center Infrastructure
Blade Server Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
Switchgear for Data Centers Market
Data Center Infrastructure
Thailand Data Center Physical Security Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
Asia-Pacific Containerized Data Center Market