
 Denmark Data Center Server Market | 2026-2036
Denmark Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Data Center Server Market Insights
The EU Energy Efficiency Directive is recalibrating the cost-of-entry calculus for data center operators entering Denmark, raising minimum performance thresholds for server infrastructure. Cisco Systems Inc leverages its networking-server integration to sustain design wins at hyperscale edge nodes. Dell Inc anchors its Nordic position through direct liquid cooling partnerships with Copenhagen-area facilities. Hewlett Packard Enterprise differentiates via in-house silicon photonics R&D that reduces interconnect power in dense rack configurations.
Data center servers are computing systems engineered for continuous operation in controlled environments, typically featuring redundant power supplies, ECC memory, and thermal designs supporting 35 kW+ per rack in liquid-cooled deployments. Their primary purpose is to host virtualized workloads, distributed storage, and containerized applications for enterprise and cloud-native services. Rack servers occupy the dominant volume position among product types, driven by standardized 19-inch form factors that simplify cable management and airflow in Danish colocation halls. Hyper-convergence leads technology adoption as Danish enterprises consolidate storage and compute into single-vendor appliances to reduce cabinet counts and licensing overhead.
BIS-equivalent Danish building codes and the EU Energy Efficiency Directive jointly govern server procurement by mandating power usage effectiveness thresholds and embodied carbon disclosures for new data center builds. The Danish Energy Agency enforces national heat reuse requirements that shape server placement and waste heat recovery system design. Stakeholders must monitor whether proposed EU chip sovereignty funding redirects Nordic hyperscaler investment toward domestic server assembly capacity versus continued Asian original design manufacturer reliance.
Market Dynamics
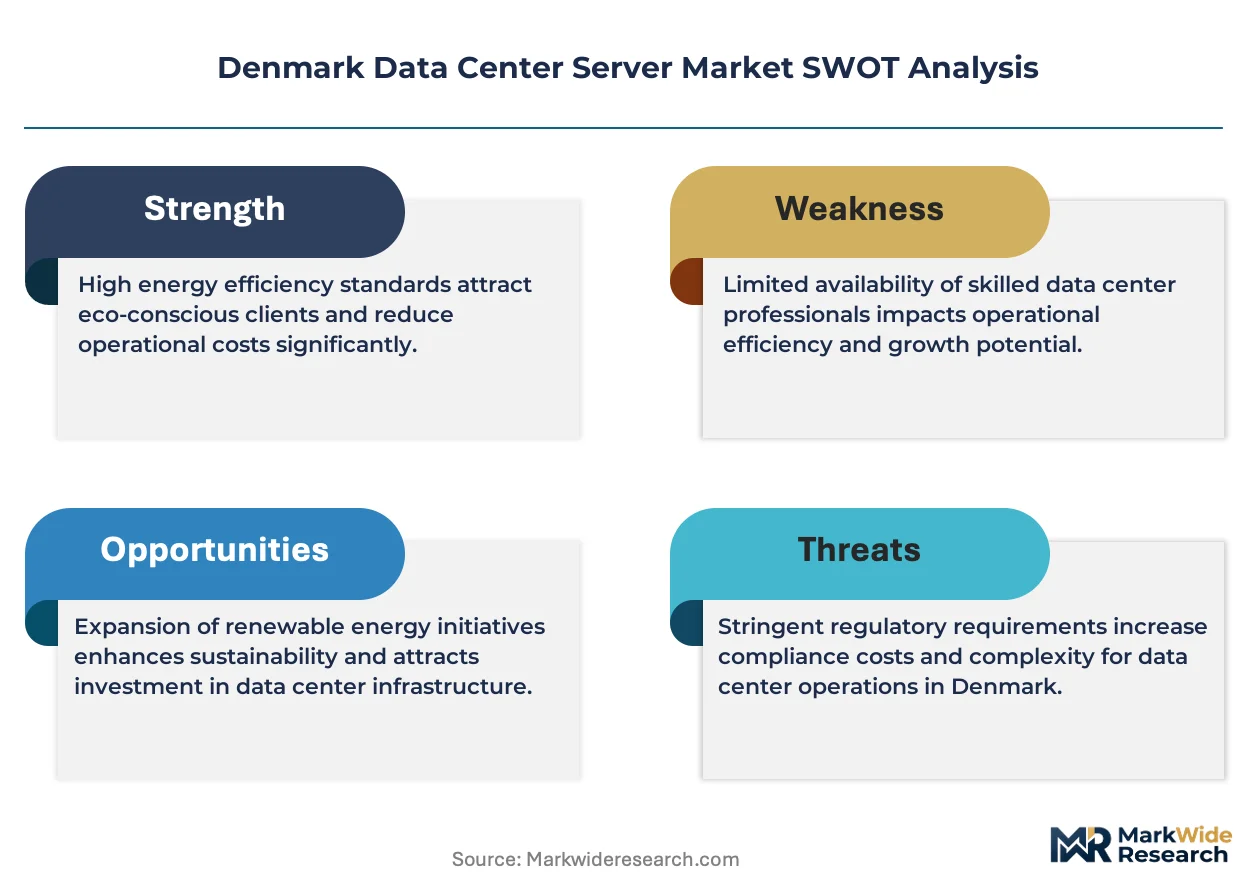
The EU Energy Efficiency Directive is compressing operational margins for Danish data center operators and redirecting capital toward liquid-cooled rack architectures that meet stricter power usage effectiveness thresholds.
Growth Catalysts
- Submarine cable landings:Copenhagen's position as a Nordic digital gateway concentrates hyperscaler demand for high-density compute infrastructure. Fiber optic capacity expansions at Bredballe and Esbjerg anchor server procurement decisions.
- Heat reuse mandates:The Danish Energy Agency requires waste heat recovery integration, creating pull for servers with elevated outlet temperatures compatible with district heating networks.
- AI workload migration:Nordic enterprises are relocating training clusters to Denmark to exploit renewable power availability and cooling efficiency advantages.
Market Restraints
- Liquid cooling capex intensity:Direct-to-chip cooling systems require 40-60% higher upfront investment than air-cooled equivalents, squeezing mid-tier colocation providers.
- Asian ODM concentration:Server assembly capacity concentrates in Taiwan and China, exposing Danish buyers to geopolitical supply disruptions and extended lead times.
- Power grid interconnection queues:Energinet's connection approval timelines for large loads now stretch 18-24 months, delaying facility commissioning.
Strategic Opportunities
- Jutland secondary clusters:Aarhus and Odense offer untapped renewable power capacity with lower land costs than Copenhagen, attracting edge compute deployments.
- Silicon photonics convergence:Integration of optical interconnects with server motherboards reduces rack-level power draw and cable complexity for dense configurations.
- EU chip sovereignty funding:Proposed subsidies for domestic semiconductor assembly could incentivize Nordic hyperscalers to localize server manufacturing.
Industry Challenges
- Liquid cooling technician scarcity:Danish facilities face acute shortages of engineers certified in coolant chemistry management and leak detection systems.
- Legacy workload migration friction:Enterprises struggle to refactor monolithic applications for containerized environments on new server generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Data Center Server Market |
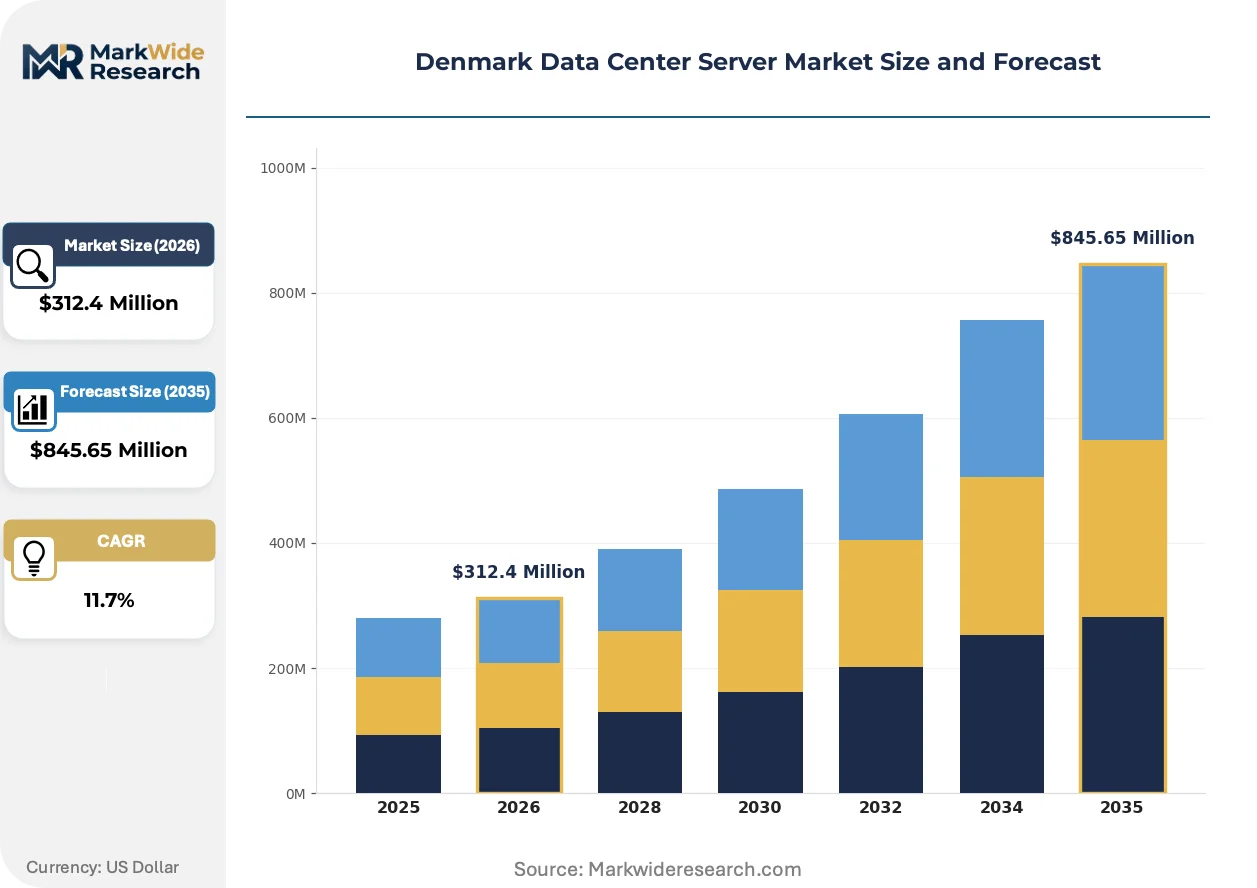
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Servers, Rack Servers, Tower Servers, Microservers End User: Cloud Providers, Enterprises, SMEs, Telecom Operators Technology: Virtualization, Hyper-Convergence, Integrated Systems, Containerization Deployment: On-Premises, Colocation, Managed Services, Hybrid |
| Companies Covered | Cisco Systems Inc, Dell Inc, Lenovo Group Limited, Kingston Technology Company Inc, Quanta Computer Inc, Hewlett Packard Enterprise, Super Micro Computer Inc, Inspur Group, International Business Machines Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Data Center Server Market Trends and Innovations
Danish data center infrastructure is undergoing rapid thermal and architectural transformation as energy mandates tighten and compute density requirements escalate.
Direct liquid cooling is consolidating rack-level thermal management by replacing air-handling units with coolant distribution networks that capture processor heat at the source. Copenhagen-area hyperscalers are adopting this technology at scale to comply with Danish Energy Agency heat reuse requirements. The shift is consolidating vendor relationships around integrated cooling-server bundles rather than discrete component procurement.
EU Energy Efficiency Directive amendments are mandating real-time power usage effectiveness monitoring and embodied carbon disclosure for new data center builds. Danish operators must now submit server-level energy consumption data to national regulators before receiving operating permits. Colocation providers are responding by standardizing on single-vendor rack architectures that simplify compliance documentation.
Danish enterprises are compressing server refresh cycles from five years to three years to exploit generational efficiency gains and avoid carbon tax penalties on older hardware. This pattern concentrates purchasing power among Copenhagen-based systems integrators with inventory financing capabilities. Financial services and pharmaceutical verticals are driving this acceleration due to ESG reporting pressures.
Denmark Data Center Server Market Segmentation
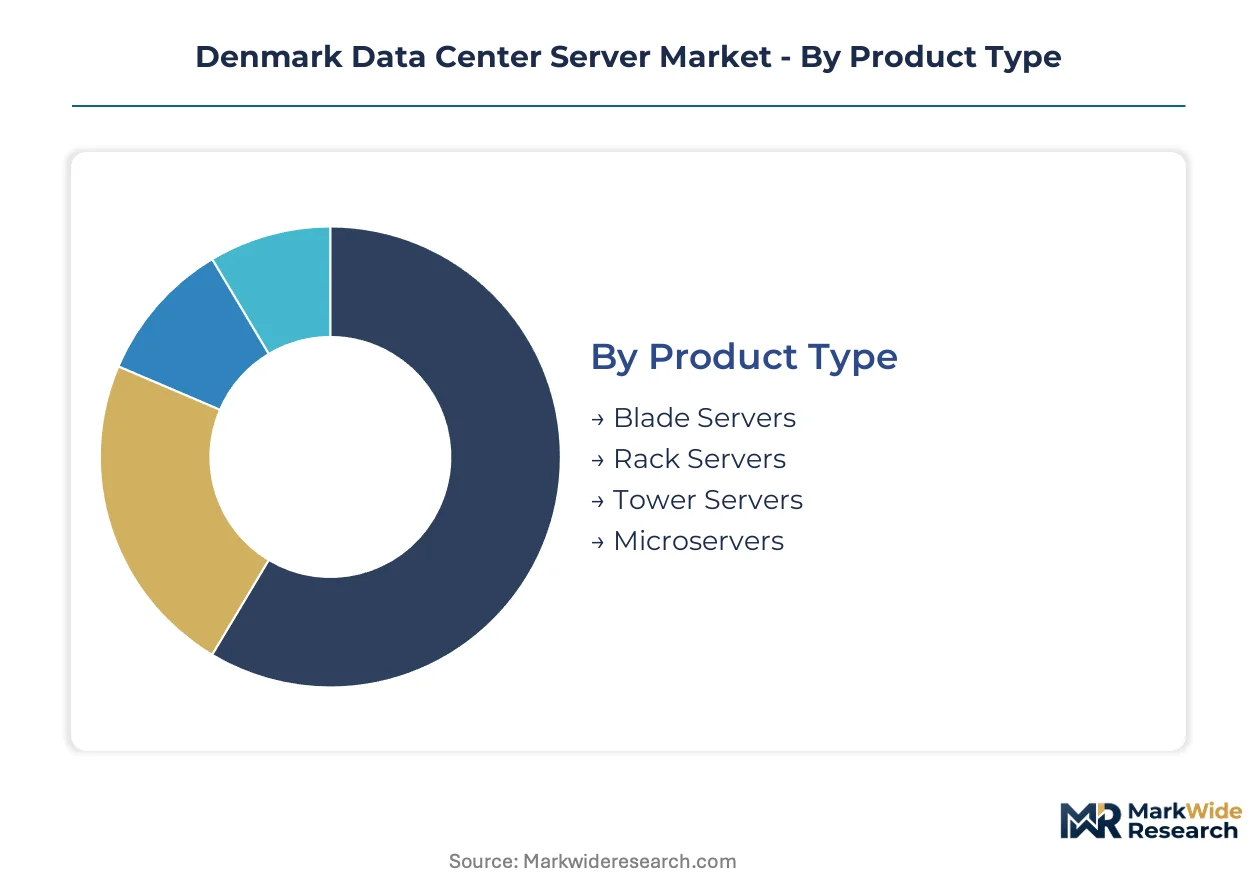
Server procurement patterns in Denmark diverge sharply across deployment footprints and workload types, with regulatory pressure on power usage effectiveness fragmenting vendor selection criteria. Understanding these segment boundaries clarifies where capital is concentrating and which configurations face obsolescence risk under tightening EU mandates.
Product Type:
Supply concentration among Taiwanese original design manufacturers favors standardized form factors that simplify logistics into Copenhagen and Esbjerg port facilities.
- Rack Servers:Standardized 19-inch chassis dominate Danish colocation halls, with configurations supporting 35 kW+ liquid-cooled densities now mandatory for new hyperscale builds. Copenhagen-area facilities procure these in volume to satisfy heat reuse integration requirements from the Danish Energy Agency.
- Blade Servers:Modular chassis with shared power and cooling infrastructure reduce cabling complexity in space-constrained urban facilities. Danish enterprises deploy these for virtualized workloads where cabinet count reduction offsets premium acquisition costs.
- Tower Servers:Standalone vertical enclosures serve remote edge locations and smaller Odense-area enterprises with limited rack infrastructure.
- Microservers:Low-power dense nodes address distributed caching and lightweight container workloads at Jutland secondary clusters.
Rack servers absorb the bulk of installed capacity; blade servers are expanding most quickly as enterprises consolidate legacy sprawl.
End User:
Customer scale determines procurement sophistication, with the largest buyers extracting custom thermal configurations unavailable to mid-tier purchasers.
- Cloud Providers:Hyperscalers command direct liquid cooling integrations and extended warranty terms from vendors. Their Copenhagen metropolitan cluster investments are reshaping server specification standards across the Nordic region.
- Enterprises:Financial services and pharmaceutical verticals in Aarhus and Odense drive accelerated refresh cycles to meet ESG disclosure deadlines and avoid carbon tax exposure on aging hardware.
- Telecom Operators:5G core network virtualization projects require edge-optimized server densities with sub-10 millisecond latency to Copenhagen aggregation points.
- SMEs:Smaller Danish businesses rely on channel-assembled configurations with standardized support tiers, limiting their access to advanced cooling integrations.
Cloud providers absorb the bulk of installed capacity; enterprises are expanding most quickly as workload migration accelerates.
Technology:
Architecture choices increasingly hinge on compliance documentation burden, with single-vendor stacks simplifying regulatory submission to Danish authorities.
- Hyper-Convergence:Unified compute-storage appliances reduce licensing overhead and cabinet counts for Danish enterprises consolidating distributed infrastructure. Copenhagen colocation providers standardize on these configurations to streamline tenant onboarding.
- Virtualization:Established hypervisor layers continue hosting legacy applications, though migration friction is forcing many Danish operators toward container alternatives for new workloads.
- Containerization:Kubernetes-orchestrated deployments are gaining share fastest among cloud-native startups and fintech clusters in the Copenhagen metropolitan area.
- Integrated Systems:Pre-validated hardware-software bundles accelerate deployment timelines for pharmaceutical and life sciences compute clusters requiring rapid qualification.
Virtualization absorbs the bulk of installed capacity; containerization is expanding most quickly among new workload deployments.
Deployment:
Facility ownership structures determine capital allocation flexibility, with outsourced arrangements shifting technology risk to operator balance sheets.
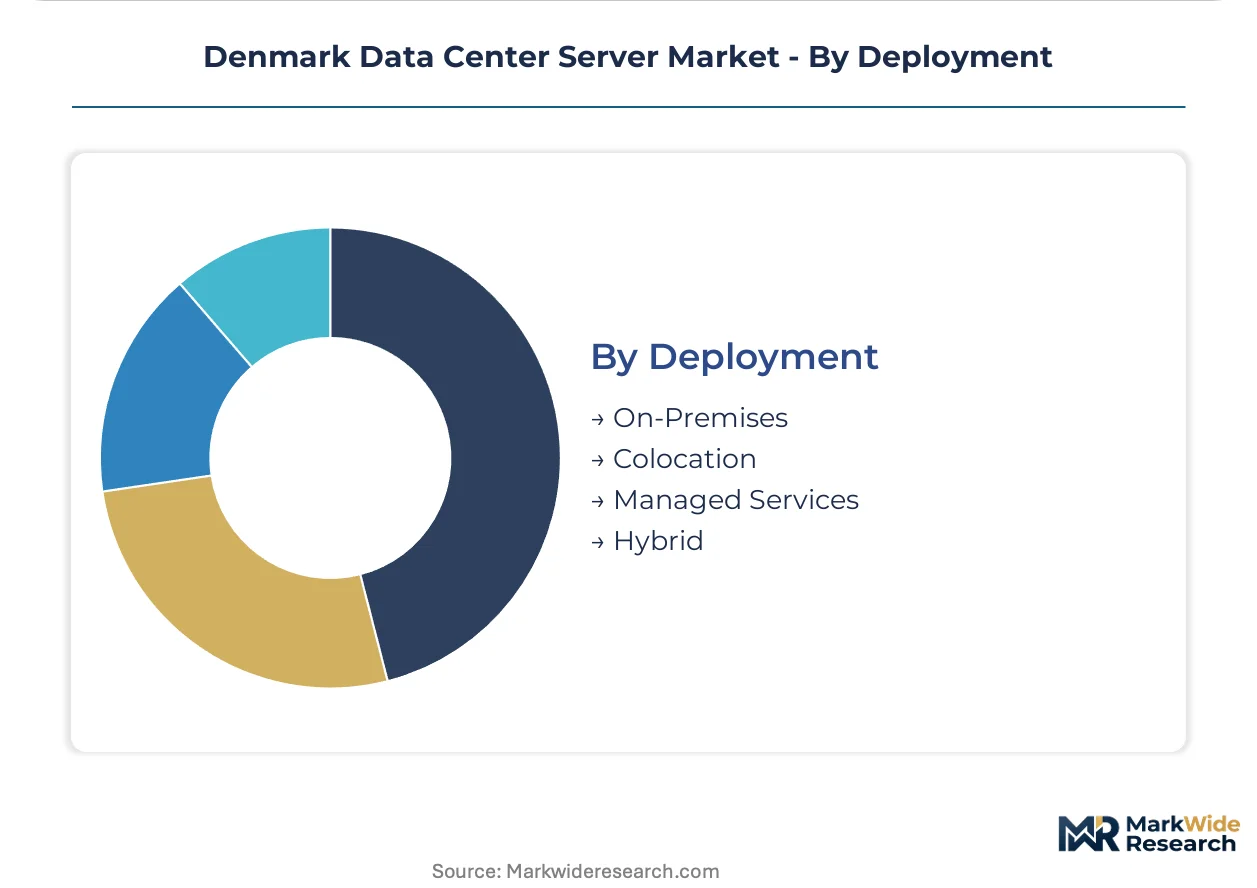
- Colocation:Third-party facilities in Copenhagen and Esbjerg offer pre-certified liquid-cooled suites that bypass 18-24 month grid interconnection queues facing self-built projects. The Danish Energy Agency's heat reuse mandates are accelerating demand for these purpose-built environments.
- On-Premises:Captive data centers persist among defense contractors and critical infrastructure operators with sovereignty requirements, though refresh cycles lag cloud-adjacent peers.
- Hybrid:Split workload arrangements allow Danish enterprises to burst AI training jobs to Copenhagen hyperscale facilities while retaining sensitive data on owned infrastructure.
- Managed Services:Outsourced server operations appeal to mid-tier enterprises lacking certified liquid cooling technicians, with providers assuming compliance liability for EU Energy Efficiency Directive reporting.
Colocation absorbs the bulk of installed capacity; hybrid deployments are expanding most quickly as workload portability becomes a procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Copenhagen metropolitan cluster anchors Danish server demand through submarine cable landings and renewable power access, while national energy efficiency mandates compress operational budgets across all sub-regions.
Capital Region
Copenhagen's position as a Nordic digital gateway concentrates hyperscaler demand for high-density compute infrastructure. The Danish Energy Agency enforces heat reuse requirements that shape server placement in Bredballe and Esbjerg facilities. Fiber optic capacity expansions anchor procurement decisions for liquid-cooled rack architectures.
Central Denmark Region
Aarhus offers untapped renewable power capacity with lower land costs than Copenhagen, attracting edge compute deployments. EU Energy Efficiency Directive amendments mandate real-time power usage effectiveness monitoring for new data center builds. Pharmaceutical and life sciences clusters drive accelerated server refresh cycles to meet ESG disclosure deadlines.
Southern Denmark Region
Odense-area enterprises with limited rack infrastructure deploy tower servers for smaller workloads while migrating larger applications to colocation facilities. The Danish Energy Agency's waste heat recovery integration requirements create pull for servers with elevated outlet temperatures compatible with district heating networks. Secondary clusters here attract mid-tier colocation providers squeezed by liquid cooling capex intensity in Copenhagen.
North Denmark Region
Aalborg's industrial base generates demand for managed server operations among enterprises lacking certified liquid cooling technicians. Energinet's connection approval timelines for large loads stretch commissioning schedules, redirecting investment toward third-party facilities with pre-certified infrastructure. Regional utilities explore waste heat capture partnerships with edge compute deployments.
Denmark Data Center Server Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Danish server market, creating a tiered structure where scale advantages meet customization capabilities. The vendor base clusters around three strategic archetypes: integrated systems vendors with cooling-server bundles, networking-centric players leveraging infrastructure convergence, and original design manufacturers supplying standardized chassis. Competitive moves concentrate on direct liquid cooling partnerships with Copenhagen-area facilities and silicon photonics R&D investments that reduce interconnect power.
Within the integrated systems tier, Dell Inc and Hewlett Packard Enterprise exemplify vendors anchoring Nordic positions through thermal innovation partnerships. Cisco Systems Inc occupies a networking-server convergence position at hyperscale edge nodes. Quanta Computer Inc represents the original design manufacturer archetype supplying standardized form factors into Danish port facilities.
| Leading Market Players |
|---|
| Cisco Systems Inc |
| Dell Inc |
| Lenovo Group Limited |
| Kingston Technology Company Inc |
| Quanta Computer Inc |
| Hewlett Packard Enterprise |
| Super Micro Computer Inc |
| Inspur Group |
| International Business Machines Corporation |
| Others |
Pricing and Supply Chain Analysis
Danish hyperscaler procurement specifications for liquid-cooled rack architectures are compressing supplier margins and forcing original design manufacturers to absorb certification costs for EU Energy Efficiency Directive compliance. This demand-side pressure concentrates pricing power among integrated cooling-server bundle vendors with Copenhagen-area facility partnerships.
Pricing Analysis
Lead-time premiums dominate Danish server procurement, with hyperscalers paying 15-25% markups for expedited delivery from Taiwanese ODMs to bypass Energinet grid interconnection delays. Three-tier pricing structure across premium liquid-cooled, standard air-cooled, and economy refurbished tiers separates buyers by thermal complexity requirements. Cost compression in mid-tier colocation is intensifying because liquid cooling capex intensity squeezes providers without Copenhagen hyperscaler scale. SMEs exhibit highest price sensitivity due to channel-assembled configuration dependence, while cloud providers absorb premiums for direct vendor integration.
Supply Chain Analysis
Reverse-logistics flows for server refurbishment are expanding as Danish enterprises accelerate refresh cycles to three years, creating secondary market supply from decommissioned Copenhagen hyperscale hardware. Assembly capacity concentrates in Taiwan, China, and South Korea, drawing from advanced packaging substrates, high-bandwidth memory modules, and silicon photonics components. Single-source vulnerability in Taiwanese ODM concentration exposes Danish buyers to geopolitical disruption and extended lead times. Distribution runs through Esbjerg and Copenhagen port facilities into colocation provider integration centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Server assembly capacity constraints in Taiwan and China prop pricing premiums for Danish buyers with secured allocation agreements, sustaining vendor margins despite operational cost pressures.
For Market Incumbents: Hedge against Asian ODM concentration by establishing secondary qualification pathways with European assembly partners and captive supply of liquid cooling components. The Danish Energy Agency's heat reuse mandates threaten vendors without integrated thermal partnerships, making backward integration into coolant distribution systems a critical defensive lever. For New Entrants and Emerging Players: EU chip sovereignty funding in Europe opens a window for domestic server assembly ventures targeting Nordic hyperscaler demand. Jutland secondary clusters in Aarhus and Odense represent the most penetrable geography, with lower land costs and untapped renewable capacity. A go-to-market angle emphasizing rapid Energinet grid interconnection bypass through pre-certified facility partnerships accelerates customer acquisition. For Investors and Strategic Acquirers: The window for entry favors liquid cooling technology specialists with Danish Energy Agency certification relationships and Copenhagen colocation operator partnerships. Long-term viability hinges on consolidation of thermal management intellectual property as rack densities exceed 35 kW. Monitor EU chip sovereignty funding disbursement timelines as the critical inflection signal for Nordic hyperscaler procurement localization.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Liquid Cooling Partnership | Copenhagen hyperscalers mandate integrated thermal bundles for heat reuse compliance. |
| Silicon Photonics R&D Investment | Hewlett Packard Enterprise's interconnect power reduction shapes dense rack configurations. |
| Secondary Cluster Expansion | Aarhus and Odense edge deployments exploit Jutland renewable capacity and lower land costs. |
| EU Chip Sovereignty Localization | Proposed subsidies could redirect Nordic hyperscaler investment toward domestic assembly. |
| Certified Technician Pipeline | Liquid cooling engineer scarcity constrains facility commissioning timelines nationwide. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, Danish Energy Agency permitting data, and EU regulatory filing timelines anchored the trend analysis, supplemented by interviews with data center facility directors, server procurement officers at Nordic cloud providers, liquid cooling system engineers, and colocation sales executives. Secondary validation drew from Energinet grid interconnection queues, Danish building code amendments, SEC filings of listed server vendors, and trade customs data through Esbjerg port authorities. Bottom-up server shipment estimates and top-down infrastructure investment flows were triangulated against facility capacity announcements.
Input-output matrices modeled server unit demand against power grid expansion, renewable energy availability, and regulatory compliance thresholds across the projection horizon. Segmentation dimensions included product type, deployment model, end-user vertical, and cooling architecture. CAGRs were derived from fitted growth curves against historical procurement patterns and announced facility investments. Forecast inputs incorporated AI workload migration velocities and district heating network expansion timelines for waste heat recovery integration.
The model assumes a particular technology adoption path; alternative pathways for immersion cooling versus direct-to-chip liquid cooling would alter the outlook for vendor market share and facility design standards. Forecasts reflect assumptions about EU subsidy disbursement schedules and Taiwanese ODM capacity expansion. Practitioners should monitor Energinet queue clearance rates and Danish Energy Agency heat reuse mandate enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Europe Data Center Power Market
Data Center Infrastructure
Asia-Pacific Hyperscale Data Center Market
Data Center Infrastructure
Composable-Disaggregated Infrastructure Market
Data Center Infrastructure
Chicago Data Center Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Multi-Tenant Data Center Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
South America Data Center Rack Market
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Data Center in Japan Market
Data Center Infrastructure
Australia Data Center Construction Market
Data Center Infrastructure
Global Edge Data Center Market
Data Center Infrastructure
Thailand Data Center Physical Security Market
Data Center Infrastructure
Data Center Blocks Market