
 Converged Infrastructure Market | 2026-2036
Converged Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Converged Infrastructure Market Analysis
Pre-validated reference architectures with bundled compute, storage, and networking components is consolidating buyer preferences away from do-it-yourself integration projects. Dell Technologies Inc. leverages its factory-integrated PowerEdge and PowerStore combinations to compress deployment timelines for enterprise data centers. Nutanix Inc. specializes in software-defined hyper-converged platforms that unify virtualization and storage management under one control plane. Hewlett Packard Enterprise Co. anchors its competitive position through GreenLake as-a-service contracts that convert capital expenditure into operational spending models.
Converged infrastructure denotes pre-integrated systems combining servers, storage arrays, networking switches, and management software into a single deployable unit, typically specified with unified APIs and policy-driven automation for resource orchestration. Hyper-converged deployments lead product type adoption by collapsing storage controllers into software running on commodity servers, while integrated systems retain dedicated hardware controllers for latency-sensitive workloads. Large enterprises dominate end-user demand as they replace siloed three-tier architectures with consolidated stacks, though government buyers are accelerating procurement for classified and sovereign cloud environments.
FCC guidelines on data center energy reporting and the EU CSRD sustainability disclosure rules are pressuring operators to document power usage effectiveness and embodied carbon in infrastructure refresh cycles. India's BIS certification requirements for imported IT equipment and the EU GDPR data residency mandates are shaping regional product configurations and local assembly decisions. Enterprises must evaluate whether hybrid deployment models or sovereign cloud partnerships better align with emerging cross-border data governance obligations.
Market Dynamics
VMware's subscription licensing pivot and the EU AI Act's data sovereignty mandates are compressing procurement cycles while forcing buyers to revalidate stack architectures against residency requirements. Large enterprises now prioritize pre-integrated systems that bundle compliance-ready configurations.
Growth Catalysts
- EU AI Act data sovereignty:Mandates for local data processing are accelerating sovereign cloud deployments across Germany, France, and the Netherlands. Government buyers specify pre-certified infrastructure stacks.
- Hyper-converged software-defined storage:Collapsing storage controllers into commodity servers reduces rack space and power draw. Financial services and healthcare verticals lead replacement cycles.
- India's data center buildout:Mumbai, Hyderabad, and Chennai clusters are absorbing integrated systems for cloud availability zones. BIS certification requirements favor locally assembled configurations.
Market Restraints
- NAND flash supply concentration:Memory controller fabrication depends on Taiwan and South Korea foundry capacity. Price volatility ripples through storage subsystem costs.
- Three-tier architecture lock-in:Legacy SAN investments in enterprise data centers create switching friction. Migration tooling gaps extend parallel operation periods.
- EU CSRD embodied carbon disclosure:Sustainability reporting rules require hardware lifecycle documentation. Smaller vendors lack supply chain traceability systems to compete.
Strategic Opportunities
- Edge computing micro-datacenters:Manufacturing and oil & gas sites need ruggedized converged nodes for real-time analytics. Latency requirements exclude centralized cloud alternatives.
- India PLI scheme incentives:Production-linked subsidies for server and storage manufacturing reduce landed costs for domestic assembly operations.
- GreenLake-style as-a-service contracts:Consumption-based pricing converts infrastructure capex into opex. Mid-market enterprises bypass internal procurement bottlenecks.
Industry Challenges
- VMware vSphere-to-AHV migration skills:Enterprise IT teams lack hypervisor transition expertise. Training timelines extend deployment schedules.
- Cross-border data governance fragmentation:India's DPDP Act, EU GDPR, and US CLOUD Act create conflicting residency obligations. Multi-region deployments require jurisdiction-specific stack configurations.
- API standardization gaps:Vendor-specific management interfaces complicate multi-vendor orchestration. Redfish and Swordfish adoption remains uneven across hardware suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Converged Infrastructure Market |
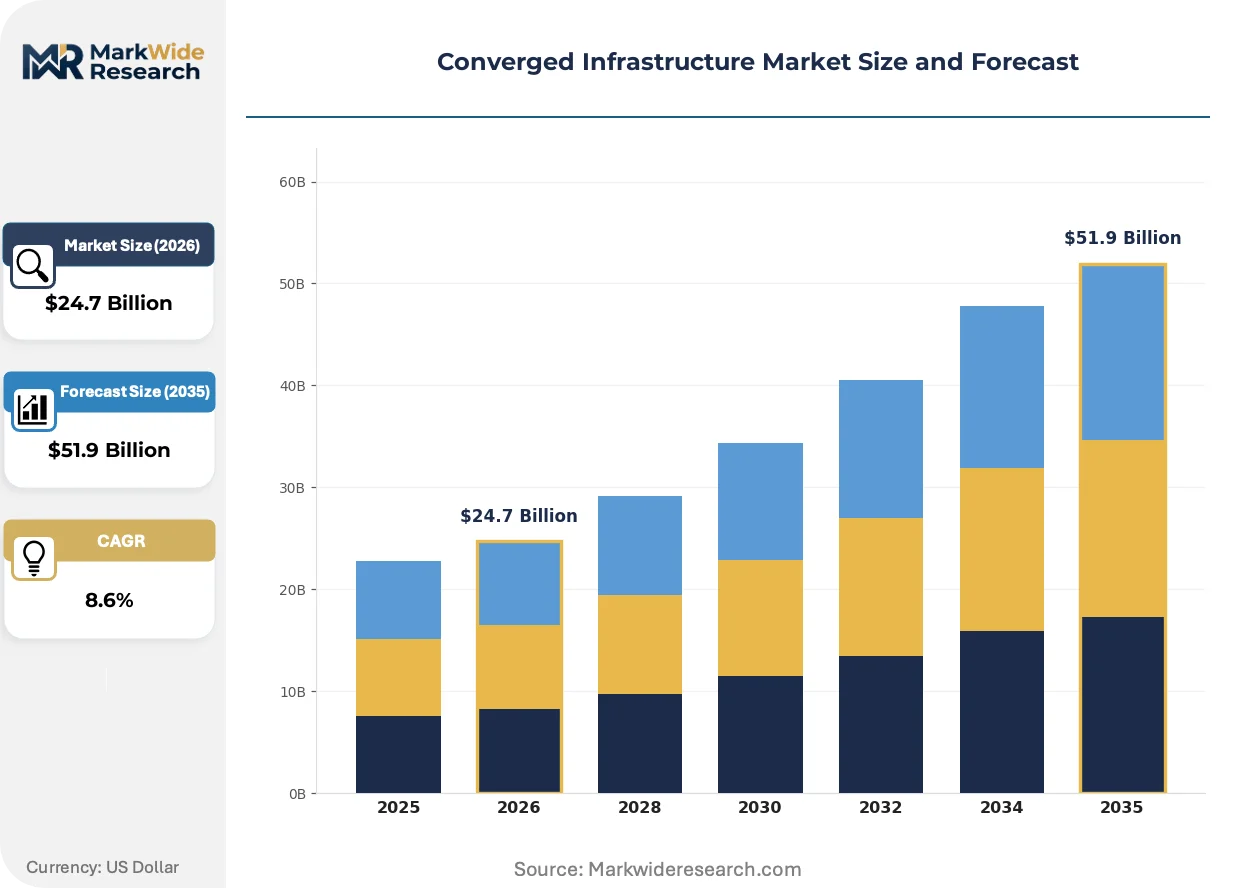
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $51.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud, Hybrid, Managed Product Type: Hyper-Converged, Converged, Integrated, Reference Architecture End User: SMEs, Large Enterprises, Government, Educational Institutions Service Type: Support, Maintenance, Consulting, Integration |
| Companies Covered | Cisco Systems Inc., Microsoft Corporation, Dell Technologies Inc., IBM Technology Corp., NetApp Inc., Nutanix Inc., VMware Inc., Super Micro Computer Inc., Hewlett Packard Enterprise Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Converged Infrastructure Market Emerging Trajectories
Disaggregated composable infrastructure is fragmenting traditional converged categories while liquid cooling integration and sovereign cloud specifications rewrite procurement criteria. Buyers now evaluate thermal design power and residency certification alongside performance metrics.
Software-defined composable infrastructure is expanding into high-performance computing and AI training clusters. Research institutions and hyperscale operators deploy PCIe fabric-attached resources that reallocate GPUs, memory, and storage dynamically. This architecture eliminates stranded capacity and compresses hardware refresh intervals from five years to eighteen-month cycles.
The EU CSRD sustainability disclosure rules are mandating power usage effectiveness reporting and embodied carbon tracking for data center operators. Infrastructure vendors must now supply granular component-level emissions data. German and French enterprise buyers prioritize systems with verified lifecycle assessments over uncertified alternatives.
Consumption-based financing models are displacing traditional capital purchase cycles for mid-market enterprises. GreenLake-style contracts bundle hardware, software, and managed services into single monthly payments. This pattern concentrates in the United States and United Kingdom where CFOs favor opex treatment for balance sheet optimization.
Converged Infrastructure Market Segmentation
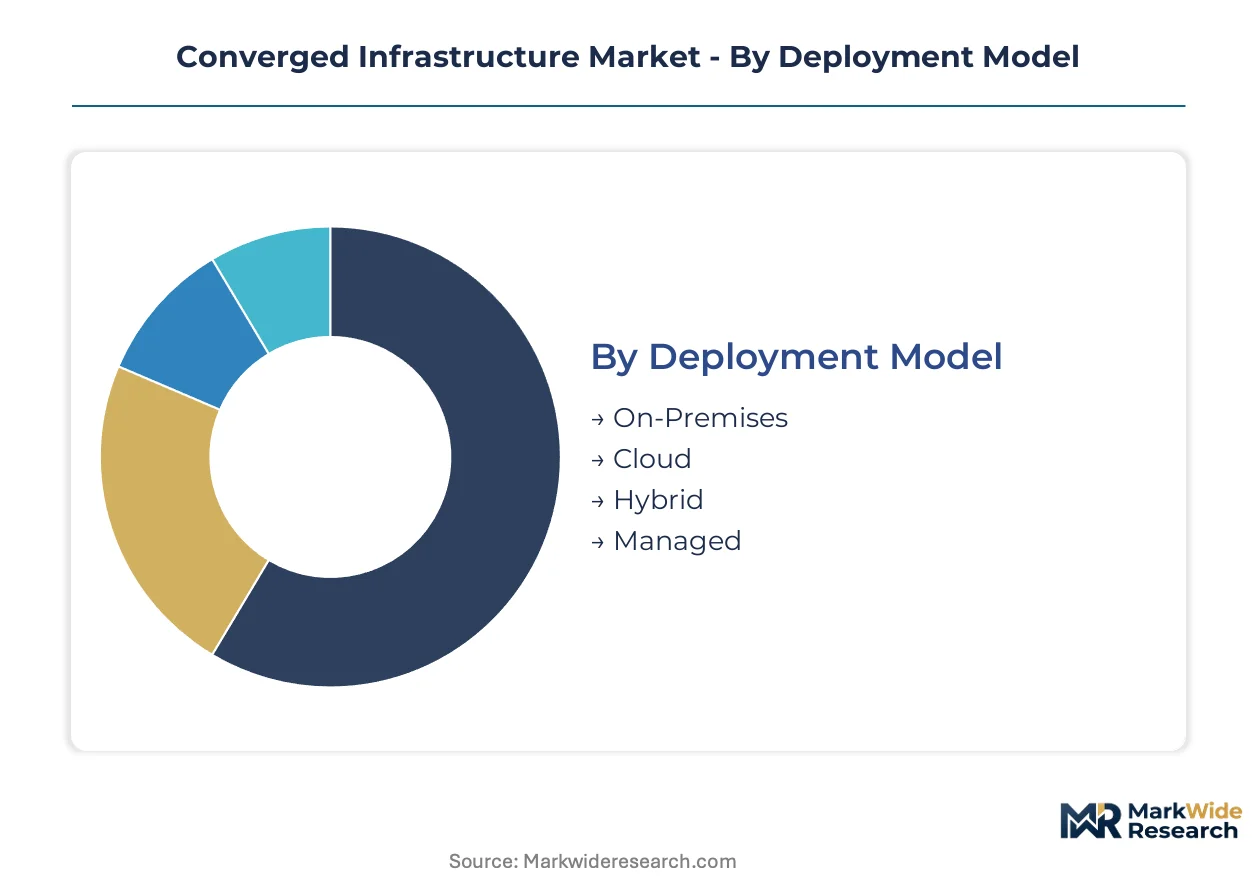
Segmentation in converged infrastructure reveals how procurement patterns split between capital-intensive ownership models and operational expenditure alternatives. Buyers navigate trade-offs between control, compliance, and cost structure across deployment architectures and service layers.
Deployment Model:
On-premises deployments demand the highest capital commitment, requiring rack space, power provisioning, and in-house operational expertise.
- On-Premises:Enterprises retain full hardware ownership within corporate data centers or colocation facilities. Financial services and defense contractors in Germany and the United States favor this model for EU AI Act and ITAR compliance.
- Cloud:Fully hosted infrastructure eliminates facility management. SaaS providers and mid-market enterprises in India leverage this to bypass BIS certification complexity for imported equipment.
- Hybrid:Workload portability across owned and rented capacity. Retailers and healthcare networks use this to keep patient records on-premises while bursting analytics to public cloud.
- Managed:Third-party operators handle hardware lifecycle and monitoring. This appeals to educational institutions lacking specialized IT staffing.
On-premises absorbs the bulk of installed capacity; hybrid is expanding most quickly as sovereignty requirements clash with cloud agility demands.
Product Type:
Product architecture determines whether storage controllers remain discrete hardware or collapse into software-defined layers.
- Hyper-Converged:Storage, compute, and virtualization fuse onto commodity servers with no dedicated SAN hardware. VMware's pivot to subscription licensing is accelerating AHV migration assessments in United States enterprise accounts.
- Converged:Pre-validated compute-storage-networking bundles ship as integrated units but retain separate hardware components. Latency-sensitive manufacturing execution systems in Germany specify these for deterministic performance.
- Integrated:Factory-assembled systems from single vendors minimize deployment risk. Indian data center operators favor locally assembled integrated stacks to satisfy PLI scheme incentives and BIS certification.
- Reference Architecture:Vendor-certified blueprints guide do-it-yourself integration. Research institutions with specialized workload requirements adopt these for customization flexibility.
Hyper-converged claims the steepest expansion trajectory; converged maintains the largest revenue base among legacy enterprise refresh cycles.
End User:
End-user scale dictates whether procurement flows through centralized IT governance or distributed departmental budgets.
- SMEs:Resource-constrained organizations prioritize opex-friendly as-a-service contracts. GreenLake-style consumption models unlock mid-market access without procurement committee delays.
- Large Enterprises:Three-tier architecture replacement drives volume. These buyers negotiate enterprise license agreements and demand API standardization across multi-vendor environments.
- Government:Sovereign cloud mandates and classified processing requirements shape specifications. EU AI Act data residency rules accelerate pre-certified stack procurement in France and the Netherlands.
- Educational Institutions:Grant-funded research computing and student-facing services create mixed demand. These buyers balance HPC cluster performance against semester-budget constraints.
Large enterprises dominate current revenue; government verticals are climbing the fastest as sovereign cloud buildouts accelerate across Germany, France, and India.
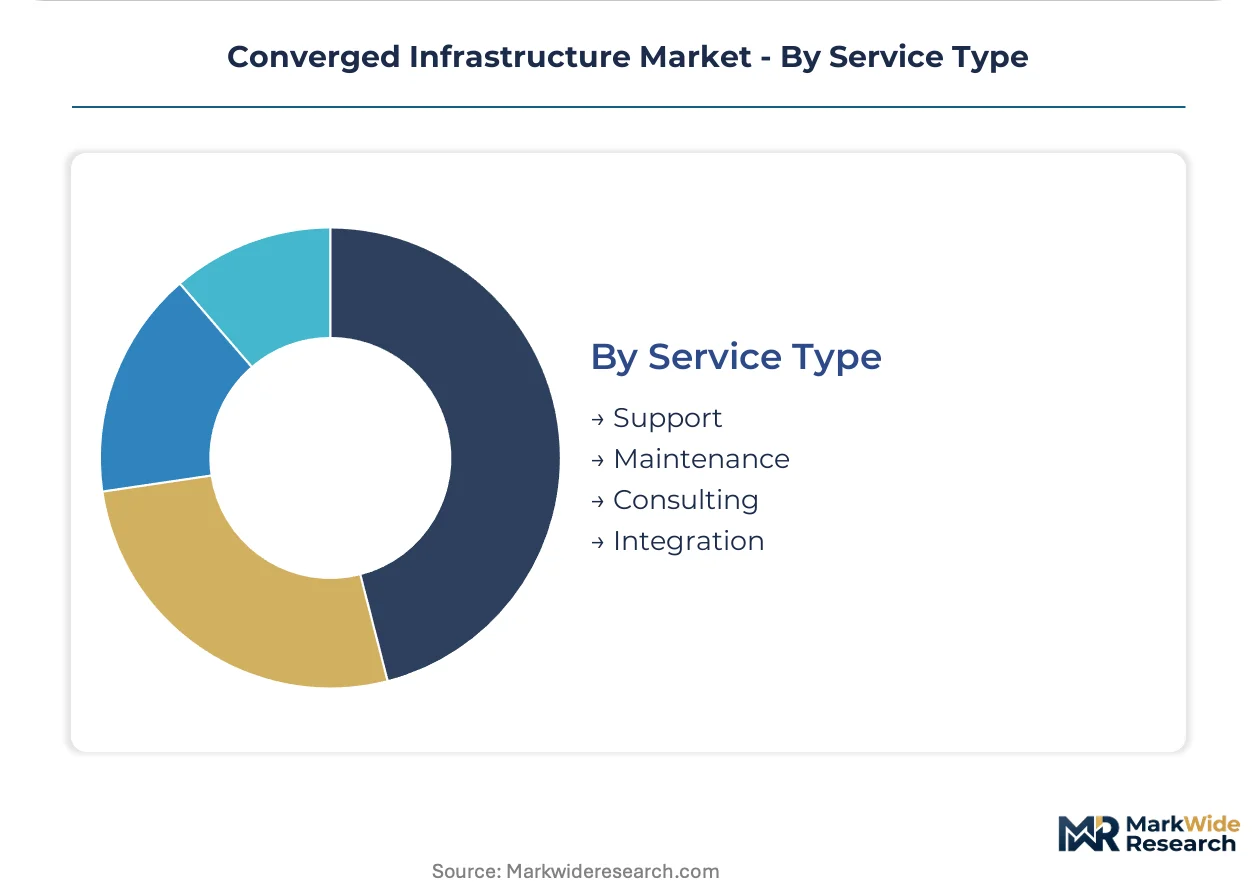
Service Type:
Service attach rates vary by buyer technical maturity and the complexity of hypervisor migration paths.
- Support:Tiered response-time contracts cover hardware replacement and software patches. Mission-critical manufacturing sites in the United States specify four-hour parts replacement guarantees.
- Maintenance:Proactive firmware updates and capacity planning prevent unplanned downtime. Healthcare networks facing HIPAA audit requirements prioritize these contracts.
- Consulting:Architecture design and workload placement optimization. VMware-to-AHV migration skills gaps are extending consulting engagement durations.
- Integration:Custom API development and multi-vendor orchestration. Financial services buyers need these for core banking system connectivity.
Support and maintenance together capture the majority of services revenue; consulting is gaining share fastest as skills shortages complicate platform transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Mumbai, Frankfurt, and Northern Virginia concentrate data center investment through tax abatements and streamlined permitting. Sovereign cloud mandates and AI Act compliance requirements are reshaping procurement patterns across these jurisdictions.
United States
Hyperscale operators and defense contractors drive demand for pre-integrated stacks with ITAR-compliant configurations. FCC energy reporting guidelines pressure operators in Northern Virginia and Dallas-Fort Worth to document power usage effectiveness. The Department of Defense accelerates classified processing deployments in Maryland and Colorado.
Germany
Automotive manufacturers and financial institutions replace legacy three-tier architectures with latency-optimized converged systems. EU AI Act data sovereignty mandates require local processing for AI training workloads in Frankfurt and Munich clusters. BSI certification requirements favor pre-certified infrastructure stacks for federal procurement.
India
Cloud availability zone expansion in Mumbai, Hyderabad, and Chennai absorbs factory-integrated systems for domestic hyperscalers. PLI scheme production-linked incentives reduce landed costs for locally assembled server and storage configurations. BIS certification requirements for imported IT equipment favor domestic assembly operations.
France
Healthcare networks and research institutions deploy sovereign cloud infrastructure to satisfy GDPR and EU AI Act residency obligations. ANSM data localization requirements shape procurement specifications for patient record processing. Île-de-France and Occitanie regions host government-certified data center clusters.
United Kingdom
Financial services firms in London and Edinburgh modernize core banking infrastructure with subscription-based consumption models. FCA operational resilience rules mandate documented recovery capabilities for critical payment systems. The Midlands and Northern England regions attract secondary data center investment for disaster recovery capacity.
Converged Infrastructure Market Vendor Landscape
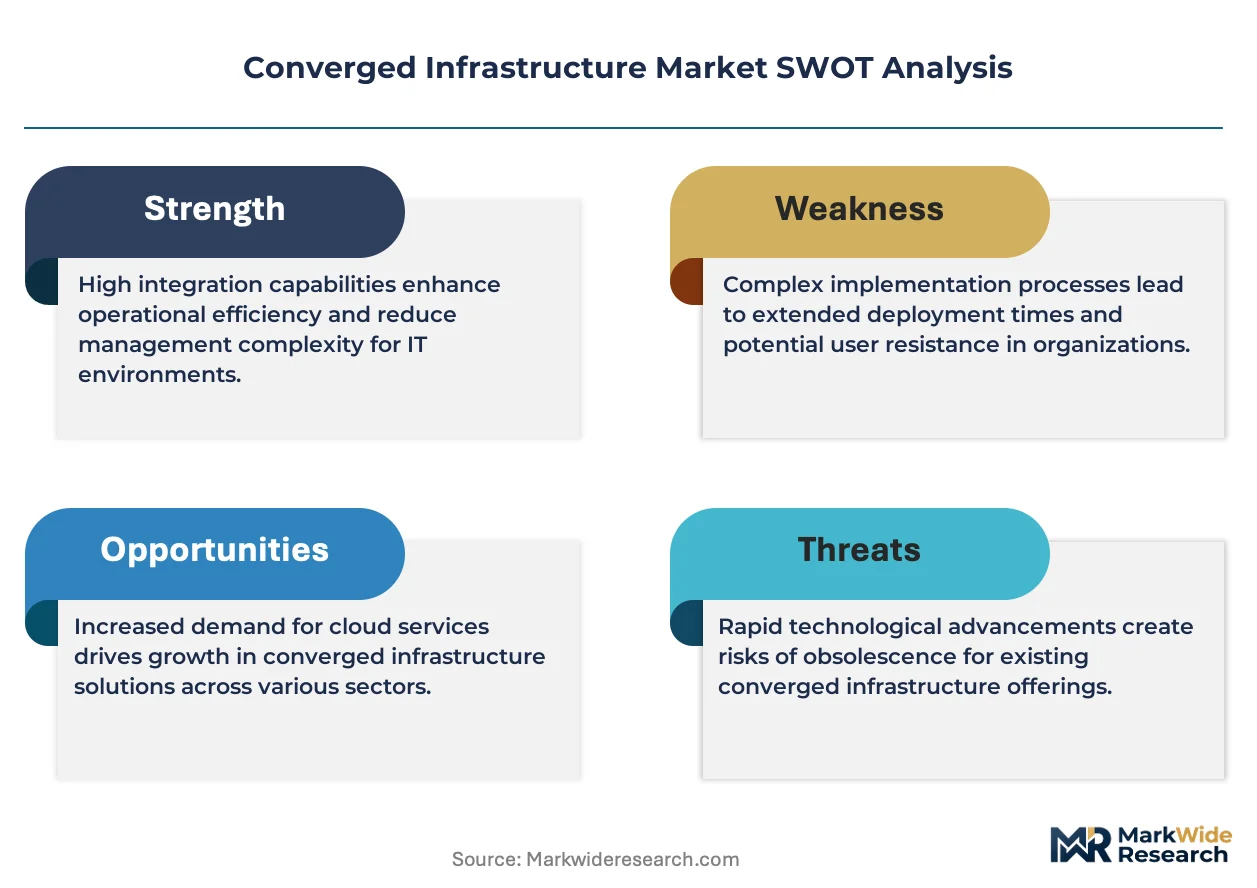
Diversified conglomerates compete with focused pure-play specialists across the converged infrastructure landscape. The vendor base spans three distinct tiers: full-stack hardware integrators, software-defined platform vendors, and component subsystem suppliers. Strategic differentiation concentrates on subscription licensing transitions and sovereign cloud certification capabilities. Competitive moves emphasize GreenLake-style as-a-service contracts and hyper-converged software migration tooling.
Among diversified technology conglomerates, Dell Technologies Inc. and Hewlett Packard Enterprise Co. occupy positions spanning integrated hardware systems and consumption-based financing models. Cisco Systems Inc. represents the networking-centric archetype with unified compute-networking fabric integration. Nutanix Inc. exemplifies the software-defined pure-play specialist focused on hyper-converged virtualization platforms. VMware Inc. sits within the virtualization layer segment undergoing subscription licensing transformation.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Microsoft Corporation |
| Dell Technologies Inc. |
| IBM Technology Corp. |
| NetApp Inc. |
| Nutanix Inc. |
| VMware Inc. |
| Super Micro Computer Inc. |
| Hewlett Packard Enterprise Co. |
| Others |
Supply Flow & Price Mechanics
EU CSRD embodied carbon disclosure mandates gate qualified supply and premium-tier pricing access by requiring component-level emissions documentation that smaller vendors cannot provide. Large enterprises in Germany and France now specify verified lifecycle assessments as procurement criteria, forcing infrastructure vendors to absorb certification costs or exit premium contract pools.
Pricing Analysis
Margin tightening in subscription-tier offerings reflects VMware's licensing pivot and the operational burden of sovereign cloud compliance engineering. Three-tier pricing structure across premium certified, standard validated, and economy reference architectures separates buyers by residency certification requirements and bundled managed service levels. Cost-down pressure on integrated hardware bundles accelerates because Indian PLI scheme subsidies compress landed costs for locally assembled configurations. Mid-market enterprises exhibit highest price sensitivity due to internal procurement bottlenecks, while defense contractors demonstrate lowest sensitivity given ITAR compliance non-negotiability.
Supply Chain Analysis
Workforce availability constraints in Taiwan and South Korea foundry clusters constrain memory controller fabrication capacity for NAND flash subsystems. Component supply concentrates in Taiwan, South Korea, and China for semiconductor fabrication, with Malaysia and Mexico hosting final assembly operations. Raw material dependencies span silicon wafers, rare earth elements for magnetics, and copper for interconnects. Single-source vulnerability around Taiwan Strait logistics chokepoints threatens storage subsystem delivery timelines. Distribution runs through direct enterprise contracts for large deployments and channel partners for mid-market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The converged infrastructure market functions as a cost-of-compliance story where EU AI Act data sovereignty mandates erect barrier-to-entry moats favoring vendors with pre-certified stack architectures.
For Market Incumbents: Deepen sovereign cloud certification capabilities across German BSI and French ANSM frameworks to defend against specialized compliance-first entrants. Invest in backward integration into liquid cooling component manufacturing to capture margin from thermal design power escalation in AI training clusters. VMware-to-AHV migration tooling represents the critical capability gap extending competitor displacement timelines. For New Entrants and Emerging Players: Cloud-native deployment channels unlock mid-market access without capital-intensive field sales organizations. Target Indian domestic hyperscalers in Mumbai and Hyderabad availability zones where PLI scheme incentives reduce incumbent cost advantages. Sovereign cloud partnerships with government-certified data center operators provide the most penetrable entry vector. For Investors and Strategic Acquirers: Accelerated government procurement timelines for classified processing environments are the leading indicator that sovereign cloud infrastructure will outperform general enterprise refresh cycles. Vertically integrated hardware-software specialists with established EU residency certifications represent the optimal acquisition archetype. Watch for BIS certification completion rates among Indian assembly operations as the signal for supply-side competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Investment | EU AI Act compliance unlocks German and French government procurement pipelines. |
| Subscription Licensing Transition | VMware's pivot forces customer retention through migration tooling and support contracts. |
| Local Assembly Operations | Indian PLI scheme subsidies reduce landed costs for BIS-certified configurations. |
| Liquid Cooling Integration | Thermal design power requirements from AI training clusters differentiate high-performance offerings. |
| GreenLake-Style As-a-Service Contracts | Consumption-based pricing converts mid-market capex barriers into recurring revenue streams. |
Methodological Framework
SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory submission databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with data center procurement officers, infrastructure vendor solution architects, and sovereign cloud program directors validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled unit shipment estimates against enterprise IT spending surveys.
Bottom-up modeling aggregated deployment volumes across on-premises, cloud, hybrid, and managed service architectures. Segmentation dimensions included product type, deployment model, end-user scale, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to validated base-year estimates. Forecast inputs incorporated VMware licensing transition timelines and EU AI Act implementation schedules.
The model holds under stable regulatory implementation timelines; deviation in NAND flash supply concentration or Taiwan Strait logistics disruption would shift capacity expansion assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
United Arab Emirates Data Center Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market
Data Center Infrastructure
Data Center Direct-to-Chip Coolant Fluids Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Rack Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Switchgear for Data Centers Market
Data Center Infrastructure
Data Center Fabric Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
Delhi-NCR Data Center Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
Germany Data Center Rack Market