
 Europe Data Center Rack Market | 2026-2036
Europe Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Center Rack Market Insights
Subscription-based thermal management and remote monitoring software is hardening into a standard component of rack procurement contracts. Schneider Electric SE leverages its integrated software stack to anchor recurring revenue alongside hardware sales. Rittal GmbH & Co. KG sustains manufacturing scale through its German production network and deep specialization in enclosure systems. Vertiv Group Corp. competes on thermal optimization technology leadership for high-density AI workloads.
A data center rack is a standardized metal framework designed to house servers, networking equipment, and power distribution units, typically measured in rack units (U) with 19-inch mounting widths and load ratings up to 1,500 kg for enterprise deployments. Its primary purpose is to optimize space utilization, cable management, and airflow in compute-intensive facilities. Enclosed racks command premium positioning due to integrated security and environmental containment features demanded by financial services and government clients. Rack-as-a-Service installations represent the fastest-expanding installation type as colocation providers seek operational flexibility without capital intensity. Open frame configurations retain cost advantages in hyperscale builds where physical security is handled at the facility perimeter.
EU Green Deal efficiency targets and the F-Gas Regulation are reshaping thermal design requirements, pushing manufacturers toward liquid cooling compatibility and lower global warming potential refrigerants. CE marking and the EU AI Act's infrastructure transparency provisions add compliance layers that filter smaller suppliers from enterprise and public sector tenders. ECHA substance restrictions on flame retardants in electronics housings further constrain material choices for enclosure producers. Stakeholders must weigh modular rack architectures against custom installations as workload density requirements diverge between cloud hyperscalers and regulated enterprise data centers.
Market Dynamics
EU Green Deal efficiency mandates and the F-Gas Regulation are compressing thermal design cycles, forcing rack manufacturers to liquid-cooling compatibility and low-global-warming-potential refrigerants ahead of legacy air-cooled architectures.
Growth Catalysts
- EU AI Act infrastructure transparency:Public sector tenders now mandate rack-level monitoring capabilities, expanding addressable demand for instrumented enclosures across government and healthcare data centers.
- Cloud service provider expansion:Hyperscale operators in Germany, France, and the Netherlands are deploying high-density configurations that require specialized load-bearing and thermal management specifications.
- Liquid cooling:Direct-to-chip and immersion systems are penetrating financial services facilities where heat density from AI training clusters exceeds conventional air-cooling thresholds.
Market Restraints
- Steel and aluminum input volatility:Enclosure fabrication costs fluctuate with commodity pricing, compressing margin buffers for mid-tier manufacturers without long-term supply agreements.
- CE marking complexity:Multi-country certification requirements for electromagnetic compatibility and mechanical safety extend time-to-revenue for new product introductions.
- Substitution by prefabricated modular data centers:Integrated factory-built solutions capture edge computing deployments that might otherwise specify discrete rack systems.
Strategic Opportunities
- Poland and Nordic markets:These geographies within Europe offer underpenetrated colocation development with favorable renewable energy profiles for sustainable rack deployments.
- Rack-as-a-Service:Operational expenditure models allow colocation providers to defer capital intensity while securing recurring thermal management and remote monitoring revenue streams.
- CSRD-aligned circular design:The Corporate Sustainability Reporting Directive creates procurement preference for recyclable aluminum enclosures and take-back programs among enterprise buyers.
Industry Challenges
- Integration with legacy raised-floor facilities:Older data centers in Frankfurt and London require structural reinforcement and power distribution upgrades to accommodate 1,500 kg load ratings.
- Flame retardant material transitions:ECHA substance restrictions on halogenated compounds force reformulation of enclosure polymers without compromising fire safety certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Center Rack Market |
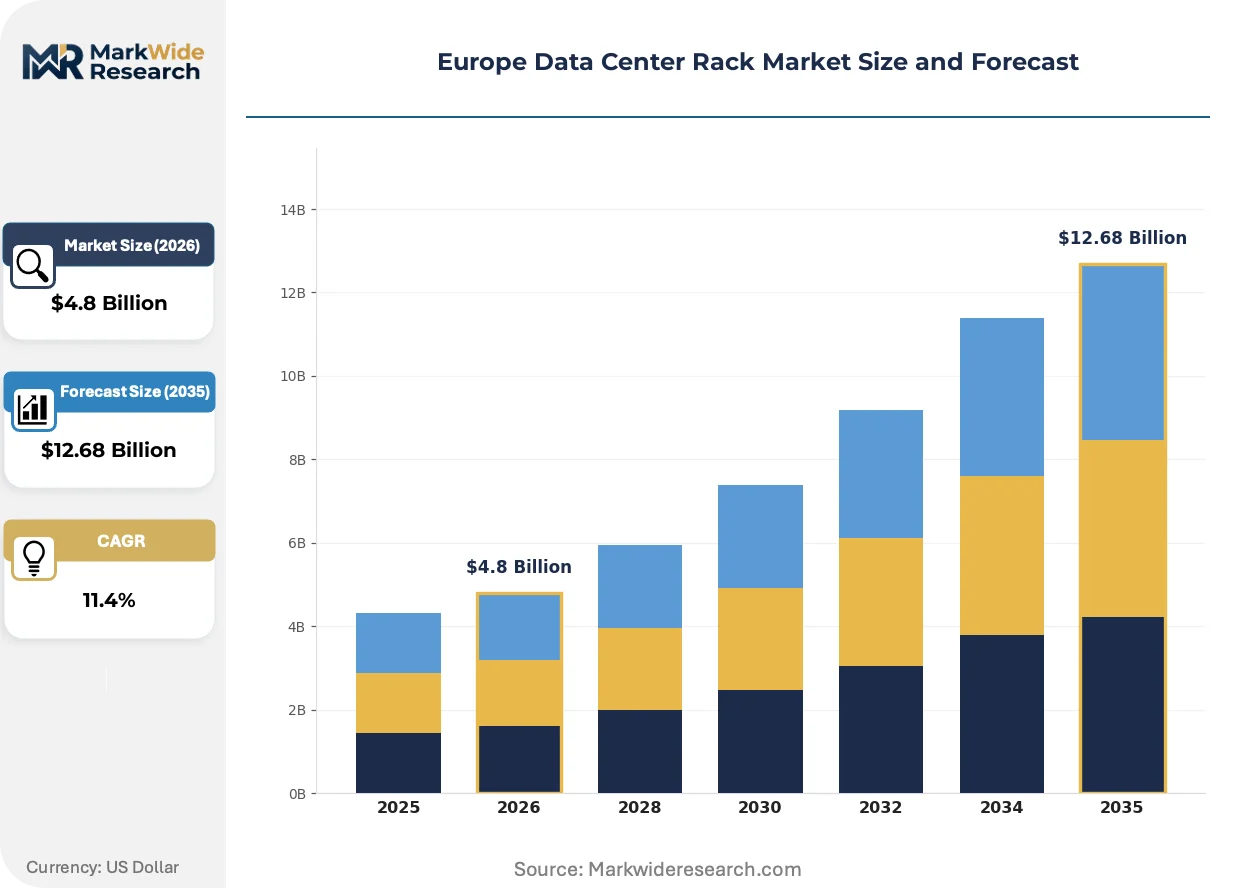
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame Racks, Enclosed Racks, Wall-Mount Racks, Rack Accessories End User: Colocation Providers, Enterprises, Cloud Service Providers, Telecom Companies Installation Type: On-Premises, Rack-as-a-Service, Modular, Custom Installation Configuration: 2U, 4U, 24U, 42U |
| Companies Covered | Rittal GmbH & Co. KG, Schneider Electric SE, Vertiv Group Corp., Legrand SA, Hewlett Packard Enterprise, Dell Technologies, Eaton Corporation plc, nVent Electric plc, Fujitsu Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Center Rack Market Trends and Innovations
Liquid cooling architectures and intelligent power distribution are converging to redefine rack-level value propositions, with software-defined thermal management emerging as the primary differentiation axis for European suppliers.
Direct-to-chip liquid cooling is integrating precision coolant distribution units with server-level cold plates, enabling 50-100 kW per rack densities. Financial services operators in London and Frankfurt are piloting these configurations for derivatives trading platforms. The technology is integrating thermal and power telemetry into unified building management systems, compressing the traditional separation between facilities and IT infrastructure teams.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in precision air conditioning units coupled to rack rows. This industrial consequence accelerates adoption of refrigerant-free liquid cooling and ambient air economization in Nordic facilities. German and Dutch colocation providers are most affected, responding with facility redesigns that eliminate compressor-based cooling from rack-adjacent infrastructure.
Colocation buyers are consolidating vendor relationships around integrated hardware-software contracts rather than discrete equipment purchases. The channel being disrupted is traditional distributor-led procurement; managed infrastructure providers are capturing specification authority. This pattern is most visible in the Netherlands, where AMS-IX proximity drives demand for fully serviced rack deployments with guaranteed thermal performance SLAs.
Europe Data Center Rack Market Segmentation
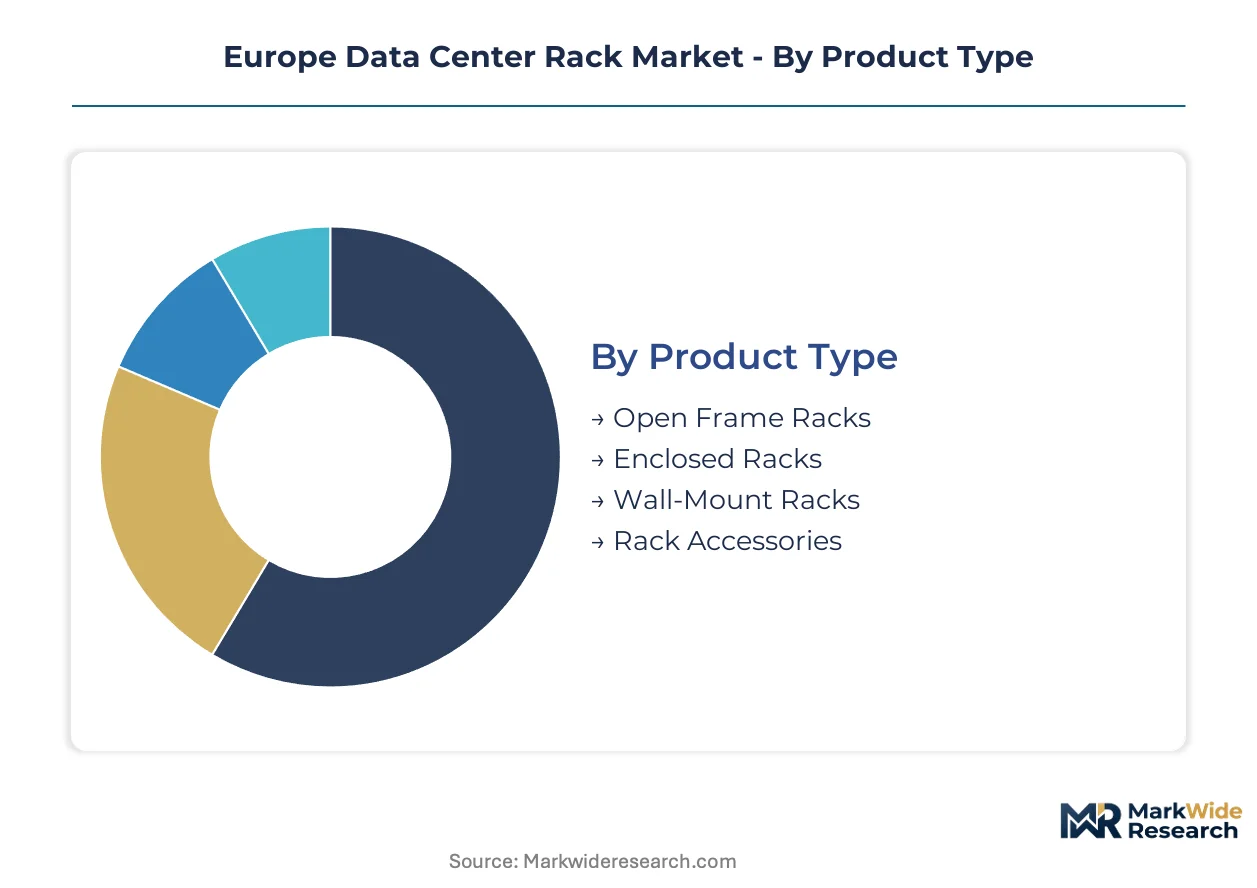
European data center rack procurement diverges sharply between hyperscale operators demanding commodity scale and regulated enterprises requiring certified, instrumented enclosures. Segmentation reveals how thermal density requirements and compliance mandates fragment specification authority across buyer types.
Product Type:
Standardization dominates at the commodity end while security-sensitive buyers drive premium enclosure complexity.
- Open Frame Racks:Four-post or two-post frameworks without side panels, optimized for airflow and cable access in hyperscale facilities. German and Dutch cloud operators deploy these for AI training clusters where facility-level perimeter security replaces physical rack barriers.
- Enclosed Racks:Lockable metal housings with integrated side panels, front/rear doors, and environmental sealing. Frankfurt financial services firms mandate these for derivatives trading infrastructure under EU AI Act transparency requirements.
- Wall-Mount Racks:Compact swing-out or fixed enclosures for network closets and edge locations.
- Rack Accessories:Cable management arms, blanking panels, and power distribution mounting kits.
Leading the category by volume: Open Frame Racks. Growing fastest: Enclosed Racks.
End User:
Procurement scale and thermal sophistication separate capital-light operators from infrastructure owners.
- Colocation Providers:Multi-tenant facility operators purchasing racks as service-delivery infrastructure. Netherlands-based operators near AMS-IX specify instrumented enclosures with guaranteed thermal SLAs to attract financial services tenants.
- Cloud Service Providers:Hyperscale operators deploying homogeneous rack fleets across regional campuses. These buyers in France and Germany drive 42U high-density configurations with liquid cooling compatibility.
- Enterprises:Corporate IT departments maintaining owned facilities.
- Telecom Companies:Carrier-neutral and integrated network operators.
Highest specification complexity: Cloud Service Providers. Expanding most quickly: Colocation Providers.
Installation Type:
Capital deployment models determine whether racks arrive as owned assets or subscribed infrastructure.
- On-Premises:Customer-owned installation within self-managed facilities. Legacy Frankfurt and London data centers require structural reinforcement for these deployments under 1,500 kg load ratings.
- Rack-as-a-Service:Operational expenditure contracts bundling hardware, thermal management, and remote monitoring. Polish and Nordic colocation markets favor this model to defer capital intensity while securing recurring revenue streams.
- Modular:Pre-integrated rack rows shipped as factory-tested units.
- Custom Installation:Site-specific engineering for non-standard footprints or legacy constraints.
Dominant by deployment count: On-Premises. Steepest expansion trajectory: Rack-as-a-Service.
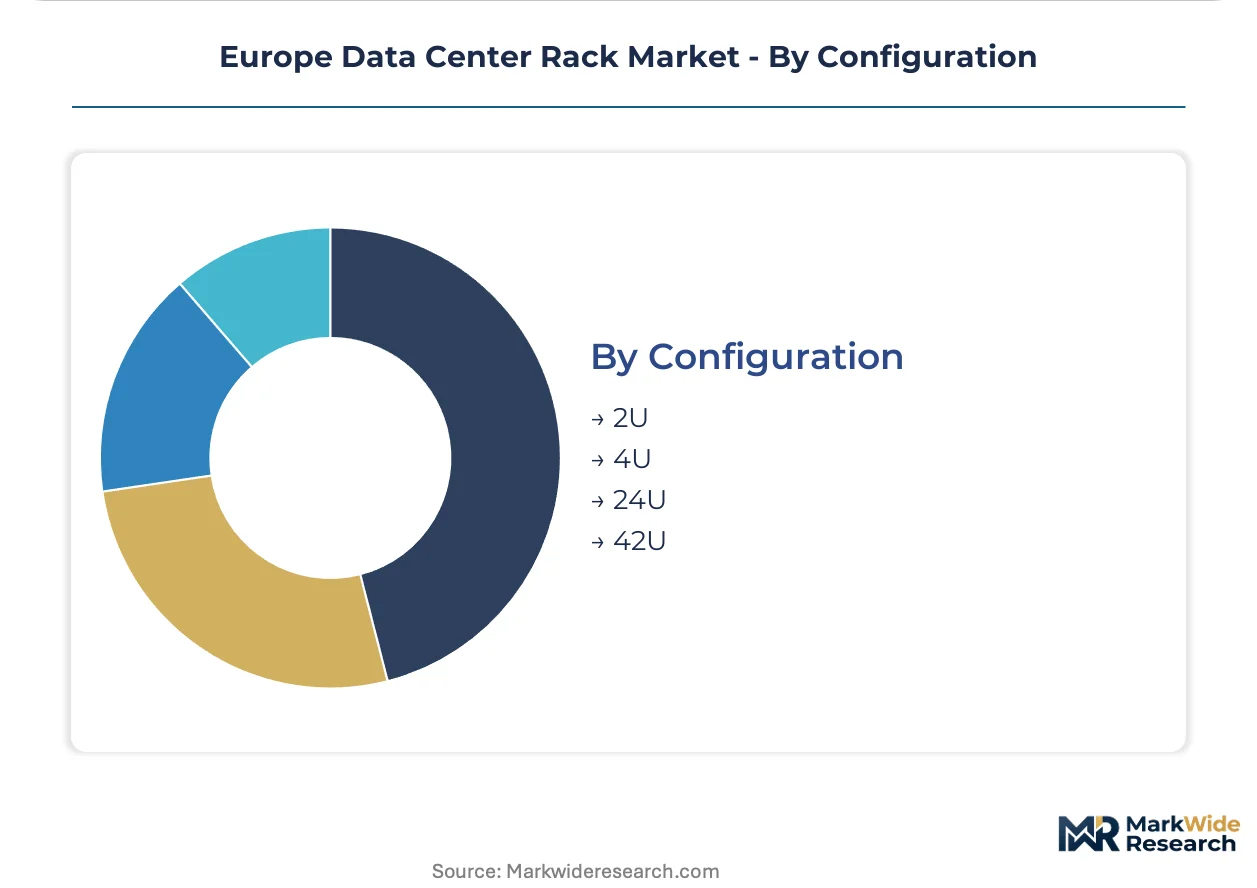
Configuration:
Vertical density correlates directly with power-per-rack requirements and cooling architecture selection.
- 42U:Full-height enterprise standard supporting 50-100 kW densities with liquid cooling integration. Financial services AI clusters in London and Frankfurt standardize on this configuration for derivatives trading platforms.
- 24U:Mid-density option balancing floor space against compute capacity.
- 4U:Compact form factor for network equipment and shallow-depth servers.
- 2U:Minimal rack unit for single-server or appliance deployments.
Highest revenue concentration: 42U. Gaining share fastest: 24U configurations in edge deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in Germany and the Netherlands supplies rack systems across Europe, while demand clusters in Frankfurt, London, and Amsterdam absorb the highest deployment volumes. Production capacity near industrial centers in North Rhine-Westphalia and Brabant feeds hyperscale and colocation buildouts. Consumption patterns split between legacy facility retrofits in established markets and greenfield expansions in emerging geographies.
Germany
Hyperscale cloud operators and financial services firms drive rack procurement in the Frankfurt Rhine-Main cluster, where AI training infrastructure demands liquid-cooled 42U configurations. The EU Green Deal and national efficiency mandates compress thermal design cycles for enclosure suppliers. Bavarian manufacturing networks around Augsburg produce precision metalwork for high-load rack systems serving derivatives trading platforms.
Netherlands
AMS-IX proximity attracts colocation providers specifying instrumented enclosures with thermal performance SLAs for multi-tenant facilities. The F-Gas Regulation accelerates refrigerant-free cooling architectures in Amsterdam and Eindhoven data center corridors. Randstad-based operators are consolidating vendor relationships around integrated hardware-software contracts rather than discrete equipment purchases.
United Kingdom
London financial services operators pilot direct-to-chip liquid cooling for AI-driven trading infrastructure exceeding conventional air-cooling thresholds. The UK Net Zero Strategy and building efficiency codes reshape thermal specifications for legacy City of London and Docklands facilities. Slough and Hayes data center clusters require structural reinforcement to accommodate 1,500 kg rack loadings.
France
Cloud service providers expand high-density configurations across Paris and Marseille campus developments, driving demand for liquid-cooling compatibility. CE marking and electromagnetic compliance requirements filter supplier participation in public sector tenders. Île-de-France colocation markets favor Rack-as-a-Service models to defer capital intensity while securing recurring monitoring revenue.
Poland
Underpenetrated colocation development in Warsaw and Kraków attracts investment seeking operational expenditure flexibility through subscribed rack infrastructure. Favorable renewable energy profiles support sustainable deployment claims under CSRD-aligned procurement preferences. Emerging data center clusters near the German border leverage cross-border connectivity while meeting EU-wide efficiency standards.
Europe Data Center Rack Market Competitive Landscape
Top-tier vendors anchor integrated hardware-software portfolios, while mid-tier fabricators compete on thermal specialization and regional manufacturing scale. The market structures around three concentration layers: multinational electrical infrastructure conglomerates, enclosure-focused specialists with captive production networks, and IT equipment OEMs extending into rack systems. Strategic moves concentrate on thermal technology licensing partnerships and backward integration into precision metal fabrication to secure margin control.
Within the integrated infrastructure tier, Schneider Electric SE and Vertiv Group Corp. exemplify vendors bundling thermal management software with enclosure hardware to capture recurring revenue streams. Rittal GmbH & Co. KG occupies a position among German-based specialists leveraging deep manufacturing scale in enclosure systems. These three represent distinct competitive archetypes: software-anchored platform vendors, thermal optimization technology leaders, and precision fabrication scale players.
| Leading Market Players |
|---|
| Rittal GmbH & Co. KG |
| Schneider Electric SE |
| Vertiv Group Corp. |
| Legrand SA |
| Hewlett Packard Enterprise |
| Dell Technologies |
| Eaton Corporation plc |
| nVent Electric plc |
| Fujitsu Limited |
| Others |
Pricing and Supply Chain Analysis
Captive manufacturing networks in Germany and the Netherlands anchor supply positions for European rack producers while underwriting pricing power through precision metalwork capabilities and proximity to hyperscale demand clusters.
Pricing Analysis
Cost-down pressure on mid-tier enclosure fabricators accelerates because steel and aluminum input volatility erodes margin buffers without long-term supply agreements. Three-tier pricing structure across premium instrumented racks, standard enterprise enclosures, and commodity open-frame configurations separates buyers by certification grade and thermal monitoring integration. CE marking complexity and EU AI Act compliance requirements filter smaller suppliers from public sector tenders, compressing competitive intensity at the premium tier. Cloud service providers exhibit lowest price sensitivity due to homogeneous fleet procurement scale, while Polish and Nordic colocation operators prioritize operational expenditure flexibility over upfront capital minimization.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale buyers mandate multi-supplier qualification across German, Dutch, and Czech manufacturing networks to mitigate single-source vulnerability. Enclosure fabrication draws from cold-rolled steel mills in North Rhine-Westphalia, aluminum extrusion facilities in Bavaria, and precision stamping operations in Brabant. Commodity price volatility in base metals represents the dominant structural risk, compressing fabrication margins during input spikes. Distribution runs through direct OEM relationships with cloud operators and colocation providers, bypassing traditional distributor channels as managed infrastructure providers capture specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision metalwork capacity scarcity in certified European fabrication networks props pricing for compliant enclosure suppliers against commodity import alternatives.
For Market Incumbents: Deepen thermal software integration to anchor recurring revenue streams against hardware commoditization pressure from Asian competitors. Secure captive aluminum supply through backward integration into Bavarian extrusion networks. Invest in liquid-cooling compatibility certification ahead of F-Gas Regulation enforcement timelines to defend specification authority in Frankfurt and Amsterdam financial services tenders. For New Entrants and Emerging Players: Capture underpenetrated Polish and Nordic colocation markets through Rack-as-a-Service operational expenditure models that defer customer capital intensity. Target Warsaw and Kraków greenfield developments where renewable energy profiles support CSRD-aligned procurement preferences. Lead with integrated remote monitoring software bundled into thermal management contracts rather than discrete hardware sales. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to electrical infrastructure conglomerates seeking thermal technology capabilities. Long-term viability hinges on software-defined thermal management differentiation rather than commodity enclosure fabrication. Monitor hyperscaler capital expenditure disclosure patterns as the inflection signal for rack procurement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Compatibility Investment | Positions suppliers for EU F-Gas Regulation compliance and AI workload density requirements in Frankfurt. |
| Software-Defined Thermal Management Development | Captures recurring revenue streams through remote monitoring subscriptions alongside hardware sales. |
| Poland and Nordic Geographic Expansion | Accesses underpenetrated colocation markets with favorable renewable energy profiles for sustainable deployments. |
| CSRD-Aligned Circular Design Program | Meets Corporate Sustainability Reporting Directive procurement preferences for recyclable aluminum enclosures. |
| Rack-as-a-Service Model Launch | Defers customer capital intensity while securing long-term thermal management and monitoring revenue streams. |
Research Methodology
Independent corroboration across primary interviews with data center facility managers, colocation procurement directors, and thermal engineering specialists underwrites the qualitative findings. Secondary validation draws from hyperscaler capital expenditure disclosures, EU regulatory filings documenting F-Gas and AI Act implementation, and customs data tracking aluminum and steel trade flows. Bottom-up rack deployment estimates triangulate against top-down data center construction pipeline assessments across the analysis window.
Comparable-period anchoring to historical hyperscale facility commissioning timelines establishes the forecast framework baseline. Segmentation modeling spans product type, installation model, configuration density, and end-user archetype across the projection horizon. CAGRs derive from facility power density trajectories, liquid cooling penetration curves, and regulatory compliance cost absorption rates. Forecast inputs incorporate EU Green Deal efficiency mandate enforcement schedules and cloud operator regional expansion commitments.
The model holds under steady EU regulatory enforcement and sustained hyperscale capital deployment; deviation in commodity metal pricing volatility or F-Gas Regulation timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
United Arab Emirates Data Center Power Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
Data Center Fabric Market
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
New Zealand Data Center Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Global Data Center Rack PDU Market
Data Center Infrastructure
DC Powered Servers Market
Data Center Infrastructure
Jakarta Data Center Market
Data Center Infrastructure
Poland Data Center Construction Market
Data Center Infrastructure
United Kingdom Data Center Physical Security Market