
 Mumbai Data Center Market | 2026-2036
Mumbai Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Mumbai Data Center Market Insights
India's Digital Personal Data Protection Act is pivoting compliance costs upward for new entrants. STT GDC India leverages its Panvel hyperscale campus to anchor wholesale capacity. CtrlS Datacenters sustains dominance in tier-4 certified facilities. Yotta Infrastructure positions its Navi Mumbai campus as a dedicated AI and cloud node.
A data center is a dedicated facility housing computing infrastructure with redundant power, precision cooling maintaining 18-27°C, and cross-connect fiber density exceeding 500 strands per suite, designed to ensure continuous availability for enterprise and consumer digital services. Colocation commands the largest revenue share as enterprises exit owned facilities. Cloud services represent the fastest-expanding product type, driven by SaaS providers seeking edge proximity to Mumbai's financial district. Hybrid deployment architectures are capturing margin pools from regulated BFSI clients requiring on-premises control with burst elasticity.
MeitY's data localization directives and BIS standards for IT infrastructure shape facility design and certification pathways. TRAI's cloud services framework and Maharashtra's industrial power tariff policies influence site economics and interconnection pricing. Stakeholders must monitor evolving state-level land-use clearances and renewable power purchase obligations that will determine build-out velocity in the Mumbai metropolitan region.
Market Dynamics
Data localization mandates under India's Digital Personal Data Protection Act are forcing enterprises to migrate workloads from foreign cloud regions to domestic facilities, compressing deployment timelines and reshaping capacity planning across the Mumbai metropolitan region.
Growth Catalysts
- Financial Services Expansion:BFSI institutions are scaling captive and third-party colocation footprints to meet RBI data residency requirements for payment systems and customer records.
- Edge Computing Proximity:SaaS providers are establishing Mumbai nodes to reduce latency for Maharashtra's enterprise base and western India consumer markets.
- AI/Cloud Convergence:GPU-intensive training clusters are driving demand for high-density cooling and specialized power configurations in Navi Mumbai facilities.
Market Restraints
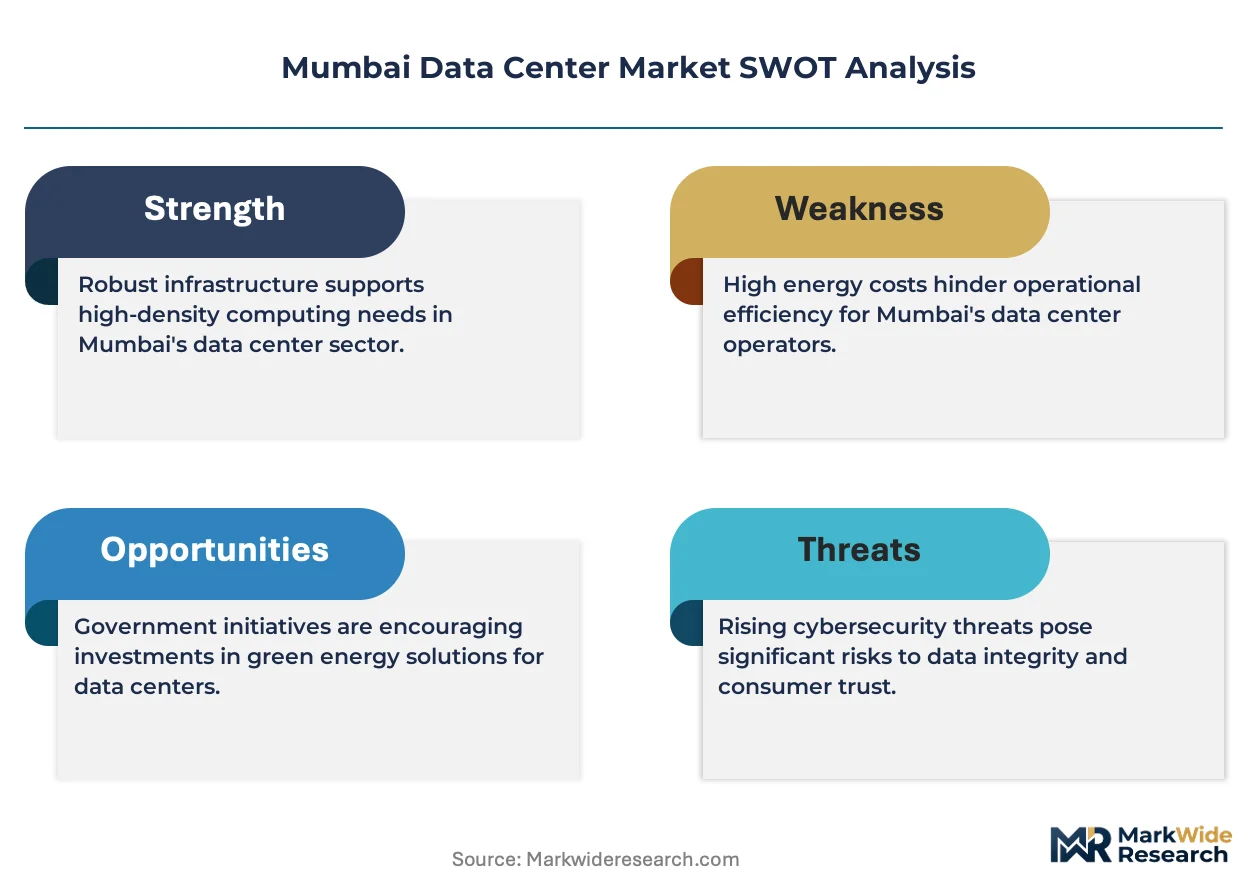
- Land Scarcity Premium:Mumbai's constrained real estate market pushes facility costs 40-60% above comparable Indian metros, elevating total cost of ownership for operators.
- Power Infrastructure Bottlenecks:Maharashtra State Electricity Distribution Company Limited's transmission constraints in Thane-Bhiwandi corridor limit rapid megawatt-scale expansion.
- Skilled Technician Shortfall:Certified data center engineering talent pools in Mumbai lag facility build-out velocity, extending commissioning timelines.
Strategic Opportunities
- Renewable Power Arbitrage:Maharashtra's solar-wind hybrid purchase obligations create cost differentiation for operators securing green tariffs ahead of renewable mandates.
- Government Cloud Migration:MeitY's cloud-first directives for central and state agencies are opening dedicated sovereign facility requirements.
- Liquid Cooling Adoption:Direct-to-chip and immersion technologies are enabling 50kW+ rack densities for AI training workloads, commanding premium pricing structures.
Industry Challenges
- Tier-4 Certification Bottlenecks:Uptime Institute's rigorous fault-tolerance assessments extend design-to-operation cycles by 8-14 months for mission-critical financial clients.
- Legacy System Integration Friction:Mainframe-dependent BFSI institutions face complex workload orchestration when bridging on-premises infrastructure with cloud-adjacent colocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mumbai Data Center Market |
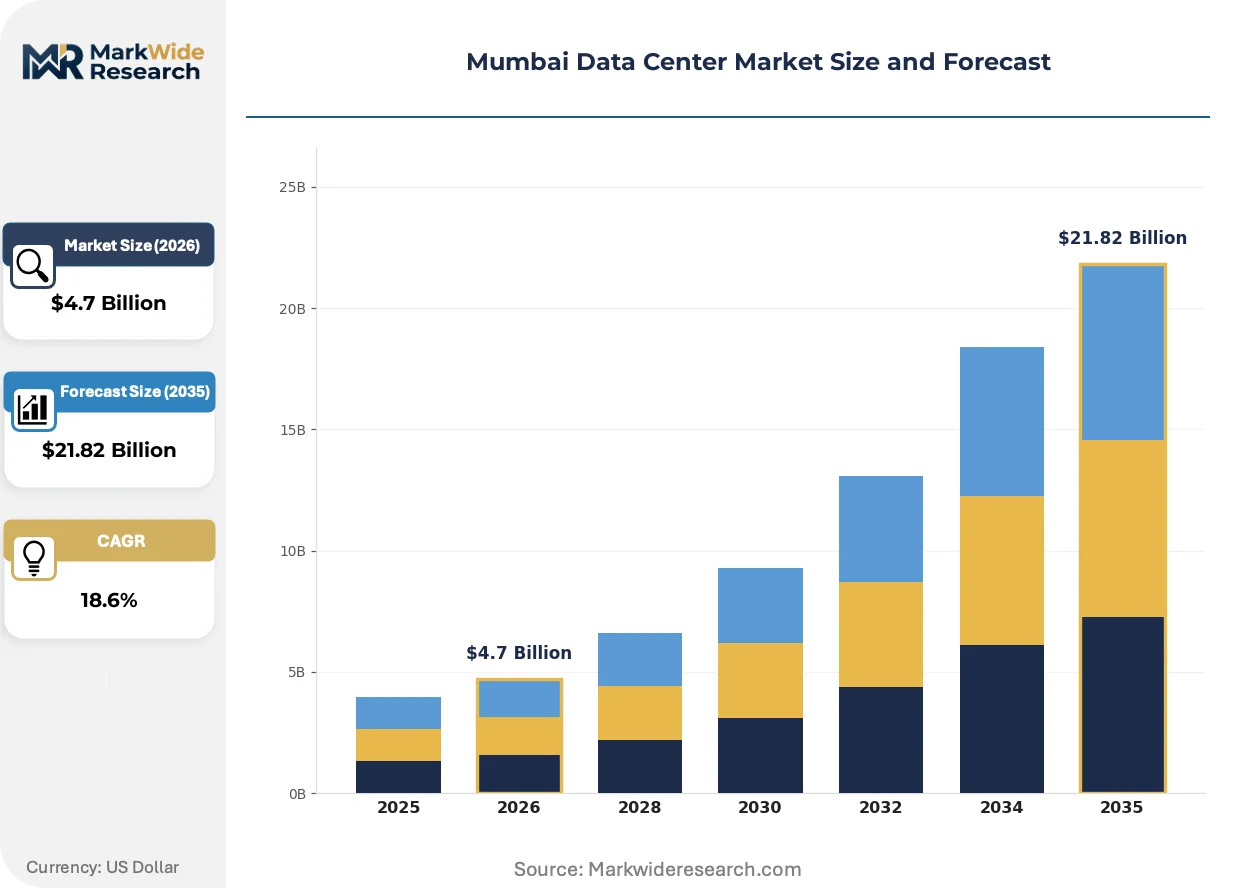
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Managed Hosting, Cloud Services, Disaster Recovery End User: Telecommunication, BFSI, IT Services, E-Commerce Deployment: On-Premises, Off-Premises, Hybrid, Edge Solution: Infrastructure as a Service, Platform as a Service, Software as a Service, Others |
| Companies Covered | STT GDC India, CtrlS Datacenters, Sify Technologies, NTT Global Data Centers, Equinix India, Yotta Infrastructure, AdaniConneX, Nxtra Data, Reliance Jio, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mumbai Data Center Market Trends and Innovations
Facility architecture is pivoting from generic compute housing to specialized AI infrastructure, with cooling density and power delivery becoming primary competitive differentiators rather than raw square footage.
Direct liquid cooling is electrifying rack-level thermal management in Mumbai's hyperscale campuses. The technology circulates dielectric fluid through cold plates mounted directly to GPU and CPU packages. Financial services AI labs and generative model training operations are adopting this at 30-40kW per rack and beyond. Traditional air-cooled designs are compressing into legacy tiers as liquid-cooled facilities capture premium tenancy contracts.
India's BIS IT infrastructure standards are mandating seismic zone III compliance and redundant substation connectivity for new certifications. These requirements are elevating capital intensity for greenfield projects. Operators are responding with modular prefabricated designs that factory-integrate power and cooling skids to accelerate compliance timelines.
Consumption-based power pricing is displacing flat-rate colocation contracts across Maharashtra's enterprise segment. Buyers now meter actual IT load rather than contracted space, aligning costs with utilization. This shift is most visible among fintech scale-ups in Mumbai's Bandra-Kurla Complex seeking operational flexibility without stranded capacity commitments.
Mumbai Data Center Market Segmentation
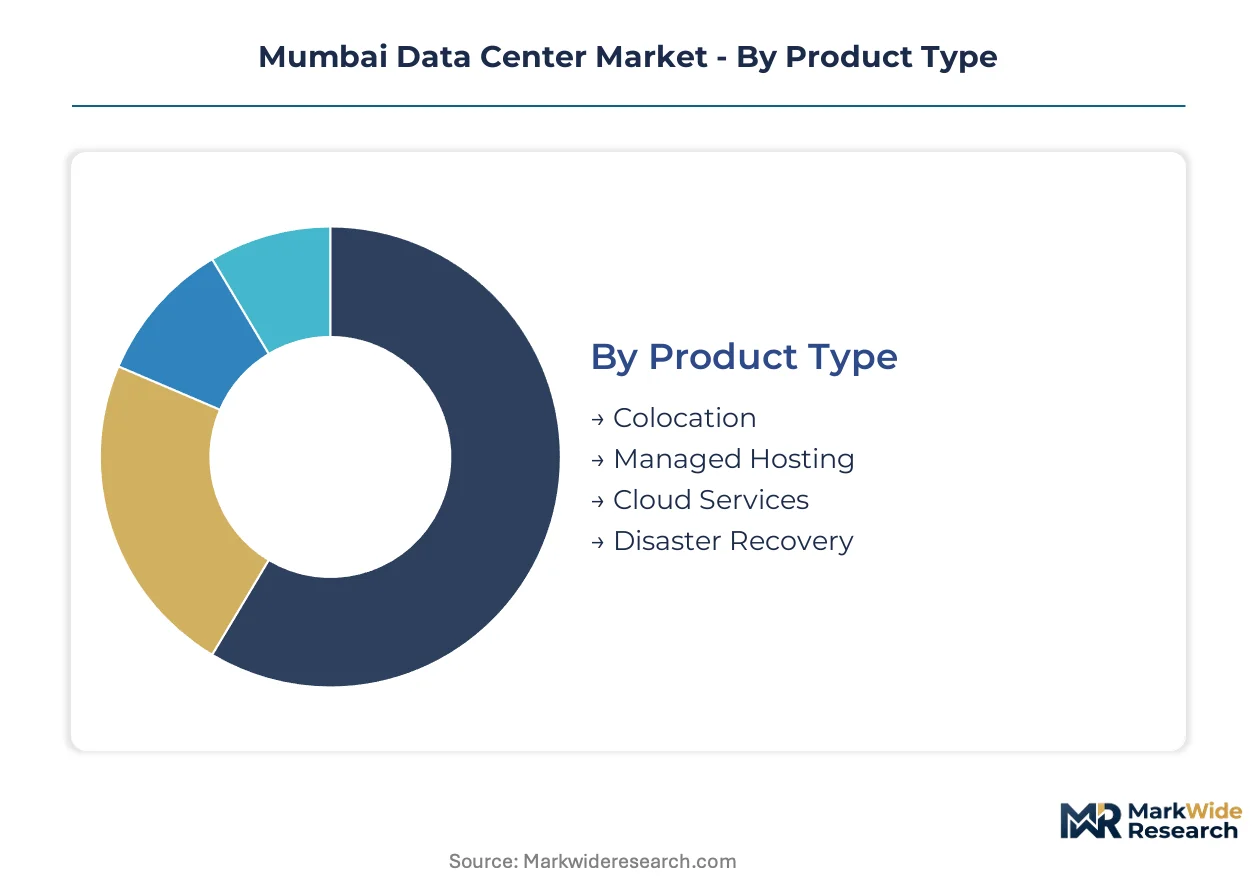
Segmentation in Mumbai's data center market reveals how buyer priorities diverge across regulatory mandates, workload characteristics, and risk tolerance. Understanding these fault lines enables operators to align capacity investments with revenue pools that command sustainable pricing power.
Product Type:
Buyers select product tiers based on internal IT capability depth and compliance burden intensity.
- Colocation:Wholesale and retail space leasing with redundant power and cross-connect fiber density exceeding 500 strands per suite. BFSI institutions in Mumbai's Bandra-Kurla Complex are migrating owned facilities to third-party colocation to satisfy RBI data residency requirements without capital deployment.
- Cloud Services:On-demand compute and storage with API-driven provisioning and consumption-based metering. SaaS providers targeting Maharashtra's enterprise base are establishing Mumbai nodes to reduce latency below 20 milliseconds for western India markets.
- Managed Hosting:Operator-administered servers with SLA-backed uptime guarantees and patch management. Mid-market enterprises lacking certified data center engineering talent pools favor this option to compress commissioning timelines.
- Disaster Recovery:Secondary site replication with RPO/RTO guarantees and automated failover orchestration. Regulated sectors mandate geographic separation between primary Mumbai facilities and Thane-Bhiwandi corridor recovery nodes.
Colocation leads on scale; Cloud Services leads on momentum.
End User:
Vertical-specific compliance regimes and latency sensitivity shape facility selection criteria across buyer categories.
- BFSI:Banking, insurance, and capital markets institutions with RBI-mandated data localization for payment systems and customer records. Captive and third-party capacity expansion is accelerating across Navi Mumbai's hyperscale corridor.
- IT Services:System integrators and managed service providers delivering infrastructure outsourcing to global and domestic clients. Hybrid deployment architectures are capturing margin pools from clients requiring on-premises control with burst elasticity.
- Telecommunication:Mobile network operators and internet service providers hosting core network functions and content delivery infrastructure. Edge computing proximity requirements are driving metro fiber densification.
- E-Commerce:Online retail platforms and logistics aggregators with seasonal demand volatility and payment processing workloads. Consumption-based power pricing aligns costs with utilization spikes during festival quarter surges.
BFSI dominates committed capacity; E-Commerce shows steepest expansion trajectory.
Deployment:
Architecture decisions reflect trade-offs between control, capital efficiency, and regulatory auditability.
- Hybrid:Integrated on-premises and off-premises infrastructure with unified orchestration and policy-driven workload placement. Regulated BFSI clients are adopting this model to maintain sovereign data custody while accessing cloud elasticity.
- Off-Premises:Fully outsourced facility operations with multi-tenant shared infrastructure and standardized service catalogs. Fintech scale-ups favor this option to avoid stranded capacity commitments during uncertain growth phases.
- On-Premises:Enterprise-owned facilities with dedicated power, cooling, and physical security. Legacy mainframe-dependent institutions retain this architecture for core banking systems requiring millisecond latency.
- Edge:Distributed micro-facilities positioned within 10 kilometers of data generation sources. AI inference workloads and IoT aggregation points are driving pilot deployments in Mumbai's industrial zones.
Hybrid architectures lead on deal value; Edge deployments lead on pilot velocity.
Solution:
Abstraction layer selection determines operational flexibility and vendor lock-in exposure for enterprise buyers.
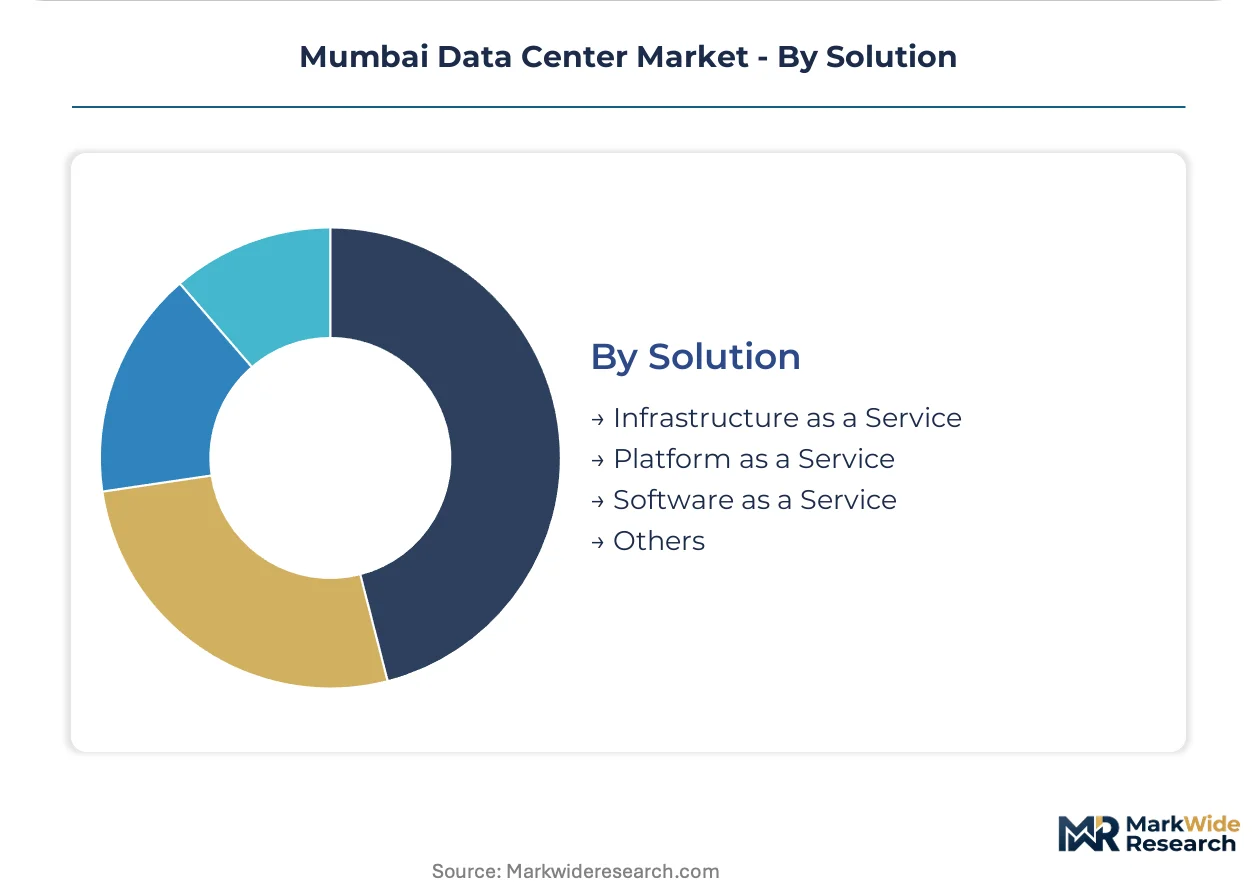
- Infrastructure as a Service:Virtualized compute, storage, and networking resources with self-service provisioning portals. GPU-intensive training clusters are driving demand for high-density cooling configurations in Navi Mumbai facilities.
- Software as a Service:Application-level consumption with zero infrastructure management and automatic feature updates. Enterprise productivity and collaboration tools are consolidating on Mumbai-hosted instances to satisfy MeitY data localization directives.
- Platform as a Service:Developer-centric runtime environments with managed middleware and database services. IT Services firms leverage this tier to accelerate client application deployment without underlying infrastructure oversight.
- Others:Specialized offerings including bare-metal provisioning, dedicated private cloud instances, and custom managed security services. Niche requirements from defense and government contractors populate this residual category.
Infrastructure as a Service leads on revenue concentration; Software as a Service leads on contract velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's certified data center engineering talent pools anchor facility build-out velocity across the Mumbai metropolitan region, with specialized technicians commanding premium wages in Navi Mumbai's hyperscale corridor.
Navi Mumbai
GPU-intensive training clusters and AI inference workloads are concentrating in Panvel's emerging hyperscale campus zone. TRAI's cloud services framework shapes interconnection pricing for facilities serving SaaS providers. STT GDC India's wholesale capacity anchors this sub-region's dominance in western India's digital infrastructure map.
Thane-Bhiwandi Belt
Disaster recovery nodes and secondary site replication are migrating here to satisfy geographic separation mandates from RBI. Maharashtra State Electricity Distribution Company Limited's transmission constraints limit megawatt-scale expansion timelines. Yotta Infrastructure positions dedicated AI and cloud nodes to capture BFSI compliance-driven demand.
Bandra-Kurla Complex
Fintech scale-ups and BFSI headquarters are driving consumption-based power pricing adoption for operational flexibility. MeitY's data localization directives compress deployment timelines for enterprises exiting foreign cloud regions. CtrlS Datacenters sustains tier-4 certified facility dominance to serve mission-critical financial clients.
Powai-Vikhroli Corridor
IT services firms and system integrators are establishing hybrid deployment architectures for global client delivery. BIS standards for IT infrastructure mandate seismic zone III compliance and redundant substation connectivity. Modular prefabricated designs are accelerating facility commissioning for mid-market managed hosting demand.
Andheri-MIDC Belt
Telecommunication operators and content delivery networks are densifying metro fiber for edge computing proximity. Maharashtra's industrial power tariff policies influence site economics for legacy air-cooled facility retrofits. Liquid cooling pilot deployments are capturing premium tenancy contracts from generative model training operations.
Mumbai Data Center Market Competitive Landscape
The competitive structure tilts toward hyperscale campus operators with captive power arrangements and tier-4 certification pathways. Market concentration is elevating as land scarcity premiums and renewable purchase obligations favor capital-intensive players with multi-site portfolios. Two strategic archetypes dominate: global platform operators with interconnection density and domestic specialists with sovereign compliance depth. Capacity expansion and green tariff securing represent the dominant competitive moves reshaping positioning.
Among domestic hyperscale specialists, STT GDC India and CtrlS Datacenters exemplify divergent certification strategies, while Yotta Infrastructure occupies a position at the AI-cloud convergence frontier. Global platform operators including NTT Global Data Centers and Equinix India anchor interconnection-centric positioning. Reliance Jio and AdaniConneX represent infrastructure conglomerate entries leveraging captive energy and land assets for vertical integration advantages.
| Leading Market Players |
|---|
| STT GDC India |
| CtrlS Datacenters |
| Sify Technologies |
| NTT Global Data Centers |
| Equinix India |
| Yotta Infrastructure |
| AdaniConneX |
| Nxtra Data |
| Reliance Jio |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up hyperscale specialists anchor Mumbai's data center supply base, translating concentrated ownership into disciplined pricing power and synchronized capacity deployment across the Navi Mumbai-Thane corridor. Their captive land banks and renewable power purchase agreements insulate wholesale pricing from Maharashtra's industrial tariff volatility while compressing margins for unbundled retail competitors.
Pricing Analysis
The bundled-vs-unbundled service split defines Mumbai's pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates tier-4 certified facilities from tier-3 designs and basic colocation space. Price differentiation rests on certification grade and power density configuration, with liquid-cooled AI racks commanding substantial premiums over air-cooled legacy tiers. Cost compression in retail colocation is intensifying because fintech scale-ups are migrating to consumption-based metering models. Mid-market enterprises lacking internal engineering capability show highest price sensitivity, while RBI-regulated BFSI institutions prioritize sovereign compliance over unit economics.
Supply Chain Analysis
Certification and qualification gating through BIS IT infrastructure standards and Uptime Institute tiering protocols filter equipment vendors and EPC contractors serving the Mumbai market. Supply concentrates in China for precision cooling systems, India for electrical switchgear and cabling infrastructure, and Germany for high-efficiency UPS systems. Raw material dependencies span copper busbars, dielectric cooling fluids, and seismic-grade steel framing. Single-source vulnerability runs through imported liquid cooling components subject to DGFT licensing requirements. Distribution runs through operator-direct procurement for hyperscale campuses and systems-integrator channels for mid-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mumbai's data center market offers margin-expansion pathways as renewable power arbitrage and AI-density premiums shift revenue mix toward higher-yielding infrastructure tiers. Liquid cooling adoption and green tariff securing represent the dominant levers for capturing this uplift.
For Market Incumbents: To counter land scarcity premiums eroding returns in the Thane-Bhiwandi belt, STT GDC India and CtrlS Datacenters should deepen backward integration into captive renewable generation assets. Securing solar-wind hybrid purchase obligations ahead of Maharashtra's escalating renewable mandates preserves cost differentiation against AdaniConneX and Reliance Jio's energy conglomerate parents. Tier-4 certification investment in Navi Mumbai facilities locks in BFSI tenancy with switching-cost protection. For New Entrants and Emerging Players: Channel partners specializing in IT services outsourcing represent the fastest path to contracted capacity. Edge micro-facilities in Mumbai's industrial zones offer underpenetrated white space, with AI inference workloads and IoT aggregation points showing pilot velocity unmatched by hyperscale saturation. A sovereign cloud positioning targeting MeitY's government migration directives bypasses direct competition with established wholesale operators. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic tier-3 operators lacking certification pathways to tier-4 or liquid cooling retrofit capability. Long-term viability over the coming decade hinges on renewable power purchase obligation compliance and AI-density rack penetration rates. The signal to watch is Maharashtra State Electricity Distribution Company Limited transmission upgrade announcements in the Panvel corridor, which would unlock megawatt-scale expansion timelines and re-rate facility valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Power Purchase Agreement | Secures green tariffs ahead of Maharashtra's escalating renewable mandates for cost differentiation. |
| Liquid Cooling Infrastructure Deployment | Enables 50kW+ rack densities for GPU-intensive AI training workloads commanding premium tenancy. |
| Tier-4 Certification Investment | Locks in RBI-regulated BFSI clients with fault-tolerant requirements and high switching costs. |
| Modular Prefabricated Facility Design | Accelerates BIS seismic compliance timelines and compresses commissioning cycles in land-constrained Mumbai. |
| Edge Micro-Facility Pilot Program | Captures AI inference and IoT aggregation demand in Mumbai's industrial zones with sub-10km latency. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center facility directors, BFSI technology procurement heads, Maharashtra regulatory affairs specialists, and EPC contractors with secondary validation. SEC filings of listed operators, TRAI cloud services framework documents, BIS IT infrastructure standards, and Maharashtra State Electricity Distribution Company Limited tariff orders anchored the data foundation. Bottom-up capacity build-out tracking across Navi Mumbai, Thane-Bhiwandi, and Bandra-Kurla Complex sub-regions triangulated against top-down demand modeling from BFSI and SaaS verticals.
Segment-weighting across product type, end user vertical, deployment architecture, and solution abstraction layer drove the analytical framework. Infrastructure-as-a-Service and colocation revenue pools were modeled separately from cloud services momentum trajectories. CAGRs derived from facility commissioning timelines, power infrastructure expansion schedules, and regulatory compliance cost curves. GPU density adoption curves and renewable power purchase obligation fulfillment rates served as industry-specific forecast inputs across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Maharashtra transmission infrastructure build-out velocity and RBI data localization enforcement intensity. Forecasts reflect assumptions on land-use clearance timelines and skilled technician pipeline development that material deviation would revise. A model refresh is warranted upon material change in MSEDCL transmission upgrade announcements or MeitY sovereign cloud procurement directives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
Hong Kong Data Center Construction Market
Data Center Infrastructure
Indonesia Data Center Market
Data Center Infrastructure
Singapore Data Center Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
Managed IT Infrastructure Services Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
Netherlands Data Center Power Market
Data Center Infrastructure
United States (US) Data Center Construction Market
Data Center Infrastructure
Mexico Data Center Power Market
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
Brazil Data Center Power Market