
 Indonesia Enterprise Network Infrastructure Market | 2026-2036
Indonesia Enterprise Network Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Enterprise Network Infrastructure Market Insights
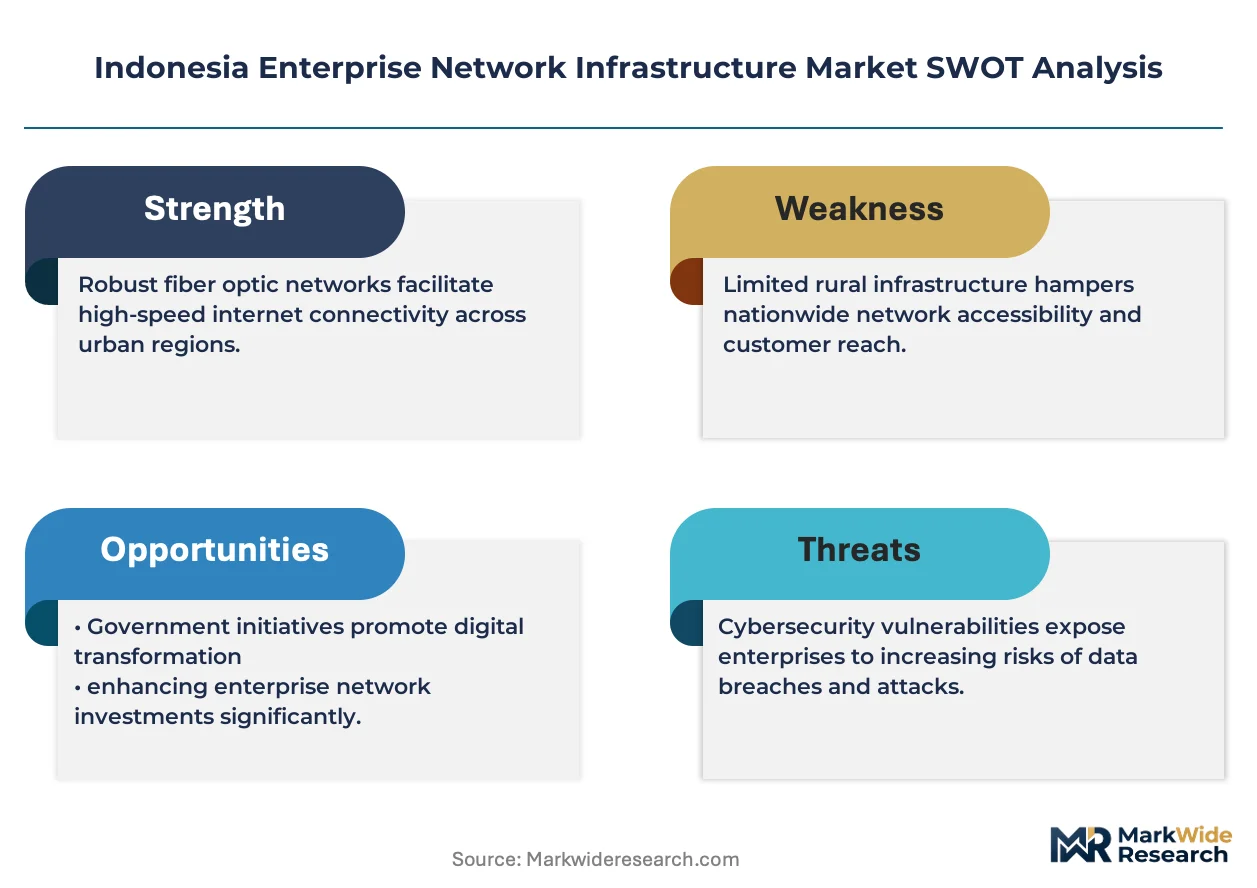
Multi-source procurement for core networking hardware is pivoting toward hybrid vendor strategies as Indonesian enterprises diversify supply risk. Cisco Systems, Inc. anchors its position through deep channel partnerships with local system integrators. Huawei Technologies Co., Ltd. competes aggressively on total cost of ownership for routing and switching portfolios. HPE Aruba Networking differentiates through cloud-managed campus networking solutions tailored to mid-market verticals.
Indonesia enterprise network infrastructure comprises the physical and virtual equipment, protocols, and management systems that enable data transmission, security, and connectivity across organizational environments, typically operating at Layer 2 through Layer 7 of the OSI model with throughput specifications ranging from gigabit to multi-terabit capacities depending on deployment scale. Its primary commercial purpose is to ensure reliable, secure, and scalable communication between distributed workforces, cloud resources, and edge devices. Routers and switches form the mature revenue base where replacement cycles drive steady demand, while SD-WAN deployments represent the fastest-expanding technology segment as enterprises phase out legacy MPLS circuits. Cloud-based and hybrid deployment models are capturing disproportionate margin pools by reducing capital intensity and accelerating time-to-service for branch rollouts.
BIS certification mandates and the Ministry of Communication and Informatics (Kominfo) cybersecurity frameworks are tightening equipment approval pathways and elevating compliance costs for foreign suppliers entering Indonesia. The Personal Data Protection Law and national critical infrastructure designations further constrain how enterprises architect cross-border data flows and select sovereign-hosted network management platforms. Stakeholders must weigh localization requirements against vendor interoperability when designing multi-year infrastructure refresh cycles.
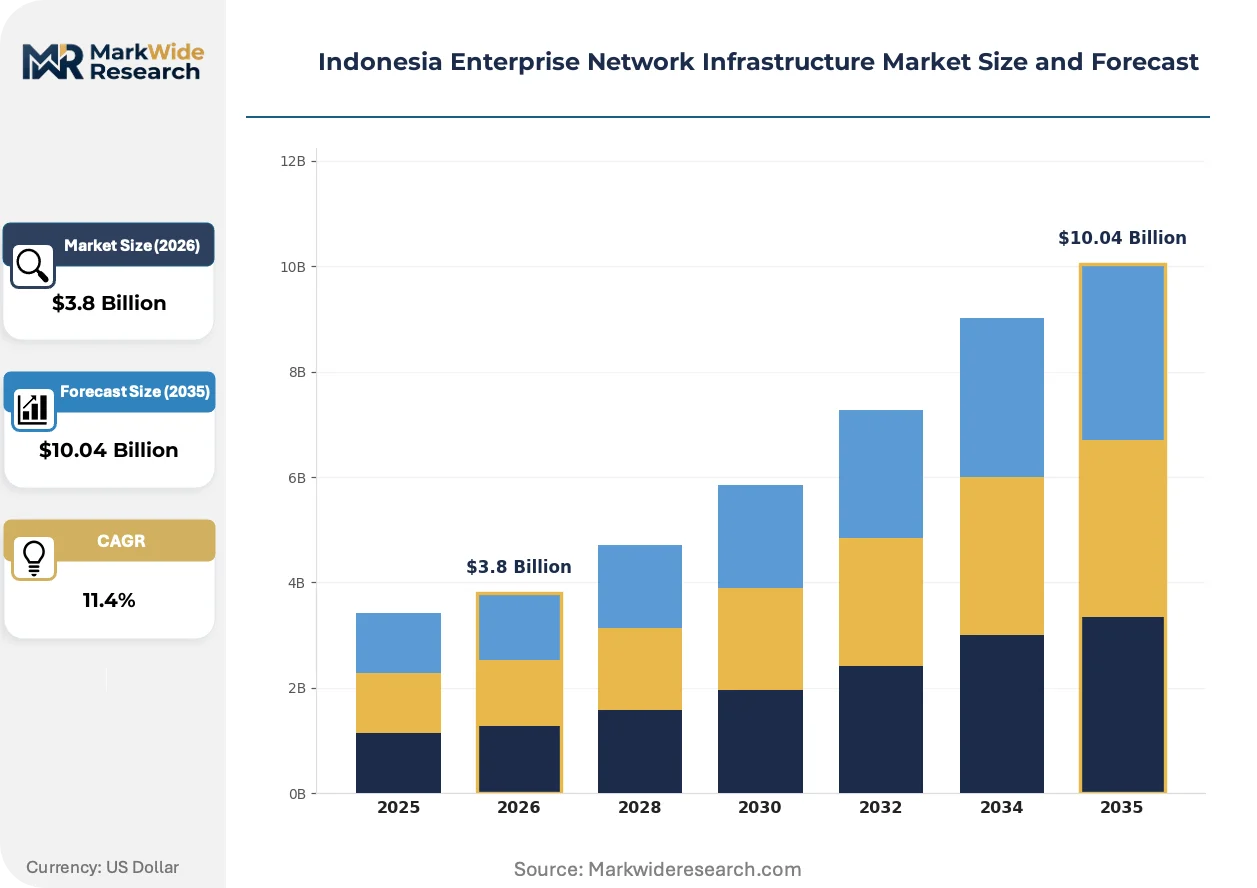
Market Dynamics
SD-WAN rollouts are compressing MPLS dependency across Indonesian banking and retail networks, while Kominfo's BIS certification mandates force foreign suppliers into localized testing partnerships before equipment deployment.
Growth Catalysts
- Digital Banking Infrastructure:Indonesian financial services institutions are accelerating branch modernization to support real-time payment clearing and mobile banking traffic surges.
- Data Center Buildouts:Cloud service providers and hyperscalers are expanding capacity in the Greater Jakarta corridor, driving demand for high-throughput spine-leaf architectures.
- Kominfo Cybersecurity Frameworks:Mandatory security audits and critical infrastructure designations are compelling enterprises to refresh aging perimeter equipment with certified next-generation platforms.
Market Restraints
- Import Duty Volatility:Fluctuating tariffs on optical transceivers and specialized semiconductors inflate total landed costs for routing hardware.
- Testing Bottlenecks:Limited BIS-accredited laboratories in Indonesia extend equipment approval timelines, delaying project commissioning for foreign vendors.
- Skills Concentration:Certified network engineers cluster in Java, leaving Sumatra and Sulawesi enterprises dependent on fly-in specialists for complex deployments.
Strategic Opportunities
- Eastern Indonesia Expansion:Underpenetrated markets in Papua and Maluku present first-mover advantages for SD-WAN providers targeting resource extraction and logistics verticals.
- 5G Enterprise Private Networks:Manufacturing campuses in Batam and Surabaya are piloting dedicated spectrum slices for industrial automation and AGV control systems.
- Managed Security Service Bundling:Channel partners are wrapping network hardware with SOC-as-a-service offerings to capture recurring revenue streams from mid-market clients.
Industry Challenges
- Legacy MPLS Migration Complexity:Enterprises with decade-old WAN contracts face contract breakage penalties and inter-site compatibility testing during hybrid transition phases.
- Certification Documentation Gaps:Inconsistent BIS interpretation across regional Kominfo offices creates approval uncertainty for multi-site rollouts spanning multiple provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Enterprise Network Infrastructure Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Routers, Switches, Firewalls, Access Points Deployment Model: On-Premises, Hybrid, Cloud-Based, Virtual End User: SMEs, Large Enterprises, Government, Education Technology: SD-WAN, MPLS, Ethernet, Wi-Fi 6 |
| Companies Covered | Cisco Systems, Inc., HPE Aruba Networking, Huawei Technologies Co., Ltd., Nokia Corporation, Dell Technologies, Juniper Networks, Inc., Extreme Networks, Inc., ZTE Corporation, VMware LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Enterprise Network Infrastructure Market Trends and Innovations
Network virtualization and intent-based automation are displacing manual configuration workflows, while sovereign data requirements reshape how Indonesian enterprises evaluate cloud-managed versus on-premises control planes.
SD-WAN with integrated SASE security stacks is consolidating branch networking and perimeter protection into single-vendor platforms. Indonesian retail chains and logistics operators are adopting these converged appliances to reduce truck-roll dependencies for distributed locations. This consolidation is compressing procurement cycles from multi-vendor RFPs to single-source negotiations.
Kominfo's Personal Data Protection Law enforcement is tightening cross-border traffic inspection requirements. Financial institutions must now demonstrate data localization for customer transaction logs before receiving operational permits. Banks are responding by deploying in-country network management controllers rather than cloud-hosted alternatives.
Enterprise buyers are unbundling hardware acquisition from managed services, preferring to own core switching assets while outsourcing day-to-operations. System integrators in Jakarta and Surabaya are restructuring compensation models around service attach rates rather than equipment margins. This shift is most pronounced in healthcare and education verticals with constrained capital budgets.
Indonesia Enterprise Network Infrastructure Market Segmentation
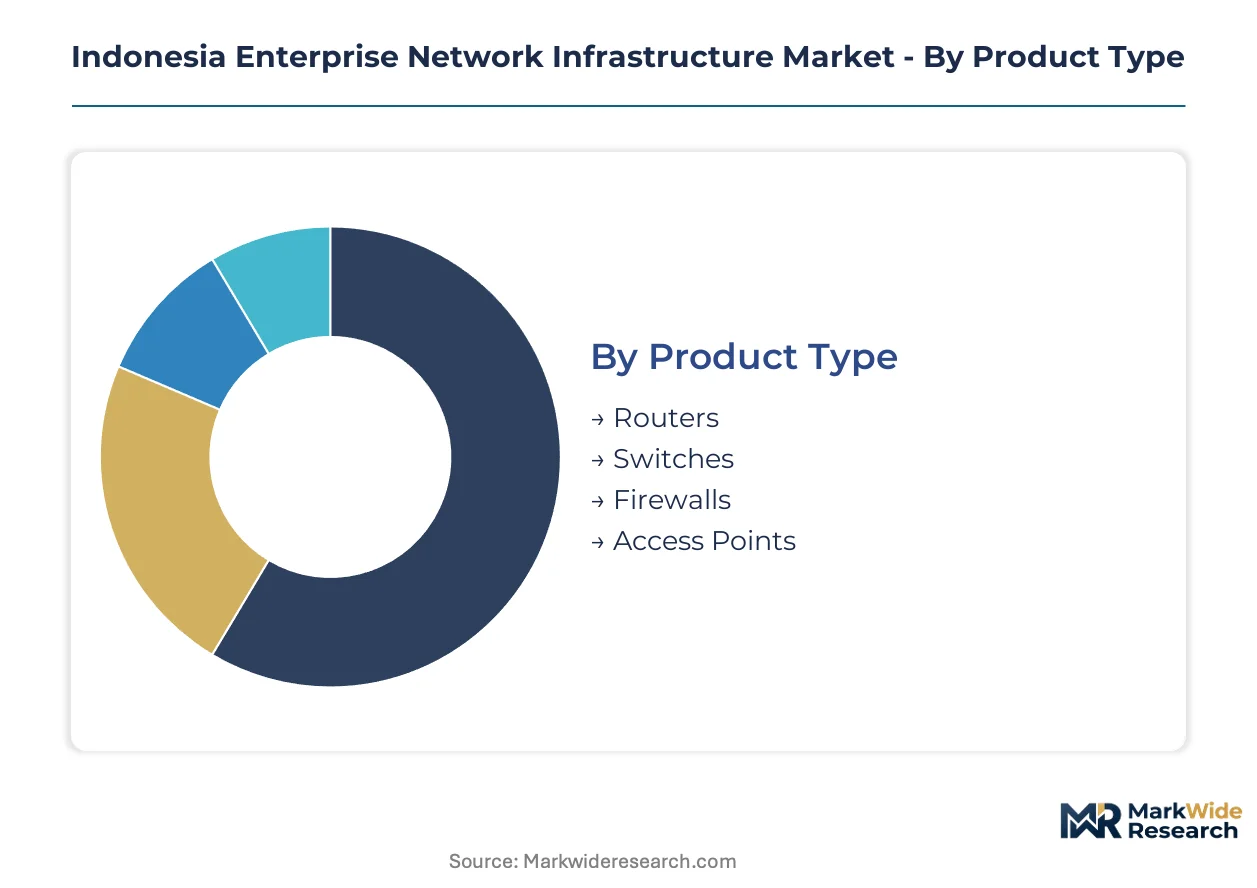
Indonesian enterprises navigate procurement through layered technical and regulatory lenses. Equipment categories face divergent BIS certification timelines, while deployment choices hinge on data sovereignty mandates under Kominfo frameworks.
Product Type:
BIS certification burdens vary sharply across hardware categories, with core routing equipment facing extended laboratory testing cycles compared to peripheral access gear.
- Routers:High-throughput devices processing multi-gigabit traffic flows across WAN boundaries. Banking networks in Greater Jakarta drive replacement demand as institutions migrate from legacy MPLS to SD-WAN architectures.
- Switches:Layer 2 and Layer 3 devices enabling campus and data center fabric connectivity. Hyperscaler buildouts in the Jakarta corridor are absorbing spine-leaf configurations with 100G and 400G port densities.
- Firewalls:Next-generation appliances with deep packet inspection capabilities for perimeter defense. Mandatory security audits under Kominfo cybersecurity frameworks are accelerating refresh cycles.
- Access Points:Wi-Fi 6 and Wi-Fi 6E radios for high-density enterprise environments. Retail chains and logistics hubs in Surabaya and Bandung are deploying these for warehouse automation and customer connectivity.
Switches sit at the top of the volume ranking, with SD-WAN-enabled routers climbing the fastest.
Deployment Model:
Capital intensity and operational control trade-offs define how Indonesian enterprises distribute workloads across infrastructure layers.
- On-Premises:Physical hardware residing in enterprise-owned facilities with full administrative control. Financial institutions favor this model for core transaction processing to satisfy data localization requirements.
- Hybrid:Split architectures combining private data centers with selective cloud burst capacity. Manufacturing campuses in Batam use this approach to isolate production systems while leveraging SaaS for ERP functions.
- Cloud-Based:Fully managed network services with vendor-hosted control planes. Mid-market retailers are adopting these to eliminate hardware refresh capital outlays.
- Virtual:Software-defined network functions running on commodity compute infrastructure. Telecommunications providers are virtualizing customer premises equipment to reduce truck-roll costs.
On-premises deployments retain the largest installed base, though cloud-based configurations are gaining share fastest among SMEs.
End User:
Budget cycles and compliance obligations create distinct purchasing rhythms across organizational categories.
- SMEs:Organizations with constrained IT capital favoring subscription-based network services. These buyers prioritize rapid deployment over customization, driving channel partner bundling of hardware with managed services.
- Large Enterprises:Multinational corporations and domestic conglomerates with dedicated network engineering teams. Mining and plantation operators in Sumatra and Kalimantan require ruggedized equipment for remote site connectivity.
- Government:Central and regional agencies subject to national critical infrastructure designations. Procurement flows through formal tender processes with extended vendor qualification requirements.
- Education:Universities and vocational institutions expanding campus networks to support hybrid learning models. Public funding cycles create concentrated demand windows aligned with fiscal year appropriations.
Large enterprises command the highest absolute spending, with government segments showing the steepest expansion trajectory following cybersecurity mandate enforcement.
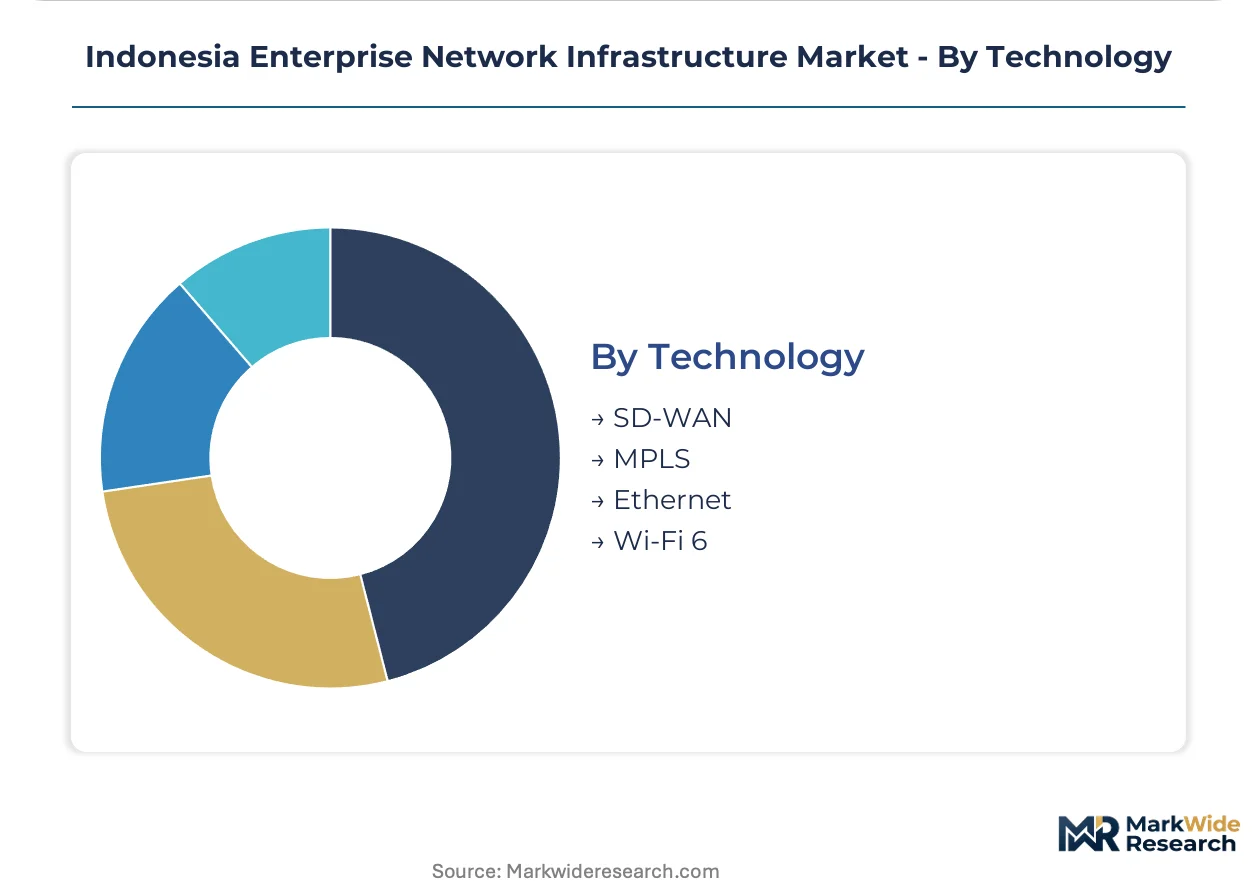
Technology:
Protocol transitions are compressing legacy service revenues while creating openings for converged platforms.
- SD-WAN:Software-defined overlays abstracting transport independence across multiple underlying circuits. Indonesian banks are deploying these to aggregate broadband, LTE, and remaining MPLS links into unified branch connectivity.
- MPLS:Traditional carrier-managed private networks with guaranteed service level agreements. Contract breakage penalties and inter-site compatibility testing are complicating migration timelines for decade-old deployments.
- Ethernet:Standardized Layer 2 connectivity for campus and metropolitan area networks. Data center operators in the Greater Jakarta corridor are driving demand for 25G, 50G, and 100G server access speeds.
- Wi-Fi 6:IEEE 802.11ax standard delivering higher spectral efficiency and lower latency. Healthcare facilities in Surabaya are upgrading to support real-time location systems and medical device telemetry.
Ethernet maintains dominant volume position, while SD-WAN is expanding most quickly as enterprises phase out legacy WAN contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment vendors are relocating certification testing and pre-deployment staging to Indonesia to compress BIS approval timelines and avoid duty volatility on finished goods. This regulatory-arbitrage migration is concentrating technical capabilities in Java while creating satellite support nodes in secondary cities.
Java
Greater Jakarta anchors national demand through hyperscaler data center buildouts and banking network modernizations. Kominfo's cybersecurity frameworks mandate localized network management controllers for financial institutions. Surabaya and Bandung host expanding channel partner ecosystems serving manufacturing and retail verticals with SD-WAN deployments.
Sumatra
Mining conglomerates and plantation operators drive ruggedized routing equipment procurement for remote site connectivity. BIS certification requirements force extended lead times for equipment imports, favoring vendors with established Jakarta warehousing. Medan functions as the northern logistics hub for cross-strait deployments to Malaysia and Singapore.
Sulawesi
Nickel processing facilities and port modernization projects are absorbing industrial-grade switching infrastructure. The central government's Trans-Sulawesi economic corridor program is funding fiber backbone extensions. Makassar hosts the region's only BIS-accredited testing laboratory, creating a bottleneck for equipment approvals.
Kalimantan
Coal and palm oil operators require satellite-backup WAN solutions where terrestrial infrastructure remains sparse. The new capital city relocation to Nusantara is triggering greenfield network deployments for government and commercial tenants. Balikpapan serves as the primary procurement coordination point for East Kalimantan resource projects.
Eastern Indonesia
Papua and Maluku present underpenetrated markets where logistics costs dominate total cost of ownership calculations. Maritime logistics operators are piloting private LTE networks for port automation. Ambon and Jayapura function as distribution endpoints with limited local technical support capacity.
Indonesia Enterprise Network Infrastructure Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native management platforms and subscription-based delivery models. The vendor landscape stratifies across three tiers: global networking incumbents with deep channel partnerships, regional challengers competing on total cost of ownership, and software specialists abstracting hardware dependencies. Consolidation pressure is intensifying as enterprises reduce vendor counts through SD-WAN and SASE convergence. Dominant competitive moves include strategic partnerships with local system integrators and portfolio diversification into managed security services.
Within the incumbent tier, Cisco Systems, Inc. and HPE Aruba Networking exemplify channel-centric strategies that embed equipment vendors into multi-year service relationships. Huawei Technologies Co., Ltd. occupies a distinct position competing aggressively on price-performance metrics for routing and switching portfolios while navigating geopolitical procurement restrictions. These three anchors demonstrate how vendor selection in Indonesia increasingly hinges on BIS certification readiness and localized support infrastructure rather than technical specifications alone.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| HPE Aruba Networking |
| Huawei Technologies Co., Ltd. |
| Nokia Corporation |
| Dell Technologies |
| Juniper Networks, Inc. |
| Extreme Networks, Inc. |
| ZTE Corporation |
| VMware LLC |
| Others |
Pricing and Supply Chain Analysis
Captive integration into BIS-certified testing partnerships anchors both supply security and pricing power for foreign equipment vendors serving Indonesian enterprises. Vendors that control localized staging facilities bypass approval bottlenecks while commanding premium positioning against competitors dependent on fly-in certification support.
Pricing Analysis
Distributor margin layers absorb 15-25 points before equipment reaches end-user sites, compressing vendor netbacks. Three-tier pricing structure across premium, standard, and economy levels separates Cisco and HPE Aruba from Huawei and ZTE offerings. Cost compression in the economy tier is intensifying because BIS testing delays force project cost overruns onto budget-constrained buyers. SMEs exhibit highest price sensitivity, while government tenders prioritize certification compliance over unit economics.
Supply Chain Analysis
Workforce availability constraints in Malaysia and Vietnam push final assembly toward China and Taiwan for core routing silicon. Optical transceiver sourcing draws from Chinese component houses, Japanese precision manufacturers, and South Korean laser diode specialists. Single-source vulnerability concentrates in 400G and 800G coherent optics where two vendors control global capacity. Distribution runs through Jakarta-based system integrators with satellite stocking points in Surabaya and Medan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Indonesia enterprise network infrastructure market compounds steadily as data center buildouts and banking modernization create replacement-cycle visibility. Kominfo regulatory enforcement sustains equipment refresh demand regardless of macro volatility.
For Market Incumbents: Extend managed service attach rates to capture recurring revenue from hardware refresh cycles. Deepen backward integration into BIS pre-certification staging within Java to compress approval timelines against emerging competitors. Fortify channel exclusivity with Surabaya and Bandung system integrators before regional challengers establish local presence.
For New Entrants and Emerging Players: Enter via cloud-native SD-WAN platforms targeting mid-market retailers in secondary cities outside Greater Jakarta. Eastern Indonesia logistics operators present the most penetrable vertical given limited incumbent service infrastructure. Lead with subscription pricing to bypass capital-budget procurement friction in healthcare and education segments.
For Investors and Strategic Acquirers: Roll-up economics work for managed security service providers because Indonesian enterprises are unbundling hardware ownership from operational support. Five-to-ten year viability hinges on recurring revenue transformation rather than equipment shipment volumes. Monitor BIS laboratory accreditation expansion as the inflection signal for foreign vendor competitive intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Pre-Staging | Local testing partnerships compress approval timelines from 14 weeks to 6 weeks for routing equipment. |
| Managed Security Service Bundling | Channel partners wrap SOC-as-a-service with hardware to capture recurring revenue from mid-market clients. |
| SD-WAN Platform Integration | Converged SASE appliances reduce truck-roll dependencies for retail chains with distributed branch footprints. |
| Hyperscaler Data Center Partnership | Spine-leaf architecture deployments in Greater Jakarta absorb 100G and 400G switching at scale. |
| Eastern Indonesia Channel Expansion | First-mover positioning in Papua and Maluku captures resource extraction and maritime logistics verticals. |
Research Methodology
Multiple input streams — network engineering directors at Indonesian banks, procurement leads at hyperscaler data center operators, channel sales managers at Jakarta system integrators, and regulatory affairs specialists familiar with Kominfo frameworks — were reconciled against secondary validation. SEC filings from Cisco, HPE, and Juniper provided equipment shipment disclosures. Kominfo regulatory bulletins and BIS certification databases supplied compliance timeline data. Bottom-up equipment unit estimates and top-down addressable market sizing were cross-referenced for triangulation.
Data-stream reconciliation across deployment model, organization size, vertical industry, and regional adoption pattern enabled segmentation-level forecasting. CAGRs were derived from replacement cycle analysis and technology transition curves rather than extrapolation. SD-WAN penetration rates and data center capex trajectories served as primary demand inputs. Cloud-managed versus on-premises control plane splits were modeled against data sovereignty enforcement intensity.
Inputs from primary stakeholder interviews and regulatory documentation were available through the study window; gaps in real-time hyperscaler buildout pacing and BIS laboratory queue depths introduce uncertainty bands around near-term equipment shipment timing. Material deviation in Kominfo cybersecurity mandate enforcement or BIS accreditation expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Cloud Network Infrastructure Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Virtualized Data Center Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
United States Data Center Server Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Norway Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Chennai Data Center Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
Delhi-NCR Data Center Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Philippines Data Center Market
Data Center Infrastructure
South Africa Data Center Market