
 Data Center Power Solutions Market | 2026-2036
Data Center Power Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Power Solutions Market Outlook
Chinese power electronics manufacturing is pivoting toward high-density data center infrastructure. Huawei Digital Power leverages its integrated digital and power electronics portfolio to compete in smart modular UPS systems. Schneider Electric anchors its position through end-to-end electrical distribution architecture spanning medium voltage to rack power. Siemens differentiates via its SICAM power management platform and industrial automation heritage applied to mission-critical facilities.
Data center power solutions encompass the electrical infrastructure, conversion equipment, and distribution systems that deliver conditioned, uninterrupted power to server racks and cooling apparatus, typically operating at voltages from 480V AC down to 240/415V three-phase or 48V DC rack-level feeds with redundancy configurations from N+1 to 2N. The primary purpose is eliminating downtime from grid disturbances while optimizing energy efficiency across the power usage effectiveness ratio. UPS systems dominate product type revenue due to their non-negotiable role in bridging generator start-up delays, though energy storage technology is gaining structural importance as lithium-ion batteries displace valve-regulated lead-acid designs. Cloud service providers represent the fastest-expanding end user segment, driven by generative AI training clusters requiring multi-megawatt power densities that strain legacy distribution architectures.
The US EPA enforces ENERGY STAR certification thresholds for data center equipment efficiency, while the EU's Energy Efficiency Directive mandates power usage effectiveness reporting and waste heat recovery planning for new facilities. China's MIIT imposes GB standard compliance on data center power density and renewable energy integration ratios for new hyperscale projects. Stakeholders must monitor how evolving grid interconnection rules and carbon border adjustments reshape site selection economics and equipment procurement specifications.
Market Dynamics
Generative AI training clusters are forcing hyperscale operators to reengineer power distribution architectures, compressing legacy 480V AC designs toward 48V DC rack-level feeds to accommodate multi-megawatt density requirements.
Growth Catalysts
- EU Energy Efficiency Directive:Mandates power usage effectiveness reporting and waste heat recovery planning for new hyperscale facilities, accelerating equipment refresh cycles across member states.
- Lithium-ion battery chemistry:Displaces valve-regulated lead-acid designs in UPS systems, reducing footprint and maintenance burden while enabling longer runtime configurations.
- Northern Virginia's Data Center Alley:Concentrates demand for modular power infrastructure as cloud providers expand contiguous megawatt-scale campuses with shared substation architectures.
Market Restraints
- Copper and silicon carbide supply concentration:Chinese processing dominance for rare earth magnet materials and wide-bandgap semiconductor substrates creates input cost volatility and geopolitical exposure.
- Grid interconnection queue delays:US FERC interconnection reform implementation lags behind data center construction timelines, stranding completed facilities without energization dates.
- Thermal density physics:Air-cooled rack limits near 30kW constrain power delivery scaling for AI accelerators without liquid cooling infrastructure overhaul.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Incentivizes domestic production of power conversion equipment, creating localized supply alternatives to East Asian sourcing.
- Behind-the-meter solar plus storage:Enables hyperscale operators to bypass grid interconnection bottlenecks while meeting corporate renewable energy commitments.
- Software-defined power management:Converges IT and electrical infrastructure control planes, opening recurring revenue streams through predictive maintenance subscriptions.
Industry Challenges
- Medium-voltage electrical engineering talent scarcity:Specialized skills for 15kV-class switchgear design and commissioning command premium wages, constraining project velocity.
- Multi-vendor system integration complexity:Fragmented procurement across UPS, switchgear, and rack power distribution vendors creates commissioning delays and warranty boundary disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Power Solutions Market |
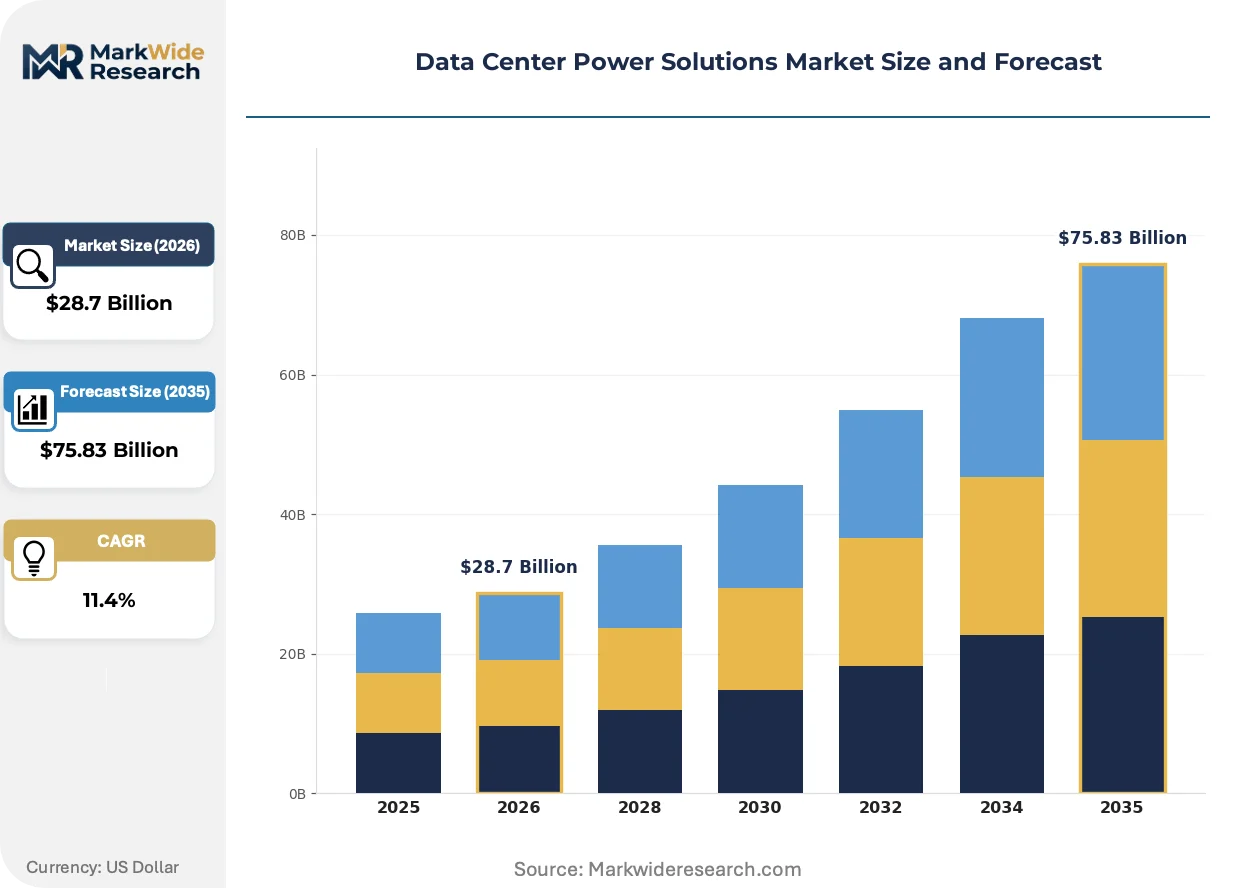
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $75.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UPS, Power Distribution Units, Generators, Racks End User: Colocation Providers, Enterprises, Cloud Service Providers, Telecom Technology: Direct Current, Alternating Current, Hybrid Systems, Energy Storage Capacity: Below 100 kW, 100-500 kW, 500-1000 kW, Above 1000 kW |
| Companies Covered | Huawei Digital Power, Delta Electronics, Schneider Electric, LITEON Technology, Siemens, Eaton, ABB, GE, Vertiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Power Solutions Market Strategic Shifts
Power architecture decisions now precede facility design, with rack-level energy density dictating building form factor rather than the reverse. This inversion compresses traditional engineering sequences and elevates electrical infrastructure to strategic procurement.
Busway power distribution is decentralizing electrical delivery by replacing centralized floor-mounted switchgear with overhead track systems that enable hot-add capacity without floor tile disruption. Hyperscale operators in Dallas-Fort Worth are adopting this topology aggressively. The technology is decentralizing the traditional electrical room, collapsing distribution layers and reducing copper conductor runs by half.
The US EPA's ENERGY STAR certification thresholds for UPS and power distribution equipment are tightening efficiency minimums for 2026 compliance windows. Manufacturers must redesign conversion topologies to meet 96% efficiency floors. Tier-III and Tier-IV certified facilities face equipment obsolescence risk if procurement precedes final rule publication.
Cloud service providers are consolidating vendor relationships from best-of-breed electrical sourcing toward integrated power and cooling package procurement. Channel partners with cross-functional engineering capabilities are displacing traditional electrical distributors in Northern Virginia and Phoenix. This concentration is most visible among generative AI training cluster deployments where single-vendor accountability reduces commissioning risk.
Data Center Power Solutions Market Segmentation
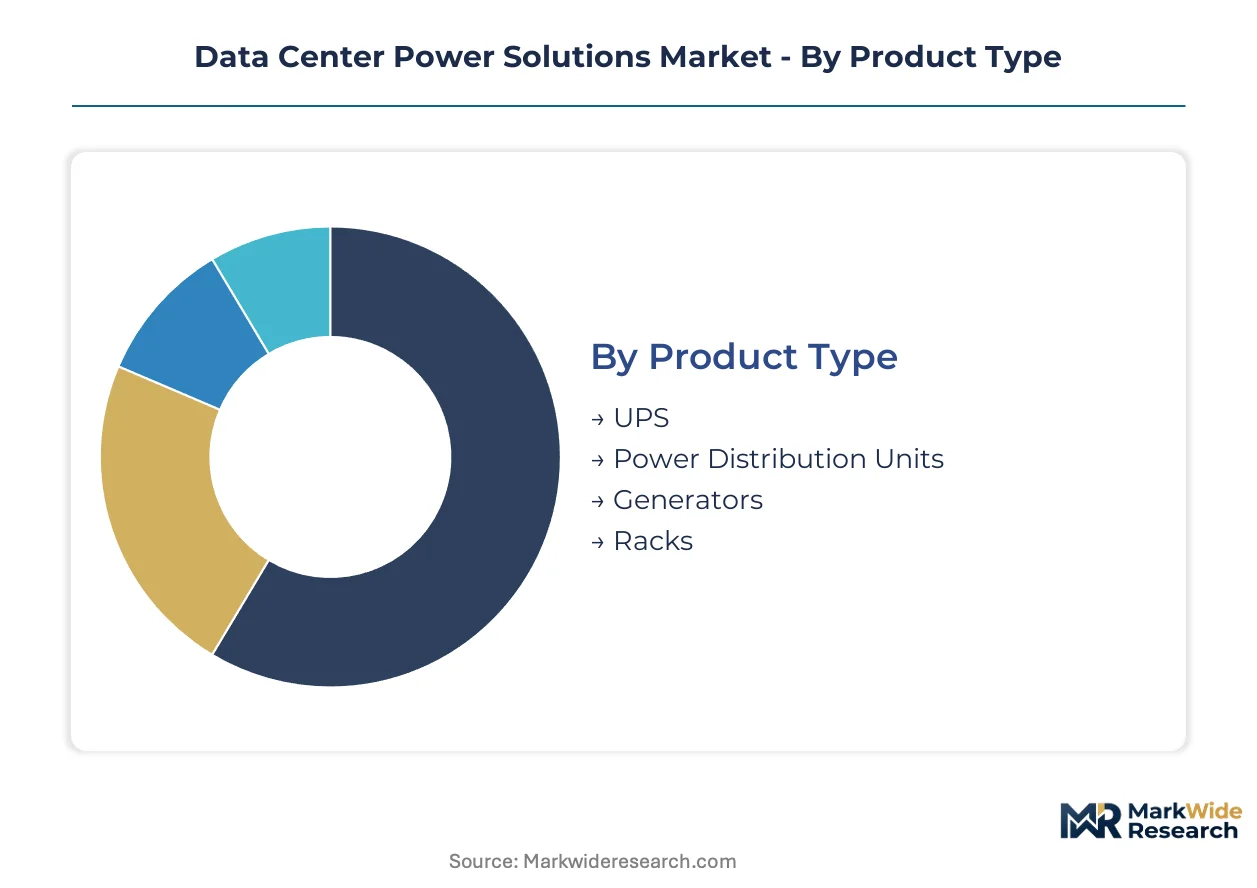
Power architecture decisions in data centers cascade through multiple specification axes simultaneously. Procurement teams evaluate conversion topology, rack density requirements, and redundancy configurations as interdependent variables rather than isolated choices.
Product Type:
Voltage conversion and distribution hardware defines the electrical backbone of facility infrastructure.
- UPS:Double-conversion and line-interactive topologies bridge generator start-up delays with lithium-ion batteries displacing valve-regulated lead-acid designs. Cloud service providers in Northern Virginia specify modular UPS architectures for megawatt-scale campuses with shared substation configurations.
- Power Distribution Units:Intelligent rack-level PDUs with outlet-level metering enable capacity planning precision for AI accelerator deployments. Dallas-Fort Worth hyperscale operators prioritize switched PDUs with remote reboot capability for unmanned edge locations.
- Generators:Diesel and natural gas standby systems provide N+1 redundancy for Tier-III and Tier-IV facilities.
- Racks:Integrated power and cooling containment structures accommodate 30kW+ densities with liquid cooling readiness.
Mature deployment sits with generators as baseline redundancy. Newer deployment is concentrated in intelligent PDUs with metering granularity.
End User:
Customer archetypes drive divergent procurement specifications based on ownership structure and workload characteristics.
- Cloud Service Providers:Hyperscale operators design proprietary power architectures with 48V DC rack feeds for generative AI training clusters. These specifications strain legacy 480V AC distribution and compress traditional engineering sequences.
- Colocation Providers:Multi-tenant facilities balance standardization against customization demands, deploying modular busway systems for hot-add capacity without floor tile disruption.
- Enterprises:Corporate data centers prioritize ENERGY STAR certification thresholds for sustainability reporting compliance.
- Telecom:Edge computing requirements favor compact, hardened power systems for remote central office deployments.
Procurement volume concentrates with cloud service providers expanding contiguous campuses. Enterprise refresh cycles lag behind hyperscale buildouts.
Technology:
Current form selection determines conversion losses, copper mass, and compatibility with renewable integration.
- Direct Current:48V and 380V DC architectures eliminate double-conversion losses for battery-backed workloads. Google and Microsoft pilot top-of-rack DC distribution for AI training infrastructure.
- Alternating Current:480V/208V three-phase remains dominant for legacy compatibility and broad vendor availability.
- Hybrid Systems:AC-DC integration layers accommodate mixed workloads during facility transition periods.
- Energy Storage:Lithium-ion battery systems enable longer runtime configurations with reduced footprint and maintenance burden.
Alternating current dominates installed base. Direct current is expanding most quickly in greenfield AI training facilities.
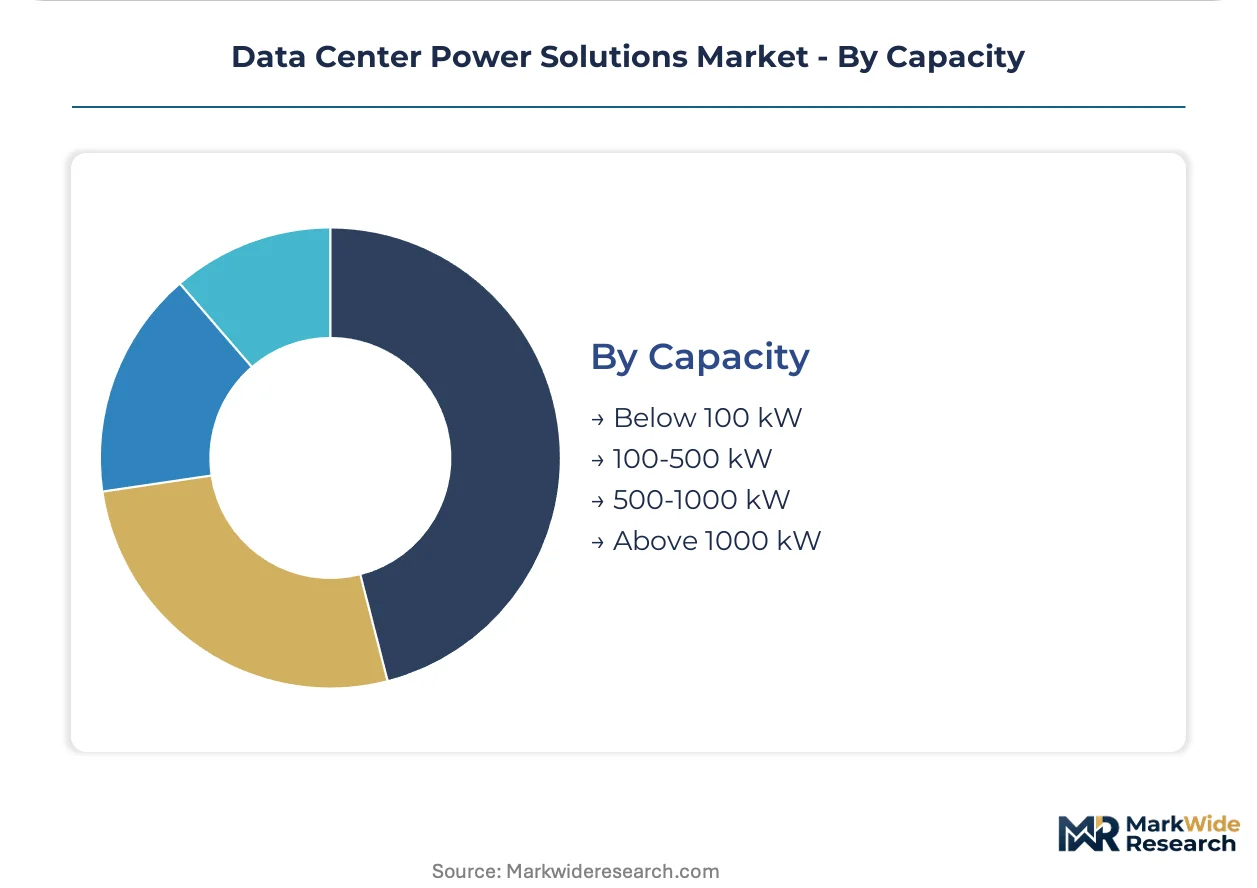
Capacity:
Scale thresholds align with redundancy architectures and physical infrastructure investment intensity.
- Above 1000 kW:Hyperscale modules deploy 2N electrical architectures with dedicated medium-voltage substations. These specifications command specialized commissioning talent and extended grid interconnection timelines.
- 500-1000 kW:Wholesale colocation suites balance density against lease flexibility for enterprise tenants with variable growth trajectories.
- 100-500 kW:Regional enterprise data centers and network edge facilities populate this mid-tier with N+1 redundancy standards.
- Below 100 kW:Micro data centers and remote telecom shelters require compact, pre-integrated power skids for rapid deployment.
Capacity planning is shifting upward as AI accelerators concentrate compute density. Sub-100 kW deployments fragment across distributed edge locations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper refining capacity in Chile and Peru underpins Latin American supply chains for electrical infrastructure. Silicon carbide substrate production concentrates in Japan and Germany. Rare earth magnet processing dominates Chinese industrial zones.
United States
Hyperscale cloud operators in Northern Virginia's Data Center Alley drive modular UPS procurement at megawatt scale. The US EPA's ENERGY STAR certification thresholds tighten efficiency minimums for 2026 compliance. Dallas-Fort Worth operators adopt busway power distribution to enable hot-add capacity without floor tile disruption.
China
GB standard compliance from MIIT mandates power density and renewable integration ratios for new hyperscale projects. Domestic power electronics manufacturing pivots toward high-density infrastructure. Yangtze River Delta clusters concentrate lithium-ion battery production for UPS runtime configurations.
Germany
Industrial automation heritage from Siemens anchors mission-critical facility expertise. The EU Energy Efficiency Directive mandates power usage effectiveness reporting and waste heat recovery planning. Frankfurt's financial data centers refresh equipment cycles to meet tightening efficiency floors.
India
PLI scheme incentives for electronics manufacturing attract power conversion equipment production. CEA grid interconnection standards shape facility commissioning timelines. Mumbai and Bangalore hyperscale campuses deploy shared substation architectures for contiguous expansion.
Japan
METI industrial policy supports wide-bandgap semiconductor substrate development for next-generation conversion efficiency. Tokyo and Osaka metro areas concentrate enterprise data center refresh demand. Local engineering talent commands premium wages for medium-voltage switchgear commissioning.
Data Center Power Solutions Market Competitive Environment
Global majors compete with regional champions across electrical distribution architecture and power conversion technology. The vendor base organizes into three tiers: integrated platform providers, component specialists, and emerging modular system fabricators. Strategic differentiation centers on end-to-end accountability versus best-of-breed flexibility. Competitive moves concentrate on vertical integration into battery cell production and software-defined power management platforms.
Among integrated platform providers, Schneider Electric occupies a position exemplifying end-to-end electrical distribution architecture spanning medium voltage to rack power. Siemens represents the industrial automation heritage applied to mission-critical facilities. Huawei Digital Power anchors the smart modular UPS segment through integrated digital and power electronics portfolios. These three exemplify how vendor consolidation toward single-source accountability reduces commissioning risk for generative AI training cluster deployments.
| Leading Market Players |
|---|
| Huawei Digital Power |
| Delta Electronics |
| Schneider Electric |
| LITEON Technology |
| Siemens |
| Eaton |
| ABB |
| GE |
| Vertiv |
| Others |
Value Chain & Pricing Dynamics
Captive lithium-ion cell production anchors supply positioning and pricing power for integrated UPS manufacturers, compressing margins for vendors dependent on Chinese battery imports while rewarding those with in-house chemistry capabilities and ENERGY STAR-certified conversion topologies.
Pricing Analysis
Warranty and commissioning service bundling separates premium-tier electrical infrastructure vendors from unbundled component suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and runtime configuration, with Tier-IV 2N architectures commanding substantial premiums over N+1 colocation specifications. Cost compression in mid-tier modular UPS is intensifying because lithium-ion battery commoditization erodes hardware differentiation. Cloud service providers exhibit lowest price sensitivity given single-source accountability requirements, while regional enterprises negotiate aggressively on extended maintenance terms.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Northern Virginia maintain hub-and-spoke patterns for rapid-deployment power skids. Silicon carbide substrates draw from Japanese and German wafer fabrication, while rare earth magnet processing concentrates in Chinese industrial zones. Single-source vulnerability in wide-bandgap semiconductor substrates creates exposure to export control adjustments. Distribution runs through channel partners with cross-functional engineering capabilities rather than traditional electrical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data center power solutions are navigating a technology-transition phase as 48V DC rack-level architectures displace legacy 480V AC distribution for generative AI training clusters.
For Market Incumbents: Cement end-to-end accountability positions by acquiring commissioning-specialist firms and securing captive lithium-ion supply through joint venture structures. Defensive moves must counter emerging modular system fabricators in India's PLI-subsidized manufacturing zones. Certification investment in EU Energy Efficiency Directive compliance represents a critical lever for European facility refresh cycles. For New Entrants and Emerging Players: Regional enterprise data centers in secondary US markets represent an underserved buyer archetype with lagging refresh cycles and limited vendor consolidation pressure. White-space targets include software-defined power management subscriptions and behind-the-meter solar-plus-storage integration for grid-constrained campuses. Channel partnership with established cooling infrastructure vendors offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated platform providers seeking battery cell production capabilities and predictive maintenance software assets. Long-term viability favors vendors with vertically controlled semiconductor substrate access and hyperscale commissioning track records. The signal to watch is FERC interconnection queue reform implementation velocity as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Production | Captive lithium-ion supply secures margin control against Chinese processing concentration. |
| Software-Defined Power Management Platform Launch | Predictive maintenance subscriptions open recurring revenue streams from hyperscale operators. |
| Busway Distribution Topology Expansion | Overhead track systems enable hot-add capacity for Dallas-Fort Worth campus buildouts. |
| 48V DC Rack-Level Architecture Certification | Google and Microsoft pilot programs validate conversion topology for AI training clusters. |
| India PLI Manufacturing Footprint Establishment | Domestic power conversion production bypasses East Asian sourcing exposure and tariff risk. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with data center facility directors, electrical infrastructure procurement leads, EPC contractors, and utility interconnection planners combined with hyperscaler capex disclosures, FERC interconnection queue databases, EPA ENERGY STAR certification records, and EU Energy Efficiency Directive implementation reports. Bottom-up capacity modeling and top-down demand triangulation validated segment-level outputs.
Granularity-level modeling deployed capacity-tier segmentation for above-1000kW hyperscale modules down to sub-100kW edge deployments, technology-type splits across AC, DC, and hybrid architectures, and end-user archetypes from cloud service providers through telecom edge operators. CAGRs derived from facility construction pipeline analysis and equipment replacement cycle timing. Forecast inputs incorporated grid interconnection approval velocity and lithium-ion battery cost curve trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FERC interconnection reform implementation, Chinese export control adjustments on wide-bandgap substrates, and thermal density physics constraints on air-cooled rack limits. Forecasts reflect documented assumptions regarding hyperscale construction timelines and renewable integration mandates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Taiwan Data Center Rack Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
France Data Center Server Market
Data Center Infrastructure
Indonesia Data Center Power Market
Data Center Infrastructure
UAE Data Center Server Market
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
Saudi Arabia Data Center Rack Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
New York Data Center Market
Data Center Infrastructure
Global Data Center Rack PDU Market