
 Japan Data Center Physical Security Market | 2026-2036
Japan Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Data Center Physical Security Market Insights
Integrated security suites is rebalancing procurement patterns across Japanese data center operators, who now favor bundled access control and surveillance packages over standalone component purchases. Axis Communications AB dominates network camera deployments with deep channel control across Kanto-region integrators. Bosch Sicherheitssysteme GmbH anchors high-assurance biometric access through specialized engineering partnerships with domestic construction firms. Johnson Controls leverages its building-management heritage to extend into environmental monitoring tied to physical security dashboards.
Japan Data Center Physical Security encompasses perimeter barriers, biometric authentication hardware, video surveillance infrastructure, intrusion detection sensors, and environmental threat monitoring systems engineered to protect mission-critical computing facilities from unauthorized physical access, natural disasters, and operational disruption. Surveillance Cameras leads technology spending due to AI-enabled video analytics demand, while Access Control Systems captures expanding margin pools as multimodal biometric adoption accelerates among financial services end users. Managed Security Services shows structural momentum as cloud service providers outsource round-the-clock monitoring and incident response to specialized operators.
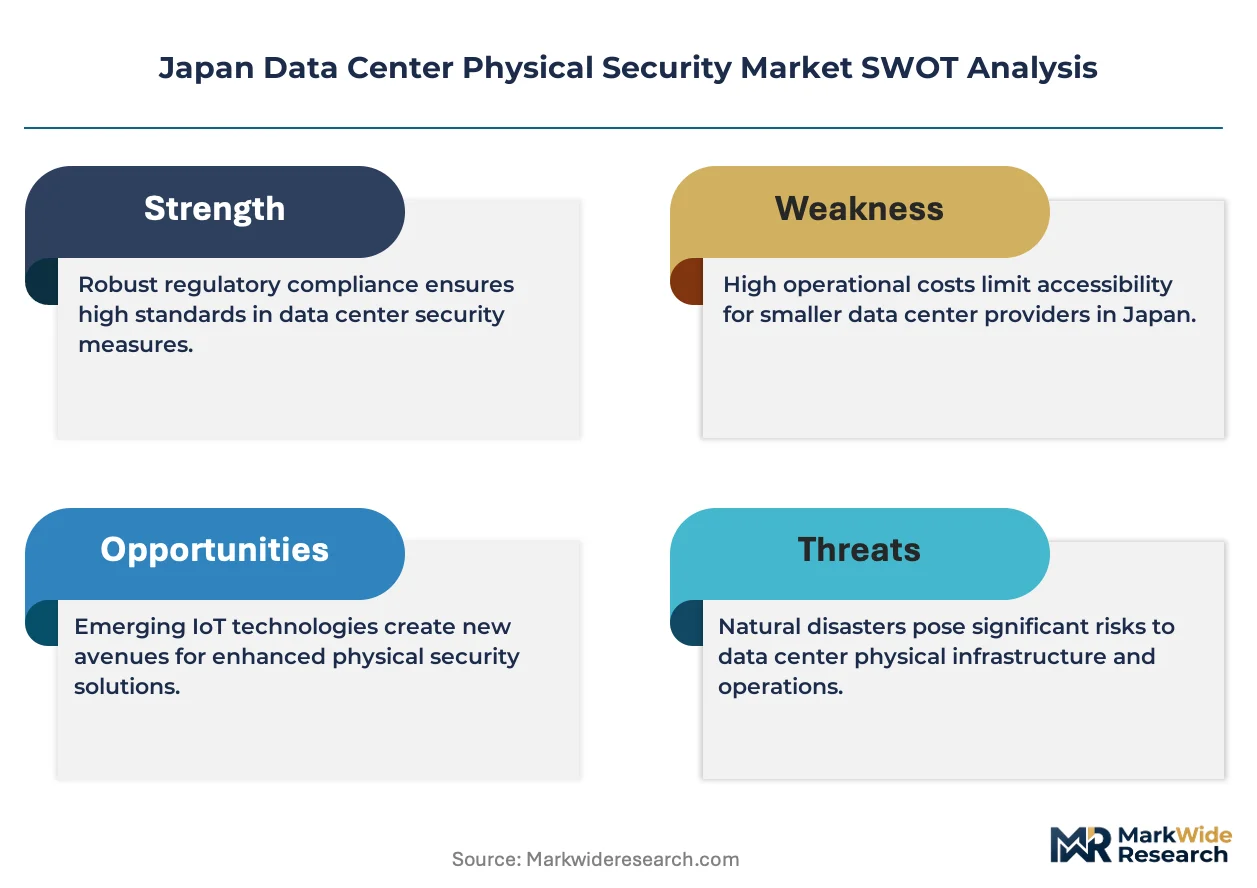
METI facility guidelines and JIS standards for seismic resilience shape equipment mounting, enclosure hardening, and redundancy specifications that vendors must satisfy for domestic market access. PMDA data-protection protocols for pharmaceutical and medical cloud infrastructure add compliance layers that drive premium-tier security architecture. Stakeholders must monitor evolving METI energy-efficiency mandates that increasingly tie physical security power consumption to overall facility certification status.
Market Dynamics
Hyperscale cloud expansion across Greater Tokyo and Osaka is compressing procurement cycles and forcing seismic-hardened designs into tighter integration with biometric and video analytics layers.
Growth Catalysts
- METI data sovereignty mandates:Domestic infrastructure resilience requirements tighten compliance specifications for perimeter protection and access logging, pulling investment toward certified domestic suppliers.
- Multimodal biometric adoption:Financial services end users accelerate deployment of fingerprint-iris fusion systems for high-assurance zones, expanding margin pools in access control hardware.
- Earthquake-hardened campus construction:Hyperscale operators in Tokyo Bay and Osaka Plain demand integrated environmental monitoring tied to physical security dashboards, bundling previously separate procurement categories.
Market Restraints
- Specialized engineering talent scarcity:Domestic construction firms with JIS-certified seismic integration expertise command premium pricing, constraining vendor margin expansion.
- Component import concentration:High-resolution image sensors and specialized biometric modules flow through limited Asian supply corridors, exposing lead time volatility.
- PMDA pharmaceutical cloud protocols:Data-protection layering for medical infrastructure adds certification friction that extends sales cycles by 6-12 months for non-incumbent vendors.
Strategic Opportunities
- Fukuoka-Kyushu corridor underpenetration:Secondary data center clusters outside Kanto lack mature security integrator networks, creating first-mover positioning for bundled service entrants.
- AI-enabled video analytics convergence:Edge computing deployment at camera endpoints enables real-time anomaly detection without centralized processing, compressing response latency for critical facility zones.
- METI energy-efficiency certification linkage:Physical security power consumption now factors into overall facility certification status, creating demand for low-draw biometric and surveillance architectures.
Industry Challenges
- Seismic-JIS certification timelines:Equipment mounting and enclosure hardening validation stretches product launch schedules, forcing vendors to front-load regulatory engagement.
- Legacy access control integration:Established financial and telecom facilities operate proprietary credential systems that resist open-architecture migration without costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Data Center Physical Security Market |
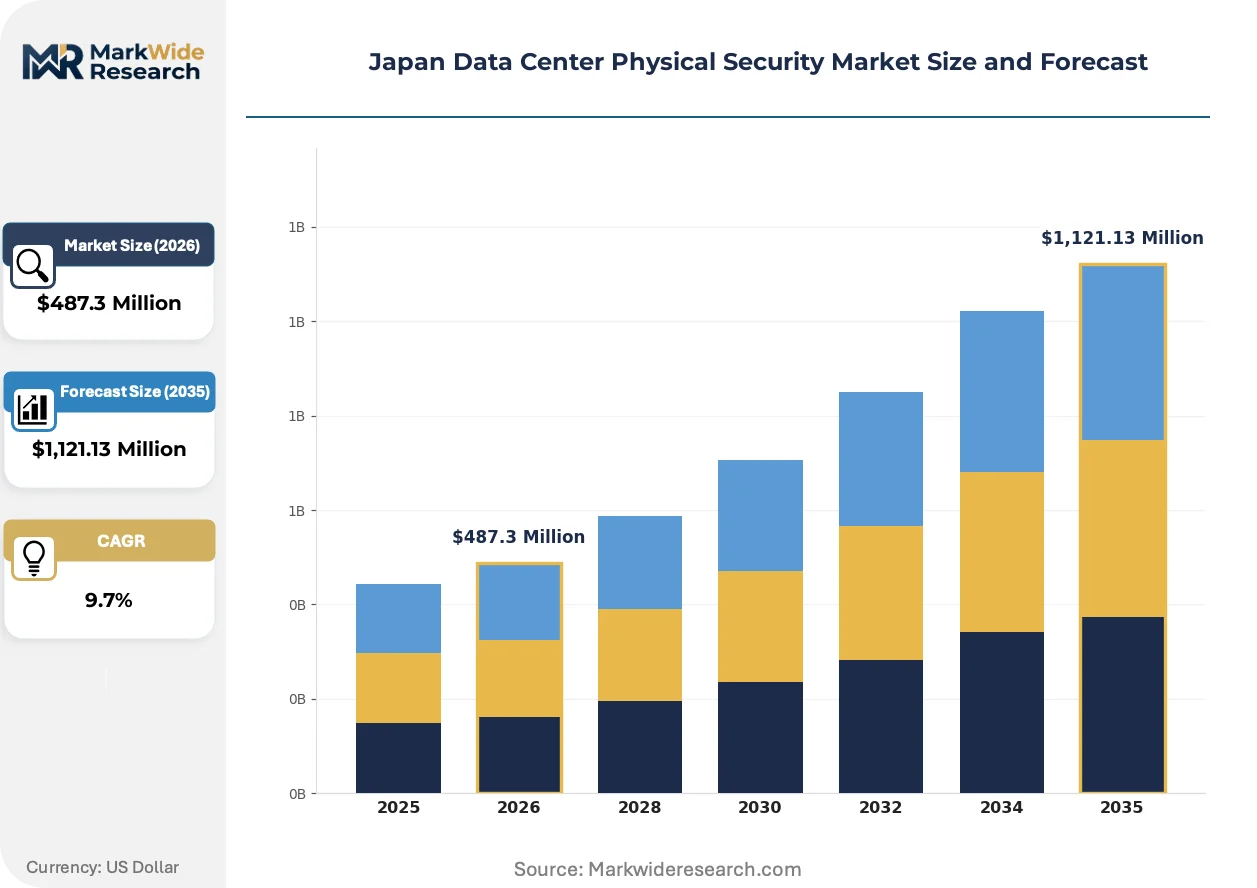
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,121.13 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Access Control Systems, Surveillance Cameras, Intrusion Detection, Environmental Monitoring Service Type: Consulting, Installation, Maintenance, Managed Security Services End User: Telecommunications, Cloud Service Providers, Government, Financial Services Application: Preventive Security, Risk Assessment, Emergency Response, Compliance Management |
| Companies Covered | Axis Communications AB, Bosch Sicherheitssysteme GmbH, Honeywell International Inc., Johnson Controls, ABB Ltd, Schneider Electric, ASSA ABLOY, Cisco Systems Inc., Dahua Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Data Center Physical Security Market Trends and Innovations
Edge-native processing architectures are collapsing the traditional boundary between surveillance capture and real-time decision layers, compressing infrastructure footprints while elevating software dependency.
AI-enabled video analytics is integrating behavioral pattern recognition directly into camera firmware, eliminating centralized server bottlenecks. Hyperscale operators in Tokyo and Osaka deploy these systems across perimeter and internal zones simultaneously. This compression of processing geography is integrating security operations with facility management dashboards through unified data streams.
METI facility guidelines now mandate redundant power and environmental monitoring as co-certified elements of physical security architecture. Vendors must demonstrate seismic resilience across integrated system stacks rather than isolated components. Pharmaceutical and medical cloud infrastructure faces additional PMDA data-protection layering that drives premium-tier specification adoption.
Cloud service providers increasingly unbundle hardware procurement from continuous monitoring obligations, contracting specialized operators for round-the-clock incident response. This service separation compresses capital deployment for facility owners while shifting operational risk to managed security providers. Financial services verticals in Tokyo exhibit the strongest preference for outsourced monitoring given regulatory audit trail requirements.
Japan Data Center Physical Security Market Segmentation
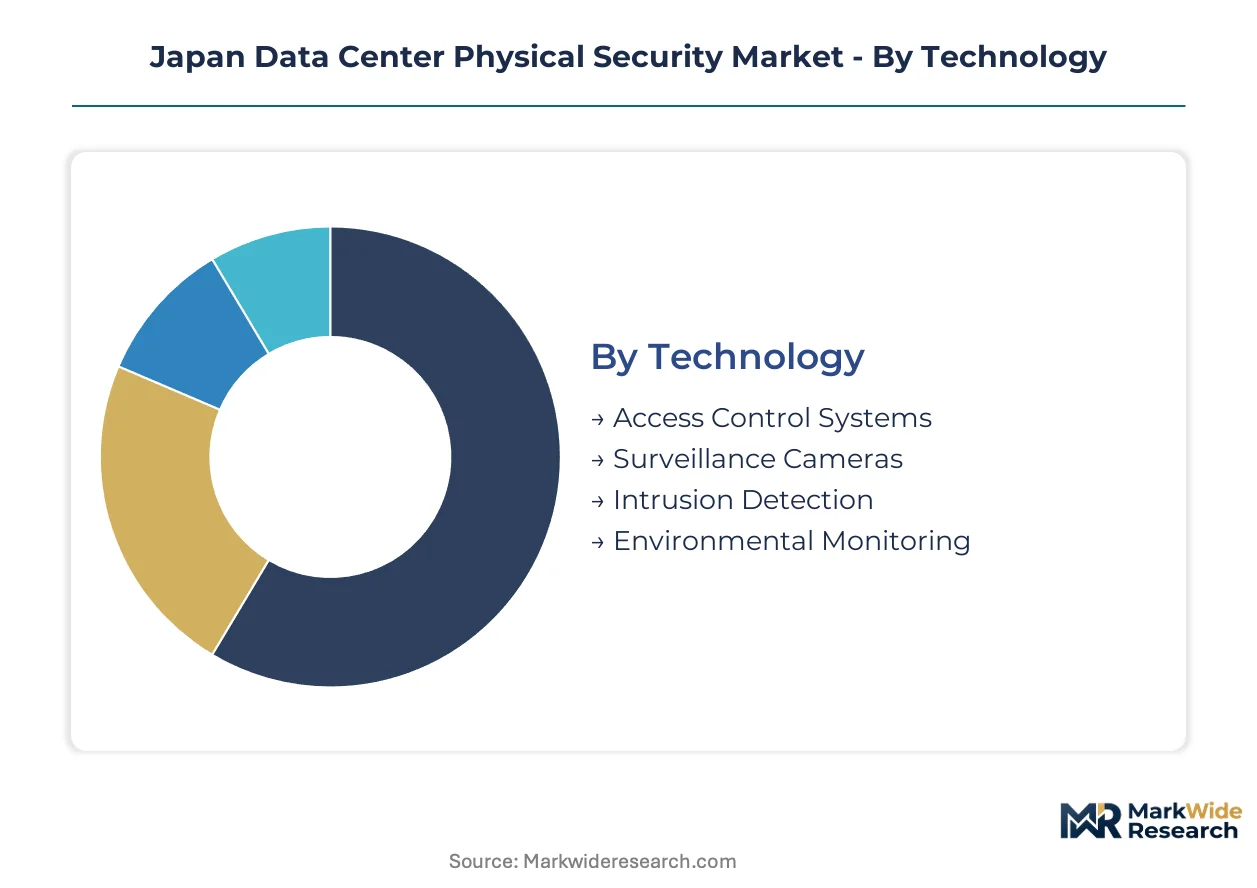
Japan's data center physical security market fragments across technology stacks, service delivery models, and end-user verticals with distinct procurement rhythms. METI compliance mandates and seismic resilience requirements pull segmentation toward integrated rather than component-based purchasing across hyperscale campuses in Greater Tokyo and Osaka.
Technology:
Specification hierarchies in Japanese deployments prioritize earthquake-hardened enclosures with integrated biometric and video analytics layers.
- Surveillance Cameras:AI-enabled video analytics with edge-native processing architectures dominate hyperscale operator procurement in Tokyo Bay. Cloud service providers demand behavioral pattern recognition firmware that eliminates centralized server bottlenecks for real-time perimeter monitoring.
- Access Control Systems:Multimodal biometric hardware—fingerprint-iris fusion systems—commands premium positioning in financial services facilities across central Tokyo. METI data sovereignty mandates tighten audit trail specifications for high-assurance zones.
- Intrusion Detection:Seismic-resistant sensor arrays with redundant power integration meet JIS-certified mounting requirements for Osaka Plain campuses.
- Environmental Monitoring:Temperature-humidity-vibration sensing bundles now co-certify with physical security stacks under METI facility guidelines.
Mature deployment sits with Surveillance Cameras. Newer deployment is concentrated in Environmental Monitoring.
Service Type:
Procurement unbundling separates capital hardware from continuous operational obligations across Japanese facility operators.
- Managed Security Services:Round-the-clock monitoring and incident response outsourcing compresses capital deployment for cloud service providers in Greater Tokyo. Financial services verticals exhibit strongest preference given regulatory audit trail requirements.
- Installation:JIS-certified seismic integration expertise concentrates among domestic construction firms with specialized engineering partnerships.
- Maintenance:Post-deployment service contracts extend vendor relationships through equipment lifecycle management.
- Consulting:Compliance architecture design for PMDA pharmaceutical cloud protocols extends sales cycles with certification friction.
Revenue concentration favors Managed Security Services. Margin expansion concentrates in Installation due to scarce certified engineering talent.
End User:
Vertical-specific compliance layering shapes security architecture depth across Japanese data center demand.
- Cloud Service Providers:Hyperscale operators in Tokyo and Osaka drive bundled procurement of biometric-video-environmental integrated stacks with aggressive facility footprint expansion.
- Financial Services:Tokyo-based banks and insurers accelerate multimodal biometric adoption with premium-tier specification for high-assurance zones.
- Government:METI facility guidelines mandate domestic infrastructure resilience with tightened perimeter protection and access logging.
- Telecommunications:Legacy facilities operate proprietary credential systems resisting open-architecture migration without costly middleware development.
Volume leadership belongs to Cloud Service Providers. PMDA compliance complexity elevates specification intensity for Financial Services.
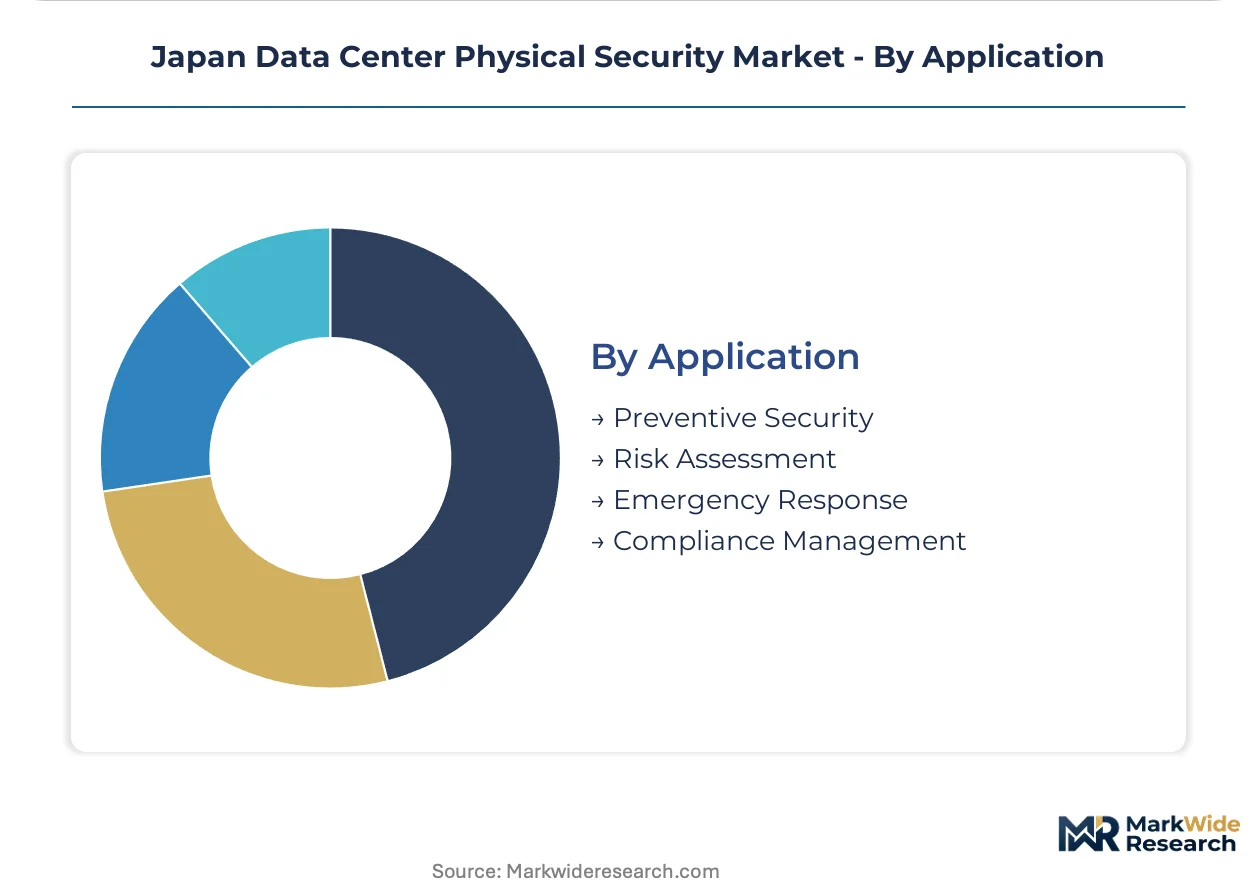
Application:
Functional deployment priorities reflect regulatory pressure sequencing across facility lifecycle management.
- Compliance Management:METI data sovereignty and PMDA pharmaceutical protocols drive premium-tier architecture with redundant certification documentation.
- Preventive Security:Perimeter barriers and access control layers form baseline procurement for all facility tiers.
- Emergency Response:Earthquake-triggered automated protocols integrate physical security dashboards with environmental monitoring systems.
- Risk Assessment:Pre-deployment vulnerability analysis informs seismic-hardened design specifications for Osaka Plain and Tokyo Bay construction.
Procurement priority ranks Compliance Management highest. Operational deployment frequency concentrates in Preventive Security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Greater Tokyo and Osaka while consumption spreads across secondary clusters seeking seismic resilience and METI compliance. Domestic infrastructure mandates pull investment toward certified suppliers with JIS integration expertise.
Kanto/Tokyo
Hyperscale cloud operators dominate procurement of bundled biometric-video-environmental stacks across Tokyo Bay campuses. METI data sovereignty requirements tighten perimeter protection specifications and access logging protocols. Financial services verticals in central Tokyo accelerate multimodal biometric deployment for high-assurance zones.
Kansai/Osaka
Osaka Plain construction demands earthquake-hardened designs with integrated sensor arrays and redundant power systems. JIS-certified mounting requirements for seismic-resistant enclosures extend vendor certification timelines. Cloud service providers expand facility footprints aggressively while outsourcing round-the-clock monitoring to managed security specialists.
Chubu/Nagoya
Industrial automation heritage creates demand for environmental monitoring tied to physical security dashboards. Manufacturing-linked data centers require vibration-sensing bundles that co-certify with security stacks under METI guidelines. Nagoya-based integrators specialize in construction-firm partnerships for seismic integration.
Kyushu
Fukuoka corridor remains underpenetrated with immature security integrator networks relative to Kanto. Secondary data center clusters seek bundled service entrants for first-mover positioning. Local operators face certification friction for PMDA pharmaceutical cloud protocols that extend sales cycles.
Hokkaido
Cold-climate data center development drives environmental threat monitoring specifications for temperature-humidity sensing. Remote location increases preference for outsourced managed security services over in-house operations. Sapporo-area facilities prioritize earthquake-triggered automated protocols integrating physical security with building management systems.
Japan Data Center Physical Security Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement categories. The market structures around three tiers: building-management heritage players extending into security dashboards, specialized biometric and surveillance component manufacturers, and managed service operators capturing outsourced monitoring obligations. Consolidation pressure intensifies as hyperscale operators compress procurement cycles and demand bundled certification across integrated system stacks.
Among European-headquartered security specialists, Axis Communications AB and Bosch Sicherheitssysteme GmbH occupy positions reflecting deep channel control and high-assurance biometric engineering respectively. Johnson Controls represents the building-management heritage archetype extending into environmental monitoring integration. These three exemplify how vendor positioning stratifies between component specialization and systems integration capabilities.
| Leading Market Players |
|---|
| Axis Communications AB |
| Bosch Sicherheitssysteme GmbH |
| Honeywell International Inc. |
| Johnson Controls |
| ABB Ltd |
| Schneider Electric |
| ASSA ABLOY |
| Cisco Systems Inc. |
| Dahua Technology |
| Others |
Pricing and Supply Chain Analysis
Specialist security integrators rolled up through private-equity consolidation command pricing power across Kanto-region hyperscale deployments, translating scarce JIS-certified engineering capacity into premium service rates while compressing component margins through volume aggregation.
Pricing Analysis
Margin tightening in biometric hardware reflects multimodal fusion complexity and METI audit-trail certification costs. Three-tier pricing structure across premium, standard, and economy levels separates financial services specifications from cloud provider procurement and government baseline deployments. Pricing pressure stems from hyperscale buyers bundling surveillance-access-environmental stacks into single-source contracts. Cloud service providers exhibit highest price sensitivity; pharmaceutical operators under PMDA protocols show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated security suites across Greater Tokyo. Manufacturing concentrates in Japan, South Korea, and Taiwan for seismic-hardened enclosures and edge-native camera processors. High-resolution image sensors and specialized biometric modules draw from concentrated Asian supply corridors. Single-source vulnerability in semiconductor-grade sensor components exposes lead time volatility. Distribution runs through domestic construction-firm partnerships with JIS certification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge-native AI processing architectures are displacing centralized server-based video analytics, forcing legacy infrastructure operators toward firmware-integrated behavioral recognition systems.
For Market Incumbents: Acquire JIS-certified seismic engineering partnerships to lock in construction-firm channel control against emerging bundled-service competitors. Consolidate managed security service capabilities to capture cloud provider outsourcing momentum as procurement unbundling accelerates. Threat substitution from AI-native camera firmware compresses hardware replacement cycles; lever R&D investment into edge-computing biometric modules. For New Entrants and Emerging Players: Begin with Fukuoka-Kyushu corridor penetration where security integrator networks remain immature relative to Kanto density. White-space targets include pharmaceutical cloud infrastructure facing PMDA certification friction that extends incumbent sales cycles. Go-to-market angle emphasizes rapid METI compliance documentation for mid-tier data center operators bypassing hyperscale procurement complexity. For Investors and Strategic Acquirers: Distressed-cycle entries favor managed security service operators with established Tokyo-Osaka monitoring infrastructure over capital-intensive hardware manufacturers. Long-term viability centers on recurring revenue models as facility owners outsource round-the-clock incident response. Signal to watch is METI energy-efficiency certification linkage tightening physical security power consumption standards.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric-Video Integration | Firmware-level fusion eliminates middleware costs for Tokyo financial services deployments. |
| JIS Certification Investment | Seismic resilience validation opens Osaka Plain hyperscale construction pipelines. |
| Managed Security Service Expansion | Outsourced monitoring captures cloud provider operational risk transfer. |
| Edge-Native Processing Development | Camera-embedded AI reduces centralized infrastructure for real-time anomaly detection. |
| Environmental Monitoring Bundling | Temperature-humidity-vibration co-certification meets METI facility guideline requirements. |
Research Methodology
Trade association filings, customs import records, and METI regulatory guidance documents formed the secondary backbone. Primary interviews with data center facility managers, security system integrators, JIS certification engineers, and cloud provider procurement officers validated demand-side assumptions. Bottom-up and top-down triangulation cross-referenced equipment shipment data against facility construction permits across the analysis window.
Bottom-up modeling aggregated individual technology segment trajectories while top-down validation checked aggregate figures against infrastructure investment disclosures. Segmentation dimensions included technology stack, service delivery model, end-user vertical, and regional compliance cluster. CAGRs derived from equipment replacement cycles, facility expansion pipelines, and regulatory mandate implementation timelines. Forecast inputs incorporated hyperscale operator capex commitments and seismic resilience specification evolution.
Underlying measurement precision varies by segment; surveillance camera volumes carry tighter precision than emerging environmental monitoring categories. Forecasts reflect assumptions about METI guideline enforcement intensity and PMDA pharmaceutical cloud protocol adoption velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Japan Data Center Market
Data Center Infrastructure
Asia-Pacific Data Center Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
China Data Center Storage Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
Public Cloud System Infrastructure Service Market
Data Center Infrastructure
Europe Data Center Construction Market
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
South Africa Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Server Market