
 North America Data Center Infrastructure Management Market | 2026-2036
North America Data Center Infrastructure Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Data Center Infrastructure Management Market Analytics
The gap between premium AI-optimized DCIM suites and commodity monitoring tools is expanding across North American facilities. Schneider Electric leverages deep integration with its power distribution hardware to anchor high-margin enterprise contracts. Vertiv competes through thermal management specialization that extends its software value proposition into liquid cooling coordination. Device42 differentiates via agentless discovery technology that maps hybrid infrastructure without deployment friction.
Data Center Infrastructure Management encompasses software, hardware, and services that monitor, measure, manage, and control data center resources and energy consumption across IT and facility infrastructure, typically operating through protocols such as SNMP, Modbus, and BACnet to aggregate real-time telemetry from power distribution units, cooling systems, and server assets. Its primary commercial purpose is to optimize capacity utilization, prevent downtime, and reduce operational expenditure across multi-tenant and enterprise facilities. Software platforms capture the dominant margin pool as operators prioritize predictive analytics and digital twin capabilities over basic monitoring. Cloud-based and hybrid deployment models are gaining fastest among service providers managing distributed edge footprints, while on-premise installations retain strength in financial services and government end users with stringent data sovereignty requirements.
FERC Order 2222 and state public utility commission rules across Texas, California, and New York are reshaping how data centers participate in demand response programs, directly influencing DCIM investment for load flexibility verification. NERC CIP reliability standards enforce cybersecurity monitoring of critical cyber assets, compelling operators to integrate security event management into infrastructure platforms. EPA Energy Star certification and emerging DOE efficiency benchmarks further tighten performance disclosure requirements. Stakeholders must weigh capital allocation between retrofitting legacy facilities with integrated DCIM stacks versus greenfield deployments designed around AI workload orchestration from inception.
Market Dynamics
Hyperscale cloud operators are forcing a bifurcation in DCIM procurement patterns, splitting the market between integrated platform investments for new builds and retrofit complexity for legacy facilities. This structural tension concentrates vendor attention on Northern Virginia's Data Center Alley while leaving secondary markets underserved.
Growth Catalysts
- NERC CIP reliability standards:Cybersecurity monitoring mandates for critical cyber assets compel operators to embed security event management within infrastructure platforms, expanding software attach rates.
- State clean energy mandates:California's SB 100 and New York's CLCPA accelerate demand for load flexibility verification tools that DCIM platforms provide for grid-interactive data centers.
- Liquid cooling coordination:AI workload densities above 50kW per rack require thermal management software that orchestrates direct-to-chip and immersion systems as standard practice.
Market Restraints
- Copper and rare earth input volatility:Power distribution hardware costs fluctuate with commodity markets, compressing margins for integrated DCIM-hardware bundles.
- Vendor concentration in power distribution:Three suppliers control over 70% of intelligent PDU manufacturing, creating single-source risk for integrated deployments.
- Legacy protocol fragmentation:BACnet, Modbus, and SNMP interoperability gaps force expensive middleware development for brownfield installations.
Strategic Opportunities
- Texas ERCOT demand response participation:FERC Order 2222 implementation creates first-mover advantage for DCIM vendors certifying load flexibility in the state's deregulated power market.
- Edge facility distributed footprints:Cloud providers' metro edge expansions into secondary cities require lightweight, cloud-native DCIM deployments without on-premise infrastructure.
- Digital twin convergence with AI operations:Physics-based simulation layered with machine learning inference enables predictive failure modeling that basic monitoring cannot replicate.
Industry Challenges
- Facility engineer skill scarcity:Cross-functional expertise spanning electrical engineering, thermal physics, and software integration commands premium compensation that strains operator opex.
- NERC CIP compliance timeline compression:Reliability standard enforcement windows leave insufficient runway for legacy system retrofits without operational disruption.
- Hybrid cloud visibility gaps:Agentless discovery tools struggle to map ephemeral container workloads across multi-cloud architectures with sufficient granularity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Data Center Infrastructure Management Market |
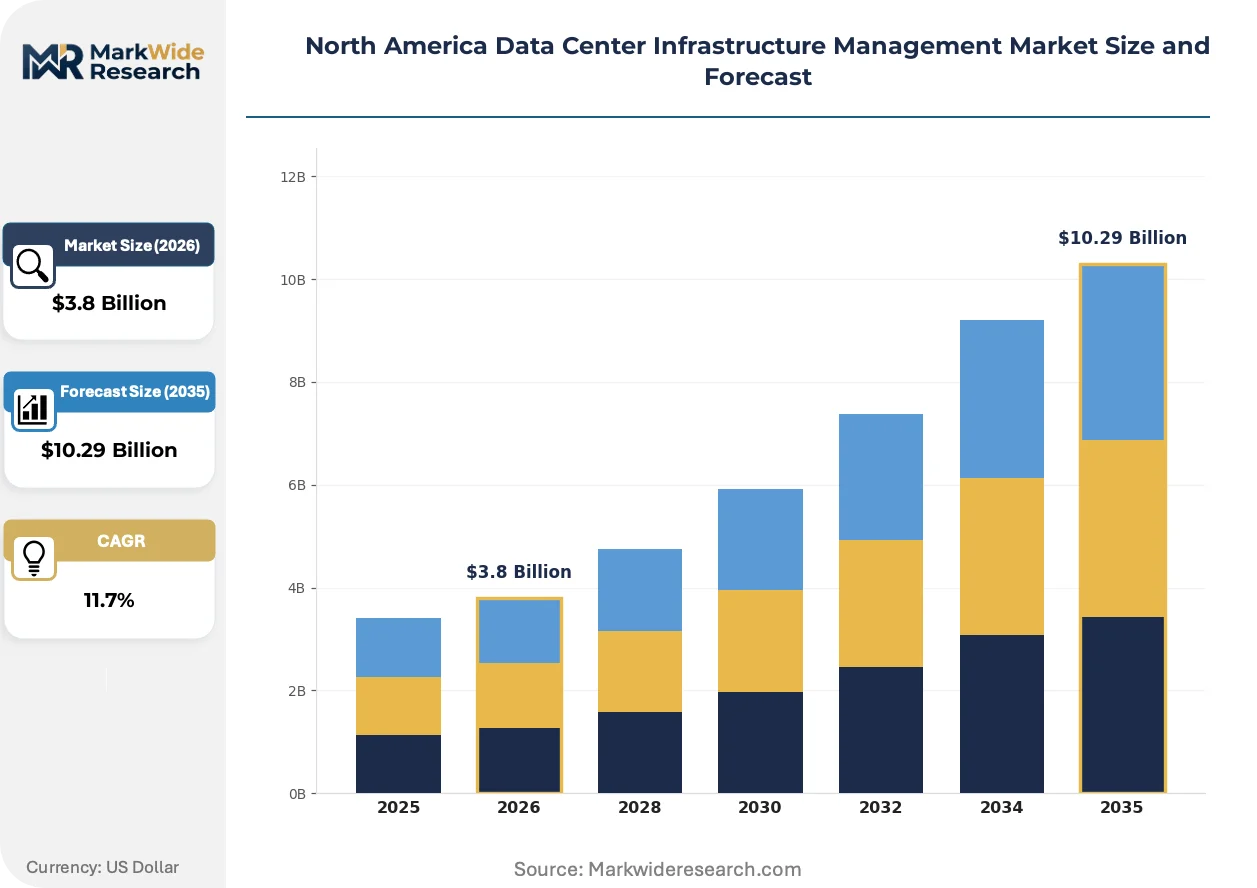
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Services, Hardware, Platform Deployment Model: On-Premise, Cloud-Based, Hybrid, Multi-Cloud End User: Small Enterprises, Large Enterprises, Government, Service Providers Management Function: Capacity Planning, Asset Management, Performance Monitoring, Alarming |
| Companies Covered | Schneider Electric, Vertiv, Johnson Controls, Eaton, ABB, Device42, FNT Software, Modius, Sunbird Software, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Data Center Infrastructure Management Market Evolving Landscape
Software-defined power and thermal orchestration is displacing static provisioning models across North American facilities. This shift reconfigures vendor value propositions from monitoring dashboards toward autonomous infrastructure control.
Digital twin technology is absorbing capital allocation from traditional building management system upgrades. These virtual replicas simulate power flow, thermal distribution, and failure scenarios before physical deployment. Hyperscale operators in Northern Virginia and Dallas-Fort Worth are mandating twin-based commissioning for new facilities. The technology is compressing design-validation cycles from months to weeks while reducing stranded capacity risk.
FERC Order 2222 and companion state utility commission rules are reshaping data center participation in wholesale electricity markets. The regulation enables aggregated distributed energy resources to bid into grid services, creating revenue streams that justify advanced DCIM instrumentation. Texas and California facilities face the steepest compliance curves as their markets open first to demand response aggregation.
Colocation buyers are unbundling facility management services from rack contracts, treating DCIM access as a separately negotiable line item. This procurement pattern forces operators to price software transparency independently from space and power. Financial services tenants in New York and Chicago metro markets are driving the practice, using their own telemetry layers to verify SLA compliance rather than trusting provider dashboards.
North America Data Center Infrastructure Management Market Segmentation
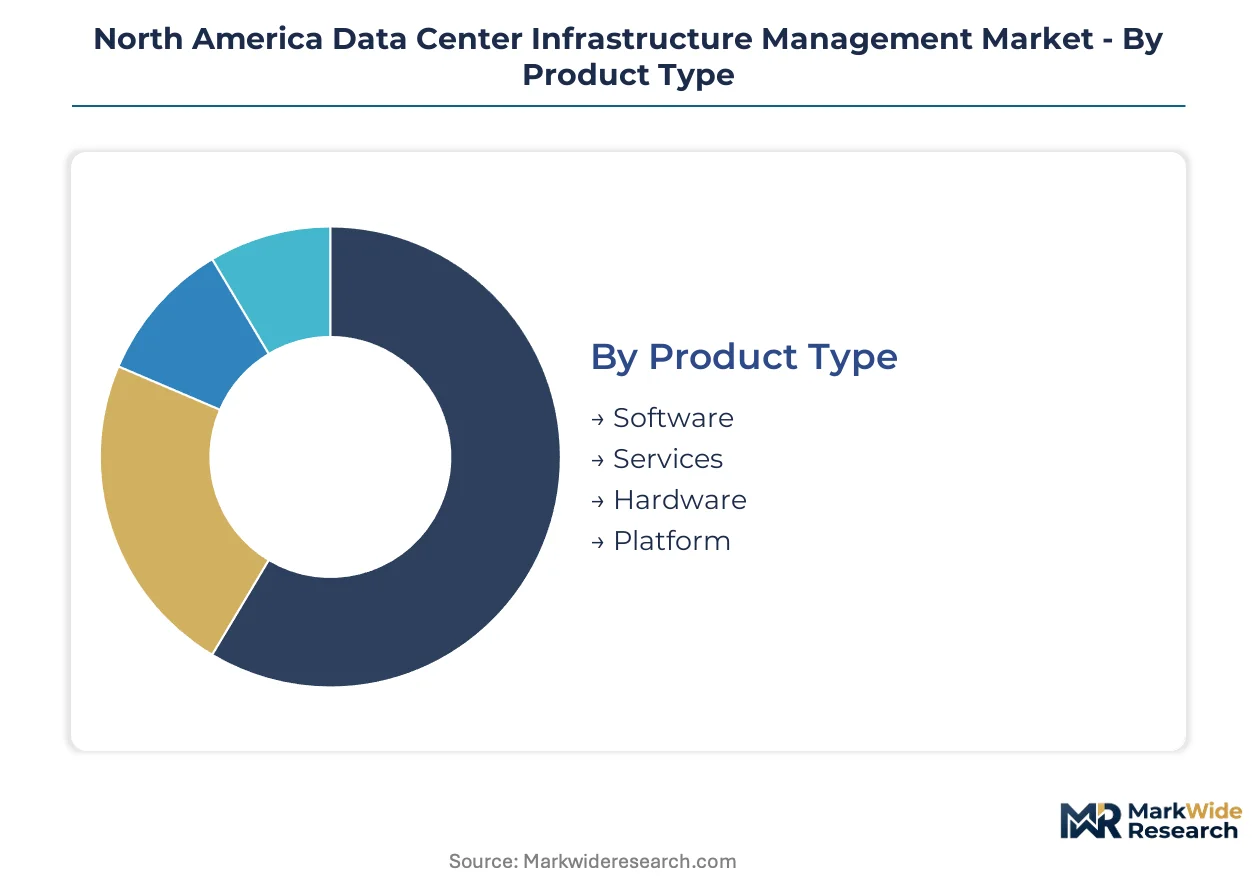
DCIM procurement patterns fragment sharply between hyperscale cloud operators demanding unified platforms and legacy enterprises managing retrofit complexity. Understanding these segment boundaries reveals where vendor R&D investments concentrate versus where price competition erodes margins.
Product Type:
Software commands premium pricing through predictive analytics modules, while hardware bundles face commodity pressure from intelligent PDU standardization.
- Software:Platforms aggregate real-time telemetry from power distribution units, cooling systems, and server assets through SNMP, Modbus, and BACnet protocols. Demand concentrates most intensely in Northern Virginia's Data Center Alley, where facility density drives advanced monitoring investments for multi-tenant optimization.
- Services:Implementation and integration offerings bridge brownfield protocol fragmentation for legacy facility retrofits. Financial services tenants in New York and Chicago metro markets are unbundling these services from colocation contracts, treating DCIM deployment as separately negotiable.
- Hardware:Intelligent PDUs and environmental sensors form the physical telemetry layer. Copper and rare earth input volatility compresses margins for integrated DCIM-hardware bundles.
- Platform:Unified suites combining software, hardware, and managed services. Hyperscale cloud operators are accelerating adoption across their facilities for AI workload orchestration.
Mature deployment sits with Hardware. Newer deployment is concentrated in Platform.
Deployment Model:
Cloud-native architectures are expanding most quickly among service providers managing distributed edge footprints, while sovereign data requirements protect on-premise installations.
- On-Premise:Installations retain strength in financial services and government end users with stringent data sovereignty requirements. FERC Order 2222 compliance for demand response participation still requires localized control systems in Texas ERCOT markets.
- Cloud-Based:Lightweight deployments serve cloud providers' metro edge expansions into secondary cities without on-premise infrastructure overhead. EPA Energy Star certification and emerging DOE efficiency benchmarks tighten performance disclosure requirements for these configurations.
- Hybrid:Architectures split critical control functions locally while pushing analytics to cloud tiers. NERC CIP reliability standards enforce cybersecurity monitoring that complicates this split for critical cyber assets.
- Multi-Cloud:Orchestration layers map infrastructure across AWS, Azure, and Google Cloud environments. Agentless discovery tools struggle to map ephemeral container workloads with sufficient granularity.
Regulatory compliance anchors On-Premise. Operational flexibility is driving Hybrid expansion.
End User:
Large enterprises generate the deepest software attach rates, while service providers are forcing vendor roadmaps toward API-first architectures.
- Small Enterprises:Limited IT staffing drives preference for managed DCIM services over in-house platform operation. SaaS pricing models reduce capital barriers for these buyers.
- Large Enterprises:Multi-facility footprints justify integrated platform investments with digital twin capabilities. State clean energy mandates in California and New York accelerate demand for load flexibility verification tools.
- Government:Federal data centers face NERC CIP reliability standards with compressed compliance timelines. Procurement cycles favor established vendors with FedRAMP authorization.
- Service Providers:Colocation operators treat DCIM access as a separately negotiable line item from rack contracts. Northern Virginia facilities lead in mandating tenant-facing telemetry transparency.
Procurement standardization dominates Government. Feature velocity is highest among Service Providers.
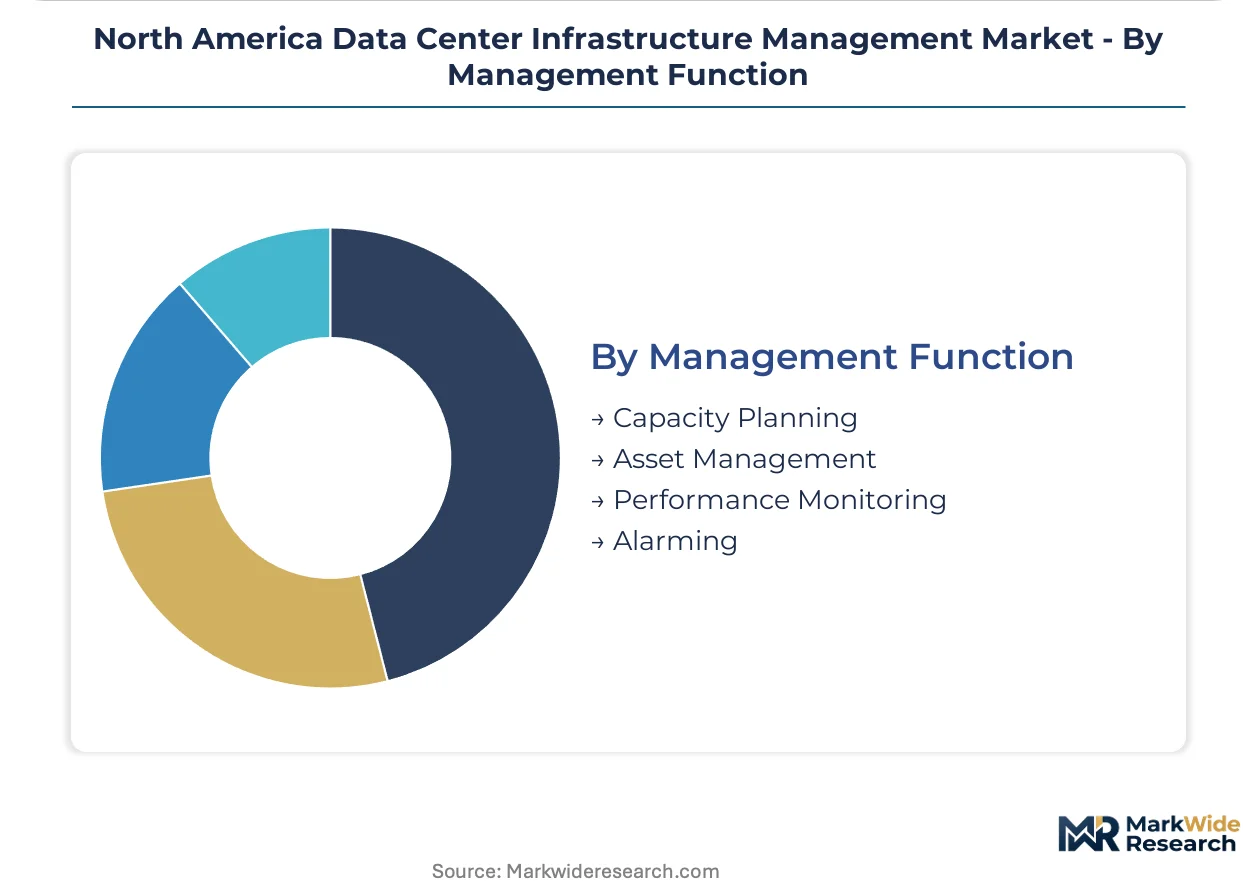
Management Function:
Asset management and capacity planning capture disproportionate R&D investment as AI workload densities reshape power and thermal provisioning.
- Capacity Planning:Physics-based simulation layered with machine learning inference enables predictive failure modeling. Liquid cooling coordination for AI densities above 50kW per rack requires thermal management software as standard practice.
- Asset Management:Agentless discovery technology maps hybrid infrastructure without deployment friction. Device42 and comparable vendors differentiate through reduced implementation overhead.
- Performance Monitoring:Real-time dashboards track PUE, WUE, and carbon intensity metrics. Schneider Electric leverages deep integration with its power distribution hardware to anchor high-margin enterprise contracts.
- Alarming:Threshold-based notifications escalate to security event management platforms. Vertiv competes through thermal management specialization extending into cooling coordination.
Basic functionality resides in Alarming. Predictive capabilities are advancing fastest in Capacity Planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's Data Center Alley anchors North American DCIM deployment intensity, with facility density driving advanced monitoring investments across multi-tenant and hyperscale footprints.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth mandate digital twin-based commissioning for new facilities, compressing design-validation cycles. FERC Order 2222 enables aggregated distributed energy resources to bid into Texas ERCOT wholesale markets, creating demand response revenue streams. California's SB 100 clean energy mandate accelerates load flexibility verification tool adoption across Silicon Valley and Los Angeles metro facilities.
Canada
Financial services tenants in Toronto and Montreal drive unbundled DCIM procurement, treating software transparency as separately negotiable from colocation contracts. Federal data centers face compressed compliance timelines for cybersecurity monitoring standards. Hydro-Québec's low-carbon power attracts AI training facility investments around Montreal, requiring liquid cooling coordination software for densities above 50kW per rack.
Mexico
Nearshoring manufacturing demand fuels edge facility expansion into Querétaro and Nuevo León, requiring lightweight cloud-native DCIM deployments. CFE grid instability drives investment in localized power quality monitoring and backup orchestration. Monterrey's emerging data center cluster attracts cross-border capacity from US operators seeking geographic diversification.
North America Data Center Infrastructure Management Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software-hardware integration depth, with unified platform vendors capturing attach rates that basic monitoring tools cannot replicate. The vendor base organizes into three strategic tiers: integrated infrastructure conglomerates, thermal management specialists, and agentless discovery pure-plays. Dominant competitive moves include portfolio diversification through adjacent software acquisitions and vertical integration into intelligent power distribution hardware.
Within the integrated platform tier, Schneider Electric and Vertiv anchor high-margin enterprise positioning through deep hardware-software bundling. Device42 exemplifies the agentless discovery archetype, reducing deployment friction for hybrid infrastructure mapping. Johnson Controls and Eaton occupy positions bridging facility automation with IT infrastructure visibility.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv |
| Johnson Controls |
| Eaton |
| ABB |
| Device42 |
| FNT Software |
| Modius |
| Sunbird Software |
| Others |
Value Network & Pricing Analysis
Backward integration into intelligent PDU manufacturing anchors pricing power for Schneider Electric and Vertiv, compressing margins for vendors dependent on third-party power distribution hardware. This captive supply structure concentrates cost control among integrated platform providers while forcing pure-play software vendors toward subscription models to offset hardware procurement volatility.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for DCIM platforms serving hyperscale operators, with Schneider Electric commanding premiums through deep hardware-software bundling. Three-tier pricing structure across enterprise, mid-market, and edge deployments stratifies by deployment complexity and integration depth. Pricing pressure stems from intelligent PDU standardization commoditizing the hardware telemetry layer. Small enterprises exhibit highest price sensitivity, driving SaaS preference over perpetual licensing.
Supply Chain Analysis
Regional distribution centers in Texas, California, and Northern Virginia feed hub-and-spoke patterns serving data center construction clusters. Manufacturing concentrates in China, Mexico, and the United States for environmental sensors and power distribution units. Copper and rare earth dependencies create input cost volatility. Single-source vulnerability concentrates in intelligent PDU controllers from three dominant suppliers. Distribution runs through direct OEM channels and specialized IT infrastructure distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NERC CIP reliability standards construct a cost-of-compliance moat that favors established vendors with FedRAMP authorization and embedded security event management capabilities, raising barriers for unproven entrants lacking certification infrastructure.
For Market Incumbents: Lock in hyperscale cloud contracts through digital twin commissioning mandates that embed long-term platform dependencies. Acquire agentless discovery specialists to neutralize Device42's deployment-friction advantage. Prioritize Texas ERCOT demand response certification to capture FERC Order 2222 revenue streams before competitors complete compliance cycles.
For New Entrants and Emerging Players: Enter via lightweight cloud-native DCIM deployments targeting cloud providers' metro edge expansions into secondary North American cities. Focus initial penetration on colocation operators unbundling facility management services from rack contracts. Lead with API-first architectures that service providers force onto vendor roadmaps.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated infrastructure conglomerates seeking software attach rate expansion. Long-term viability favors vendors with thermal management specialization bridging liquid cooling coordination for AI densities above 50kW per rack. Monitor FERC Order 2222 implementation velocity across state utility commissions as inflection indicator for demand response monetization potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep hardware-software bundling anchors Schneider Electric's enterprise contract retention. |
| Acquisition of Specialist Firm | Agentless discovery capabilities reduce deployment friction for hybrid infrastructure mapping. |
| Geographic Expansion | Texas ERCOT demand response certification captures FERC Order 2222 grid services revenue. |
| Product Launch | Liquid cooling coordination software addresses AI workload densities above 50kW per rack. |
| Strategic Partnership | Colocation telemetry transparency mandates in Northern Virginia drive tenant-facing dashboard development. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, state utility commission rulemakings, and NERC CIP enforcement timelines anchored the trend analysis, supplemented by interviews with data center facility engineers, colocation procurement officers, DCIM platform product managers, and thermal management specialists. Secondary validation drew from FERC filings, EPA Energy Star certification databases, hyperscaler sustainability reports, and intelligent PDU manufacturer SEC disclosures. Bottom-up facility deployment estimates triangulated against top-down software revenue aggregation.
Input-output matrices modeled deployment model, end-user scale tier, management function depth, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market boundary conditions. Forecast inputs incorporated AI workload density trajectories, state clean energy mandate compliance deadlines, and copper price volatility assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated NERC CIP enforcement or prolonged copper supply disruption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Data Center Rack PDU Market
Data Center Infrastructure
Germany Data Center Power Market
Data Center Infrastructure
Denmark Data Center Power Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Global Data Center Accelerator Market
Data Center Infrastructure
Fiber Management Systems Market
Data Center Infrastructure
China Data Center Storage Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Philippines Data Center Rack Market