
 Brazil Data Center Physical Security Market | 2026-2036
Brazil Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Data Center Physical Security Market Insights
Multi-vendor integration contracts is pivoting as the dominant sourcing pattern for Brazilian colocation operators. Schneider Electric anchors its position through deep backward integration into building management systems. Hikvision competes aggressively on camera density pricing for large campus deployments. Johnson Controls differentiates through unified command platforms that merge fire suppression with access logging.
Brazil Data Center Physical Security encompasses layered protection systems—biometric readers, video analytics servers, mantrap portals, and fiber-optic perimeter detection—engineered to maintain uptime guarantees exceeding 99.99% for critical infrastructure. These installations serve primarily to prevent unauthorized physical access, environmental sabotage, and supply-chain tampering at facilities processing sensitive financial and health records. CCTV and access control hardware currently capture the bulk of capital expenditure as legacy analog upgrades proceed. Managed services deployment is gaining share fastest among mid-tier banking data centers that lack in-house security operations centers. Integration services command premium pricing where LGPD compliance auditing requires certified documentation trails.
ANVISA mandates pharmaceutical-grade environmental monitoring at health-data facilities, directly expanding demand for biometric-restricted clean zones. ABNT NBR ISO/IEC 27001 certification requirements, coupled with LGPD physical-access logging rules, compel operators to replace standalone locks with networked identity platforms. BIS-equivalent electrical safety standards for critical power paths further shape vendor qualification lists. Stakeholders must weigh the trade-off between cloud-based security management scalability and on-premises data sovereignty as regulatory enforcement tightens.
Market Dynamics
Cloud service providers are accelerating hyperscale campus buildouts across São Paulo state, forcing security vendors to engineer integrated biometric-video-analytics platforms that satisfy ANVISA data integrity rules and LGPD privacy mandates simultaneously.
Growth Catalysts
- ANVISA pharmaceutical-grade mandates:Health-data facilities must deploy biometric-restricted clean zones with continuous environmental monitoring, expanding demand for mantrap portals and fiber-optic perimeter detection at facilities processing sensitive patient records.
- LGPD physical-access logging rules:Operators must replace standalone locks with networked identity platforms that generate certified documentation trails, directly pulling capital into multi-factor authentication hardware and audit-ready management software.
- Hyperscale concentration in Campinas:Cloud providers are clustering facilities near the ABC Paulista corridor, creating dense procurement volumes for unified command platforms that merge fire suppression systems with real-time access logging.
Market Restraints
- Import dependency on specialized sensors:Brazil lacks domestic production of fiber-optic perimeter detection cables and high-resolution thermal cameras, exposing operators to currency volatility and extended lead times from Asian manufacturing hubs.
- ABNT NBR ISO/IEC 27001 certification friction:The multi-stage audit timeline for physical security management systems stretches 14-18 months, delaying facility commissioning and compressing vendor cash conversion cycles.
- Legacy analog infrastructure lock-in:Mid-tier banking data centers face sunk-cost barriers when upgrading from coaxial CCTV networks to IP-based video analytics servers requiring complete cable plant replacement.
Strategic Opportunities
- Managed security services for mid-tier banks:Institutions lacking in-house security operations centers are outsourcing 24/7 monitoring and incident response, creating recurring revenue streams for vendors with LGPD-certified documentation capabilities.
- Integration services premium:Multi-vendor contracts commanding higher margins where compliance auditing requires certified documentation trails spanning biometric readers, video analytics servers, and environmental monitoring systems.
- Edge facility expansion in secondary São Paulo municipalities:Latency-sensitive financial services are driving smaller data center deployments in Sorocaba and Jundiaí, opening demand for modular physical security packages.
Industry Challenges
- Certified security engineer scarcity:The intersection of LGPD compliance auditing, ANVISA environmental protocols, and ABNT certification requirements demands personnel with cross-functional expertise that training institutions have not scaled to produce.
- Multi-vendor integration complexity:Colocation operators stitching together Schneider Electric building management systems, Hikvision camera networks, and Johnson Controls fire suppression platforms face interoperability failures that threaten 99.99% uptime guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Data Center Physical Security Market |
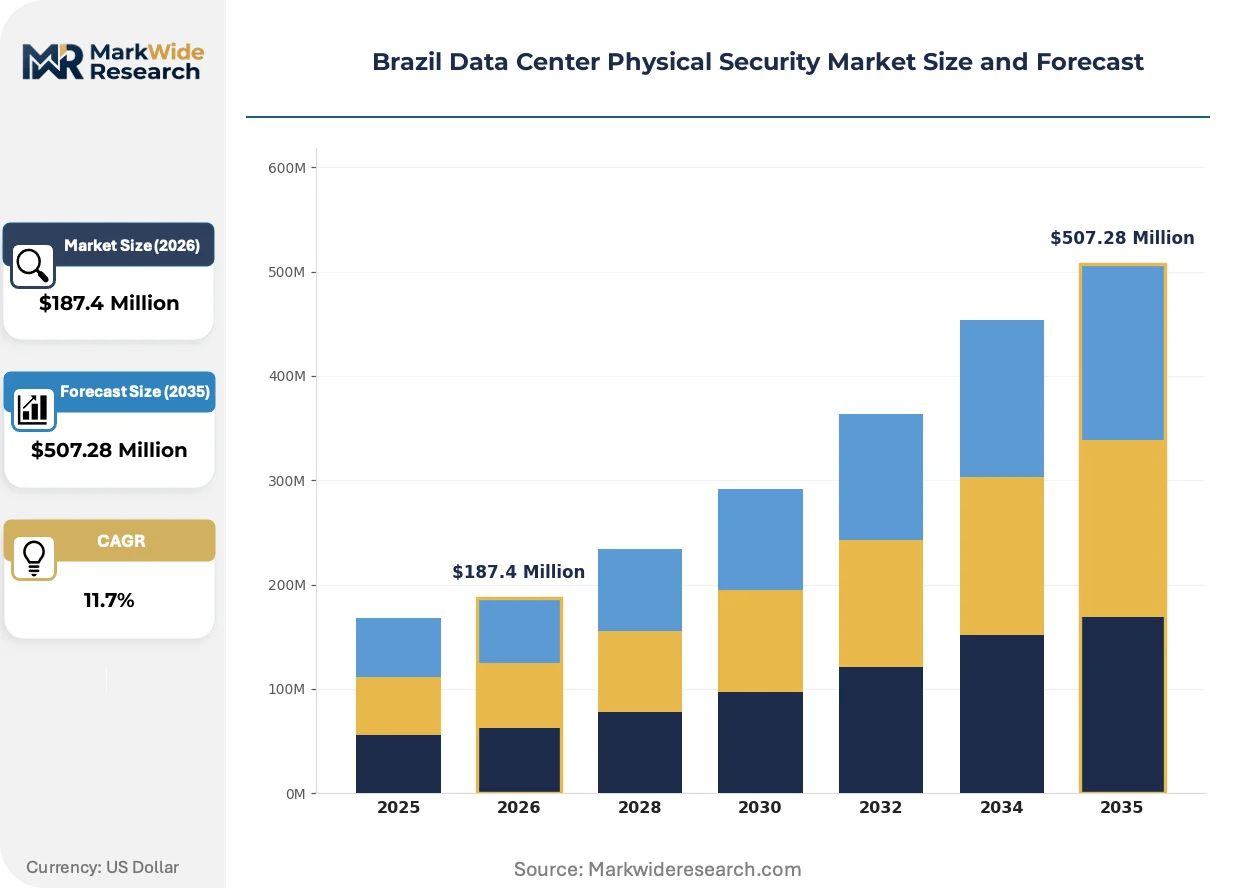
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Security Solution: CCTV, Access Control, Intrusion Detection, Perimeter Security End User: Telecommunications, Banking, Government, Healthcare Deployment Model: On-Premises, Managed Services, Hybrid, Cloud-Based Component: Hardware, Software, Services, Integration |
| Companies Covered | Axis Communications AB, Schneider Electric, Honeywell International Inc., Hikvision, ABB Ltd., Johnson Controls, Siemens AG, Genetec, Bosch Sicherheitssysteme GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Data Center Physical Security Market Trends and Innovations
Physical security architectures are converging around unified command platforms that collapse previously siloed access control, video analytics, and environmental monitoring into single-pane management, compressing procurement cycles and reshaping vendor competitive positioning.
Artificial intelligence-enabled video analytics is consolidating threat detection accuracy at hyperscale campuses. These systems perform behavioral analysis and anomaly flagging across thousands of camera feeds without proportional headcount expansion. Cloud service providers in Campinas are deploying these platforms at full scale, compressing the market for standalone human monitoring services and forcing traditional guarding firms to reposition around platform management.
LGPD enforcement is tightening physical-access documentation requirements across all health and financial data facilities. The national data protection authority now mandates immutable logging of every biometric scan, card tap, and visitor escort event with minimum seven-year retention. Banking data centers in São Paulo municipality are responding by accelerating replacement of standalone electronic locks with networked identity platforms that auto-generate audit trails.
Mid-tier financial institutions are unbundling security operations from capital expenditure, preferring subscription-based managed services over owned security operations centers. This procurement pattern displaces hardware-heavy purchasing with integrated service contracts spanning installation, monitoring, and compliance documentation. The shift is most visible among regional banks in the ABC Paulista corridor that lack scale to justify dedicated 24/7 staffing.
Brazil Data Center Physical Security Market Segmentation
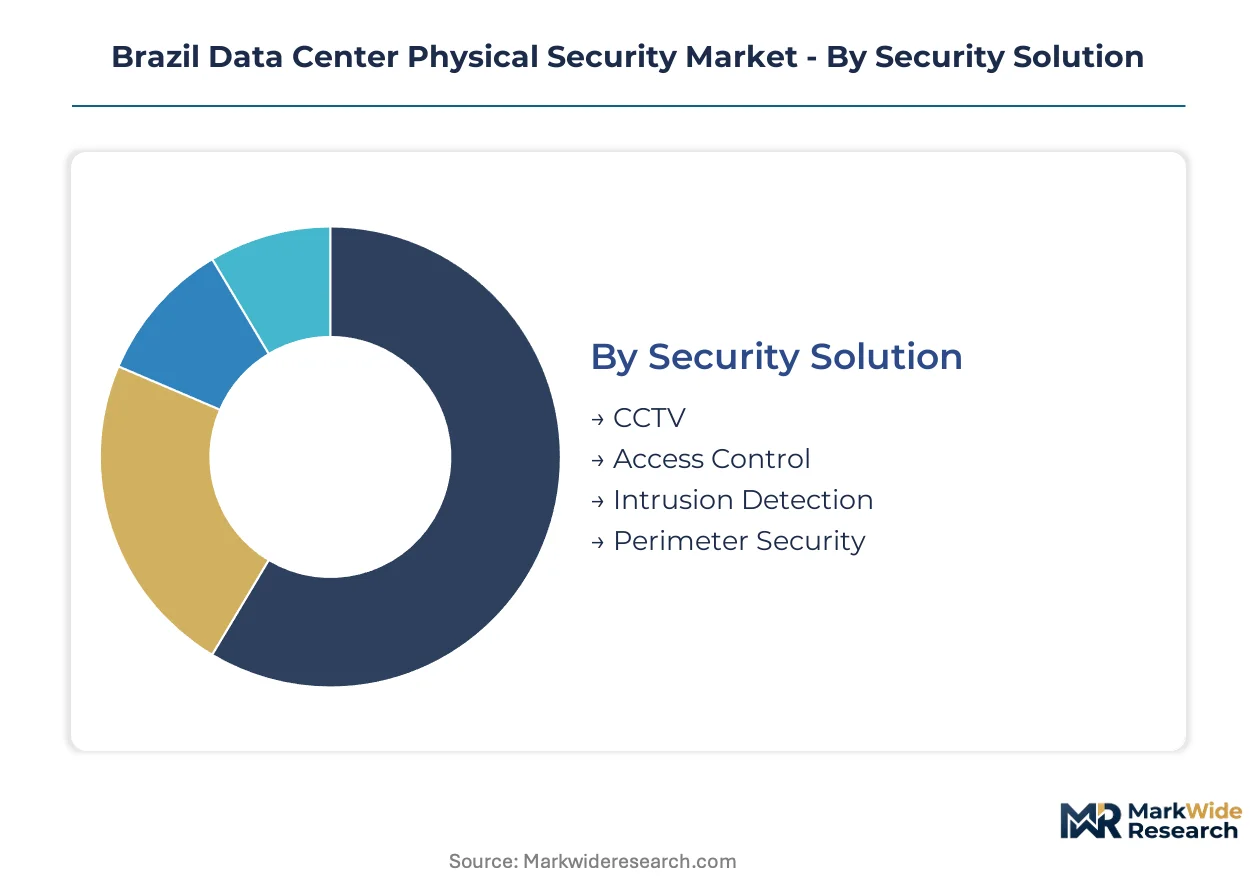
Physical security procurement in Brazilian data centers fragments across four critical dimensions. Buyers weigh capital intensity against compliance mandates, with ANVISA and LGPD rules forcing trade-offs between hardware ownership and outsourced accountability. Each segmentation axis reveals distinct vendor positioning strategies and margin structures.
Security Solution:
Hyperscale operators prioritize integration depth over standalone capability, driving consolidation toward unified platforms.
- CCTV:IP-based camera networks with AI-enabled video analytics perform behavioral analysis across thousands of feeds. Cloud campuses in Campinas deploy these at full scale, compressing demand for human monitoring services while satisfying LGPD visual documentation requirements.
- Access Control:Networked identity platforms replace standalone locks to auto-generate immutable audit trails. Banking data centers in São Paulo municipality accelerate procurement here to meet seven-year retention mandates from the national data protection authority.
- Intrusion Detection:Fiber-optic and thermal sensor arrays protect critical power paths. Import dependency on Asian manufacturing exposes operators to currency volatility and extended lead times.
- Perimeter Security:Mantrap portals and biometric-restricted clean zones serve ANVISA pharmaceutical-grade mandates at health-data facilities. Demand concentrates near the ABC Paulista corridor.
CCTV leads on scale; Access Control leads on momentum.
End User:
Regulatory exposure and uptime guarantees vary sharply across buyer categories, reshaping vendor qualification requirements.
- Telecommunications:Cloud service providers anchor hyperscale campus buildouts across São Paulo state. These buyers demand integrated biometric-video-analytics platforms with 99.99% uptime guarantees.
- Banking:Mid-tier institutions outsource security operations to avoid dedicated 24/7 staffing costs. Regional banks in the ABC Paulista corridor favor subscription-based managed services over capital-heavy purchasing.
- Government:Federal and state facilities require ABNT NBR ISO/IEC 27001 certification spanning 14-18 month audit timelines. Procurement cycles stretch longer than private sector equivalents.
- Healthcare:ANVISA mandates pharmaceutical-grade environmental monitoring with biometric-restricted clean zones. Facilities processing sensitive patient records drive demand for continuous monitoring integration.
Telecommunications leads on scale; Healthcare leads on momentum.
Deployment Model:
Data sovereignty concerns and compliance documentation needs determine cloud versus on-premises trade-offs.
- On-Premises:Fully owned infrastructure satisfies strictest data sovereignty requirements. Large financial institutions in São Paulo municipality retain this model for core transaction processing facilities.
- Managed Services:Outsourced 24/7 monitoring and incident response creates recurring revenue streams. Regional banks lacking in-house security operations centers drive fastest expansion here.
- Hybrid:Split architectures separate sensitive access logging from cloud-based video analytics. This configuration addresses LGPD compliance while retaining scalability.
- Cloud-Based:Centralized security management platforms serve edge facility expansions in Sorocaba and Jundiaí. Latency-sensitive financial services deploy modular physical security packages through this model.
On-Premises leads on scale; Managed Services leads on momentum.
Component:
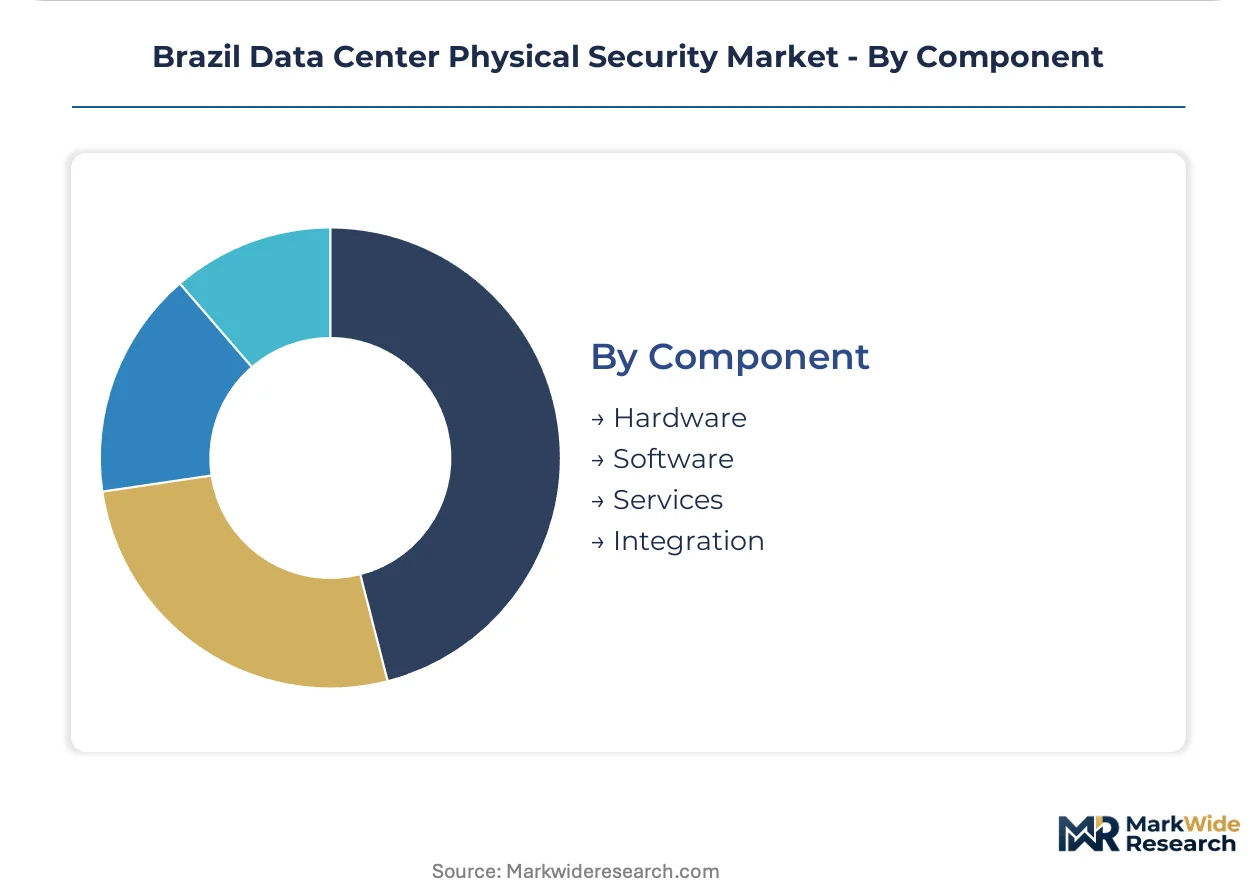
Margin concentration shifts toward integration and software as hardware commoditizes.
- Hardware:Biometric readers, video analytics servers, and mantrap portals capture bulk of current capital expenditure. Legacy analog upgrades proceed across mid-tier banking data centers.
- Software:Unified command platforms merge fire suppression with real-time access logging. Johnson Controls differentiates here against point-solution competitors.
- Services:LGPD-certified documentation capabilities command premium pricing. Multi-vendor contracts with certified audit trails generate higher margins than standalone hardware sales.
- Integration:Colocation operators face interoperability failures stitching together building management systems, camera networks, and fire suppression platforms. Certified security engineer scarcity constrains delivery capacity.
Hardware leads on scale; Services leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state anchors Brazil's data center physical security procurement, with hyperscale campuses clustering near Campinas and the ABC Paulista corridor driving concentrated demand for integrated biometric-video-analytics platforms.
São Paulo
Hyperscale cloud buildouts in Campinas and Sorocaba dominate capital deployment. ANVISA pharmaceutical-grade mandates expand biometric-restricted clean zones at health-data facilities. Banking data centers in São Paulo municipality accelerate replacement of standalone locks with networked identity platforms to satisfy LGPD seven-year retention rules.
Minas Gerais
Belo Horizonte's emerging fintech ecosystem drives mid-tier data center security outsourcing. The state's central bank regulator enforces ABNT NBR ISO/IEC 27001 certification timelines stretching 14-18 months. Regional banks in Contagem favor subscription-based managed services over owned security operations centers.
Rio de Janeiro
Oil and gas sector data facilities require fiber-optic perimeter detection for critical infrastructure protection. Petrobras-driven procurement emphasizes environmental monitoring integration with access control. Niterói's port-adjacent industrial zones attract edge facility deployments serving latency-sensitive commodity trading applications.
Rio Grande do Sul
Porto Alegre's agribusiness technology sector generates specialized demand for supply-chain tampering prevention. LGPD enforcement at agricultural commodity exchanges compels immutable logging of physical access events. Local operators face import dependency on Asian-manufactured thermal cameras and fiber-optic sensors.
Paraná
Curitiba's government data center consolidation creates procurement volume for ABNT-certified physical security management systems. State-level digital transformation programs mandate unified command platforms merging fire suppression with real-time access logging. Public sector audit timelines compress vendor cash conversion cycles.
Brazil Data Center Physical Security Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue managed services specialization and edge facility modularization. The vendor base stratifies across three functional layers: building management system integrators, point-solution hardware manufacturers, and compliance-centric service providers. Dominant competitive moves include backward integration into software platforms and geographic clustering near São Paulo state hyperscale corridors. Multi-vendor integration contracts now command premium pricing where LGPD-certified documentation trails are required.
Within the integrated platform tier, Schneider Electric and Johnson Controls exemplify unified command architectures that merge fire suppression with access logging. Hikvision occupies a position among camera density specialists competing aggressively on large campus deployment pricing. These three anchors represent divergent strategic postures: European-headquartered conglomerates with deep backward integration into building management systems, and Asia-based manufacturers pursuing volume-driven hardware penetration.
| Leading Market Players |
|---|
| Axis Communications AB |
| Schneider Electric |
| Honeywell International Inc. |
| Hikvision |
| ABB Ltd. |
| Johnson Controls |
| Siemens AG |
| Genetec |
| Bosch Sicherheitssysteme GmbH |
| Others |
Pricing and Supply Chain Analysis
Fiber-optic perimeter detection cables from Asian manufacturing hubs flow through import channels into three-tier pricing structures across premium, standard, and economy levels, with currency volatility compressing margins at the economy tier while ANVISA-certified installations sustain premium positioning.
Pricing Analysis
Input-cost pass-through from thermal camera imports and specialized sensor freight runs through subscription-based managed services for mid-tier banks, while project-based hardware procurement dominates hyperscale campuses. Price differentiation separates LGPD-certified documentation capabilities from standalone equipment sales, with certification investment and volume scale as primary tiering drivers. Pricing pressure stems from Hikvision's aggressive camera density pricing, eroding standalone hardware margins. Regional banks in the ABC Paulista corridor exhibit highest price sensitivity; cloud service providers in Campinas prioritize integration depth over unit cost.
Supply Chain Analysis
Reverse-logistics flows for biometric reader refurbishment and video analytics server redeployment remain underdeveloped, constraining circular economy participation in Brazilian data center security. Supply concentration rests on China, South Korea, and Taiwan for fiber-optic sensors, thermal cameras, and AI-enabled video analytics chipsets. Raw material dependencies include rare-earth magnet components for biometric actuators, high-purity silicon for thermal imaging arrays, and specialized optical glass for perimeter detection cables. Single-source vulnerability around Taiwanese semiconductor fabrication exposes operators to geopolitical disruption. Distribution runs through São Paulo-based systems integrators serving Campinas hyperscale corridors and ABC Paulista banking clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in managed services bundling and LGPD-certified integration contracts, with labor arbitrage from certified security engineer scarcity supporting premium pricing power.
For Market Incumbents: Anchor market position through backward integration into unified command software platforms that merge fire suppression with access logging, countering point-solution commoditization from Hikvision's hardware penetration. Deepen captive supply of biometric reader manufacturing to reduce import dependency exposure. Invest in ABNT NBR ISO/IEC 27001 certification pipelines to compress 14-18 month audit timelines that currently delay facility commissioning and compress cash conversion cycles. For New Entrants and Emerging Players: Mid-tier regional banks lacking in-house security operations centers represent the most penetrable buyer archetype, with subscription-based managed services displacing capital-heavy procurement. Edge facility expansions in Sorocaba and Jundiaí offer modular physical security package opportunities with lower competitive density than Campinas hyperscale corridors. Pursue LGPD-certified documentation capabilities as the primary go-to-market wedge, commanding premium pricing against hardware-only competitors. For Investors and Strategic Acquirers: Roll-up economics work for managed security services specialists because certified engineer scarcity and fragmented regional banking relationships create durable local moats that resist national platform consolidation. Target acquisition profiles center on São Paulo state operators with existing ANVISA compliance track records and established relationships with healthcare data facilities. Monitor LGPD enforcement intensity and audit fine issuance as the critical inflection signal for accelerated hardware replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Schneider Electric's building management system convergence with Johnson Controls fire suppression creates unified command architectures. |
| Certification Investment | ABNT NBR ISO/IEC 27001 pipeline development compresses 14-18 month audit timelines that currently constrain vendor cash conversion. |
| Managed Services Expansion | Outsourced 24/7 monitoring contracts with LGPD-certified documentation displace hardware-heavy purchasing among regional banks. |
| Backward Integration | In-house biometric reader production reduces currency volatility exposure from Asian-manufactured component imports. |
| Geographic Expansion | Edge facility security packages in Sorocaba and Jundiaí capture latency-sensitive financial services deployments outside Campinas density. |
Research Methodology
Coverage spans São Paulo, Minas Gerais, Rio de Janeiro, Rio Grande do Sul, and Paraná states, with primary inputs from each region combined with secondary validation. Interviews with data center facility managers, physical security systems integrators, LGPD compliance auditors, ANVISA pharmaceutical-grade certification specialists, and banking IT procurement officers informed demand-side dynamics. Secondary sources include ANVISA regulatory filings, ABNT certification databases, BIS-equivalent electrical safety standards documentation, cloud service provider capex disclosures, and customs import records for security hardware. Bottom-up facility counts triangulate against top-down market sizing from vendor revenue disclosures.
Granularity-level modeling distinguishes hyperscale cloud campuses from mid-tier banking data centers and edge facility deployments, with separate treatment of on-premises, managed services, hybrid, and cloud-based deployment architectures. Segmentation dimensions include security solution type, end-user vertical, deployment model, and component category, with ANVISA regulatory exposure and LGPD compliance intensity as cross-cutting modifiers. CAGRs derive from facility pipeline analysis and replacement cycle timing across analog-to-IP CCTV upgrades. Forecast inputs incorporate certified security engineer supply constraints and import lead time volatility for fiber-optic perimeter detection components.
Underlying measurement precision varies by segment; São Paulo state hyperscale deployments carry tighter precision than secondary municipality edge facilities due to disclosed cloud provider capex visibility. Forecasts reflect assumptions around LGPD enforcement intensity, ANVISA audit staffing levels, and currency stability for Asian-manufactured component imports. Practitioners should monitor central bank foreign exchange intervention patterns and national data protection authority fine issuance rates for early signals of cost structure and compliance timeline shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Global Containerized Data Center Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Internet Data Center Market
Data Center Infrastructure
Canada Data Center Rack Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
France Data Center Market
Data Center Infrastructure
New Zealand Data Center Rack Market
Data Center Infrastructure
New Zealand Data Center Power Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
Multi-Tenant Data Center Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
South Africa Data Center Power Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
North America Hyperscale Data Center Market