
 Retail Colocation Market | 2026-2036
Retail Colocation Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Colocation Market Outlook
Buyer concentration among financial institutions and cloud service providers is expanding as these sectors consolidate their data center footprints into fewer, larger retail colocation deployments. Equinix leverages its global interconnection platform to capture cross-border traffic flows between financial hubs. CyrusOne anchors its competitive position through hyperscale-ready designs that accommodate rapid tenant expansion. Digital Realty competes by extending its portfolio across key metropolitan markets with diverse fiber pathways.
Retail colocation denotes multi-tenant data center space leased in incremental units—typically single cabinets, cages, or dedicated suites—where the operator manages power, cooling, physical security, and network cross-connects, with power densities commonly ranging from 5 kW to 15 kW per cabinet. The primary commercial purpose centers on enabling enterprises to deploy IT infrastructure without capital expenditure on facility construction while maintaining direct control over hardware and software stacks. Managed hosting and interconnection services generate the deepest margin pools as operators layer value-added services atop base space leases. Hybrid cloud deployment models show the steepest adoption curve as enterprises distribute workloads across owned infrastructure and hyperscaler platforms.
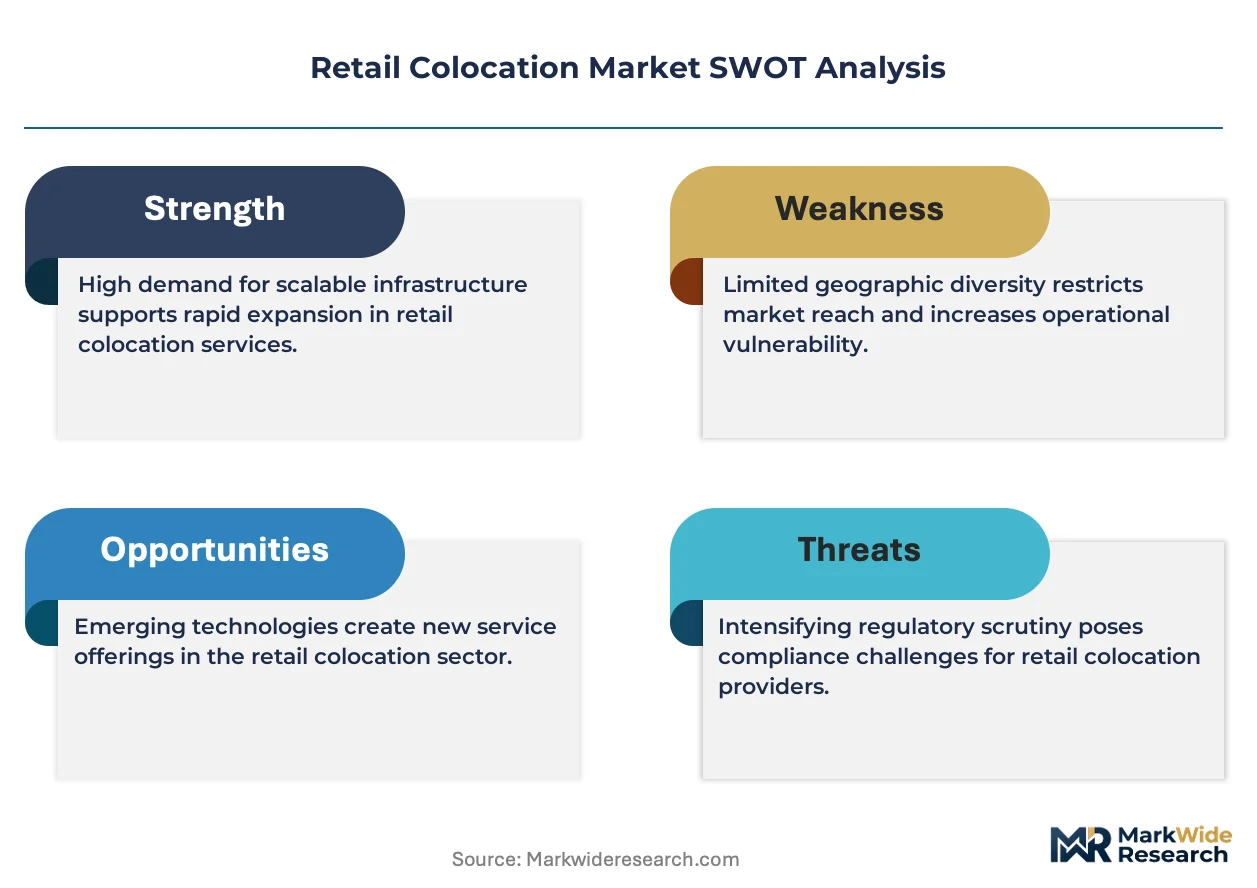
Regulators in the United States, including the EPA and OSHA, enforce emissions controls and workplace safety standards that directly influence cooling system selection and facility operational protocols. The EU F-Gas Regulation and national building codes across Germany, France, and the Netherlands constrain refrigerant choices and mandate energy performance disclosures from colocation operators. Stakeholders must monitor evolving carbon accounting requirements and their impact on tenant procurement criteria and contract structures.
Market Dynamics
Financial institutions and hyperscale cloud providers are compressing procurement cycles and demanding higher power densities per cabinet, forcing operators to reengineer thermal management and electrical distribution architectures within existing facility footprints.
Growth Catalysts
- Algorithmic Trading Latency Requirements:Financial institutions in Frankfurt, London, and New York require sub-millisecond proximity to exchanges, driving multi-tenant deployments in fiber-dense metropolitan clusters.
- EU Energy Efficiency Directive:Mandatory energy performance disclosures and carbon reporting standards are accelerating facility upgrades that attract sustainability-conscious enterprise tenants.
- Liquid Cooling Adoption:Direct-to-chip and immersion cooling technologies are enabling 30-50 kW rack densities that support AI training workloads without facility reconstruction.
Market Restraints
- Copper and Aluminum Price Volatility:Busbar and cable costs fluctuate with commodity markets, compressing margins on power distribution upgrades in legacy facilities.
- Frankfurt Fiber Concentration Risk:Over 60% of Central European interconnection capacity routes through single metropolitan infrastructure, creating systemic resilience exposure.
- F-Gas Phase-Down Constraints:The EU F-Gas Regulation limits refrigerant options for retrofitted cooling systems, extending deployment timelines for expanded capacity.
Strategic Opportunities
- Secondary German Markets:Munich, Hamburg, and Düsseldorf offer lower land costs and emerging fiber ecosystems for distributed colocation networks serving latency-tolerant workloads.
- Edge Computing Convergence:Integration of 5G MEC nodes with retail colocation creates hybrid architectures for manufacturing and autonomous vehicle data processing.
- CSRD-Aligned Service Packaging:The EU Corporate Sustainability Reporting Directive creates demand for Scope 3 emissions tracking bundled with colocation contracts.
Industry Challenges
- Electrical Engineering Talent Scarcity:Specialized skills in medium-voltage distribution and critical power architecture command premium compensation, constraining expansion velocity.
- Legacy Building Integration Complexity:Retrofitting pre-2010 facilities with modern fire suppression and seismic isolation requires extensive structural remediation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Colocation Market |
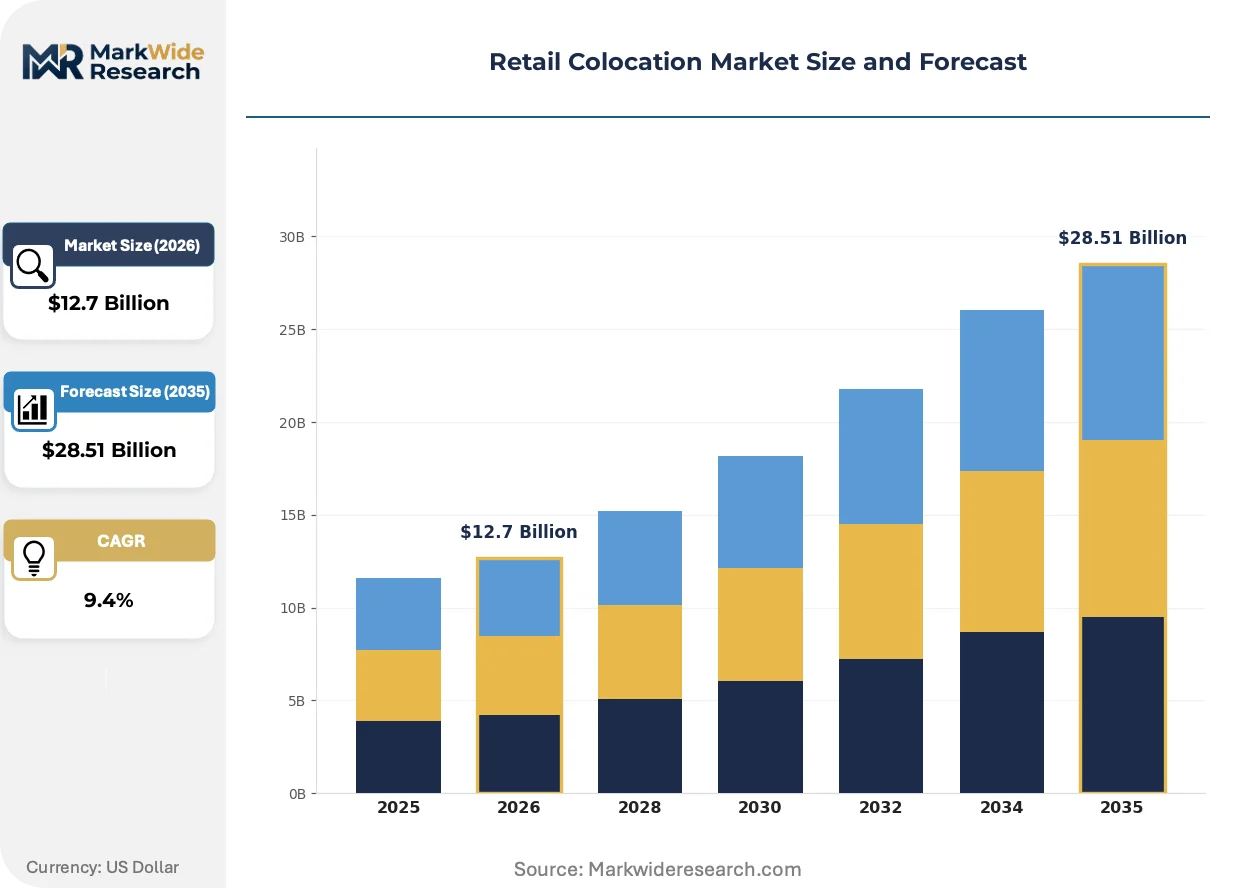
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $28.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Hosting, Dedicated Servers, Cloud Services, Interconnection End User: Retail Enterprises, E-commerce Platforms, Financial Institutions, Content Providers Deployment Model: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud Cabinet Size: 1U, 2U, 4U, 42U |
| Companies Covered | CyrusOne, Centersquare, Equinix, Iron Mountain, QTS Realty Trust, Digital Realty, CoreSite, Switch, NTT Global Data Centers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Colocation Market Strategic Shifts
Operational technology stacks are converging with information technology systems, enabling predictive maintenance and automated workload placement that reshape how colocation operators compete on service reliability rather than base rent.
Software-defined power distribution is consolidating control plane functions across previously siloed electrical infrastructure. Large enterprises with dynamic workload patterns are adopting these platforms to shift power allocations between cabinets in real-time. This consolidation is compressing the advantage of operators who rely on manual change orders for capacity modifications.
The EU F-Gas Regulation and national building codes in Germany, France, and the Netherlands are prohibiting high-global-warming-potential refrigerants in new cooling installations. Facility operators must select alternative chemistries or invest in water-based systems that require different physical footprints. German operators are responding fastest due to stricter federal implementation timelines and higher enforcement visibility.
Enterprise procurement teams are unbundling interconnection services from base space leases, negotiating cross-connect fees and cloud exchange access as separate line items. This fragmentation pressures operators who previously captured margin through bundled pricing. Financial services buyers in London and Frankfurt are driving this shift most aggressively, using their transaction volumes to extract granular contract terms.
Retail Colocation Market Segmentation
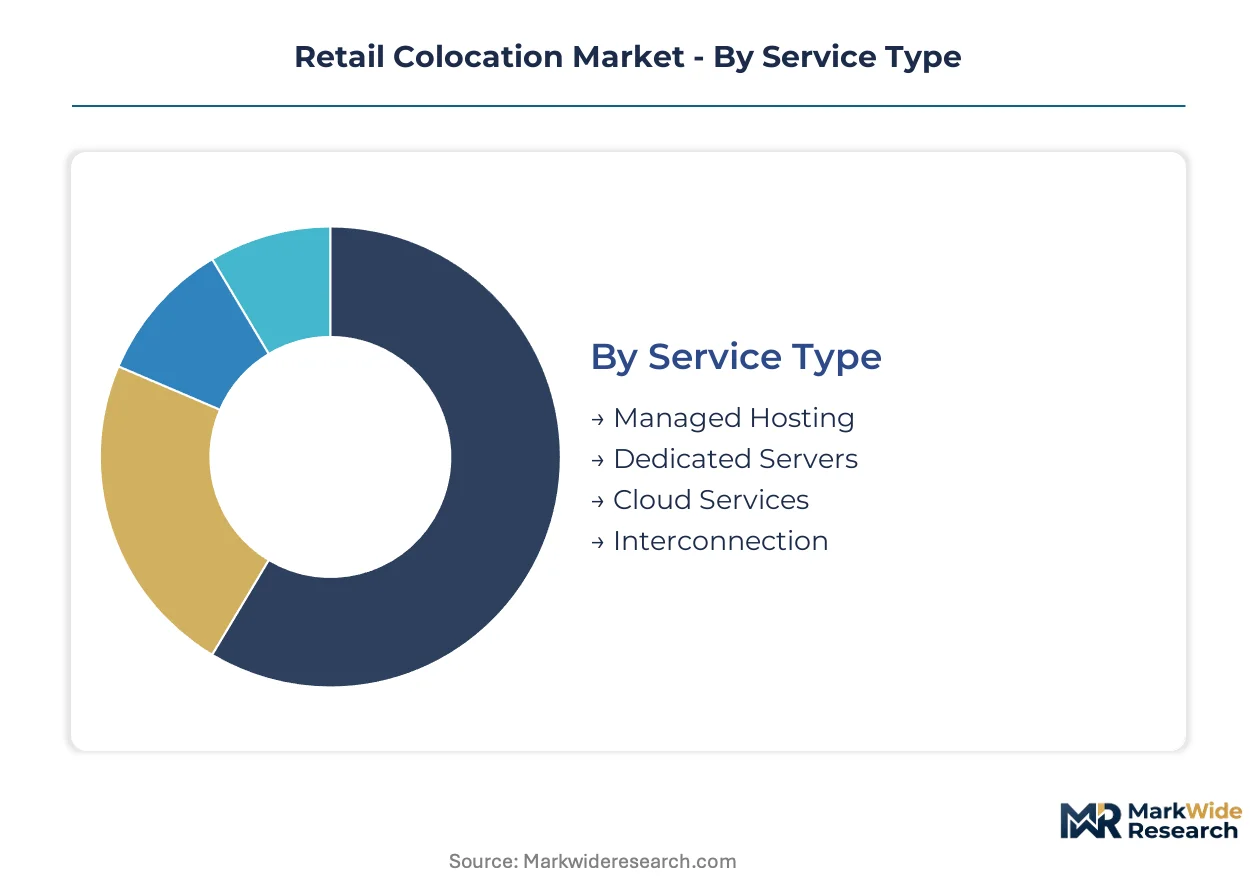
Retail colocation operators structure service portfolios around distinct operational requirements. Segmentation reveals where margin pools concentrate and which deployment configurations command premium pricing.
Service Type:
Certification burdens vary sharply across service tiers, with interconnection and managed hosting requiring SOC 2 Type II and ISO 27001 attestations that pure space leases escape.
- Managed Hosting:Operators retain full infrastructure management responsibility including OS patching, security monitoring, and backup orchestration. Financial institutions in Frankfurt and London concentrate procurement here to satisfy MiFID II data residency requirements without building captive facilities.
- Interconnection:Physical and virtual cross-connects to cloud exchanges, carriers, and financial networks generate recurring revenue with minimal incremental facility cost. Demand clusters in fiber-dense metropolitan cores where latency arbitrage justifies premium port fees.
- Dedicated Servers:Single-tenant bare metal deployments bridge colocation and cloud consumption models. E-commerce platforms favor this configuration for predictable performance during demand spikes.
- Cloud Services:Operator-managed hyperscaler resale and cloud-adjacent storage. Content providers with bursty traffic patterns drive adoption for CDN origin infrastructure.
Leading the category by volume: Managed Hosting. Growing fastest: Interconnection.
End User:
Procurement sophistication and contract scale diverge substantially across buyer categories, with financial institutions demanding granular SLAs that retail enterprises rarely negotiate.
- Financial Institutions:Investment banks, hedge funds, and exchanges require sub-millisecond proximity to matching engines. Algorithmic trading desks in Frankfurt, London, and New York anchor the highest-density deployments, with power allocations per cabinet reaching 30-50 kW for co-located trading infrastructure.
- E-commerce Platforms:Seasonal demand volatility drives preference for short-term leases with burst capacity options. These buyers concentrate in Northern Virginia and Amsterdam, where cloud on-ramps enable hybrid fulfillment architectures.
- Retail Enterprises:Brick-and-mortar chains and regional distributors seeking disaster recovery without capital expenditure. Procurement emphasizes geographic redundancy over performance optimization.
- Content Providers:Streaming services and gaming platforms with asymmetric bandwidth requirements. These tenants generate asymmetric revenue profiles—high egress fees offset by lower per-cabinet rents.
Financial Institutions command the steepest pricing. E-commerce Platforms are expanding most quickly.
Deployment Model:
Margin structures align with operational complexity, with hybrid configurations requiring the most intensive customer engineering support.
- Hybrid Cloud:Workload distribution across owned cabinets and hyperscaler regions. Manufacturing enterprises in Germany adopt this model to retain sensitive ERP data on-premises while bursting analytics to public cloud.
- Private Cloud:Dedicated infrastructure pools with software-defined resource allocation. Healthcare systems favor this configuration for HIPAA-aligned patient data processing.
- Public Cloud:Operator-facilitated hyperscaler access without physical cabinet commitment. Serves as entry point for enterprises testing cloud migration.
- On-Premises:Traditional colocation with full hardware control retained by tenant. Mature workloads with stable resource requirements dominate this segment.
Hybrid Cloud leads by committed revenue. Private Cloud shows the steepest expansion trajectory.
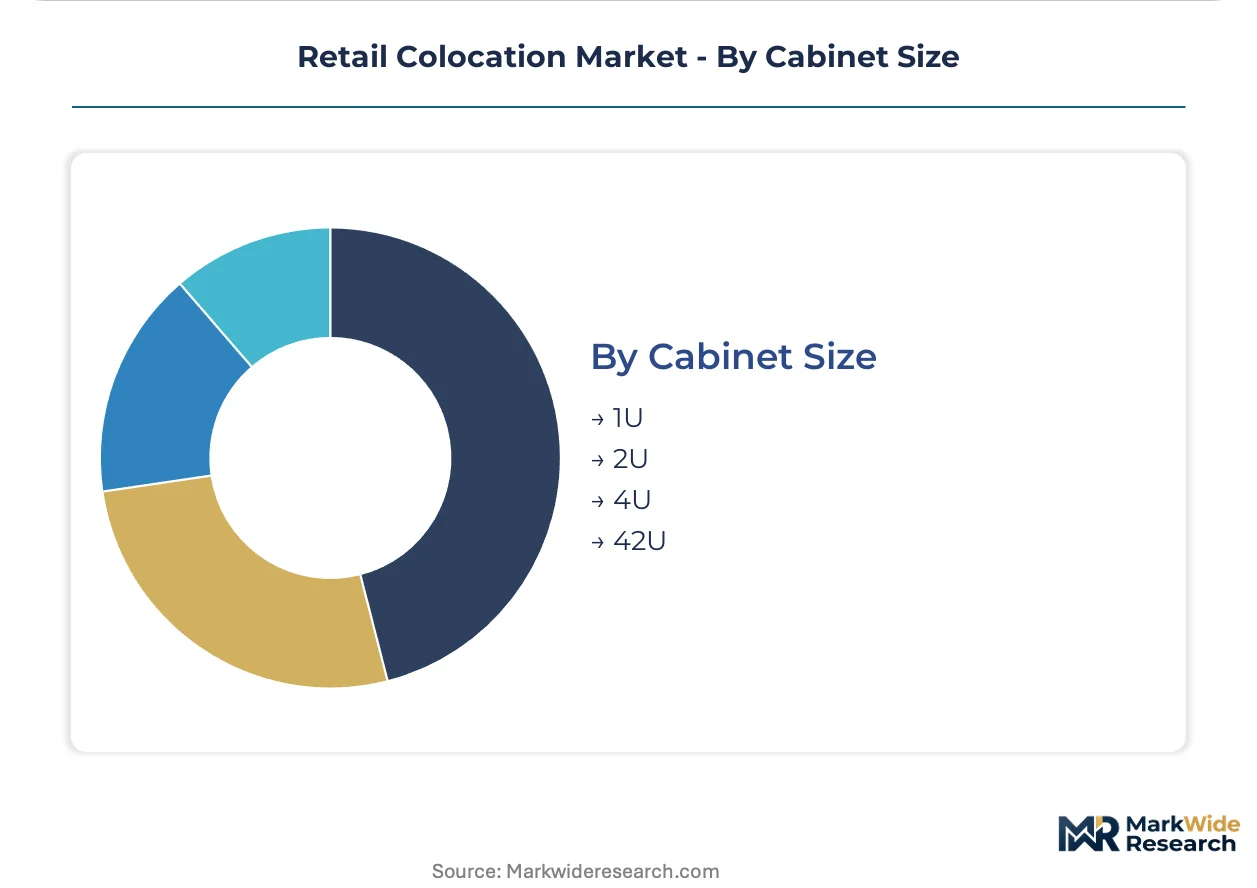
Cabinet Size:
Physical footprint directly determines power allocation economics and cross-connect density potential.
- 42U:Full-height cabinets supporting 10-15 kW standard deployments. Financial trading firms and AI training clusters drive demand for these units in Frankfurt and London.
- 4U:Mid-size enclosures for network equipment and storage arrays. Edge computing nodes in secondary German markets favor this form factor.
- 2U:Compact server housing for distributed applications. Regional enterprise disaster recovery sites deploy these for cost-efficient redundancy.
- 1U:Single-unit server slots for minimal footprint requirements. Declining share as density requirements rise across all buyer categories.
42U cabinets dominate committed power volumes. 4U configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial institutions and cloud service providers concentrate procurement in fiber-dense metropolitan clusters where sub-millisecond latency determines competitive positioning. This demand-side concentration shapes facility investment patterns across key national markets.
Germany
Frankfurt's dense interconnection ecosystem anchors Central European trading infrastructure, with algorithmic desks demanding 30-50 kW cabinet densities. The EU F-Gas Regulation constrains refrigerant choices for cooling system retrofits, extending deployment timelines. Munich and Hamburg emerge as secondary nodes for latency-tolerant workloads seeking lower land costs.
United States
Investment banks and hedge funds in New York and Chicago drive multi-tenant deployments near exchange matching engines. EPA emissions controls and OSHA workplace safety standards directly influence cooling system selection and operational protocols. Northern Virginia's cloud corridor concentrates e-commerce and content provider demand with extensive hyperscaler on-ramps.
United Kingdom
MiFID II data residency requirements push financial institutions toward managed hosting configurations in London. The UK Building Regulations set energy performance standards that shape facility upgrade priorities. The Docklands and Slough clusters host dense fiber interconnection for cross-border traffic arbitrage.
Netherlands
Amsterdam serves as a secondary European hub for content delivery and disaster recovery deployments. National building codes mandate energy performance disclosures that accelerate sustainability-focused facility upgrades. The Amsterdam Science Park and Schiphol Rijk areas concentrate carrier-neutral interconnection capacity.
France
Paris attracts financial services tenants seeking geographic diversification from London and Frankfurt. ANSM and CNIL oversight creates compliance requirements for healthcare and financial data processing. The Paris-Saclay cluster and La Défense business district host emerging multi-tenant facilities.
Retail Colocation Market Competitive Environment
US-based operators anchor the global tier with hyperscale-ready designs and interconnection platforms; European specialists hold regional density advantages through fiber ecosystem integration. Market structure consolidates around three to five dominant platforms with extensive metropolitan footprints, while mid-scale regional operators serve latency-sensitive niches. Strategic archetypes include global interconnection platforms, hyperscale-ready developers, and carrier-neutral specialists. Competitive dynamics center on capacity expansion in fiber-dense metros and strategic partnerships for cross-border traffic exchange.
Within the global platform tier, Equinix, Digital Realty, and CyrusOne exemplify distinct strategic positioning. Equinix occupies a position as the interconnection archetype with exchange-focused facility design. Digital Realty represents the metropolitan diversification approach with presence across key fiber pathways. CyrusOne anchors the hyperscale-ready segment with rapid tenant expansion capabilities. These three operators collectively illustrate how scale, specialization, and geographic coverage define competitive differentiation in multi-tenant data center markets.
| Leading Market Players |
|---|
| CyrusOne |
| Centersquare |
| Equinix |
| Iron Mountain |
| QTS Realty Trust |
| Digital Realty |
| CoreSite |
| Switch |
| NTT Global Data Centers |
| Others |
Value Chain & Pricing Dynamics
Copper busbar and medium-voltage cable costs cascade through retail colocation pricing tiers, with commodity volatility in electrical distribution components compressing margins on legacy facility retrofits while operators pass through premium charges for liquid-cooled high-density cabinets to algorithmic trading firms in Frankfurt and London.
Pricing Analysis
Volume commitments from hyperscale cloud providers anchor standard cabinet rates at 5-15 kW densities, while financial institutions trading latency arbitrage absorb 40-60% premiums for sub-millisecond proximity to exchange matching engines. Price differentiation hinges on power density tiers and SOC 2 Type II certification bundling, with managed hosting configurations capturing deeper margins than pure space leases. Pricing pressure intensifies in secondary German markets as Munich and Hamburg operators undercut Frankfurt premiums for latency-tolerant workloads. E-commerce platforms exhibit highest price sensitivity, negotiating burst capacity options and short-term lease structures that erode operator yield.
Supply Chain Analysis
Domestic content requirements under the EU F-Gas Regulation and national building codes in Germany, France, and the Netherlands are reshaping cooling equipment sourcing, prohibiting high-global-warming-potential refrigerants and mandating local energy performance disclosures. Manufacturing concentration for precision cooling systems rests on Germany, the United States, and Japan, with critical dependencies on aluminum heat exchangers, copper refrigerant lines, and specialized compressor assemblies. Single-source vulnerability concentrates in Frankfurt's fiber ecosystem, where over 60% of Central European interconnection capacity routes through one metropolitan infrastructure. Distribution runs through operator-direct procurement with Tier 1 mechanical-electrical contractors managing facility integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Corporate Sustainability Reporting Directive creates a cost-of-compliance moat that favors incumbent operators with established Scope 3 emissions tracking infrastructure, raising capital barriers for new entrants lacking bundled sustainability service capabilities.
For Market Incumbents: Hedge against fiber concentration risk in Frankfurt by diversifying interconnection capacity into secondary German markets and liquid-cooled retrofit investments for AI training workloads. Acquire specialized electrical engineering talent pools in Munich and Hamburg to constrain expansion velocity for competitors. Prioritize CSRD-aligned service packaging to capture enterprise procurement teams unbundling interconnection from base space leases. For New Entrants and Emerging Players: Capture white-space opportunity in edge computing convergence with 5G MEC nodes for manufacturing and autonomous vehicle data processing in secondary German markets. Target latency-tolerant disaster recovery deployments from retail enterprises seeking geographic redundancy without Frankfurt premiums. Lead with modular liquid-cooled designs that bypass F-Gas retrofit constraints plaguing legacy operators. For Investors and Strategic Acquirers: Frankfurt fiber ecosystem consolidation announcements are the leading indicator that secondary market valuations will re-rate upward as latency-tolerant workloads redistribute. Frame long-term viability around operators with hybrid cloud integration capabilities and established Scope 3 tracking infrastructure. Target acquisition profiles emphasizing hyperscale-ready designs with rapid tenant expansion capabilities in fiber-dense metropolitan clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Enables 30-50 kW rack densities for AI training workloads without facility reconstruction. |
| Secondary Market Geographic Expansion | Munich and Hamburg capture latency-tolerant workloads seeking lower land costs outside Frankfurt. |
| CSRD-Aligned Service Packaging | Bundled Scope 3 emissions tracking attracts sustainability-conscious enterprise procurement teams. |
| Interconnection Platform Integration | Physical and virtual cross-connects to cloud exchanges generate recurring revenue with minimal incremental cost. |
| Electrical Engineering Talent Acquisition | Specialized medium-voltage distribution skills constrain competitor expansion velocity in constrained labor markets. |
Study Parameters
Document review covered SEC filings from publicly traded operators, EU regulatory submissions under F-Gas and Energy Efficiency Directive frameworks, and hyperscaler capex disclosures, complemented by interviews with data center facility directors, interconnection platform engineers, financial services infrastructure procurement leads, and mechanical-electrical contracting executives. Secondary validation drew from customs records for cooling equipment imports, national building code registries, and carrier-neutral fiber exchange databases. Bottom-up and top-down triangulation reconciled tenant-level contract analysis with aggregate metropolitan capacity estimates.
Market sizing outputs reflect installed base depreciation schedules and new supply absorption curves across the projection horizon, with segmentation modeled by service type, end user vertical, deployment architecture, and cabinet density tier. CAGRs derive from power commitment trajectories and interconnection port growth rates specific to financial services and cloud service provider demand clusters. Forecast inputs incorporate F-Gas phase-down compliance timelines and algorithmic trading latency requirement evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper and aluminum commodity volatility, electrical engineering labor market tightness, and Frankfurt fiber ecosystem resilience events. Forecasts reflect documented assumptions regarding hyperscaler expansion pacing and EU carbon reporting standard enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Taiwan Data Center Market
Data Center Infrastructure
Poland Data Center Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
France Data Center Power Market
Data Center Infrastructure
Colocation Edge Data Center Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
Brazil Data Center Physical Security Market
Data Center Infrastructure
Israel Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
Switzerland Data Center Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Italy Data Center Rack Market