
 United Kingdom Data Center Power Market | 2026-2036
United Kingdom Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Data Center Power Market Insights
The premium hyperscale tier is consolidating around liquid-cooled infrastructure and direct grid interconnections, while commodity enterprise deployments remain anchored to traditional air-cooled UPS and diesel backup configurations. Schneider Electric SE leverages its integrated power and cooling portfolio to dominate large-scale deployments across southern England. Vertiv Group Corp. sustains technology leadership in thermal management systems that support higher rack densities. ABB Ltd. competes through advanced medium-voltage switchgear and digital monitoring platforms for mission-critical facilities.
United Kingdom Data Center Power encompasses the generation, conditioning, distribution, and backup systems that ensure continuous electrical supply for server, storage, and networking infrastructure, typically operating at voltages from 400V to 33kV with redundancy architectures ranging from N+1 to 2N configurations. Its primary purpose is to eliminate downtime in facilities where power interruption causes immediate operational and financial damage. Diesel generators retain the largest installed base across legacy facilities, though renewable energy and grid power integrations are capturing the fastest growth as operators pursue Scope 2 carbon reductions. Hyperscale data centers command the deepest capital pools and longest contract terms, while edge deployments remain fragmented with shorter asset lifecycles and lower switching costs.
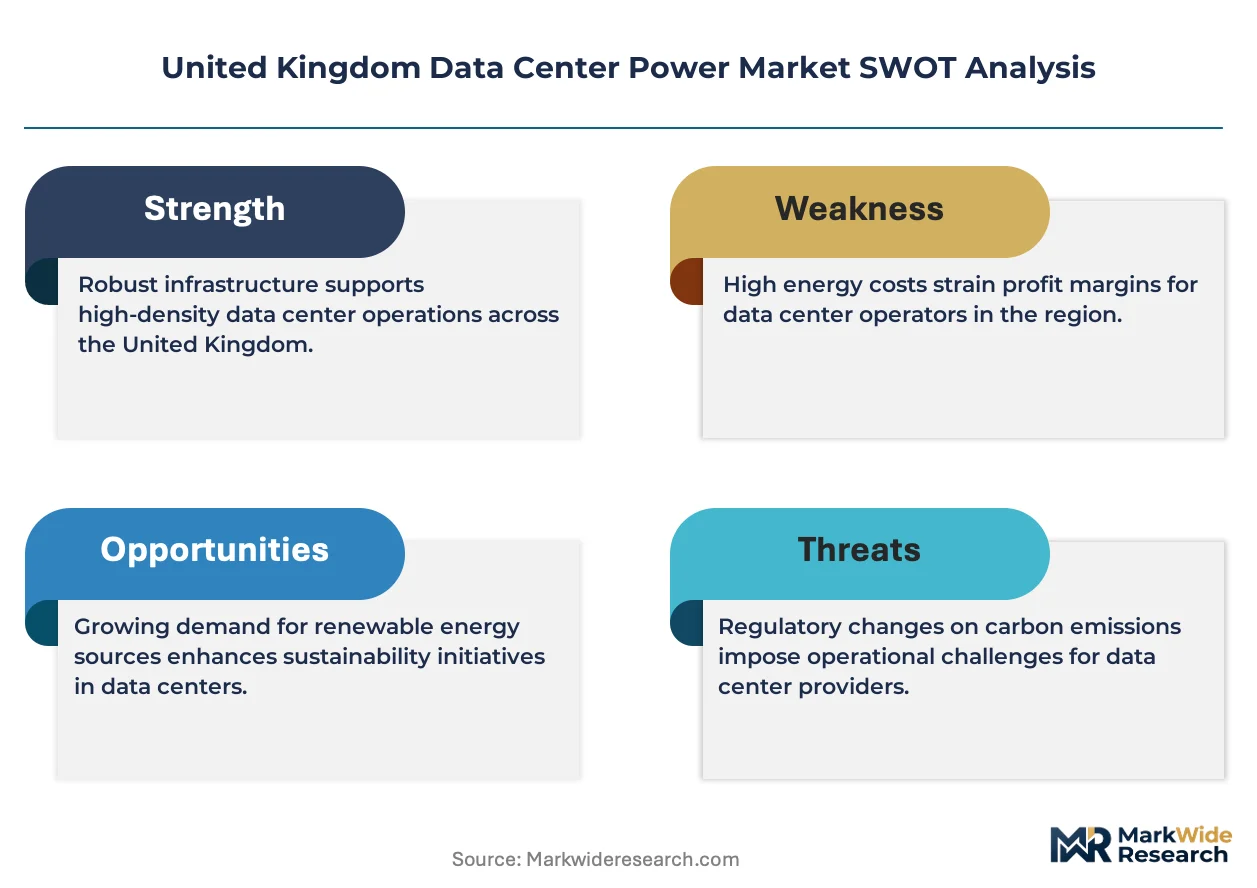
The Environment Agency enforces climate change agreements that mandate energy efficiency improvements across data center operations, while Ofgem regulates grid connection tariffs and capacity market participation that directly influence power sourcing economics. BSI standards for electrical installation and the UK's Building Regulations Part L set minimum efficiency thresholds for new facility construction. Stakeholders must monitor how carbon border adjustments and evolving capacity market rules reshape the cost structure of on-site generation versus grid-purchased renewable power.
Market Dynamics
Hyperscale operators in Slough and Manchester are driving liquid-cooled infrastructure adoption as rack densities exceed 50kW, forcing power architecture redesigns that favor direct current distribution and grid-interactive UPS systems over traditional alternating current topologies.
Growth Catalysts
- Ofgem capacity market reforms:New grid connection tariffs incentivize data center operators to install battery energy storage systems that participate in frequency response services, creating dual-revenue streams from backup assets.
- AI training clusters:GPU-intensive workloads in Greater London facilities are demanding 2N+1 redundancy configurations that expand addressable equipment spend per megawatt of IT capacity.
- Midlands fiber expansion:Virgin Media Business and CityFibre deployments in Birmingham and Nottingham are unlocking greenfield data center sites with available grid headroom that legacy markets lack.
Market Restraints
- Copper and silicon carbide supply concentration:Chinese refining dominance for power semiconductor substrates creates input cost volatility for medium-voltage switchgear manufacturers serving UK facilities.
- Grid connection queues:National Grid's 5-7 year lead times for new 132kV substations in the South East throttle expansion velocity for planned hyperscale campuses.
- Diesel generator phase-out friction:The Environment Agency's tightening emissions standards for non-road mobile machinery threaten stranded asset risk for facilities with recently installed backup gensets.
Strategic Opportunities
- Wales and Scotland greenfield development:Abundant renewable generation and cooler ambient temperatures in Cardiff and Glasgow offer PUE advantages for operators willing to bypass London proximity requirements.
- Grid-interactive UPS monetization:Synthetic inertia and fast frequency response contracts allow power infrastructure to generate ancillary revenue beyond standby functions.
- Hydrogen-ready backup systems:The UK Hydrogen Strategy's production targets position dual-fuel turbines as a compliance pathway for 2035 net-zero commitments without full infrastructure replacement.
Industry Challenges
- High-voltage direct current skill scarcity:Specialist electrical engineers capable of commissioning 1,500V DC bus architectures command premium wages that inflate project labor costs by 40% versus conventional AC deployments.
- Legacy infrastructure retrofit complexity:Facilities built under 2010 Building Regulations face costly electrical room reconfigurations to accommodate liquid-cooled power distribution units and higher fault current ratings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Data Center Power Market |
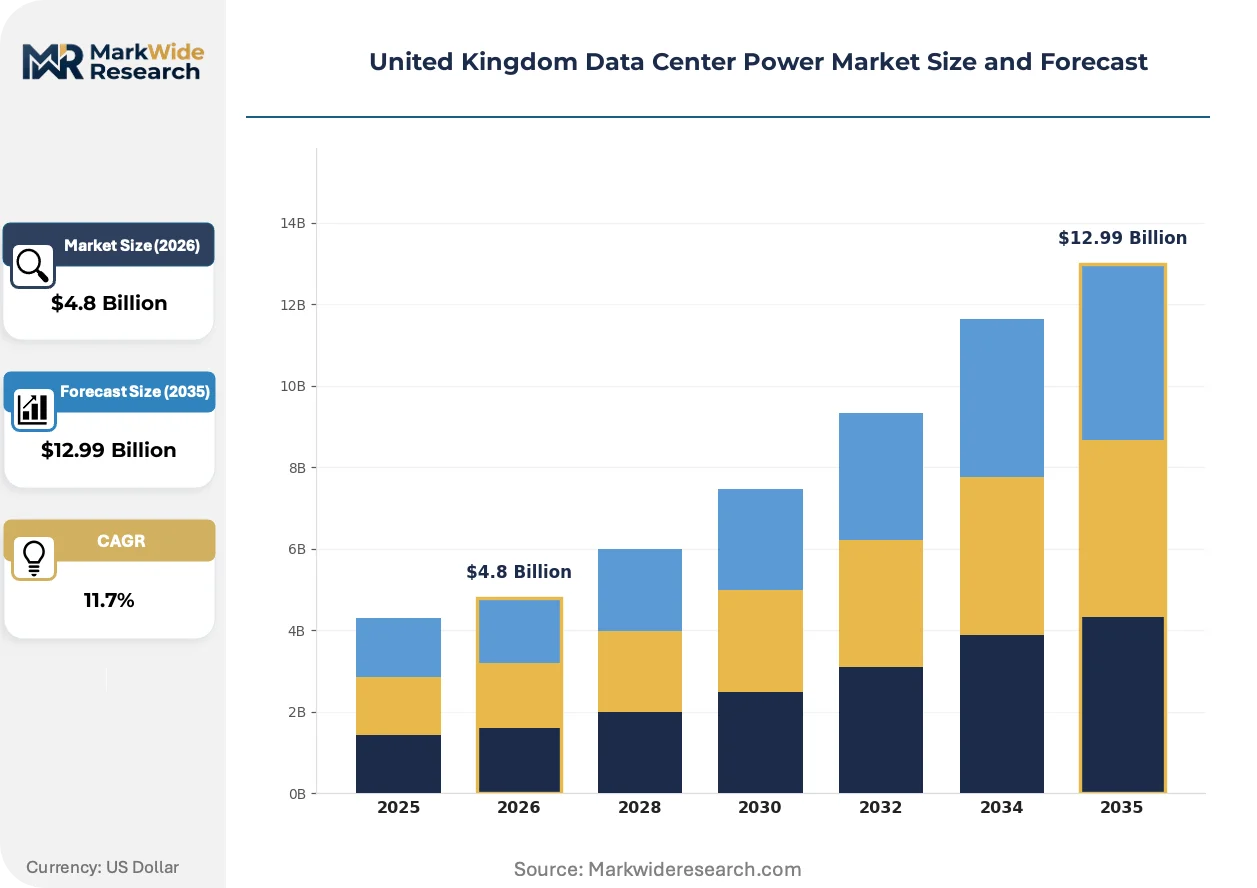
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable Energy, Diesel Generators, Grid Power, UPS Systems Data Center Type: Hyperscale, Colocation, Edge, Enterprise Cooling Technology: Air-Cooled, Liquid-Cooled, Evaporative Cooling, Raised Floor End User: IT Services, Media & Entertainment, Financial Services, E-commerce |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp., ABB Ltd., Eaton Corporation plc, Caterpillar Inc., Delta Electronics, Cummins, Rolls-Royce, AEG Power Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Data Center Power Market Trends and Innovations
Power infrastructure in UK data centers is transitioning from passive backup to active grid assets, with thermal management and electrical systems converging around shared control platforms that optimize energy flows in real time.
Liquid-cooled power distribution units are electrifying rack-level energy delivery by eliminating the efficiency losses of traditional air-cooled transformers and enabling direct-to-chip cooling integration. Colocation operators in Slough and London are specifying these systems for new 30MW+ halls, compressing the payback period for thermal-electrical convergence investments to under four years.
The Environment Agency's climate change agreement scheme is tightening energy efficiency benchmarks that mandate annual 15% improvement targets for participating facilities. Operators must now submit verified PUE data or face carbon price penalties, driving procurement of intelligent power monitoring platforms that granularly track consumption by workload type.
Power purchase agreement structures are displacing traditional utility contracts as the dominant procurement model for renewable energy sourcing. Hyperscale tenants in Manchester and the Thames Valley are negotiating sleeved PPAs that transfer volume risk to offtakers, while enterprise colocation customers absorb green premiums through pass-through rate structures.
United Kingdom Data Center Power Market Segmentation
Power infrastructure procurement in United Kingdom data centers follows distinct upgrade cycles that vary by facility scale, cooling architecture, and regulatory exposure. Understanding these segmentation boundaries clarifies where capital deployment concentrates and which technology transitions command priority investment timelines.
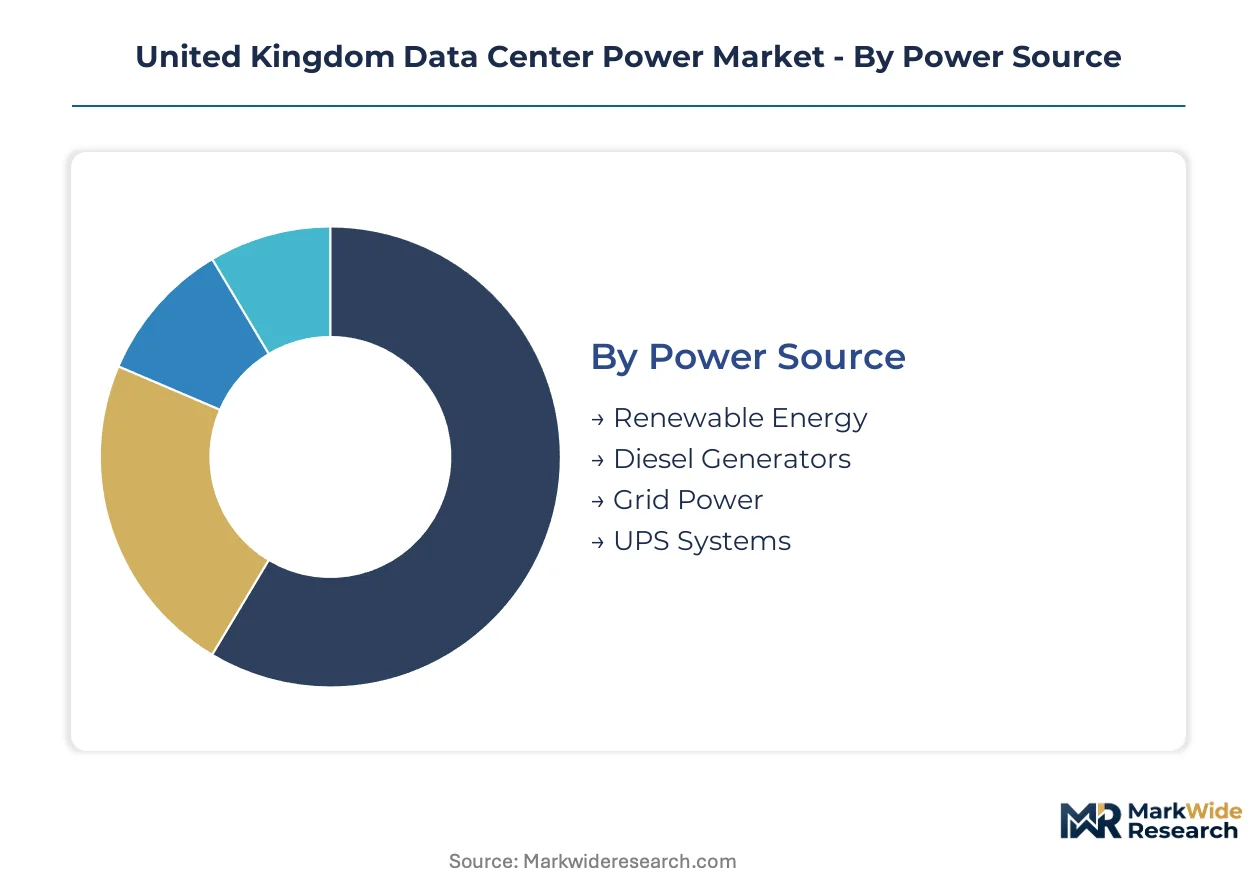
Power Source:
Replacement cycles for on-site generation and conditioning equipment accelerate as carbon compliance deadlines approach and grid-interactive revenue models mature.
- Renewable Energy:Direct solar PV and wind PPAs integrated with battery storage displace conventional backup in new Slough and Manchester builds. Grid connection queues in the South East push operators toward sleeved renewable contracts that bypass substation lead times.
- Diesel Generators:Legacy 2MW+ genset installations face stranded asset risk under Environment Agency emissions tightening. Facilities commissioned under pre-2020 Building Regulations now confront costly retrofit or replacement decisions before 2035 net-zero commitments.
- Grid Power:Direct utility supply dominates enterprise and edge deployments where capital constraints limit on-site infrastructure investment.
- UPS Systems:Lithium-ion battery topologies with frequency response capability capture hyperscale specification in Greater London facilities.
Volume placements concentrate in Grid Power; the faster expansion belongs to Renewable Energy.
Data Center Type:
Capital intensity and contract duration create divergent procurement patterns across facility scales, with hyperscale operators commanding bespoke power architectures unavailable to smaller deployments.
- Hyperscale:Purpose-built 30MW+ campuses specify liquid-cooled busbars and 2N+1 redundancy. Microsoft and Amazon Web Services deployments in the Midlands drive medium-voltage switchgear demand that outstrips regional supplier capacity.
- Colocation:Multi-tenant facilities balance standardization against tenant customization, with power density commitments now reaching 15kW per rack in London Docklands facilities.
- Edge:Distributed micro data centers prioritize rapid deployment over efficiency optimization, accepting higher PUE in exchange for latency positioning.
- Enterprise:Captive facilities in financial services and manufacturing segments lag hyperscale technology adoption due to capital approval cycles and internal IT governance constraints.
Procurement value concentrates in Hyperscale; the steepest expansion trajectory belongs to Edge.
Cooling Technology:
Thermal management architecture directly determines power distribution topology, with liquid-cooled racks demanding DC bus configurations that obsolete traditional transformer-based designs.
- Liquid-Cooled:Direct-to-chip and immersion systems enable 50kW+ rack densities in AI training clusters. Schneider Electric and Vertiv compete for specification in Slough facilities where PUE targets now sit below 1.15.
- Air-Cooled:Conventional CRAC and CRAH units retain dominance in legacy enterprise facilities and edge deployments where rack densities remain below 10kW.
- Evaporative Cooling:Adiabatic systems exploit cooler ambient temperatures in Scotland and northern England to reduce mechanical refrigeration load.
- Raised Floor:Perforated tile architectures persist in older facilities but constrain power density growth and complicate liquid cooling retrofits.
Deployment volume concentrates in Air-Cooled; the technology gaining share fastest is Liquid-Cooled.
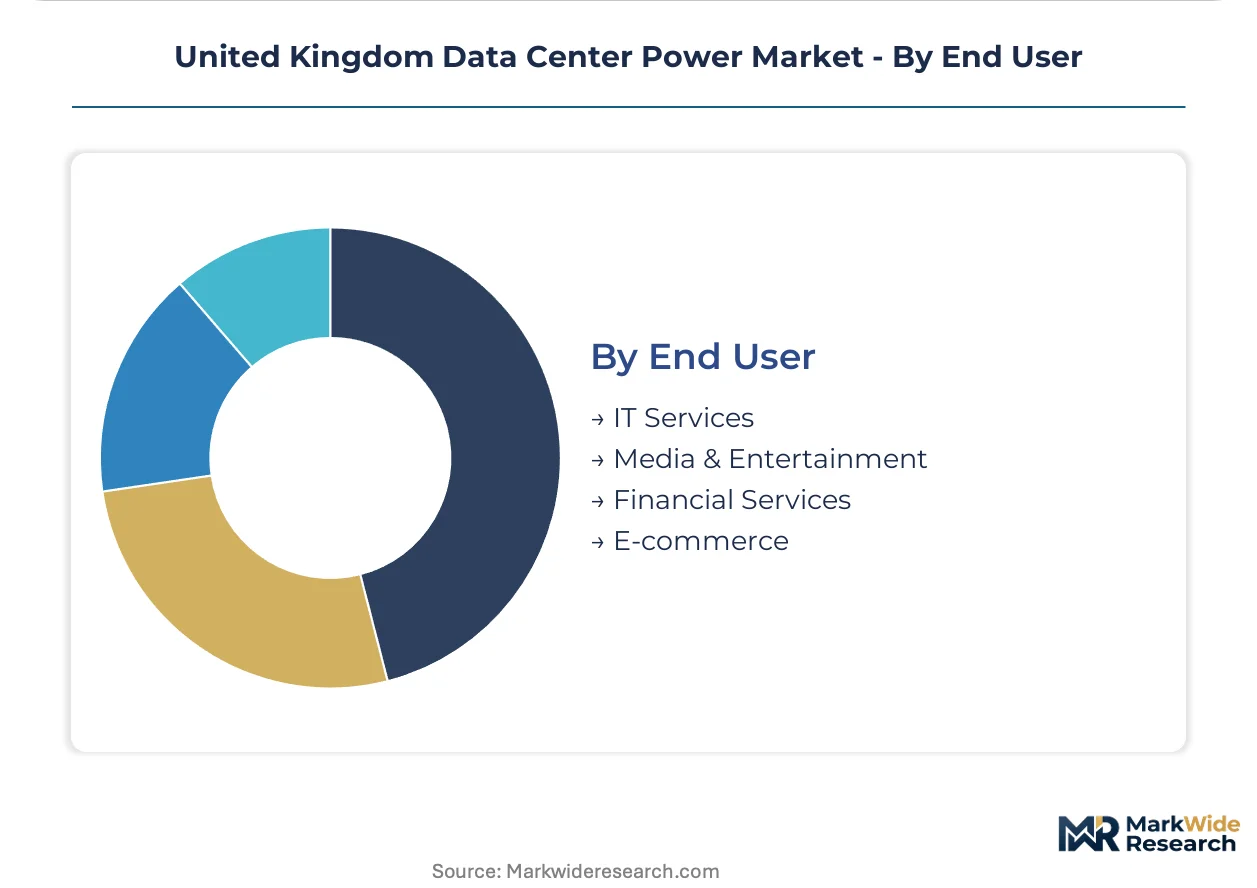
End User:
Workload characteristics and regulatory exposure shape power infrastructure requirements, with financial services and AI training clusters driving the most demanding reliability specifications.
- IT Services:Cloud providers and managed hosting operators in London and Manchester specify N+1 or 2N redundancy with sub-15-minute failover guarantees.
- Financial Services:Trading floor and clearing infrastructure in the City of London demands uninterruptible power with documented compliance to FCA operational resilience requirements.
- Media & Entertainment:Content delivery and streaming infrastructure prioritizes bandwidth proximity over power efficiency, concentrating in Thames Valley fiber hubs.
- E-commerce:Fulfillment-adjacent data centers in the Midlands align with logistics corridors, accepting moderate redundancy in exchange for geographic positioning.
Contract value concentrates in IT Services; the segment climbing the fastest is Financial Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London dominates United Kingdom data center power demand, with Slough and Docklands corridors anchoring hyperscale expansion. Grid capacity constraints and net-zero carbon commitments are redistributing investment toward the Midlands and northern sub-regions.
London and Southeast
Hyperscale operators in Slough and the Thames Valley specify liquid-cooled busbars for 50kW+ AI rack densities. Ofgem's capacity market reforms incentivize battery storage participation in frequency response services. London Docklands facilities now require 2N+1 redundancy for financial services tenants under FCA operational resilience rules.
Midlands
Virgin Media Business and CityFibre fiber expansions in Birmingham and Nottingham unlock greenfield sites with available grid headroom. The UK's Building Regulations Part L mandates minimum efficiency thresholds for new facility construction. Microsoft and Amazon Web Services campuses in the East Midlands drive medium-voltage switchgear demand that strains regional supplier capacity.
North England
Manchester data centers concentrate fiber connectivity and cooler ambient conditions that reduce mechanical cooling loads. The Environment Agency's climate change agreements enforce annual 15% energy efficiency improvement targets. Trafford Park and Salford Quays clusters attract colocation investment seeking PUE advantages below London levels.
Scotland
Abundant renewable generation and sub-15°C average ambient temperatures position Glasgow and Edinburgh for PUE-optimized hyperscale deployment. Scottish Power's grid interconnection queue moves faster than England's congested South East. Strathclyde and Edinburgh Park corridors host pilot direct liquid cooling installations for HPC workloads.
Wales
Cardiff and Newport offer untapped grid capacity and proximity to Celtic Sea offshore wind interconnectors. The UK Hydrogen Strategy's production targets support dual-fuel turbine pilot programs for 2035 net-zero compliance. South Wales data center proposals accelerate as London proximity requirements relax for latency-tolerant workloads.
United Kingdom Data Center Power Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and project scale, with hyperscale-specified liquid-cooled architectures commanding pricing power over air-cooled legacy configurations. The vendor base stratifies between integrated power-cooling platform providers, specialized thermal management specialists, and component-scale electrical equipment manufacturers. Three archetypes dominate: full-stack infrastructure integrators, thermal-electrical convergence specialists, and switchgear-focused electrical equipment houses. Competitive moves concentrate on strategic partnerships for grid-interactive UPS deployment and geographic expansion into Midlands greenfield corridors.
Within the integrated platform tier, Schneider Electric SE and Vertiv Group Corp. exemplify full-stack positioning that spans medium-voltage switchgear through rack-level power distribution. ABB Ltd. anchors the electrical equipment specialist archetype with advanced switchgear and digital monitoring platforms. These three companies collectively represent the technology leadership layer that hyperscale operators in Slough and Manchester specify for 30MW+ campus developments.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp. |
| ABB Ltd. |
| Eaton Corporation plc |
| Caterpillar Inc. |
| Delta Electronics |
| Cummins |
| Rolls-Royce |
| AEG Power Solutions |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide substrate costs cascade through medium-voltage switchgear pricing tiers, with Chinese refining dominance compressing margins for UK-specified electrical equipment while hyperscale operators absorb premiums for liquid-cooled busbar configurations that bypass traditional transformer architectures.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for hyperscale deployments in Slough and Manchester, where 2N+1 redundancy specifications command substantial premiums over N+1 enterprise configurations. Price differentiation separates liquid-cooled direct-current architectures from air-cooled alternating-current legacy systems, with certification to BSI electrical installation standards and Environment Agency climate change agreement compliance adding further tier separation. Pricing pressure stems from copper and rare earth magnet cost volatility transmitted through medium-voltage switchgear supply contracts. Enterprise colocation customers exhibit highest price sensitivity due to pass-through rate structures, while AI training cluster operators prioritize density specifications over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese silicon carbide wafer refining for power semiconductor substrates, creating input cost instability for ABB and Schneider Electric medium-voltage equipment serving UK facilities. Manufacturing concentrates in China, Germany, and the United States for critical power infrastructure components. Raw material dependencies include copper busbar stock, lithium-ion battery cells, and silicon carbide MOSFETs. Supply chain risk centers on tariff exposure from carbon border adjustments affecting imported electrical equipment. Distribution runs through direct OEM relationships with hyperscale operators and tiered channel partnerships for enterprise and edge deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over lithium-ion battery cell supply and liquid-cooled power distribution unit manufacturing determines margin capture in hyperscale specifications.
For Market Incumbents: Deepen backward integration into silicon carbide substrate sourcing to insulate medium-voltage switchgear margins from Chinese supply volatility. Secure captive production capacity for lithium-ion battery energy storage systems in the Midlands to capture Ofgem frequency response revenue streams. Colocation operators in London Docklands represent substitution threat as they consolidate procurement around integrated power-cooling platforms. For New Entrants and Emerging Players: Channel partnerships with Virgin Media Business and CityFibre infrastructure deployers unlock greenfield data center sites in Birmingham and Nottingham where grid headroom exceeds London availability. Wales and Scotland offer most penetrable geography for PUE-optimized facilities leveraging cooler ambient temperatures and faster grid interconnection queues. Position around hydrogen-ready backup system pilot programs aligned with UK Hydrogen Strategy production targets. For Investors and Strategic Acquirers: Grid-interactive UPS deployment announcements from hyperscale operators are the leading indicator that ancillary revenue monetization is shifting from pilot to scale. Long-term viability favors vertically integrated specialists spanning thermal management through electrical distribution with demonstrated liquid-cooled commissioning capability. Acquisition targets should show proven deployment track record in 30MW+ campuses and established relationships with National Grid for substation co-location.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Energy Storage Integration | Ofgem capacity market reforms enable dual-revenue streams from backup assets participating in frequency response services. |
| Liquid-Cooled Busbar Deployment | Direct-to-chip cooling integration eliminates transformer losses and supports 50kW+ rack densities for AI clusters. |
| Grid-Interactive UPS Monetization | Synthetic inertia contracts transform passive backup infrastructure into active grid assets generating ancillary revenue. |
| Hydrogen-Ready Backup Systems | Dual-fuel turbine pilots align with 2035 net-zero commitments without full diesel generator replacement. |
| Midlands Greenfield Expansion | Virgin Media Business and CityFibre fiber deployments unlock sites with available grid headroom legacy markets lack. |
Research Methodology
Regulatory filings from Ofgem and the Environment Agency, National Grid interconnection queue data, and hyperscale operator capital expenditure disclosures formed the secondary backbone for market sizing. Primary interviews with data center engineering directors, electrical contractors specializing in 1,500V DC architectures, and procurement leads at colocation operators validated equipment specification trends and pricing dynamics. Bottom-up triangulation across facility-level power infrastructure spend and top-down reconciliation against aggregate market value estimates produced volume and value outputs.
Historical trendline analysis of power infrastructure procurement cycles by facility type informed the projection framework across the analysis window. Segmentation dimensions modeled include power source topology, data center scale tier, cooling technology architecture, and end-user workload characteristics. CAGRs were derived from regression analysis of capital deployment patterns correlated with grid connection queue lengths and carbon compliance deadline proximity. Industry-specific forecast inputs incorporated Environment Agency climate change agreement participation rates and Building Regulations Part L efficiency threshold adoption curves.
Caveats apply where National Grid substation lead time extensions, carbon border adjustment implementation scope, or silicon carbide supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding hyperscale expansion velocity in Greater London and the Midlands, renewable energy PPA pricing trajectories, and liquid-cooled infrastructure penetration rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
Data Center Construction Market
Data Center Infrastructure
United Kingdom Data Center Market
Data Center Infrastructure
New York Data Center Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
Europe Data Center Physical Security Market
Data Center Infrastructure
Global Datacenter Deployment Spending Market
Data Center Infrastructure
Middle East Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
Switchgear for Data Centers Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Italy Data Center Power Market
Data Center Infrastructure
Germany Data Center Market