
 US Prefabricated Buildings Market | 2026-2036
US Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
US Prefabricated Buildings Market Analytics
Energy-efficient building certification is rotating toward the center of buyer procurement criteria in the US prefabricated buildings sector. Clayton Homes, Inc. leverages its manufactured housing scale to dominate rural and suburban distribution channels. Champion Home Builders, Inc. anchors its position through vertical integration across component supply and final assembly. Prescient Co. differentiates through precision-engineered steel framing systems designed for mid-rise commercial applications.
US prefabricated buildings are factory-built structural assemblies manufactured under controlled conditions, then transported and installed at permanent sites, with specifications typically governed by ICC standards and state modular administrative programs. The primary purpose is compressing construction schedules while reducing material waste and labor variability. Modular buildings command the largest product-type position due to their adaptability across residential and commercial end uses. Panelized systems represent the fastest-expanding construction method category as builders adopt hybrid on-site and off-site workflows. Steel and wood materials split the market along project height and fire-rating requirements, with steel capturing mid-rise commercial and wood retaining single-family residential dominance.
FHA, VA, and HUD code frameworks govern financing eligibility and construction standards for manufactured housing, directly shaping consumer access and resale liquidity in the US market. State-level modular building programs, particularly California's HCD certification and Florida's DBPR oversight, create fragmented compliance pathways that favor multi-state operators with dedicated regulatory affairs capacity. Stakeholders must monitor evolving local zoning amendments that alternately restrict or permit modular density in transit-oriented development zones.
Market Dynamics
Federal infrastructure spending through the Infrastructure Investment and Jobs Act is compressing project timelines and forcing contractors toward off-site fabrication methods that bypass weather delays and labor shortages. State-level modular administrative programs are simultaneously standardizing inspection protocols, reducing the regulatory friction that previously slowed interstate deployment.
Growth Catalysts
- HUD Code financing frameworks:FHA and VA loan eligibility for manufactured housing expands consumer access in rural markets where conventional construction financing remains scarce.
- Panelized construction methods:Hybrid on-site and off-site workflows accelerate project velocity for multi-family developers facing compressed delivery schedules in Texas and Florida housing markets.
- California HCD certification:Streamlined factory inspection protocols reduce time-to-occupancy for affordable housing projects in transit-oriented development zones.
Market Restraints
- Lumber input volatility:Price swings in dimensional lumber and engineered wood products destabilize project budgeting for wood-dominant single-family prefabricated units.
- Steel supply concentration:Domestic steel framing component sourcing clusters in Midwest production corridors, creating vulnerability to regional logistics disruptions.
- Florida DBPR compliance fragmentation:State-specific modular building oversight creates redundant certification burdens for multi-state operators lacking dedicated regulatory affairs capacity.
Strategic Opportunities
- Mid-rise commercial steel framing:Precision-engineered systems for five-to-twelve-story buildings address zoning density incentives in California and Texas urban cores.
- Energy-efficient certification mandates:California Title 24 building efficiency standards drive specification of high-performance envelope assemblies in factory-controlled conditions.
- Direct-to-developer digital platforms:Online configuration tools bypass traditional distributor networks, capturing margin from design-through-delivery workflows.
Industry Challenges
- Skilled factory technician scarcity:CNC equipment operation and precision assembly expertise lags demand in rural manufacturing locations.
- Interstate transport dimensional limits:Highway load restrictions constrain module sizing, forcing design compromises or costly permit acquisitions.
- Legacy site integration complexity:Foundation tolerances and utility connection standards vary by municipality, complicating factory-to-field handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Prefabricated Buildings Market |
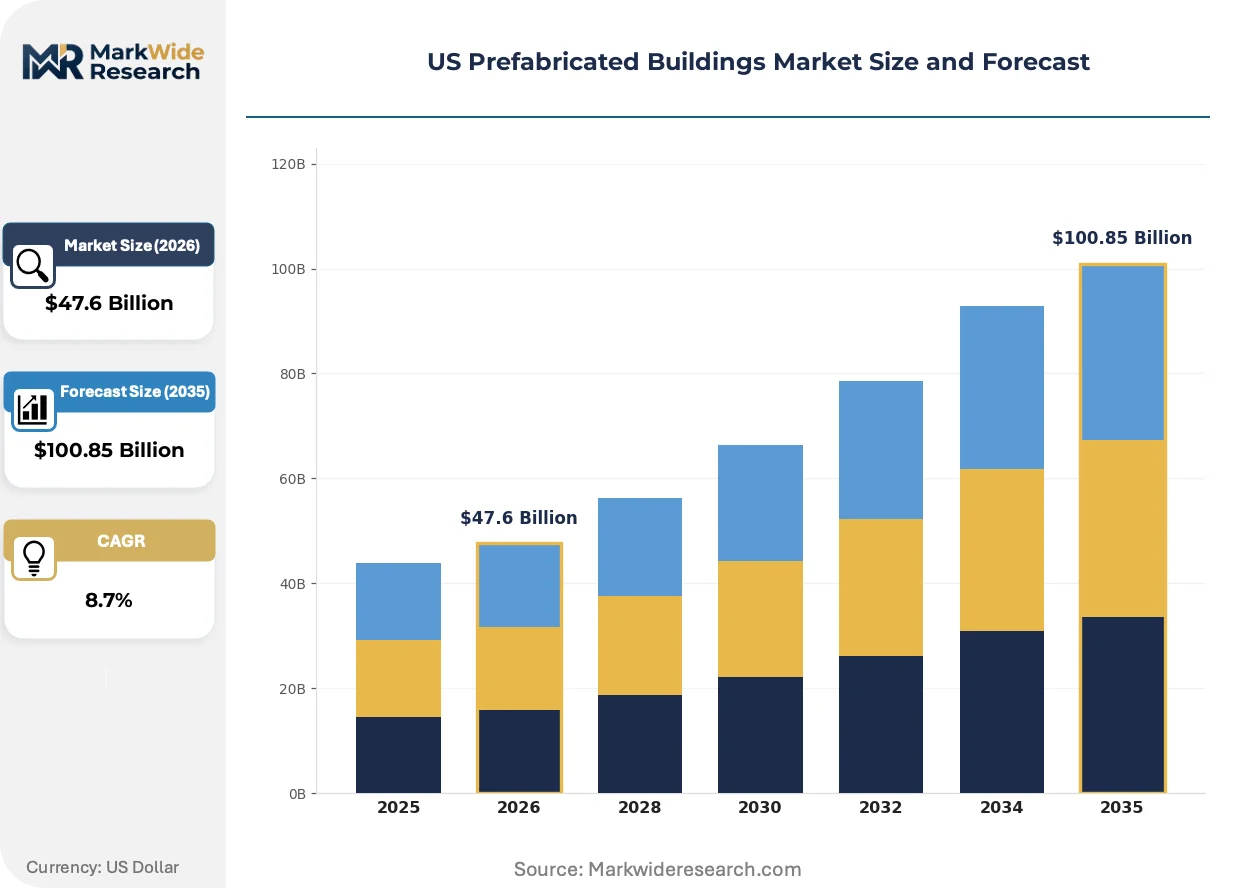
| Market Size in 2026 | $47.6 Billion |
| Market Size in 2035 | $100.85 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Buildings, Panelized Buildings, Prefab Homes, Precast Concrete End User: Residential, Commercial, Educational, Healthcare Construction Method: Traditional, Hybrid, Off-Site, On-Site Material: Wood, Steel, Concrete, Composite |
| Companies Covered | Champion Home Builders, Inc., Guerdon, LLC, Clayton Homes, Inc., Prescient Co., Plant Prefab, Skyline Champion Corporation, Boxabl, Inc., Factory OS, Cavco Industries, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Prefabricated Buildings Market Evolving Landscape
Digital fabrication and advanced materials are compressing the traditional trade-off between customization and scale in factory-built construction. Regulatory pressure on embodied carbon and operational energy is simultaneously elevating performance specifications.
Cross-laminated timber (CLT) and mass timber systems are displacing conventional steel and concrete in mid-rise commercial applications. Multi-family developers in Pacific Northwest markets adopt these materials for five-to-eight-story projects seeking biogenic carbon credits. The structural consequence is a resegmentation of the mid-rise category, with timber-captured projects achieving faster permitting through green building incentive programs.
California's Title 24 building efficiency standards and the federal Inflation Reduction Act tax credits for energy-efficient construction are tightening envelope performance requirements. Factory-built assemblies with integrated continuous insulation and thermal bridge elimination outperform field-built equivalents in blower-door testing. Affordable housing developers in California leverage these code advantages to secure low-income housing tax credit allocations that prioritize energy performance.
Hospital and healthcare facility procurement teams now specify modular mechanical penthouses and plant rooms as standard practice, compressing construction schedules for critical infrastructure. General contractors in Texas and Florida medical markets subcontract these systems to prefabrication specialists rather than self-performing. This behavioral shift is most visible in acute care expansion projects where revenue-per-day calculations magnify schedule risk.
US Prefabricated Buildings Market Segmentation
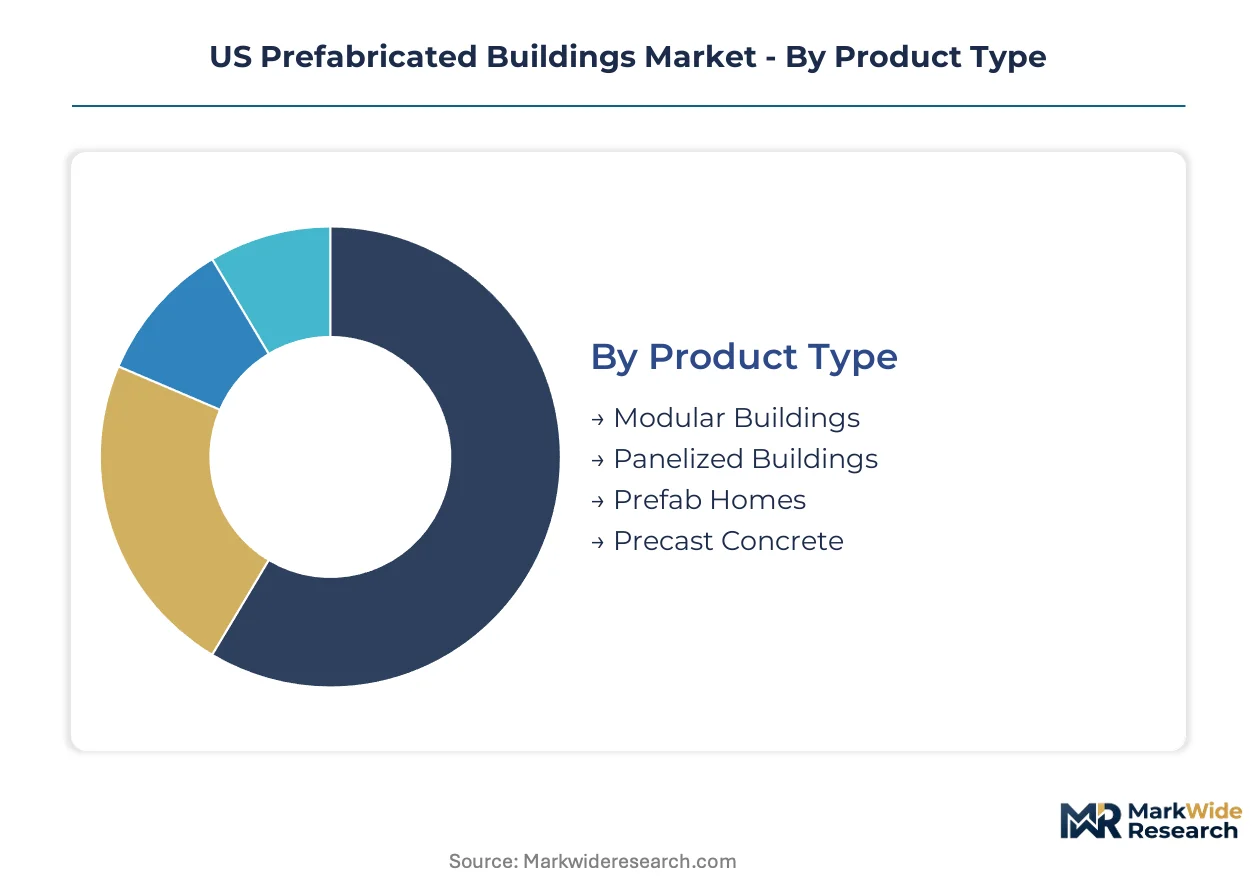
Segmentation in the US prefabricated buildings sector reveals how construction methods and material choices determine competitive vulnerability. Each dimension exposes different pressure points from substitutes like conventional stick-built construction and tilt-up concrete.
Product Type:
Panelized buildings face the most acute substitution pressure from site-built framing, while modular and precast systems defend through factory precision that field construction cannot replicate.
- Modular Buildings:Fully volumetric units constructed to ICC standards and state modular administrative programs, then craned onto permanent foundations. Demand concentrates in California affordable housing and Texas multi-family projects where HCD certification and compressed schedules offset transport costs.
- Panelized Buildings:Wall, floor, and roof components fabricated off-site for rapid on-site assembly. Texas and Florida homebuilders adopt these for single-family subdivisions where hybrid workflows balance labor savings against foundation tolerance risks.
- Prefab Homes:HUD Code-manufactured housing units serving rural markets with FHA and VA financing access.
- Precast Concrete:Factory-cast structural and architectural concrete elements for parking structures and institutional facades.
Modular buildings retain volume leadership; panelized buildings hold the steepest expansion curve.
End User:
Cost tier differentiation separates high-specification healthcare and educational procurement from price-sensitive residential development.
- Residential:Single-family and multi-family housing across manufactured, modular, and panelized formats. California's transit-oriented development zones and Florida's retirement communities drive specification of energy-efficient envelope assemblies.
- Commercial:Office, retail, and hospitality structures where steel-framed modular systems capture five-to-twelve-story urban infill in Texas and California density corridors.
- Educational:K-12 and university facilities procured through public bond financing with compressed summer construction windows.
- Healthcare:Acute care expansions and outpatient clinics where modular mechanical penthouses and plant rooms compress revenue-critical schedules.
Residential commands absolute volume; commercial posts the steepest expansion curve.
Construction Method:
Application maturity varies sharply, with hybrid workflows penetrating fastest where labor constraints meet legacy contractor relationships.
- Hybrid:Combined off-site component fabrication with on-site structural and MEP integration. Multi-family developers in Texas and Florida adopt these workflows to accelerate delivery without abandoning established general contractor relationships.
- Off-Site:Complete structural assembly in factory conditions with minimal field work. California affordable housing developers leverage this method to satisfy Title 24 energy standards through controlled envelope fabrication.
- Traditional:Conventional site-built construction retaining dominance in custom single-family and renovation markets.
- On-Site:Limited prefabrication with primarily field-based assembly, common in small-scale residential and remote geographies.
Hybrid methods retain volume leadership; off-site construction holds the steepest expansion curve.
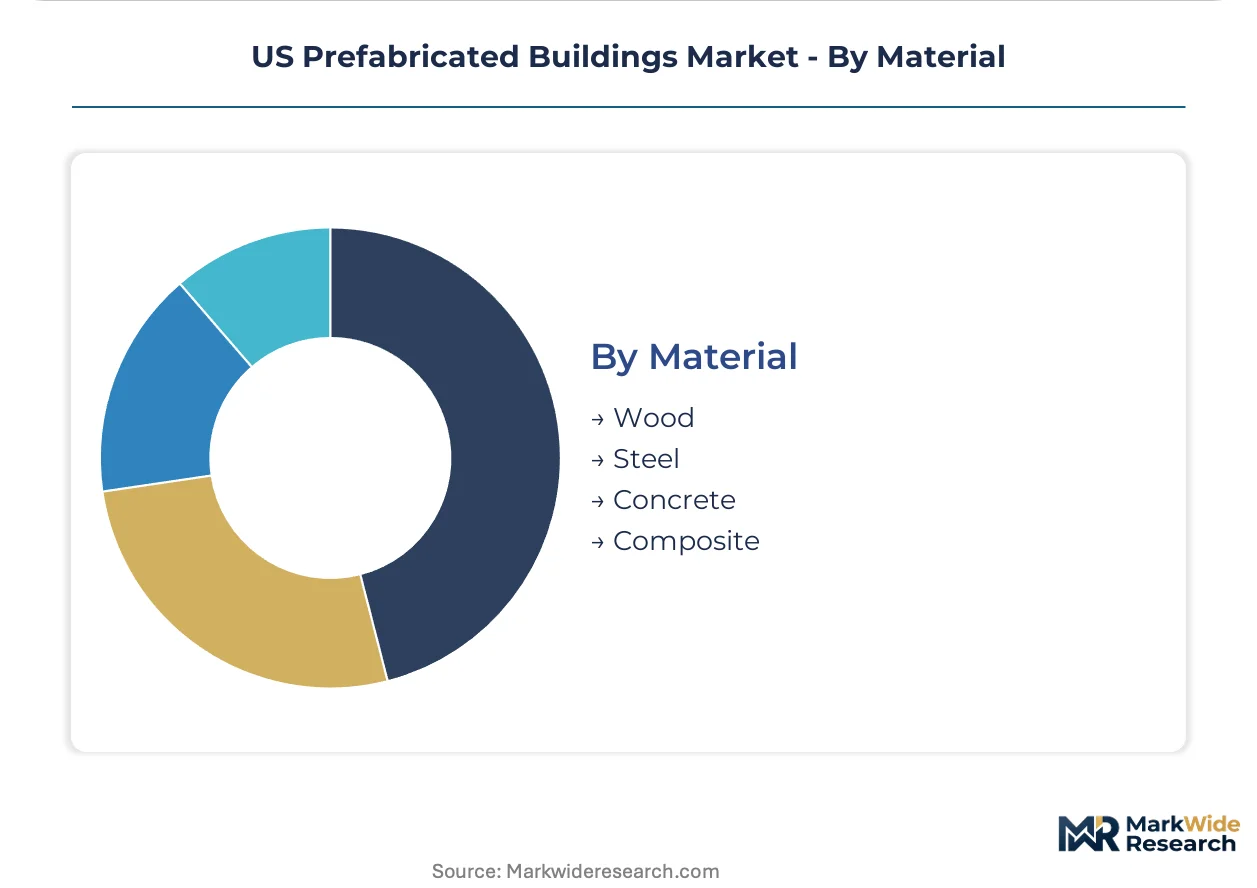
Material:
Customer type segmentation splits the market between wood-dependent residential builders and steel-specifying commercial developers.
- Wood:Dimensional lumber and engineered wood products dominating single-family manufactured housing and panelized residential construction. Price volatility in lumber inputs destabilizes project budgeting for wood-dominant prefabricated units.
- Steel:Cold-formed and structural steel framing systems specified for mid-rise commercial and multi-family projects. California and Texas urban cores drive demand for precision-engineered steel systems that satisfy fire-rating and seismic requirements.
- Concrete:Precast and tilt-up concrete for parking structures, institutional buildings, and heavy industrial applications.
- Composite:Cross-laminated timber and fiber-reinforced polymer systems gaining specification in Pacific Northwest five-to-eight-story commercial projects seeking biogenic carbon credits.
Wood retains volume leadership; steel holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory fabrication capacity clusters along interstate corridors where module transport costs and state regulatory alignment minimize friction. Texas, California, and Florida concentrate demand through distinct housing shortage profiles and modular code maturity.
California
Transit-oriented development zones in Los Angeles and San Francisco Bay Area drive specification of steel-framed modular systems for five-to-twelve-story density projects. California HCD certification streamlines factory inspection protocols, compressing affordable housing delivery timelines. Sacramento and Riverside manufacturing corridors host precision-engineered panel producers serving Title 24 energy compliance mandates.
Texas
Houston and Dallas-Fort Worth multi-family developers adopt hybrid panelized workflows to bypass labor constraints in compressed construction windows. State modular administrative programs align with ICC standards, reducing interstate deployment friction for factory-built components. Austin and San Antonio urban cores attract mid-rise commercial steel framing specialists addressing zoning density incentives.
Florida
Retirement community expansion in Tampa and Orlando corridors sustains demand for manufactured housing with FHA and VA financing access. Florida DBPR oversight creates compliance fragmentation that favors operators with dedicated regulatory affairs capacity. Miami-Dade and Broward counties specify modular mechanical penthouses for hospital expansion projects where schedule compression carries revenue-critical weight.
Pacific Northwest
Seattle and Portland multi-family developers specify cross-laminated timber systems for five-to-eight-story projects seeking biogenic carbon credits under green building incentive programs. Washington and Oregon state energy codes tighten envelope performance requirements that factory-controlled fabrication satisfies more reliably than field-built equivalents. Vancouver, Washington manufacturing clusters serve cross-border demand from British Columbia mass timber adopters.
Southeast
Atlanta and Charlotte commercial developers deploy precast concrete systems for parking structures and institutional facades where fire-rating requirements exceed wood capabilities. Georgia and North Carolina modular building programs standardize inspection protocols, attracting multi-state operators seeking regulatory efficiency. Charleston and Raleigh manufacturing corridors supply panelized components for single-family subdivisions balancing labor savings against foundation tolerance risks.
US Prefabricated Buildings Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the US prefabricated buildings sector. Manufactured housing specialists leverage scale economies in rural distribution, while precision-engineered steel framers capture premium positioning in mid-rise commercial applications. The competitive terrain splits between volume-driven producers of standardized units and project-specific fabricators of custom architectural assemblies. Dominant competitive moves include backward integration into component supply and geographic expansion through state modular program certification.
Among US-based fabricators, Champion Home Builders, Inc. and Clayton Homes, Inc. occupy positions within the manufactured housing volume tier, while Prescient Co. exemplifies the precision-engineered commercial steel framing specialist archetype. These three anchors represent distinct strategic postures: scale-driven rural distribution, integrated supply chain control, and technology-differentiated mid-rise specification respectively.
| Leading Market Players |
|---|
| Champion Home Builders, Inc. |
| Guerdon, LLC |
| Clayton Homes, Inc. |
| Prescient Co. |
| Plant Prefab |
| Skyline Champion Corporation |
| Boxabl, Inc. |
| Factory OS |
| Cavco Industries, Inc. |
| Others |
Value Network & Pricing Analysis
Cross-laminated timber displacing steel and concrete in Pacific Northwest mid-rise projects simultaneously redraws procurement geography toward British Columbia and Washington manufacturing clusters while compressing pricing premiums previously commanded by conventional materials. This substitution dynamic forces steel-framed modular producers to defend margin position through factory automation investments that offset biogenic carbon credit advantages accruing to mass timber competitors.
Pricing Analysis
HUD Code financing frameworks dictate the pricing tier structure across manufactured housing, separating FHA-eligible economy units from premium modular systems certified under California HCD and Florida DBPR programs. Price differentiation rests on certification level and energy performance grade, with Title 24-compliant envelope assemblies commanding substantial premiums in California transit-oriented zones. Cost compression in wood-dominant panelized residential construction is intensifying because dimensional lumber input volatility destabilizes project budgeting. Multi-family developers in Texas and Florida exhibit highest price sensitivity, while acute care healthcare procurement teams prioritize schedule certainty over unit cost minimization.
Supply Chain Analysis
Inbound logistics costs from West Coast port congestion and container availability constraints on Asia-Pacific trade lanes elevate landed costs for engineered wood products and cold-formed steel components. Domestic supply concentrates in Midwest steel production corridors, Pacific Northwest mass timber facilities, and Southern engineered wood manufacturing clusters. Raw material dependencies center on dimensional lumber, structural steel coil, and continuous insulation feedstock. Single-source vulnerability in precision CNC equipment sourcing from Germany and Japan creates disruption exposure. Distribution runs through factory-direct channels for large developers and regional distributor networks serving smaller contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multi-state developers with dedicated regulatory affairs capacity, fragmenting procurement influence previously dispersed across localized general contractors. This consolidation intensifies price pressure on fabricators lacking direct-to-developer digital platforms.
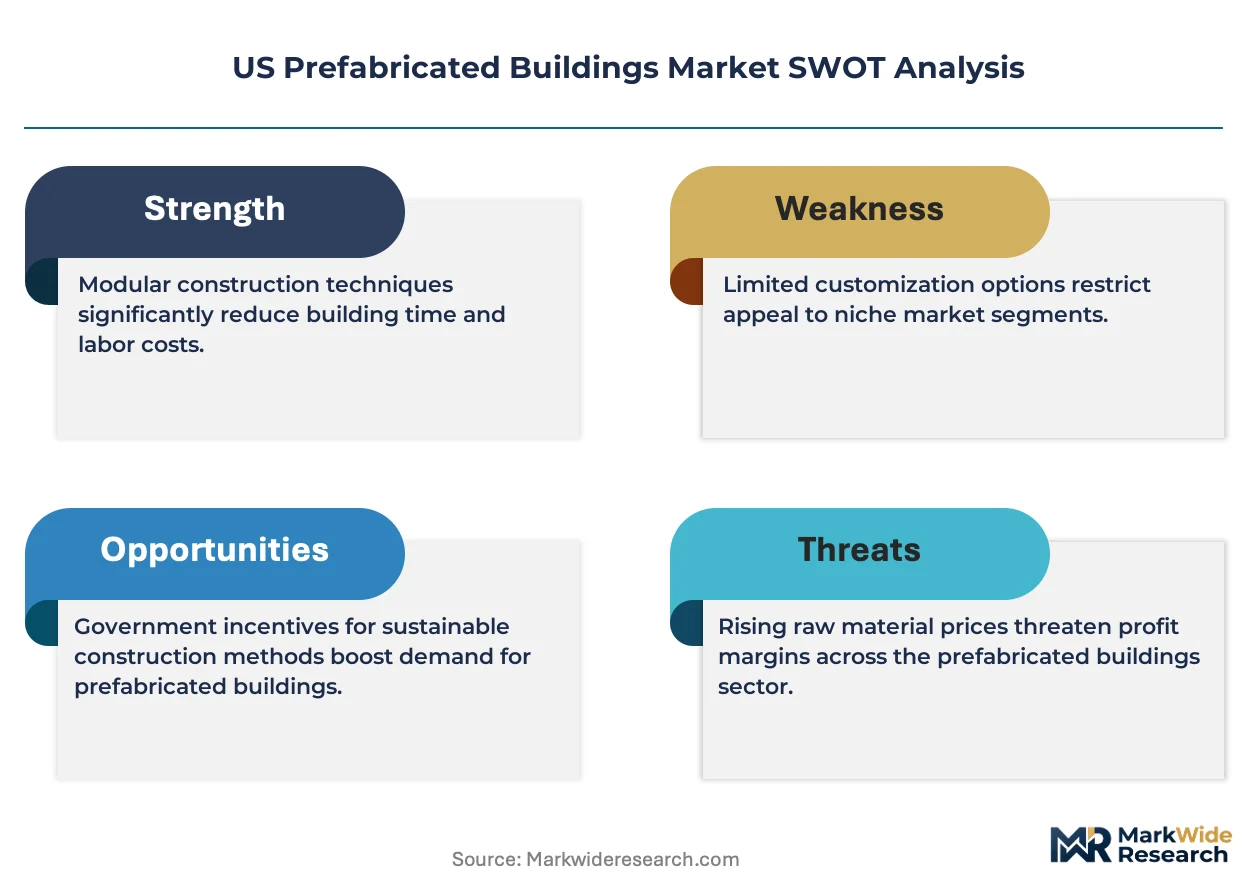
For Market Incumbents: Fortify competitive position through backward integration into engineered wood component supply and captive steel coil sourcing that insulates margin from raw material volatility. Champion Home Builders and Clayton Homes must defend against precision-engineered steel specialists like Prescient Co. by accelerating HCD and DBPR certification expansion into adjacent state modular programs. Factory automation in CNC equipment operation addresses skilled technician scarcity threatening production velocity. For New Entrants and Emerging Players: Regulatory compliance services for multi-state operators represent a service-layer gap where incumbents under-serve, creating white-space for specialized consultancies bundling California HCD, Florida DBPR, and Texas modular administrative program navigation. Direct-to-developer digital configuration platforms bypass traditional distributor networks in Texas and Florida multi-family markets. Panelized hybrid workflows for single-family subdivisions offer the most penetrable entry point, leveraging established general contractor relationships without requiring full modular factory capital deployment. For Investors and Strategic Acquirers: The market sits at a technology-adoption phase that favors precision-engineered steel framing specialists with mid-rise commercial positioning over volume-driven manufactured housing producers facing lumber input volatility. Long-term viability over the next decade hinges on regulatory affairs capacity and factory automation sophistication. Acquisition targets should demonstrate multi-state modular program certification and digital platform integration. The signal to watch is California Title 24 envelope performance standard tightening, which would accelerate factory-built assembly specification over field-built equivalents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Component Supply | Captive engineered wood and steel coil sourcing insulates margin from commodity volatility destabilizing project budgeting. |
| Multi-State Modular Program Certification | HCD, DBPR, and Texas administrative program alignment reduces regulatory friction for interstate deployment of factory-built units. |
| Direct-to-Developer Digital Platform Launch | Online configuration tools capture margin from design-through-delivery workflows bypassing traditional distributor networks. |
| Factory Automation Investment | CNC equipment and precision assembly automation addresses skilled technician scarcity constraining rural manufacturing locations. |
| Energy-Efficient Certification Program | Title 24 and Inflation Reduction Act tax credit alignment secures specification in California affordable housing procurement. |
Research Methodology
A standing panel of modular factory operations directors, multi-family development project managers, state modular program administrators, and healthcare facility procurement officers provided ongoing calibration across the research process. Primary interviews with these stakeholders combined with secondary validation against ICC standards documentation, HUD Code regulatory filings, California HCD inspection protocols, and Florida DBPR administrative records. Bottom-up project pipeline analysis and top-down construction spending data triangulated volume estimates.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation dimensions modeled include product type, end user, construction method, material, and regional regulatory cluster. CAGRs derived from historical construction cost indices and factory capacity utilization trends, incorporating labor constraint severity indices and material input price volatility measures specific to engineered wood and structural steel markets.
Forecasts assume regulatory continuity in HUD, HCD, and DBPR regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Germany Prefabricated Buildings Market
Building Construction
Italy Construction Market
Building Construction
El Salvador Construction Market
Building Construction
Construction Market
Building Construction
Precast Construction Market
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
Saudi Arabia Infrastructure Sector Market
Building Construction
Japan Commercial Construction Market
Building Construction
Europe Modular Construction Market
Building Construction
Tanzania Construction Market
Building Construction
Energy-Efficient Building Market
Building Construction
Poland Construction Market
Building Construction
Africa Construction Market
Building Construction
France Prefab Wood Building Market
Building Construction
Saudi Arabia Construction Market