
 Vietnam Ceramic Tiles Market | 2026-2036
Vietnam Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Ceramic Tiles Market Outlook
The capital-intensity gap between automated kiln operators and manual plants is collapsing as energy costs reshape viability thresholds. Viglacera Corporation leverages captive gas supply and integrated clay sourcing to sustain margin buffers against volatile input prices. Prime Group anchors its position through large-format porcelain specialization, while Bạch Mã competes on heritage brand recognition in northern provincial channels.
Vietnam ceramic tiles are sintered clay-based surfacing materials fired at temperatures between 1,000°C and 1,250°C, forming dense, wear-resistant slabs for interior and exterior architectural coverage. Porcelain tiles command the premium tier due to lower water absorption rates below 0.5 percent, making them suitable for high-traffic commercial flooring and humid tropical climates. The residential end-user segment leads volume absorption as apartment construction expands in Danang and Binh Duong, while wall cladding applications in hospitality projects represent the fastest-growing margin pool. Distribution through direct sales to project developers controls the largest value channel, though online sales gain share among retail renovators seeking standardized formats.
Vietnam's Ministry of Construction enforces QCVN national technical standards for ceramic product durability and chemical resistance, while the country's national standards body administers TCVN certification for factory quality systems. These frameworks shape demand by disqualifying substandard imports and compelling domestic upgrades to ISO-grade production lines. Stakeholders must monitor how forthcoming amendments to building energy codes affect specification requirements for thermal-efficient tile systems in green-certified developments.
Market Dynamics
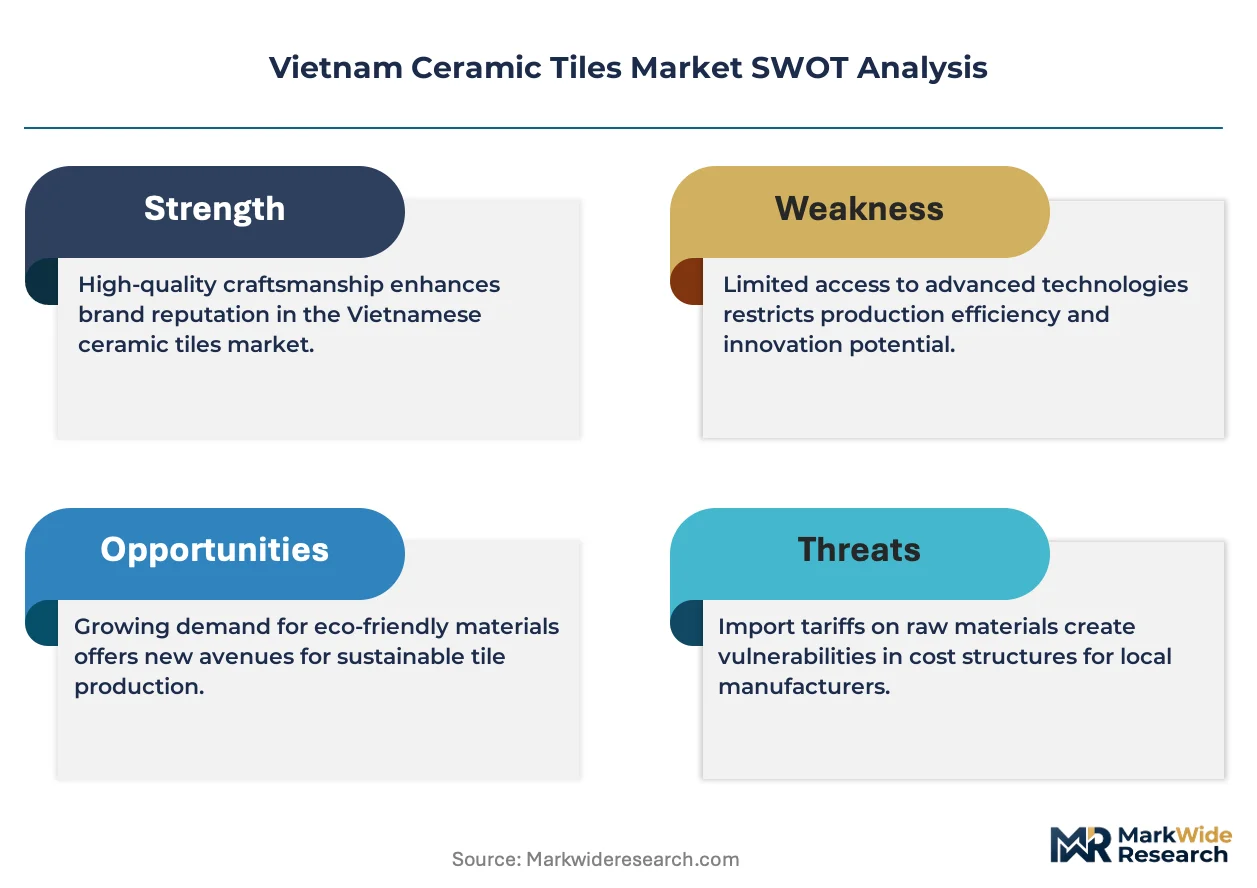
Energy cost volatility is compressing margin differentials between automated and manual kiln operations, forcing a wave of capital retooling across Vietnamese manufacturing clusters. This structural pressure is reshaping competitive viability thresholds faster than product innovation cycles.
Growth Catalysts
- QCVN Durability Mandates:Vietnam's Ministry of Construction tightened technical standards under Circular 09/2023, disqualifying substandard imports and compelling domestic upgrades to ISO-grade production lines.
- Red River Delta Urbanization:Accelerated residential construction in Hanoi and surrounding provinces concentrates demand for glazed wall tiles in high-rise apartment complexes.
- Large-Format Porcelain Technology:Advanced dry-pressing equipment enables 600x1200mm and 750x1500mm slab production, opening specification opportunities in hospitality flooring.
Market Restraints
- Natural Gas Price Volatility:Kiln operators face margin erosion as spot LNG contracts fluctuate, disadvantaging plants without captive supply agreements.
- Import Concentration in Pigments:Ceramic colorants and frits remain concentrated among Spanish and Italian suppliers, exposing Vietnamese finishers to euro-denominated input cost swings.
- Water Absorption Floor for Exterior Cladding:Porcelain tiles below 0.5% absorption command premium positioning, but technical barriers limit domestic supply of frost-resistant grades for northern mountainous climates.
Strategic Opportunities
- Southeast Region Logistics Hubs:Binh Duong and Dong Nai provinces offer underexploited distribution infrastructure for direct-to-developer bulk supply to Ho Chi Minh City construction corridors.
- Green Building Certification Tailwinds:Amendments to Vietnam's building energy codes create specification pull for thermally efficient tile systems in LEED and LOTUS-certified commercial developments.
- Digital Specification Platforms:Online sales channels gain traction among retail renovators seeking standardized formats, compressing traditional distributor markups.
Industry Challenges
- ISO-Grade Quality System Implementation:TCVN certification timelines stretch 12-18 months for mid-cap plants, delaying access to government project tenders.
- Continuous Roller Kiln Retrofit Costs:Conversion from intermittent to tunnel firing demands capital outlays that strain balance sheets without project finance guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Ceramic Tiles Market |
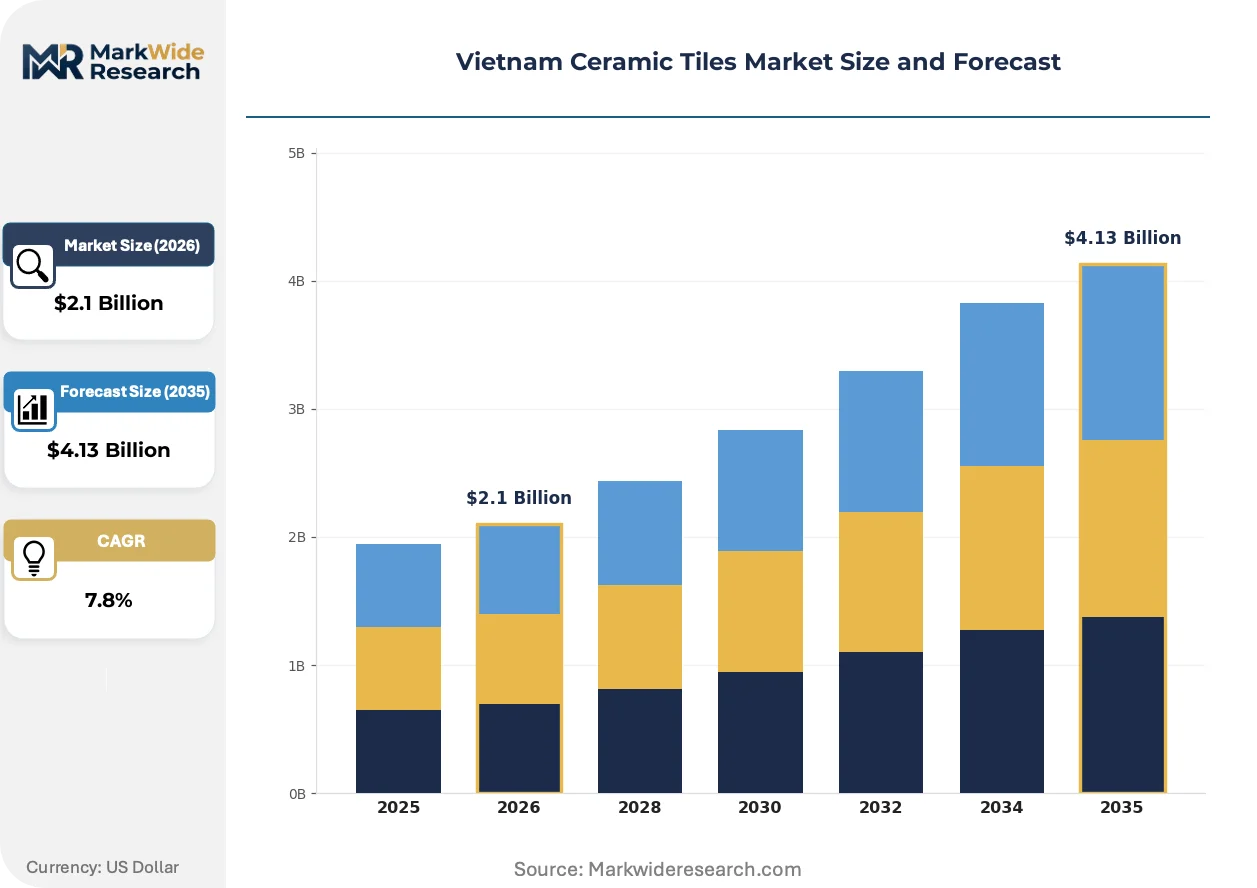
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Tiles, Unglazed Tiles, Porcelain Tiles, Stoneware Tiles End User: Residential, Commercial, Industrial, Institutional Application: Flooring, Wall Cladding, Countertops, Backsplashes Distribution Channel: Direct Sales, Retail Stores, Online Sales, Distributors |
| Companies Covered | Taicera Enterprise Company, Bạch Mã (White Horse Ceramics), Viglacera Corporation, Hoàng Gia Royal Group, CMC JSC (Catalan Tiles), Prime Group, Thạch Bàn Group, Mikado Ceramic, Đồng Tâm Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Ceramic Tiles Market Strategic Shifts
Digital inkjet decoration is decomposing traditional screen-printing cost structures while enabling batch-size flexibility. This technology shift intersects with regulatory pressure on emissions and evolving procurement behaviors among project developers.
Dry-pressed porcelain body formulation is decomposing the historical premium attached to imported Italian slabs. Domestic manufacturers in Binh Duong are adopting high-tonnage presses and advanced atomized clay preparation to achieve sub-0.5% absorption rates. Hospitality developers in Danang and Phu Quoc now specify Vietnamese large-format porcelain for lobby and corridor flooring, compressing the import premium to 15-20% from historical 40-50% spreads.
Vietnam's Ministry of Construction is enforcing QCVN 16:2023 amendments on chemical resistance and slip coefficient testing, tightening market access for ungraded imports. Factory quality systems must now document batch traceability and third-party laboratory verification. Northern provincial distributors report inventory write-downs on non-compliant stock, accelerating consolidation toward TCVN-certified domestic suppliers.
Project developers in Ho Chi Minh City are consolidating procurement through direct mill relationships, bypassing traditional tile market intermediaries. Volume buyers now negotiate annual framework agreements with fixed-price escalators tied to gas indexation. This channel compression is most visible in the Southeast region, where residential tower contractors source 60-70% of ceramic surfacing through direct developer-mill contracts rather than wholesale distributors.
Vietnam Ceramic Tiles Market Segmentation
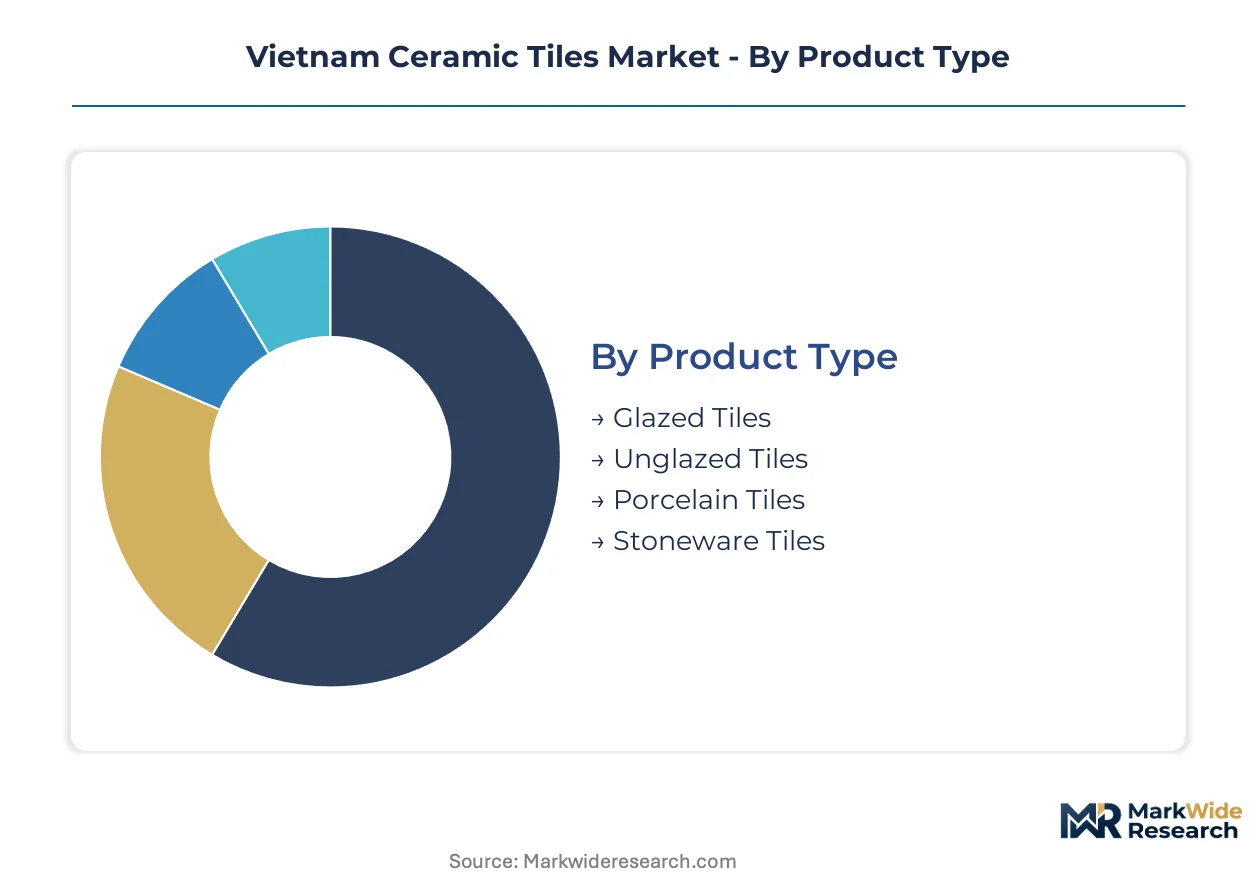
Vietnam's ceramic tiles market fragments across four structural dimensions that each carry distinct margin profiles and regulatory exposure. Product type differentiation determines QCVN compliance tiers, while distribution channel selection shapes working capital intensity and price realization for manufacturers.
Product Type:
QCVN 16:2023 amendments enforce divergent testing protocols across absorption grades, with sub-0.5% porcelain facing stricter chemical resistance verification than glazed alternatives.
- Glazed Tiles:Glass-coated clay bodies fired at 1,000-1,150°C deliver decorative surface variety for interior wall applications. Hanoi high-rise residential towers specify glazed formats for bathroom and kitchen vertical surfaces, though circular economy mandates from the Ministry of Construction are pressuring lead-free glaze reformulation timelines.
- Porcelain Tiles:High-density sintering above 1,200°C achieves sub-0.5% water absorption suitable for commercial flooring and exterior cladding. Danang hospitality projects and Ho Chi Minh City retail developments drive specification pull for large-format 600x1200mm slabs, with frost-resistant grades commanding premium positioning in northern mountainous provinces.
- Unglazed Tiles:Natural clay surfaces without vitreous coating rely on body color and texture for aesthetic differentiation, serving utility-focused applications in industrial settings and exterior paving where slip resistance takes priority over design flexibility.
- Stoneware Tiles:Intermediate density bodies between porcelain and earthenware offer cost-positioned alternatives for residential renovation segments in Binh Duong and Dong Nai provinces where budget constraints dominate procurement decisions.
Porcelain handles the majority of throughput; glazed wall formats are climbing the fastest on share as apartment construction concentrates in urban corridors.
End User:
Customer type segmentation maps directly to contract structure complexity, with institutional buyers demanding TCVN-certified batch traceability that mid-cap residential developers often waive.
- Residential:Apartment construction in Ho Chi Minh City and Hanoi absorbs volume through developer-direct procurement, with individual renovators in secondary cities like Can Tho and Hai Phong driving retail channel activity for standardized formats.
- Commercial:Office towers, retail malls, and hospitality projects in Danang and Phu Quoc specify large-format porcelain for high-traffic flooring, with LEED and LOTUS certification requirements filtering supplier pools toward ISO-grade manufacturers.
- Industrial:Manufacturing facilities and logistics warehouses prioritize unglazed or heavy-duty porcelain for abrasion resistance, sourcing through annual framework agreements with fixed-price escalators tied to natural gas indices.
- Institutional:Government buildings, schools, and hospitals under Ministry of Construction oversight mandate full QCVN compliance and third-party laboratory verification, extending procurement cycles but securing multi-year supply relationships.
Residential commands absolute volume; commercial applications are expanding most quickly as hospitality investment accelerates along Vietnam's central coast.
Application:
Functional use case determines technical specification intensity, with flooring applications facing the most stringent slip coefficient and load-bearing requirements under national standards.
- Flooring:Horizontal surfacing for residential, commercial, and industrial spaces demands abrasion resistance and slip coefficient compliance, with high-traffic hospitality lobbies in Ho Chi Minh City specifying rectified porcelain edges for minimal grout lines.
- Wall Cladding:Vertical applications in bathrooms, kitchens, and building facades emphasize water absorption limits and aesthetic variety, with digital inkjet decoration enabling batch flexibility for boutique hotel projects in Hoi An and Hue.
- Countertops:Work surface applications require stain resistance and structural integrity under point loads, representing a niche but high-margin segment where imported quartz competes with domestic thick-body porcelain.
- Backsplashes:Decorative vertical strips in residential kitchens prioritize design coordination with cabinetry, typically sourcing through retail channels in smaller format tiles with lower technical barriers to entry.
Flooring absorbs the dominant share of tonnage; wall cladding in hospitality projects is gaining share fastest as hotel development intensifies.
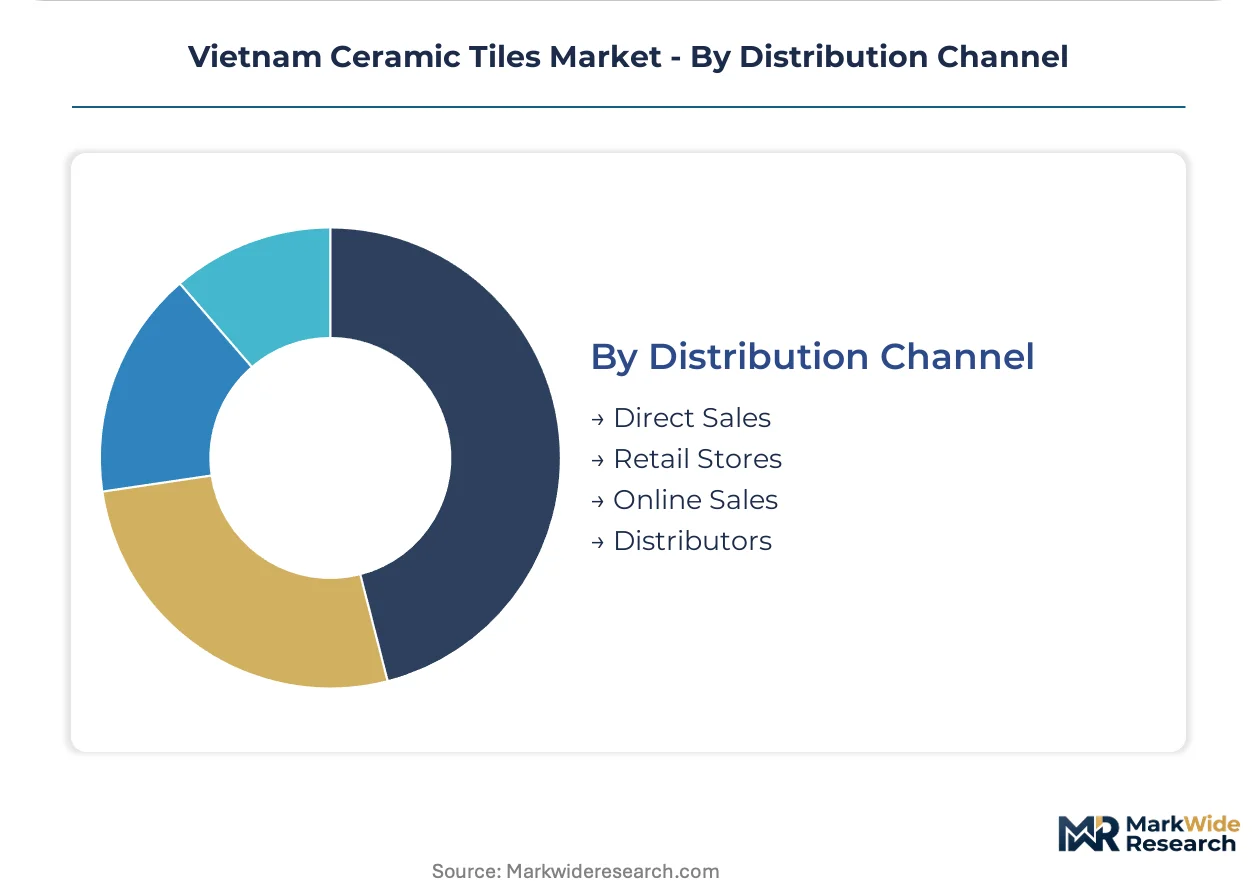
Distribution Channel:
Channel selection determines margin capture and customer relationship depth, with direct sales compressing traditional distributor economics while digital platforms reshape retail renovation procurement.
- Direct Sales:Mill-to-developer relationships bypass wholesale markups, with Southeast region residential tower contractors sourcing 60-70% of ceramic surfacing through annual framework agreements indexed to input costs.
- Retail Stores:Physical showrooms in Hanoi and Ho Chi Minh City tile markets serve individual renovators and small contractors, carrying inventory risk but enabling tactile specification decisions for design-sensitive residential clients.
- Online Sales:Digital platforms gain traction among retail renovators seeking standardized formats, compressing traditional distributor economics through transparent pricing and logistics integration.
- Distributors:Regional wholesalers maintain inventory positions in northern provincial channels, though consolidation pressure from direct procurement and e-commerce is eroding their historical role in value chain intermediation.
Direct sales channel the largest value flow; online platforms are expanding most quickly as urban renovators adopt digital procurement habits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price realization in Vietnam's Red River Delta outperforms Mekong Delta benchmarks by 12-18% for equivalent porcelain grades, reflecting construction density premiums in Hanoi versus dispersed demand in southern provincial markets.
Red River Delta
Hanoi's high-rise residential towers and northern industrial zones absorb glazed wall tiles and heavy-duty porcelain for manufacturing facilities. Vietnam's Ministry of Construction enforces QCVN 16:2023 durability standards that disqualify substandard imports, tightening specification pools. Bac Ninh and Hai Duong provinces concentrate automated kiln capacity serving developer-direct procurement channels.
Southeast Region
Ho Chi Minh City construction corridors and Binh Duong industrial parks drive demand for large-format porcelain in hospitality and retail flooring. The Ministry of Construction's Circular 09/2023 mandates ISO-grade production line upgrades for government project eligibility. Dong Nai province hosts underexploited logistics infrastructure for bulk mill-to-developer supply contracts.
North Central Coast
Danang's hospitality investment wave and Phu Quoc resort developments specify frost-resistant porcelain for exterior cladding and lobby surfacing. Building energy code amendments create specification pull for thermally efficient tile systems in LOTUS-certified commercial projects. Thua Thien-Hue province channels artisanal heritage tile production toward boutique hotel renovation segments.
South Central Coast
Khanh Hoa and Binh Thuan provinces absorb utility-focused unglazed formats for industrial warehousing and logistics facilities. Provincial construction departments enforce TCVN certification timelines that stretch 12-18 months for mid-cap plant upgrades. Nha Trang's condominium construction concentrates demand for standardized glazed wall formats through retail distributor networks.
Mekong Delta
Can Tho and secondary cities drive retail channel activity for residential renovation segments seeking cost-positioned stoneware alternatives. The national standards body administers factory quality system audits that delay market access for uncertified producers. An Giang and Long An provinces supply raw clay feedstock to integrated manufacturers with captive material sourcing.
Vietnam Ceramic Tiles Market Competitive Environment
Concentration sits with integrated conglomerates possessing captive gas supply and backward clay sourcing, while mid-cap specialists compete on format specialization and provincial channel depth. State-linked holding companies and private family-owned groups divide the manufacturing base between scale-driven porcelain output and heritage brand positioning in northern markets. Two strategic archetypes dominate: vertically integrated energy-secure operators and technology-focused large-format specialists. Competitive moves center on continuous roller kiln retrofits for emission compliance and direct-to-developer procurement relationships that bypass wholesale markups.
Among Vietnamese-based manufacturers, Viglacera Corporation, Prime Group, and Bạch Mã occupy distinct positioning tiers. Viglacera exemplifies the integrated conglomerate archetype through state-linked holding structures and captive infrastructure. Prime Group represents technology-forward specialization in advanced dry-pressing formats. Bạch Mã anchors heritage brand recognition in northern provincial distribution channels. These three entities collectively illustrate how competitive advantage fragments across energy security, technical capability, and channel legacy rather than consolidating around uniform scale metrics.
| Leading Market Players |
|---|
| Taicera Enterprise Company |
| Bạch Mã (White Horse Ceramics) |
| Viglacera Corporation |
| Hoàng Gia Royal Group |
| CMC JSC (Catalan Tiles) |
| Prime Group |
| Thạch Bàn Group |
| Mikado Ceramic |
| Đồng Tâm Group |
| Others |
Value Chain & Pricing Dynamics
TCVN certification timelines gate both factory qualification and price tiering simultaneously, compressing uncertified producers into commodity stoneware segments while ISO-grade operators capture porcelain premiums through developer-direct contracts.
Pricing Analysis
Configured-to-order spreads separate large-format porcelain slabs from standardized glazed wall formats by 25-35% in Ho Chi Minh City procurement. Contract-based long-term offtake dominates developer-direct channels, with price differentiation anchored in certification grade and captive gas supply. Cost compression in mid-tier stoneware intensifies as Binh Duong plants absorb TCVN upgrade delays. Individual renovators in secondary cities exhibit highest price sensitivity, while hospitality developers in Danang prioritize frost-resistant performance over unit cost.
Supply Chain Analysis
Malacca Strait transit underwrites frit and pigment supply from Spanish and Italian specialty chemical producers, exposing Vietnamese finishers to euro-denominated input volatility. Raw material dependencies center on atomized clay from Dong Nai deposits, natural gas from Nam Con Son basin contracts, and imported ceramic colorants. Single-source vulnerability concentrates in European glaze additive suppliers. Distribution runs through direct mill-to-developer frameworks in the Southeast region, bypassing traditional wholesale markups for 60-70% of residential tower volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation and surface treatment services expand faster than tile hardware as hospitality developers bundle specification with certified applicator networks, creating recurring revenue layers beyond unit sales.
For Market Incumbents: Secure captive clay deposits in Dong Nai and Long An provinces to buffer against feedstock cost swings from integrated competitors. Accelerate continuous roller kiln retrofits before QCVN emission amendments tighten, as mid-cap plants without project finance face 12-18 month certification delays that freeze government tender access. For New Entrants and Emerging Players: Anchor in North Central Coast hospitality corridors where Danang and Phu Quoc resort developments specify frost-resistant porcelain with limited domestic supply. Target boutique hotel renovation segments in Thua Thien-Hue through artisanal heritage tile positioning, leveraging digital inkjet flexibility for batch-size customization that mass producers cannot match. For Investors and Strategic Acquirers: Circular 09/2023 implementation reshapes the acquisition landscape by disqualifying substandard import competitors and consolidating share toward TCVN-certified domestic assets. Long-term viability favors automated kiln operators with backward integration into gas supply and clay sourcing. Monitor Ministry of Construction amendments to building energy codes as the signal for thermal-efficient tile system demand inflection in green-certified commercial developments.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Roller Kiln Retrofit | Enables QCVN 16:2023 emission compliance and access to government project tenders. |
| Captive Clay Deposit Acquisition | Secures Dong Nai and Long An feedstock supply against volatile raw material spot markets. |
| Large-Format Porcelain Capacity Expansion | Captures Danang hospitality specification pull for 600x1200mm and 750x1500mm slabs. |
| Direct-to-Developer Procurement Framework | Bypasses wholesale markups in Ho Chi Minh City construction corridors through annual volume agreements. |
| Digital Inkjet Decoration Platform | Decomposes screen-printing cost structures for boutique hotel batch flexibility in Hoi An and Hue. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, Ministry of Construction circulars, and national standards body certification registries. Primary interviews engaged plant operations directors, procurement leads at residential tower developers, distribution channel partners in Hanoi tile markets, and technical R&D heads at dry-pressing equipment suppliers. Bottom-up volume triangulation against top-down construction spend allocation validates segment-level outputs.
Segmentation dimensions modeled span product type, end-user category, application function, and distribution channel across the projection horizon. CAGRs derive from trend extrapolation of urbanization rates, kiln capacity utilization, and regulatory compliance timelines. Forecast inputs incorporate natural gas price indexation patterns and hospitality investment pipelines along Vietnam's central coast.
Underlying assumptions cover sustained Red River Delta and Southeast region construction activity, with deviation risk concentrated in LNG contract renegotiations and QCVN amendment timing. Practitioners should keep alternative scenarios live as Ministry of Construction energy code revisions and circular economy mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
Silos Market
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
Corrugated Steel Panels Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
North America Non-Residential Polished Concrete Market
Building & Construction Materials
Metal Roofing Market
Building & Construction Materials
Europe Oriented Strand Board Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Autoclave Aerated Concrete Market
Building & Construction Materials
Concrete Formwork System Market
Building & Construction Materials
ASEAN Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Fire-Retardant Treated Wood Market