
 Suspended Ceiling Systems Market | 2026-2036
Suspended Ceiling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Suspended Ceiling Systems Market Analysis
REACH compliance is consolidating the cost-of-entry calculus for European suspended ceiling imports, forcing reformulation of mineral fiber binders and surface coatings. Armstrong World Industries leverages its captive mineral wool supply chain to sustain margin stability under tightened chemical disclosure rules. Saint-Gobain anchors its position through gypsum board verticality, while Rockfon competes on acoustic performance certification density across Nordic and Central European specification channels.
Suspended ceiling systems comprise modular panels or tiles hung from structural soffits via metal grid frameworks, typically specified with noise reduction coefficients between 0.50 and 0.95 and fire resistance ratings up to two hours for commercial safety compliance. These assemblies conceal mechanical infrastructure while delivering acoustic attenuation, thermal regulation, and lighting integration in occupied spaces. Acoustic panels lead product type revenue due to mandatory sound control in open-plan offices and healthcare corridors, whereas metal tiles capture premium specification in transportation hubs where durability and cleanability dominate. Grid systems remain the dominant installation category, though clip-in methods gain share in retrofit contexts where speed and labor minimization determine award decisions.
EPA emissions standards for formaldehyde-based resins and OSHA workplace noise exposure limits directly shape mineral fiber product development and end-user specification behavior in the United States. ECHA substance restrictions under REACH and the EU Green Deal building renovation targets create parallel compliance obligations across European member states, with CE marking and CPR performance declarations now baseline requirements for market access. Stakeholders must monitor evolving embodied carbon accounting rules and circular economy material passports, as these frameworks will increasingly determine which ceiling system suppliers retain specification priority in public and institutional procurement.
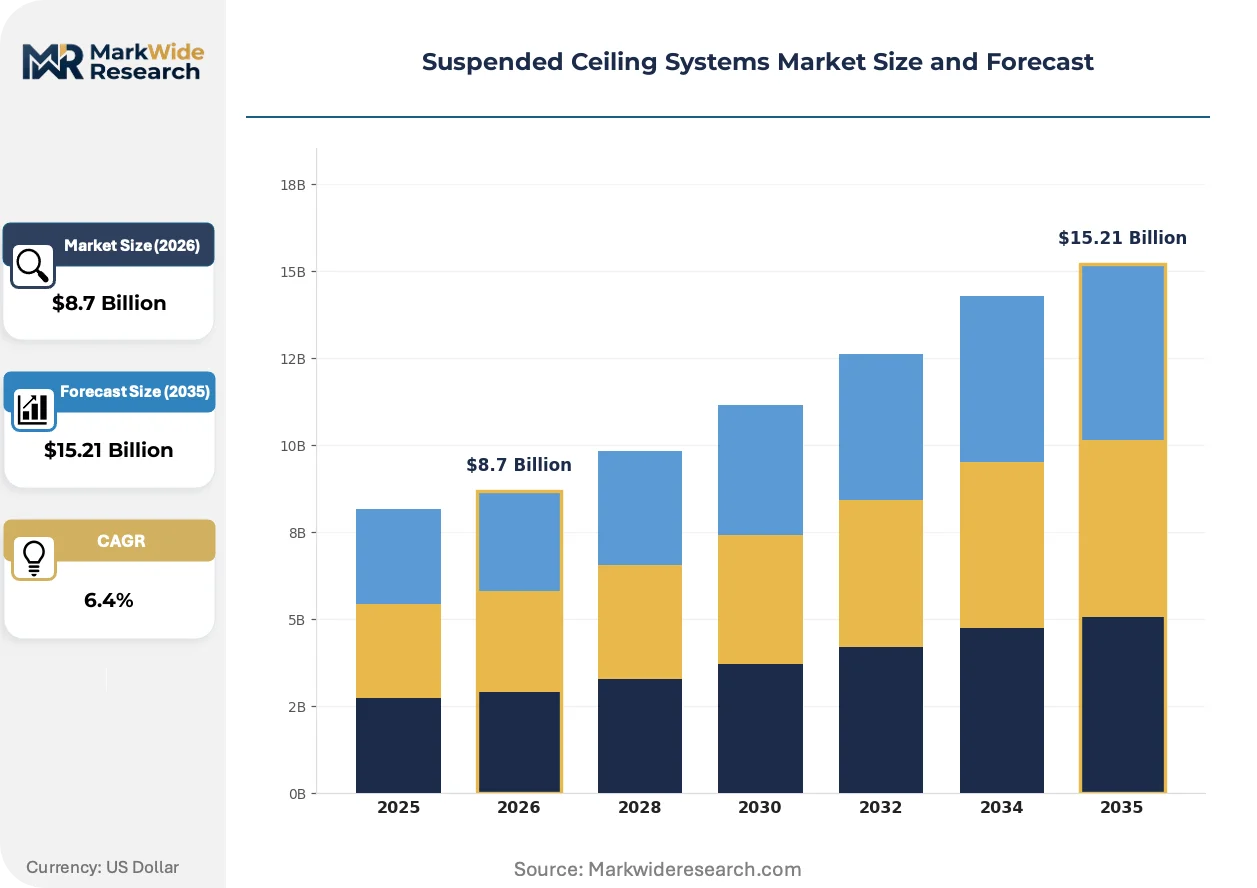
Market Dynamics
Acoustic performance mandates in healthcare and open-plan commercial construction are compressing specification cycles, forcing mineral fiber and metal tile suppliers to pre-certify assemblies against evolving fire resistance and noise reduction standards before project bidding begins.
Growth Catalysts
- REACH substance restrictions:ECHA-driven reformulation of mineral fiber binders and surface coatings is accelerating R&D investment in low-emission alternatives, expanding addressable specification pools for compliant suppliers.
- Healthcare construction:Infection control protocols in hospital corridors and patient zones mandate cleanable, acoustic-rated ceiling assemblies, driving specification volume for mineral fiber panels with enhanced surface durability.
- Retrofit acceleration:Clip-in installation methods are capturing share in aging office stock renovation across Germany and the United States, where speed and labor minimization determine contractor award decisions.
Market Restraints
- Mineral wool supply concentration:Captive vertical integration among top-tier suppliers limits mid-scale manufacturer access to cost-competitive raw material inputs, compressing margin flexibility for non-integrated competitors.
- Formaldehyde resin cost volatility:EPA emissions standards for formaldehyde-based binders are increasing compliance overhead for mineral fiber production, particularly for imports targeting United States specification channels.
- Metal tile substitution ceiling:Premium metal tile specification faces price resistance in mid-market commercial projects where painted gypsum board delivers sufficient fire rating at lower installed cost.
Strategic Opportunities
- Embodied carbon accounting:EU Green Deal building renovation targets and emerging material passport requirements create first-mover advantage for suppliers with verified lifecycle data and circular economy take-back programs.
- Transportation hub specification:Durability and cleanability requirements in airport terminals and rail stations favor metal tile and specialty acoustic metal systems, a segment with limited current supplier penetration.
- OSHA workplace noise rules:Stricter occupational exposure limits in United States manufacturing and logistics facilities are expanding retrofit demand for high-NRC ceiling assemblies beyond traditional office and healthcare verticals.
Industry Challenges
- CE marking timeline compression:CPR performance declaration requirements and evolving harmonized European standards are extending product certification cycles, delaying market entry for reformulated or novel assembly designs.
- Grid-clip integration complexity:Specification of mixed installation methods in retrofit contexts demands installer retraining and inventory complexity, creating execution risk for contractors managing multiple project types simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suspended Ceiling Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic Panels, Metal Tiles, Gypsum Boards, Wood Grids Installation Type: Grid Systems, Direct Attach, Hook-On, Clip-In End User: Commercial Buildings, Residential Spaces, Industrial Facilities, Educational Institutions Material: Mineral Fiber, PVC, Metal, Fiberglass |
| Companies Covered | Armstrong World Industries, Saint-Gobain, Knauf, USG Corporation, Rockfon, SAS International, Hunter Douglas, OWA Ceiling Systems, CertainTeed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suspended Ceiling Systems Market Emerging Trajectories
Digital specification tools and predictive acoustic modeling are compressing design-to-procurement timelines, while regulatory pressure on embodied carbon is forcing material transparency upstream into raw fiber and coating supply chains.
Microperforated metal panels with integrated acoustic backing are rewriting specification norms in transportation and healthcare verticals. Airport terminal developers in Germany and the United States specify these systems for simultaneous durability, cleanability, and noise control. The technology is compressing the traditional trade-off between metal tile longevity and mineral fiber acoustic performance.
EU Green Deal building renovation targets are mandating material passports and circular economy documentation for public procurement eligibility. CE marking and CPR performance declarations now require embodied carbon disclosure, forcing mineral fiber suppliers to reconfigure binder chemistries and document supply chain provenance. Nordic and Central European specification channels show earliest compliance adoption.
Integrated design-build procurement is consolidating ceiling specification authority into general contractor and developer hands, displacing traditional architect-led material selection. Large-scale office and healthcare projects in Germany and China increasingly bundle acoustic ceiling assemblies into broader interior fit-out contracts. This concentration is visible most acutely in United States design-build delivery growth.
Suspended Ceiling Systems Market Segmentation
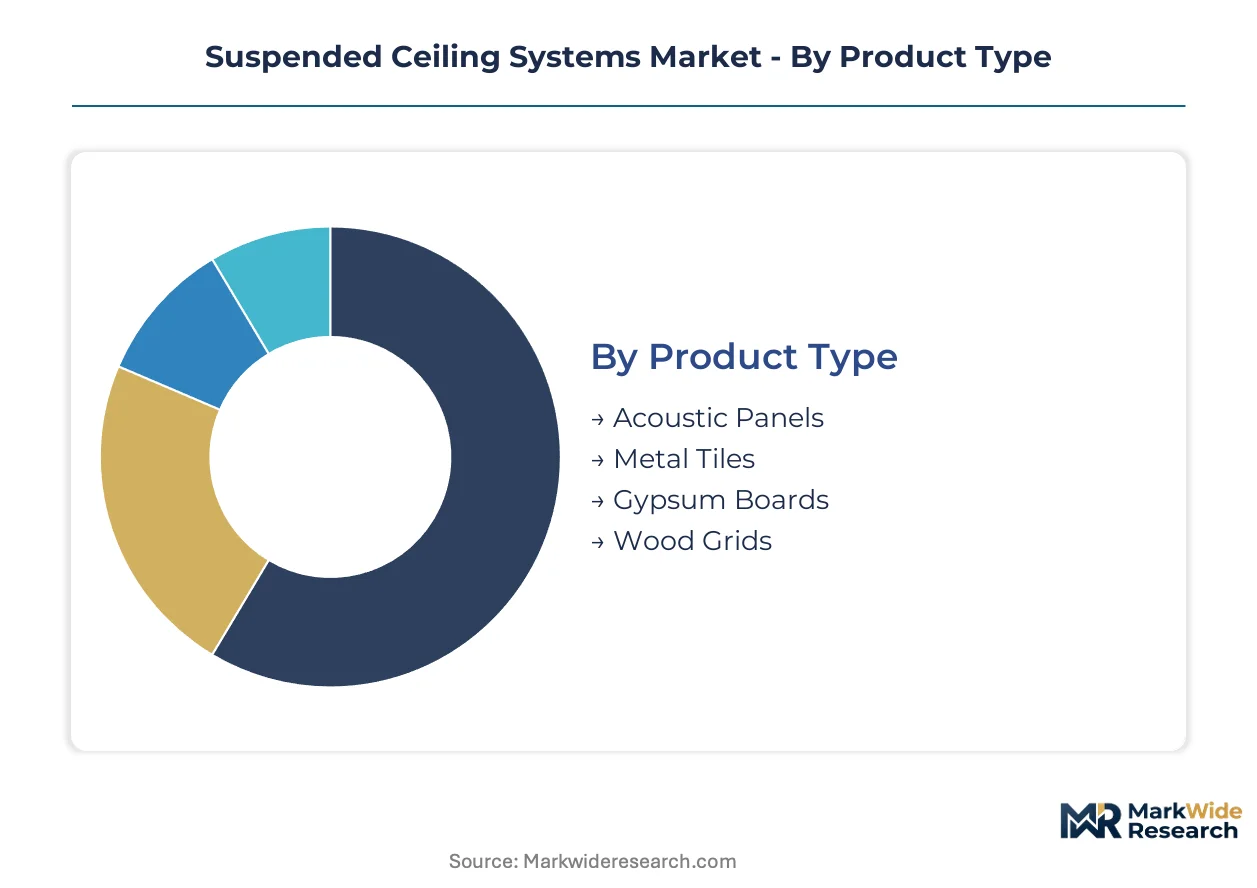
Segmentation in suspended ceiling systems reveals how specification authority fragments across installation constraints, acoustic performance thresholds, and material compliance obligations. Distinct procurement patterns emerge when contractors, developers, and facilities managers prioritize speed, durability, or regulatory certification.
Product Type:
Technical specification and acoustic performance ratings determine product selection across commercial, healthcare, and transportation verticals.
- Acoustic Panels:Mineral fiber or fiberglass composite panels engineered with noise reduction coefficients between 0.70 and 0.95. Hospital corridor and open-plan office specifications in Germany and the United States drive volume, with infection control protocols mandating cleanable surface treatments.
- Metal Tiles:Aluminum or steel panels with powder-coated or anodized finishes, specified for durability in airport terminals and rail stations. Microperforated variants with acoustic backing are gaining specification share where longevity and cleanability outweigh first-cost considerations.
- Gypsum Boards:Calcium sulfate core panels with paper or fiberglass facings, common in fire-rated assemblies.
- Wood Grids:Veneered or solid wood linear systems specified for aesthetic priority in hospitality and corporate reception spaces.
Acoustic Panels lead on scale; Metal Tiles lead on momentum.
Installation Type:
Labor economics and project timeline compression are reshaping contractor preference across new construction and retrofit contexts.
- Grid Systems:Suspended T-bar or concealed metal frameworks supporting lay-in tiles, dominant in commercial new-build specifications. United States office construction and German healthcare projects standardize on 15/16-inch and 9/16-inch face configurations for mechanical access and lighting integration.
- Clip-In:Spring-loaded tile retention enabling rapid installation without full grid exposure. Aging office stock renovation across Germany and the United States favors this method where speed and labor minimization determine award decisions.
- Direct Attach:Adhesive or mechanical fastening to structural soffits, common in low-clearance retrofits.
- Hook-On:Concealed carrier systems with visible panel edges, specified for premium architectural finishes.
Grid Systems retain volume dominance; Clip-In methods are climbing the fastest.
End User:
Procurement concentration varies sharply between institutional buyers with extended specification cycles and commercial developers optimizing installed cost.
- Commercial Buildings:Office, retail, and hospitality fit-outs specifying acoustic-rated assemblies for tenant comfort and lease competitiveness. Stricter energy codes and indoor air quality mandates in North America and Europe are expanding specification of low-emission mineral fiber systems.
- Healthcare Facilities:Hospitals and clinics requiring cleanable, acoustic-rated ceiling assemblies with enhanced surface durability. Infection control protocols in patient zones and corridors mandate mineral fiber panels with scrubbable finishes.
- Educational Institutions:Schools and universities balancing acoustic performance against constrained capital budgets.
- Residential Spaces:Multi-family and senior living applications with lower acoustic performance thresholds.
- Industrial Facilities:Manufacturing and logistics spaces requiring corrosion resistance and high-humidity tolerance.
Commercial Buildings anchor specification volume; Healthcare Facilities show the steepest expansion trajectory.
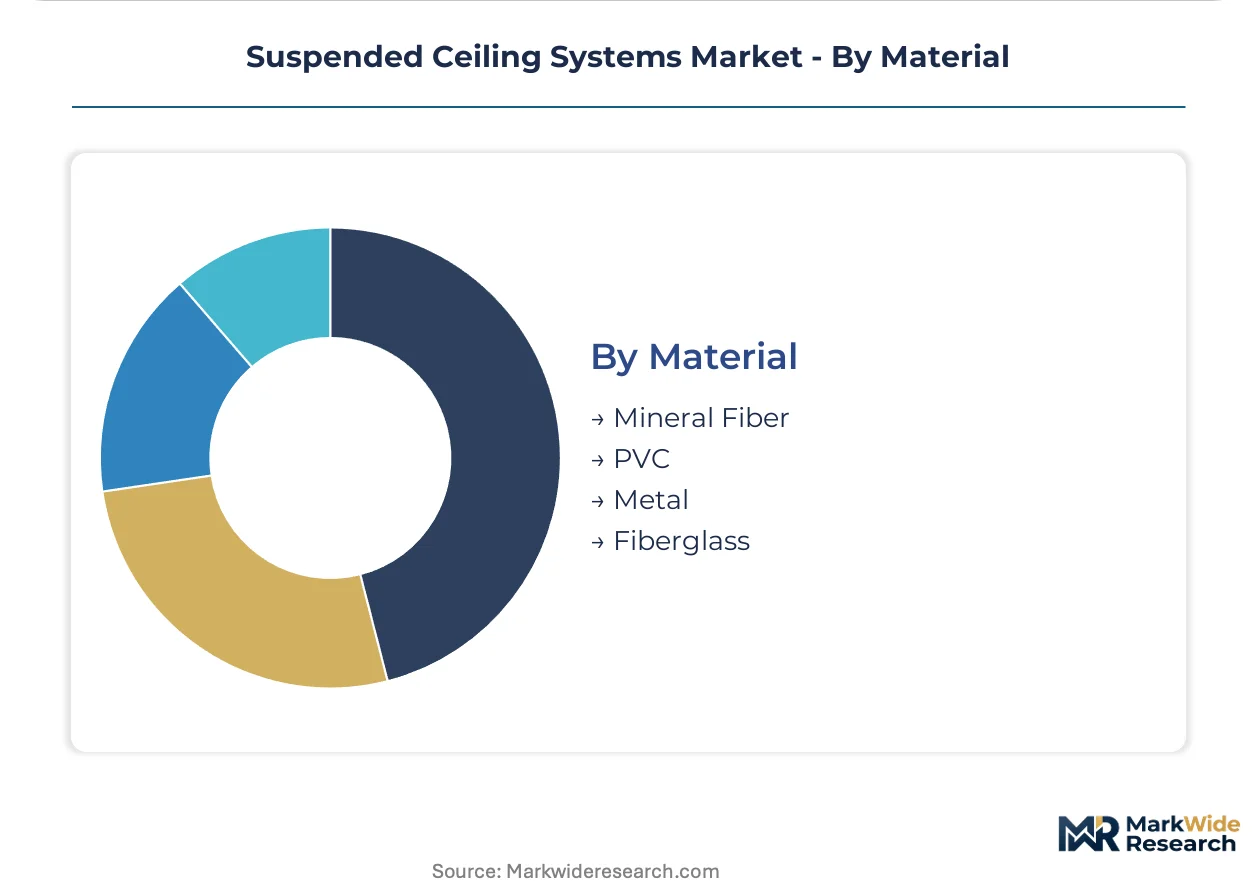
Material:
Supply chain provenance and embodied carbon disclosure are emerging as procurement filters alongside traditional performance metrics.
- Mineral Fiber:Slag wool or rock wool binders with formaldehyde-based resins, dominant in acoustic panel production. REACH compliance and EPA emissions standards are forcing reformulation of binders and surface coatings, consolidating cost-of-entry for European and United States imports.
- Metal:Aluminum and steel substrates for tile and grid production, with recycled content claims gaining specification weight.
- PVC:Vinyl-faced tiles and grids for moisture-resistant applications.
- Fiberglass:High-NRC panels for critical acoustic environments.
Mineral Fiber dominates current specification; Metal substrates are gaining share fastest on circular economy credentials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled acoustic engineering talent clusters in Germany, the United States, and China anchor specification authority for high-performance ceiling assemblies. These concentrations drive divergent procurement patterns shaped by local energy codes, chemical disclosure mandates, and construction delivery models.
Germany
Healthcare construction in Berlin and Hamburg drives specification of cleanable mineral fiber panels with enhanced surface durability. ECHA substance restrictions under REACH force reformulation of formaldehyde-based binders, consolidating cost-of-entry for imported systems. The Rhine-Ruhr industrial corridor hosts specification engineering firms that pre-certify assemblies against evolving harmonized European standards.
United States
Retrofit acceleration in aging office stock across Chicago and New York favors clip-in installation methods where labor minimization determines contractor awards. EPA emissions standards for formaldehyde-based resins increase compliance overhead for mineral fiber production. Dallas-Fort Worth and Atlanta construction markets concentrate design-build procurement authority into general contractor hands.
China
Large-scale commercial and transportation hub construction in Shanghai and Beijing drives volume specification of metal tile systems. GB standards for fire resistance and indoor air quality reshape material selection in public procurement. The Yangtze River Delta manufacturing base supplies grid frameworks and acoustic backing materials to regional project pipelines.
United Kingdom
Office renovation in London and Manchester prioritizes low-emission mineral fiber systems under tightening energy codes. CE marking and CPR performance declarations now require embodied carbon disclosure for public sector eligibility. The Midlands manufacturing belt hosts metal tile fabrication capacity serving healthcare and education verticals.
India
Commercial building expansion in Mumbai and Bangalore creates specification demand for cost-competitive acoustic assemblies. BIS standards for fire-rated construction materials gain enforcement weight in metro development authority procurement. The Delhi-NCR corridor concentrates distributor networks for imported grid systems and mineral fiber panels.
Suspended Ceiling Systems Market Vendor Landscape
The competitive structure tilts toward vertically integrated mineral fiber specialists with captive raw material supply. Three tiers have crystallized: global building materials conglomerates with gypsum board verticality, Nordic acoustic specialists with dense certification portfolios, and regional metal fabricators serving transportation hub durability requirements. Capacity expansion and circular economy take-back programs represent the dominant competitive moves as embodied carbon accounting gains procurement weight.
Within the conglomerate tier, Armstrong World Industries and Saint-Gobain exemplify divergent strategic anchors: the former leverages captive mineral wool supply chains to sustain margin stability under tightened chemical disclosure rules, while the latter anchors position through gypsum board verticality across European specification channels. Rockfon occupies a specialist position, competing on acoustic performance certification density in Nordic and Central European markets where healthcare and education procurement demands extensive pre-certification documentation.
| Leading Market Players |
|---|
| Armstrong World Industries |
| Saint-Gobain |
| Knauf |
| USG Corporation |
| Rockfon |
| SAS International |
| Hunter Douglas |
| OWA Ceiling Systems |
| CertainTeed Corporation |
| Others |
Supply Flow & Price Mechanics
Clip-in installation method procurement in German and United States office retrofits is compressing contractor margins and forcing suppliers to unbundle grid systems from panel sales, fragmenting traditional pricing structures into component-level negotiations. This demand-side shift toward speed-driven specification is reshaping how mineral fiber and metal tile suppliers configure their cost stacks and allocate manufacturing capacity.
Pricing Analysis
Bundled full-system contracts versus unbundled component sales now define the pricing architecture across commercial and healthcare verticals. Price differentiation hinges on acoustic certification density and after-sales installation support, with premium NRC-rated assemblies commanding substantial markups over baseline fire-rated alternatives. Cost compression in mid-market mineral fiber panels is intensifying because painted gypsum board substitutes erode specification share. Facilities managers in educational institutions exhibit the highest price sensitivity, while hospital procurement committees prioritize infection-control performance over first-cost considerations.
Supply Chain Analysis
Circular economy take-back programs and refurbishment flows are emerging as critical supply chain nodes as EU Green Deal material passport requirements gain enforcement weight. Manufacturing concentration centers on Germany, the United States, and China, with the Yangtze River Delta supplying grid frameworks and acoustic backing materials. Production draws from captive mineral wool supply, formaldehyde-based resin binders, and recycled aluminum substrates. Single-source vulnerability in mineral wool supply chains poses structural risk for non-integrated competitors. Distribution runs through specification engineering firms and general contractor design-build channels rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe create specification windows for United States suppliers with pre-certified low-emission alternatives, while Chinese metal tile producers exploit domestic vertical integration to undercut premium European acoustic systems.
For Market Incumbents: Deepen backward integration into mineral wool supply to defend margin stability against formaldehyde resin cost volatility and captive supply concentration among top-tier competitors. Invest in CE marking pre-certification capacity to compress timeline-to-market for reformulated binder chemistries under evolving ECHA substance restrictions. Channel control through specification engineering firm partnerships represents the critical defensive lever against design-build procurement consolidation. For New Entrants and Emerging Players: Capture transportation hub specification in airport terminals and rail stations where microperforated metal panels with acoustic backing face limited incumbent penetration and durability requirements favor new technology adoption. Target Nordic and Central European healthcare corridors where acoustic performance certification density determines award decisions and specialist positioning gaps exist. A go-to-market angle anchored in embodied carbon disclosure and material passport compliance offers procurement differentiation in public sector eligibility. For Investors and Strategic Acquirers: Asymmetric upside sits with Nordic acoustic specialists possessing dense certification portfolios and circular economy take-back infrastructure. Long-term viability over the next decade rests on regulatory compliance capability rather than scale economics alone. Acquisition targets should demonstrate verified lifecycle data and pre-positioned low-emission product lines. The signal to watch is harmonized European standard revision timelines that could accelerate consolidation among suppliers with delayed certification cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Circular Economy Take-Back Program | Material passport compliance secures public procurement eligibility under EU Green Deal mandates. |
| Backward Integration into Mineral Wool | Captive raw material supply insulates margin stability from formaldehyde resin cost volatility. |
| Microperforated Metal Panel Launch | Acoustic-backed durability systems penetrate transportation hub specification with limited incumbent presence. |
| CE Marking Pre-Certification Investment | Compressed timeline-to-market accelerates specification capture under evolving harmonized European standards. |
| Design-Build Channel Partnership | General contractor authority consolidation demands direct procurement relationships displacing architect-led selection. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with specification engineers, facilities managers, general contractor procurement leads, and acoustic product R&D directors with secondary validation from customs trade data, SEC filings of building materials conglomerates, ECHA substance restriction databases, and hospital procurement contract disclosures. Bottom-up project pipeline aggregation and top-down sectoral expenditure analysis provided triangulation checks across volume and value estimates.
Historical reference periods anchored the forecast window to pre-pandemic construction cycles and post-regulatory-shift adoption curves, with analytical frameworks modeling product type, installation method, end-use vertical, material substrate, and geographic regulatory cluster dimensions across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro construction expenditure forecasts, incorporating mineral fiber binder reformulation timelines, metal tile substitution elasticity parameters, and clip-in installation method penetration curves as industry-specific inputs.
Regulatory timeline slippage, construction labor availability shocks, and raw material supply concentration events are the dominant revision risks that could alter trajectory assumptions. Practitioners should monitor ECHA substance restriction enforcement intensity, REACH compliance cost pass-through rates, and design-build procurement market share shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Sandwich Panel System Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Global Steel Wire Rod Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Particleboard Market
Building & Construction Materials
Silos Market
Building & Construction Materials
Africa Vinyl Windows Market
Building & Construction Materials
Global Hydraulic Door Closer Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Bollard Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
Building Insulation Materials Market
Building & Construction Materials
Concrete Cooling Market
Building & Construction Materials
Corrugated Polycarbonate Panels Market