
 Concrete Grinder Market | 2026-2036
Concrete Grinder Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Grinder Market Analytics
After-sales maintenance contracts and remote diagnostics software is expanding as a revenue layer alongside hardware sales. Husqvarna Group leverages its global service network to sustain recurring revenue from fleet operators. Tyrolit Group anchors its position through specialized diamond tooling integrated with grinder platforms. Superabrasive (Lavina) differentiates via concentrated R&D in planetary drive systems for large-scale polishing.
A concrete grinder is a powered machine using rotating abrasive discs or diamond segments to cut, grind, or polish concrete surfaces, typically operating at speeds between 250 and 1,500 RPM depending on application. Its primary purpose is substrate preparation and finish work for flooring systems in commercial, industrial, and residential construction. Floor grinders occupy the largest installed base due to versatility across surface preparation and polishing workflows, while planetary grinders command premium positioning for high-precision commercial finishes. Electric technology leads unit shipments given indoor usability and tightening emissions protocols, though gas-powered units retain share in remote or heavy-removal exterior jobs.
OSHA enforces permissible exposure limits for respirable crystalline silica, directly mandating dust collection integration and vacuum compatibility on jobsite grinder equipment. EPA regulations on engine emissions constrain gas-powered model specifications, while ISO 19432 provides machinery safety benchmarks that manufacturers must satisfy for North American and European market access. Stakeholders must weigh electrification roadmaps against residual demand for high-torque gas and hydraulic units in infrastructure rehabilitation.
Market Dynamics
OSHA's respirable crystalline silica enforcement is compressing equipment specifications and forcing dust collection integration across all grinder classes, while electrification roadmaps clash with residual infrastructure rehabilitation demand for high-torque gas and hydraulic units.
Growth Catalysts
- Warehouse Conversion Surge:E-commerce fulfillment center buildouts in the United States are driving fleet expansion among floor installation contractors. Retrofit construction concentrates grinder deployment in logistics corridors.
- OSHA Silica Rule Tightening:Permissible exposure limit reductions mandate vacuum-compatible equipment specifications. Dust collection integration is becoming a non-negotiable procurement criterion.
- Polished Concrete Aesthetics:Commercial retail and hospitality sectors specify diamond-polished finishes over epoxy overlays. Planetary grinder demand accelerates in high-visibility architectural applications.
Market Restraints
- Diamond Segment Cost Volatility:Synthetic diamond feedstock prices fluctuate with industrial abrasive demand cycles. Tooling replacement costs constrain small contractor margins.
- Supply Concentration in Abrasives:Specialized diamond tooling production clusters in limited manufacturing geographies. Disruption risk elevates inventory carrying costs for distributors.
- Gas-Powered Regulatory Friction:EPA engine emission standards constrain specifications for exterior heavy-removal applications. Electrification gaps persist in remote infrastructure sites.
Strategic Opportunities
- Remote Diagnostics Software:Telematics-enabled fleet management creates recurring revenue streams. Predictive maintenance contracts reduce downtime for multi-unit operators.
- Planetary Drive Convergence:Integration of precision gear systems with variable speed controls enables single-machine versatility. Large-scale polishing contractors consolidate equipment types.
- Service Network Gaps:After-sales infrastructure remains underdeveloped in secondary metropolitan markets. Authorized repair depots capture sticky revenue from fleet operators.
Industry Challenges
- Silica Competency Certification:Competent person training requirements under OSHA construction standards strain smaller contracting operations. Certification timelines delay crew deployment.
- Electrification Capex Burden:Battery-powered grinder platforms require charging infrastructure investment. Fleet conversion costs compress near-term capital availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Grinder Market |
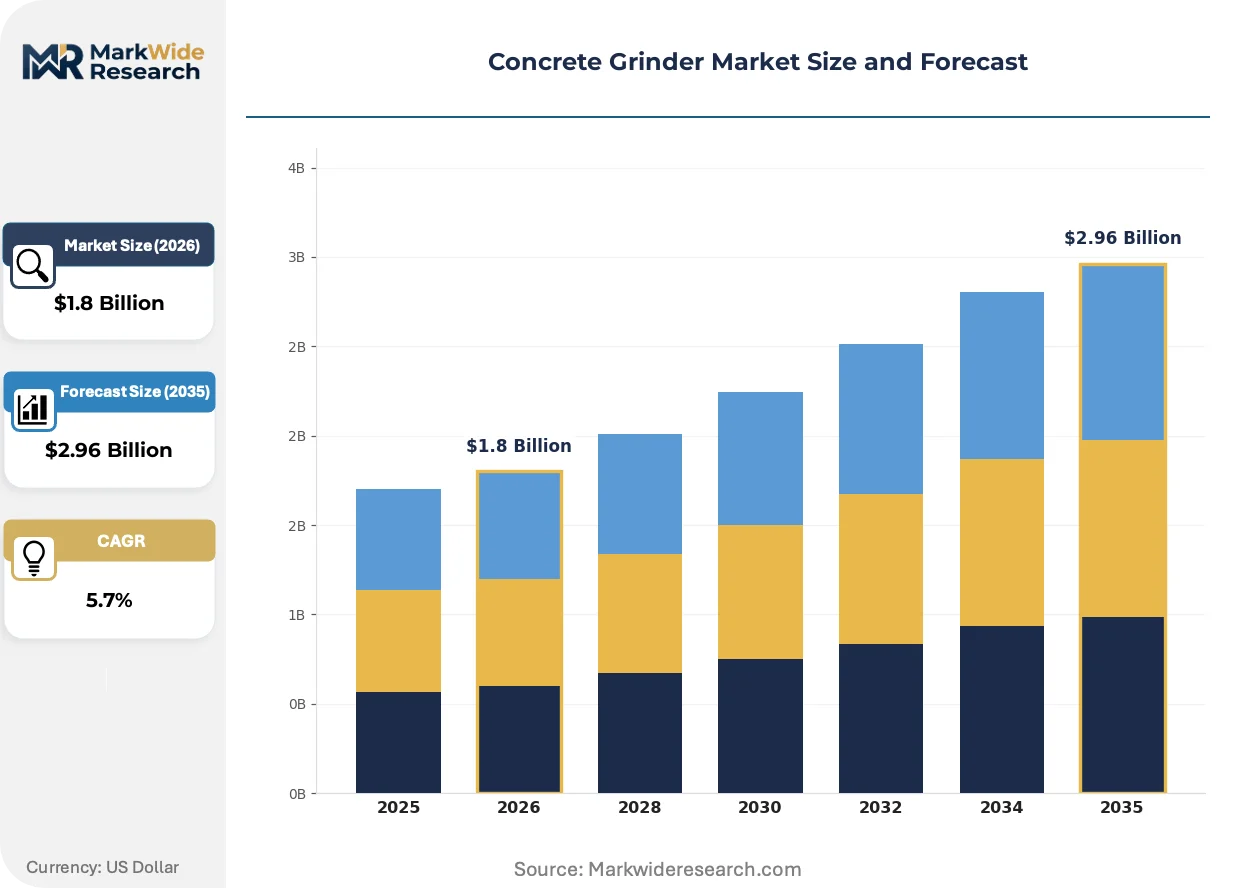
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Grinders, Hand-held Grinders, Edge Grinders, Planetary Grinders End User: Construction Companies, Floor Installers, DIY Enthusiasts, Industrial Facilities Technology: Electric, Gas-powered, Hydraulic, Pneumatic Application: Surface Preparation, Repair, Polishing, Coating Removal |
| Companies Covered | Husqvarna Group, Tyrolit Group, Klindex, Fujian Xingyi Polishing Machine Co., Ltd, Bartell Global, Achilli S.r.l., Superabrasive (Lavina), Scanmaskin Sverige AB, National Flooring Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Grinder Market Evolving Landscape
Grinder platforms are converging with digital telemetry and automated surface mapping, compressing the skill gap between novice operators and polished concrete specialists while reshaping contractor procurement priorities.
Machine guidance systems using LiDAR surface profiling are automating depth control and pattern consistency across large-format commercial floors. National retail chains with standardized finish specifications are adopting these systems fastest. The technology is automating quality variance reduction that previously required decade-experienced operators.
OSHA's updated National Emphasis Program on respirable crystalline silica is accelerating vacuum-integrated grinder specifications. Equipment manufacturers are redesigning airflow architectures to meet real-time exposure monitoring compatibility. Floor preparation contractors in California and Texas are retrofitting existing fleets ahead of anticipated enforcement waves.
Rental channel penetration is displacing direct equipment purchases among sporadic-use contractors. National equipment rental chains are expanding concrete surface preparation categories with telematics-equipped units. This shift concentrates most visibly among residential basement finishing contractors in the Midwest and Southeast.
Concrete Grinder Market Segmentation
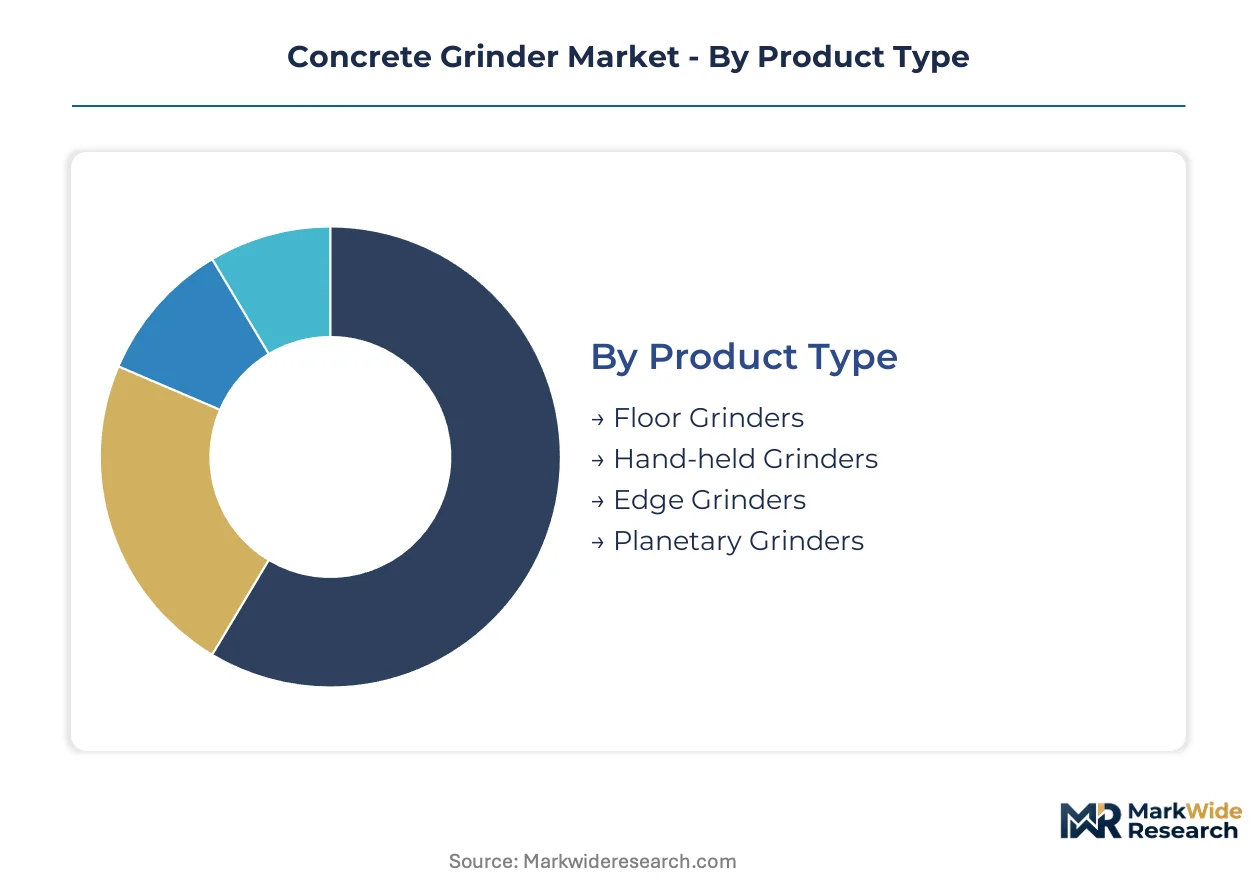
Concrete grinder procurement patterns diverge sharply between fleet operators seeking standardized platforms and specialty contractors optimizing for single-application performance. Segmentation clarity enables equipment manufacturers to align R&D roadmaps with distinct margin profiles and service attach rates across customer types.
Product Type:
Standalone floor systems dominate commercial fleet deployments, while embedded edge and handheld units serve specialized finishing workflows where maneuverability constraints override throughput priorities.
- Floor Grinders:Walk-behind platforms with rotating disc configurations from single-head to multi-planetary drive systems. Warehouse conversion contractors in the United States deploy these across large-format logistics floors where OSHA silica compliance mandates integrated dust collection architectures.
- Planetary Grinders:Precision gear-driven systems with three or more satellite heads rotating around a central axis, delivering consistent scratch patterns for architectural polished concrete. High-visibility retail and hospitality projects in commercial corridors specify these for premium finish specifications.
- Hand-held Grinders:Compact units for detail work and confined access zones where walk-behind equipment cannot operate.
- Edge Grinders:Specialized platforms addressing wall-to-floor transitions and perimeter finishing requirements.
Volume placements concentrate in Floor Grinders; the faster expansion belongs to Planetary Grinders.
End User:
Customer procurement sophistication stratifies by fleet scale, with multi-unit operators prioritizing telematics compatibility and sporadic users favoring rental channel access over capital deployment.
- Construction Companies:General contractors integrating surface preparation into broader project workflows. These stakeholders specify grinder platforms with rapid tooling changeover to compress schedule risk across diverse substrate conditions.
- Floor Installers:Specialized contractors whose equipment utilization rates justify premium platform investments. This segment drives aftermarket attachment for remote diagnostics and predictive maintenance contracts.
- Industrial Facilities:In-house maintenance departments managing periodic floor rehabilitation without external contractor engagement.
- DIY Enthusiasts:Residential basement finishing and small-scale renovation operators accessing equipment primarily through rental channels.
Construction Companies account for the largest equipment placement volumes; Floor Installers are climbing the fastest in platform sophistication and service contract penetration.
Technology:
Power source selection trades emissions compliance against torque requirements, with indoor-outdoor work mix determining electrification feasibility for specific contractor portfolios.
- Electric:Corded and battery-powered platforms dominating indoor commercial applications. EPA emission standards and OSHA confined space ventilation requirements accelerate displacement of combustion alternatives in enclosed construction environments.
- Gas-powered:High-torque units retaining position in exterior heavy-removal and remote infrastructure sites where grid connectivity is unavailable.
- Hydraulic:Specialized platforms for extreme material removal rates in bridge deck and highway rehabilitation.
- Pneumatic:Compressed-air systems deployed in explosive atmosphere environments where electrical spark risk is prohibitive.
Electric platforms command the dominant shipment share; battery-powered variants are gaining share fastest as charging infrastructure penetrates construction sites.
Application:
Workflow sequencing determines equipment specification intensity, with polishing applications demanding precision control systems absent from aggressive removal operations.
- Surface Preparation:Aggressive grinding to achieve specified concrete surface profile for coating adhesion. This foundational step consumes the highest equipment hours across commercial flooring projects.
- Polishing:Multi-stage diamond refinement to specified gloss levels. National retail chains with standardized finish specifications drive demand for automated depth control and pattern consistency systems.
- Coating Removal:Aggressive material stripping of existing epoxy, urethane, or adhesive residues.
- Repair:Localized grinding for crack chasing, spall repair, and leveling compound integration.
Surface Preparation generates the highest equipment utilization hours; Polishing commands the steepest expansion trajectory as architectural concrete aesthetics displace overlay systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concrete grinder manufacturing clusters in Italy and China supply equipment to construction markets where consumption concentrates in the United States and Germany. Production capacity expansion in East Asia serves export demand while North American and European contractors drive specification standards for dust-integrated platforms.
United States
E-commerce fulfillment center buildouts across logistics corridors in Texas, California, and the Midwest dominate grinder deployment volumes. OSHA's National Emphasis Program on respirable crystalline silica mandates vacuum-compatible equipment specifications nationwide. Floor installation contractors in the Dallas-Fort Worth metroplex are retrofitting fleets ahead of anticipated enforcement waves in 2025.
Germany
Industrial flooring specialists specify precision planetary systems for automotive manufacturing plant renovations. REACH regulations on abrasive material composition constrain diamond tooling import sourcing from non-EU suppliers. Equipment fabricators in Baden-Württemberg are integrating real-time exposure monitoring compatibility into grinder architectures.
China
Domestic infrastructure rehabilitation programs sustain demand for high-torque gas-powered units in remote western provinces. GB standards on machinery safety and MEE emission protocols shape export-oriented manufacturing specifications. Production clusters in Fujian Province supply planetary grinder platforms to Southeast Asian commercial construction markets.
Italy
Specialized stone and concrete finishing equipment exports anchor the grinder manufacturing base in Emilia-Romagna. CE marking requirements and EU machinery directives govern product certification for intra-European trade. Bologna-area fabricators concentrate R&D investment in automated depth control systems for architectural polished concrete applications.
Canada
Warehouse conversion activity in the Greater Toronto Area and Vancouver logistics corridors drives electric grinder adoption. Health Canada alignment with OSHA silica exposure guidelines influences provincial occupational safety enforcement. Alberta oil sands maintenance contractors retain gas-powered units for exterior heavy-removal applications in remote site conditions.
Concrete Grinder Market Competitive Landscape
Top-tier vendors anchor premium planetary and dust-integrated platforms, while mid-tier fabricators compete on electric floor grinder standardization. Market structure shows moderate consolidation around construction equipment conglomerates with surface preparation divisions, alongside specialized Italian and Chinese grinder manufacturers. Two strategic archetypes dominate: diversified industrial equipment groups leveraging global service networks, and focused specialists concentrating R&D in diamond tooling integration or drive system mechanics. Competitive moves center on M&A activity targeting regional rental channel access and vertical integration into specialized abrasive supply.
Among diversified equipment conglomerates, Husqvarna Group and Tyrolit Group exemplify the service-network archetype with recurring revenue attachments. Superabrasive (Lavina) occupies a specialist position representing concentrated investment in planetary drive mechanics. Fujian Xingyi Polishing Machine Co., Ltd. anchors the Chinese manufacturing cluster serving export markets with standardized platform economics. These three company patterns illustrate how competitive positioning splits between scale-driven aftermarket capture and focused technical differentiation.
| Leading Market Players |
|---|
| Husqvarna Group |
| Tyrolit Group |
| Klindex |
| Fujian Xingyi Polishing Machine Co., Ltd |
| Bartell Global |
| Achilli S.r.l. |
| Superabrasive (Lavina) |
| Scanmaskin Sverige AB |
| National Flooring Equipment |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Italy and China anchor grinder manufacturing, concentrating supply-side pricing power while private-equity-rolled-up rental chains compress procurement margins through fleet standardization mandates.
Pricing Analysis
Margin tightening in economy-tier floor grinders traces to rental channel expansion and fleet standardization by national equipment chains. Three-tier pricing structure across premium planetary systems, standard electric platforms, and economy walk-behind units stratifies by dust-collection certification level and telematics bundling. Cost-down pressure on economy tiers accelerates because Chinese manufacturers compete on export volume economics. Small residential contractors exhibit highest price sensitivity; national retail chains with standardized finish specifications show lowest.
Supply Chain Analysis
OSHA silica compliance rules in the United States are reshaping sourcing toward vacuum-integrated architectures and domestic assembly partnerships. Manufacturing gravity centers on Italy for precision planetary systems and China for standardized electric platforms, with diamond tooling production clustering in limited geographies. Synthetic diamond feedstock and specialized gear systems constitute critical input dependencies. Single-source vulnerability in abrasive supply elevates inventory carrying costs for distributors. Distribution runs through authorized equipment dealers and expanding national rental chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-powered grinder platforms are displacing gas-powered legacy systems in commercial construction, compressing the electrification investment window for fleet operators.
For Market Incumbents: Extend service network density into secondary metropolitan markets to capture sticky aftermarket revenue from multi-unit fleet operators. Deepen backward integration into specialized diamond tooling production to defend margin position against synthetic diamond price volatility. Counter rental channel displacement by embedding predictive maintenance software as standard equipment features. For New Entrants and Emerging Players: OSHA's National Emphasis Program on respirable crystalline silica in the United States opens a window for vacuum-integrated grinder specialization targeting California and Texas retrofit contractors ahead of enforcement waves. White-space concentrates in battery-powered planetary systems for mid-size polishing contractors and in authorized repair depot networks across Midwest logistics corridors. Go-to-market through regional floor-installer associations accelerates specification penetration. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized Italian planetary-drive fabricators with CE marking infrastructure and export relationships to Southeast Asian commercial construction markets. Long-term viability hinges on electrification R&D depth and aftermarket service attach rates. Monitor battery energy density improvements in construction equipment as inflection signal for gas-powered displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diamond Tooling | Captive abrasive supply insulates Husqvarna and Tyrolit from synthetic diamond feedstock price cycles. |
| Telematics-Enabled Fleet Management | Predictive maintenance contracts reduce downtime for National Flooring Equipment's multi-unit operator base. |
| Battery Platform Standardization | Interchangeable power systems let Scanmaskin Sverige AB consolidate charging infrastructure across grinder classes. |
| Regional Service Depot Expansion | Authorized repair networks in Dallas-Fort Worth and Toronto capture sticky revenue from warehouse conversion contractors. |
| Automated Depth Control Integration | LiDAR surface profiling from Italian manufacturers compresses quality variance for national retail chain specifications. |
Research Methodology
SEC 10-K filings, customs trade databases, and equipment registration records formed the secondary backbone, cross-referenced with primary interviews involving maintenance directors at industrial facilities, procurement leads at floor installation contractors, aftermarket service heads at rental chains, and plant engineers at logistics fulfillment centers. Bottom-up and top-down triangulation validated shipment volumes and specification trends.
Bottom-up modeling aggregated grinder deployments by product type, power source, and end-user segment across the projection horizon, while top-down analysis tracked construction spending and warehouse conversion permits as macro anchors. Segmentation dimensions spanned floor versus planetary versus handheld configurations, electric versus gas versus hydraulic technology, and construction company versus floor installer versus industrial facility end-use. CAGRs derived from equipment replacement cycles and electrification penetration curves, with OSHA enforcement timelines and battery energy density improvements as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for battery-powered displacement would alter the outlook if charging infrastructure deployment lags or gas-powered torque requirements persist in remote infrastructure rehabilitation. Forecasts reflect assumptions about regulatory enforcement intensity and synthetic diamond supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Broaching Machine Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market
Construction Equipment
Piles Turner Market
Construction Equipment
Robotic Total Stations (RTS) Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
Autonomous Heavy Equipment Market
Construction Equipment
Refurbished Construction Equipment Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Water Sprinkler Market
Construction Equipment
Concrete Pumps Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Bale Openers Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Track Mounted Gangway Market