
 Tar Paper Market | 2026-2036
Tar Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Tar Paper Market Analytics
Aftermarket service revenue is rewriting profit dynamics across the tar paper supply chain. GAF leverages backward integration into asphalt refining to sustain margin control across volatile feedstock cycles. Johns Manville anchors its position through fiberglass mat technology leadership that differentiates its saturated felt products from commodity competitors. Owens Corning competes by extending its building materials ecosystem into waterproofing membranes that occupy adjacent specification channels.
Tar paper denotes a bitumen-impregnated felt or fiberglass mat used as a weather-resistant underlayment, typically manufactured through saturation of organic or inorganic substrates with hot asphalt or coal tar pitch at temperatures exceeding 150°C to achieve specified permeance ratings below one perm. Modified bitumen sheets dominate specification-grade roofing applications where polymer-enhanced formulations outperform conventional asphalt felt in thermal cycling resistance. The waterproofing segment leads volume absorption from below-grade foundation projects, while fiber-reinforced variants represent the fastest-growing structural category as contractors specify tear-resistant membranes for mechanically attached systems. Distribution runs through regional roofing distributors that control contractor access and influence brand selection through stocking agreements.
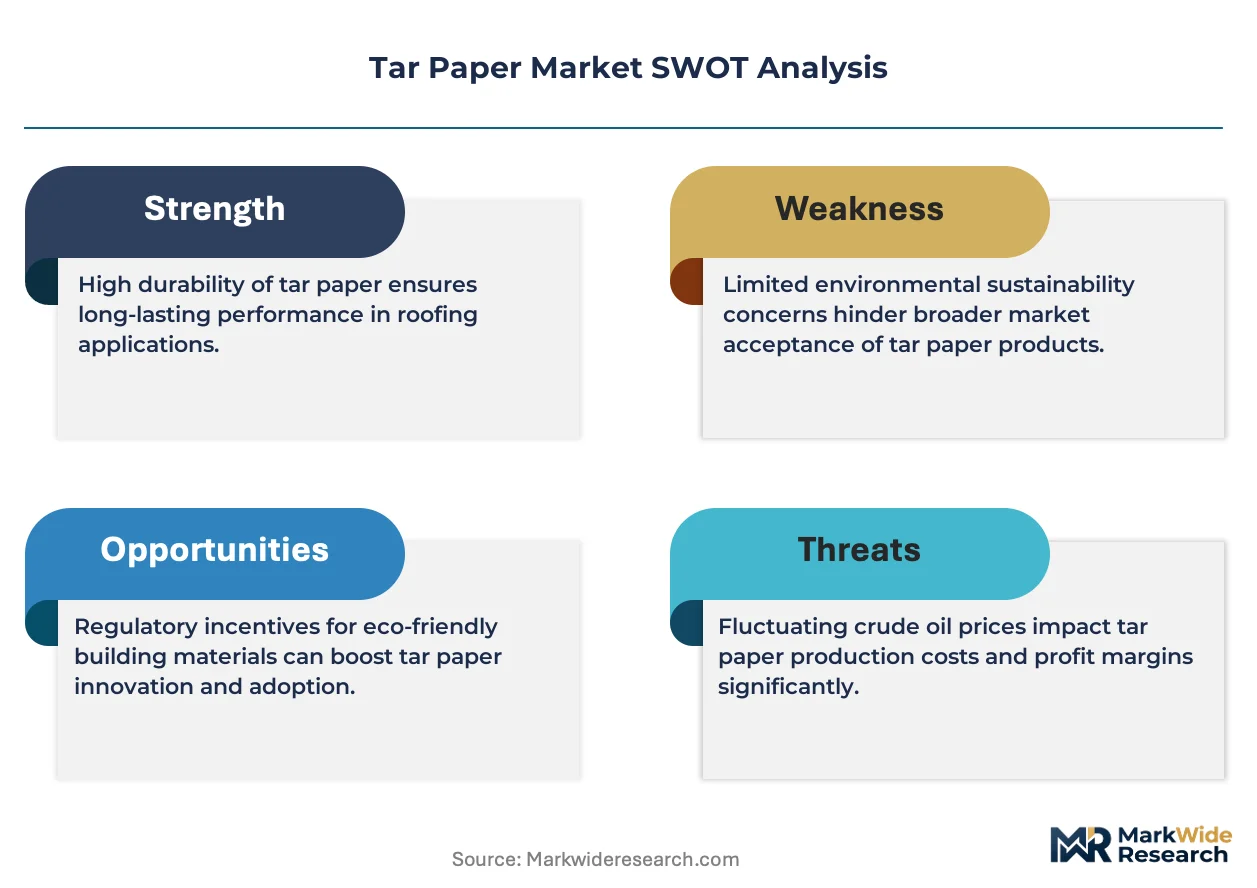
US building codes enforced by the International Code Council and state-level amendments shape product certification requirements for fire resistance and wind uplift performance. EPA regulations on polycyclic aromatic hydrocarbon emissions from coal tar processing push manufacturers toward refined asphalt feedstocks and bio-based modifiers. OSHA workplace exposure limits for bitumen fumes during hot-applied installation create compliance costs that favor roll-good manufacturers supplying low-fume adhesive-compatible membranes. Stakeholders must monitor feedstock substitution economics as petroleum asphalt price volatility intersects with emerging bio-bitumen pilot programs.
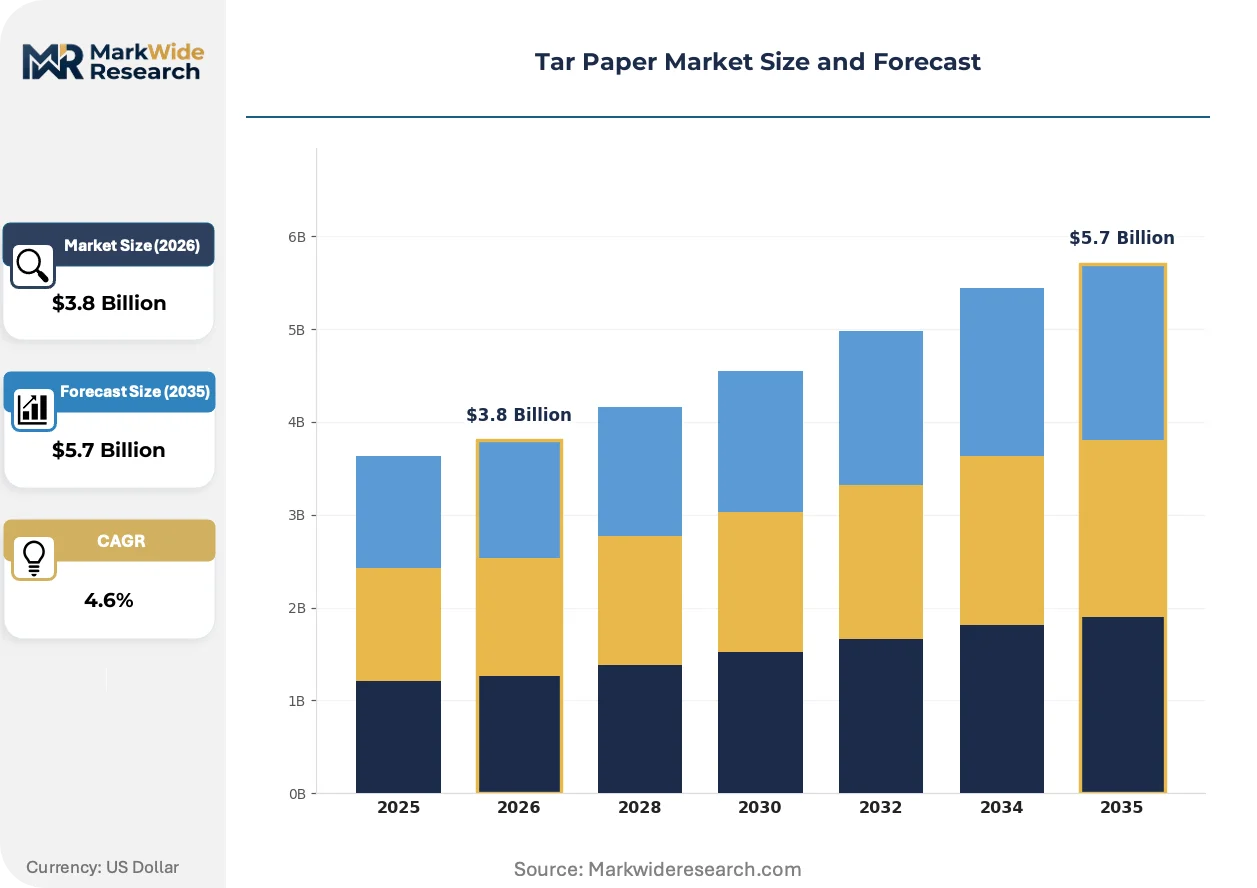
Market Dynamics
Coal tar pitch displacement by modified bitumen formulations is compressing feedstock flexibility while EPA polycyclic aromatic hydrocarbon regulations accelerate refinery-based asphalt sourcing across North American manufacturing corridors.
Growth Catalysts
- International Code Council wind uplift mandates:Stricter building envelope codes in hurricane-prone US jurisdictions force contractors toward fiber-reinforced underlayment specifications that command premium placement.
- Below-grade waterproofing absorption:Foundation contractors in the Gulf Coast corridor specify saturated felt membranes for vapor barrier integration, creating volume anchors independent of residential roofing cyclicality.
- Petrochemical feedstock proximity:Integrated manufacturing clusters along Texas and Louisiana refining corridors capture logistics cost advantages that sustain margin competitiveness through volatile asphalt price cycles.
Market Restraints
- Crude oil price volatility:Vacuum distillation residue costs for asphalt saturation fluctuate with Brent crude benchmarks, compressing converter margins during upstream commodity spikes.
- Coal tar pitch supply concentration:Coking byproduct availability depends on steel production economics in Appalachia and the Rust Belt, creating input scarcity during metallurgical coal demand troughs.
- OSHA bitumen fume exposure limits:Workplace ventilation requirements for hot-applied installation add compliance overhead that disadvantages small roofing contractors relative to mechanized membrane alternatives.
Strategic Opportunities
- Bio-bitumen pilot scale-up:Pyrolysis of lignin waste streams from pulp and paper operations offers pathway to renewable binder substitution for sustainability-specified commercial projects.
- Mechanically attached system penetration:Tear-resistant fiberglass mat products enable specification in high-wind zones previously served by fully adhered single-ply membranes.
- Regional distributor consolidation:Independent roofing supply houses in secondary Midwest markets present acquisition targets for national roll-good manufacturers seeking contractor channel control.
Industry Challenges
- Hot-melt saturation operator certification:Skilled technicians capable of maintaining 150°C+ temperature uniformity across continuous felt webs remain scarce in rural manufacturing locations.
- Fire resistance rating backlog:UL 790 Class A certification timelines stretch to 18 months for new polymer-modified formulations, delaying product launches behind competitor window.
- Legacy inventory obsolescence:Coal tar pitch stockpiles face stranded asset risk as state-level amendments to International Building Code restrict specification in public construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tar Paper Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Asphalt Felt, Coal Tar Pitch, Modified Bitumen, Fiber Reinforced Application: Roofing, Waterproofing, Insulation, Soundproofing End User: Construction, Manufacturing, Energy, Transportation Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | GAF, Johns Manville, CertainTeed, IKO Industries Ltd, Owens Corning, TAMKO Roofing Products Inc., Carlisle Companies Inc., Atlas Roofing Corporation, Siplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tar Paper Market Evolving Landscape
Polymer modification of bitumen binders is redefining performance thresholds while regulatory pressure on aromatic hydrocarbons redirects R&D investment toward refined petroleum and bio-based feedstock pathways.
Styrene-butadiene-styrene modified bitumen is hybridizing conventional asphalt saturation with elastomeric flexibility. Commercial roofing contractors in the US Sun Belt specify SBS sheets for thermal cycling resistance across 40°C daily temperature swings. The technology is hybridizing product portfolios toward specification-grade membranes that capture margin previously ceded to TPO and EPDM single-ply systems.
REACH authorization requirements for coal tar pitch derivatives in European construction materials are tightening impurity thresholds for benzo[a]pyrene content. Manufacturers serving EU export markets must reformulate around refined asphalt or secure costly authorization continuations. Waterproofing membrane producers in Germany and Benelux markets are accelerating substitution timelines to avoid 2026 authorization cliff risks.
Contractor procurement consolidation through national roofing distributor networks is compressing brand loyalty cycles. Regional independents in the US Southeast face displacement by Beacon Roofing Supply and ABC Supply stocking agreements that bundle underlayment with shingle and accessory packages. The consolidation is most visible in Florida and Georgia markets where hurricane repair volume concentrates buying power with top-10 roofing contractors.
Tar Paper Market Segmentation
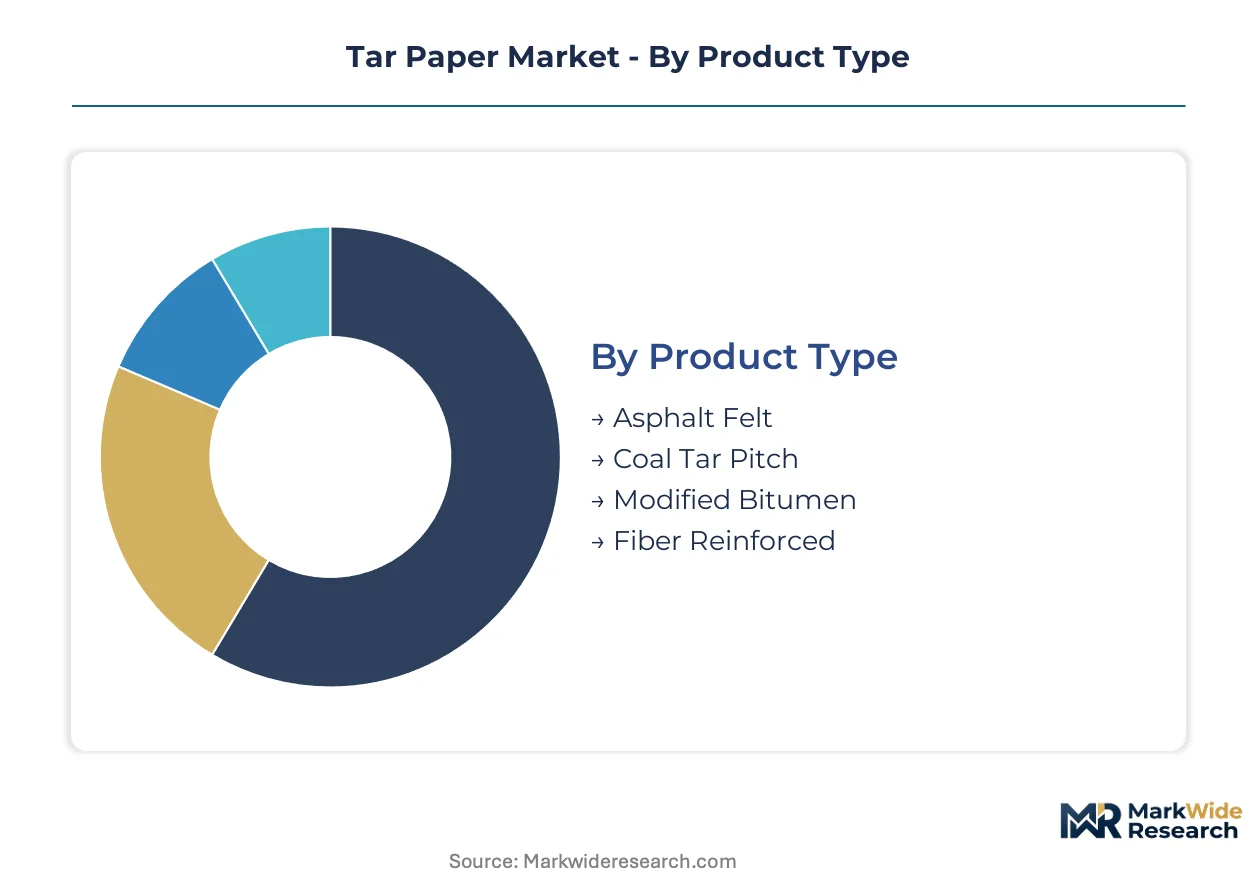
Tar paper segmentation reveals how substrate chemistry and installation method dictate margin structure across the value chain. Product formulation choices cascade through application specifications, end-user procurement patterns, and channel economics in ways that concentrate competitive advantage among integrated manufacturers.
Product Type:
Mature asphalt formulations coexist with emerging polymer-modified technologies that command specification premiums in high-performance building envelopes.
- Asphalt Felt:Saturated organic or fiberglass mat substrates impregnated with hot petroleum asphalt remain the volume foundation for residential roofing underlayment. Contractors in the United States Gulf Coast corridor specify standard #15 and #30 felt for cost-sensitive reroofing projects where building codes permit traditional permeance ratings.
- Modified Bitumen:SBS and APP polymer additives enhance thermal cycling resistance and tensile strength for commercial low-slope applications. Demand concentrates in Sun Belt metropolitan areas where daily temperature swings exceed 35°C and single-ply membrane alternatives face specification pressure from integrated roofing systems.
- Coal Tar Pitch:Coking byproduct formulations deliver superior chemical resistance for below-grade waterproofing but face feedstock scarcity as Appalachian steel production economics fluctuate.
- Fiber Reinforced:Fiberglass mat substrates provide dimensional stability and tear resistance for mechanically attached systems in high-wind zones.
Asphalt Felt retains volume leadership; Modified Bitumen holds the steepest expansion curve.
Application:
Application segmentation tracks how building envelope function determines performance specifications and regulatory exposure across project types.
- Roofing:Steep-slope underlayment and low-slope membrane systems constitute the dominant consumption category. Residential contractors in hurricane-prone United States jurisdictions specify fiber-reinforced products meeting ICC wind uplift standards.
- Waterproofing:Below-grade foundation and plaza deck membranes absorb volume through vapor barrier integration in commercial construction. Gulf Coast foundation contractors anchor demand independent of residential roofing cyclicality.
- Insulation:Bituminous facers and vapor retarders complement rigid foam systems in commercial building envelopes.
- Soundproofing:Mass-loaded barrier applications in multi-family construction represent a niche specification channel.
Roofing commands the largest share of manufacturer throughput; Waterproofing demonstrates the most resilient demand profile across construction cycles.
End User:
End-user segmentation exposes how procurement scale and technical sophistication fragment pricing power across customer categories.
- Construction:General contractors and roofing specialists drive specification through distributor relationships and brand stocking agreements. National top-10 roofing contractors in Florida and Georgia concentrate buying power through hurricane repair volume.
- Manufacturing:OEM demand from prefabricated building component producers creates steady roll-good consumption for integrated membrane systems.
- Energy:Petrochemical facility maintenance and pipeline coating applications specify chemical-resistant coal tar pitch formulations.
- Transportation:Bridge deck waterproofing and railcar roofing represent specialized specification channels with extended certification timelines.
Construction absorbs the majority of unit volume; Manufacturing offers the most predictable procurement patterns for production planning.
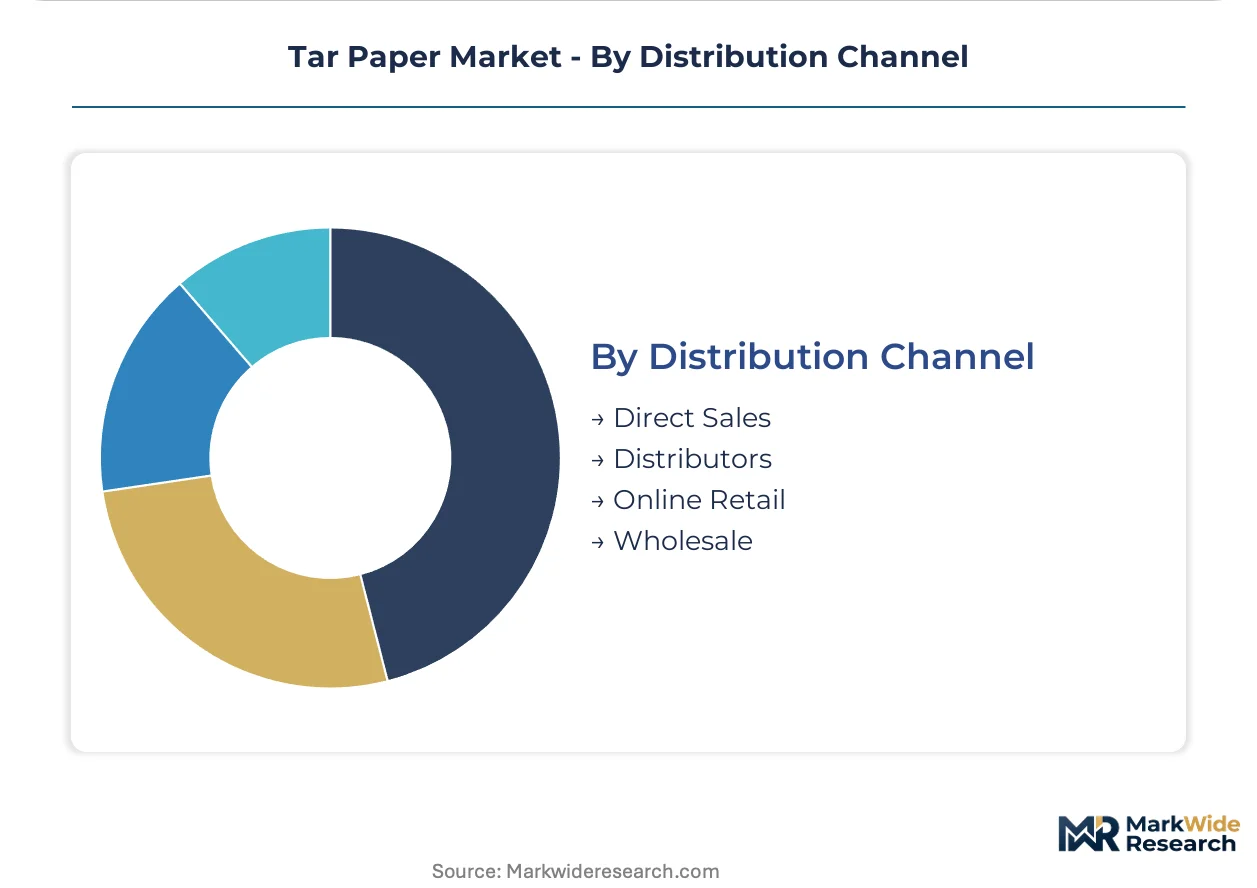
Distribution Channel:
Channel segmentation illuminates how contractor access control shapes brand selection and margin capture across the supply chain.
- Direct Sales:Large commercial roofing contractors procure container-load quantities directly from manufacturers, bypassing distributor markups on specification-grade modified bitumen membranes.
- Distributors:Regional roofing supply houses and national networks like Beacon Roofing Supply and ABC Supply control contractor access through bundled stocking agreements that tie underlayment to shingle and accessory packages.
- Online Retail:E-commerce penetration remains limited to small contractor and DIY segments for standard felt products with straightforward logistics requirements.
- Wholesale:Building material cooperatives and independent supply houses serve secondary Midwest markets with fragmented contractor bases.
Distributors retain channel dominance; Direct Sales is gaining share fastest among large commercial contractors seeking price transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in hurricane-prone United States jurisdictions exhibit low price elasticity for wind-rated fiber-reinforced membranes, while European contractors facing REACH authorization costs show higher substitution sensitivity toward single-ply alternatives.
United States
Residential roofing contractors in Florida and Georgia drive specification-grade membrane demand through hurricane repair volume concentration. The International Code Council enforces wind uplift mandates that disqualify standard asphalt felt in coastal zones. Manufacturing clusters along the Texas and Louisiana Gulf Coast capture feedstock logistics advantages from adjacent petrochemical refining corridors.
Canada
Cold-climate building envelope codes in Ontario and Quebec prioritize vapor barrier performance for below-grade waterproofing applications. Health Canada and PMRA regulate bitumen fume exposure limits that shape contractor safety compliance costs. Industrial concentration in the Prairie Provinces serves oil sands facility maintenance demand for chemical-resistant membrane systems.
Germany
Waterproofing membrane producers in Benelux-exporting regions accelerate coal tar pitch substitution ahead of REACH authorization deadlines. ECHA benzo[a]pyrene thresholds force reformulation toward refined asphalt binders. Manufacturing in the Rhine-Ruhr corridor leverages integrated chemical processing infrastructure for polymer-modified bitumen production.
China
Urban renewal projects in the Yangtze River Delta absorb fiber-reinforced underlayment for high-density residential construction. GB standards for building waterproofing establish performance benchmarks that differentiate specification-grade from commodity products. Shandong Province manufacturing bases source vacuum distillation residue from local refining capacity.
India
Infrastructure investment in Maharashtra and Gujarat creates below-grade waterproofing demand for commercial foundation projects. BIS certification requirements for roofing materials establish quality tiers that influence contractor procurement patterns. Tamil Nadu industrial corridors host emerging modified bitumen production targeting Southeast Asian export markets.
Tar Paper Market Competitive Landscape
Integrated bitumen refiners and specialized membrane fabricators split the market along feedstock control versus formulation expertise lines. Consolidation concentrates among North American roofing material conglomerates with captive asphalt supply, while regional specialists retain share in waterproofing niches. Two archetypes dominate: backward-integrated petrochemical players capturing margin through feedstock cycles, and technology-differentiated mat manufacturers competing on tear resistance and fire ratings. Competitive moves center on distributor channel consolidation and fiberglass substrate technology licensing.
Within the integrated-refiner archetype, GAF and Owens Corning occupy positions shaped by captive asphalt sourcing and building materials ecosystem extension. Johns Manville exemplifies the substrate-technology vector through fiberglass mat leadership that differentiates saturated felt from commodity competitors. These three manufacturers anchor the competitive structure through distinct capability configurations rather than overlapping strategic postures.
| Leading Market Players |
|---|
| GAF |
| Johns Manville |
| CertainTeed |
| IKO Industries Ltd |
| Owens Corning |
| TAMKO Roofing Products Inc. |
| Carlisle Companies Inc. |
| Atlas Roofing Corporation |
| Siplast |
| Others |
Value Network & Pricing Analysis
Texas and Louisiana Gulf Coast refining corridors concentrate vacuum distillation residue supply, translating feedstock proximity into margin resilience for saturated felt manufacturers during asphalt price volatility cycles. Regional distributors capture pricing power through contractor stocking agreements that bundle underlayment with complementary roofing materials.
Pricing Analysis
Aftermarket service revenue from contractor training and installation support drives lifetime value for membrane manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates UL 790 Class A certified fiber-reinforced products from commodity #15 felt and modified bitumen specification grades. Price differentiation hinges on fire resistance certification tier and volume scale procurement by national roofing contractors. Pricing pressure stems from Brent crude volatility transmitting through vacuum distillation residue costs. Small residential contractors exhibit highest price sensitivity, while hurricane-zone commercial specifiers show low elasticity for wind-rated membranes.
Supply Chain Analysis
Export-control regimes on petroleum refining technology limit capacity expansion in emerging manufacturing jurisdictions, preserving North American supply dominance. Production concentrates in the United States, Canada, and Germany, with Shandong Province emerging as a secondary hub serving domestic Chinese demand. Raw material flows draw from coking byproduct streams, vacuum distillation residue, and polymer modifier additives. Single-source vulnerability runs through Appalachian metallurgical coal supply for coal tar pitch feedstock. Distribution runs through regional roofing supply houses and national distributor networks that control contractor channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated national roofing contractors in Florida and Georgia, where hurricane repair volume concentrates procurement leverage with top-10 firms and fragments pricing power among fragmented regional independents.
For Market Incumbents: Insulate margin position through backward integration into asphalt refining and captive fiberglass mat production. Secure distributor exclusivity agreements in secondary Midwest markets before regional independents consolidate. Prioritize UL 790 Class A certification investment to maintain specification-grade positioning against TPO and EPDM membrane substitutes.
For New Entrants and Emerging Players: Pursue bio-bitumen formulation partnerships with pulp and paper operations to capture sustainability-specified commercial project demand. Target below-grade waterproofing applications in the Gulf Coast corridor where foundation contractor demand anchors volume independent of residential roofing cyclicality. Lead with low-fume adhesive-compatible membrane systems that reduce OSHA compliance burden for small contractors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors substrate-technology specialists with fiberglass mat differentiation over commodity asphalt felt producers. Five-to-ten year viability hinges on polymer modification R&D pipelines and REACH-compliant formulation transitions. Monitor ECHA authorization timelines for coal tar pitch derivatives as inflection indicator for accelerated substitution investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Asphalt Refining | GAF captures margin control through captive vacuum distillation residue supply from Gulf Coast facilities. |
| Fiberglass Mat Technology Licensing | Johns Manville extends substrate differentiation revenue through technology partnerships with regional fabricators. |
| Regional Distributor Acquisition | National manufacturers consolidate contractor channel control in fragmented Midwest supply markets. |
| Bio-Bitumen Pilot Scale-Up | Lignin waste stream pyrolysis offers renewable binder pathway for EU REACH-compliant waterproofing specifications. |
| Fire Resistance Certification Investment | UL 790 Class A rating timelines stretch to eighteen months, creating competitive moat for early certifiers. |
Research Methodology
The analysis maps asphalt felt, modified bitumen, coal tar pitch, and fiber-reinforced membrane sub-sectors, each validated through saturation plant managers, regional distributor procurement leads, commercial roofing contractor estimators, and building code enforcement officials. Primary interview findings triangulate against secondary sources including International Code Council amendment filings, EPA polycyclic aromatic hydrocarbon emission databases, OSHA workplace exposure limit documentation, and SEC 10-K disclosures from integrated building materials conglomerates. Bottom-up production volume estimates reconcile with top-down construction spending attribution across residential, commercial, and infrastructure end-uses.
Assumptions hold fixed current International Building Code wind uplift mandates and OSHA bitumen fume exposure limits while varying crude oil price scenarios and REACH authorization timelines. Segmentation dimensions span substrate chemistry, application function, end-user procurement scale, and distribution channel structure. CAGRs derive from elasticity-adjusted demand projections and capacity expansion schedules across the analysis window. Forecast inputs incorporate Gulf Coast petrochemical feedstock pricing dynamics and hurricane frequency patterns for coastal United States demand zones.
Sensitivities concentrate around crude oil volatility, coal tar pitch feedstock scarcity, and regulatory acceleration of bio-based binder substitution. Forecasts reflect documented assumptions on construction cycle timing and code adoption rates. Material shifts in EPA polycyclic aromatic hydrocarbon enforcement or ECHA authorization cliff timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Modular Commercial Building System Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
US Steel Rebar Market
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Plastic Roofing Tiles Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Silos Market
Building & Construction Materials
Skirting Board Market
Building & Construction Materials
Asia-Pacific Gypsum Board Market
Building & Construction Materials
Asia-Pacific Flanges Market