
 Global Polyaspartic Coatings Market | 2026-2036
Global Polyaspartic Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyaspartic Coatings Market Intelligence
The European Union's F-Gas Regulation and similar VOC restrictions in North America are rebalancing the cost-of-entry calculus for new formulations. Covestro AG leverages its expertise in polyisocyanate chemistry to supply raw materials. The Sherwin-Williams Company competes through its extensive distribution network and brand recognition among contractors. Sika AG specializes in high-performance systems for demanding construction applications.
Polyaspartic coatings are two-component systems derived from the reaction of an aliphatic polyisocyanate with an aspartic ester. Their primary function is to provide a highly durable, UV-resistant, and fast-curing protective layer for substrates like concrete and steel. Floor coatings represent a dominant product type, driven by industrial and residential applications requiring minimal downtime. Fast-curing formulations gain share, particularly among professional contractors seeking to accelerate project timelines.
The US Environmental Protection Agency (EPA) sets VOC limits that influence product development for the North American market. Concurrently, compliance with ISO 9001 standards for quality management is a prerequisite for supplying major OEMs and industrial projects. The key decision for formulators is balancing cure speed against application window to meet varying climate conditions and end-user skill levels.
Market Dynamics
The central dynamic in the polyaspartic coatings market is the tension between the demand for rapid project turnaround and the increasing stringency of environmental regulations. This forces formulators to innovate on cure speed without compromising compliance with VOC limits set by bodies like the EU's ECHA.
Growth Catalysts
- Regulatory Mandates:Frameworks like the EU's REACH directive and VOC limits from the US EPA favor low-to-zero VOC polyaspartic systems, accelerating their substitution for solvent-heavy traditional coatings in industrial and architectural applications.
- Industrial Infrastructure Expansion:Demand for fast-curing flooring in logistics centers, manufacturing plants, and food processing facilities across Germany and China drives adoption, as minimizing operational downtime is a primary economic driver for asset owners.
- Formulation Advancement:The development of polyaspartic esters with slower reactivity extends the pot life and application window of coatings, making these systems more accessible to contractors with varying skill levels and in diverse climatic conditions.
Market Restraints
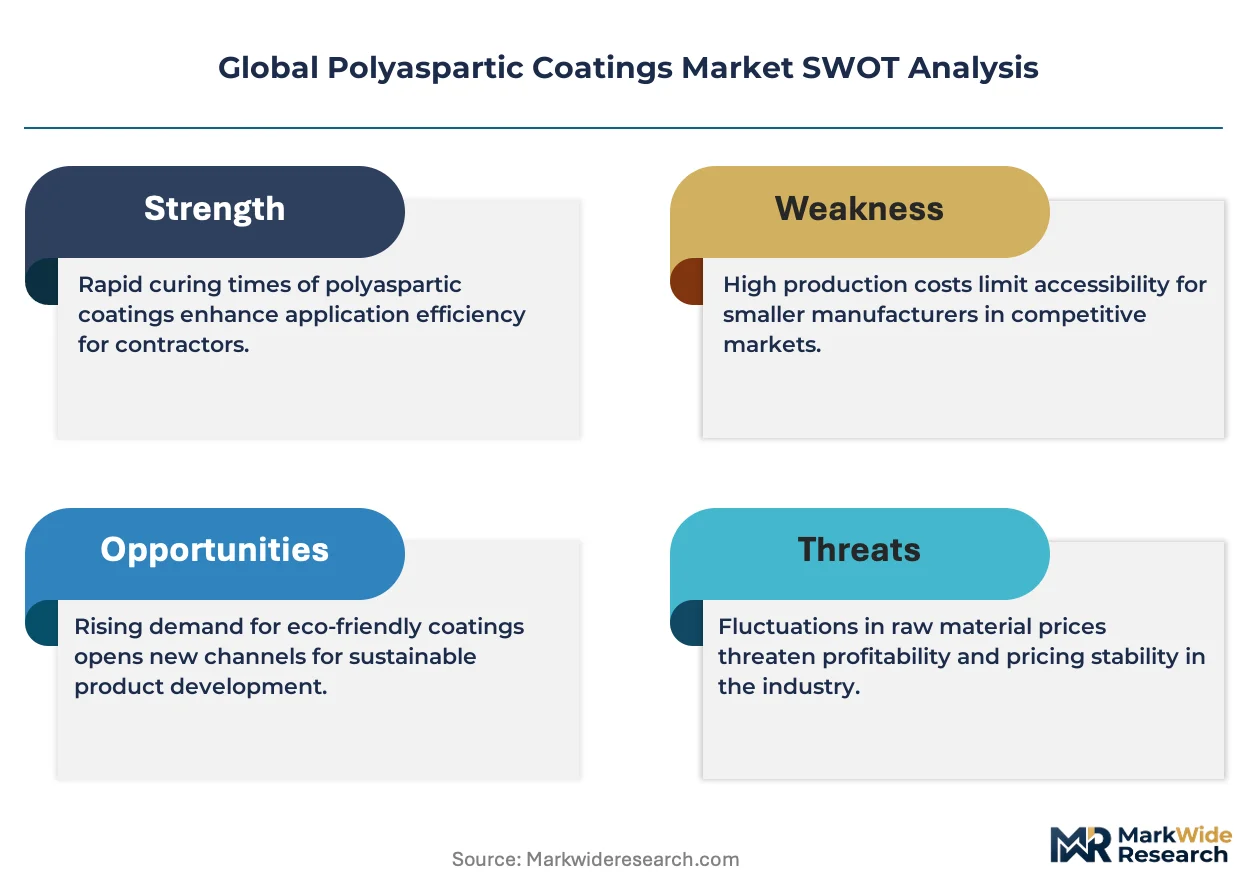
- Higher Material Costs:The primary raw materials, specifically aliphatic polyisocyanates and aspartic esters, carry a significant cost premium over the base components of traditional epoxy and polyurethane systems, limiting adoption in cost-sensitive projects.
- Application Sensitivity:Polyaspartic systems are highly sensitive to ambient humidity and substrate moisture during application, which can lead to blistering, amine blush, or poor adhesion if not managed by skilled applicators.
- Raw Material Concentration:The supply of specialized aspartic ester amines is concentrated among a few chemical manufacturers, creating potential for supply chain bottlenecks and price volatility that can impact formulators' margins.
Strategic Opportunities
- Expansion in Renewable Energy:The UV and corrosion resistance of polyaspartics creates an opportunity for protective coatings on wind turbine towers and blades, an application where long-term durability and minimal maintenance are critical.
- Water-Based Formulations:Developing commercially viable water-based polyaspartic systems would unlock new markets, particularly in interior architectural and institutional settings where odor and flammability are major concerns.
- Growth in Southeast Asian Markets:Underpenetrated markets in countries like Vietnam and Indonesia, with their expanding industrial and manufacturing bases, present significant growth potential as awareness of high-performance coatings increases.
Industry Challenges
- Applicator Skill Gap:The extremely fast cure time of many polyaspartic formulations requires specialized training and equipment, and a shortage of qualified contractors can hinder market growth and lead to application failures.
- Performance Standardization:A lack of universally accepted standards for testing abrasion resistance, UV stability, and chemical exposure across different polyaspartic systems makes it difficult for end-users to compare products directly.
- Navigating Global Regulations:Formulators face the complexity of creating products that comply with a patchwork of differing VOC content rules, such as those from the California Air Resources Board (CARB) and the EU's Decopaint Directive.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyaspartic Coatings Market |
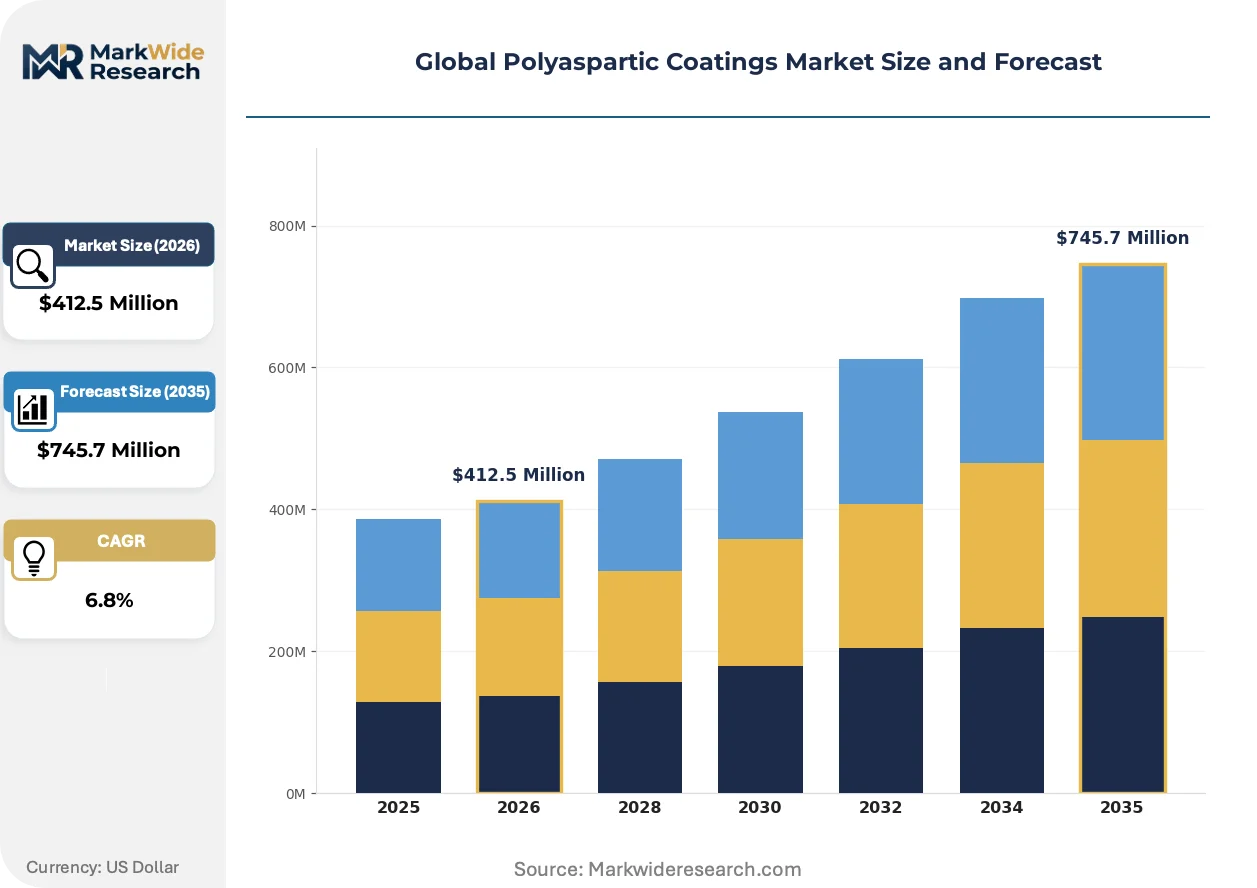
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exterior, Interior, Floor, Roof Application: Automotive, Marine, Industrial, Residential Curing Mechanism: Aliphatic, Aromatic, Hybrid, Fast-Curing End User: Contractors, OEMs, DIY Users, Manufacturers |
| Companies Covered | Covestro AG, PPG Industries, Inc., Akzo Nobel N.V., BASF SE, The Sherwin-Williams Company, Sika AG, Carboline, Rust-Oleum Corporation, LATICRETE International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyaspartic Coatings Market Strategic Shifts & Innovations
Formulation science is advancing toward systems that offer greater application forgiveness without sacrificing performance. This push for more user-friendly, sustainable coatings is happening alongside a shift in how these high-performance materials are specified and sold in major construction and industrial projects.
Advanced formulation software incorporates predictive modeling based on real-time temperature and humidity data. Large-scale flooring contractors and industrial coating formulators are adopting these tools to optimize catalyst and solvent packages for specific job-site conditions. This development is automating the selection of additives, which reduces the risk of application errors and minimizes material waste on complex projects.
The European Union's F-Gas Regulation is tightening restrictions on fluorinated gases, which can be components in certain specialty solvents or additives used in coatings. This regulatory pressure compels chemical suppliers and formulators to accelerate R&D into compliant, low-GWP alternatives. The OEM and transportation finishing sectors are particularly affected, driving innovation toward 100% solids and water-based polyaspartic technologies.
A distinct behavioral shift sees manufacturers moving from transactional product sales to early-stage specification partnerships with architectural and engineering firms. This model disrupts the traditional distributor-to-contractor channel by embedding the coating solution within the project's initial design and performance requirements. This trend is most prominent in large-scale commercial and institutional projects across North America where lifecycle costing is a key factor.
Global Polyaspartic Coatings Market Segmentation
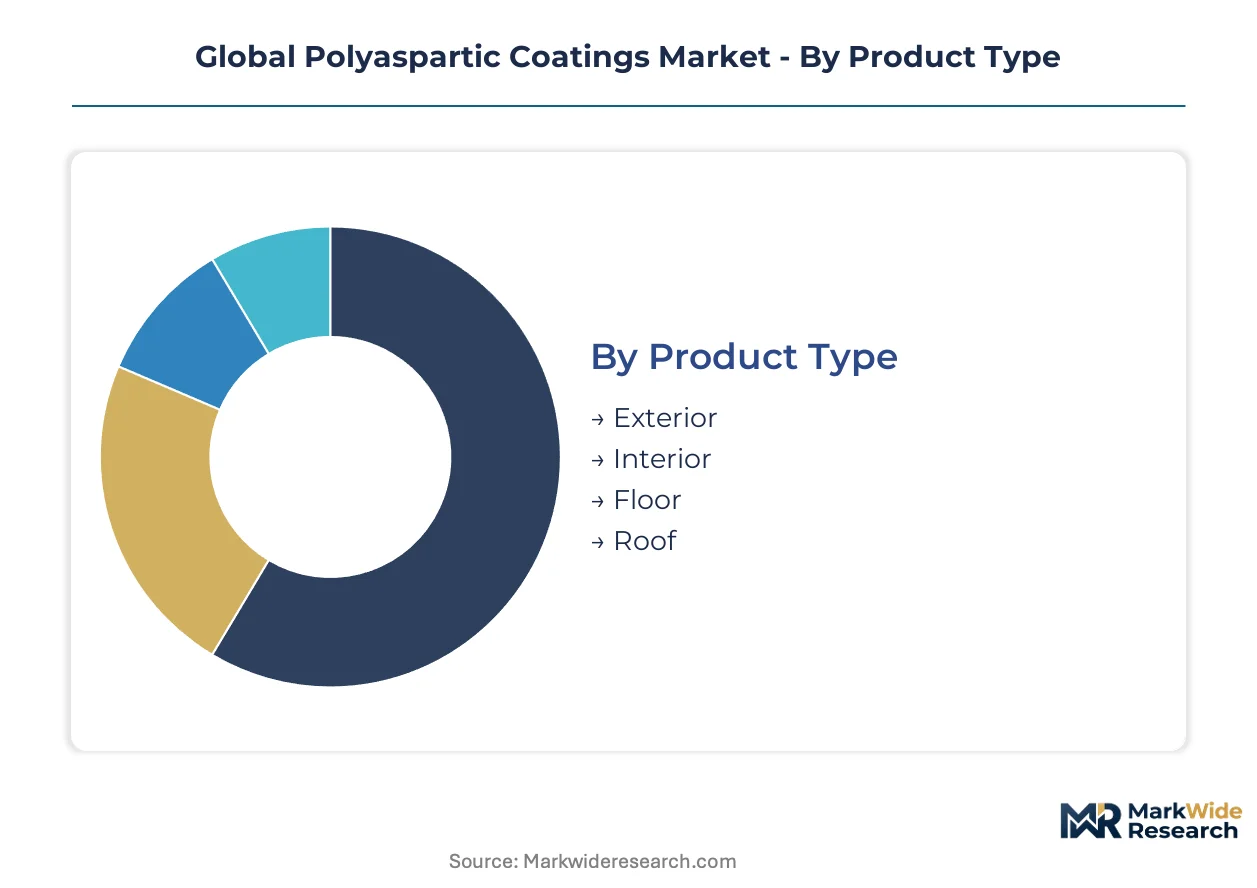
Segmentation within the global polyaspartic coatings market reveals the diverse requirements and opportunities across various product types, applications, curing mechanisms, and end-user groups. Understanding these distinctions is critical for formulators and suppliers to tailor offerings and navigate specific market demands effectively.
Product Type:
The Product Type segmentation highlights how varying regulatory requirements, such as those from the US EPA and the EU's ECHA, influence formulation and market entry for polyaspartic coatings depending on their intended use environment.
- Floor:Primary function is to provide highly durable, fast-curing protective layers for concrete in industrial and residential settings. Demand concentrates in logistics centers and manufacturing plants across Germany and China, driven by the need for minimal operational downtime.
- Exterior:These coatings offer superior UV resistance and weatherability for outdoor applications on substrates like steel and concrete. Demand is significant in infrastructure projects and renewable energy installations, such as wind turbine towers, requiring long-term durability.
- Interior:Applied in indoor environments, these formulations often prioritize low VOC content to meet air quality standards in commercial and institutional buildings.
- Roof:Polyaspartic roof coatings provide durable, weather-resistant membranes, extending the lifespan of commercial and industrial roofing systems.
Floor coatings sit at the top of the volume ranking, with Exterior applications climbing the fastest.
Application:
Application segments delineate where the cost-benefit analysis of polyaspartic systems provides a clear advantage over traditional coatings, despite their higher initial material costs.
- Industrial:Encompasses a broad range of heavy-duty uses in manufacturing, warehouses, and chemical processing facilities, where chemical resistance and rapid return-to-service are critical. Demand is particularly strong in Germany and China's expanding manufacturing sectors.
- Residential:Includes garage floors, patios, and other home improvement projects, benefiting from the fast-curing properties and aesthetic appeal of polyaspartics. This segment is expanding as consumer awareness of durable, low-maintenance flooring solutions increases.
- Automotive:Used for protective and decorative finishes on vehicle components and in repair shops, valuing their durability and quick drying times for production efficiency.
- Marine:Applied to vessels and offshore structures, providing corrosion protection and UV stability in harsh saltwater environments.
Industrial applications command the largest market share, while residential uses are gaining traction due to increased consumer awareness.
Curing Mechanism:
The Curing Mechanism category reflects the chemical diversity and formulation complexity inherent in polyaspartic systems, influencing their performance characteristics and application windows.
- Fast-Curing:These formulations are engineered for extremely rapid drying and return-to-service, crucial for projects with minimal downtime requirements in industrial flooring. They gain share among professional contractors seeking to accelerate project timelines.
- Aliphatic:Derived from aliphatic polyisocyanates, these systems provide excellent UV stability and non-yellowing properties, making them suitable for exterior and high-visibility applications. Their chemical backbone contributes to long-term color retention.
- Aromatic:Aromatic polyaspartics offer cost advantages and good chemical resistance but typically exhibit less UV stability, limiting their use to interior or basecoat applications.
- Hybrid:These systems combine polyaspartic chemistry with other resin types to optimize specific properties like flexibility, adhesion, or cost-effectiveness for varied applications.
Fast-Curing formulations are experiencing the steepest expansion trajectory, driven by contractor demand for efficiency.
End User:
End User segmentation highlights the varying technical expertise and application requirements across different customer groups, from highly skilled professionals to individual consumers.
- Contractors:Professional applicators who specialize in installing polyaspartic systems for industrial, commercial, and residential projects, requiring specialized training due to fast cure times. They value formulations that offer extended pot life for application forgiveness.
- OEMs:Original Equipment Manufacturers integrate polyaspartic coatings into their production processes for new products, such as automotive parts or industrial machinery, demanding consistent quality and compliance with ISO 9001 standards.
- DIY Users:Individual consumers applying polyaspartic coatings for smaller residential projects, often preferring simpler, more forgiving formulations with longer application windows.
- Manufacturers:Companies that produce goods and utilize polyaspartics for in-house maintenance, equipment protection, or as a component in their final products.
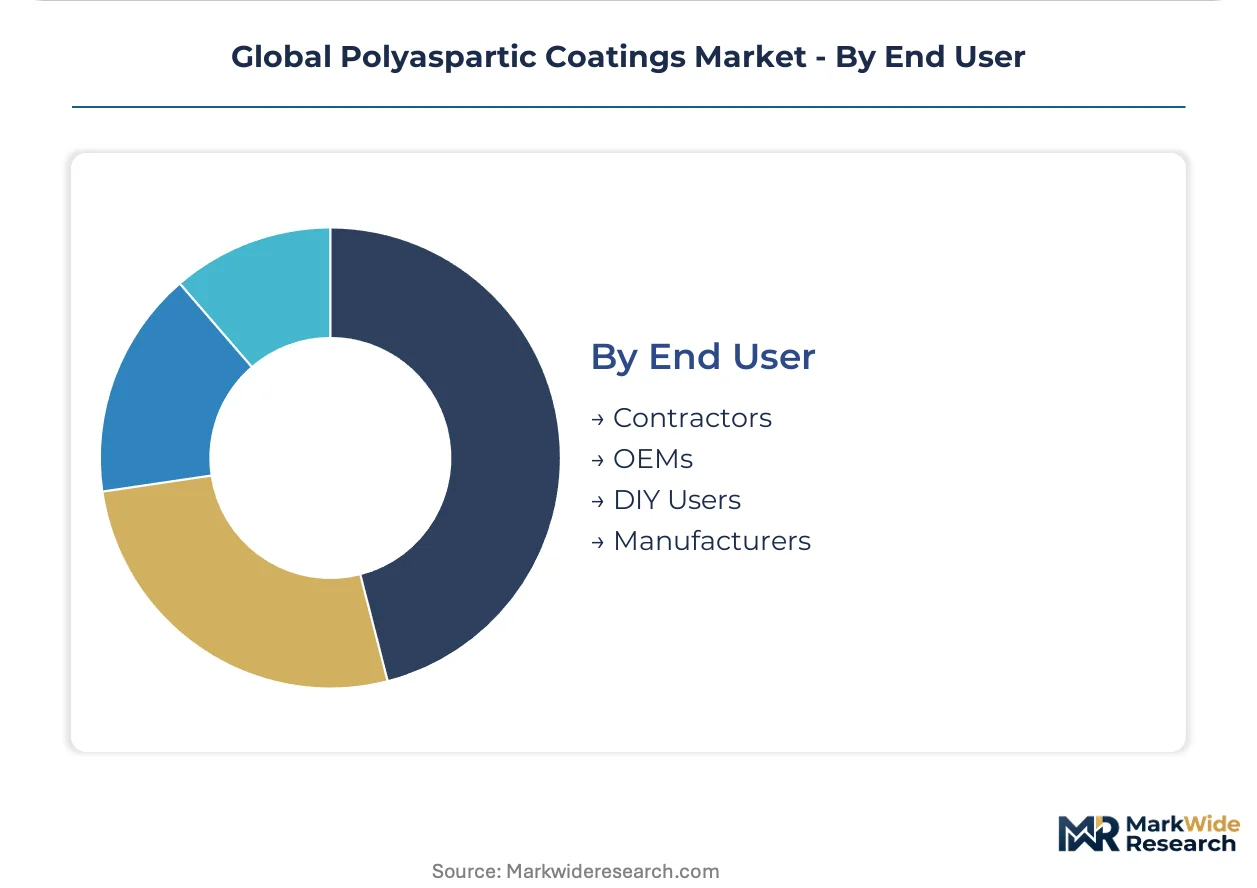
Contractors represent the largest consumption segment, while OEM demand is steadily growing for integrated solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced chemical engineering talent pool anchors significant innovation in polyaspartic coatings. This concentration of expertise drives development of specialized formulations meeting stringent environmental and performance criteria. Formulators leverage this knowledge base for high-performance industrial applications.
United States
Demand for fast-curing flooring solutions in United States logistics drives polyaspartic adoption. The US Environmental Protection Agency (EPA) sets VOC limits influencing product development for the North American market. Industrial hubs like the Ohio River Valley see increased specification for durable, quick return-to-service coatings in manufacturing.
Germany
Stringent environmental regulations in Germany, like the EU's REACH framework, favor low-VOC polyaspartic systems over traditional options. Industrial infrastructure expansion in North Rhine-Westphalia requires rapid return-to-service for new logistics centers and automotive plants. Asset owners prioritize polyaspartic systems to minimize operational downtime and ensure compliance.
China
Expanding manufacturing bases across China generate substantial demand for durable industrial flooring, especially in the Yangtze River Delta. The Chinese Ministry of Ecology and Environment (MEE) promotes environmentally compliant coating solutions for industrial applications. Large-scale factory constructions in Guangdong province integrate polyaspartic systems for fast-curing properties and long-term protection.
Vietnam
Industrialization and infrastructure development in Vietnam create new opportunities for high-performance protective coatings. The country's national environmental protection agency encourages adoption of low-VOC materials in new construction projects. Manufacturing zones near Ho Chi Minh City adopt polyaspartic systems for factories to meet international quality standards and reduce downtime.
United Kingdom
The UK construction sector prioritizes long-lasting, low-maintenance finishes for commercial and public infrastructure projects. Environmental regulations, including VOC content, influence material selection for building specifications. Significant investment in logistics and data centers across Southeast England drives demand for high-performance, fast-curing floor coatings.
Global Polyaspartic Coatings Market Key Industry Players
The competitive structure tilts toward a tiered system, with large chemical conglomerates supplying raw materials and specialized formulators developing application-specific solutions. This market exhibits both consolidation at the raw material production level and fragmentation among downstream applicators. Key strategic archetypes include global chemical suppliers, integrated coating manufacturers, and niche high-performance system providers. Dominant competitive moves involve portfolio diversification into adjacent high-performance segments and strategic partnerships to secure raw material supply.
Within the raw material supply chain, Covestro AG, a German-based chemical giant, represents a critical upstream supplier of polyisocyanate chemistry for polyaspartic systems. The Sherwin-Williams Company, an American-headquartered entity, exemplifies a global integrated coatings manufacturer, leveraging its extensive distribution network and brand recognition among contractors. Sika AG, a Swiss-domiciled specialist, occupies a position as a provider of high-performance construction chemical systems, including advanced polyaspartic solutions for demanding applications. These entities collectively demonstrate the diverse roles played by major participants in the polyaspartic coatings market.
| Leading Market Players |
|---|
| Covestro AG |
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| BASF SE |
| The Sherwin-Williams Company |
| Sika AG |
| Carboline |
| Rust-Oleum Corporation |
| LATICRETE International, Inc. |
| Others |
Cost & Logistics Intelligence
Demand for rapid project turnaround across industrial and infrastructure applications is forcing formulators to balance cure speed with cost. This dynamic influences raw material procurement strategies and ultimately shapes end-product pricing for polyaspartic systems.
Pricing Analysis
Bundled product-and-application services command a premium, while unbundled material sales often follow a project-based pricing model for polyaspartic coatings. Price differentiation stems from specialized formulation for specific end-uses and the inclusion of skilled application services. Pricing softness runs through standard industrial flooring applications due to increased competition from traditional systems. DIY users represent the most price-sensitive segment, while OEMs prioritize performance and consistency over lowest cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized aspartic ester amine manufacturers, primarily concentrated in Germany and China. The market relies heavily on aliphatic polyisocyanates and aspartic esters as primary raw materials. Commodity price volatility for these chemical intermediates poses a significant structural risk to formulators' margins. Downstream distribution runs through a network of specialized chemical distributors and direct sales to large industrial contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyaspartic coatings market embodies a late-cycle quality story, driven by a demand shift towards premium specifications for long-term asset protection. Strategic actions must align with evolving regulatory landscapes and end-user performance expectations.
For Market Incumbents: Deploy continuous R&D investment into low-VOC, water-based polyaspartic formulations. This defends against the threat of stringent environmental regulations like the EU's F-Gas Regulation and supports market share against substitute technologies. Investing in applicator training programs deepens channel control and mitigates the applicator skill gap, a key market restraint. Strategic partnerships with large-scale industrial contractors ensure consistent product specification.
For New Entrants and Emerging Players: Begin with targeting underpenetrated Southeast Asian markets, such as Vietnam, where industrialization is accelerating. Focus on developing user-friendly formulations with extended pot life, making them accessible for contractors with varying skill levels. The residential garage floor segment offers a penetrable entry point due to increasing consumer awareness. A direct-to-contractor sales model, emphasizing technical support and training, provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized formulators possessing proprietary low-VOC polyaspartic chemistries. The long-term viability of this market, over a five to ten-year window, is strong due to regulatory tailwinds and performance advantages. Acquisition targets should be mid-sized companies with established distribution networks and strong R&D capabilities in sustainable formulations. The signal to watch is the widespread adoption of water-based polyaspartic systems in interior architectural applications.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Water-Based Formulations | Developing viable water-based polyaspartic systems unlocks new markets in interior architectural settings and addresses odor concerns. |
| Expansion in Southeast Asia | Targeting Vietnam and Indonesia leverages expanding industrial bases and increasing demand for high-performance coatings. |
| Applicator Training Programs | Addressing the applicator skill gap ensures proper application of fast-curing polyaspartics and reduces project failures. |
| Partnerships with A&E Firms | Early-stage specification partnerships embed polyaspartic solutions within project design, disrupting traditional sales channels. |
| Sustainable Raw Material Sourcing | Securing compliant, low-GWP alternatives for specialty solvents aligns with EU F-Gas Regulation and reduces supply chain risk. |
Research Approach
Bottom-up industrial flooring modeling reconciled against top-down raw material supply tracking forms the analytical core for this study. This approach integrates primary interviews with R&D directors, procurement leads, and large-scale flooring contractors. Secondary validation draws from customs data, chemical industry association reports, and regulatory filings from bodies like the US EPA and ECHA. This triangulation ensures robust data integrity.
Historical trendline analysis projects market evolution across the analysis window, considering past performance and future growth drivers. Segmentation dimensions modeled include product type, application, curing mechanism, and end-user type, alongside regional regulatory clusters. Compound Annual Growth Rates (CAGRs) derive from a weighted average of segment-specific growth trajectories. Industrial infrastructure expansion rates in Germany and China serve as key forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen geopolitical disruptions or rapid, disruptive technological shifts. Forecasts reflect assumptions regarding raw material price stability and consistent regulatory enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
South Korea Automotive OEM Coatings Market
Coatings
Waterborne Automobile Coating Market
Coatings
Protective Coatings Market
Coatings
Solar Reflective Film Market
Coatings
Morocco Automotive OEM Coatings Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
Asia-Pacific Epoxy Powder Coatings Market
Coatings
Coatings Raw Materials Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Color-Shifting Coating Market
Coatings
Anti Soiling Coating Market
Coatings
Europe Anti-Friction Coatings Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
FBE Coatings Market
Coatings
Extrusion Coating Market
Coatings
Global Fusion Bonded Epoxy Coatings Market