
 Sri Lanka Paints and Coatings Market | 2026-2036
Sri Lanka Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Sri Lanka Paints and Coatings Market Analytics
Sri Lanka's domestic manufacturing base is reshaping supply availability for architectural and industrial finishes. Jotun leverages its marine coating expertise to dominate port-adjacent projects along Colombo's waterfront. Akzo Nobel NV anchors premium decorative demand through specialized color matching and durability guarantees. Lankem Robbialac sustains broad distribution across Sri Lankan retail channels, competing on accessibility and local brand recognition.
Paints and coatings are liquid or powder formulations comprising pigments, binders, solvents, and additives that cure to form protective or decorative films on substrates, with viscosity typically ranging from 70 to 120 Krebs units for brush-applied architectural grades. Their primary purpose is to shield surfaces from corrosion, weathering, and chemical attack while providing aesthetic finish. Architectural Paints generates the largest revenue pool due to sustained housing and commercial construction, though Industrial Coatings captures higher per-liter margins from automotive and machinery applications. Water-Based formulations are displacing solvent alternatives as SLSI environmental rules tighten, while Powder Coatings grows fastest among factory-applied industrial segments.
Sri Lanka Standards Institution (SLSI) mandates compliance with national VOC emission ceilings, compelling reformulation across domestic production. The country's central environmental regulator enforces industrial discharge permits that affect coating plant siting and wastewater treatment investment. Construction sector procurement officers must monitor raw material import costs and currency volatility when sourcing binders and titanium dioxide. Stakeholders should track how SLSI alignment with ISO 14001 environmental management standards evolves, as this will determine which formulation technologies qualify for public infrastructure tenders.
Market Dynamics
Sri Lanka's paint and coatings sector operates under acute pressure from SLSI-mandated VOC ceilings, forcing domestic manufacturers to abandon solvent-based chemistries and rebuild formulation capabilities around water-borne systems. This regulatory compression is restructuring competitive advantage toward firms with in-house resin synthesis and rapid reformulation capacity.
Growth Catalysts
- Western Province construction cluster:Colombo's port expansion and residential tower development concentrate demand for marine-grade and decorative finishes. Contractors specify certified low-emission products to meet public tender requirements.
- SLSI environmental alignment:The national standards body's progressive adoption of ISO 14001-equivalent benchmarks creates procurement preference for compliant domestic manufacturers in infrastructure bids.
- Titanium dioxide substitution research:Local laboratories are validating calcium carbonate and kaolin extenders to reduce import dependency for white pigment feedstocks.
Market Restraints
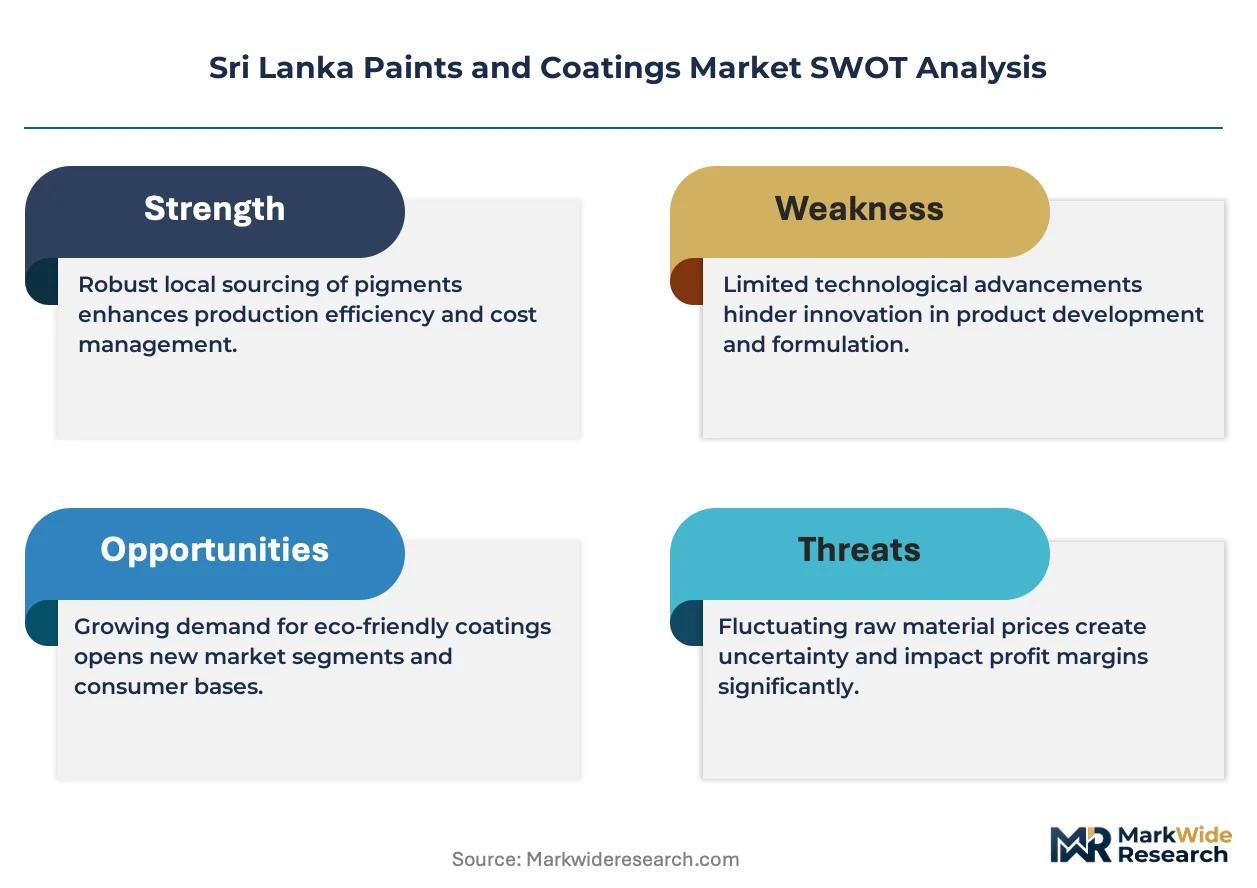
- Raw material import concentration:Over seventy percent of acrylic resins and specialty additives enter through Colombo Port, exposing margins to rupee depreciation against dollar-denominated supplier contracts.
- Solvent inventory stranding:SLSI's phased VOC reduction timeline leaves distributors with obsolete alkyd stock that cannot clear remaining shelf life before compliance deadlines.
- Technical service scarcity:Industrial coating specification requires certified applicator networks that remain underdeveloped outside the Western Province, limiting machinery and automotive segment penetration.
Strategic Opportunities
- Northern and Eastern Province recovery:Post-conflict reconstruction in Jaffna and Trincomalee generates demand for protective infrastructure coatings with limited established supplier presence.
- Powder coating convergence:Electrostatic application technology paired with domestic metal fabrication growth opens factory-applied finishes for appliance and furniture exports.
- Retail channel digitization:E-commerce platforms are capturing specification-grade decorative paint orders from Colombo-based architects, bypassing traditional distributor markups.
Industry Challenges
- Formulation chemist scarcity:Sri Lankan universities produce limited polymer science graduates capable of accelerating water-based product development cycles under SLSI deadlines.
- Quality certification bottlenecks:SLSI testing laboratory capacity constraints extend product approval timelines, delaying commercial launches and locking working capital in pre-certified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sri Lanka Paints and Coatings Market |
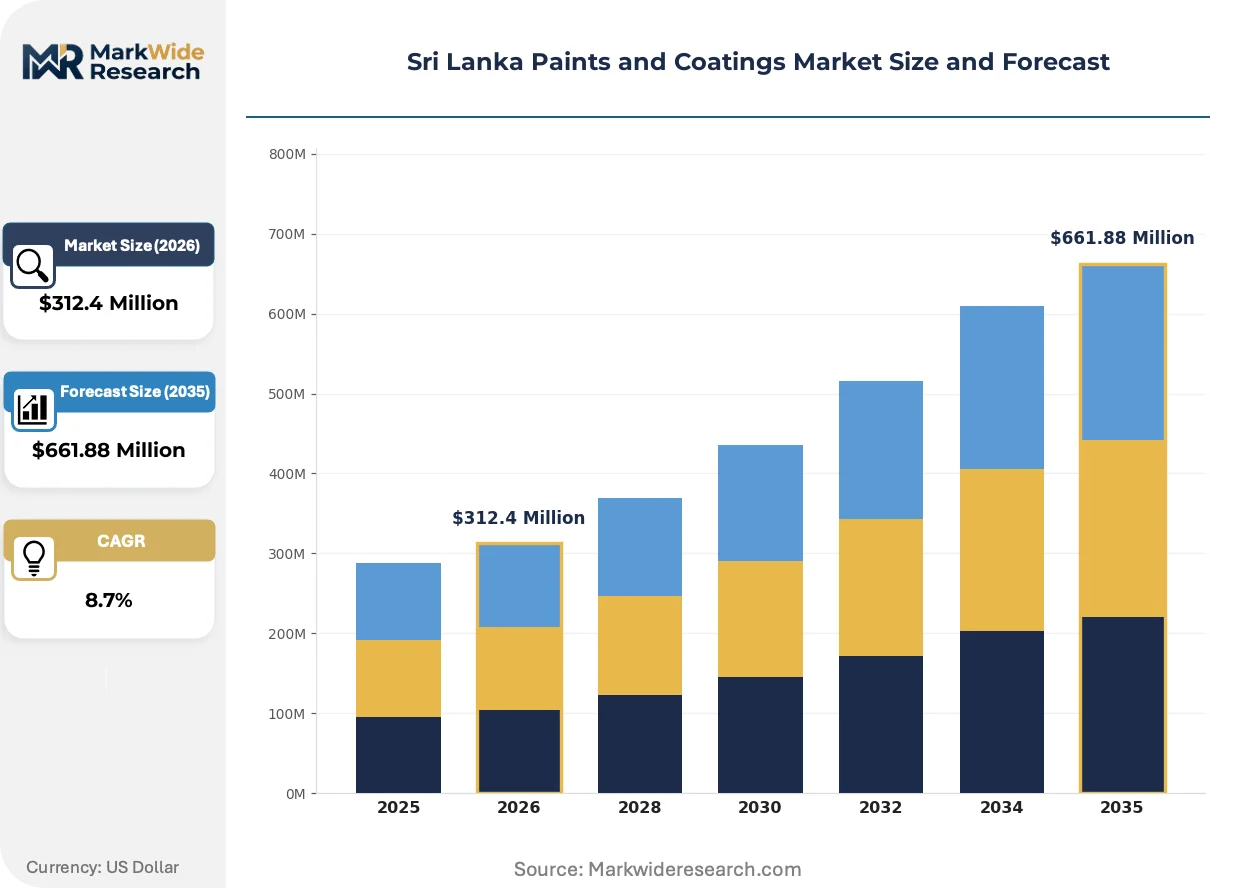
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural Paints, Industrial Coatings, Protective Coatings, Special Effect Coatings End User: Construction, Automotive, Marine, Consumer Goods Formulation: Water-Based, Solvent-Based, Powder Coatings, UV-Curable Coatings Application: Interior, Exterior, Heavy-Duty, Decorative |
| Companies Covered | Jotun, Kansai Paint Co Ltd, Akzo Nobel NV, Lankem Robbialac, Royal Paints Lanka (Pvt) Ltd, Asian Paints, The Sherwin-Williams Company, PPG Industries Inc, Nippon Paint Holdings Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sri Lanka Paints and Coatings Market Evolving Landscape
Reformulation chemistry and application technology are converging to compress product development cycles and expand performance boundaries for Sri Lankan manufacturers. Three distinct vectors are reshaping how coatings are specified, produced, and applied across the island's construction and industrial segments.
Water-borne acrylic-urethane hybrid technology is collapsing the performance gap between low-VOC architectural grades and traditional solvent-based durability standards. Colombo-based commercial contractors are specifying these systems for high-traffic interior applications previously reserved for alkyd enamels. The shift is compressing SKU portfolios as manufacturers consolidate around multi-substrate compatible formulations.
SLSI's phased alignment with ISO 14001 environmental management protocols is mandating documented lifecycle assessment for coatings entering public infrastructure tenders. Domestic producers must now maintain third-party verified carbon footprint data from resin sourcing through application. Industrial coatings for port machinery and power generation equipment face the most immediate compliance pressure due to state-owned buyer procurement rules.
Architect specification behavior is fragmenting across project scale, with boutique Colombo design firms demanding custom color-matching services and rapid sample turnaround while volume residential developers standardize on pre-curated palettes. Large-scale housing projects in the Western Province are bypassing traditional distributor networks through direct manufacturer relationships that bundle technical support with volume pricing.
Sri Lanka Paints and Coatings Market Segmentation
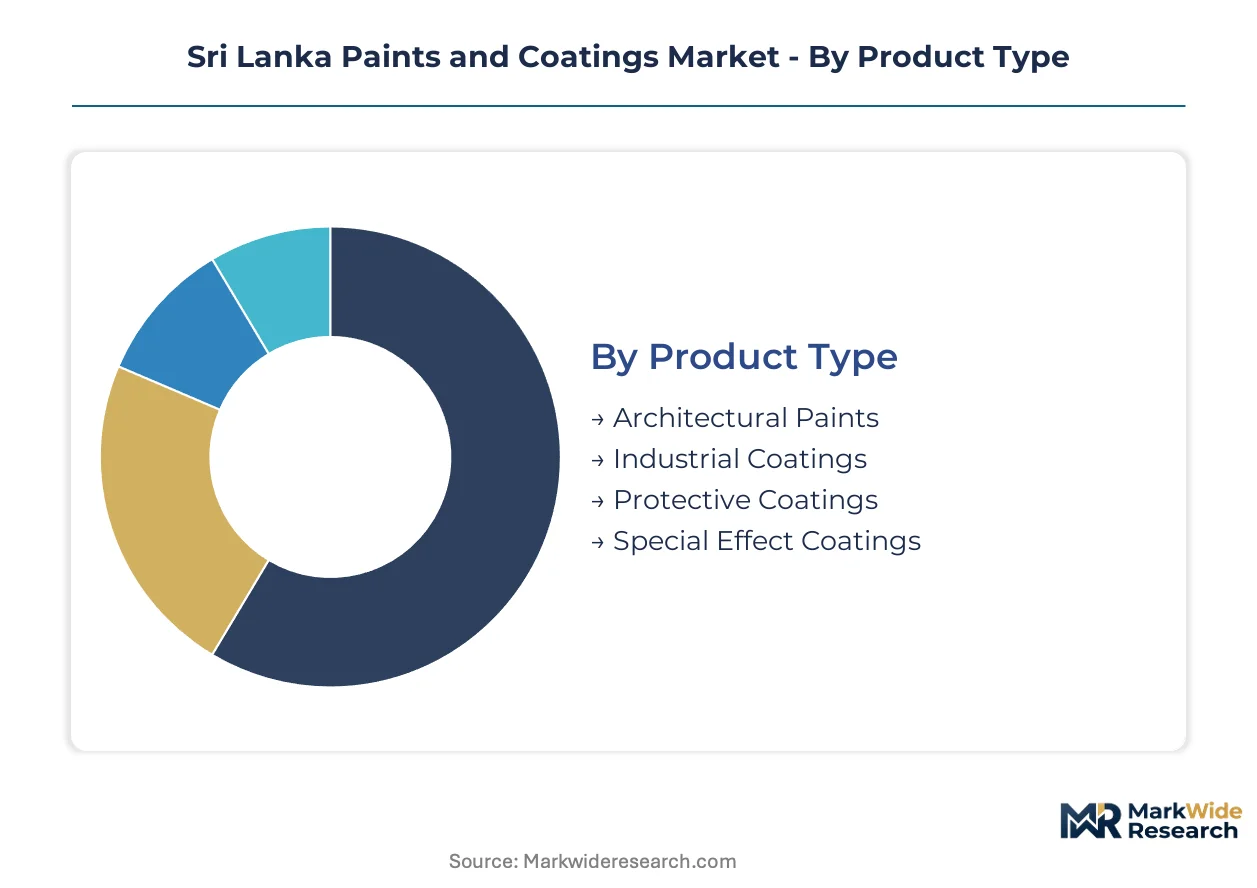
Segmentation in Sri Lanka's paints and coatings market reveals how formulation chemistry, end-use specifications, and application environments create distinct competitive arenas. Understanding these divisions exposes where technical service intensity varies and where procurement power concentrates across the island's construction and industrial clusters.
Product Type:
After-sales service intensity varies sharply across product categories, with industrial and protective systems demanding on-site technical support while decorative lines rely on retail troubleshooting.
- Architectural Paints:Water-borne acrylic and alkyd formulations dominate residential and commercial building finishes. Demand clusters in Colombo's Western Province tower developments, where contractors specify certified low-VOC systems to meet SLSI procurement rules for public housing tenders.
- Industrial Coatings:Epoxy and polyurethane systems protect machinery, automotive components, and factory infrastructure. Jaffna and Trincomalee reconstruction projects are generating protective infrastructure demand with limited established applicator networks, constraining penetration.
- Protective Coatings:High-performance anti-corrosion films for bridges, ports, and power equipment. Sri Lanka's port expansion drives specification of marine-grade zinc-rich primers and fluoropolymer topcoats.
- Special Effect Coatings:Metallic, pearlescent, and textured decorative finishes for premium residential and hospitality interiors. Colombo boutique design firms drive custom color-matching and rapid sample turnaround requirements.
Architectural Paints holds the largest share; momentum sits with Industrial Coatings.
End User:
Cost tier stratification separates specification-grade projects with certified applicator requirements from mass-market retail purchases.
- Construction:Residential, commercial, and infrastructure building activity generates volume demand across decorative and protective categories. Western Province contractors are bundling technical support with direct manufacturer relationships to bypass distributor markups on large-scale housing developments.
- Automotive:OEM finishing and refinish coatings for vehicle assembly and repair. Technical service scarcity outside Colombo limits machinery and automotive segment penetration in peripheral provinces.
- Marine:Antifouling, deck, and superstructure coatings for commercial vessels and port infrastructure. Colombo waterfront projects specify systems from suppliers with marine coating expertise and local technical presence.
- Consumer Goods:Appliance, furniture, and general manufacturing finishes. Domestic metal fabrication growth is opening factory-applied powder coating opportunities for export-oriented producers.
Construction commands the dominant volume position; steepest expansion trajectory belongs to Marine applications.
Formulation:
Technology maturity curves separate established water-borne systems from emerging UV-curable platforms still seeking local applicator acceptance.
- Water-Based:Acrylic, polyurethane, and hybrid dispersions replacing solvent alternatives under SLSI VOC mandates. Colombo-based commercial contractors specify acrylic-urethane hybrids for high-traffic interiors previously reserved for alkyd enamels.
- Solvent-Based:Traditional alkyd and epoxy systems facing phased compliance deadlines. Distributors hold obsolete inventory that cannot clear remaining shelf life before SLSI enforcement dates.
- Powder Coatings:Thermoset epoxy and polyester powders applied electrostatically to metal substrates. Appliance and furniture export manufacturers are adopting these systems to eliminate solvent handling and reduce film thickness variability.
- UV-Curable Coatings:Rapid-curing acrylate formulations for wood, plastic, and specialized industrial substrates. Limited local UV application equipment constrains adoption outside a few Colombo-area industrial facilities.
Water-Based formulations hold the largest share; Powder Coatings is climbing the fastest.
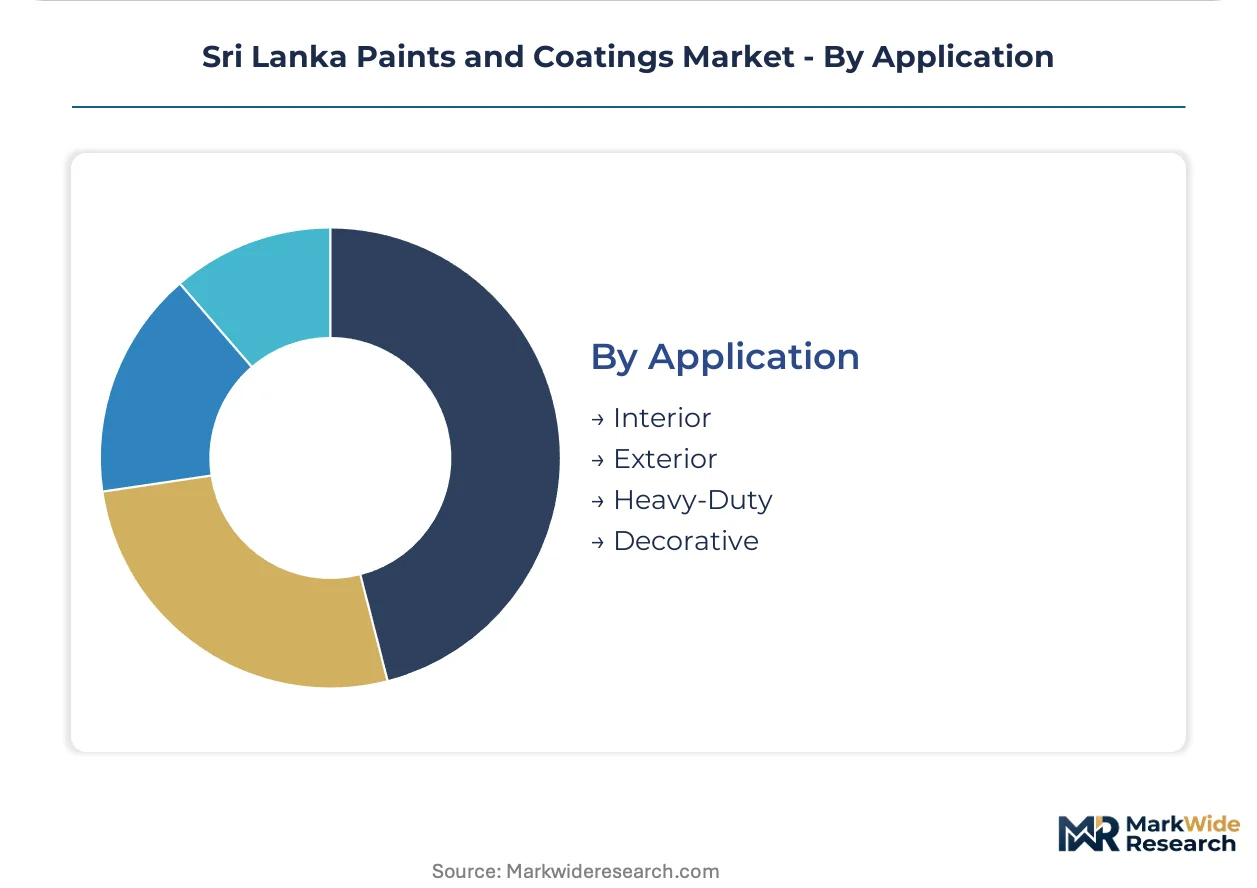
Application:
Geographic concentration patterns separate interior specification work in Colombo's commercial towers from exterior protective projects distributed across provincial infrastructure.
- Interior:Wall, ceiling, and trim finishes for residential and commercial enclosed spaces. Western Province residential developers standardize on pre-curated palettes while boutique architects demand custom color services.
- Exterior:Weather-resistant facades, roofs, and structural coatings exposed to tropical humidity and monsoon cycles. SLSI lifecycle assessment requirements for public infrastructure tenders favor documented durability guarantees.
- Heavy-Duty:Chemical-resistant, abrasion-proof industrial floors, tanks, and equipment. Northern and Eastern Province reconstruction generates demand with limited supplier technical service coverage.
- Decorative:Aesthetic finishes emphasizing color, texture, and visual effect over protective performance. E-commerce platforms are capturing specification-grade orders from Colombo-based architects, disrupting traditional distributor channels.
Interior applications hold the largest share; Heavy-Duty coatings are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Province contractors consume marine-grade and decorative finishes at intensities unmatched elsewhere, while Northern and Eastern Province buyers prioritize protective infrastructure coatings with limited local technical support.
Western Province
Colombo's port expansion and residential tower development concentrate demand for certified low-VOC architectural systems. SLSI procurement rules for public housing tenders mandate documented environmental compliance. The Colombo waterfront cluster specifies marine-grade finishes from suppliers with established technical presence.
Central Province
Kandy's commercial construction generates specification-grade decorative demand with slower sample turnaround expectations than Colombo. The national standards body's testing laboratory constraints extend product approval timelines for regional distributors. Kandy-based contractors source primarily through Colombo-linked supply chains.
Southern Province
Galle and Matara hospitality developments drive premium special-effect finishes for boutique interiors. Sri Lanka Standards Institution VOC ceilings apply uniformly, forcing identical reformulation investments as Western Province manufacturers. The Galle Fort restoration cluster sources protective coatings through Colombo-based importers.
Northern Province
Jaffna post-conflict reconstruction generates protective infrastructure coating demand with severely limited established applicator networks. SLSI environmental discharge permits affect coating plant siting decisions in formerly restricted zones. Jaffna-based contractors face extended lead times due to Colombo-centric distribution patterns.
Eastern Province
Trincomalee port and power infrastructure projects specify heavy-duty anti-corrosion systems with sparse local technical service coverage. The central environmental regulator enforces industrial discharge standards that raise capital requirements for regional production facilities. The Trincomalee industrial zone attracts powder coating investment linked to metal fabrication export growth.
Sri Lanka Paints and Coatings Market Competitive Landscape
Capability concentration sits with multinational specialists possessing marine coating expertise and rapid reformulation capacity; scale advantage sits with domestic distributors maintaining broad retail channel presence. The vendor base separates into three strategic archetypes: global technical specialists, regional brand licensors, and domestic volume distributors. Competitive moves center on direct manufacturer relationships with large-scale developers and e-commerce platform partnerships that bypass traditional distributor markups.
Among global technical specialists, Jotun and Akzo Nobel NV occupy positions anchored by marine-grade formulation heritage and premium decorative color-matching infrastructure. Lankem Robbialac exemplifies the domestic volume distributor archetype with established retail channel penetration. These three entities represent distinct competitive vectors: technical specification capture, premium brand positioning, and mass-market accessibility.
| Leading Market Players |
|---|
| Jotun |
| Kansai Paint Co Ltd |
| Akzo Nobel NV |
| Lankem Robbialac |
| Royal Paints Lanka (Pvt) Ltd |
| Asian Paints |
| The Sherwin-Williams Company |
| PPG Industries Inc |
| Nippon Paint Holdings Co Ltd |
| Others |
Value Network & Pricing Analysis
Rupee depreciation against dollar-denominated supplier contracts determines both pricing tier spreads and supply chain shape across Sri Lanka's paints and coatings sector. Currency volatility compresses margins on imported acrylic resins while forcing domestic manufacturers to absorb cost shocks or risk volume erosion in price-sensitive construction segments.
Pricing Analysis
Western Province contractors pay premiums of fifteen to twenty percent over Northern Province buyers for identical certified low-VOC formulations due to Colombo's concentration of specification-grade demand and technical service bundling. Three-tier pricing structure across premium, standard, and economy levels separates SLSI-certified infrastructure grades from retail decorative lines and unbranded commodity offerings. Pricing pressure stems from titanium dioxide import costs and currency hedging expenses that manufacturers cannot fully pass through to public tender bidders. Residential developers in mass-market housing projects exhibit highest price sensitivity, while marine coating specifications for port infrastructure demonstrate lowest elasticity due to performance guarantees and applicator certification requirements.
Supply Chain Analysis
Export-control restrictions on advanced resin synthesis technology from European and Japanese suppliers limit domestic formulation capabilities and compel reliance on licensed production arrangements. Raw material flows concentrate through India, China, and Thailand for acrylic monomers, specialty additives, and pigment intermediates. Sri Lankan manufacturers draw from Colombo Port for over seventy percent of binder feedstocks, creating single-source vulnerability to shipping disruptions and customs clearance delays. Distribution runs through manufacturer-direct relationships with large Western Province developers alongside traditional distributor networks serving retail channels in peripheral provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sri Lanka's paints and coatings market demands substitution defense against ceramic tile and polished concrete surface finishes that increasingly displace decorative coatings in premium commercial interiors. Incumbents must demonstrate performance differentiation that justifies applied cost premiums over these emerging alternatives.
For Market Incumbents: Entrench SLSI certification leadership by accelerating in-house resin synthesis capabilities before phased VOC deadlines eliminate solvent-based inventory options. Defend channel position through direct technical service relationships with Colombo-based contractors specifying marine-grade and heavy-duty protective systems. Backward integration into water-borne polymer production reduces rupee exposure and locks supply security for infrastructure tender participation.
For New Entrants and Emerging Players: Establish a beachhead in Jaffna and Trincomalee reconstruction corridors where protective coating demand outruns established applicator network coverage. Target powder coating convergence opportunities linked to Eastern Province metal fabrication export growth. Bypass traditional distributor markups through e-commerce platform partnerships capturing specification-grade orders from Colombo architects.
For Investors and Strategic Acquirers: SLSI's alignment with ISO 14001 environmental management protocols reshapes the acquisition landscape toward domestic manufacturers with verified lifecycle assessment capabilities and public infrastructure tender eligibility. Five-to-ten year viability favors targets possessing rapid reformulation chemistry and Western Province logistics infrastructure. Watch for SLSI testing laboratory capacity expansion as signal of accelerated product approval timelines that unlock working capital efficiency.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Borne Resin Synthesis Investment | Captures SLSI compliance premium while reducing dollar-denominated import dependency. |
| Direct Contractor Relationship Program | Bypasses distributor markups on Western Province tower developments and infrastructure tenders. |
| Powder Coating Application Technology Partnership | Opens factory-applied finishes for appliance and furniture export manufacturers. |
| Northern Province Technical Service Expansion | Addresses protective coating demand in Jaffna reconstruction with limited established presence. |
| E-Commerce Platform Integration | Captures specification-grade decorative orders from Colombo architects disrupting traditional channels. |
Research Methodology
Desk research of SLSI regulatory filings, customs import records, and construction sector procurement databases preceded structured interviews with plant managers at domestic coating facilities, procurement leads at Western Province developers, distribution channel partners, and technical R&D directors overseeing water-borne formulation transitions. Primary fieldwork with Colombo-based contractors and Jaffna reconstruction project officers validated secondary estimates of regional demand concentration and applicator network coverage gaps. Bottom-up volume modeling across formulation types triangulated against top-down construction expenditure forecasts.
Assumptions held SLSI VOC enforcement timelines and rupee-dollar exchange rate bands within historical volatility ranges while varying infrastructure investment trajectories and titanium dioxide substitution research outcomes. Segmentation dimensions modeled include formulation chemistry, end-use industry, application environment, and provincial demand cluster. CAGRs were derived from weighted scenario outputs across the projection horizon. Industry-specific inputs encompassed construction sector cement consumption correlations and port cargo throughput indices proxying marine coating demand.
Stress conditions across currency depreciation severity, SLSI deadline acceleration, and raw material import disruption duration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factor weightings. Material shifts in SLSI alignment with international environmental standards or sustained rupee depletion beyond stress-test thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Global Anti-Formaldehyde Paint Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Italy Industrial Wood Coatings Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Paint Curing Lamp Market
Paints & Coatings
Bahrain Paints and Coatings Market
Paints & Coatings
Paint and Coating Stripper Market
Paints & Coatings
Epoxy Paint Thinner Market
Paints & Coatings
Faux Paints and Coatings Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Fluorescent Paint Market
Paints & Coatings
India Floor Coatings Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Global Decorative Paints and Coatings Market
Paints & Coatings
Iraq Paints and Coatings Market