
 Topcoat Market | 2026-2036
Topcoat Market Size, Share, and Industry Trends Forecast 2026-2036
Topcoat Market Analytics
Multi-source resin procurement is realigning how topcoat formulators manage supply security and cost predictability. PPG Industries leverages captive acrylic resin production in North America to buffer against petrochemical volatility. Akzo Nobel anchors its European network through long-term supplier partnerships for specialty isocyanates used in polyurethane systems.
A topcoat constitutes the final protective and decorative film applied over primer or basecoat layers, typically formulated at 25–60% solids content with binders, pigments, and functional additives that cure through oxidation, polymerization, or UV irradiation to deliver gloss retention, chemical resistance, and weatherability. Water-based formulations now lead volume growth in automotive and furniture applications as manufacturers phase out high-VOC solvent systems. Epoxy topcoats dominate industrial equipment protection where chemical and abrasion resistance command premium pricing, while UV-cured systems represent the fastest-expanding formulation category for high-speed furniture finishing lines.
EPA emissions standards and REACH substance restrictions are forcing reformulation investments across solvent-based product lines, with China's MEE enforcing comparable VOC caps on industrial coatings. ECHA classification updates for isocyanates are reshaping hazard communication and personal protective equipment requirements in European manufacturing plants. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and redundant certification costs.
Market Dynamics
Water-based polyurethane systems are displacing solvent-borne formulations across automotive OEM refinishing as EPA and REACH VOC limits tighten, forcing capital reallocation toward resin synthesis and application equipment retrofitting.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving isocyanate classifications are accelerating water-based polyurethane adoption in German automotive plants seeking compliance certainty.
- Industrial equipment manufacturing:China's MEE enforcement of VOC caps on metal finishing operations is redirecting specification demand toward epoxy and water-based systems.
- UV irradiation curing:Furniture manufacturers in Italy and Poland are installing high-speed UV lines to compress finishing cycles and reduce energy consumption.
Market Restraints
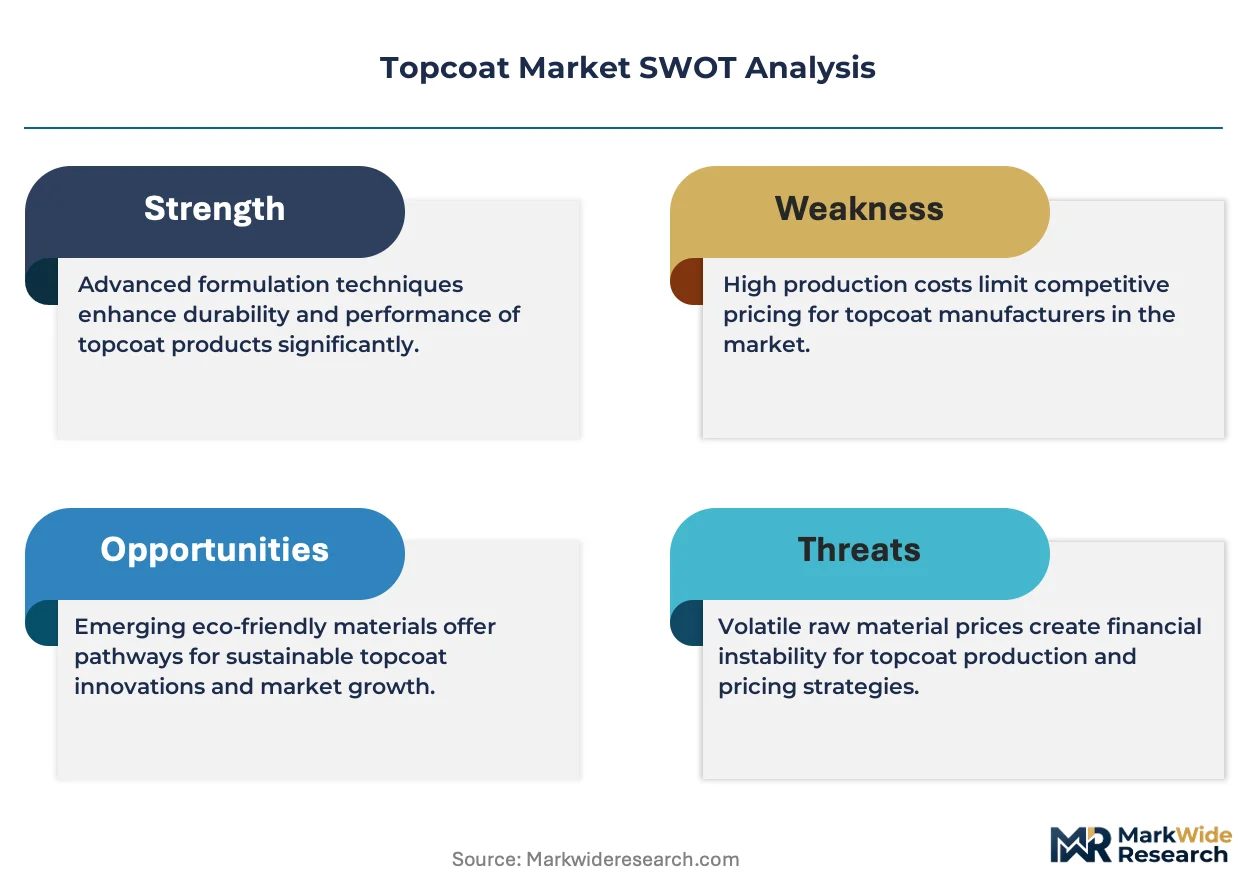
- Petrochemical feedstock volatility:Acrylic and isocyanate monomer costs fluctuate with crude oil derivatives, compressing margin predictability for independent formulators lacking captive resin supply.
- Specialty isocyanate supply concentration:European polyurethane topcoat producers depend on a limited supplier base for aliphatic isocyanates, creating vulnerability to force majeure disruptions.
- Water-based performance gaps:Solvent-borne systems retain superior humidity resistance and substrate adhesion in certain industrial climates, slowing full substitution.
Strategic Opportunities
- India's PLI scheme for manufacturing:Industrial equipment producers qualifying for production-linked incentives are expanding domestic coating demand as localized supply chains mature.
- UV-cured wood finishing:High-speed furniture lines in Vietnam and Indonesia represent underpenetrated capacity for low-VOC, instant-cure topcoat systems.
- Automotive refinishing consolidation:Collision repair networks in Brazil and Mexico are centralizing procurement, creating volume concentration for compliant water-based system suppliers.
Industry Challenges
- Formulation chemist scarcity:Water-based polyurethane development requires hybrid expertise in colloid stability and film formation that outpaces current technical training pipelines.
- Application equipment retrofit costs:Body shops and industrial finishers face capital outlays for spray booth ventilation and gun systems compatible with higher-viscosity water-based materials.
- Cross-jurisdiction certification complexity:Divergent VOC test methods between EPA Method 24 and EU Directive 2004/42/EC force redundant product validation for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Topcoat Market |
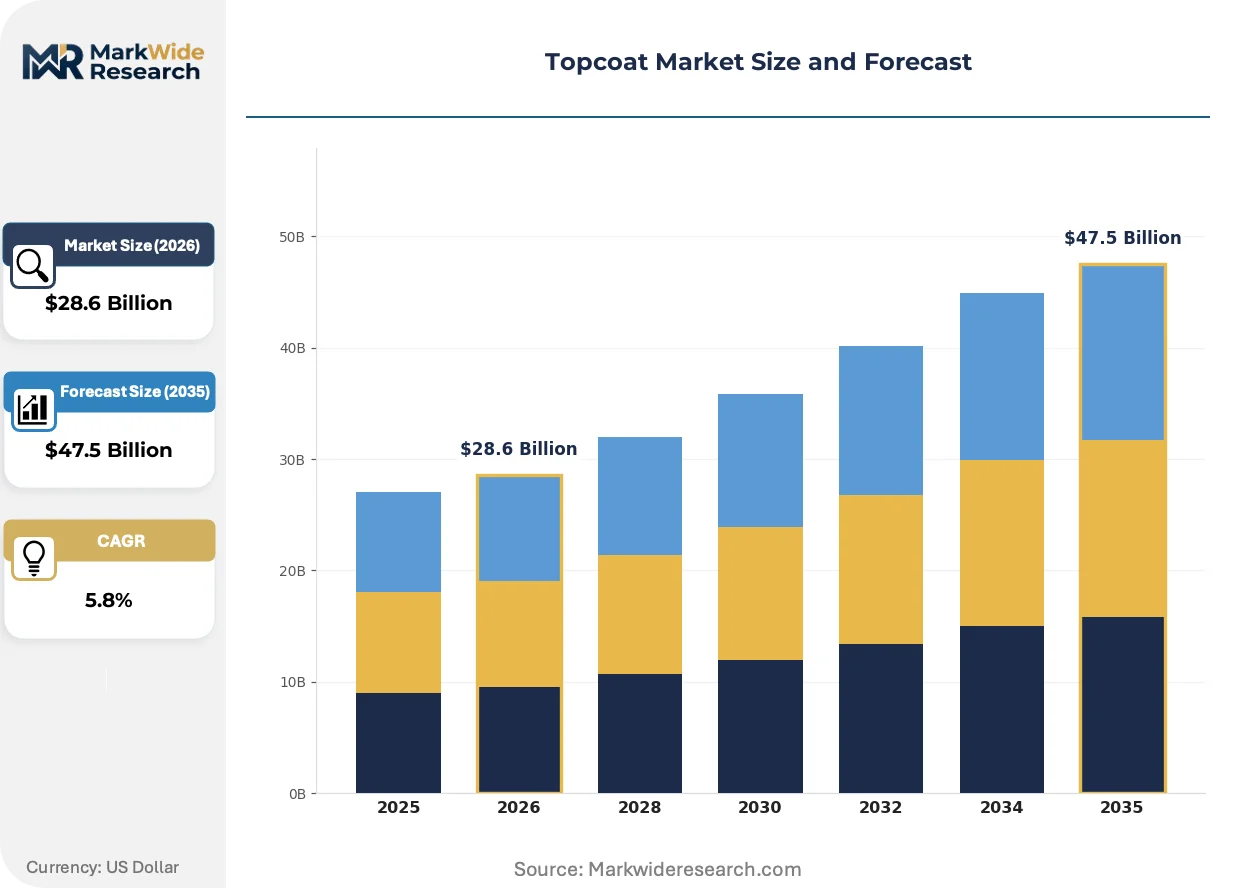
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Acrylic, Polyurethane, Epoxy, Alkyd Application: Automotive, Furniture, Aerospace, Industrial Equipment Formulation: Water-based, Solvent-based, Naturally Derived, UV-Cured End User: Manufacturers, Contractors, DIY Enthusiasts, Distributors |
| Companies Covered | BASF SE, Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Axalta Coating Systems, Hempel A/S, RPM International, DuPont, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Topcoat Market Evolving Landscape
Digital color matching platforms and self-healing polymer chemistries are converging with regulatory pressure to redefine performance expectations and procurement workflows across automotive and industrial verticals.
Photoinitiator-free UV LED curing systems are decentralizing high-speed finishing operations by eliminating mercury lamp infrastructure and thermal substrate damage risks. Italian furniture manufacturers are retrofitting compact LED arrays into existing production lines. This technology is decentralizing capital requirements for UV capability, enabling mid-tier finishers to compete with integrated producers on throughput and energy efficiency.
EPA's updated National Emission Standards for Hazardous Air Pollutants (NESHAP) for surface coating operations are mandating add-on control devices or reformulation to lower HAP content. Automotive refinishing shops in California and Texas face accelerated compliance timelines. Collision repair networks are consolidating preferred supplier agreements with water-based system vendors to standardize inventory and training investments.
Subscription-based coating supply contracts are replacing spot purchasing among multi-site industrial equipment manufacturers. German and Japanese automotive OEMs are piloting total-cost-per-part agreements that bundle material, application support, and waste management. This model is most visible in North American heavy machinery production, where procurement teams prioritize predictable unit economics over lowest material cost.
Topcoat Market Segmentation
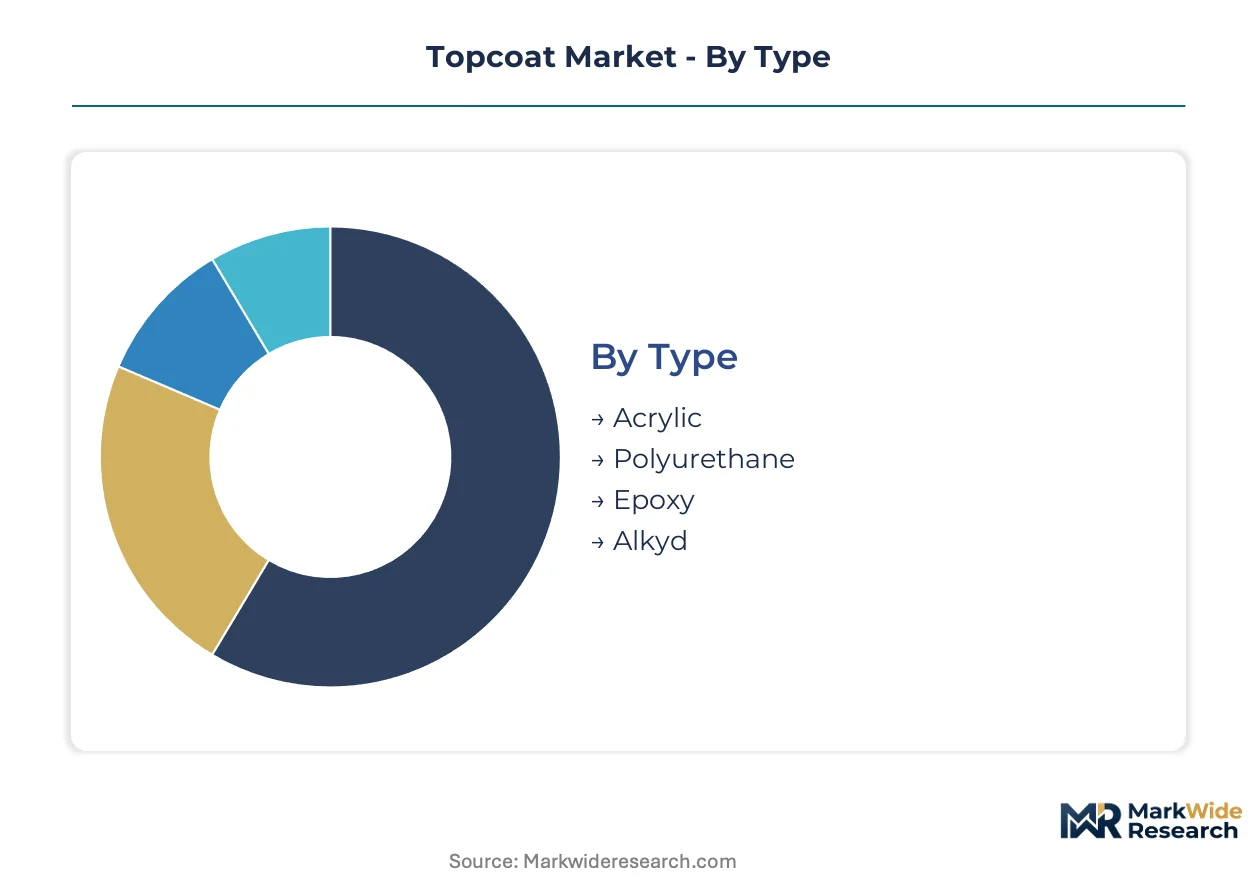
Topcoat specification varies sharply across end-use durability requirements and regulatory exposure. Formulators align resin chemistry and curing mechanisms with substrate demands, VOC constraints, and application infrastructure. Understanding segment boundaries clarifies where capital deployment and technical differentiation yield sustainable margin.
Type:
Capital intensity escalates with specialty monomer requirements and curing complexity.
- Polyurethane:Aliphatic isocyanate crosslinking delivers exceptional gloss retention and UV stability for exterior automotive and aerospace exposure. German automotive OEMs specify water-based polyurethane systems as ECHA isocyanate classifications tighten hazard communication protocols. REACH compliance investments dominate formulation priorities.
- Acrylic:Thermoplastic or thermoset acrylic binders offer rapid dry-to-touch properties and color clarity for mass-market automotive refinishing. PPG Industries anchors North American supply through captive resin production buffering petrochemical volatility. Demand concentrates in collision repair networks consolidating procurement.
- Epoxy:Amine-cured bisphenol systems dominate industrial equipment protection where chemical and abrasion resistance command premium positioning.
- Alkyd:Oxidative-cure oil-modified polyesters retain cost advantage in decorative and light-duty industrial maintenance.
Most installed capacity flows through Acrylic. Expansion is steepest in Polyurethane.
Application:
Volume distribution tracks manufacturing output intensity and coating specification sophistication.
- Automotive:OEM and refinishing operations demand matched color systems with crash-damage repairability and weathering warranties. Water-based polyurethane adoption accelerates in Germany and the United States as EPA and REACH VOC limits tighten. California and Texas collision repair networks face accelerated NESHAP compliance timelines.
- Industrial Equipment:Heavy machinery, agricultural implements, and material handling systems require chemical-resistant films in aggressive operating environments. China's MEE enforces VOC caps redirecting specification toward epoxy and water-based alternatives. Metal finishing operations in Shanghai and Guangzhou drive reformulation demand.
- Furniture:Decorative and protective films for wood substrates emphasize scratch resistance and aesthetic depth.
- Aerospace:Qualified product lists and stringent flame-smoke-toxicity standards restrict supplier participation to certified formulators.
Automotive commands the largest revenue pool. Industrial Equipment is gaining share fastest.
Formulation:
Margin structure diverges with raw material sourcing security and application equipment requirements.
- Water-based:Acrylic and polyurethane dispersions replace solvent systems where VOC regulations prohibit high-emission alternatives. China's MEE, Japan's Ministry of Environment, and South Korea's air quality standards enforce comparable industrial caps. Formulation chemists with hybrid colloid stability expertise command scarcity premiums.
- UV-Cured:Photoinitiator-free LED systems eliminate mercury lamp infrastructure and thermal damage risks. Italian furniture manufacturers retrofit compact LED arrays into existing lines. Vietnam and Indonesian wood finishing capacity remains underpenetrated for instant-cure systems.
- Solvent-based:Conventional high-solids and conventional solids retain performance advantages in humidity-critical climates.
- Naturally Derived:Bio-based binders from plant oils and agricultural byproducts address sustainability procurement criteria.
Water-based formulations carry the heaviest installed base. UV-Cured is climbing the fastest.
End User:
Procurement sophistication scales with technical specification authority and volume concentration.
- Manufacturers:Industrial equipment and automotive OEMs specify coating systems with embedded application support and waste management. German and Japanese automotive producers pilot total-cost-per-part agreements bundling material and technical service. North American heavy machinery procurement prioritizes predictable unit economics.
- Contractors:Collision repair networks and industrial finishing shops face capital outlays for spray booth ventilation and gun systems compatible with higher-viscosity water-based materials. Brazil and Mexico refinishing consolidation creates volume concentration for compliant system suppliers.
- Distributors:Inventory pooling and technical service provision bridge formulator and applicator relationships.
- DIY Enthusiasts:Retail-format products emphasize ease-of-application and color-matching simplicity.
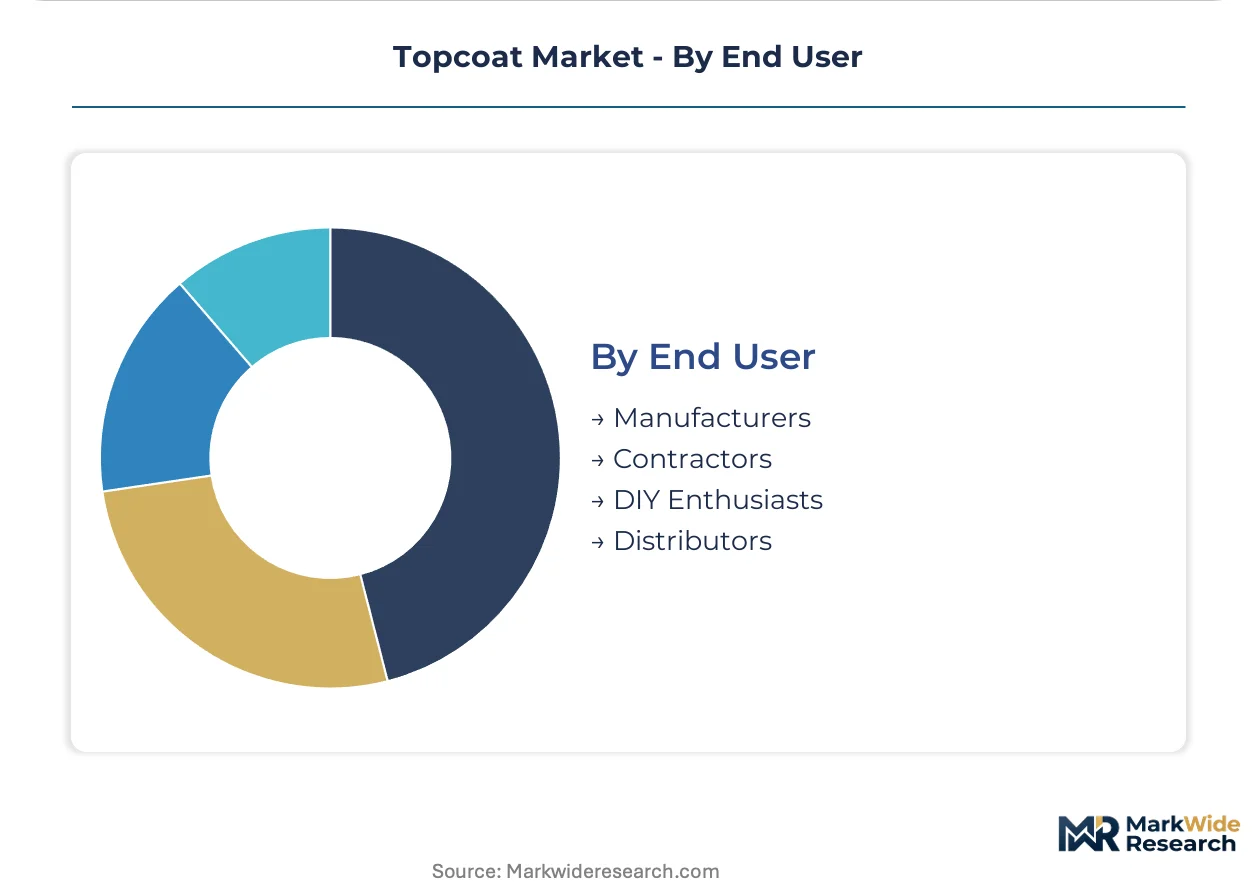
Manufacturers anchor the value chain. Contractors are expanding procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive OEM refinishing clusters in Stuttgart and Munich drive premium polyurethane specification. Water-based system adoption accelerates as ECHA tightens isocyanate classifications. REACH compliance investments dominate formulation priorities across Bavarian and Baden-Württemberg production facilities.
Germany
Automotive OEM refinishing operations in Stuttgart and Munich specify aliphatic polyurethane systems for exterior durability. ECHA's evolving isocyanate classifications accelerate water-based adoption as hazard communication protocols tighten. Collision repair networks in Bavaria consolidate procurement around compliant system vendors to standardize training investments.
United States
EPA NESHAP enforcement targets surface coating operations in California and Texas with accelerated compliance timelines. Automotive refinishing shops face capital outlays for spray booth ventilation compatible with higher-viscosity water-based materials. PPG Industries leverages captive acrylic resin production in North America to buffer petrochemical feedstock volatility.
China
Industrial equipment manufacturers in Shanghai and Guangzhou confront MEE enforcement of VOC caps on metal finishing operations. Metal finishing demand redirects toward epoxy and water-based alternatives as air quality standards tighten. Formulation chemists with hybrid colloid stability expertise command scarcity premiums in Yangtze River Delta coating hubs.
Japan
Automotive OEMs and industrial equipment producers face Ministry of Environment directives comparable to EU VOC restrictions. Water-based polyurethane development concentrates in Nagoya and Osaka manufacturing corridors. Technical training pipelines struggle to supply sufficient formulation chemists with dispersion stability expertise.
India
Industrial equipment producers qualifying under the PLI scheme expand domestic coating demand as localized supply chains mature. Maharashtra and Gujarat manufacturing clusters attract reformulation investment from multinational system suppliers. Contract finishing networks in Chennai and Pune retrofit application equipment for water-based material compatibility.
Topcoat Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue UV-cured and bio-based formulation niches. The supplier base concentrates around resin-integrated formulators and specialty chemical distributors with technical service capabilities. Three archetypes dominate: captive resin producers buffering feedstock volatility, application-technology bundlers, and regional compliance specialists. Competitive moves center on backward integration into resin synthesis and strategic partnerships for specialty isocyanate security.
Within the captive supply tier, BASF SE and PPG Industries exemplify integrated producers controlling critical raw material streams. Akzo Nobel N.V. occupies a position among European formulators anchoring networks through long-term supplier partnerships. These three entities represent distinct strategic postures—German chemical conglomerate depth, North American automotive coating dominance, and Dutch-Belgian industrial specialization—without implying specific market share claims.
| Leading Market Players |
|---|
| BASF SE |
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Axalta Coating Systems |
| Hempel A/S |
| RPM International |
| DuPont |
| 3M |
| Others |
Value Network & Pricing Analysis
Water-based polyurethane formulation transitions simultaneously compress production economics and concentrate supply leverage among resin-integrated producers. PPG Industries' captive acrylic production in North America buffers petrochemical volatility that independent formulators cannot absorb, while Akzo Nobel's European isocyanate partnerships lock in specialty crosslinker access unavailable to spot-market buyers.
Pricing Analysis
Acrylic and isocyanate monomer cost pass-through from crude oil derivatives dominates pricing volatility for non-integrated formulators. Three-tier pricing structure across premium, standard, and economy levels separates aliphatic polyurethane systems from thermoplastic acrylics and oxidative-cure alkyds. Pricing pressure stems from REACH compliance investments and spray booth retrofit costs that collision repair networks attempt to push upstream. Independent contractors in Brazil and Mexico show highest price sensitivity; German automotive OEMs demonstrate lowest due to total-cost-per-part contracting.
Supply Chain Analysis
Reverse logistics for solvent recovery and waste treatment reshape distribution economics as EPA NESHAP and REACH substance restrictions tighten. Raw material concentration centers on Germany, the United States, and China for specialty isocyanates, acrylic resins, and epoxy hardeners. Supply chains draw from petrochemical feedstocks, aliphatic isocyanate monomers, and photoinitiator chemicals. Single-source vulnerability for European aliphatic isocyanates creates force majeure exposure. Distribution runs through certified system houses and direct OEM supply agreements bundling technical service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Specification demand is hardening toward water-based polyurethane systems with embedded compliance certification as ECHA isocyanate classifications tighten.
For Market Incumbents: Hedge petrochemical volatility through backward integration into acrylic resin synthesis or long-term isocyanate offtake agreements. Consolidate collision repair network procurement in Brazil and Mexico before regional compliance deadlines accelerate. Prioritize captive supply over spot-market sourcing as margin predictability erodes. For New Entrants and Emerging Players: Enter via UV-cured wood finishing in Vietnam and Indonesia where instant-cure capacity remains underpenetrated and application equipment retrofit costs exclude established solvent-system suppliers. Target mid-tier furniture manufacturers seeking photoinitiator-free LED systems without mercury lamp infrastructure. Lead with compact LED array retrofit packages that compress capital requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among regional compliance specialists with ECHA certification depth and water-based formulation libraries. Long-term viability favors suppliers with hybrid colloid stability expertise and bundled service contracts over commodity resin traders. Monitor MEE enforcement intensity in Shanghai and Guangzhou metal finishing clusters as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | PPG Industries' captive acrylic production buffers petrochemical volatility unavailable to independent formulators. |
| Long-term Isocyanate Supply Partnerships | Akzo Nobel's European network anchors polyurethane system security against force majeure disruptions. |
| UV LED Retrofit Equipment Bundling | Italian furniture manufacturers adopt compact LED arrays that eliminate mercury lamp thermal damage risks. |
| Total-Cost-Per-Part Service Contracts | German automotive OEMs pilot subscription models bundling material, application support, and waste management. |
| Regional Compliance Certification Investment | ECHA isocyanate classification updates force hazard communication protocol investments that exclude undercapitalized competitors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged formulation chemists, automotive OEM procurement leads, collision repair network operators, and industrial equipment plant managers. Secondary validation drew from EPA NESHAP filings, ECHA substance restriction updates, MEE enforcement bulletins, and customs trade data for acrylic and isocyanate monomer flows. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Comparable-period anchoring linked projection assumptions to historical VOC regulatory phase-in patterns across EPA Method 24 and EU Directive 2004/42/EC implementation timelines. The analytical framework modeled resin chemistry type, curing mechanism, end-use durability tier, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level volume trajectories adjusted for compliance-driven substitution elasticity and application equipment retrofit lag.
Inputs from regulatory filings and trade databases were available through the study window; gaps in real-time collision repair network procurement data introduce uncertainty bands around contractor segment forecasts. Forecasts reflect documented assumptions about MEE enforcement intensity and ECHA classification timelines. Practitioners should monitor REACH substance restriction update cadence and UV LED equipment cost curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Cold Gas Spray Coating Market
Coatings
Global Sputter Coatings Market
Coatings
Cool Roof Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
Global Solar Panel Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Color-Shifting Coating Market
Coatings
Electron Beam Curable Coating Market
Coatings
Asia-Pacific Radiation Curable Coatings Market
Coatings
Silicone Coating Market
Coatings
Anti-Microbial Powder Coatings Market
Coatings
Global Hydrophobic Coating Market
Coatings
Global Nanocoatings Market
Coatings
Vacuum Coating Machine Market
Coatings
South America Thermal Spray Market
Coatings
Global Water-Based Coatings Market