
 Anti Soiling Coating Market | 2026-2036
Anti Soiling Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Anti Soiling Coating Market Outlook
Buyer concentration in the renewable energy sector is shifting as utility-scale solar developers consolidate procurement decisions across multi-gigawatt portfolios. BASF SE leverages its polymer chemistry depth to supply hydrophobic formulations for photovoltaic glass substrates. PPG Industries anchors its position through automotive glass partnerships that demand optical clarity under soiling stress. Jotun competes in marine and offshore segments where salt deposition accelerates coating degradation cycles.
Anti soiling coatings are thin-film surface treatments, typically 2–10 microns in thickness, engineered with fluoropolymer or silica-based chemistries to minimize particulate adhesion and enable rain-wash cleaning. Their primary industrial purpose is maintaining optical transmittance on exposed surfaces while reducing manual maintenance frequency. Hydrophobic coatings lead product type revenue due to established supply chains in automotive and solar applications, while self-cleaning formulations represent the fastest-expanding category as photocatalytic titanium dioxide integration matures. Spray coating dominates technology deployment for field-applied solar installations, whereas chemical vapor deposition commands premium positioning in precision electronics and aerospace surface protection.
EPA regulations under the Toxic Substances Control Act constrain perfluorinated compound content in U.S.-manufactured coatings, while REACH authorization requirements in Europe restrict specific persistent organic pollutants in imported formulations. China's MEE enforces volatile organic compound emission standards that reshape local manufacturing processes and raw material sourcing. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate reformulation costs and certify products for differentiated market access.
Market Dynamics
Utility-scale solar developers are consolidating procurement decisions across multi-gigawatt portfolios, compressing supplier margins while demanding extended performance warranties on hydrophobic and photocatalytic formulations.
Growth Catalysts
- Photocatalytic titanium dioxide integration:Self-cleaning formulations leveraging TiO2 activation under UV exposure are maturing, enabling rain-wash maintenance reduction on photovoltaic glass in high-dust climates.
- China's domestic solar scaling:Local manufacturers are seeking durable surface protection solutions as installation volumes accelerate, creating concentrated demand for fluoropolymer-based thin films.
- REACH authorization tightening:Persistent organic pollutant restrictions in Europe are accelerating reformulation toward silica-based alternatives, opening technical differentiation for compliant suppliers.
Market Restraints
- Fluoropolymer feedstock concentration:Perfluorinated compound precursors face supply constraints as EPA Toxic Substances Control Act enforcement tightens permissible content in U.S.-manufactured coatings.
- Technical durability gaps:Salt deposition in marine environments accelerates coating degradation cycles, limiting warranty periods for offshore wind and coastal solar installations.
- Reformulation cost burden:Divergent MEE volatile organic compound standards in China versus REACH requirements force parallel product lines, elevating working capital intensity.
Strategic Opportunities
- India's solar park expansion:Central Electricity Authority targets and PLI scheme incentives are creating procurement windows for anti-soiling coating suppliers in arid western states.
- Electronics precision protection:Chemical vapor deposition technology is penetrating aerospace and semiconductor manufacturing, commanding premium positioning beyond field-applied solar markets.
- Automotive glass partnerships:Optical clarity requirements under soiling stress are extending coating specifications from OEM windshields into autonomous sensor housings.
Industry Challenges
- Photocatalytic formulation expertise scarcity:Titanium dioxide integration at scale requires specialized surface chemistry talent that coating manufacturers struggle to recruit.
- Multi-jurisdiction certification timelines:Parallel EPA, REACH, and MEE compliance testing extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti Soiling Coating Market |
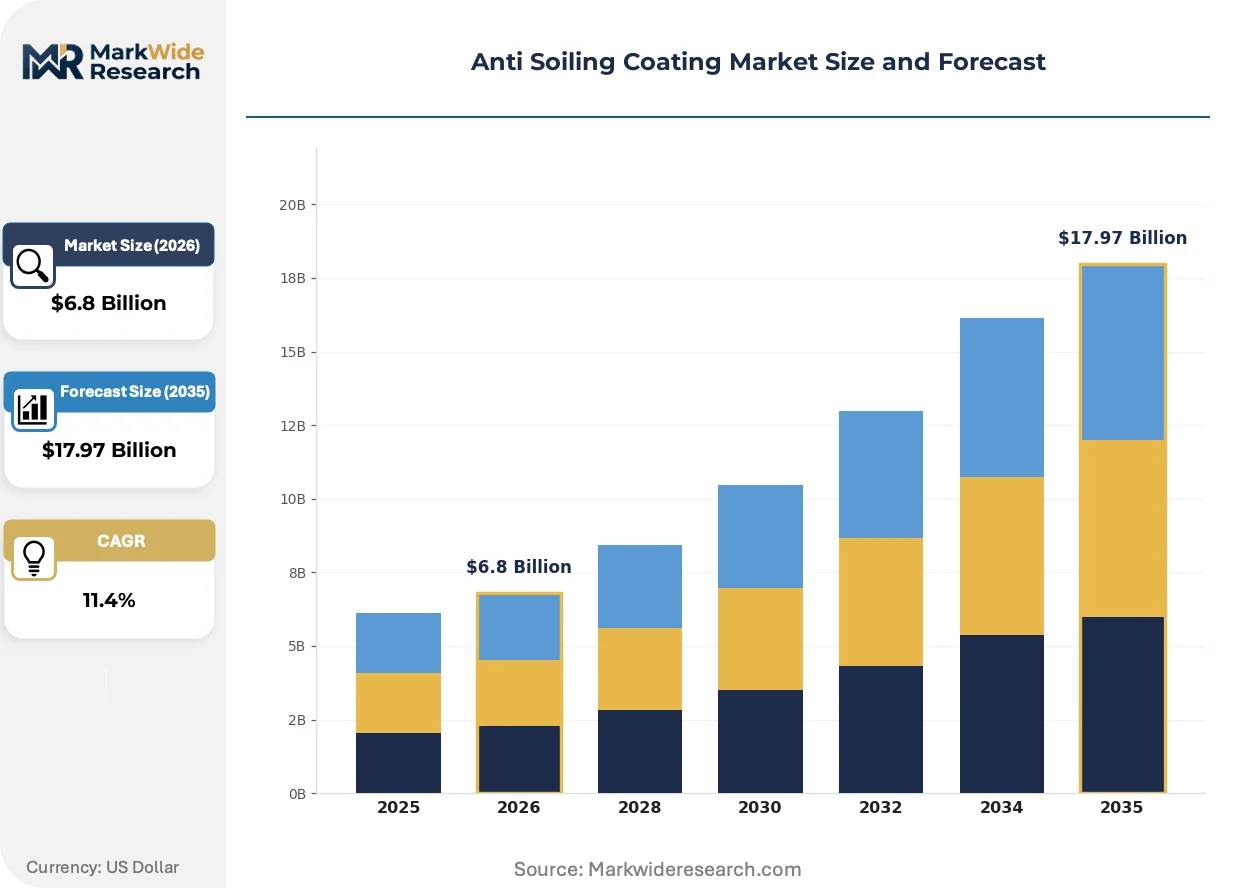
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrophobic Coatings, Hydrophilic Coatings, Self-Cleaning Coatings, UV-Resistant Coatings Application: Building Facades, Automotive Glass, Solar Panels, Textile Surfaces End User: Construction Industry, Automotive Sector, Renewable Energy Firms, Textile Manufacturers Technology: Chemical Vapor Deposition, Sol-Gel Process, Spray Coating, Dip Coating |
| Companies Covered | BASF SE, PPG Industries Inc., Akzo Nobel N.V., Nippon Paint Marine Coatings Co. Ltd., Sherwin-Williams Company, Jotun, 3M Company, Hempel A/S, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti Soiling Coating Market Strategic Shifts
Coating chemistry is converging with surface engineering disciplines, blurring traditional boundaries between hydrophobic, oleophobic, and photocatalytic functionalities while regulatory pressure accelerates material substitution cycles.
Hybrid fluoropolymer-silica nanocomposite technology is unifying water-repellent and self-cleaning properties within single-layer architectures. Solar panel manufacturers in the Middle East and Australia are piloting these formulations to reduce soiling-induced output degradation. The technology is unifying previously separate coating application steps, compressing field installation time and reducing labor cost structures for utility-scale developers.
EPA enforcement under the Toxic Substances Control Act is constraining long-chain perfluorinated compound content in U.S.-manufactured formulations. Coating producers are accelerating silica-based and short-chain fluoropolymer alternatives to maintain market access. Photovoltaic glass suppliers serving the U.S. utility sector are reformulating supply agreements to specify compliant chemistries ahead of 2027 enforcement milestones.
Integrated coating-application service contracts are displacing standalone product sales in utility-scale solar procurement. Engineering-procurement-construction firms are bundling surface treatment into turnkey installation packages, compressing direct manufacturer-buyer relationships. This model is most visible in Saudi Arabia and the UAE, where gigawatt-scale project developers demand single-point accountability for performance warranties spanning 25-year asset lifetimes.
Anti Soiling Coating Market Segmentation
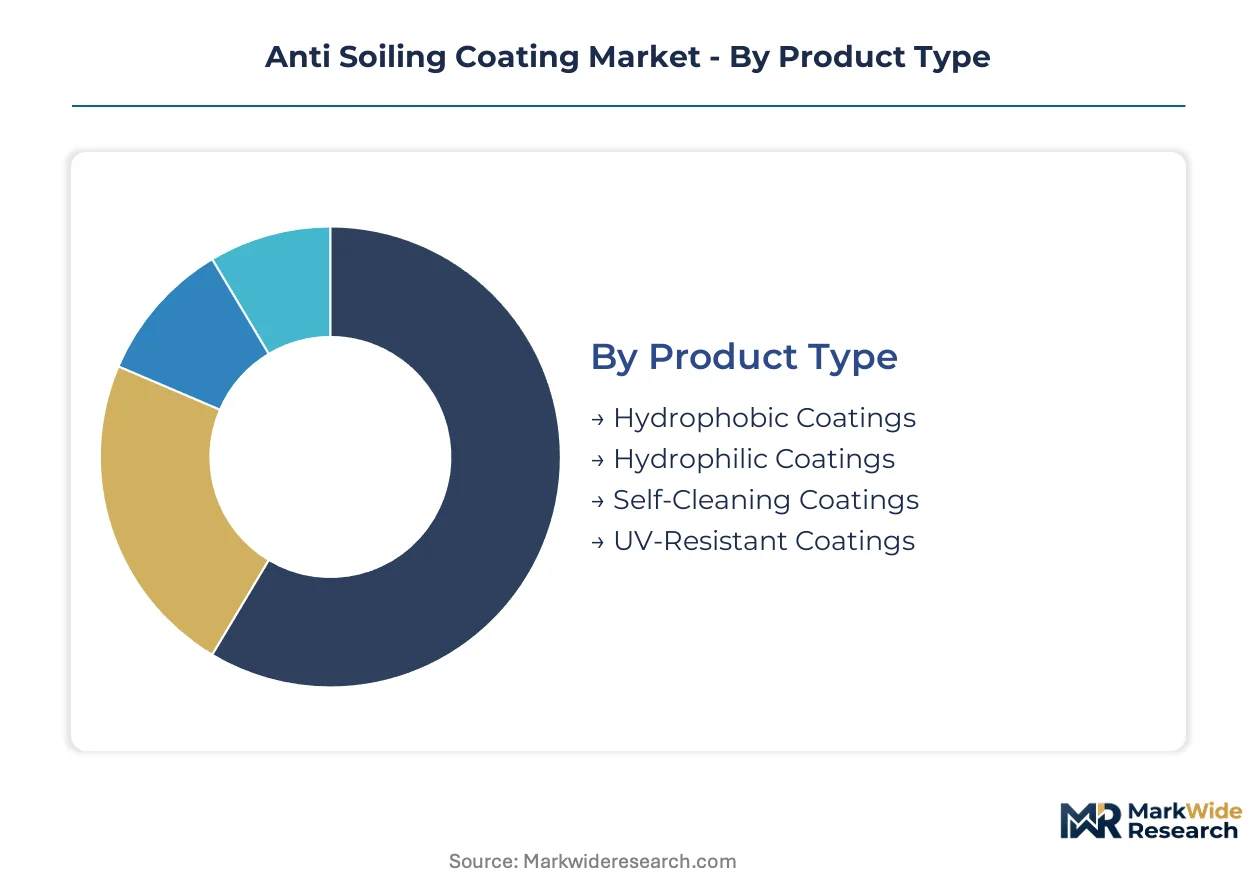
Anti-soiling coating procurement varies sharply by performance requirement and regulatory exposure. Segmentation reveals where certification burdens concentrate and which technical specifications command premium positioning across solar, automotive, and construction verticals.
Product Type:
REACH authorization and EPA Toxic Substances Control Act enforcement divide this category by reformulation burden, with fluoropolymer-dependent segments facing steeper compliance costs than silica-based alternatives.
- Hydrophobic Coatings:Fluoropolymer or silicone-based formulations repel water and particulate matter through low surface energy. Solar panel manufacturers in China and the Middle East specify these for utility-scale arrays where manual cleaning costs erode project returns. REACH restrictions on long-chain perfluorinated compounds are forcing suppliers toward short-chain alternatives.
- Self-Cleaning Coatings:Photocatalytic titanium dioxide integration enables UV-activated decomposition of organic soiling. Renewable energy firms in Australia and Saudi Arabia pilot these formulations to eliminate labor-intensive maintenance in high-dust climates. Technical talent scarcity constrains scale-up.
- Hydrophilic Coatings:Silica-based chemistries attract water to form uniform sheets that wash away debris. Preferred in automotive OEM specifications where optical clarity regulations apply.
- UV-Resistant Coatings:Absorber-stabilized formulations protect underlying substrates from photodegradation. Deployed in aerospace and marine applications where extended asset lifetimes justify material cost.
Hydrophobic coatings sit at the top of the volume ranking, with self-cleaning formulations climbing the fastest.
Application:
Field-applied segments compete on installation speed and labor substitution, while precision-manufactured applications prioritize optical specification and warranty duration.
- Solar Panels:Photovoltaic glass substrates demand coatings maintaining transmittance above 90% after years of soiling exposure. China's MEE volatile organic compound standards and India's Central Electricity Authority procurement guidelines shape formulation choices for suppliers targeting these markets.
- Automotive Glass:Windshield and sensor housing applications require oleophobic-hydrophobic hybrid performance under highway debris and hydrocarbon exposure. OEM specifications increasingly extend to autonomous vehicle LiDAR enclosures.
- Building Facades:Architectural glass and cladding treatments balance aesthetic maintenance reduction with structural load considerations. Urban air quality variations drive regional specification divergence.
- Textile Surfaces:Functional fabric treatments for outdoor and industrial apparel leverage sol-gel compatibility with fiber substrates. Performance warranty periods remain shorter than glass applications.
Solar panels command the largest application share, with automotive glass gaining share fastest as sensor integration accelerates.
End User:
Procurement consolidation patterns separate this category, with utility-scale developers bundling coatings into turnkey contracts while automotive buyers maintain direct supplier relationships.
- Renewable Energy Firms:Utility-scale solar developers consolidate multi-gigawatt procurement decisions, compressing supplier margins while demanding 25-year performance warranties. Saudi Arabia and UAE gigawatt projects increasingly specify integrated coating-application service contracts.
- Automotive Sector:Tier-1 glass suppliers and OEMs specify coatings for windshields, sunroofs, and emerging sensor housings. Optical clarity under soiling stress drives qualification protocols.
- Construction Industry:Commercial facade contractors and architectural specifiers select coatings based on regional climate exposure and maintenance access economics.
- Textile Manufacturers:Technical apparel and industrial fabric producers integrate anti-soiling functionality into performance product lines.
Renewable energy firms represent the dominant end-user segment, with automotive sector procurement expanding most quickly.
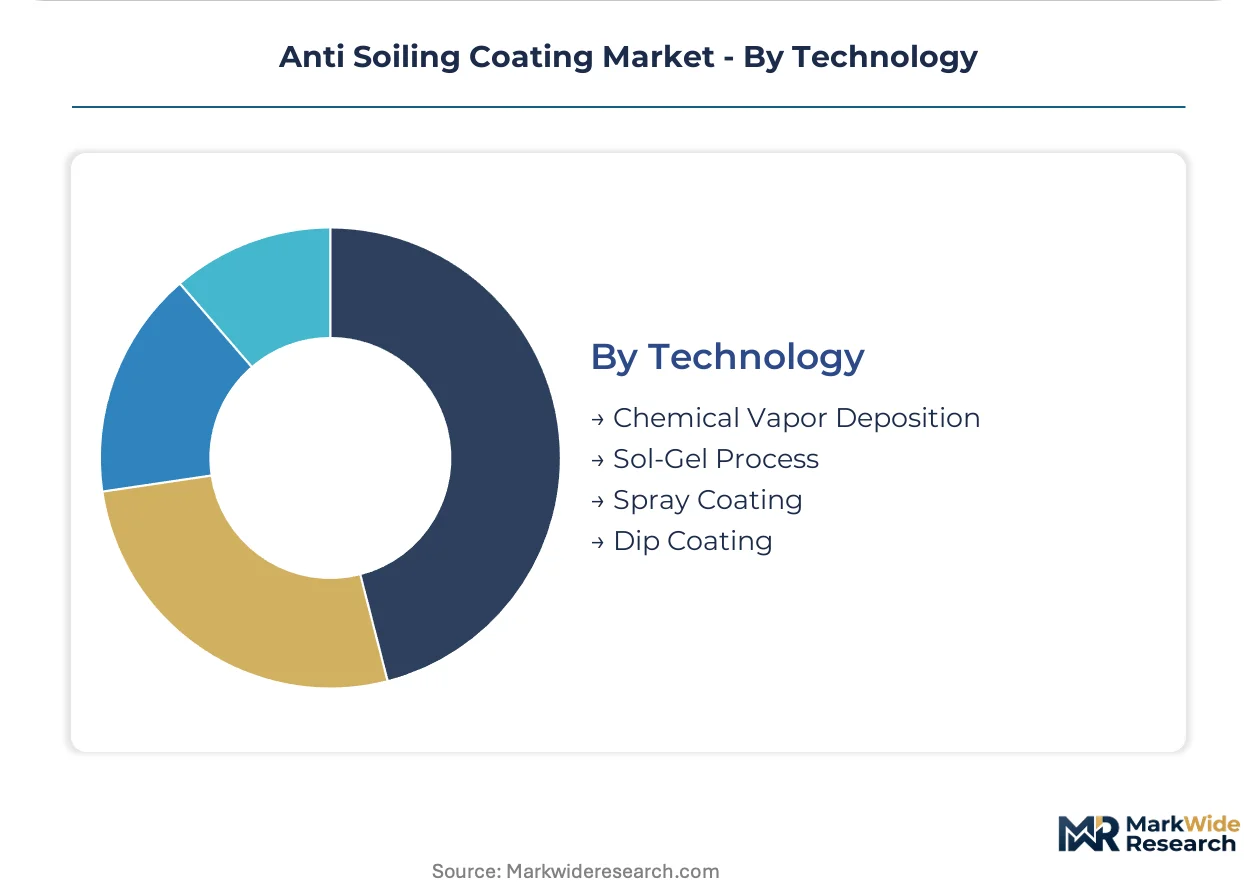
Technology:
Capital intensity and throughput economics stratify this category, with batch precision processes commanding premiums over continuous field application methods.
- Spray Coating:Field-deployed application dominates utility-scale solar installations, enabling rapid coverage of existing panel arrays. Labor cost structures and weather window constraints shape equipment investment decisions.
- Chemical Vapor Deposition:Vacuum-based precision deposition commands premium positioning in semiconductor and aerospace surface protection, where nanometer-scale uniformity determines performance.
- Sol-Gel Process:Wet chemical synthesis enables dip and spin coating of complex geometries at moderate capital cost. Preferred for textile and small-format glass applications.
- Dip Coating:Immersion-based application suits high-volume continuous processing of standardized substrates. Common in automotive glass manufacturing lines.
Spray coating leads by deployment volume, with chemical vapor deposition showing the steepest expansion trajectory in precision electronics manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surface chemists and polymer engineers cluster in industrial corridors near photovoltaic manufacturing zones and automotive glass production centers. Their geographic concentration shapes regional formulation capabilities and regulatory response speeds.
China
Domestic solar panel manufacturers in Jiangsu and Zhejiang provinces drive concentrated demand for fluoropolymer-based thin films as installation volumes accelerate. MEE volatile organic compound emission standards reshape local manufacturing processes and raw material sourcing patterns. The Yangtze River Delta hosts coating application service providers bundling surface treatment into turnkey utility-scale installation contracts.
United States
Utility-scale solar developers in Texas and California consolidate multi-gigawatt procurement decisions, compressing supplier margins while demanding extended performance warranties. EPA enforcement under the Toxic Substances Control Act constrains perfluorinated compound content in domestically manufactured formulations. Photovoltaic glass suppliers serving southwestern utility sectors reformulate supply agreements to specify compliant chemistries ahead of enforcement milestones.
Germany
Automotive OEMs and Tier-1 glass suppliers in Baden-Württemberg specify coatings for windshields and emerging autonomous sensor housings. REACH authorization requirements restrict specific persistent organic pollutants in imported formulations, accelerating reformulation toward silica-based alternatives. The Stuttgart industrial corridor anchors optical clarity qualification protocols under soiling stress conditions.
Saudi Arabia
Gigawatt-scale project developers in the Kingdom demand single-point accountability for performance warranties spanning 25-year asset lifetimes. SFDA chemical safety standards intersect with procurement guidelines from the national renewable energy program. Integrated coating-application service contracts displace standalone product sales in utility-scale solar procurement across the Eastern Province solar clusters.
India
Central Electricity Authority targets and PLI scheme incentives create procurement windows for anti-soiling coating suppliers in arid western states. BIS certification requirements and state-level solar park regulations shape qualification timelines for foreign suppliers. Gujarat and Rajasthan host concentrated solar park development where dust accumulation drives specification of hydrophobic and photocatalytic formulations.
Anti Soiling Coating Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and application technology vectors. The vendor base stratifies into three tiers: integrated chemical majors with polymer research depth, coating specialists with sector-specific expertise, and regional application service providers. Dominant competitive moves include backward integration into fluoropolymer feedstock production and strategic partnerships with photovoltaic glass manufacturers to secure specification in OEM supply chains.
Among diversified chemical majors, BASF SE and Covestro AG occupy positions anchored by polymer chemistry research infrastructure and multi-sector formulation portfolios. PPG Industries Inc. exemplifies the coating specialist archetype with established automotive glass partnerships. Jotun represents marine and offshore segment concentration where salt deposition accelerates coating degradation cycles. These three companies illustrate how competitive positioning diverges by end-use specialization rather than geographic footprint alone.
| Leading Market Players |
|---|
| BASF SE |
| PPG Industries Inc. |
| Akzo Nobel N.V. |
| Nippon Paint Marine Coatings Co. Ltd. |
| Sherwin-Williams Company |
| Jotun |
| 3M Company |
| Hempel A/S |
| Covestro AG |
| Others |
Value Chain & Pricing Dynamics
REACH authorization requirements gate qualified supply for European market access while compressing margins on legacy fluoropolymer formulations that fail compliance thresholds. This regulatory filter simultaneously elevates premium-tier pricing for silica-based alternatives and forces parallel product line investments that strain working capital across supplier tiers.
Pricing Analysis
The bundled-versus-unbundled service split separates project-based coating-application contracts from standalone chemical sales across utility-scale solar procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—REACH-compliant silica formulations command top positioning, short-chain fluoropolymers occupy mid-tier, and legacy chemistries face cost compression. Pricing pressure stems from procurement consolidation among multi-gigawatt renewable energy developers. Renewable energy firms exhibit highest price sensitivity due to levelized cost of energy calculations, while aerospace semiconductor buyers prioritize optical specification over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese fluoropolymer precursor production that feeds global coating formulation networks. Manufacturing gravity centers on China, Germany, and the United States for differentiated chemistries. Raw material dependencies span titanium dioxide for photocatalytic grades, fluorinated feedstocks for hydrophobic formulations, and silica nanoparticles for REACH-compliant alternatives. Supply chain risk concentrates in tariff exposure on Chinese chemical imports into Western markets. Distribution runs through photovoltaic glass manufacturers and engineering-procurement-construction firms that bundle surface treatment into turnkey installation packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in anti-soiling coatings rests on reformulation cost-down curves as silica-based chemistries scale and premium-tier self-cleaning formulations capture share from commodity hydrophobic alternatives.
For Market Incumbents: Anticipate REACH enforcement tightening by accelerating backward integration into silica nanoparticle supply and securing photocatalytic formulation talent pools before scarcity intensifies. Defensive moves center on locking multi-year specification agreements with Tier-1 photovoltaic glass manufacturers and investing in chemical vapor deposition capacity for precision electronics diversification. Regulatory shift toward perfluorinated compound restrictions in multiple jurisdictions threatens legacy product lines. For New Entrants and Emerging Players: The price-point gap between premium photocatalytic coatings and economy hydrophobic alternatives creates entry space for hybrid fluoropolymer-silica nanocomposite offerings. White-space targets concentrate on India's arid western states under PLI scheme procurement windows and chemical vapor deposition services for aerospace semiconductor manufacturing. A service-led go-to-market bundling application with formulation supply bypasses entrenched direct-sales relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional coating-application service providers because procurement consolidation among utility-scale developers favors single-point accountability vendors. Long-term viability across a decade horizon favors specialists with photocatalytic expertise and multi-jurisdiction certification capabilities. Watch for inflection in Saudi Arabia and UAE gigawatt project tender specifications mandating integrated service contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Feedstock | REACH compliance secures European market access while reducing reformulation cost exposure. |
| Photocatalytic Formulation Scale-Up | TiO2 integration capability addresses talent scarcity constraining self-cleaning coating expansion. |
| Integrated Service Contract Positioning | Turnkey bundling captures procurement consolidation in Saudi and UAE gigawatt solar clusters. |
| Chemical Vapor Deposition Capacity Addition | Precision deposition technology penetrates aerospace semiconductor premium segments. |
| Multi-Jurisdiction Certification Investment | Parallel EPA, REACH, and MEE compliance compresses product launch cycles for qualified suppliers. |
Study Parameters
Bottom-up renewable energy procurement modeling reconciled against top-down chemical manufacturing tracking forms the analytical core of this study. Primary interviews with utility-scale solar developers, photovoltaic glass procurement leads, coating application service contractors, and polymer chemistry R&D directors combined with secondary validation from customs trade data, SEC 10-K filings of diversified chemical majors, MEE emission standard disclosures, and project development databases. Top-down and bottom-up triangulation cross-validates volume estimates against production capacity and end-use consumption patterns.
Historical trendline analysis of coating adoption rates across solar installation vintages informs the projection framework. Segmentation dimensions modeled include product chemistry tier, application technology, end-use industry vertical, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to disclosed procurement volumes and capacity expansion announcements. Industry-specific forecast inputs incorporate photovoltaic glass production forecasts and utility-scale solar pipeline data from arid-climate markets.
The model assumes a particular technology adoption path; alternative pathways for photocatalytic titanium dioxide integration at scale would alter the outlook. Forecasts reflect assumptions about REACH enforcement timelines, MEE standard implementation, and procurement consolidation trajectories among renewable energy developers. Specific risk factors include feedstock supply disruptions from fluoropolymer precursor constraints and divergence in regional regulatory stringency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Japan Automotive OEM Coatings Market
Coatings
Batters and Coatings Market
Coatings
Germany Protective Coatings Market
Coatings
Packaging Coatings Market
Coatings
Cladding Coatings Market
Coatings
Coated Casing Market
Coatings
Waterborne Automobile Coating Market
Coatings
Canada Automotive OEM Coatings Market
Coatings
Cold Gas Spray Coating Market
Coatings
Trim Coatings Market
Coatings
Conductive Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Protective Coatings Market
Coatings
Stain Resistant Coatings Market
Coatings
Anti-Graffiti Coatings Market
Coatings
Automotive Refinish Coatings Market