
 Middle East and Africa Orthopedic Biomaterial Market | 2026-2036
Middle East and Africa Orthopedic Biomaterial Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Orthopedic Biomaterial Market Foresight
Project finance requirements for manufacturing facilities is narrowing the field of viable competitors across the Middle East and Africa. DePuy Synthes leverages its established distribution infrastructure to sustain premium positioning in Gulf Cooperation Council states. Zimmer Biomet anchors its regional presence through specialized training partnerships with university hospitals in Cairo and Johannesburg. Stryker Corporation differentiates by controlling direct procurement channels with ministry-of-health buyers in Saudi Arabia and the UAE.
Orthopedic biomaterials comprise engineered substances—including calcium phosphate ceramics, bioactive glass formulations, and synthetic polymer matrices—designed to integrate with bone tissue and restore musculoskeletal function following trauma or degenerative disease. These materials must achieve specific porosity thresholds and degradation rates to permit osteoconduction while maintaining mechanical load-bearing capacity. Bone grafts and joint reconstruction products occupy the dominant revenue positions within the product type dimension, with synthetic materials representing the fastest-expanding margin pool as hospitals seek alternatives to autograft harvesting. Within applications, knee surgery and hip surgery generate the highest procedure volumes, while spine surgery commands premium pricing due to the complexity of intervertebral fusion constructs.
South Africa's Health Products Regulatory Authority, Saudi Arabia's Food and Drug Authority, and the UAE's Ministry of Health and Prevention collectively enforce biocompatibility ISO standards and clinical evidence requirements that determine market access timelines. These frameworks compel manufacturers to maintain localized regulatory affairs capabilities and in-country testing partnerships. Stakeholders must monitor how procurement centralization under Gulf national health insurance schemes reshapes pricing power and distributor relationships.
Market Dynamics
Hospital privatization across Gulf Cooperation Council states is channeling sovereign capital into orthopedic service lines, reshaping procurement relationships and compressing distributor margins as ministry-of-health buyers consolidate purchasing authority.
Growth Catalysts
- SFDA hospital privatization mandates:Saudi Arabia's Food and Drug Authority frameworks accelerate capital deployment into specialized orthopedic units, expanding addressable procedure volumes for implantable biomaterials.
- Ceramic-composite trauma implants:Tertiary hospitals in Johannesburg and Cape Town expand ceramic-composite adoption for load-bearing applications, displacing traditional metal fixation in complex fracture cases.
- ISO 10993 biocompatibility harmonization:Alignment between South Africa's Health Products Regulatory Authority and Gulf regulators streamlines multi-market registration pathways for synthetic bone graft substitutes.
Market Restraints
- Calcium phosphate raw material concentration:Synthesis-grade hydroxyapatite precursors concentrate among limited specialty chemical suppliers in Europe and East Asia, exposing manufacturers to input cost volatility and currency risk.
- MOHAP clinical evidence requirements:The UAE's Ministry of Health and Prevention mandates extended local follow-up data for permanent implantables, extending market access timelines beyond comparable jurisdictions.
- Autograft harvesting persistence:Cost-conscious public hospitals in Egypt and Nigeria continue prioritizing autologous bone grafts despite donor-site morbidity, limiting synthetic material penetration in price-sensitive segments.
Strategic Opportunities
- Ethiopia and Kenya orthopedic infrastructure:Underpenetrated East African markets present first-mover advantages as Chinese development finance funds hospital construction in Addis Ababa and Nairobi.
- 3D-printed patient-specific implants:Convergence of additive manufacturing with CT-based surgical planning enables custom porous titanium scaffolds for complex pelvic reconstructions in Gulf private hospitals.
- University hospital training partnerships:Specialized credentialing programs with Cairo and Johannesburg academic medical centers create captive demand channels and lock in procurement relationships.
Industry Challenges
- Biomaterials engineering talent scarcity:Osteoconductive surface modification expertise concentrates in North American and European research clusters, complicating localized R&D hiring in Middle East and Africa markets.
- Cleanroom manufacturing capex intensity:ISO 13485-certified production facilities for synthetic polymer matrices require capital deployment that exceeds mid-cap manufacturer balance sheet capacity.
- Multi-jurisdiction certification complexity:Divergent biocompatibility testing protocols between South Africa's Health Products Regulatory Authority and Saudi Arabia's Food and Drug Authority force redundant validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Orthopedic Biomaterial Market |
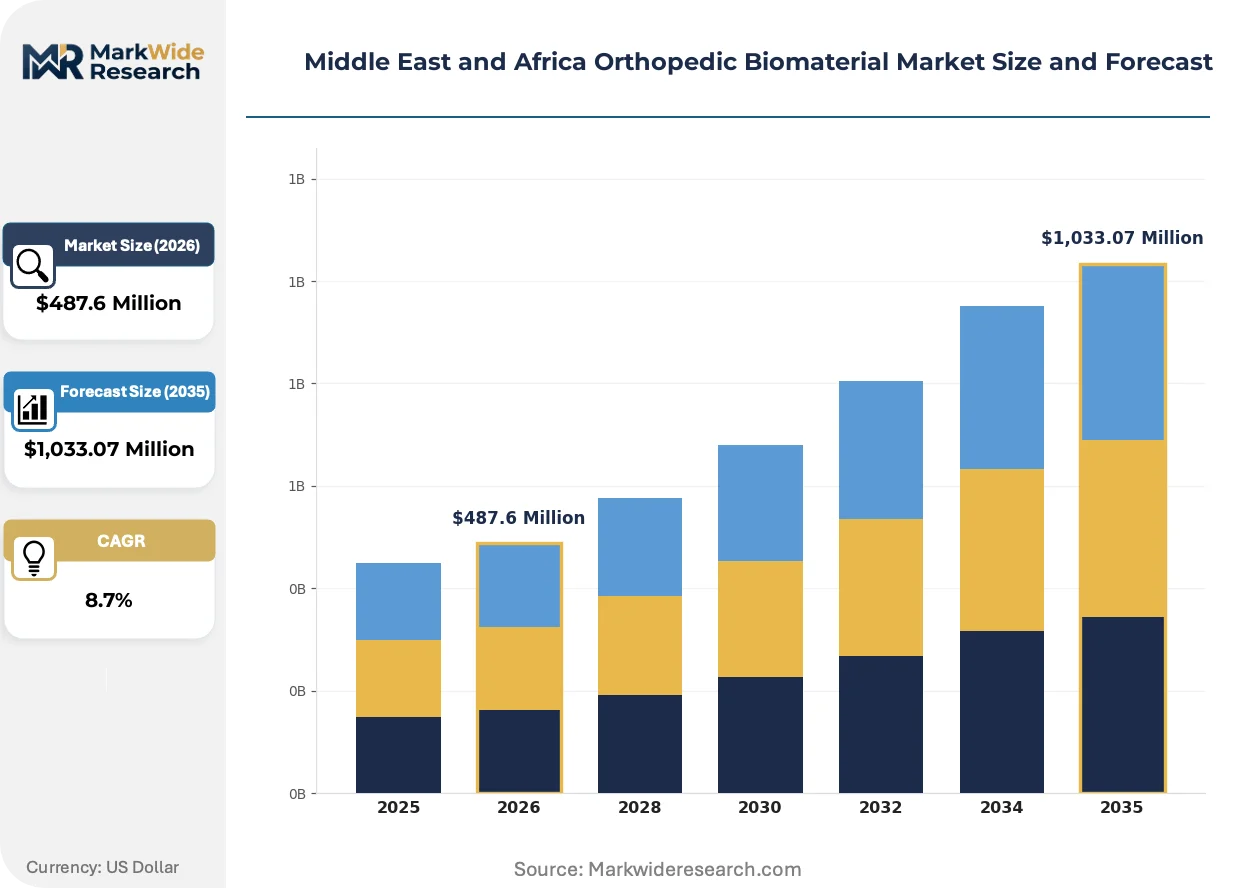
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Grafts, Cartilage Repair, Joint Reconstruction, Synthetic Materials Application: Knee Surgery, Hip Surgery, Spine Surgery, Trauma Surgery End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Research Institutions Material: Bioactive Glass, Polyurethane, Natural Polymers, Calcium Phosphate |
| Companies Covered | DePuy Synthes, Royal DSM, Zimmer Biomet, Evonik Industries, BASF SE, Stryker Corporation, Medtronic, Corbion N.V., Wright Medical, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Orthopedic Biomaterial Market Shifts & Advancements
Digital surgical planning platforms are compressing the traditional implant sizing workflow, while regulatory convergence across Gulf and African markets accelerates product registration strategies.
Patient-specific instrumentation derived from preoperative CT segmentation is virtualizing the conventional implant trialing process in Cairo and Riyadh university hospitals. Orthopedic departments at King Faisal Specialist Hospital and Ain Shams University Medical Center deploy these platforms for complex revision arthroplasty cases. This virtualization collapses operative time and inventory carrying costs while demanding real-time data infrastructure investments from implant suppliers.
South Africa's Health Products Regulatory Authority tightened permanent implantable documentation rules, compelling manufacturers to submit extended biocompatibility portfolios and local clinical follow-up data. The regulatory friction extends market access timelines for synthetic bone graft substitutes and ceramic-composite trauma implants. Multinational suppliers respond by establishing in-country regulatory affairs capabilities and Johannesburg-based testing partnerships.
Ministry-of-health procurement centralization under Saudi Arabia's NPHIES platform and UAE's mandatory health insurance schemes concentrates purchasing authority among fewer authorized buyers. Distributor networks face margin compression as direct manufacturer-to-hospital contracting displaces traditional multi-tier distribution in Dubai and Jeddah. This concentration is most visible in knee and hip reconstruction segments where procedure volumes justify dedicated supply agreements.
Middle East and Africa Orthopedic Biomaterial Market Segmentation
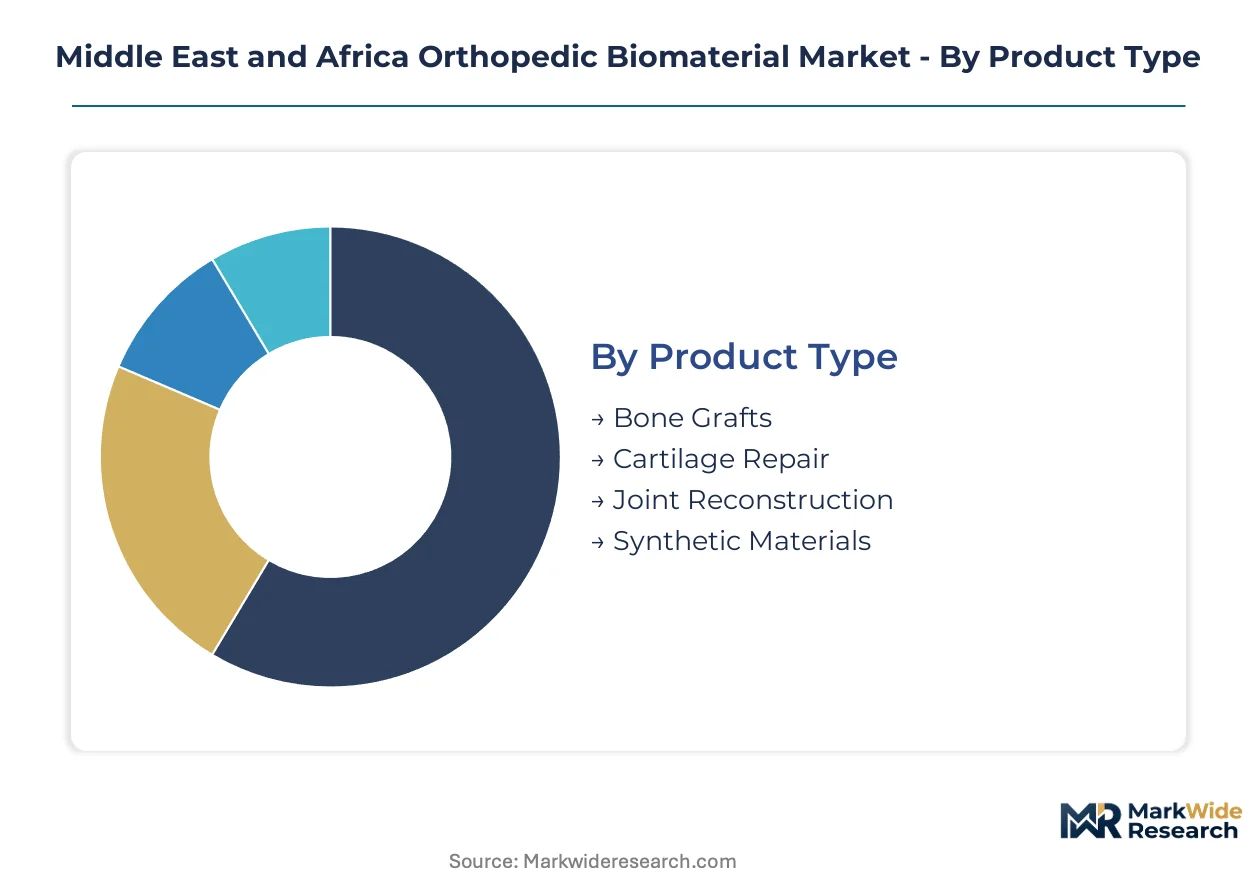
Orthopedic biomaterial purchasing patterns diver sharply across the Middle East and Africa based on procedural complexity, reimbursement pathways, and infrastructure maturity. Understanding these segment boundaries reveals where capital deployment concentrates and where synthetic substitutes displace traditional autograft harvesting.
Product Type:
Mature allograft systems coexist with emerging synthetic platforms across the region's surgical theaters, with adoption curves tracking hospital privatization timelines.
- Joint Reconstruction:Metallic and ceramic bearing surfaces for total knee and hip arthroplasty dominate procurement volumes in Saudi Arabia's NPHIES-integrated hospitals. Ministry-of-health centralization favors suppliers with direct contracting capability over fragmented distributor networks.
- Bone Grafts:Demineralized bone matrix and synthetic hydroxyapatite formulations serve spinal fusion and trauma void-filling applications. South Africa's Health Products Regulatory Authority tightened biocompatibility documentation requirements, extending registration timelines for novel osteoconductive scaffolds.
- Cartilage Repair:Autologous chondrocyte implantation and matrix-induced autologous chondrocyte implantation procedures concentrate in Cairo and Johannesburg university hospitals with cell processing infrastructure.
- Synthetic Materials:Polymer-ceramic composites and bioactive glass formulations gain traction as alternatives to autograft harvesting in Gulf private hospitals seeking reduced donor-site morbidity.
Joint Reconstruction retains volume leadership; Synthetic Materials holds the steepest expansion curve.
Application:
Procedure economics and pricing power vary dramatically across surgical sites, with spinal interventions commanding premium material specifications relative to extremity fixation.
- Spine Surgery:Intervertebral fusion cages and posterior instrumentation demand the highest biomaterial performance thresholds. The UAE's Ministry of Health and Prevention mandates extended local follow-up data for permanent spinal implantables, compressing margins through regulatory compliance costs.
- Knee Surgery:Primary and revision total knee arthroplasty generates the largest absolute procedure volumes across Saudi Arabia's privatizing hospital network. Ceramic-composite bearing surfaces displace conventional polyethylene in high-activity patient segments.
- Hip Surgery:Femoral stem fixation and acetabular component seating utilize cemented and cementless biomaterial interfaces. Tertiary centers in Cape Town and Johannesburg favor porous titanium coatings for osseointegration reliability.
- Trauma Surgery:Load-bearing plates, screws, and intramedullary nails deploy in fracture fixation across Egypt's public hospital system where cost constraints persist.
Knee Surgery captures the largest addressable procedure base; Spine Surgery maintains the highest revenue per intervention.
End User:
Capital intensity and procurement authority concentrate in hospital systems, while outpatient settings handle lower-acuity interventions with reduced biomaterial specifications.
- Hospitals:Tertiary academic medical centers and ministry-of-health facilities control the overwhelming share of joint reconstruction and spinal fusion volumes. King Faisal Specialist Hospital and Ain Shams University Medical Center anchor demand for patient-specific instrumentation and advanced ceramic composites.
- Orthopedic Clinics:Ambulatory surgery centers in Dubai and Riyadh perform arthroscopic procedures and minor fracture fixation with streamlined material inventories.
- Rehabilitation Centers:Post-surgical recovery facilities coordinate with implanting surgeons on weight-bearing protocols but do not directly procure biomaterials.
- Research Institutions:University laboratories in Johannesburg and Cairo conduct preclinical validation of novel osteoconductive surface modifications under ISO 10993 frameworks.
Hospitals dominate absolute purchasing power; Orthopedic Clinics are expanding fastest as Gulf ambulatory surgery infrastructure matures.
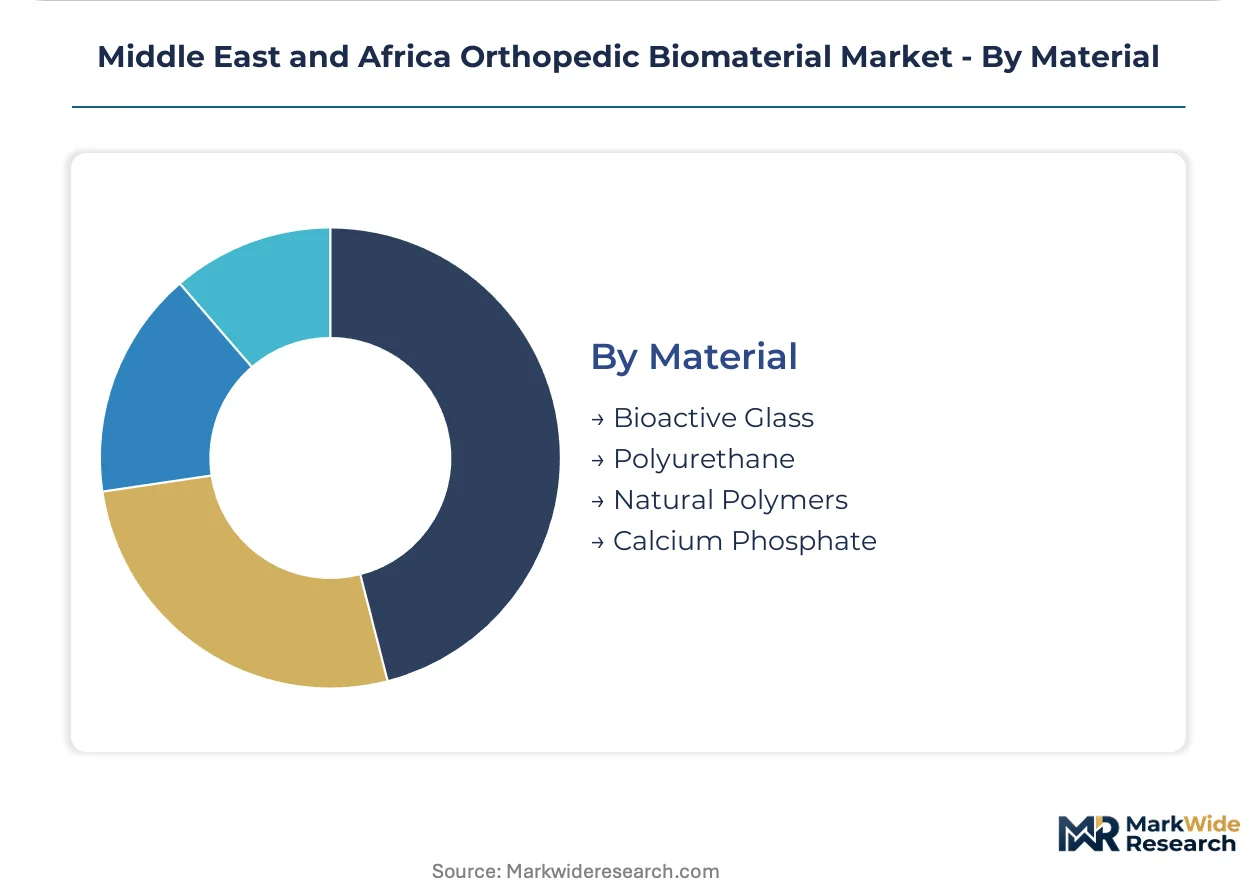
Material:
Supply chain geography and synthesis complexity create divergent cost structures across the four primary biomaterial chemistries.
- Calcium Phosphate:Hydroxyapatite and tricalcium phosphate scaffolds serve as the workhorse synthetic bone graft substitute. Raw material concentration among European and East Asian specialty chemical suppliers exposes manufacturers to currency volatility and input cost pressure.
- Bioactive Glass:Silicate-based formulations release therapeutic ion concentrations that stimulate osteogenesis and angiogenesis. 45S5 composition variants show particular promise in periodontal and craniofacial defect applications.
- Natural Polymers:Collagen, chitosan, and hyaluronic acid derivatives provide biodegradable matrices for cartilage repair and soft tissue engineering.
- Polyurethane:Segmented polyurethane elastomers enable compliant load-bearing structures for intervertebral disc replacement and soft tissue reconstruction.
Calcium Phosphate maintains the broadest clinical utilization; Bioactive Glass demonstrates the most rapid indication expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Saudi Arabia's privatizing hospital networks while South Africa's regulatory tightening compresses margins for implant suppliers. The Gulf Cooperation Council states channel sovereign capital into orthopedic infrastructure, diverging from cost-constrained public systems in Egypt and Nigeria.
Saudi Arabia
Ministry of Health hospital privatization under Vision 2030 is deploying capital into specialized orthopedic units at King Faisal Specialist Hospital and Johns Hopkins Aramco Healthcare. The Saudi Food and Drug Authority (SFDA) harmonizes biocompatibility documentation with Gulf standards, accelerating multi-market registrations for synthetic bone graft substitutes. Riyadh and Jeddah anchor demand for ceramic-composite bearing surfaces in revision arthroplasty.
United Arab Emirates
Dubai's mandatory health insurance schemes and Abu Dhabi's SEHA network centralize procurement authority among fewer authorized buyers. The Ministry of Health and Prevention (MOHAP) mandates extended local follow-up data for permanent spinal implantables, extending market access timelines. Cleveland Clinic Abu Dhabi and Mediclinic City Hospital deploy patient-specific instrumentation for complex pelvic reconstructions.
South Africa
Private hospital groups Netcare and Life Healthcare expand ceramic-composite trauma implant adoption in Johannesburg and Cape Town tertiary centers. The Health Products Regulatory Authority (SAHPRA) tightened biocompatibility documentation rules for permanent implantables in 2023, compelling localized testing partnerships. Groote Schuur Hospital and Chris Hani Baragwanath Academic Hospital drive demand for porous titanium coatings in hip revision cases.
Egypt
Ain Shams University Medical Center and Cairo University Hospitals concentrate cartilage repair procedures requiring cell processing infrastructure. Cost-conscious public hospitals prioritize autologous bone grafts despite donor-site morbidity, limiting synthetic material penetration. The Egyptian Drug Authority maintains biocompatibility standards aligned with ISO 10993 frameworks.
Israel
Hadassah Medical Center and Sheba Medical Center pioneer 3D-printed patient-specific implants for complex spinal reconstructions. The Ministry of Health regulates permanent implantables through AMAR certification pathways. Tel Aviv's medical technology cluster attracts additive manufacturing partnerships with Gulf hospital networks seeking custom porous titanium scaffolds.
Middle East and Africa Orthopedic Biomaterial Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying raw ceramic precursors and polymer matrices. The vendor base stratifies between multinational device conglomerates with direct ministry contracting capability and mid-cap material suppliers dependent on distributor networks. Three archetypes dominate: integrated orthopedic device platforms, specialty chemical feedstock providers, and regional distribution intermediaries. Competitive dynamics center on backward integration into hydroxyapatite synthesis and captive supply agreements with privatizing hospital networks.
Among integrated device platforms, DePuy Synthes, Zimmer Biomet, and Stryker Corporation occupy positions reflecting distinct geographic anchoring strategies. DePuy Synthes exemplifies Gulf Cooperation Council penetration through established distribution infrastructure. Zimmer Biomet represents the university hospital training partnership model in Cairo and Johannesburg. Stryker Corporation sits within the direct procurement channel archetype, supplying ministry-of-health buyers in Saudi Arabia and the UAE.
| Leading Market Players |
|---|
| DePuy Synthes |
| Royal DSM |
| Zimmer Biomet |
| Evonik Industries |
| BASF SE |
| Stryker Corporation |
| Medtronic |
| Corbion N.V. |
| Wright Medical |
| Others |
Supply & Pricing Matrix
Single-source dependency on European and East Asian synthesis-grade hydroxyapatite precursors determines both the three-tier pricing structure across premium, standard, and economy levels and the elongated supply chain configuration favoring distributor-heavy downstream models. Manufacturers face compressed margins when currency volatility hits procurement of these specialty ceramic feedstocks, forcing tiered pricing spreads that separate Gulf private hospital buyers from cost-constrained public systems in Egypt and Nigeria.
Pricing Analysis
Ministry-of-health buyers anchor contract-based long-term offtake structures that favor direct manufacturer contracting over fragmented distributor networks. Price differentiation hinges on ISO 10993 certification tier and volume scale, with NPHIES-integrated Saudi hospitals commanding preferential terms through consolidated purchasing authority. Pricing pressure stems from SAHPRA's tightened biocompatibility documentation requirements, which extend compliance costs into registration timelines. Public hospital systems in Egypt exhibit the highest price sensitivity, while Gulf private hospitals absorb premium ceramic-composite bearing surfaces with limited negotiation leverage.
Supply Chain Analysis
Extended payment terms from sovereign-backed hospital privatization vehicles in Saudi Arabia and the UAE reshape working capital requirements for upstream suppliers. Geographic supply concentration centers on Germany, Japan, and China for hydroxyapatite precursors, bioactive glass formulations, and porous titanium coatings. Raw material dependencies include tricalcium phosphate scaffolds, silicate-based bioactive glass, and segmented polyurethane elastomers. Single-source vulnerability runs through European specialty chemical suppliers for medical-grade ceramic synthesis. Distribution runs through authorized distributor networks facing margin compression as direct procurement channels expand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
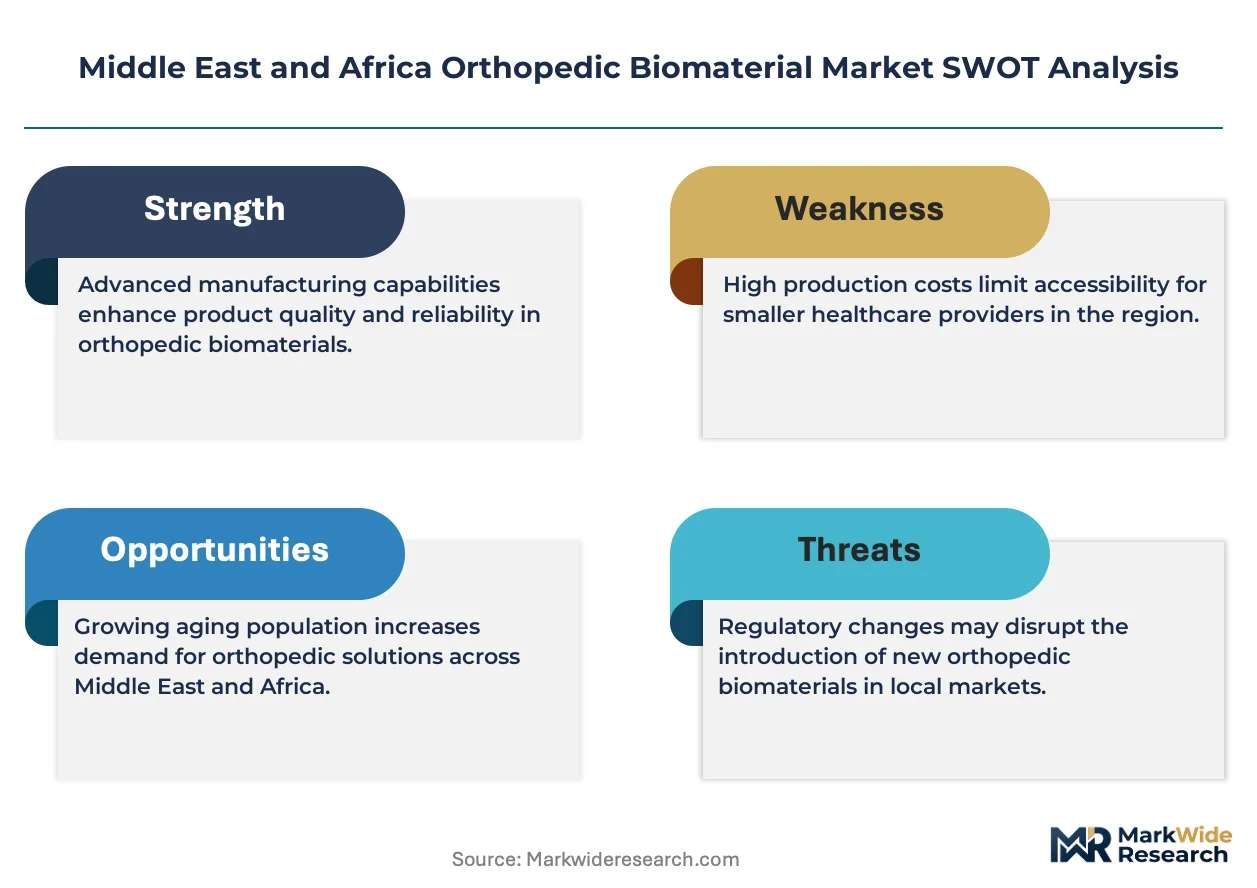
Hospital privatization across Gulf Cooperation Council states fragments procurement authority between ministry buyers and emerging private operators, creating niche entry points for specialized biomaterial suppliers outside integrated device platforms.
For Market Incumbents: Pre-empt margin erosion in ceramic-composite trauma implants by securing captive supply agreements with Netcare and Life Healthcare in South Africa before mid-cap competitors establish Johannesburg-based testing partnerships. Lock in direct NPHIES platform access through regulatory affairs localization in Riyadh, countering the threat of distributor disintermediation. Backward integration into hydroxyapatite precursor synthesis hedges against European supplier concentration. For New Entrants and Emerging Players: Build out regulatory-first entry through SAHPRA harmonization pathways that enable multi-market registrations spanning South Africa and Gulf states. Target Ethiopia and Kenya orthopedic infrastructure as the most penetrable geography, where Chinese development finance funds hospital construction without established supplier relationships. Pursue university hospital training partnerships in Cairo and Johannesburg as the primary go-to-market angle, creating captive demand channels before procurement centralization solidifies. For Investors and Strategic Acquirers: SFDA hospital privatization mandates reshape the acquisition landscape by concentrating orthopedic service line capital deployment under fewer authorized buyers with direct contracting preference. Long-term viability favors platform integrators with ministry-level access over component specialists dependent on distributor networks. Acquisition target archetype: mid-cap synthetic bone graft substitute manufacturers with SAHPRA registration progress and Gulf regulatory affairs capabilities. Watch SAHPRA-SFDA biocompatibility harmonization completion as the signal for accelerated multi-market consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Pathway | Accelerates multi-market access across South Africa and harmonized Gulf jurisdictions. |
| University Hospital Partnership | Creates captive demand channels through specialized credentialing programs in Cairo and Johannesburg. |
| Ceramic-Composite Manufacturing Scale-Up | Addresses load-bearing trauma implant demand from expanding tertiary centers in Cape Town. |
| Backward Integration into Hydroxyapatite | Reduces exposure to European specialty chemical supplier concentration and currency volatility. |
| NPHIES Direct Contracting Capability | Bypasses distributor margin compression under Saudi procurement centralization. |
Research Methodology
Initial hypotheses were tested against primary input from orthopedic surgeons, hospital procurement committee members, biomedical engineers, and regulatory affairs directors at SFDA and SAHPRA, and refined through secondary validation. Sources included ISO 10993 biocompatibility filing databases, hospital procurement records from Saudi Arabia's NPHIES platform, South African customs data for ceramic precursor imports, and GPO contract disclosures. Bottom-up procedure volume estimates triangulated with top-down market sizing across product type and application dimensions.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling patient procedure volumes against manufacturing capacity deployment and regulatory approval timelines. Segmentation dimensions included material chemistry, surgical application, hospital privatization status, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for synthetic material substitution and orthopedic infrastructure investment trajectories. Industry-specific inputs incorporated SAHPRA registration timeline data and Gulf hospital privatization capital commitment flows.
Stress conditions across hydroxyapatite precursor pricing volatility, SFDA documentation requirement changes, and NPHIES procurement centralization pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about continued regulatory harmonization and sovereign capital deployment into orthopedic infrastructure. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Biomaterial in Surgical Mesh Market
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Global Biomaterials Market
Biomaterials
US Heparin Market
Biomaterials
Global Medical Engineered Materials Market
Biomaterials
Biodegradable Bone Graft Polymers Market
Biomaterials
Chitosan Oligosaccharides and Glucosamine Market
Biomaterials
Biomimetic Materials Market
Biomaterials
Hydrogel Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Global Hydroxyapatite Market
Biomaterials
United Kingdom Collagen Market
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
North America Chitosan Market