
 Calcium Phosphate Market | 2026-2036
Calcium Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Phosphate Market Analysis
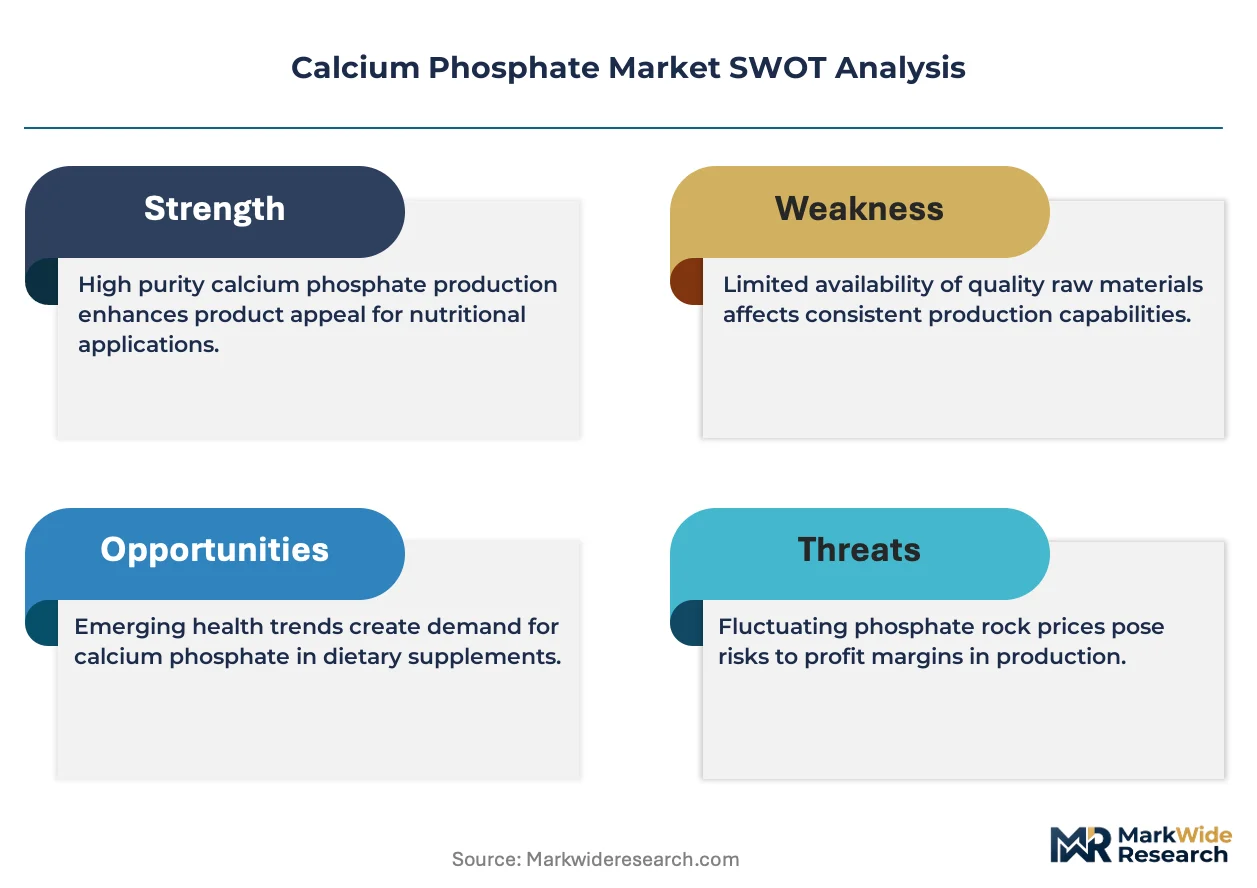
The EU Medical Device Regulation is hardening purity requirements for implantable-grade calcium phosphates, compelling suppliers to recertify manufacturing lines. Merck KGaA leverages its pharmaceutical-grade production infrastructure to sustain premium positioning in dental and orthopedic applications. The Mosaic Company anchors North American supply through integrated phosphate mining and downstream processing capabilities.
Calcium phosphate comprises a family of inorganic minerals with the general formula Ca3(PO4)2 and its hydrated or substituted variants, synthesized via wet chemical precipitation, solid-state reaction, or hydrothermal methods depending on crystallinity and stoichiometry requirements. These compounds serve as bone graft substitutes, tablet excipients, leavening agents, and phosphate fertilizers owing to their biocompatibility, pH buffering capacity, and nutritional phosphorus content. Hydroxyapatite dominates the product type landscape due to its structural homology with natural bone mineral, while the pharmaceutical application segment commands the densest margin pools as regulatory compliance costs filter out commodity producers. Food and beverage applications for dicalcium phosphate and tricalcium phosphate retain volume leadership but face pricing pressure from mineral supplement alternatives.
The European Medicines Agency enforces pharmacopeial standards for calcium phosphate excipients under the European Pharmacopoeia, while the FDA's Center for Drug Evaluation and Research governs GRAS status and drug master file requirements for ingestible grades in the United States. China's National Medical Products Administration is aligning domestic pharmaceutical-grade phosphate standards with ICH Q3D elemental impurity guidelines, reshaping export qualification protocols for Asian manufacturers. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF, EP, and JP monographs to anticipate qualification burdens that will determine competitive viability in regulated end markets.
Market Dynamics
The EU Medical Device Regulation is forcing wholesale recertification of implantable-grade calcium phosphate production lines, compressing supplier margins while elevating compliance barriers for commodity-grade entrants. Pharmaceutical and orthopedic device manufacturers now demand documented traceability from phosphate rock source to finished hydroxyapatite powder.
Growth Catalysts
- EMA Pharmacopeial Harmonization:The European Medicines Agency's alignment of elemental impurity standards with ICH Q3D guidelines is accelerating qualification timelines for high-purity excipient suppliers serving sterile implant applications.
- Germany's Medical Device Cluster:Concentrated orthopedic OEM demand around Tuttlingen and Berlin-Brandenburg is pulling specialized hydroxyapatite coating capacity toward just-in-time delivery models.
- Biomimetic Surface Engineering:Nanostructured calcium phosphate deposition techniques are displacing plasma-sprayed coatings in spinal fusion and dental implant fixtures.
Market Restraints
- Phosphate Rock Supply Concentration:Morocco and Western Sahara control approximately 70% of global phosphate rock reserves, creating geopolitical exposure for downstream calcium phosphate processors.
- Wet Chemical Synthesis Energy Intensity:Precipitation-based hydroxyapatite production requires sustained thermal processing, rendering European and North American facilities vulnerable to natural gas price volatility.
- Carbonate Apatite Substitution:Synthetic carbonate-substituted apatites with faster resorption kinetics are capturing share in biodegradable bone graft applications.
Strategic Opportunities
- India's CDSCO Alignment:The Central Drugs Standard Control Organization's adoption of ICH Q3D standards creates a regulatory runway for export-qualified Chinese and European suppliers to penetrate pharmaceutical-grade markets.
- 3D-Printed Scaffold Convergence:Additive manufacturing of patient-specific bone implants is converging with custom calcium phosphate slurry formulation services.
- Japan's PMDA Regenerative Medicine Framework:The Pharmaceuticals and Medical Devices Agency's accelerated approval pathway for combination products is opening demand for GMP-grade hydroxyapatite-collagen composites.
Industry Challenges
- ISO 13485 Quality Management Implementation:Medical device-grade calcium phosphate suppliers face 12-18 month certification timelines with notified bodies experiencing backlog congestion.
- Cross-Contamination Control Infrastructure:Dual-use facilities producing both food-grade and pharmaceutical-grade phosphates require segregated air handling and dedicated production suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Phosphate Market |
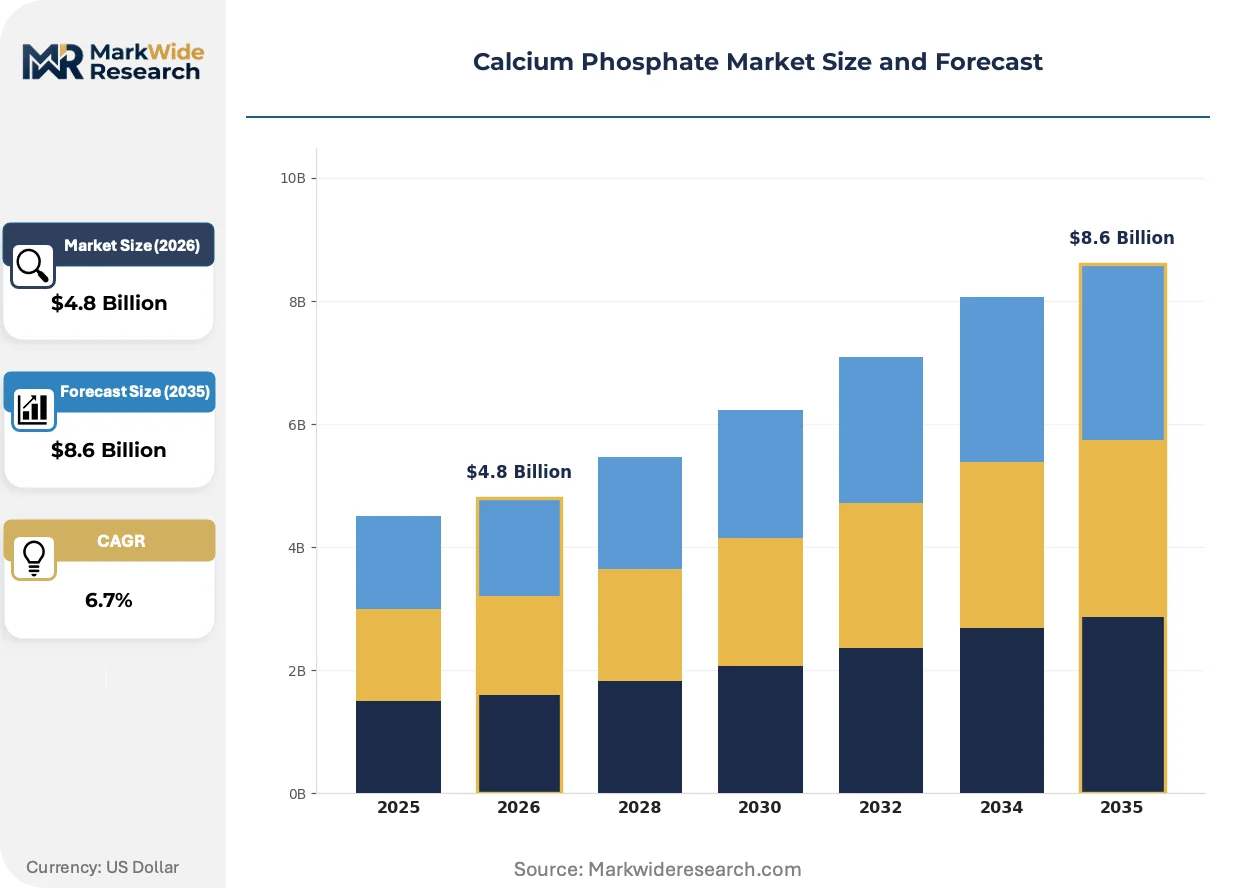
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dicalcium Phosphate, Tricalcium Phosphate, Octacalcium Phosphate, Hydroxyapatite Application: Food & Beverage, Pharmaceutical, Dental Care, Fertilizers End User: Pharmaceutical Companies, Nutraceuticals, Agriculture, Consumer Products Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Innophos Holdings, Inc., Merck KGaA, The Mosaic Company, EuroChem Group AG, Nutrien Ltd., ICL Group, OCP Group, Aditya Birla Chemicals, PhosAgro Group of Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Phosphate Market Emerging Trajectories
Synthetic biology and precision manufacturing techniques are reshaping how calcium phosphate materials are designed, regulated, and procured across medical and industrial end uses. Three interconnected developments are compressing traditional qualification cycles.
Electrospinning of calcium phosphate-loaded polymer nanofibers is converging with conventional bone graft substitute manufacturing. Spinal implant OEMs in Germany and Switzerland are integrating these hybrid scaffolds into their product pipelines faster than standard sintered ceramic timelines permit. The technology is converging with established orthopedic supply chains by enabling room-temperature processing of thermally sensitive biologics.
China's National Medical Products Administration is tightening export qualification protocols for pharmaceutical-grade phosphates through alignment with ICH Q3D elemental impurity guidelines. Domestic manufacturers must now document heavy metal testing across raw material streams previously exempt from batch-level verification. Export-oriented producers in Jiangsu and Zhejiang provinces are absorbing laboratory infrastructure investments to retain European and Japanese customer access.
Orthopedic device procurement is consolidating supplier relationships around vertically integrated coating service providers. German and Swiss implant manufacturers are reducing their approved vendor lists from multiple powder suppliers to single-source partners with in-house plasma spray and sol-gel capabilities. This concentration is most visible in Tuttlingen's precision machining cluster, where device OEMs now bundle material supply with surface engineering contracts.
Calcium Phosphate Market Segmentation
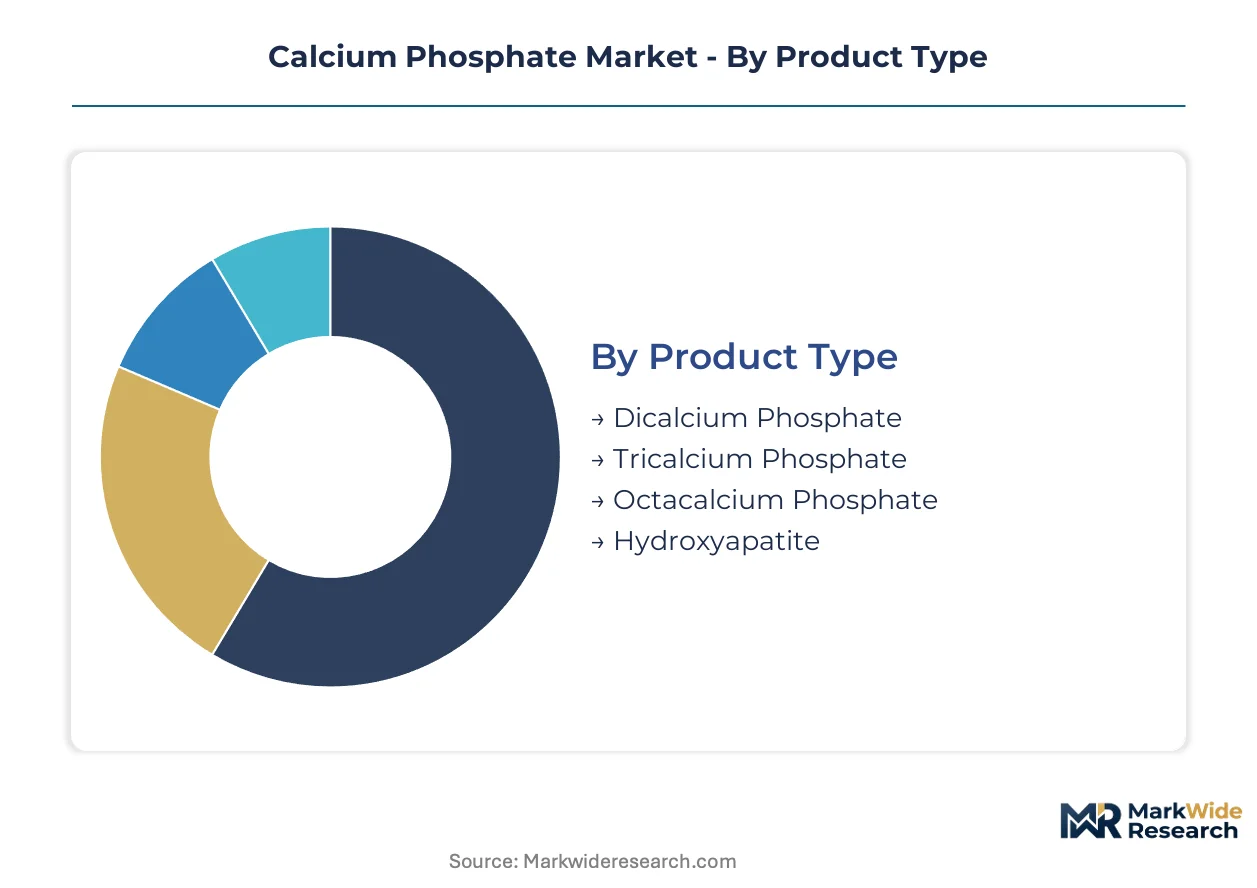
Calcium phosphate buyers fragment sharply across purity grades and regulatory thresholds. Pharmaceutical and orthopedic OEMs impose documentation burdens that commodity food-grade suppliers cannot absorb, forcing parallel supply chains with minimal overlap.
Product Type:
Buyers in this category separate by crystallinity requirements and thermal processing tolerance.
- Hydroxyapatite:Synthetic hydroxyapatite mimics the Ca10(PO4)6(OH)2 stoichiometry of natural bone mineral with tunable porosity for osseointegration. Orthopedic implant manufacturers in Germany's Tuttlingen cluster and dental fixture producers in Switzerland demand documented traceability from phosphate rock to finished powder under EU MDR recertification timelines.
- Dicalcium Phosphate:Dihydrate and anhydrous forms serve as leavening agents and calcium fortifiers with lower purity thresholds than medical grades. Food manufacturers in the United States source this grade through GRAS-qualified suppliers facing pressure from mineral supplement alternatives.
- Tricalcium Phosphate:Higher calcium-to-phosphorus ratio suits nutritional supplements and antacid formulations requiring moderate purity.
- Octacalcium Phosphate:Transient precursor phase in biomineralization research and specialized bone graft applications with limited commercial scale.
Volume sits with dicalcium phosphate; growth tilts toward hydroxyapatite.
Application:
Regulatory jurisdiction determines supplier qualification costs and margin capture.
- Pharmaceutical:Tablet excipients and bone graft substitutes must meet USP-NF, EP, and JP monograph harmonization requirements. EMA's ICH Q3D alignment for elemental impurities is compressing qualification timelines for sterile implant applications.
- Dental Care:Hydroxyapatite coatings and remineralizing agents command premium positioning. Swiss and German dental OEMs are consolidating vendor lists around vertically integrated coating service providers with in-house plasma spray capabilities.
- Food & Beverage:Leavening agents and calcium fortifiers retain volume leadership but face pricing pressure from carbonate and citrate alternatives.
- Fertilizers:Phosphorus nutrition applications source lower-grade material with minimal processing overhead.
Revenue concentrates in pharmaceutical; dental care is climbing the fastest.
End User:
Procurement sophistication varies from commodity spot purchasing to multi-year qualification contracts.
- Pharmaceutical Companies:Require drug master files and batch-level heavy metal documentation. China's NMPA alignment with ICH Q3D is reshaping export protocols for Asian suppliers seeking European access.
- Nutraceuticals:Dietary supplement manufacturers prioritize cost position over pharmacopeial compliance, sourcing food-grade or USP-grade material depending on label claims.
- Agriculture:Fertilizer blenders purchase bulk phosphate with minimal specification overhead.
- Consumer Products:Toothpaste and oral care brands specify cosmetic-grade hydroxyapatite with moderate purity requirements.
Contract value peaks with pharmaceutical companies; nutraceuticals are gaining share fastest.
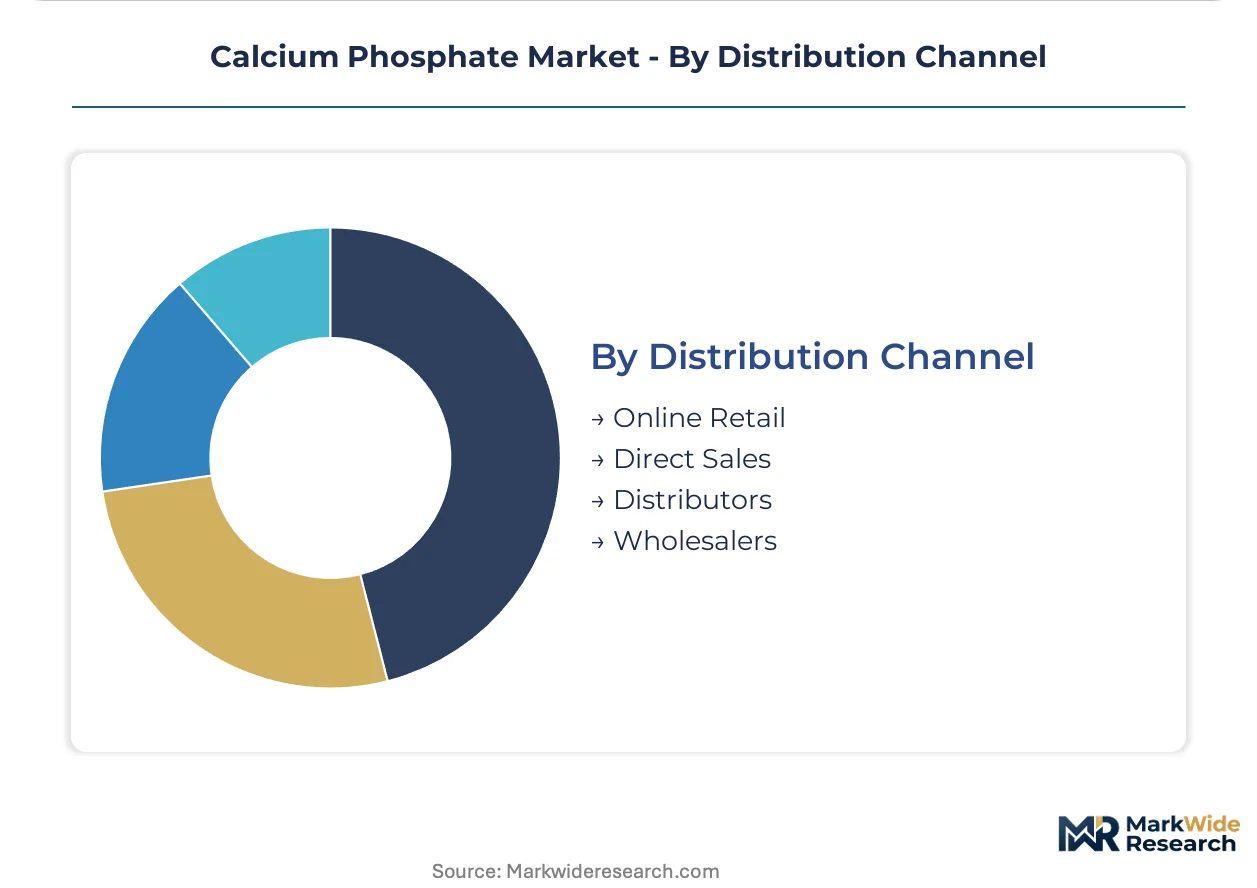
Distribution Channel:
Channel selection tracks order size, technical service requirements, and geographic proximity to production.
- Direct Sales:Pharmaceutical and orthopedic OEMs negotiate long-term supply agreements with technical support and custom formulation services. German medical device clusters favor direct relationships with hydroxyapatite producers offering just-in-time delivery.
- Distributors:Regional chemical distributors stock food-grade and technical-grade material for smaller manufacturers lacking volume to justify direct contracts.
- Online Retail:Nutraceutical and consumer product ingredient sourcing through B2B platforms with limited technical consultation.
- Wholesalers:Agricultural and commodity-grade phosphate moves through bulk material wholesalers with minimal value-added services.
Transaction volume flows through distributors; direct sales capture the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tuttlingen's precision machining cluster in southwestern Germany anchors European orthopedic demand for implantable-grade hydroxyapatite coatings. Device manufacturers there now bundle material procurement with surface engineering contracts under EU MDR recertification timelines.
United States
FDA's Center for Drug Evaluation and Research governs GRAS status and drug master file requirements for ingestible calcium phosphate grades. Pharmaceutical companies in the Greater Boston and New Jersey corridors demand documented traceability from phosphate rock to finished excipient. The Mosaic Company anchors North American supply through integrated phosphate mining and downstream processing capabilities in Florida and Louisiana.
Germany
The EU Medical Device Regulation is hardening purity requirements for implantable-grade calcium phosphates, compelling suppliers to recertify manufacturing lines. EMA pharmacopeial standards under the European Pharmacopoeia compress qualification timelines for sterile implant applications. Berlin-Brandenburg's medical device ecosystem is pulling specialized hydroxyapatite coating capacity toward just-in-time delivery models alongside Tuttlingen.
China
NMPA alignment with ICH Q3D elemental impurity guidelines is reshaping export qualification protocols for pharmaceutical-grade phosphate producers. Domestic manufacturers in Jiangsu and Zhejiang provinces must now document heavy metal testing across raw material streams. Yangtze River Delta chemical clusters are absorbing laboratory infrastructure investments to retain European and Japanese customer access.
Switzerland
Swissmedic regulates dental and orthopedic implant materials under harmonized EU MDR frameworks with additional cantonal manufacturing standards. Dental fixture producers in the Basel-Zurich corridor are consolidating vendor lists around vertically integrated coating service providers. Swiss OEMs now reduce approved supplier lists from multiple powder sources to single-source partners with in-house plasma spray capabilities.
India
CDSCO adoption of ICH Q3D standards creates a regulatory runway for export-qualified Chinese and European suppliers to penetrate pharmaceutical-grade markets. Maharashtra and Gujarat-based generic drug manufacturers source tablet excipients through distributors lacking direct technical service relationships. Domestic nutraceutical blenders prioritize cost position over pharmacopeial compliance, sourcing food-grade material for dietary supplement applications.
Calcium Phosphate Market Vendor Landscape
The competitive structure tilts toward integrated mining-to-chemical processors commanding raw material security. Tiered supplier archetypes separate pharmaceutical-grade specialists with pharmacopeial compliance infrastructure from commodity fertilizer producers with downstream purification capabilities. Strategic moves concentrate on backward integration into phosphate rock mining and forward integration into coating service provision for orthopedic OEMs. M&A activity targets regional distributors with established relationships to medical device clusters.
Within the integrated mining-chemical tier, The Mosaic Company exemplifies North American supply anchoring through captive phosphate rock reserves and downstream processing infrastructure. Merck KGaA occupies a position representing pharmaceutical-grade production infrastructure leveraged for premium positioning in dental and orthopedic applications. EuroChem Group AG and OCP Group sit within the resource-backed processor archetype, with Moroccan phosphate rock access providing feedstock security for downstream calcium phosphate purification.
| Leading Market Players |
|---|
| Innophos Holdings, Inc. |
| Merck KGaA |
| The Mosaic Company |
| EuroChem Group AG |
| Nutrien Ltd. |
| ICL Group |
| OCP Group |
| Aditya Birla Chemicals |
| PhosAgro Group of Companies |
| Others |
Supply Flow & Price Mechanics
Orthopedic OEM consolidation around Tuttlingen and Berlin-Brandenburg is compressing supplier margins as device manufacturers bundle material procurement with surface engineering contracts, forcing calcium phosphate producers to absorb coating service investments or surrender pricing power to vertically integrated competitors.
Pricing Analysis
Pharmacopeial certification grade anchors value-based pricing across pharmaceutical and implantable applications, with USP-NF and EP compliance commanding substantial premiums over food-grade alternatives. Price differentiation separates GMP-certified hydroxyapatite with full traceability documentation from technical-grade material serving fertilizer and feed markets. Pricing pressure stems from carbonate apatite substitution in biodegradable bone graft applications, eroding share in the fastest-growing therapeutic segment. Food and beverage buyers exhibit highest price sensitivity, sourcing dicalcium phosphate through spot purchasing against mineral supplement alternatives.
Supply Chain Analysis
Phosphate rock supply rests on Moroccan and Western Saharan reserves controlling approximately seventy percent of global feedstock, tethering downstream calcium phosphate processors to concentrated upstream geology. Wet chemical synthesis draws from sulfuric acid and thermal energy inputs, with European and North American facilities exposed to natural gas price volatility. Single-source vulnerability concentrates in high-purity hydroxyapatite production, where qualified suppliers face twelve-to-eighteen month ISO 13485 certification timelines. Distribution runs through direct sales relationships for pharmaceutical and orthopedic OEMs, while regional chemical distributors handle food-grade and technical-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcium phosphate market is becoming a vertical-integration race as producers pursue captive phosphate rock mining to secure feedstock against geopolitical concentration, or downstream coating services to capture orthopedic OEM procurement consolidation.
For Market Incumbents: Anchor market position through backward integration into phosphate rock mining or forward integration into plasma spray coating services, as German and Swiss device OEMs reduce approved vendor lists. Defend against carbonate apatite substitution by accelerating nanostructured deposition technique qualification with spinal implant manufacturers. Prioritize ISO 13485 certification maintenance during notified body backlog congestion to preserve medical device-grade supply relationships. For New Entrants and Emerging Players: Capture white-space opportunity in India's pharmaceutical-grade market as CDSCO ICH Q3D alignment creates regulatory runway for export-qualified suppliers. Target Maharashtra and Gujarat generic drug manufacturers currently sourcing through distributors lacking technical service capabilities. Penetrate via direct sales model offering drug master file support and batch-level heavy metal documentation that incumbent distributors cannot match. For Investors and Strategic Acquirers: The window for entry favors resource-backed processors with Moroccan phosphate rock access or European coating service providers with established Tuttlingen cluster relationships. Long-term viability hinges on regulatory compliance infrastructure amortization across multi-year qualification contracts. Watch NMPA export protocol enforcement as the inflection indicator for Chinese supplier competitive viability in European and Japanese markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | Secures feedstock supply against Moroccan reserve concentration and geopolitical exposure. |
| Forward Integration into Coating Services | Captures orthopedic OEM procurement consolidation bundling material with surface engineering. |
| ISO 13485 Certification Investment | Preserves medical device-grade supply access during EU MDR recertification timelines. |
| ICH Q3D Laboratory Infrastructure | Retains European and Japanese market access under tightening NMPA export protocols. |
| 3D-Printed Scaffold Slurry Formulation | Converges with additive manufacturing of patient-specific bone implants in Japan's PMDA framework. |
Methodological Framework
Document review covered regulatory filings with FDA, EMA, and NMPA, trade data from customs authorities, and pharmacopeial monograph harmonization records, complemented by interviews with calcium phosphate plant managers, orthopedic OEM procurement leads, pharmaceutical excipient buyers, and dental implant coating specialists. Secondary validation drew from SEC filings of integrated mining-chemical processors, EU Medical Device Regulation implementation guidance, and ICH Q3D elemental impurity guideline documentation. Bottom-up volume estimates triangulated against top-down market sizing across product grades and application segments.
Cross-referencing historical capacity expansion patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation modeling incorporated product type crystallinity requirements, application regulatory thresholds, end-user procurement sophistication, and distribution channel technical service intensity. CAGRs derived from demand elasticity analysis for hydroxyapatite coatings against substitute materials and fertilizer-grade phosphate pricing dynamics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to phosphate rock supply disruption, natural gas price volatility affecting wet chemical synthesis economics, and regulatory harmonization pace between USP-NF, EP, and JP monographs. Forecasts reflect assumptions regarding EU MDR recertification timeline completion and CDSCO enforcement consistency. A small set of triggers—NMPA export protocol stringency, notified body certification backlog resolution, and carbonate apatite clinical adoption rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Chitosan-Based Biomaterials Market
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Self-Healing Materials Market
Biomaterials
Mushroom Materials Market
Biomaterials
Scaffold Materials Market
Biomaterials
Europe Collagen Market
Biomaterials
Biomaterial Wound Dressing Market
Biomaterials
Biomimetic Peptides Market
Biomaterials
Hydrogel Market
Biomaterials
Global Bioactive Materials Market
Biomaterials
Global Biomaterials Market
Biomaterials
Crocodile Peptide Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Heparin Market
Biomaterials
Chitosan Market
Biomaterials
Global Medical Engineered Materials Market