
 Global Polymeric Biomaterials Market | 2026-2036
Global Polymeric Biomaterials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polymeric Biomaterials Market Foresight
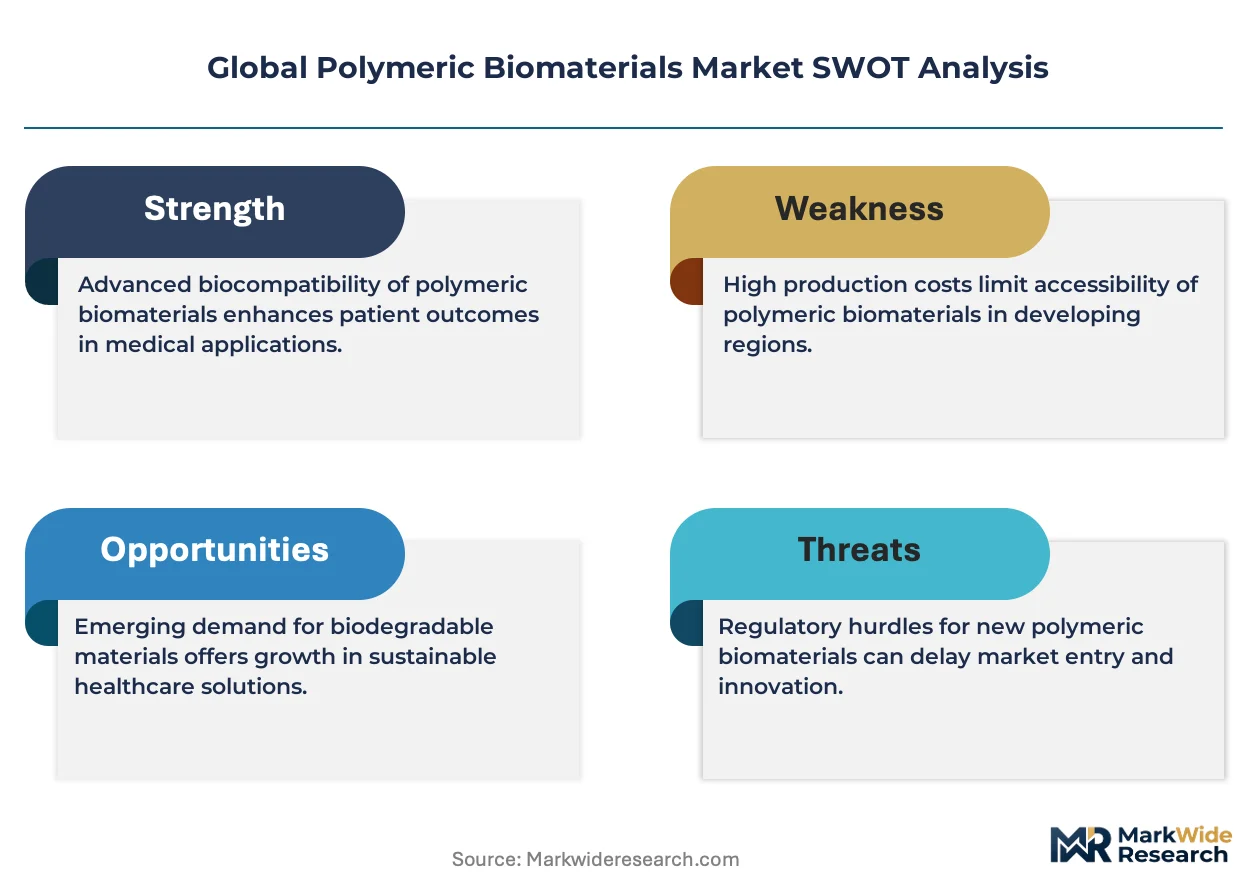
Project finance for dedicated biopolymer manufacturing facilities is reconfiguring competitive entry barriers, allowing specialized firms to scale without full capital ownership. Evonik Industries AG leverages its backward integration into amino acid precursors to sustain margin control across medical-grade polyamide supply chains. BASF SE anchors global supply through certified production hubs, while Victrex PLC specializes in high-performance PEEK biomaterials for spinal implant applications.
Polymeric biomaterials comprise macromolecular compounds engineered for biological interfacing, including polyester scaffolds with controlled degradation rates measured in weeks to years and thermoplastic elastomers processed via solvent casting or electrospinning. These materials serve primarily as structural matrices, controlled-release vehicles, and surface-modified device components in therapeutic and diagnostic systems. Biodegradable polymers capture dominant volume share in tissue engineering and drug delivery applications where resorption eliminates explantation surgery, while non-biodegradable polymers retain stronghold positions in permanent orthopedic and dental implants demanding decades-long mechanical stability. Medical device manufacturers represent the most concentrated end-user channel, with pharmaceutical companies expanding polymer-based formulation pipelines fastest.
FDA enforces ISO 10993 biocompatibility evaluation series for all implantable polymeric devices, while EMA's Medical Device Regulation mandates clinical evidence thresholds that filter lower-capability suppliers from European market access. China's NMPA has aligned its polymer implant registration pathways with international standards, reducing dual-testing burdens for multinationals. Stakeholders must monitor evolving regulatory convergence between FDA breakthrough device pathways and EMA's priority medicine frameworks to anticipate qualification timeline shifts.
Market Dynamics
FDA's tightening ISO 10993 biocompatibility protocols are compressing qualification timelines for implantable polymer platforms, forcing manufacturers to front-load toxicology and sterilization validation costs before market entry.
Growth Catalysts
- EMA Medical Device Regulation:Clinical evidence thresholds filter marginal suppliers from European access, concentrating procurement among qualified vendors with certified polymer supply chains.
- Resorbable polymer scaffolds:Orthopedic implant manufacturers accelerate adoption of controlled-degradation matrices measured in weeks to years, eliminating explantation surgery.
- German applied research clusters:Fraunhofer institutes anchor polymer innovation hubs, attracting device manufacturers seeking co-development partnerships for next-generation biomaterials.
Market Restraints
- Medical-grade amino acid precursors:Backward integration requirements for polyamide supply chains concentrate margin control among integrated chemical conglomerates, squeezing specialized entrants.
- Dual-testing burdens:Misalignment between FDA breakthrough pathways and EMA priority medicine frameworks extends qualification timelines for multinationals seeking concurrent market access.
- Permanent implant mechanical stability:Non-biodegradable polymers retain stronghold positions in orthopedic and dental applications, limiting biodegradable polymer penetration in load-bearing segments.
Strategic Opportunities
- China NMPA alignment:Registration pathway convergence with international standards reduces redundant testing for multinationals, accelerating market entry for qualified polymer platforms.
- Electrospinning-solvent casting convergence:Hybrid processing technologies enable sub-micron fiber architectures with tunable porosity, opening vascular graft and neural conduit applications.
- Project finance restructuring:Dedicated biopolymer manufacturing facilities allow specialized firms to scale production without full capital ownership, lowering competitive entry barriers.
Industry Challenges
- ISO 10993-18 chemical characterization:Extractables and leachables testing for polymer implants requires specialized analytical toxicology talent that remains scarce across contract research organizations.
- PEEK spinal implant sterilization:Gamma irradiation and ethylene oxide validation for high-performance thermoplastics demands extended stability studies that compress development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polymeric Biomaterials Market |
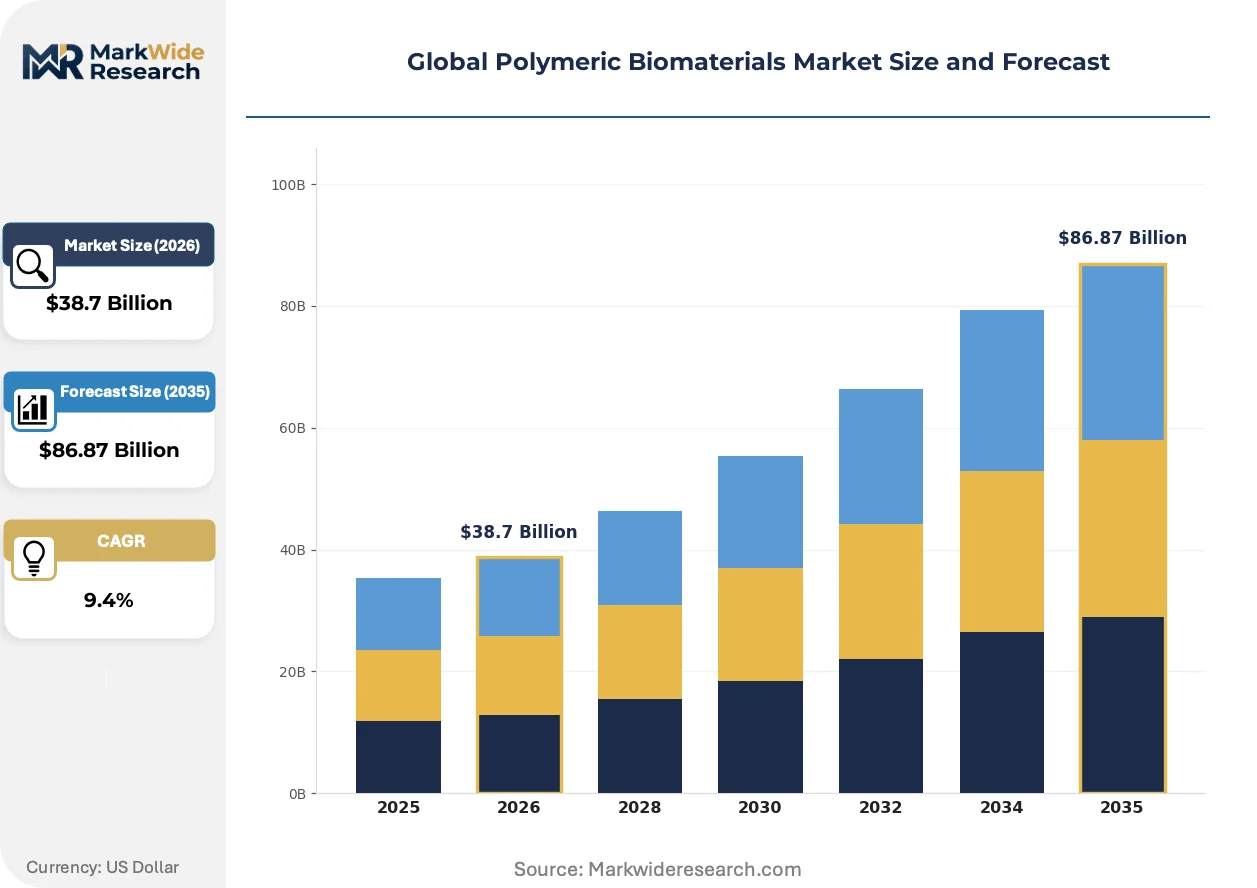
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Polymers, Non-Biodegradable Polymers, Natural Polymers, Synthetic Polymers, Composite Polymers Application: Tissue Engineering, Drug Delivery, Medical Devices, Wound Healing, Dental Implants End User: Research Laboratories, Medical Device Manufacturers, Pharmaceutical Companies, Academic Institutions, Contract Research Organizations Technology: Electrospinning, 3D Printing, Solvent Casting, Emulsion Polymerization, Freeze Drying |
| Companies Covered | BASF SE, Evonik Industries AG, Covestro AG, DSM, Corbion NV, Bezwada Biomedical, Victrex PLC, Stryker, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polymeric Biomaterials Market Shifts & Advancements
Surface-modified polymer architectures are displacing bulk material differentiation as the primary competitive axis, with device manufacturers prioritizing bioactive coatings and topographical patterning over base resin selection.
4D-printed shape-memory polymers are rendering obsolete static scaffold designs in craniofacial reconstruction. Academic medical centers in Switzerland and the Netherlands pilot patient-specific implants with programmed degradation sequences. This capability is compressing revision surgery rates and shifting value capture toward design software and bioprinting service platforms.
REACH restriction proposals on persistent organic pollutants are forcing reformulation of fluorinated polymer processing aids used in medical-grade polyolefin extrusion. Compounders serving cardiovascular device manufacturers face supply requalification cycles. German and French notified bodies are prioritizing technical documentation reviews for alternative lubricant systems.
Hospital procurement consortia now mandate polymer implant traceability through blockchain-enabled supply chain verification. Group purchasing organizations in the United States and United Kingdom pilot lot-level pedigree requirements for spinal and orthopedic devices. This behavioral shift elevates certified production hubs over distributed manufacturing networks in vendor selection criteria.
Global Polymeric Biomaterials Market Segmentation
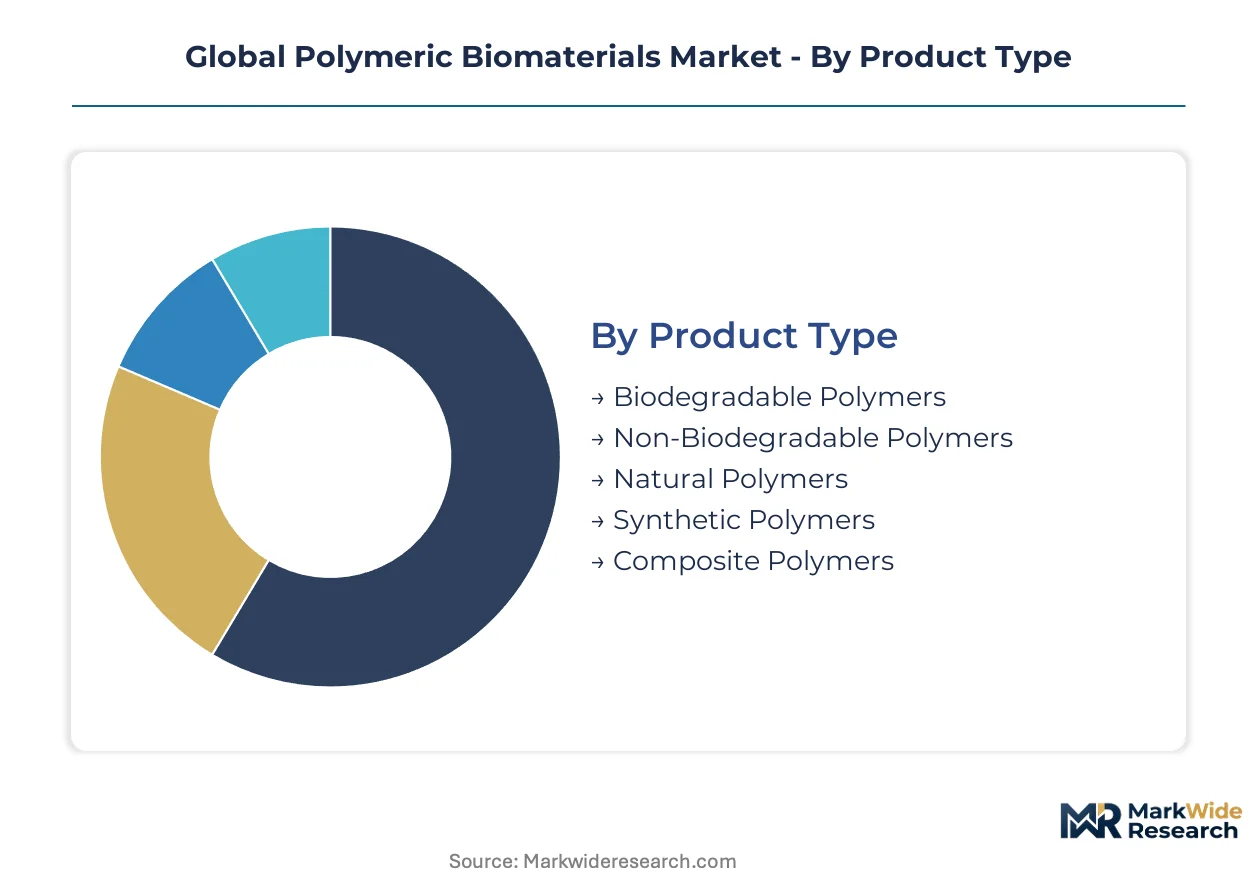
Segmentation in polymeric biomaterials reveals how material properties dictate commercial pathways. Each dimension—chemical composition, clinical application, manufacturing technology, and buyer type—creates distinct qualification barriers and margin profiles that reshape competitive positioning across the value chain.
Product Type:
Mature biodegradable platforms coexist with emerging composite architectures that blend resorbable and permanent phases.
- Biodegradable Polymers:Polyesters, polyanhydrides, and polyurethanes with hydrolytic degradation rates tunable from weeks to years. Orthopedic implant manufacturers in Germany and Switzerland concentrate procurement here for scaffold applications that eliminate secondary explantation procedures.
- Non-Biodegradable Polymers:High-performance thermoplastics including PEEK and UHMWPE engineered for decades-long mechanical stability. Spinal fusion cages and permanent dental implants in the United States and Japan drive volume, though EMA's tightened clinical evidence thresholds now filter marginal suppliers from European access.
- Natural Polymers:Collagen, chitosan, and alginate matrices derived from biological sources with inherent bioactivity. Wound care applications in France and South Korea absorb significant volumes.
- Synthetic Polymers:Petroleum-derived macromolecules with batch-to-batch consistency exceeding natural alternatives. Cardiovascular device manufacturers favor these for regulatory predictability.
- Composite Polymers:Hybrid systems integrating ceramic fillers with polymer matrices for osteoconductivity. Craniofacial reconstruction centers in the Netherlands pilot patient-specific 4D-printed variants with programmed degradation sequences.
Biodegradable polymers handle the majority of throughput; composite polymers are gaining share fastest as hybrid processing technologies mature.
Application:
Cost tier stratification separates high-value implantable devices from commoditized wound care formulations.
- Tissue Engineering:Scaffold architectures supporting cell infiltration and vascularization for organ regeneration. Academic medical centers in Switzerland and Germany anchor demand, with Fraunhofer institutes co-developing next-generation resorbable matrices.
- Drug Delivery:Polymeric nanoparticles and implantable depots enabling controlled release kinetics. Pharmaceutical companies expanding polymer-based formulation pipelines represent the most concentrated end-user channel.
- Medical Devices:Structural components in catheters, stents, and diagnostic equipment requiring ISO 10993 biocompatibility certification. FDA's tightening protocols compress qualification timelines for implantable platforms.
- Wound Healing:Hydrogels and foam dressings with moisture management properties. Hospital procurement consortia in the United Kingdom now mandate blockchain-enabled lot-level traceability.
- Dental Implants:Permanent crowns, bridges, and abutments demanding decades-long mechanical stability. Non-biodegradable polymers retain stronghold positions here, limiting biodegradable penetration.
Medical devices command the highest value per kilogram; drug delivery is expanding most quickly as formulation pipelines diversify.
End User:
Volume concentration among medical device manufacturers contrasts with margin capture by specialized research service providers.
- Research Laboratories:Discovery-stage evaluation of novel polymer architectures and surface modifications. Germany's applied polymer research clusters attract significant funding.
- Medical Device Manufacturers:The most concentrated end-user channel, integrating qualified polymer supply chains into finished implantable products. EMA's Medical Device Regulation filters procurement toward certified vendors.
- Pharmaceutical Companies:Expanding polymer-based formulation pipelines fastest, particularly for biologic stabilization and controlled-release parenterals.
- Academic Institutions:Early-stage innovation in 4D-printed shape-memory polymers and electrospun vascular grafts. Swiss and Dutch centers lead craniofacial reconstruction pilots.
- Contract Research Organizations:ISO 10993-18 chemical characterization and extractables-leachables testing. Specialized analytical toxicology talent remains scarce, elevating capable providers.
Medical device manufacturers handle the majority of throughput; contract research organizations are climbing the fastest as qualification outsourcing accelerates.
Technology:
Processing sophistication separates premium sub-micron fiber architectures from conventional bulk fabrication.
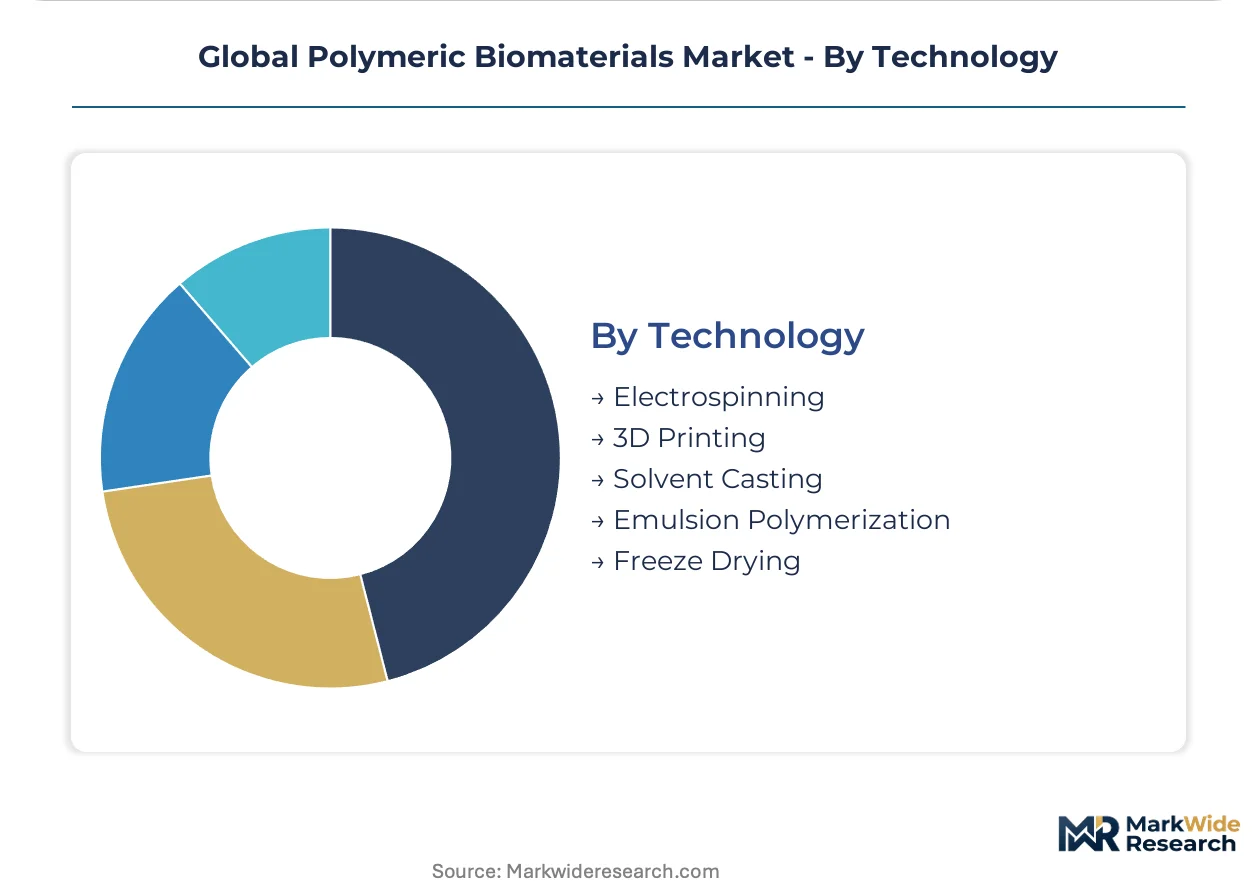
- Electrospinning:Produces non-woven mats with fiber diameters from nanometers to micrometers, enabling tunable porosity for vascular graft and neural conduit applications. Hybrid electrospinning-solvent casting convergence opens new therapeutic categories.
- 3D Printing:Patient-specific scaffold geometries with internal channel networks for nutrient perfusion. 4D-printed shape-memory variants are rendering obsolete static designs in craniofacial reconstruction.
- Solvent Casting:Thin-film and membrane production with precise thickness control. Drug delivery reservoir fabrication relies heavily on this method.
- Emulsion Polymerization:Aqueous-phase synthesis of latex particles and nanoparticles for parenteral formulations. Scales efficiently for pharmaceutical applications.
- Freeze Drying:Lyophilization of hydrogel and collagen matrices preserving porous structure for wound healing and tissue engineering. REACH restriction proposals on fluorinated processing aids force reformulation of associated polyolefin extrusion aids.
Electrospinning handles the majority of high-value throughput; 3D printing shows the steepest expansion trajectory as design software and bioprinting service platforms capture value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss polymer supply chains, while qualification cost burdens compress margins for US and Chinese manufacturers seeking dual FDA-EMA access. This asymmetry reshapes regional investment patterns across the forecast window.
United States
Hospital procurement consortia now mandate blockchain-enabled lot-level traceability for spinal and orthopedic devices, elevating certified production hubs. FDA's tightening ISO 10993-18 chemical characterization protocols compress qualification timelines for implantable polymer platforms. Greater Boston anchors academic medical center pilots in 4D-printed shape-memory polymers for craniofacial reconstruction.
Germany
Fraunhofer institutes anchor applied polymer research clusters that attract device manufacturers seeking co-development partnerships for next-generation resorbable matrices. EMA's Medical Device Regulation filters procurement toward certified vendors with qualified polymer supply chains. Bavaria concentrates medical-grade polyamide production through backward-integrated chemical conglomerates controlling amino acid precursor supply.
Switzerland
Academic medical centers pilot patient-specific implants with programmed degradation sequences, compressing revision surgery rates. Swissmedic maintains alignment with EMA clinical evidence thresholds while offering priority review pathways for breakthrough polymer platforms. Basel and Zurich anchor pharmaceutical company expansion into polymer-based formulation pipelines for biologic stabilization.
China
NMPA alignment with international standards reduces redundant testing burdens for multinationals seeking concurrent market access. Domestic orthopedic implant manufacturers accelerate adoption of resorbable polymer scaffolds to capture share from permanent implant incumbents. Yangtze River Delta biopolymer manufacturing facilities leverage project finance structures to scale without full capital ownership.
Japan
PMDA maintains stringent stability study requirements for gamma-irradiated PEEK spinal implants, extending validation timelines for new market entrants. METI funding programs support electrospinning-solvent casting convergence for sub-micron fiber vascular graft applications. Kansai region medical device manufacturers concentrate procurement of high-performance thermoplastics for permanent dental implant applications.
Global Polymeric Biomaterials Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying certified polymer resins and processed intermediates. The market exhibits tiered concentration, with integrated chemical conglomerates controlling precursor supply and specialized biomaterial firms occupying niche high-performance segments. Three archetypes dominate: backward-integrated resin producers, medical-grade compounders with certified production hubs, and design-focused device manufacturers outsourcing polymer qualification. Competitive moves center on strategic partnerships for co-development access and capacity expansion through project finance structures that avoid full capital ownership.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify archetypes of margin control through captive precursor supply and certified production hub networks. Victrex PLC occupies a specialist position in high-performance thermoplastic biomaterials. These three anchors illustrate how qualification capability and supply chain certification separate sustainable competitive position from commodity participation in implantable polymer markets.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Covestro AG |
| DSM |
| Corbion NV |
| Bezwada Biomedical |
| Victrex PLC |
| Stryker |
| Zimmer Biomet |
| Others |
Supply & Pricing Matrix
German backward-integrated chemical conglomerates controlling amino acid precursor supply for medical-grade polyamides capture disproportionate margin pools downstream, forcing specialized biomaterial firms to absorb qualification cost compression or surrender share to certified production hubs.
Pricing Analysis
Configured-to-order pricing for patient-specific 4D-printed scaffolds commands spreads exceeding three-to-one against standard-grade resorbable polyester pellets. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designation platforms from CE-marked equivalents and unregistered commodity grades. Cost compression in standard-grade biodegradable polymers intensifies as Chinese Yangtze River Delta facilities scale through project finance structures. Hospital procurement consortia exhibit lowest price sensitivity for spinal implant PEEK, while wound care hydrogel buyers drive aggressive tender competition.
Supply Chain Analysis
Upstream feedstock concentration for high-performance thermoplastics centers on Germany, Switzerland, and Japan, where captively produced specialty monomers remain unavailable on spot markets. Polymer supply chains draw from amino acid precursors, aromatic ketone monomers, and biofermentation-derived lactides with limited alternative sourcing. Single-source vulnerability in gamma-irradiation sterilization capacity for PEEK spinal implants creates bottleneck risk during facility maintenance cycles. Distribution runs through certified production hubs rather than distributed manufacturing networks, reflecting blockchain-enabled traceability mandates from United States and United Kingdom hospital consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthopedic implant demand is recovering from procedure deferrals, with resorbable scaffold adoption accelerating as surgeons prioritize revision-rate reduction in value-based care contracts.
For Market Incumbents: Pre-empt Chinese domestic manufacturers by accelerating co-development partnerships with Fraunhofer institutes for next-generation electrospun vascular grafts. Defend margin position through captive amino acid precursor supply rather than merchant market exposure. Certify alternative sterilization pathways before PEEK irradiation capacity constraints tighten. For New Entrants and Emerging Players: Establish a beachhead in composite polymer craniofacial reconstruction, where 4D-printed shape-memory platforms remain underpenetrated by incumbents focused on load-bearing orthopedic segments. Target Swiss and Dutch academic medical centers piloting patient-specific degradation sequences. Lead with bioprinting service platform partnerships rather than resin commoditization. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electrospinning-solvent casting hybrid processing, enabling asset-light scale through toll manufacturing arrangements. Five-to-ten year viability favors medical-grade compounders with ISO 10993-18 analytical toxicology capabilities rather than resin-only producers. Watch for NMPA registration pathway divergence as signal of China market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Precursors | Evonik's captive supply chain locks in margin control across medical-grade polyamide tiers. |
| CE Marking Pathway Acceleration | EMA's tightened clinical evidence thresholds filter procurement toward pre-qualified vendors. |
| Hospital System Partnership | Blockchain-enabled traceability mandates elevate certified hubs in GPO vendor selection. |
| Software Companion Development | 4D-printed scaffold design platforms capture value previously residing in base resin sales. |
| Reimbursement Strategy | Value-based care contracts reward resorbable polymer revision-rate reduction with premium positioning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across orthopedic implant manufacturers, pharmaceutical formulation scientists, hospital procurement committee members, and contract research organization analytical toxicologists. Secondary validation drew from FDA 510(k) filings, EMA Medical Device Regulation technical documentation, ISO 10993 standard revision records, and Fraunhofer institute publication databases. Bottom-up polymer consumption estimates triangulated against top-down medical device production forecasts.
Calibration against historical qualification timeline data and sterilization validation cycle lengths anchored the analytical framework across the projection horizon. Segmentation dimensions spanned biodegradation rate tier, implant permanence classification, processing technology sophistication, and regional regulatory cluster alignment. CAGRs emerged from iterative convergence of supply-side capacity expansion plans and demand-side surgeon adoption curve modeling, with particular weighting applied to resorbable scaffold penetration assumptions and REACH reformulation timelines.
Stress conditions across amino acid precursor supply disruption, gamma-irradiation capacity constraints, and NMPA registration timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EMA-FDA regulatory convergence and electrospinning yield improvement trajectories. Cross-checking against hospital procurement consortium contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Scaffold Materials Market
Biomaterials
Bioceramics and Hydroxyapatite Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Global Biomaterials Market
Biomaterials
Flowable Hemostats Market
Biomaterials
Pulp Cells Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
Chitosan Oligosaccharides Market
Biomaterials
Biomimetic Peptides Market
Biomaterials
Biomimetic Materials Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Spine Surgery Gels Market
Biomaterials
Self-Healing Hydrogels Market