
 Heparin Market | 2026-2036
Heparin Market Size, Share, and Industry Trends Forecast 2026-2036
Heparin Market Analysis
China's heparin API manufacturing base is reconfiguring global supply dynamics as domestic producers expand enzymatic extraction capacity. Shenzhen Hepalink Pharmaceutical leverages backward integration into porcine intestine sourcing to secure raw material throughput. Pfizer sustains formulation dominance through hospital pharmacy direct-tender relationships across North America and Europe. Baxter International anchors critical-care anticoagulation portfolios with intravenous heparin lock solutions for dialysis catheters.
Heparin comprises a family of sulfated glycosaminoglycan anticoagulants extracted primarily from porcine intestinal mucosa, with unfractionated forms averaging molecular weights of 15,000 daltons and low molecular weight variants ranging 4,000 to 5,000 daltons. The substance accelerates antithrombin III inhibition of thrombin and factor Xa, serving as first-line therapy for deep vein thrombosis prophylaxis, pulmonary embolism treatment, and extracorporeal circuit anticoagulation during cardiac surgery and renal replacement. Low molecular weight heparin commands the largest revenue pool due to predictable pharmacokinetics enabling outpatient subcutaneous administration without routine coagulation monitoring. Unfractionated heparin retains entrenched hospital use in surgical and intensive care settings where rapid reversibility with protamine sulfate remains clinically essential. The intravenous administration route dominates acute inpatient settings while subcutaneous delivery expands into home care and long-term care facility transitions.
The FDA enforces heparin sodium monograph standards requiring identification and quantification of oversulfated chondroitin sulfate contaminants, while the EMA's European Pharmacopoeia mandates molecular weight distribution profiling and anti-factor Xa to anti-factor IIa ratio specifications for low molecular weight heparin batches. China's NMPA implements Good Manufacturing Practice inspections for active pharmaceutical ingredient facilities exporting heparin sodium to regulated markets. Stakeholders must monitor biosimilar enoxaparin entry timelines and synthetic pentasaccharide alternatives that threaten to displace porcine-derived heparin in prophylactic indications.
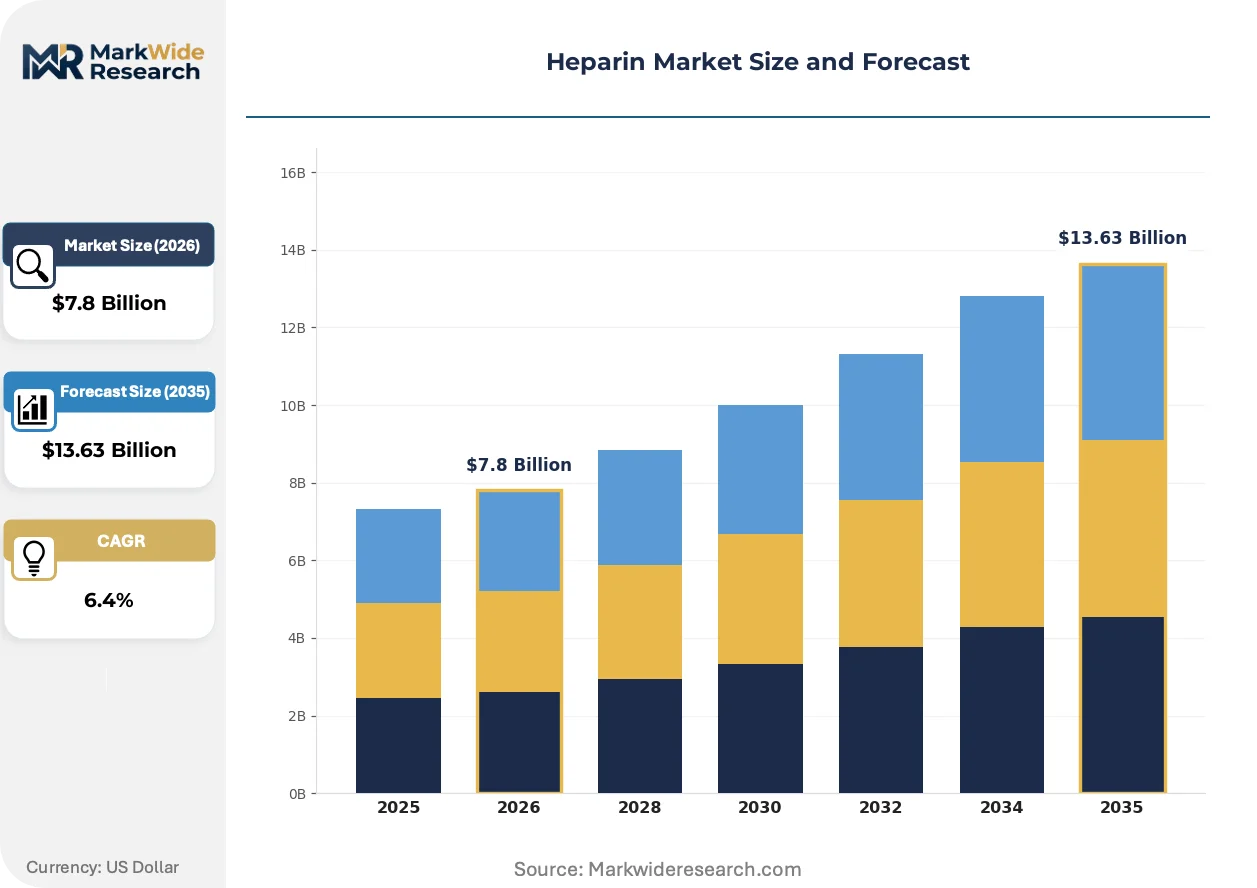
Market Dynamics
FDA's tightened heparin sodium monograph standards are forcing API manufacturers to rebuild purification infrastructure while hospital procurement consolidates purchasing power around direct-tender relationships with formulation suppliers.
Growth Catalysts
- Cardiac surgery volumes:Rising coronary artery bypass and valve replacement procedures in tertiary hospitals sustain demand for unfractionated heparin in extracorporeal circulation.
- REACH compliance:European chemical safety registration requirements for imported biological APIs are accelerating GMP upgrades among Chinese heparin sodium exporters.
- Enzymatic extraction:Advanced depolymerization methods in Shenzhen and Chongqing processing clusters are improving yield rates from porcine intestinal mucosa.
Market Restraints
- Porcine supply concentration:Over 80 percent of raw material processing clusters sit in China's southern provinces, creating geopolitical and disease-outbreak exposure.
- Synthetic pentasaccharide substitution:Fondaparinux and other factor Xa inhibitors threaten to displace low molecular weight heparin in orthopedic prophylaxis.
- EMA batch testing delays:European Pharmacopoeia molecular weight distribution verification creates 4-6 week release bottlenecks for imported API.
Strategic Opportunities
- Brazilian hospital pharmacy expansion:ANVISA's accelerated registration pathway for essential medicines opens access to Latin America's largest surgical market.
- Home anticoagulation transition:Subcutaneous low molecular weight heparin protocols for post-discharge deep vein thrombosis prophylaxis reduce readmission rates.
- ISO 13485 convergence:Medical device quality management certification for heparin-coated catheters and stents creates bundled supplier relationships.
Industry Challenges
- Analytical chemist scarcity:Oversulfated chondroitin sulfate contaminant detection requires specialized mass spectrometry expertise that outpaces training pipeline output.
- Legacy ERP integration:Batch record digitization for NMPA and FDA audit trails conflicts with paper-based quality systems at mid-scale API facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heparin Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unfractionated Heparin, Low Molecular Weight Heparin, Antidotes, Others End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Administration Route: Intravenous, Subcutaneous, Oral, Others Distribution Channel: Direct Tenders, Retail Pharmacies, Online Pharmacies, Hospital Pharmacies |
| Companies Covered | Sanofi, Teva Pharmaceutical Industries, Pfizer, LEO Pharma, Aspen Holdings, Baxter International, Fresenius Kabi, Shenzhen Hepalink Pharmaceutical, B. Braun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heparin Market Emerging Trajectories
Anticoagulation therapy is fragmenting across administration settings as point-of-care testing, synthetic alternatives, and biosimilar entry compress traditional heparin value capture.
Recombinant heparin biosynthesis is hybridizing microbial fermentation with chemoenzymatic sulfation to produce non-animal-derived anticoagulants. Academic-industry partnerships in synthetic biology are scaling pilot facilities toward commercial volumes. This technology is hybridizing the raw material base away from porcine intestine dependence toward defined-cell-line production.
EMA's Medical Device Regulation (MDR) heparin-coated device reclassification is forcing manufacturers to submit clinical evidence for thromboresistance claims. The notified body backlog extends certification timelines by 12-18 months for catheter and stent applicants. Cardiovascular device divisions are responding by internalizing heparin surface-bonding expertise rather than sourcing from external API suppliers.
Hospital pharmacy consolidation into centralized 340B purchasing entities in the United States is compressing formulary slots for anticoagulant agents. Integrated delivery networks now mandate pharmacoeconomic reviews for heparin versus direct oral anticoagulant selection. This concentration is most visible in Midwestern and Southeastern health systems where Catholic hospital mergers have created multi-state purchasing coalitions.
Heparin Market Segmentation
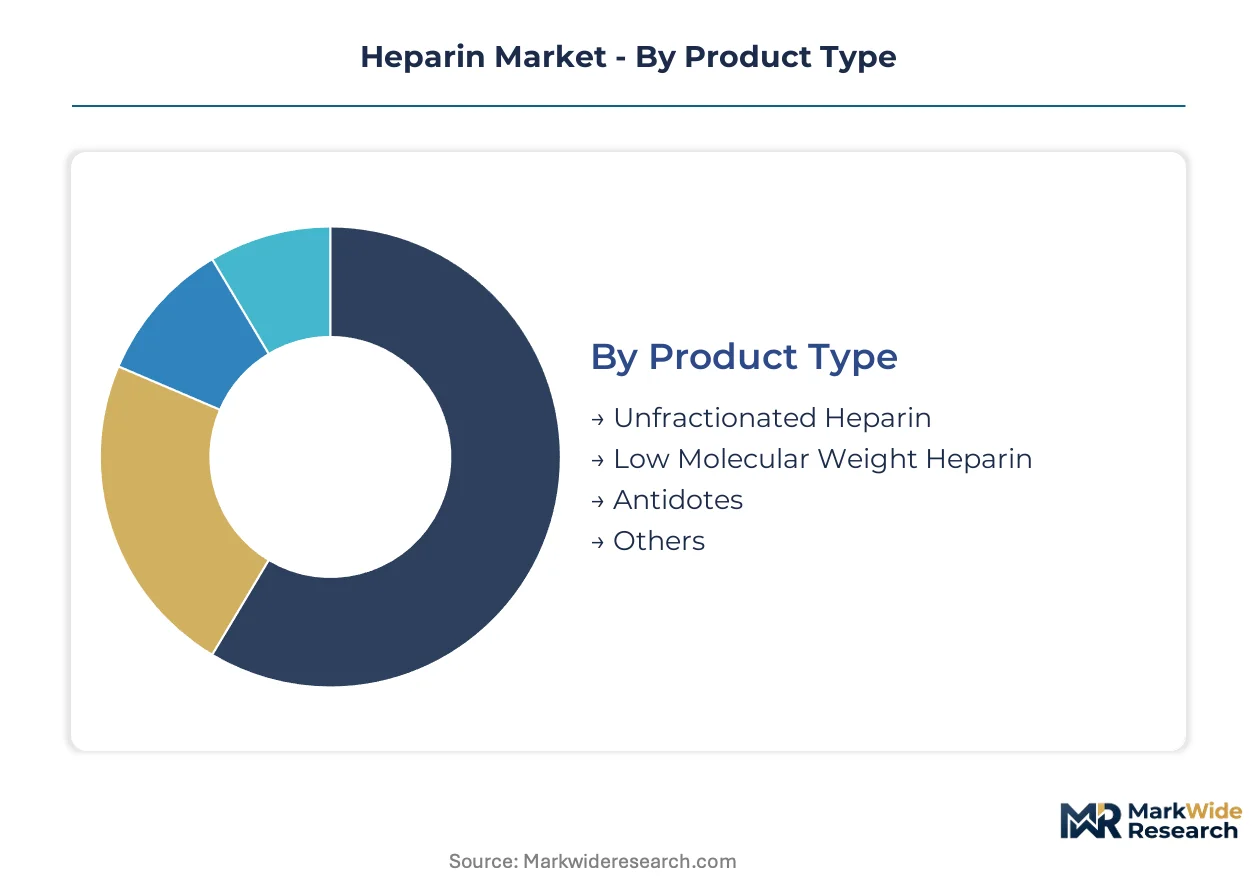
Heparin segmentation reveals how therapeutic requirements fragment across care settings. Product molecular weight determines monitoring intensity. Administration route selection hinges on reversibility needs versus outpatient convenience.
Product Type:
Mature formulations dominate hospital revenue while emerging biosynthesis technologies threaten porcine-derived supply chains.
- Unfractionated Heparin:Sulfated glycosaminoglycan chains averaging 15,000 daltons require activated partial thromboplastin time monitoring. Cardiac surgery centers in the United States and Germany sustain demand for its rapid protamine sulfate reversibility during extracorporeal circulation.
- Low Molecular Weight Heparin:Enzymatically depolymerized fractions of 4,000-5,000 daltons deliver predictable anti-factor Xa activity without routine coagulation assays. Outpatient orthopedic clinics and home care programs in France and Japan favor subcutaneous enoxaparin and dalteparin for deep vein thrombosis prophylaxis.
- Antidotes:Protamine sulfate remains the sole FDA-approved reversal agent for unfractionated heparin overdose.
- Others:Ultra-low molecular weight heparinoids and heparin-coated medical devices occupy niche anticoagulation roles.
Unfractionated heparin handles the majority of throughput in acute surgical settings; low molecular weight heparin is expanding most quickly into ambulatory care transitions.
End User:
Cost tier stratification separates capital-intensive tertiary centers from distributed outpatient channels.
- Hospitals:Tertiary medical centers with cardiac surgery and intensive care units consume unfractionated heparin through centralized pharmacy formularies. Direct-tender relationships with Pfizer and Baxter secure volume pricing for extracorporeal circuit anticoagulation protocols.
- Clinics:Ambulatory surgical centers and oncology infusion suites administer low molecular weight heparin for perioperative prophylaxis.
- Home Care:Visiting nurse services and self-instruction programs enable post-discharge subcutaneous therapy.
- Long-term Care Facilities:Skilled nursing facilities manage venous thromboembolism prevention in immobilized elderly populations.
Hospitals capture the highest absolute volume; home care shows the steepest expansion trajectory as integrated delivery networks push anticoagulation outside facility walls.
Administration Route:
Volume concentration favors injectable formats while patient preference pressures oral development.
- Intravenous:Continuous infusion via programmable pumps delivers immediate anticoagulation with titratable effect. Hemodialysis units and cardiac catheterization laboratories depend on this route for precise control during procedures.
- Subcutaneous:Abdominal or thigh injection of low molecular weight heparin enables outpatient therapy without venous access.
- Oral:No approved oral heparin formulation exists; synthetic direct oral anticoagulants compete for this administration preference.
- Others:Intramuscular and topical routes remain experimental or device-specific.
Intravenous administration anchors acute inpatient revenue; subcutaneous delivery is gaining share fastest through home care protocol expansion.
Distribution Channel:
Supply concentration clusters around institutional procurement while retail fragmentation accelerates.
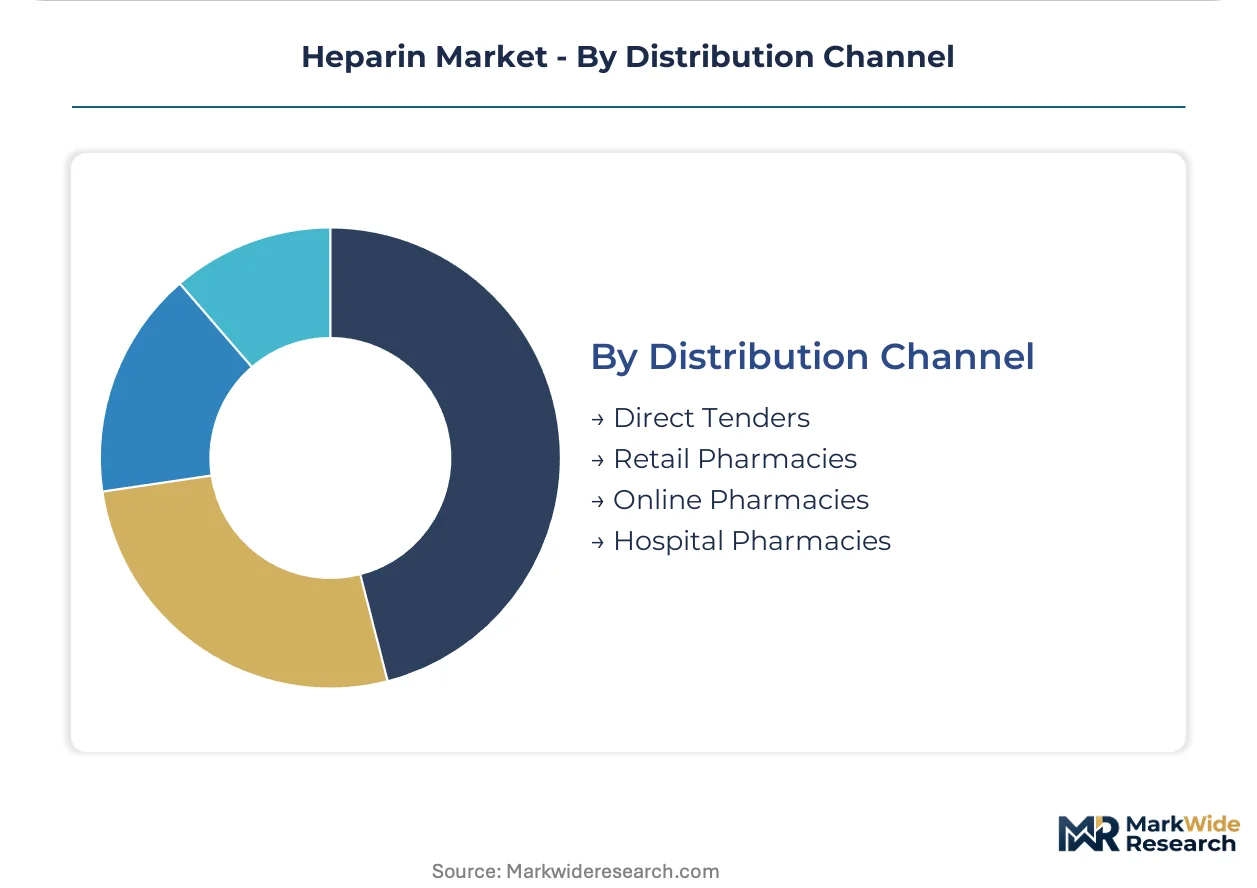
- Direct Tenders:Multi-year agreements between hospital systems and formulation manufacturers lock in unfractionated heparin supply for cardiac surgery volumes. Catholic hospital mergers in the United States Midwest have created purchasing coalitions exceeding 500 beds.
- Retail Pharmacies:Community pharmacies dispense low molecular weight heparin for outpatient prophylaxis prescriptions.
- Online Pharmacies:Mail-order and digital platforms serve chronic anticoagulation patients with recurring refill needs.
- Hospital Pharmacies:340B purchasing entities consolidate formulary decisions for integrated delivery networks.
Direct tenders command the largest contract value; online pharmacies are climbing the fastest as home care protocols extend treatment duration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shenzhen anchors Asia-Pacific heparin API throughput, handling enzymatic extraction feedstock from Chongqing processing clusters before trans-Pacific distribution to formulation sites in North America and Europe.
United States
Cardiac surgery centers at Cleveland Clinic and Mayo Clinic sustain unfractionated heparin demand for extracorporeal circulation protocols. FDA's tightened sodium monograph standards are forcing API importers to rebuild purification infrastructure. The Philadelphia-Wilmington corridor concentrates hospital pharmacy procurement for integrated delivery networks.
Germany
Tertiary cardiac centers in Munich and Heidelberg drive consumption of rapid-reversibility anticoagulants during valve replacement procedures. EMA's European Pharmacopoeia mandates molecular weight distribution profiling that creates batch release bottlenecks. The Frankfurt-Rhine-Main logistics hub coordinates API distribution to Central European formulation facilities.
China
Shenzhen Hepalink Pharmaceutical leverages backward integration into porcine intestine sourcing to secure raw material throughput. NMPA implements Good Manufacturing Practice inspections for facilities exporting sodium API to regulated markets. Chongqing's enzymatic extraction clusters are expanding capacity to meet international purity requirements.
Brazil
Hospital pharmacy expansion in São Paulo and Rio de Janeiro surgical centers is opening Latin America's largest anticoagulation market. ANVISA's accelerated registration pathway for essential medicines reduces entry timelines for imported formulations. The Port of Santos handles API shipments from Asian suppliers for local compounding operations.
Japan
Home care programs in Tokyo and Osaka are expanding subcutaneous low molecular weight heparin protocols for post-discharge thrombosis prophylaxis. PMDA enforces strict molecular weight distribution specifications for imported API batches. The Kansai region's medical device manufacturers are internalizing heparin surface-bonding expertise for coated catheter production.
Heparin Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in API extraction and purification. The heparin market structures around three tiers: multinational formulation houses with hospital direct-tender relationships, Chinese API processors with captive raw material access, and regional distributors serving fragmented clinic channels. Two strategic archetypes dominate—backward-integrated porcine processors and formulation specialists with intensive care unit formulary lock-in. Competitive moves concentrate on enzymatic yield improvement and GMP certification upgrades for regulatory market access.
Among multinational formulation houses, Pfizer and Baxter International exemplify platform dominance through hospital pharmacy relationships. Shenzhen Hepalink Pharmaceutical represents the backward-integrated API tier, anchoring Chinese supply concentration with upstream porcine sourcing control. These three occupy positions across the value chain that resist easy replication by competitors lacking equivalent raw material access or institutional procurement channels.
| Leading Market Players |
|---|
| Sanofi |
| Teva Pharmaceutical Industries |
| Pfizer |
| LEO Pharma |
| Aspen Holdings |
| Baxter International |
| Fresenius Kabi |
| Shenzhen Hepalink Pharmaceutical |
| B. Braun |
| Others |
Supply Flow & Price Mechanics
The Port of Shenzhen's trans-Pacific freight corridors transmit cost volatility from enzymatic extraction clusters to formulation sites, compressing margins for API importers while enabling three-tier pricing stratification across GMP-certified, standard-grade, and non-regulated supply tiers. Hospital procurement coalitions leverage volume concentration to extract rebates from formulation suppliers, forcing mid-scale processors to absorb logistics inflation or sacrifice market access.
Pricing Analysis
Three-tier pricing structure across GMP-certified, standard-grade, and non-regulated supply tiers separates hospital direct-tender contracts from clinic procurement and gray-market channels. Price differentiation hinges on FDA monograph compliance investment and backward integration into porcine intestine sourcing. Cost compression in standard-grade API is intensifying because EMA batch testing delays extend working capital cycles. Home care channels show highest price sensitivity due to reimbursement caps, while cardiac surgery centers prioritize rapid reversibility over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for API importers rebuilding purification infrastructure. Geographic supply concentration centers on China, Germany, and the United States, with enzymatic extraction clusters in Shenzhen and Chongqing feeding global formulation networks. Raw material dependencies rest on porcine intestinal mucosa, depolymerization enzymes, and sulfation reagents. Single-source vulnerability in southern China's raw material processing creates disease-outbreak exposure. Distribution runs through hospital pharmacy direct tenders, regional distributor networks, and emerging online pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as home anticoagulation protocols penetrate post-discharge thromboprophylaxis, extending treatment duration beyond hospital walls into visiting nurse services and self-instruction programs.
For Market Incumbents: Insulate formulation dominance by securing multi-year direct-tender renewals with cardiac surgery centers before biosimilar enoxaparin entry accelerates. Deepen upstream control over porcine intestine sourcing through captive slaughterhouse partnerships in Sichuan province, neutralizing raw material volatility that threatens margin stability. For New Entrants and Emerging Players: Build out Brazilian market presence through ANVISA's accelerated registration pathway for essential medicines, exploiting lagging local compounding capacity in São Paulo surgical centers. Target home care transitions with subcutaneous delivery training programs bundled with low molecular weight heparin supply contracts. For Investors and Strategic Acquirers: Chinese API processors with captive enzymatic extraction capacity and NMPA-GMP dual certification represent the most defensible acquisition archetype in a market consolidating around regulatory compliance moats. Synthetic heparin biosynthesis pilot-to-commercial scale-up timelines serve as the critical inflection signal for long-term porcine-derived demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Capacity Expansion | Shenzhen and Chongqing clusters improve yield rates from porcine intestinal mucosa feedstock. |
| FDA Monograph Compliance Investment | Purification infrastructure rebuilds enable API export access to regulated hospital markets. |
| Hospital Direct-Tender Consolidation | Catholic hospital mergers create multi-state purchasing coalitions exceeding 500 beds. |
| Home Care Protocol Development | Subcutaneous administration training extends therapy duration outside facility walls. |
| Synthetic Heparin Biosynthesis Scale-Up | Microbial fermentation with chemoenzymatic sulfation threatens porcine-derived supply chains. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital pharmacy directors, API manufacturing executives, regulatory affairs specialists, and GPO contract managers and refined through secondary validation against FDA heparin sodium monograph filings, EMA European Pharmacopoeia batch release records, NMPA GMP inspection reports, and customs trade data. Bottom-up volume estimates from enzymatic extraction capacity and top-down value projections from hospital procurement databases were triangulated to constrain forecast variance.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling patient population segmentation by treatment setting, molecular weight tier, administration route, and regional regulatory cluster. CAGRs were derived from surgical volume trajectories, biosimilar entry assumptions, and synthetic substitution elasticity parameters. Forecast inputs included cardiac surgery procedure counts, dialysis center expansion rates, and home care reimbursement policy shifts.
Stress conditions across porcine supply disruption, EMA batch testing duration extension, and synthetic heparin commercialization timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway stability and raw material sourcing continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Chitosan Supplements Market
Biomaterials
Bioceramics and Hydroxyapatite Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Pulp Cells Market
Biomaterials
Bone Substitutes Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
Orthopedic Bone Defect Repair Materials Market
Biomaterials
Chitosan Oligosaccharides and Glucosamine Market
Biomaterials
Bone Distractors Market
Biomaterials
Global Bioactive Materials Market
Biomaterials
Bone and Joints Ingredients Market
Biomaterials
Global Biomaterials Market
Biomaterials
Atelocollagen Market
Biomaterials
Mushroom Materials Market