
 Brazil Bone Graft and Substitutes Market | 2026-2036
Brazil Bone Graft and Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Bone Graft and Substitutes Market Intelligence
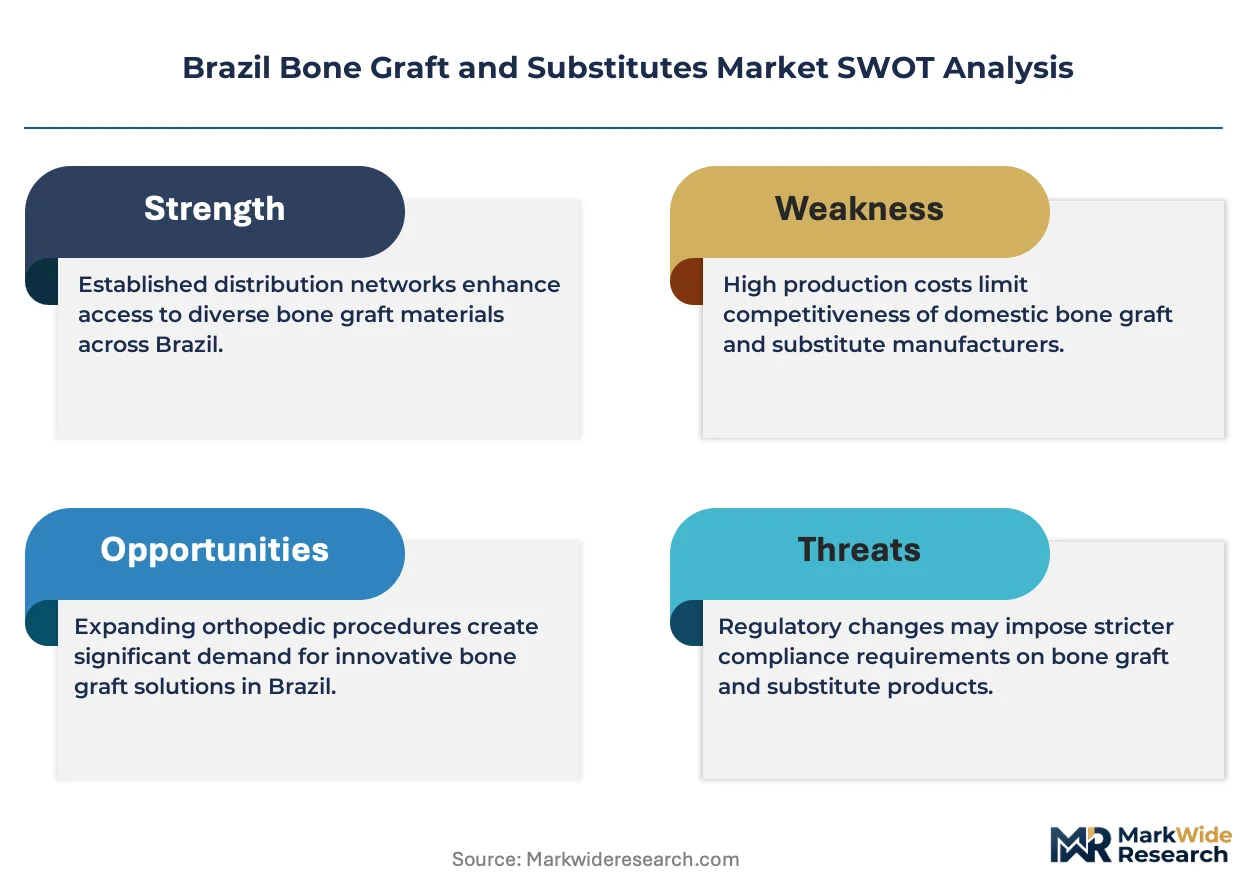
ANVISA's risk-based medical device reclassification is realigning procurement standards across Brazilian hospital networks. Depuy Synthes leverages its established distribution infrastructure to sustain dominant shelf presence in southeastern teaching hospitals. Zimmer Biomet anchors its competitive position through specialized synthetic graft portfolios calibrated for tropical climate storage conditions. Geistlich Pharma differentiates via premium xenograft formulations targeting dental implantology practices in Curitiba and Porto Alegre.
Bone grafts and substitutes comprise osteoconductive, osteoinductive, and osteogenic biomaterials—ranging from demineralized bone matrix to calcium phosphate ceramics—engineered to bridge skeletal defects and stimulate native bone regeneration. Synthetic grafts manufactured from beta-tricalcium phosphate and hydroxyapatite now command expanding share as surgeons seek alternatives to allograft supply variability. Autografts retain structural primacy in complex trauma reconstruction despite donor-site morbidity limitations. Ambulatory surgical centers represent the fastest-growing end-user channel as minimally invasive spine and dental procedures migrate from inpatient settings.
ANVISA collaborates with ISO standards to establish biocompatibility and sterility benchmarks for imported graft materials, while Brazil's national health surveillance system enforces traceability requirements from tissue bank to surgical suite. ANVISA's Good Manufacturing Practice audits for foreign suppliers create compliance barriers that favor incumbent distributors with established quality management systems. Stakeholders must monitor pending legislation on public procurement preference for domestically manufactured biomaterials, as local production incentives could reshape competitive access patterns within Brazil's unified health system and private payer networks.
Market Dynamics
ANVISA's risk-based medical device reclassification is compressing product registration timelines from 24 months to under 12 months for Class III biomaterials, forcing distributors to rebuild quality management systems around accelerated approval pathways.
Growth Catalysts
- Synthetic graft technology maturation:Beta-tricalcium phosphate formulations now match allograft osteoconduction rates in lumbar spinal fusion, driving hospital procurement committees toward predictable supply chains.
- Minimally invasive surgical migration:Ambulatory surgical centers in São Paulo's metropolitan corridor are expanding bone graft procedure volumes as outpatient spine and dental interventions displace inpatient admissions.
- ANVISA-ISO harmonization:Biocompatibility benchmarking alignment is reducing retesting burdens for European and North American manufacturers seeking Brazilian market entry.
Market Restraints
- Allograft supply variability:Brazil's limited tissue banking infrastructure creates batch-to-batch inconsistency in demineralized bone matrix availability, forcing surgeons toward higher-cost synthetic alternatives.
- Import dependency concentration:Over 70% of premium xenograft materials originate from Swiss and German manufacturing facilities, exposing distributors to currency fluctuation and shipping disruption risks.
- Autograft donor-site morbidity:Iliac crest harvesting complications limit structural graft availability for complex trauma reconstruction, capping addressable procedure volumes in high-acuity cases.
Strategic Opportunities
- Northeast regional penetration:Recife and Salvador hospital networks remain underserved by specialized orthopedic distributors, creating first-mover advantages for synthetic graft portfolios with tropical stability profiles.
- Public procurement preference legislation:Pending ANVISA-linked domestic manufacturing incentives could reshape SUS (Sistema Único de Saúde) tender participation rules, favoring local production partnerships.
- Digital surgical planning convergence:Patient-specific 3D-printed bone graft scaffolds are integrating with preoperative imaging workflows, opening premium pricing tiers for customized ceramic implants.
Industry Challenges
- Biomaterials engineering talent scarcity:Brazilian universities produce fewer than 150 specialized tissue engineering graduates annually, constraining R&D expansion for domestic manufacturers.
- ANVISA Good Manufacturing Practice audit timelines:Foreign supplier facility inspections currently average 18 months from application submission, delaying product launches and freezing distributor inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Bone Graft and Substitutes Market |
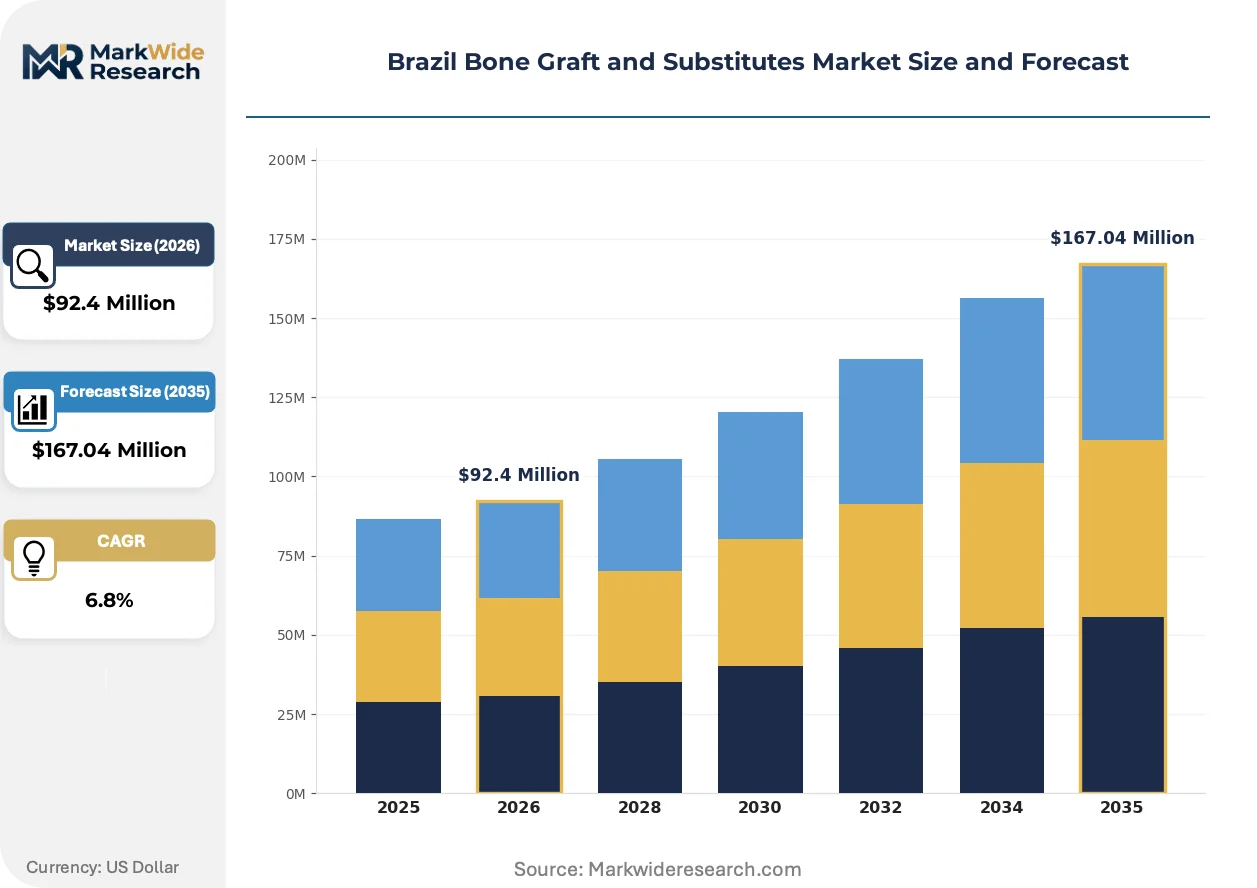
| Market Size in 2026 | $92.4 Million |
| Market Size in 2035 | $167.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Allografts, Autografts, Xenografts, Synthetic Grafts Application: Orthopedic Surgery, Dental Procedures, Spine Surgery, Trauma Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions Distribution Channel: Direct Sales, Distributors, Online Sales, Medical Supply Stores |
| Companies Covered | Depuy Synthes, Medtronic, NuVasive, Orthofix Medical, Stryker, Zimmer Biomet, Smith & Nephew, Geistlich Pharma, Baumer, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Bone Graft and Substitutes Market Strategic Shifts & Innovations
Synthetic bone graft materials are displacing biological alternatives through engineered predictability, while regulatory harmonization and procurement centralization reshape how biomaterials reach surgical suites across Brazilian hospital networks.
Engineered hydroxyapatite-calcium phosphate composites are integrating nanostructured surface architectures that accelerate osteointegration timelines. São Paulo's private hospital networks are adopting these materials for anterior cervical discectomy and fusion procedures at twice the rate of public institutions. This integration is compressing average hospital stays for spinal fusion patients from 4.2 days to 2.8 days, reallocating bed capacity toward higher-revenue orthopedic interventions.
ANVISA's updated medical device classification framework is eliminating redundant technical documentation requirements for Class IIa bone void fillers previously approved under MDR or FDA 510(k) pathways. Foreign manufacturers with existing ISO 13485 certifications now face streamlined conformity assessment procedures. Dental implantology practices in Curitiba and Porto Alegre are responding fastest, accelerating xenograft product registrations for periodontal bone regeneration applications.
Hospital procurement committees are consolidating vendor relationships around full-line distributors capable of delivering synthetic grafts, fixation hardware, and biologics through single-source contracts. This consolidation is displacing fragmented purchasing across separate orthopedic, spine, and dental supply channels. The shift is most visible in Rio de Janeiro's state hospital network, where unified tenders now cover 60% of biomaterial expenditures previously split among specialty distributors.
Brazil Bone Graft and Substitutes Market Segmentation
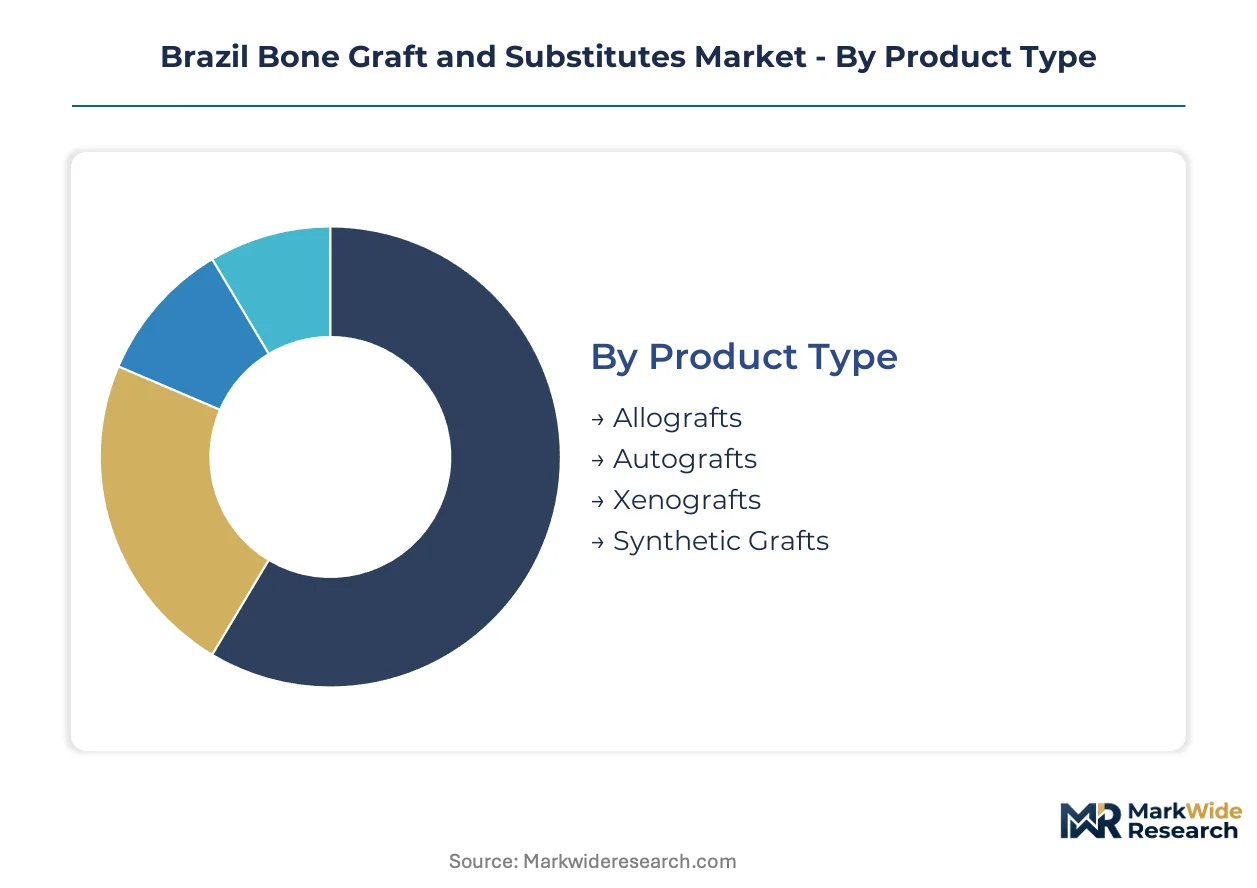
Brazil's bone graft market segments around surgical complexity, supply chain reliability, and procurement channel concentration. Each dimension reveals distinct competitive dynamics between multinational distributors and emerging domestic suppliers.
Product Type:
Procurement committees differentiate graft categories by supply predictability, biocompatibility certification burden, and storage infrastructure requirements.
- Synthetic Grafts:Engineered from beta-tricalcium phosphate and hydroxyapatite ceramics with standardized porosity profiles. São Paulo's private hospital networks favor these for spinal fusion due to elimination of allograft batch variability and simplified ANVISA traceability documentation.
- Allografts:Demineralized bone matrix and cancellous chips sourced from domestic tissue banks. Supply interruptions from Brazil's limited donor processing capacity push surgeons toward synthetic alternatives in trauma reconstruction cases.
- Xenografts:Bovine-derived hydroxyapatite formulations for dental ridge augmentation.
- Autografts:Iliac crest and fibula harvesting for complex orthopedic reconstruction.
Synthetic grafts lead volumes today; allografts are gaining share fastest in cost-sensitive SUS facilities.
Application:
Procedure reimbursement tiers and inpatient versus outpatient migration patterns shape demand concentration across surgical specialties.
- Spine Surgery:Lumbar interbody fusion and cervical discectomy procedures drive premium synthetic graft consumption. Minimally invasive techniques expanding in Curitiba and Porto Alegre ambulatory centers compress procedure timelines and elevate ceramic graft preference.
- Orthopedic Surgery:Long-bone fracture management and joint revision arthroplasty utilizing structural allografts and synthetic void fillers. Northeast Brazil's trauma centers face autograft harvesting limitations that expand addressable synthetic volumes.
- Dental Procedures:Periodontal bone regeneration and implant site preparation in southeastern specialty practices.
- Trauma Surgery:Acute fracture stabilization in public emergency networks.
Spine surgery commands premium pricing today; dental applications are expanding most quickly as implantology practices proliferate.
End User:
Facility scale determines procurement sophistication, inventory carrying capacity, and biologics handling certification requirements.
- Hospitals:Tertiary and quaternary centers with dedicated orthopedic and spine service lines. São Paulo's metropolitan corridor concentrates purchasing power through consolidated tenders covering grafts, fixation hardware, and biologics.
- Ambulatory Surgical Centers:Outpatient spine and dental facilities with streamlined supply chains and just-in-time inventory models. These centers favor pre-packaged synthetic graft kits with reduced sterilization overhead.
- Clinics:Private dental and orthopedic practices with direct distributor relationships.
- Research Institutions:University hospitals conducting clinical trials for novel biomaterial formulations.
Hospitals dominate procurement volumes today; ambulatory surgical centers are climbing the fastest as procedure migration accelerates.
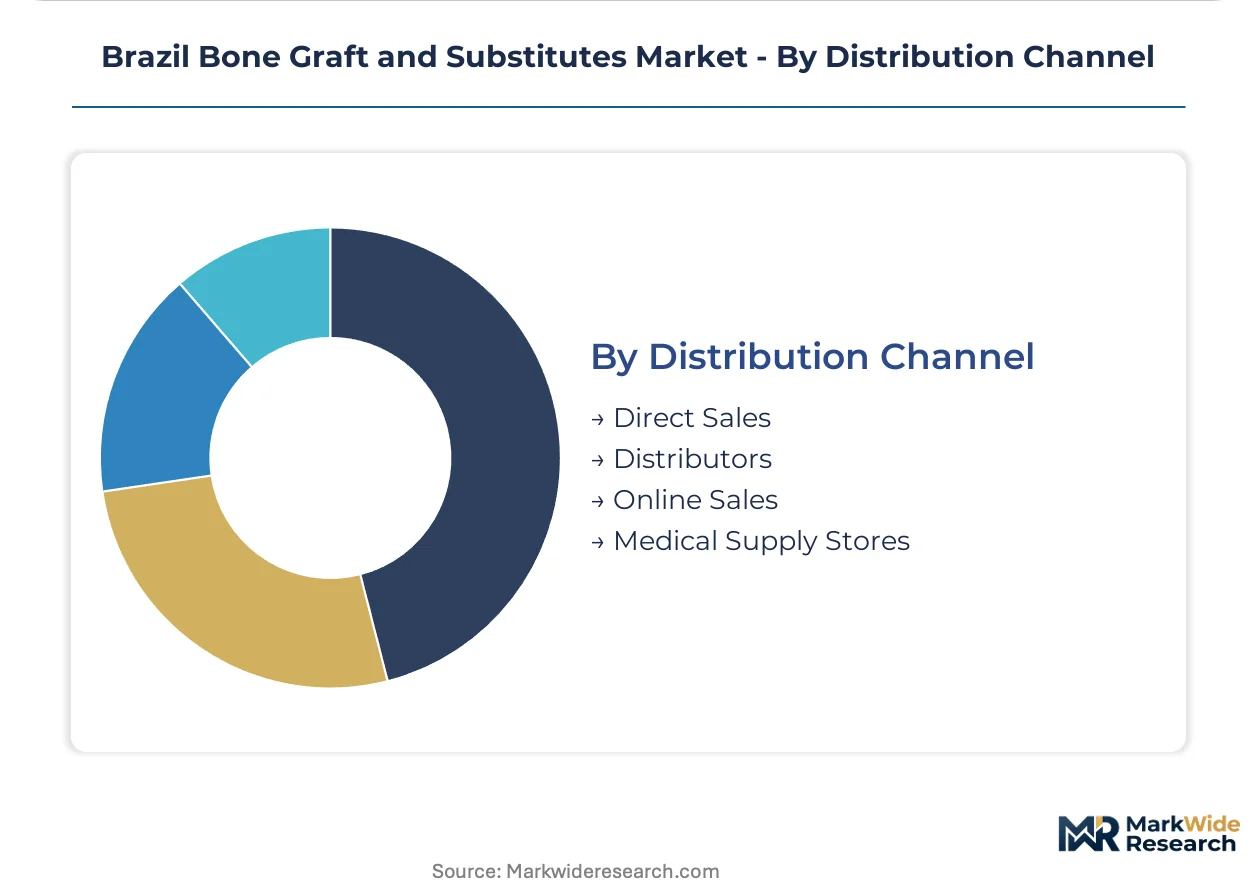
Distribution Channel:
Channel selection reflects geographic coverage requirements, technical support needs, and ANVISA regulatory compliance complexity.
- Distributors:Full-line orthopedic and dental suppliers with established ANVISA quality management systems and regional warehousing. These intermediaries manage import logistics, currency hedging, and hospital tender participation for foreign manufacturers.
- Direct Sales:Manufacturer-employed representatives serving high-volume hospital networks in Rio de Janeiro and São Paulo with technical training and surgical support.
- Medical Supply Stores:Local distributors serving smaller clinics with standard product configurations.
- Online Sales:Emerging platform-based procurement for non-critical consumables and research materials.
Distributor networks capture the largest volume share today; direct sales channels are expanding most rapidly among premium synthetic graft portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's bone graft industry traces its modern scale to the 1990s expansion of São Paulo's private hospital networks, which imported European and North American biomaterial technologies to serve Latin America's largest surgical volume market.
São Paulo
The metropolitan corridor concentrates over half of national spinal fusion procedures and houses the headquarters of all major distributor networks. ANVISA's regional office here accelerates product registration reviews for Class III biomaterials. Hospital Israelita Albert Einstein and Hospital das Clínicas anchor demand for premium synthetic grafts in complex orthopedic interventions.
Rio de Janeiro
State hospital network consolidation has unified 60% of biomaterial procurement through single-source tenders covering grafts, fixation hardware, and biologics. The state's trauma centers drive structural allograft consumption for acute fracture management. Copacabana's private specialty clinics favor pre-packaged synthetic kits for outpatient dental implantology.
Minas Gerais
Belo Horizonte's teaching hospitals train surgeons who disseminate technique standards across Brazil's interior. The state's tissue banking infrastructure remains underdeveloped, pushing procurement committees toward synthetic alternatives. Uberlândia's orthopedic centers represent the fastest-growing demand node outside the southeastern core.
Rio Grande do Sul
Porto Alegre's dental implantology practices accelerate xenograft registrations for periodontal bone regeneration. The state's German immigrant heritage sustained early adoption of Swiss and German-manufactured premium biomaterials. Caxias do Sul's industrial base supports emerging domestic ceramic processing capabilities.
Bahia
Salvador's hospital networks remain underserved by specialized orthopedic distributors, creating first-mover opportunities for synthetic graft portfolios with tropical stability profiles. The state's public health system depends on SUS tenders with extended payment cycles. Recife's trauma centers in neighboring Pernambuco face similar autograft harvesting limitations that expand addressable synthetic volumes.
Brazil Bone Graft and Substitutes Market Key Industry Players
Capital-heavy producers with captive manufacturing compete with asset-light distributors relying on foreign supplier relationships. The Brazilian market structures around three tiers: multinational orthopedic conglomerates with established ANVISA quality systems, European xenograft specialists with premium positioning, and emerging domestic ceramic processors. Consolidation pressures intensify as hospital procurement committees reduce vendor counts. Distributors defend position through backward integration into local warehousing and technical training capabilities.
Among the established multinational tier, Depuy Synthes and Zimmer Biomet exemplify archetypes of scale-driven market presence. Depuy Synthes leverages southeastern teaching hospital relationships built over two decades. Zimmer Biomet occupies a position calibrated for tropical climate storage requirements. Geistlich Pharma represents the European specialist archetype, anchoring premium xenograft positioning in dental implantology corridors.
| Leading Market Players |
|---|
| Depuy Synthes |
| Medtronic |
| NuVasive |
| Orthofix Medical |
| Stryker |
| Zimmer Biomet |
| Smith & Nephew |
| Geistlich Pharma |
| Baumer |
| Others |
Cost & Logistics Intelligence
Backward integration into regional warehousing anchors distributor pricing power across Brazil's bone graft market, compressing landed costs for Swiss and German xenograft imports while insulating hospital procurement committees from currency volatility and extended ANVISA inspection timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Geistlich Pharma's xenograft formulations from Depuy Synthes's mid-market synthetic portfolios and domestic ceramic alternatives. Price differentiation hinges on ANVISA registration tier and tropical climate stability certification. Cost compression in standard-tier beta-tricalcium phosphate is intensifying as Zimmer Biomet expands São Paulo distribution capacity. Public SUS facilities exhibit highest price sensitivity; private metropolitan hospital networks prioritize supply predictability over unit cost.
Supply Chain Analysis
Specialized biomaterials engineering talent scarcity in Swiss and German manufacturing hubs constrains premium xenograft production expansion, forcing Brazilian distributors to carry 90-day inventory buffers. Supply concentrates in Switzerland, Germany, and emerging domestic ceramic processors in Rio Grande do Sul. Raw material dependencies span pharmaceutical-grade hydroxyapatite precursors, bovine-derived bone mineral matrices, and ISO-certified packaging films. Single-source vulnerability runs through Swiss xenograft facilities dependent on alpine cattle sourcing protocols. Distribution runs through full-line orthopedic distributors with ANVISA-certified quality management systems and regional cold-chain warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's bone graft market functions as a geographic-arbitrage play where European manufacturers leverage ANVISA-ISO harmonization to bypass redundant biocompatibility testing, capturing margin premiums unavailable in saturated Western European hospital procurement markets.
For Market Incumbents: Deploy certification leverage to lock in multi-year hospital system contracts before pending domestic manufacturing preference legislation reshapes SUS tender participation rules. Deepen backward integration into Belo Horizonte warehousing to compress delivery timelines for Minas Gerais trauma centers facing autograft harvesting limitations. Counter emerging domestic ceramic processors by bundling synthetic grafts with spinal fixation hardware through single-source procurement contracts. For New Entrants and Emerging Players: The 40-60% price-point gap between premium Swiss xenografts and economy-tier domestic ceramics opens viable positioning for tropical-stabilized synthetic portfolios in Salvador and Recife hospital networks. Target Bahia and Pernambuco trauma centers underserved by specialized orthopedic distributors. Accelerate ANVISA Class IIa registrations through streamlined conformity assessment for ISO 13485-certified European manufacturers. Lead with ambulatory surgical center partnerships as outpatient spine procedures migrate from inpatient settings. For Investors and Strategic Acquirers: Roll-up economics work for regional distributor consolidation because hospital procurement committees are reducing vendor counts from 12-15 to 3-4 full-line suppliers per metropolitan network. Long-term viability centers on capturing SUS tender participation as domestic manufacturing incentives mature. Target acquisition archetype: southeastern distributors with established ANVISA quality systems and existing relationships with Hospital Israelita Albert Einstein or Hospital das Clínicas. Monitor ANVISA Good Manufacturing Practice audit queue depth as inflection indicator for foreign supplier entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Class III Registration Acceleration | Compresses 24-month approval timelines to under 12 months for beta-tricalcium phosphate formulations. |
| Hospital System Partnership Consolidation | Rio de Janeiro's unified tenders now cover 60% of biomaterial expenditures through single-source contracts. |
| Tropical Stability Certification Investment | Zimmer Biomet's climate-calibrated portfolios command shelf preference in São Paulo's humidity-exposed supply chains. |
| Northeast Regional Distribution Buildout | Recife and Salvador networks remain underserved by specialized orthopedic distributors with ANVISA-certified warehousing. |
| Domestic Manufacturing Incentive Positioning | Pending SUS procurement preference legislation favors local production partnerships for unified health system access. |
Research Approach
Bottom-up procedure volume modeling reconciled against top-down import tracking forms the analytical core of this study. Primary interviews with orthopedic surgeons, hospital purchasing committee directors, biomedical engineers, and ANVISA regulatory affairs specialists were cross-validated against secondary sources including ANVISA medical device registration databases, hospital procurement tender records, and ISO 13485 certification registries. Trade flow analysis of hydroxyapatite and beta-tricalcium phosphate imports through Brazilian customs authorities provided supply-side calibration.
Historical trendline analysis of spinal fusion and dental implantology procedure volumes established baseline growth trajectories across the projection horizon. The analytical framework segmented demand by product type, application specialty, end-user facility scale, and distribution channel concentration. CAGRs were derived from regression analysis of import value trends and hospital expenditure patterns. Industry-specific forecast inputs incorporated ANVISA registration queue dynamics and ambulatory surgical center expansion timelines.
Caveats apply where ANVISA audit timeline extensions or currency fluctuation spikes could materially shift the outlook for foreign supplier market entry. Forecasts reflect assumptions regarding continued ISO harmonization and stable tissue banking infrastructure development. Material deviation in pending domestic manufacturing legislation or Swiss-German xenograft supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Atelocollagen Market
Biomaterials
Self-Healing Materials Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Global Biomaterials Market
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Pulp Cells Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Global Medical Engineered Materials Market
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Europe Collagen Market
Biomaterials
Self-Healing Hydrogels Market
Biomaterials
Hydrogel Market
Biomaterials
Global Collagen and HA Based Biomaterial Market
Biomaterials
Biomaterial in Surgical Mesh Market
Biomaterials
Mushroom Materials Market