
 Europe Active Pharmaceutical Ingredients (API) Market | 2026-2036
Europe Active Pharmaceutical Ingredients (API) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Active Pharmaceutical Ingredients (API) Market Analytics
Oncology formulation demand is decoupling from traditional cardiovascular API volumes across European manufacturing networks. Boehringer Ingelheim International GmbH leverages its Ludwigshafen biotech hub to anchor mammalian cell culture capacity for monoclonal antibody precursors. Merck KGaA sustains dominance in high-potency API containment through proprietary isolation technology. EUROAPI competes on fermentation-derived steroid intermediates from its Toulouse operations.
Active pharmaceutical ingredients are pharmacologically active substances in finished drug products, synthesized through multi-step organic chemistry, recombinant DNA technology, or microbial fermentation to achieve specified purity thresholds typically exceeding 99.5%. These compounds serve as the therapeutic foundation for dosage forms ranging from oral tablets to injectable biologics. Generic API manufacturing commands the largest volume share but faces margin compression from Indian and Chinese import competition, while biotech API production captures premium pricing due to cold-chain requirements and biosimilar expansion. Contract API services are accelerating fastest as pharmaceutical companies divest captive manufacturing to focus on discovery pipelines.
EMA's ICH Q7 good manufacturing practice guidelines and the EU's F-Gas Regulation on fluorinated greenhouse gases shape facility investment decisions across European API sites. REACH chemical registration requirements and the EU Green Deal's pharmaceutical sector sustainability targets are forcing solvent recovery and continuous flow chemistry adoption. Stakeholders must monitor how the EU AI Act's deployment rules affect automated process analytical technology systems in GMP environments.
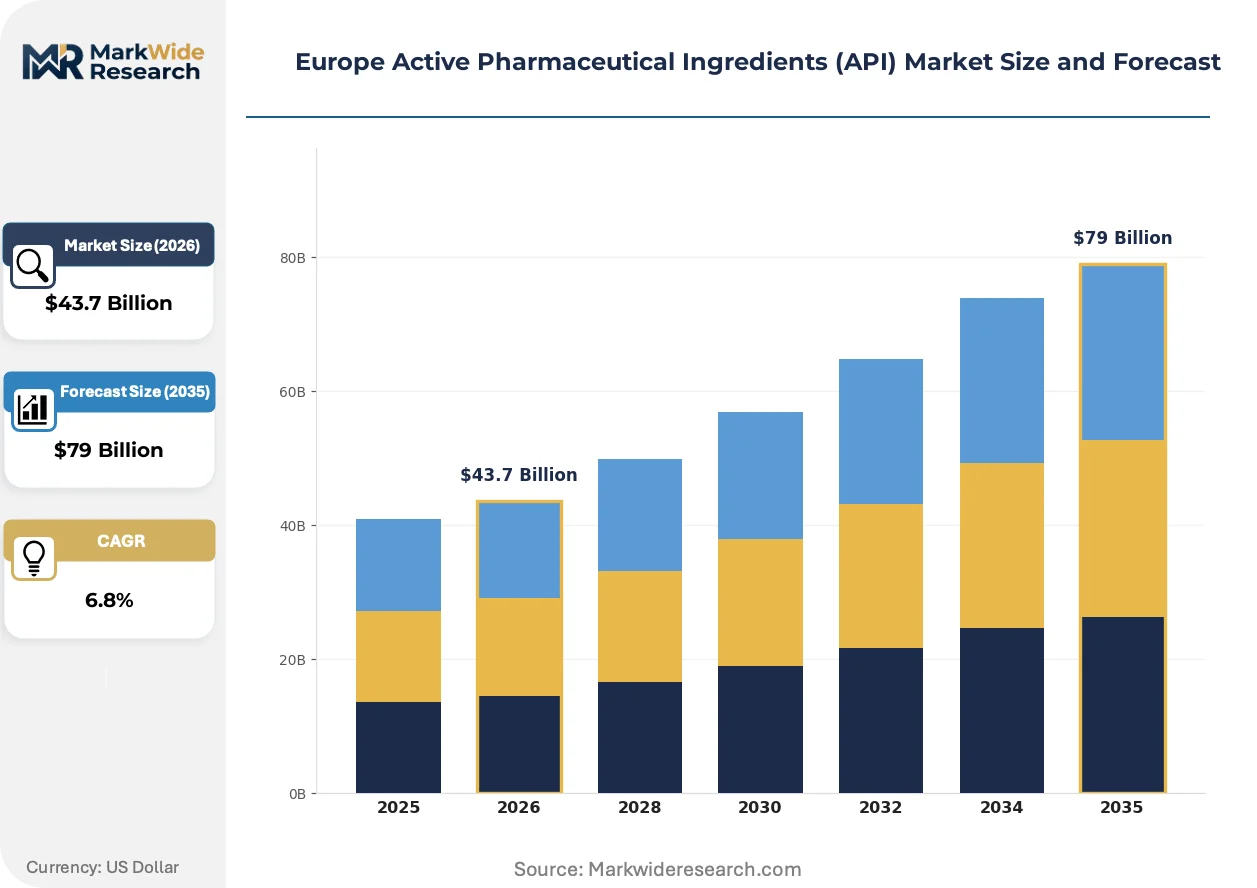
Market Dynamics
EMA's tightened ICH Q7 guidelines and the EU F-Gas Regulation are forcing API manufacturers toward continuous flow chemistry and closed-system containment, compressing legacy batch production economics while favoring capital-intensive biotech facilities.
Growth Catalysts
- Oncology biologics surge:Germany's Rhine-Main cluster anchors mammalian cell culture expansion for monoclonal antibody precursors, pulling fermentation capacity from traditional small-molecule sites.
- REACH chemical registration:The EU's substance evaluation framework is accelerating solvent recovery investments as manufacturers preempt authorization restrictions on high-volume organic intermediates.
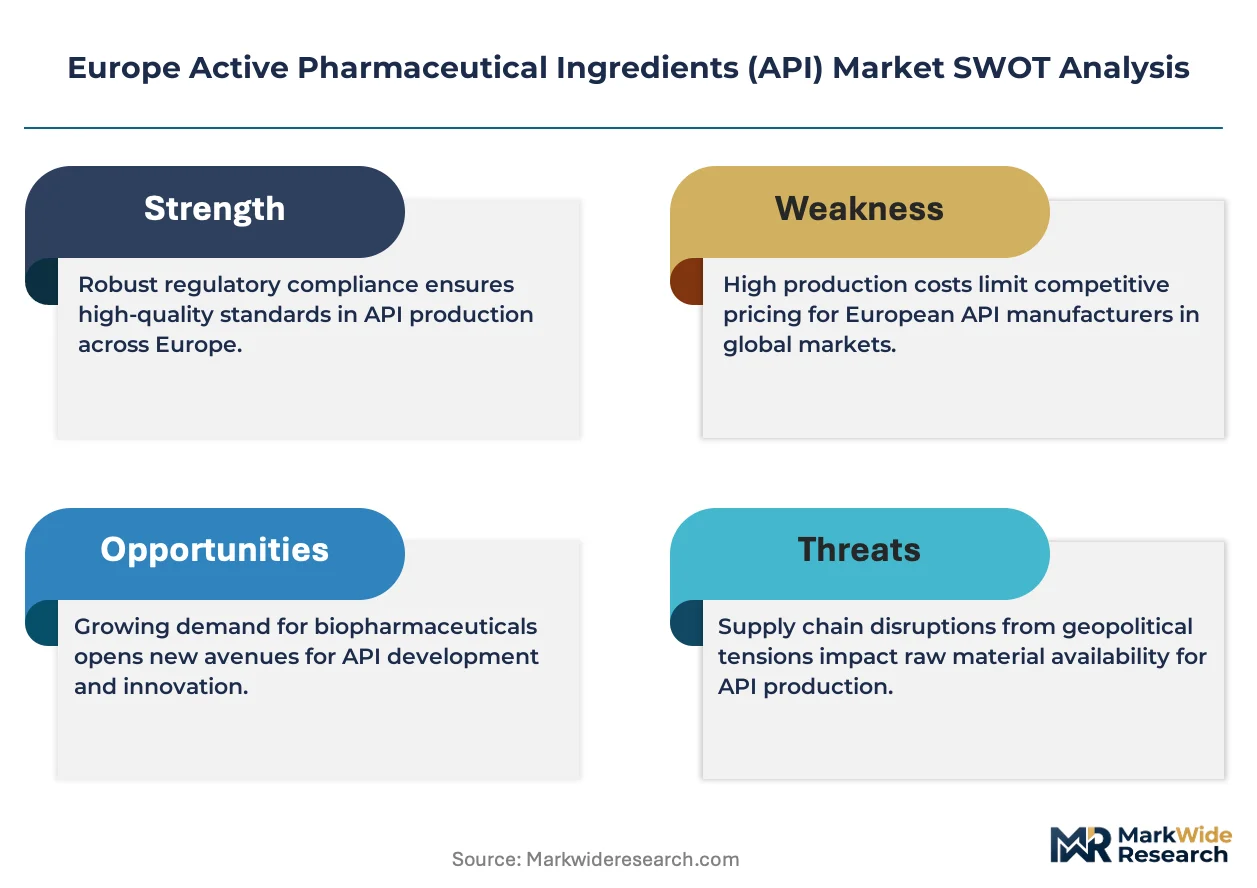
- Biosimilar pipeline depth:French and Italian developers are expanding biotech API procurement to secure post-patent biologic supply, creating captive demand for mammalian expression systems.
Market Restraints
- Indian and Chinese import competition:Generic API manufacturing faces sustained margin compression from offshore suppliers operating under lower environmental compliance costs.
- Fluorinated gas containment costs:The EU F-Gas Regulation mandates expensive isolation technology retrofits for facilities using hydrofluorocarbon-based cooling in cryogenic processes.
- Biotech cold-chain infrastructure:Temperature-controlled logistics requirements limit distribution radius and lock producers into high fixed-cost structures.
Strategic Opportunities
- Poland and Czech Republic expansion:Central European manufacturing zones offer lower-cost fermentation capacity within EU regulatory jurisdiction for mid-volume steroid intermediates.
- EU Green Deal pharmaceutical targets:Sustainability mandates create first-mover advantage for producers deploying enzymatic catalysis and bio-based solvent systems.
- Continuous flow chemistry convergence:Integration of process analytical technology with modular reactor systems enables real-time quality release and reduced batch failure rates.
Industry Challenges
- Containment engineering talent scarcity:High-potency API facilities face recruitment gaps for qualified isolation technologists and occupational exposure specialists.
- Legacy batch system integration:Retrofitting continuous flow modules into existing GMP-validated infrastructure requires extended regulatory requalification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Active Pharmaceutical Ingredients (API) Market |
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generic API, Branded API, Biotech API, Contract API Manufacturing Method: Synthetic, Biotechnology, Fermentation, Extraction End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Hospitals Therapy Area: Oncology, Cardiovascular, Neurology, Infectious Diseases |
| Companies Covered | Boehringer Ingelheim International GmbH, Merck & Co., Inc., Cipla, Inc., Sun Pharmaceutical Industries Ltd., AbbVie, Inc., Teva Pharmaceutical Industries Ltd., BASF SE, Merck KGaA, EUROAPI, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Active Pharmaceutical Ingredients (API) Market Evolving Landscape
Process intensification technologies are compressing traditional multi-step synthesis timelines, while regulatory pressure on environmental footprint forces simultaneous adoption of green chemistry principles across European API sites.
Single-use bioreactor systems are unifying upstream cell culture with downstream purification in modular configurations. Mid-scale biotech manufacturers across the Netherlands and Belgium are deploying these disposable technologies to reduce cross-contamination risk and accelerate product changeover. This unifying architecture is compressing facility build-out timelines from five years to eighteen months for mammalian-derived APIs.
The EU AI Act's deployment rules for automated process analytical technology are reshaping GMP facility design. Manufacturers must now validate algorithmic control systems for real-time release testing under EMA supervision. High-potency containment sites in Germany and Switzerland face the steepest compliance curves as they retrofit legacy distributed control systems.
Pharmaceutical companies are consolidating supplier relationships around full-service CDMO partnerships. Small and mid-cap drug developers in France and Italy are abandoning fragmented sourcing across multiple API and formulation vendors. This concentration is most visible in oncology, where integrated biotech API-to-drug-product supply chains reduce technology transfer risk and accelerate IND timelines.
Europe Active Pharmaceutical Ingredients (API) Market Segmentation
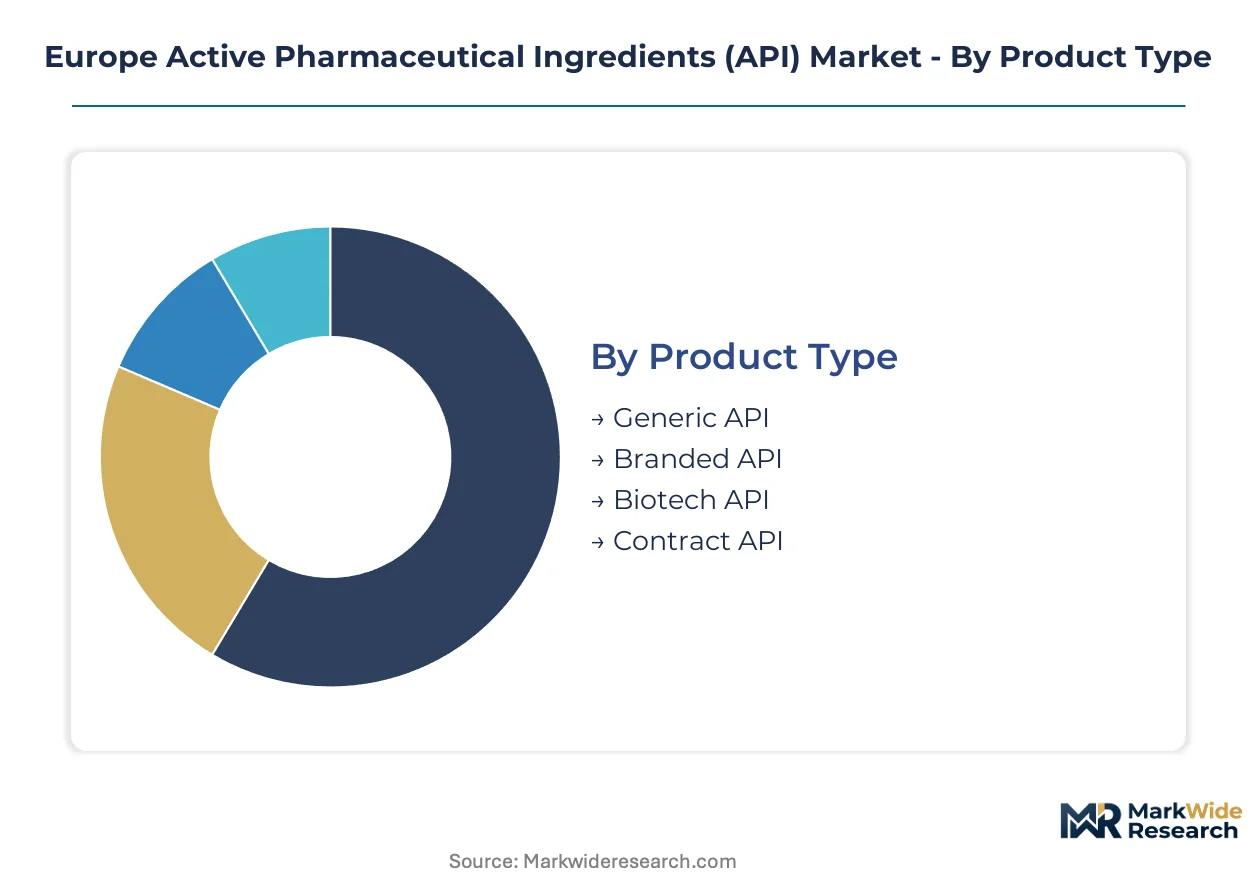
API segmentation in Europe reveals a market bifurcating between high-volume commodity production and precision biologics manufacturing. Understanding these divides exposes where capital is concentrating and which regulatory pressures reshape facility economics across the Rhine-Main corridor and beyond.
Product Type:
Generic API commands volume leadership while biotech API captures margin premiums through cold-chain complexity and biosimilar expansion.
- Generic API:Mass-produced small-molecule compounds synthesized through established chemical routes, typically achieving purity thresholds above 99.5%. Indian and Chinese import competition compresses margins for European producers, forcing consolidation around specialized high-potency niches or backward integration into formulation.
- Biotech API:Mammalian and microbial-derived proteins requiring aseptic cell culture, viral clearance validation, and continuous cold-chain stewardship. Germany's Ludwigshafen and Belgium's Ghent clusters anchor capacity expansion as French and Italian developers secure post-patent biologic supply.
- Branded API:Patent-protected innovator compounds with captive manufacturing or exclusive CDMO relationships. EMA's tightened ICH Q7 guidelines extend validation timelines for new molecular entities.
- Contract API:Outsourced manufacturing services spanning route development to commercial supply. Pharmaceutical divestment of captive facilities accelerates demand for integrated CDMO partnerships across oncology pipelines.
Today's leader: Generic API. Tomorrow's challenger: Biotech API.
Manufacturing Method:
Synthetic chemistry dominates installed capacity while biotechnology reshapes capital allocation toward mammalian expression systems.
- Synthetic:Multi-step organic chemistry employing catalytic hydrogenation, cryogenic reactions, and chromatographic purification. REACH authorization pressures and EU Green Deal solvent restrictions force continuous flow retrofits at legacy batch facilities in the Netherlands and Spain.
- Biotechnology:Recombinant DNA platforms utilizing CHO cells, E. coli, or yeast hosts for protein expression. Single-use bioreactor adoption compresses facility build-out from five years to eighteen months across Belgian and Dutch mid-scale sites.
- Fermentation:Microbial cultivation for antibiotic, steroid, and vitamin intermediates. EUROAPI's Toulouse operations anchor European fermentation capacity for corticosteroid precursors.
- Extraction:Isolation of natural product APIs from plant or animal biomass. Limited European footprint concentrates in Alpine regions with traditional botanical processing heritage.
Synthetic methods retain volume dominance. Biotechnology is gaining share fastest through monoclonal antibody precursor demand.
End User:
Pharmaceutical companies anchor demand while contract manufacturers capture outsourcing momentum from pipeline divestment strategies.
- Pharmaceutical Companies:Integrated innovators and generic houses sourcing APIs for captive formulation or arm's-length supply. Boehringer Ingelheim and Merck KGaA maintain verticalized production for high-potency and biotech portfolios.
- Contract Manufacturers:CDMOs and CMOs providing toll manufacturing across synthetic and biologic modalities. Consolidation around full-service partnerships accelerates as French and Italian mid-caps abandon fragmented vendor structures.
- Research Institutions:Academic and government laboratories procuring reference standards and investigational compounds for preclinical development. Limited volume but premium pricing for GMP-grade materials.
- Hospitals:Compounding pharmacies and health systems sourcing extemporaneous preparation ingredients. Regulatory divergence across EU member states fragments procurement standardization.
Pharmaceutical companies remain the anchor customer. Contract manufacturers represent the steepest expansion trajectory as outsourcing deepens.
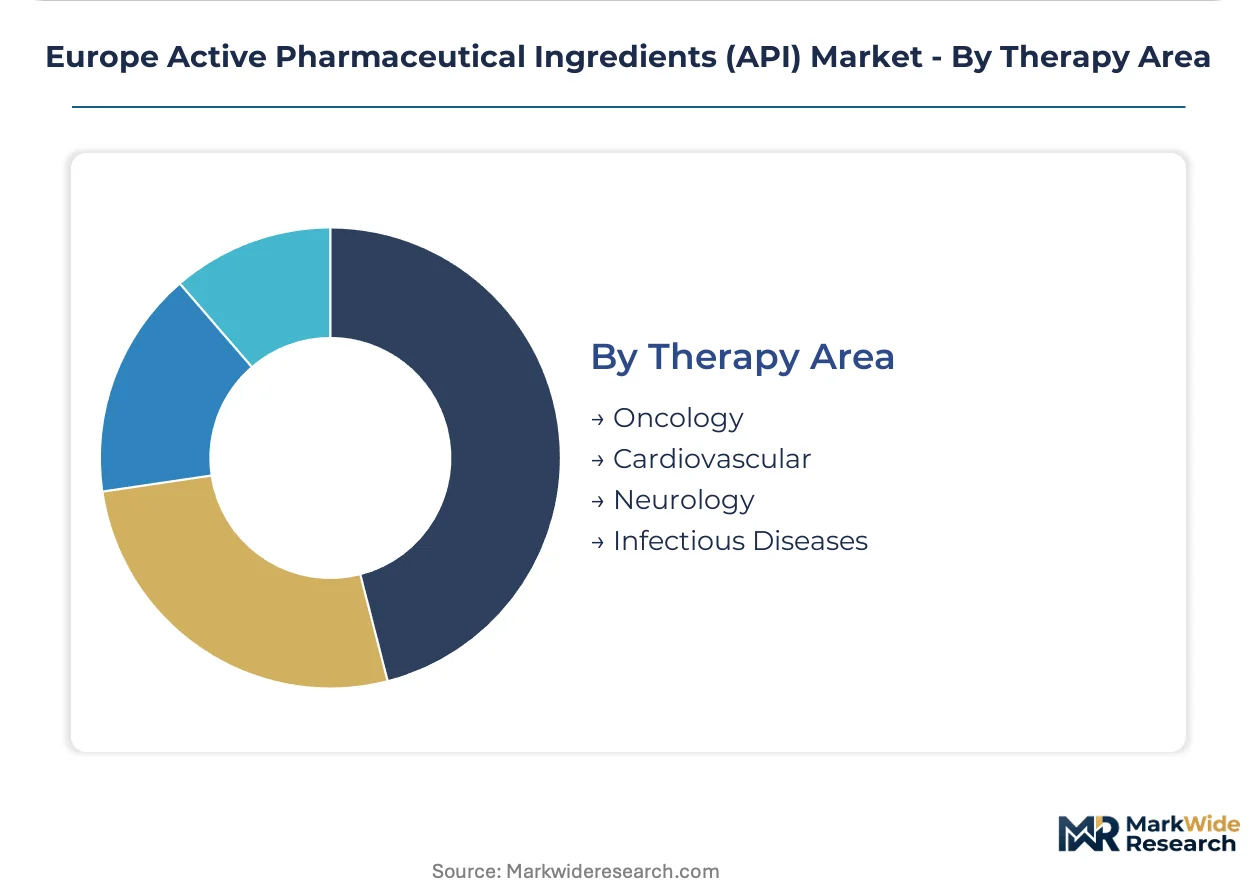
Therapy Area:
Oncology biologics pull capacity from cardiovascular small-molecules, reshaping regional specialization across European manufacturing networks.
- Oncology:Cytotoxic agents, monoclonal antibodies, and antibody-drug conjugates requiring containment engineering and aseptic processing. Germany's Rhine-Main cluster anchors mammalian cell culture expansion for HER2 and PD-1 targeted therapies.
- Cardiovascular:Statins, anticoagulants, and antihypertensives facing generic saturation and Indian import displacement. Legacy fermentation capacity in Southern Europe retools toward higher-margin specialties.
- Neurology:CNS-active compounds with blood-brain barrier penetration challenges and controlled-substance scheduling. High-potency containment requirements limit viable supplier pools.
- Infectious Diseases:Antibiotics, antivirals, and antifungals confronting resistance-driven formulation complexity. Fermentation-derived beta-lactams compete with fully synthetic alternatives on total cost.
Oncology leads therapeutic demand. Infectious diseases face structural pressure from resistance economics and reimbursement compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redirecting API investment toward Central European jurisdictions with lower environmental compliance costs while legacy manufacturing clusters in Western Europe absorb containment technology retrofits mandated by EMA and the EU F-Gas Regulation.
Germany
Oncology biologics developers in the Rhine-Main corridor are expanding mammalian cell culture capacity for monoclonal antibody precursors. EMA's tightened ICH Q7 guidelines extend validation timelines for new molecular entities. Boehringer Ingelheim's Ludwigshafen biotech hub anchors fermentation capacity pulled from traditional small-molecule sites.
France
French pharmaceutical developers are consolidating biotech API procurement to secure post-patent biologic supply chains. The EU Green Deal's pharmaceutical sector sustainability targets accelerate solvent recovery investments at legacy batch facilities. EUROAPI's Toulouse operations anchor European fermentation capacity for corticosteroid intermediates.
Italy
Italian generic houses face sustained margin compression from Indian and Chinese import competition in cardiovascular API segments. REACH authorization pressures on high-volume organic intermediates force continuous flow chemistry retrofits. Northern Italian manufacturing zones retool fermentation assets toward higher-margin oncology specialties.
Belgium
Mid-scale biotech manufacturers are deploying single-use bioreactor systems to compress facility build-out timelines from five years to eighteen months. The EU AI Act's deployment rules for automated process analytical technology reshape GMP facility design requirements. Ghent clusters anchor disposable technology adoption for mammalian-derived APIs.
Poland
Central European manufacturing zones offer lower-cost fermentation capacity within EU regulatory jurisdiction for mid-volume steroid intermediates. The F-Gas Regulation's hydrofluorocarbon containment mandates are less burdensome on new-build facilities than legacy retrofits. Warsaw and Krakow industrial parks attract contract API investment from Western European divestment strategies.
Europe Active Pharmaceutical Ingredients (API) Market Competitive Landscape
Capacity expansion dominates the current landscape as pharmaceutical companies divest captive manufacturing to focus on discovery pipelines. The vendor base stratifies between integrated innovators maintaining verticalized production, full-service CDMOs capturing outsourcing momentum, and commodity generic suppliers facing offshore displacement. Three archetypes define competitive positioning: biotech specialists commanding cold-chain premiums, high-potency containment engineers with proprietary isolation technology, and fermentation-derived intermediate producers competing on scale. M&A consolidation and strategic CDMO partnerships represent the dominant competitive moves reshaping supplier relationships.
Among Germany-based integrated innovators, Boehringer Ingelheim International GmbH and Merck KGaA exemplify the verticalized production archetype, while EUROAPI occupies a position representing the contract manufacturing tier. These entities anchor distinct competitive vectors—mammalian cell culture capacity, high-potency containment engineering, and fermentation-derived steroid intermediates—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| Merck & Co., Inc. |
| Cipla, Inc. |
| Sun Pharmaceutical Industries Ltd. |
| AbbVie, Inc. |
| Teva Pharmaceutical Industries Ltd. |
| BASF SE |
| Merck KGaA |
| EUROAPI |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's pharmaceutical sector sustainability targets gate qualified supply access and premium-tier pricing for European API manufacturers. EMA's tightened ICH Q7 guidelines and REACH authorization pressures create a bifurcation where only capital-intensive facilities with solvent recovery systems and continuous flow chemistry qualify for high-margin oncology biologics contracts.
Pricing Analysis
Direct-to-pharmaceutical-manufacturer contracting eliminates distributor margins for high-volume generic APIs, while CDMO partnerships command project-based premiums for biotech modalities. Price differentiation rests on certification tier—EMA-validated facilities versus REACH-registered-only sites—and cold-chain infrastructure depth. Cost compression in generic small-molecule segments intensifies because Indian and Chinese import competition operates under lower environmental compliance burdens. Generic houses exhibit highest price sensitivity; innovator biotech developers prioritize supply security over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from EMA and national pharmaceutical regulators mandate multi-supplier qualification for critical oncology APIs, forcing developers to maintain qualified relationships across Germany, Belgium, and Switzerland despite concentration economics. Raw material dependencies center on Chinese-sourced fermentation feedstocks, Indian-manufactured chemical intermediates, and specialized containment equipment from German engineering suppliers. Single-source vulnerability in high-potency isolation technology creates supply chain risk. Distribution runs through temperature-controlled logistics networks anchored at Rhine-Main and Ghent clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in Central European manufacturing zones where lower environmental compliance costs intersect with EU regulatory jurisdiction, creating margin expansion potential against Western European legacy facilities absorbing F-Gas Regulation retrofit burdens.
For Market Incumbents: Anchor mammalian cell culture capacity in the Rhine-Main corridor to defend against CDMO consolidation threatening captive manufacturing relationships. Deepen backward integration into fermentation feedstock supply to offset Chinese import price volatility. Prioritize continuous flow chemistry retrofits at legacy batch facilities to preempt REACH authorization restrictions on high-volume organic intermediates.
For New Entrants and Emerging Players: Digital-channel route-to-market partnerships with mid-cap French and Italian oncology developers bypass established CDMO incumbents. Target Poland and Czech Republic manufacturing zones for mid-volume steroid intermediate production where F-Gas Regulation compliance costs favor greenfield builds over legacy retrofits. Pursue single-use bioreactor deployment to compress facility qualification timelines.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale fermentation specialists because EMA validation timelines and containment engineering talent scarcity create barriers to organic capacity expansion. Platform consolidation across Belgian and Dutch disposable technology sites offers long-term viability through biosimilar pipeline depth. Watch monoclonal antibody precursor demand signals from German Rhine-Main cluster expansion announcements as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Retrofit | REACH authorization pressures force solvent recovery investments at legacy batch facilities in the Netherlands and Spain. |
| Single-Use Bioreactor Deployment | Belgian and Dutch mid-scale sites compress mammalian cell culture facility build-out from five years to eighteen months. |
| Central European Manufacturing Expansion | Poland and Czech Republic zones offer lower-cost fermentation capacity within EU regulatory jurisdiction. |
| Integrated CDMO Partnership Consolidation | French and Italian developers abandon fragmented vendor structures to reduce technology transfer risk in oncology pipelines. |
| Containment Technology Investment | EU F-Gas Regulation mandates expensive isolation retrofits for hydrofluorocarbon-based cryogenic processes. |
Research Methodology
Multiple input streams—primary interviews with drug development executives, regulatory affairs leads, and hospital procurement managers; secondary validation through EMA submissions, ClinicalTrials.gov, and customs trade data; plus bottom-up facility capacity modeling reconciled against top-down therapeutic demand projections—were synthesized to construct market estimates across the analysis window.
Historical volume trajectories were cross-referenced against expert panel inputs on biosimilar pipeline timing and containment technology adoption curves. The analytical framework segments by product type, manufacturing method, therapy area, and regional regulatory cluster. CAGRs derive from facility expansion announcements, CDMO contract visibility, and therapeutic demand elasticity modeling. Forecast inputs incorporate REACH authorization timelines and EU AI Act deployment rules for automated process analytical technology.
The model assumes a particular technology adoption path; alternative pathways for enzymatic catalysis and bio-based solvent systems would alter the outlook. Forecasts reflect assumptions around EMA validation timeline stability and F-Gas Regulation enforcement consistency. Deviation in Chinese or Indian environmental compliance cost trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Oxycodone Drugs Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Co-Crystal Ingredient Market
Pharmaceutical Ingredients
Glycylglycine Market
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Chlorzoxazone Market
Pharmaceutical Ingredients
Metformin Hydrochloride API Market