
 Spine Surgery Gels Market | 2026-2036
Spine Surgery Gels Market Size, Share, and Industry Trends Forecast 2026-2036
Spine Surgery Gels Market Insights
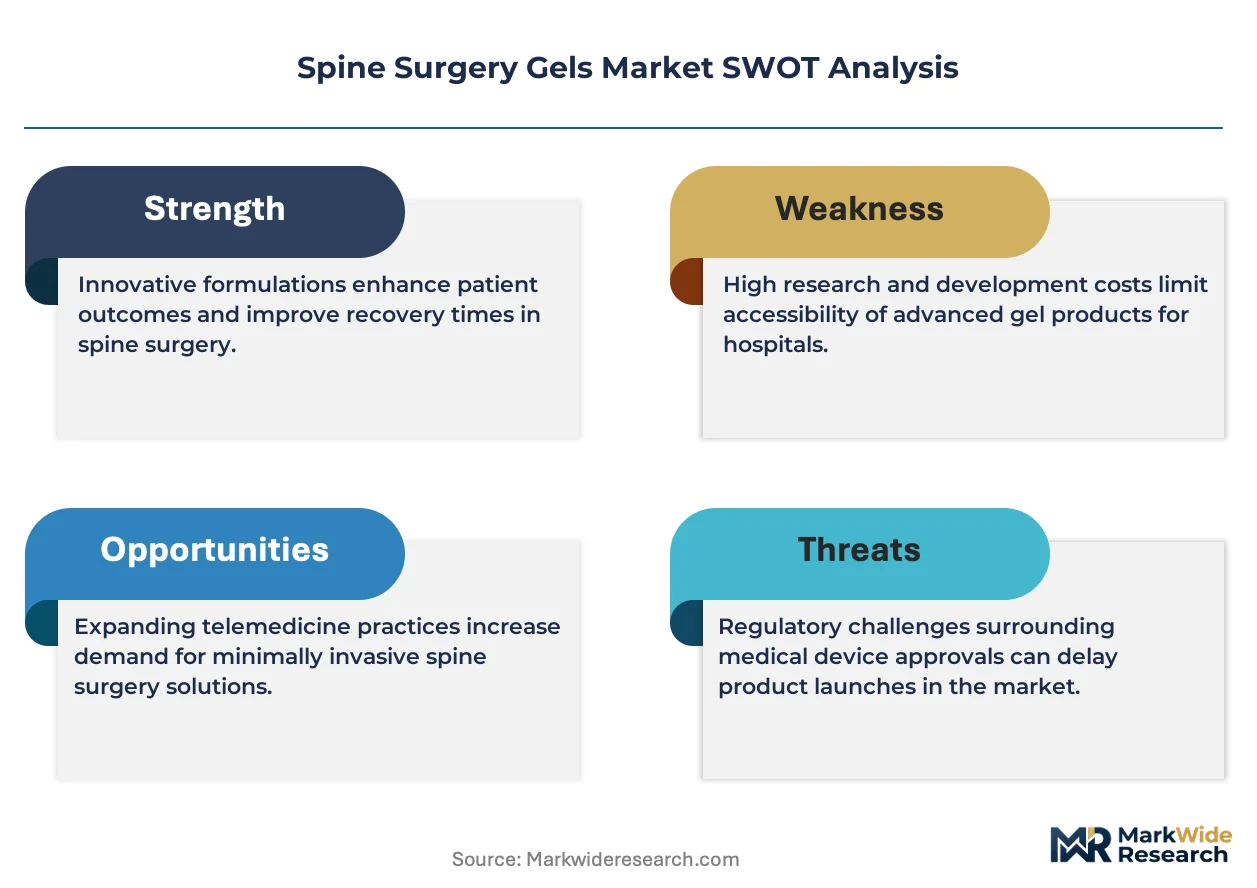
Bioabsorbable polymer crosslinking is reshaping how spine surgery gels achieve controlled degradation profiles and sustained therapeutic release. Integra LifeSciences leverages its regenerative tissue expertise to anchor premium positioning in collagen-based formulations. Medtronic competes through broad surgical portfolio integration, while Stryker differentiates via specialized orthopedic channel control.
Spine surgery gels comprise viscoelastic biomaterials—typically hyaluronic acid derivatives, collagen matrices, or synthetic polyethylene glycol formulations—engineered to provide mechanical support, hemostasis, or cellular scaffolding during spinal procedures. These materials function primarily as adjuncts to bone grafting, dural sealing, or nerve protection in cervical and lumbar interventions. Hydrogel formulations capture dominant volume due to tunable rheological properties and compatibility with minimally invasive delivery systems, while fibrin gel segments retain specialized utility in hemostatic applications despite narrower addressable procedures. Synthetic polymer gels represent the fastest-expanding category as manufacturers engineer tunable resorption kinetics that reduce immunogenic response compared with xenogeneic collagen sources.
FDA 510(k) and PMA pathways govern market access for these combination products, with the agency scrutinizing degradation byproduct biocompatibility and sterility validation. The EU MDR framework imposes additional clinical evidence requirements through notified body conformity assessments, extending certification timelines for collagen and fibrin-based formulations. Stakeholders must monitor evolving reimbursement coding for biologic adjuncts versus mechanical barriers, as payor classification decisions will determine commercial viability across ambulatory and inpatient settings.
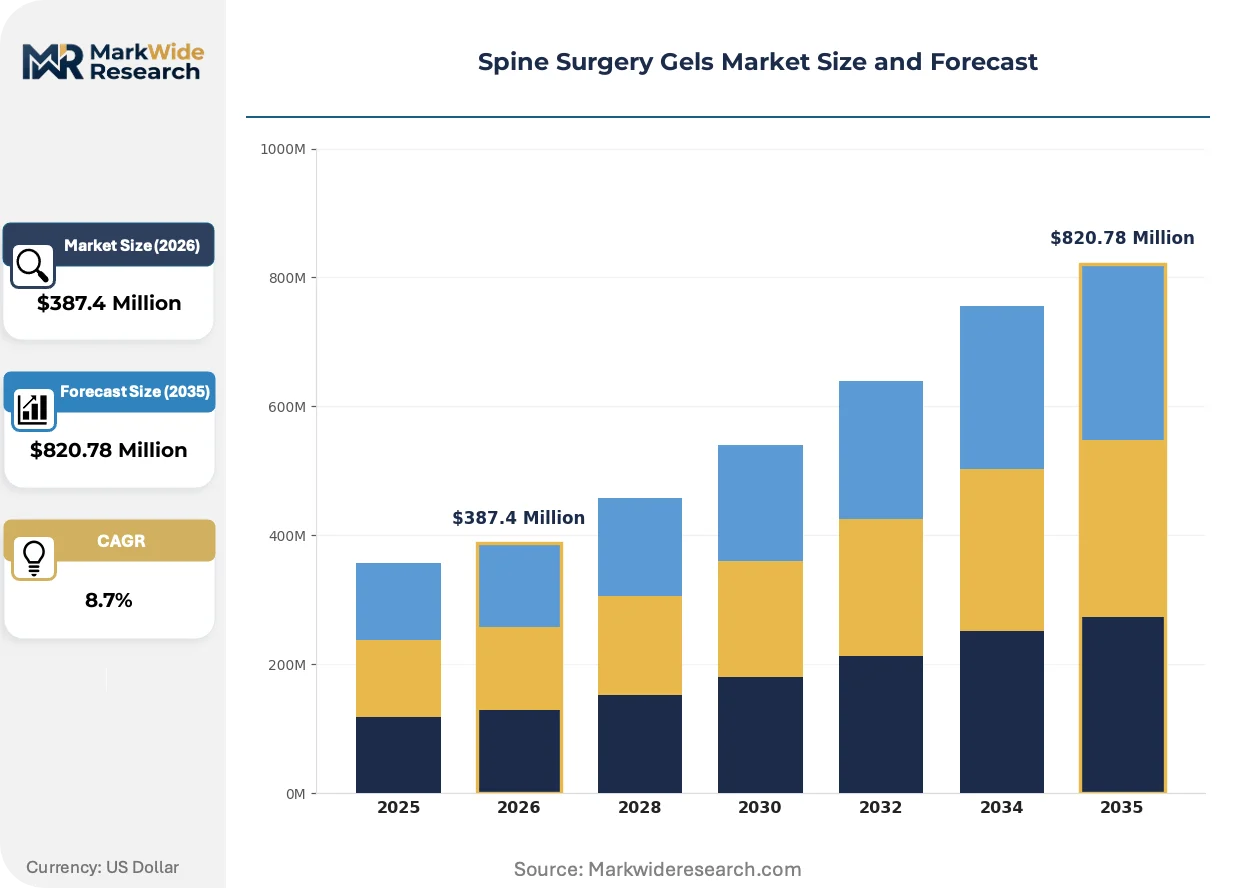
Market Dynamics
Medicare reimbursement coding for biologic adjuncts versus mechanical barriers is concentrating purchasing authority among US hospital systems, compressing vendor margins while elevating clinical evidence requirements for market access.
Growth Catalysts
- Injectable Hydrogel Platforms:Minimally invasive spinal fusion procedures are expanding addressable patient populations beyond traditional open surgery candidates. Ambulatory surgical centers in the United States are scaling same-day discharges using these delivery systems.
- FDA Combination Product Pathway Clarity:Evolving guidance on whether spine gels classify as devices, drugs, or biologics is reducing premarket uncertainty for manufacturers. This regulatory scaffolding accelerates 510(k) clearance timelines for synthetic polymer formulations.
- Aging Demographics in Developed Economies:Degenerative disc disease prevalence is rising among populations over 65 in Japan, Germany, and the United States. Elective lumbar fusion volumes are climbing in tertiary care centers serving these cohorts.
Market Restraints
- Xenogeneic Collagen Supply Concentration:Bovine and porcine tissue sourcing depends on concentrated abattoir networks in Brazil and Argentina. Viral inactivation validation adds 18-24 months to raw material qualification cycles.
- EU MDR Clinical Evidence Burden:Notified body conformity assessments for collagen and fibrin-based formulations now require prospective clinical data. Certification timelines have extended by 12-18 months compared to prior Medical Device Directive pathways.
- Synthetic Polymer Degradation Byproduct Uncertainty:Polyethylene glycol breakdown metabolites face heightened FDA scrutiny for systemic biocompatibility. Premarket submission costs for comprehensive toxicology packages are rising.
Strategic Opportunities
- Outpatient Procedure Migration:Ambulatory surgery centers in the United States are capturing lumbar decompression and fusion cases previously confined to inpatient settings. Hydrogel adjuncts with rapid setting kinetics match these facilities' throughput demands.
- Bioresorbable Synthetic Formulations:Tunable resorption kinetics that eliminate immunogenic response are displacing xenogeneic sources in premium segments. Manufacturers with polymer engineering capabilities command pricing premiums.
- Japan's Reimbursement Expansion:Japan's Ministry of Health, Labour and Welfare is reviewing biologic adjunct coding for cervical interbody fusion. Early entrants to PMDA consultation pathways secure favorable pricing benchmarks.
Industry Challenges
- Sterility Validation Complexity:Terminal sterilization of heat-sensitive hydrogels without compromising rheological properties requires specialized electron beam or gamma irradiation protocols. Validation failures trigger costly batch destruction.
- Reimbursement Coding Fragmentation:CMS, commercial payors, and Medicare Advantage plans apply inconsistent prior authorization criteria for biologic versus synthetic gel adjuncts. Sales teams must maintain parallel documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spine Surgery Gels Market |
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $820.78 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogel, Collagen Gel, Fibrin Gel, Synthetic Polymer Gel Application: Spinal Fusion, Disc Regeneration, Nerve Repair, Hemostasis End User: Neurosurgery Departments, Orthopedic Centers, Rehabilitation Clinics, Ambulatory Surgery Delivery Method: Injectable, Topical Application, Implantable, Spray |
| Companies Covered | Integra LifeSciences, Medtronic, Stryker, Johnson & Johnson, Baxter International, Anika Therapeutics, Globus Medical, Seikagaku Corporation, Medcura, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spine Surgery Gels Market Trends and Innovations
Formulation science is converging with minimally invasive delivery engineering to compress procedure times and expand treatable patient anatomies beyond traditional fusion boundaries.
Dual-network hydrogel chemistry is hybridizing covalent and physical crosslinking mechanisms to achieve simultaneous injectability and mechanical strength. Spine surgeons in high-volume US academic centers are adopting these platforms for anterior cervical discectomy and fusion. The technology is compressing operative time while reducing graft subsidence rates compared to standalone mechanical cages.
The EU Medical Device Regulation's enhanced clinical evidence requirements are forcing manufacturers to sponsor prospective post-market surveillance studies. Notified bodies in Germany and the Netherlands are rejecting equivalence arguments for collagen-based sealants without longitudinal safety data. Synthetic polymer segments are responding by accelerating biodegradation kinetics studies to preempt regulatory objections.
Hospital value analysis committees are consolidating purchasing authority for biologic adjuncts under centralized pharmacy and materials management functions. Individual surgeon preference cards are being overridden by system-level contracts in integrated delivery networks across Texas, Florida, and California. This concentration is visible most acutely in nonprofit health systems with employed physician models seeking standardized cost-per-case metrics.
Spine Surgery Gels Market Segmentation
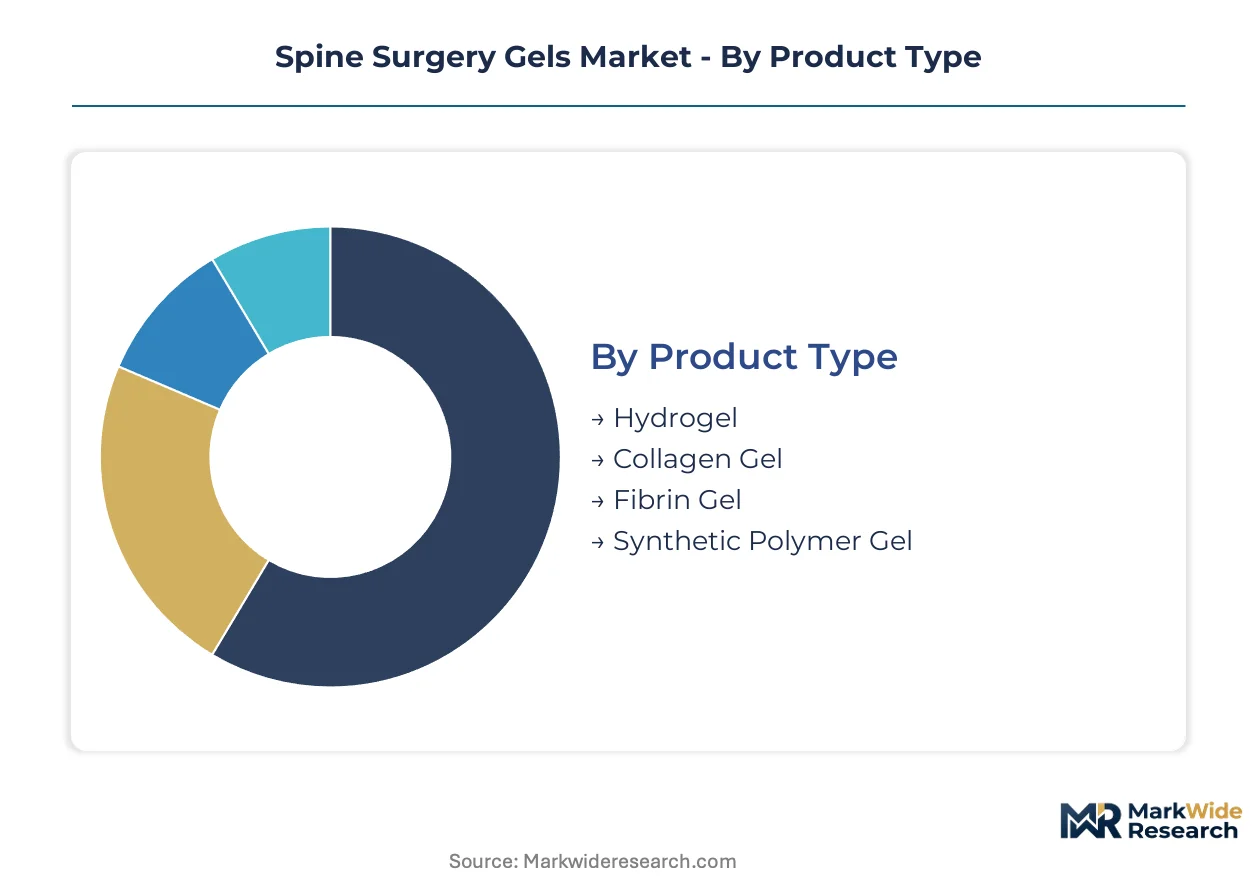
Segmentation in spine surgery gels reveals how formulation chemistry, procedural application, and delivery mechanics intersect to determine commercial viability. Manufacturers must align R&D investments with specific reimbursement pathways and sterilization requirements that vary dramatically across these dimensions.
Product Type:
Use-case spectrum spans mechanical scaffolding to active hemostasis, with degradation kinetics and immunogenic profiles determining clinical positioning.
- Hydrogel:Viscoelastic formulations—typically hyaluronic acid or polyethylene glycol derivatives—provide tunable rheology for minimally invasive delivery. Demand concentrates in United States ambulatory surgery centers where rapid-setting kinetics enable same-day discharge protocols.
- Synthetic Polymer Gel:Engineered resorption profiles eliminate xenogeneic sourcing risks while offering batch-to-batch consistency. German and Japanese tertiary centers are adopting these platforms for complex revision fusions where immunogenic response minimization is paramount.
- Collagen Gel:Xenogeneic matrices derived from bovine or porcine tissue retain specialized utility in dural sealing applications.
- Fibrin Gel:Plasma-derived formulations serve narrow hemostatic indications in open posterior approaches.
The dominant share belongs to Hydrogel, while Synthetic Polymer Gel is closing the gap fastest.
Application:
Procedure volume and reimbursement intensity create divergent margin profiles across surgical indications.
- Spinal Fusion:Anterior cervical and lumbar interbody procedures consume the highest gel volumes per case. United States hospital systems with employed surgeon models are standardizing biologic adjunct protocols to reduce graft subsidence complications.
- Hemostasis:Intraoperative bleeding control in epidural and paravertebral spaces demands rapid gelation kinetics. High-volume academic medical centers in California and Texas specify fibrin and synthetic sealants in bundled payment contracts.
- Disc Regeneration:Nucleus pulposus augmentation remains investigational in most jurisdictions.
- Nerve Repair:Dural defect sealing and neural protection applications require specialized barrier properties.
Spinal Fusion commands the largest revenue pool, though Hemostasis applications are expanding most quickly into outpatient settings.
End User:
Purchasing authority concentration varies by facility scale and physician employment structure.
- Ambulatory Surgery:Freestanding centers in Florida and Arizona are capturing lumbar decompression cases previously confined to inpatient settings. These facilities prioritize single-use gel formats with minimal preparation time to maintain throughput.
- Neurosurgery Departments:Academic institutions with residency programs drive adoption of novel dual-network hydrogels for complex cervical reconstructions. Procurement committees in these settings demand comprehensive toxicology packages for synthetic formulations.
- Orthopedic Centers:Dedicated spine hospitals concentrate volume for degenerative disc disease interventions.
- Rehabilitation Clinics:Post-surgical monitoring sites influence gel selection through readmission rate feedback.
Ambulatory Surgery is gaining share fastest as site-of-service migration accelerates, while Neurosurgery Departments retain premium pricing leverage.
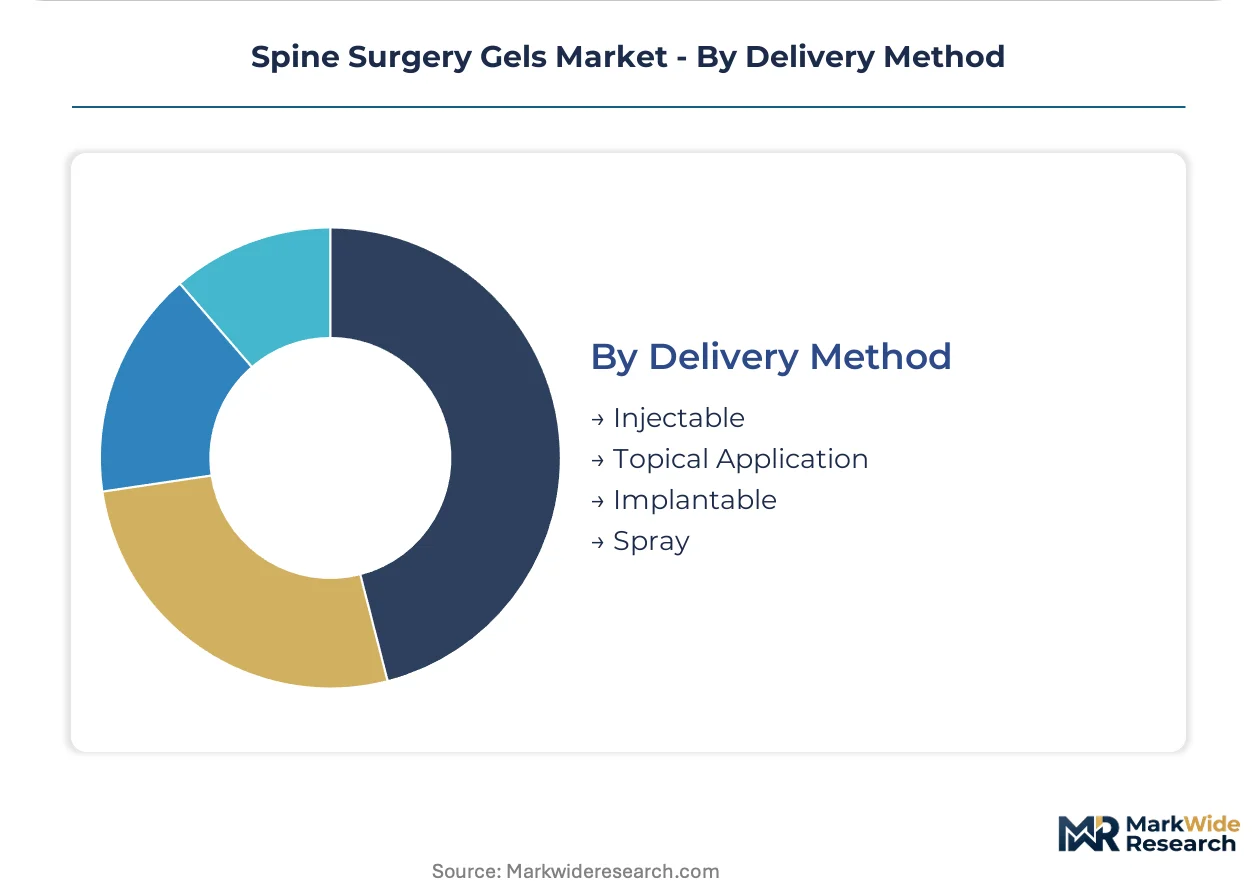
Delivery Method:
Instrumentation compatibility and sterility maintenance requirements shape formulation development priorities.
- Injectable:Syringe-based delivery through minimally invasive retractor systems dominates lumbar fusion volume. Japanese manufacturers are engineering low-viscosity variants for percutaneous endoscopic approaches.
- Implantable:Pre-formed scaffolds for interbody cages command pricing premiums in complex multi-level procedures. German notified bodies under EU MDR are scrutinizing sterility validation for these heat-sensitive formats.
- Topical Application:Direct placement during open posterior approaches serves hemostatic indications.
- Spray:Aerosolized delivery systems address irregular wound geometries in trauma settings.
Injectable methods hold the dominant position, with Implantable formats showing the steepest expansion trajectory in revision surgery segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems with employed physician models concentrate purchasing authority for spine surgery gels in the United States, while Japanese and German tertiary centers drive adoption of synthetic polymer formulations. Ambulatory surgery migration patterns differ sharply across these markets, shaping formulation preferences and reimbursement negotiations.
United States
Medicare Advantage plans and commercial payors apply inconsistent prior authorization criteria for biologic adjuncts versus synthetic gels. FDA 510(k) clearance timelines for synthetic polymer formulations are accelerating under evolving combination product guidance. Texas, Florida, and California integrated delivery networks are overriding individual surgeon preference cards with system-level contracts.
Germany
Notified bodies under EU MDR are rejecting equivalence arguments for collagen-based sealants without longitudinal safety data. Complex revision fusion volumes in Baden-Württemberg and Bavaria are elevating demand for immunogenic-minimizing synthetic platforms. Hospital value analysis committees in Berlin-Brandenburg are consolidating biologic adjunct procurement under centralized pharmacy functions.
Japan
Japan's Ministry of Health, Labour and Welfare is reviewing biologic adjunct coding for cervical interbody fusion. PMDA consultation pathways are attracting early entrants seeking favorable pricing benchmarks. Kanto region academic medical centers with residency programs are piloting dual-network hydrogels for complex cervical reconstructions.
Brazil
Bovine tissue sourcing from concentrated abattoir networks in São Paulo and Minas Gerais feeds xenogeneic collagen supply chains. ANVISA scrutiny of viral inactivation validation extends raw material qualification cycles. Private hospital chains in Rio de Janeiro are standardizing synthetic polymer protocols to reduce supply concentration risk.
United Kingdom
NHS England bundled payment contracts for spinal procedures are compressing gel adjunct margins in London and Southeast hospital trusts. MHRA post-Brexit regulatory alignment with EU MDR clinical evidence requirements is extending certification timelines. Midlands orthopedic centers are capturing lumbar decompression cases previously referred to tertiary institutions.
Spine Surgery Gels Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent distribution architectures. The vendor base organizes around three strategic archetypes: diversified surgical portfolio conglomerates, regenerative tissue specialists, and orthopedic channel-dominant manufacturers. Competitive moves concentrate on M&A for biomaterial capabilities and strategic partnerships for sterilization validation. Capacity expansion in synthetic polymer engineering is displacing legacy collagen sourcing arrangements.
Within the diversified surgical portfolio tier, Medtronic and Johnson & Johnson exemplify scale-driven positioning through broad operating room integration. Stryker occupies a channel-control position in orthopedic-specific distribution. Integra LifeSciences represents the regenerative tissue specialist archetype, anchoring premium positioning in collagen-based formulations. These three companies illustrate how competitive advantage flows from either portfolio breadth, channel dominance, or biomaterial specialization rather than overlapping capability claims.
| Leading Market Players |
|---|
| Integra LifeSciences |
| Medtronic |
| Stryker |
| Johnson & Johnson |
| Baxter International |
| Anika Therapeutics |
| Globus Medical |
| Seikagaku Corporation |
| Medcura |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Brazilian abattoir networks drives raw material scarcity for xenogeneic collagen suppliers, compressing margins for manufacturers dependent on bovine tissue sourcing while elevating pricing power for synthetic polymer producers with captive polymer engineering capabilities.
Pricing Analysis
Cost-plus contracts with polyethylene glycol feedstock indexation dominate synthetic polymer gel procurement. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared dual-network hydrogels from basic hyaluronic acid formulations and commodity hemostatic sealants. Price differentiation hinges on sterilization validation tier and ambulatory surgery center volume commitments. Cost compression in economy-tier collagen gels is intensifying because Brazilian supply concentration elevates raw material qualification costs. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with bundled payment contracts show lowest.
Supply Chain Analysis
Tariff exposure between Brazil and Argentina disrupts xenogeneic collagen supply chains serving North American and European manufacturers. Raw material sourcing draws from São Paulo and Minas Gerais abattoir networks, German polymer engineering facilities, and Japanese hyaluronic acid fermentation operations. Polyethylene glycol, bovine-derived collagen peptides, and gamma-irradiation sterilization services constitute critical input dependencies. Single-source vulnerability in South American tissue sourcing elevates supply risk. Distribution runs through orthopedic-focused GPOs and hospital system centralized pharmacy functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spine surgery gel incumbents face substitution pressure from synthetic polymer platforms displacing xenogeneic collagen in premium reimbursement tiers, requiring defensive repositioning around immunogenic response minimization and rapid-setting kinetics.
For Market Incumbents: Pre-empt synthetic polymer displacement by accelerating biodegradation kinetics studies to satisfy EU MDR longitudinal safety demands. Secure backward integration into polyethylene glycol polymer engineering to reduce feedstock cost volatility. Channel control through GPO contract consolidation defends position against emerging entrants targeting ambulatory surgery center white space. For New Entrants and Emerging Players: Establish a beachhead in Japanese cervical interbody fusion segments where PMDA consultation pathways offer favorable pricing benchmarks for early entrants. Target ambulatory surgery centers in Arizona and Florida with single-use gel formats requiring minimal preparation time. Go-to-market leverage rests on rapid-setting kinetics matching same-day discharge throughput demands. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among synthetic polymer specialists with sterilization validation capabilities and hospital system GPO contracts. Long-term viability favors manufacturers with tunable resorption kinetics IP and EU MDR certification momentum. Acquisition target archetype: mid-cap polymer engineering firms with notified body relationships. Signal to watch: Japan Ministry of Health, Labour and Welfare biologic adjunct coding decisions for cervical fusion reimbursement.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Notified body relationships in Germany and the Netherlands compress approval timelines for dual-network hydrogels. |
| Synthetic Polymer Backward Integration | Captive polyethylene glycol production insulates margins from Brazilian feedstock volatility. |
| Ambulatory Surgery Center Partnership | Florida and Arizona facility contracts capture lumbar decompression volume migrating from inpatient settings. |
| Japan PMDA Early Consultation | Ministry of Health, Labour and Welfare coding reviews secure premium reimbursement benchmarks. |
| Sterilization Validation Scale-Up | Electron beam protocol investments reduce batch destruction risk for heat-sensitive hydrogel formulations. |
Research Methodology
Operator-level perspectives from spine surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, EU MDR notified body assessment reports, CMS Medicare reimbursement databases, and hospital procurement contract repositories. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue analysis.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling across product chemistry, procedural application, delivery mechanics, and end-user facility type. CAGRs derived from procedure volume elasticity to aging demographics and reimbursement coding evolution. Forecast inputs incorporated ambulatory surgery center site-of-service migration rates and synthetic polymer degradation kinetics advancement timelines.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement policy, EU MDR enforcement intensity, or Brazilian abattoir capacity would shift the trajectory. Forecasts reflect documented assumptions subject to revision from regulatory pathway changes or sterilization validation breakthroughs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Chitosan Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
North America Chitosan Market
Biomaterials
Heparin Market
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
US Heparin Market
Biomaterials
Scaffold Materials Market
Biomaterials
Self-Healing Hydrogels Market
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
Global Medical Engineered Materials Market
Biomaterials
Europe Collagen Market
Biomaterials
Global Extracellular Matrix Patches Market
Biomaterials
Global Medical Grade Collagen Market