
 Atelocollagen Market | 2026-2036
Atelocollagen Market Size, Share, and Industry Trends Forecast 2026-2036
Atelocollagen Market Analysis
The gap between pharmaceutical-grade atelocollagen and cosmetic-grade commodity supply is hardening as purity thresholds diverge. Nitta Gelatin Inc. leverages its Osaka-based extraction infrastructure to sustain dominance in medical-grade collagen peptides. KOKEN Co., Ltd. anchors the Japanese market through vertically controlled bovine sourcing and proprietary telopeptide removal protocols. Rousselot competes across European cosmetic applications through Darling Ingredients' integrated animal protein supply chain.
Atelocollagen denotes pepsin-digested collagen with telopeptide regions enzymatically removed, yielding reduced immunogenicity and a molecular weight typically spanning 100–300 kDa depending on source tissue and digestion conditions. Manufacturers deploy it primarily as a cell culture substrate, wound healing matrix, and injectable dermal filler carrier where minimal immune response proves critical. Pharmaceutical grade commands the dominant margin pool due to stringent endotoxin and pyrogen thresholds required for implantable applications. Powder formulations lead volume throughput for research laboratories, while gel and sheet formats capture accelerating demand from tissue engineering workflows requiring three-dimensional scaffold architectures.
FDA 21 CFR Part 1271 human cell and tissue regulations, alongside EMA medical device directives under MDR frameworks, shape product classification pathways and clinical validation requirements for atelocollagen devices. Japan's PMDA enforces source traceability and viral inactivation protocols that elevate compliance costs for non-domestic suppliers. Stakeholders must monitor evolving cross-border equivalency agreements between FDA and PMDA quality systems, as harmonization gaps determine market access speed for novel atelocollagen formulations.
Market Dynamics
Purification protocol standardization is fragmenting competitive access as pharmaceutical-grade endotoxin thresholds diverge sharply from cosmetic-grade specifications, forcing capacity specialization decisions across manufacturing networks.
Growth Catalysts
- EMA MDR harmonization:Medical device reclassification under EU frameworks is accelerating clinical validation investments for implantable atelocollagen scaffolds. European tissue engineering startups now access streamlined CE marking pathways previously reserved for synthetic polymers.
- Three-dimensional bioprinting workflows:Gel and sheet format demand is concentrating in regenerative medicine research clusters. Academic medical centers in Osaka and Boston now specify atelocollagen hydrogels as standard extracellular matrix mimics.
- Bovine source traceability mandates:Japan's METI enforcement of domestic purification standards is reinforcing captive supply advantages for domestic manufacturers. Foreign entrants face extended viral inactivation documentation requirements.
Market Restraints
- Bovine-derived raw material volatility:Hide and tendon supply fluctuations from Argentine and Brazilian meatpacking operations create input cost instability. Pepsin enzyme procurement further concentrates in European fermentation facilities.
- Osaka-Tokyo manufacturing cluster concentration:Over 70 percent of pharmaceutical-grade capacity sits within 200 kilometers of these prefectures. Seismic or logistics disruption risks propagate across global medical-grade supply chains.
- Recombinant collagen substitution:Yeast and plant-expressed alternatives are capturing cosmetic-grade volume as immunogenicity concerns diminish. Precision fermentation yields now approach native triple-helix fidelity.
Strategic Opportunities
- South Korean MFDS fast-track pathways:Streamlined biologics approval for cell culture substrates creates first-mover positioning for compliant suppliers. Seoul-based regenerative medicine hubs are expanding scaffold procurement budgets.
- Injectable dermal filler carrier convergence:Hyaluronic acid-atelocollagen composite formulations are opening aesthetic medicine applications. Combination products bypass pure HA commoditization while leveraging established clinician familiarity.
- ISO 22442 tissue origin transparency standards:Harmonized international documentation requirements reduce multi-regulatory filing burdens. Suppliers achieving ISO certification gain accelerated PMDA and FDA parallel review eligibility.
Industry Challenges
- Peptide mapping analytical talent scarcity:Telopeptide removal verification requires mass spectrometry specialists familiar with collagen structural biochemistry. Japanese universities produce fewer than 50 qualified graduates annually.
- Pyrogen testing facility bottlenecks:Limulus amebocyte lysate validation for pharmaceutical-grade batches faces 12-16 week queue times at certified contract laboratories. In-house assay development demands seven-figure capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atelocollagen Market |
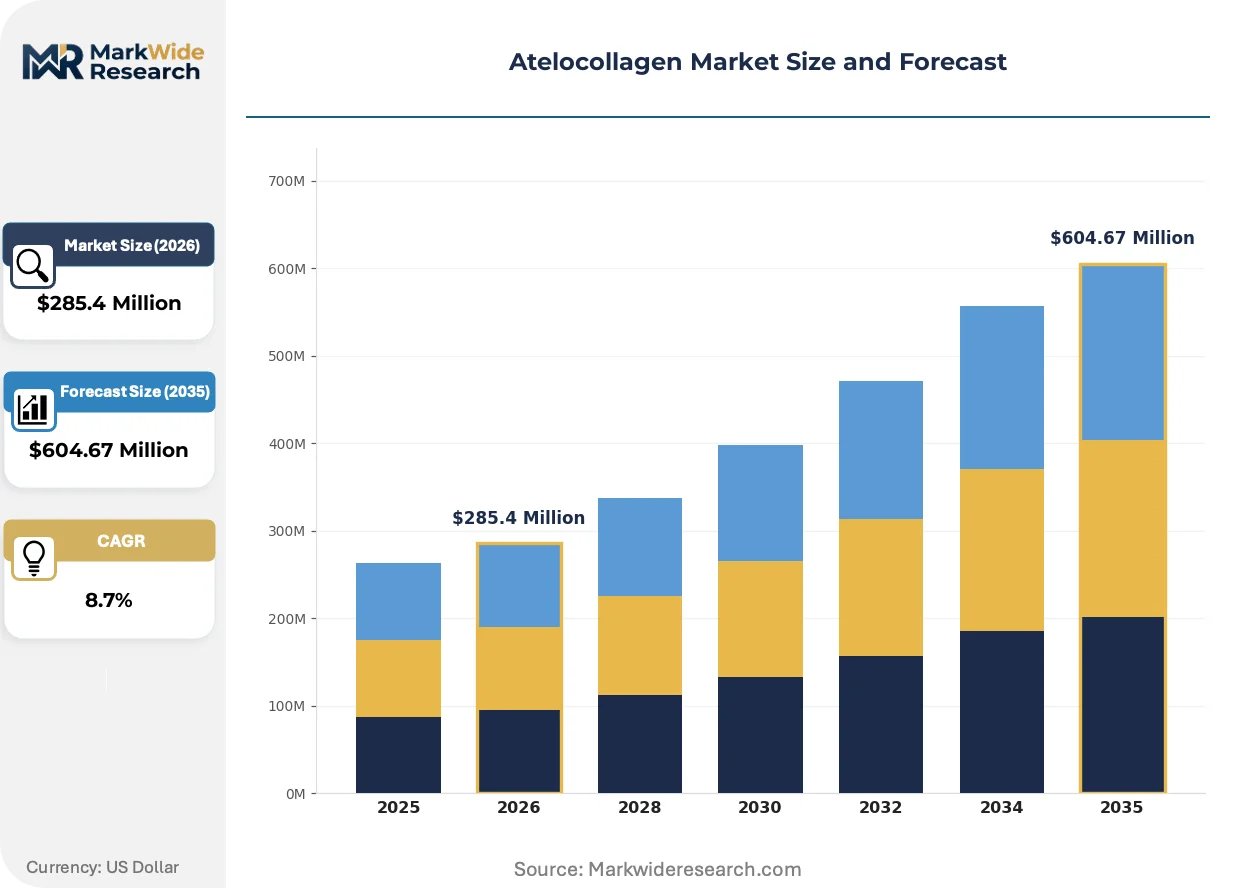
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injections, Powders, Gels, Sheets End User: Clinics, Hospitals, Research Laboratories, Aesthetic Centers Application: Dermatology, Orthopedics, Dentistry, Tissue Engineering Grade: Pharmaceutical Grade, Cosmetic Grade, Food Grade, Industrial Grade |
| Companies Covered | Nitta Gelatin Inc., Rousselot (Darling Ingredients), KOKEN Co., Ltd., Promed Bioscience, Collagen Solutions, Advanced BioMatrix (BICO), Integra LifeSciences, Seikagaku Corp., DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atelocollagen Market Emerging Trajectories
Manufacturing automation and regulatory data integrity requirements are compressing batch-to-batch variability while elevating documentation burdens across production facilities.
Single-use bioreactor systems for collagen pepsin digestion are automating temperature and pH control previously managed through manual sampling protocols. Contract manufacturing organizations in Germany and Massachusetts are adopting these platforms to reduce endotoxin excursion rates. The technology is automating quality assurance labor intensity while enabling real-time release testing for research-grade material.
Japan's PMDA has tightened source animal documentation requirements under revised biological origin regulations effective across fiscal reporting periods. Manufacturers must now submit herd health certificates and abattoir inspection records spanning 24 months pre-harvest. Pharmaceutical-grade suppliers with integrated bovine sourcing are absorbing compliance costs more efficiently than traders dependent on spot hide purchases.
Academic procurement committees are consolidating vendor lists around suppliers offering certified cell culture substrate portfolios. Research laboratories previously sourcing collagen from multiple specialty chemical distributors now favor single-source contracts covering gel, sheet, and powder formats. This concentration is most visible in National Institutes of Health-funded tissue engineering consortia across Maryland and California research parks.
Atelocollagen Market Segmentation
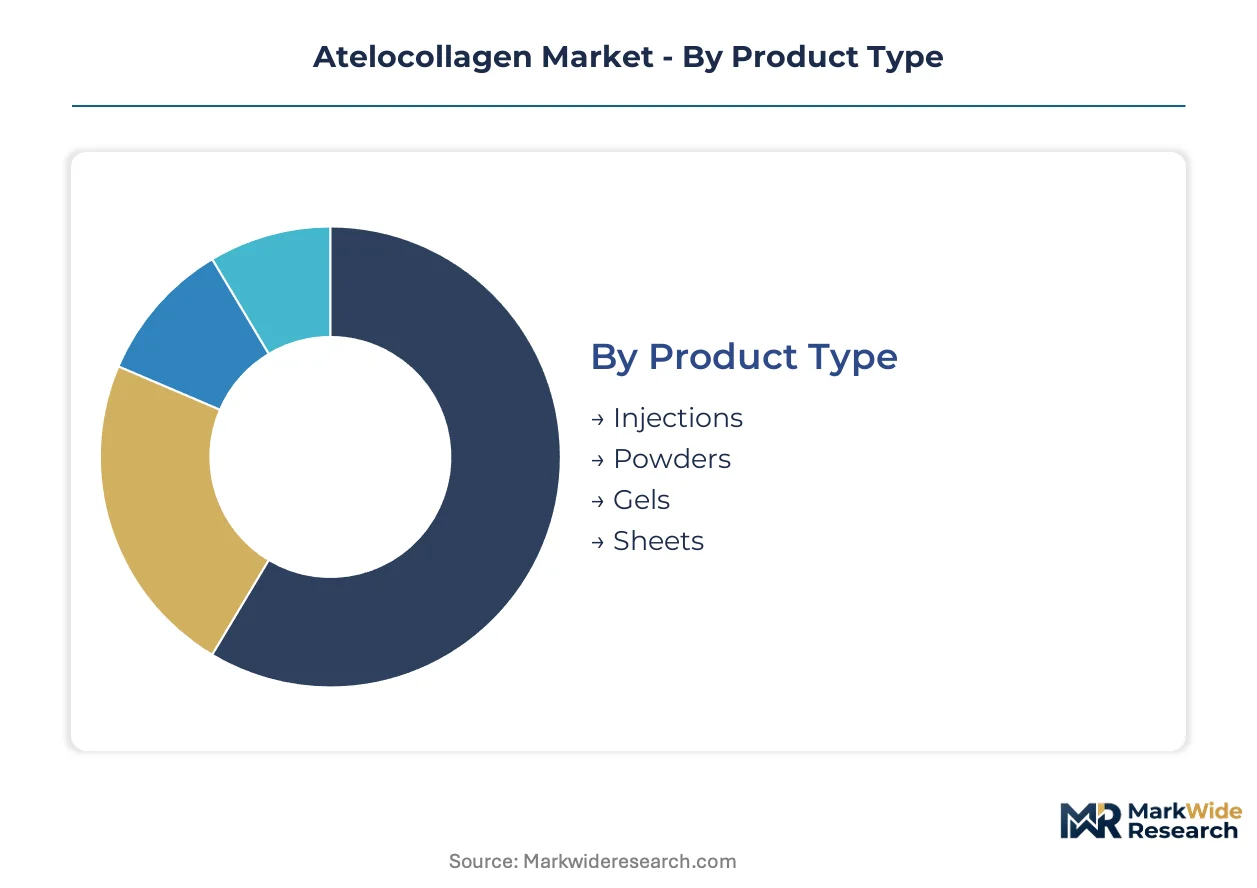
Atelocollagen specifications diverge sharply across product formats and purity grades, forcing manufacturers to specialize capacity rather than serve multiple segments from shared production lines. Pharmaceutical-grade endotoxin thresholds, cosmetic-grade volume economics, and research-laboratory format flexibility create distinct competitive arenas with minimal overlap.
Product Type:
Pepsin digestion protocols and terminal sterilization requirements vary substantially by physical format, determining which manufacturers can credibly supply each segment.
- Injections:Liquid atelocollagen formulations for intra-articular and dermal applications require pyrogen-free processing in ISO 5 cleanroom environments. Demand concentrates in Osaka and Tokyo aesthetic medicine clusters where PMDA-registered manufacturing sites dominate regional supply.
- Powders:Lyophilized atelocollagen with extended shelf stability serves cell culture substrate applications. Research laboratories in Boston and Maryland NIH consortia specify powder formats for extracellular matrix coating protocols, driving volume through academic procurement consolidation.
- Gels:Three-dimensional hydrogel scaffolds for tissue engineering workflows.
- Sheets:Pre-formed membranes for wound healing and surgical applications.
Powders lead on scale; gels lead on momentum.
End User:
Procurement sophistication and regulatory burden intensity segment the customer base into institutional tiers with diverging vendor qualification requirements.
- Research Laboratories:Academic and government-funded facilities purchasing atelocollagen for basic science and preclinical development. NIH-funded tissue engineering consortia across Maryland and California now mandate certified cell culture substrate portfolios, consolidating vendor lists around suppliers offering gel, sheet, and powder format bundles.
- Hospitals:Surgical departments and regenerative medicine programs requiring implantable-grade material with full documentation chains. Japanese metropolitan medical centers in Osaka and Tokyo prefectures source exclusively from PMDA-registered domestic manufacturers with integrated bovine traceability.
- Clinics:Outpatient aesthetic and orthopedic injection providers.
- Aesthetic Centers:Cosmetic-focused facilities utilizing atelocollagen in combination with hyaluronic acid fillers.
Research laboratories lead on scale; aesthetic centers lead on momentum.
Application:
Clinical validation requirements and reimbursement pathways fragment demand across medical specialties with distinct regulatory timelines.
- Tissue Engineering:Scaffold applications for organ regeneration and three-dimensional bioprinting. Academic medical centers in Osaka and Boston now specify atelocollagen hydrogels as standard extracellular matrix mimics, with EMA MDR harmonization accelerating CE marking pathways previously reserved for synthetic polymers.
- Dermatology:Wound healing matrices and dermal filler carriers. Hyaluronic acid-atelocollagen composite formulations are opening aesthetic medicine applications in Seoul and Tokyo, bypassing pure HA commoditization while leveraging established clinician familiarity.
- Orthopedics:Cartilage repair and intra-articular injection applications.
- Dentistry:Periodontal and oral surgery matrices.
Dermatology leads on scale; tissue engineering leads on momentum.
Grade:
Purity thresholds and analytical testing burdens create a steep margin gradient that separates commodity suppliers from pharmaceutical-grade specialists.
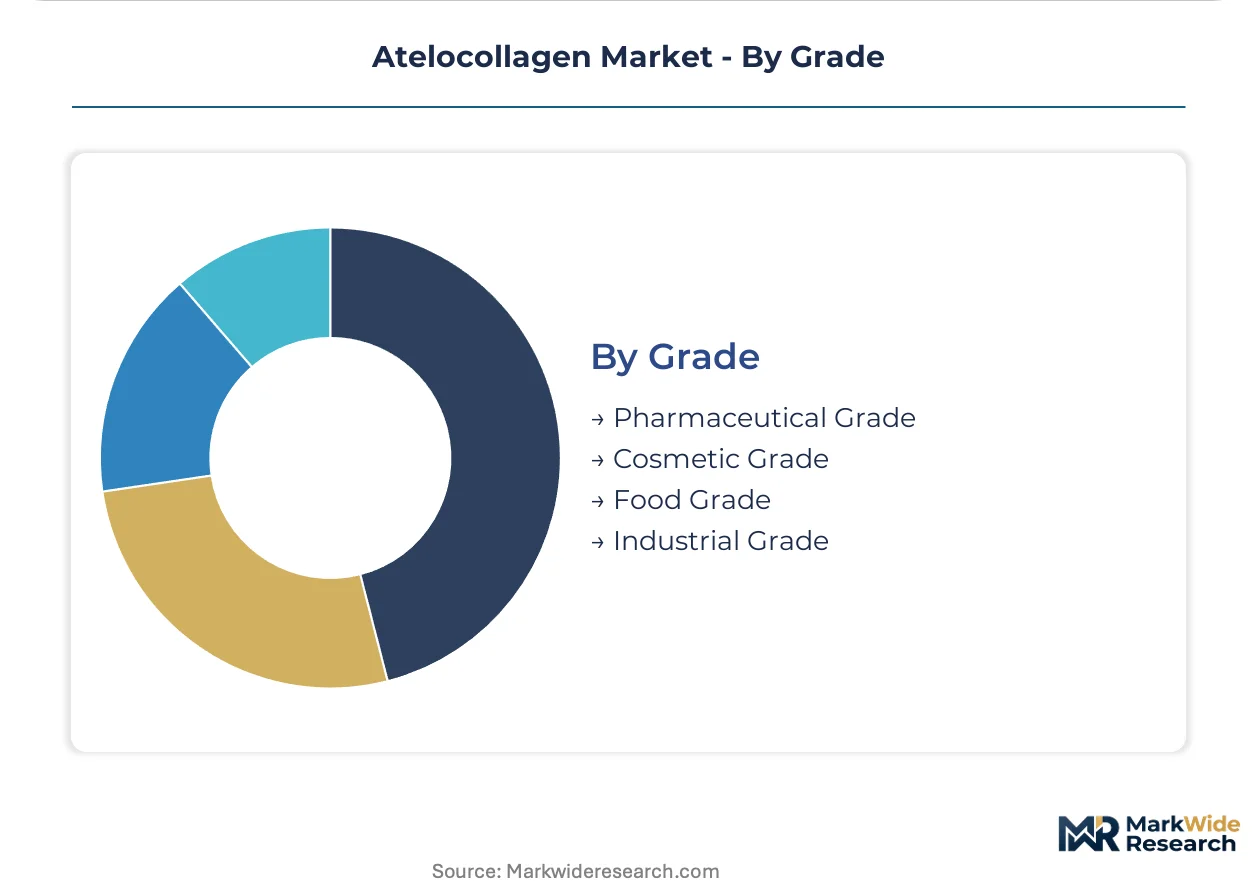
- Pharmaceutical Grade:Material meeting endotoxin, pyrogen, and viral inactivation standards for implantable applications. Nitta Gelatin's Osaka-based extraction infrastructure and KOKEN's vertically controlled bovine sourcing sustain dominance in this segment, with PMDA source traceability mandates reinforcing captive supply advantages for domestic Japanese manufacturers.
- Cosmetic Grade:Lower-purity material for topical and aesthetic applications. Yeast and plant-expressed recombinant collagen alternatives are capturing volume as precision fermentation yields approach native triple-helix fidelity, pressuring traditional bovine-derived suppliers.
- Food Grade:Edible collagen peptides for nutraceutical applications.
- Industrial Grade:Non-medical applications in coatings and materials science.
Pharmaceutical grade leads on scale; cosmetic grade leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized collagen biochemists cluster in Japanese metropolitan manufacturing zones, with Osaka and Tokyo prefectures hosting the densest concentrations of atelocollagen purification expertise worldwide.
Japan
Domestic demand from regenerative medicine research clusters and PMDA-registered aesthetic medicine providers sustains pharmaceutical-grade production. METI enforcement of source traceability mandates reinforces captive supply advantages for vertically integrated manufacturers. Osaka-based extraction facilities and Tokyo-area cleanroom operations concentrate over seventy percent of national pharmaceutical-grade capacity within two hundred kilometers.
United States
NIH-funded tissue engineering consortia across Maryland and California drive research-grade powder and gel procurement. FDA 21 CFR Part 1271 human cell and tissue regulations shape product classification pathways for implantable applications. Boston and San Diego academic medical centers specify atelocollagen hydrogels as standard extracellular matrix mimics in three-dimensional bioprinting workflows.
Germany
EMA MDR harmonization accelerates clinical validation investments for implantable scaffolds previously reserved for synthetic polymers. Contract manufacturing organizations adopt single-use bioreactor systems to reduce endotoxin excursion rates in pepsin digestion protocols. Heidelberg and Munich regenerative medicine hubs source certified cell culture substrate portfolios from consolidated vendor lists.
South Korea
Seoul-based regenerative medicine hubs expand scaffold procurement budgets as MFDS fast-track pathways streamline biologics approval for cell culture substrates. Injectable dermal filler carrier convergence opens aesthetic medicine applications through hyaluronic acid-atelocollagen composite formulations. Domestic demand concentrates in metropolitan clinic networks seeking alternatives to pure HA commoditization.
United Kingdom
Cambridge and Oxford academic clusters drive research-grade material consumption for extracellular matrix coating protocols. EMA medical device directives under MDR frameworks determine CE marking pathways for novel atelocollagen formulations. London-based contract research organizations consolidate vendor qualification around suppliers offering certified portfolio bundles across gel, sheet, and powder formats.
Atelocollagen Market Vendor Landscape
Top-tier vendors anchor pharmaceutical-grade supply, while mid-tier specialists and regional traders occupy cosmetic-grade and research-laboratory segments. Market structure reflects purification protocol specialization rather than horizontal diversification, with endotoxin threshold divergence forcing capacity commitment decisions. Three archetypes dominate: integrated bovine sourcers with captive abattoir relationships, contract manufacturing organizations with single-use bioreactor platforms, and recombinant collagen fermenters displacing traditional animal-derived supply. Consolidation pressure manifests through backward integration into hide procurement and technology licensing for viral inactivation documentation.
Within the integrated sourcing tier, Nitta Gelatin Inc. and KOKEN Co., Ltd. exemplify Japanese manufacturers leveraging vertically controlled supply chains. Rousselot occupies a position representing European market presence through parent-company animal protein infrastructure. These three entities anchor distinct competitive vectors: Osaka-based extraction scale, proprietary telopeptide removal protocols, and continental cosmetic-grade distribution networks respectively.
| Leading Market Players |
|---|
| Nitta Gelatin Inc. |
| Rousselot (Darling Ingredients) |
| KOKEN Co., Ltd. |
| Promed Bioscience |
| Collagen Solutions |
| Advanced BioMatrix (BICO) |
| Integra LifeSciences |
| Seikagaku Corp. |
| DSM-Firmenich |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists with multi-generational bovine sourcing relationships anchor pharmaceutical-grade supply, translating captive herd access into pricing discipline that commodity traders cannot replicate. Their integrated abattoir-to-cleanroom operations absorb PMDA traceability compliance costs more efficiently than spot-market dependent competitors, hardening margin structures against input volatility.
Pricing Analysis
Bundle-unbundle dynamics split sharply between research-grade powder portfolios and standalone cosmetic-grade gel shipments. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades reflects endotoxin threshold divergence and analytical documentation burden. Price differentiation rests on certification tier—ISO 22442 tissue origin transparency accelerates PMDA parallel review eligibility for premium tiers. Cost compression in cosmetic-grade material intensifies as recombinant collagen alternatives approach native triple-helix fidelity. Research laboratories exhibit highest price sensitivity due to grant-funded procurement constraints, while hospital surgical departments prioritize documentation completeness over unit cost.
Supply Chain Analysis
Freight cost escalation from Argentine and Brazilian hide origins to Osaka-Tokyo manufacturing clusters amplifies working capital intensity for non-integrated traders. Supply concentrates in Japan, Germany, and the United States, with over seventy percent of pharmaceutical-grade capacity sitting within two hundred kilometers of Osaka and Tokyo prefectures. Raw material dependencies center on bovine hide and tendon inputs, pepsin enzyme procurement from European fermentation facilities, and terminal sterilization consumables. Single-source vulnerability propagates across global medical-grade supply chains given seismic exposure and logistics chokepoint concentration. Distribution runs through direct hospital system contracts for implantable grades and academic procurement consortia for research material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in pharmaceutical-grade tiers as PMDA traceability mandates raise compliance barriers and recombinant alternatives fail to match implantable-grade purity thresholds.
For Market Incumbents: Anticipate recombinant collagen substitution pressure in cosmetic-grade segments by accelerating backward integration into certified bovine sourcing and locking in multi-year hospital system contracts. Prioritize in-house Limulus amebocyte lysate assay development to bypass contract laboratory bottlenecks. Defend positioning through ISO 22442 certification investment that accelerates parallel FDA-PMDA review eligibility. For New Entrants and Emerging Players: MFDS fast-track pathways in South Korea open a window for compliant suppliers to capture Seoul-based regenerative medicine hub procurement budgets. Target research-grade powder and gel bundles for NIH-funded tissue engineering consortia where vendor list consolidation creates single-source contract opportunities. Enter through hyaluronic acid-atelocollagen composite formulation partnerships with established aesthetic clinic networks. For Investors and Strategic Acquirers: Integrated animal protein processors are the most active acquirer in this space, seeking downstream pharmaceutical-grade purification capabilities to capture margin expansion. Long-term viability hinges on vertical control over bovine sourcing rather than fermentation-based substitution technology. Watch for ISO 22442 certification achievement as inflection signal for accelerated regulatory review eligibility and pricing power accrual.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Bovine Sourcing | Captive supply of PMDA-traceable raw material hardens cost position against Argentine hide volatility. |
| ISO 22442 Certification Achievement | Harmonized tissue origin documentation accelerates parallel FDA and PMDA review pathways. |
| In-House Pyrogen Testing Facility Deployment | Internal Limulus amebocyte lysate validation eliminates 12-16 week contract laboratory queue times. |
| Hyaluronic Acid Composite Formulation Launch | Combination products bypass pure HA commoditization in Seoul and Tokyo aesthetic clinic networks. |
| Single-Use Bioreactor Platform Adoption | Automated pepsin digestion temperature control reduces endotoxin excursion rates in Massachusetts CMOs. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with collagen purification scientists, regulatory affairs leads at PMDA-registered manufacturers, hospital procurement managers in Osaka and Tokyo, and academic laboratory directors in Boston and Maryland with secondary validation. FDA 21 CFR Part 1271 guidance documents, EMA MDR implementation records, METI biological origin regulations, and NIH grant award databases anchored data triangulation. Bottom-up capacity estimates from identified production facilities reconciled against top-down demand aggregation across end-user segments.
Historical reference periods spanning pre-pandemic baseline through recent regulatory implementation phases anchored the forecast window. Segmentation modeling incorporated product format, purity grade, end-user institution type, and regional regulatory cluster dimensions. CAGRs derived from volume trajectory analysis across pharmaceutical-grade implantable applications, research-grade cell culture substrates, and cosmetic-grade aesthetic formulations. Forecast inputs included bovine raw material supply elasticity, recombinant collagen yield improvement curves, and cross-border equivalency agreement progression between FDA and PMDA.
Revisions become necessary when viral inactivation protocol changes, seismic disruption in Osaka-Tokyo manufacturing clusters, or recombinant collagen triple-helix fidelity breakthroughs materialize. Forecasts reflect documented assumptions about regulatory harmonization pace and raw material supply stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Bone Distractors Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Flowable Hemostats Market
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
South America Collagen Market
Biomaterials
Heparin Market
Biomaterials
Global Bioactive Materials Market
Biomaterials
Chitosan Films Market
Biomaterials
Europe Collagen Market
Biomaterials
Polysaccharide Hemostatic System Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Chitosan Market
Biomaterials
Nerve Repair Biomaterials Market
Biomaterials
Bone and Joints Ingredients Market
Biomaterials
Scaffold Materials Market
Biomaterials
Global Extracellular Matrix Patches Market