
 Polysaccharide Hemostatic System Market | 2026-2036
Polysaccharide Hemostatic System Market Size, Share, and Industry Trends Forecast 2026-2036
Polysaccharide Hemostatic System Market Analytics
China is narrowing its import dependency in absorbable hemostatics through domestic fermentation capacity additions for chitosan and oxidized cellulose precursors. Baxter International leverages backward integration into polysaccharide raw material supply to sustain margin stability across hospital purchasing cycles. Medtronic plc. anchors its position through proprietary cross-linking chemistries that differentiate performance in high-bleeding-risk procedures. Johnson & Johnson Services, Inc. competes on brand recognition in trauma bays where clinician familiarity drives repeat procurement.
A polysaccharide hemostatic system comprises bioabsorbable carbohydrate-based matrices engineered to accelerate clot formation through platelet aggregation and factor activation at bleeding sites. These systems typically incorporate oxidized regenerated cellulose, chitosan, or starch derivatives processed into standardized pore architectures with defined absorption profiles ranging from 24 hours to 14 days, serving primarily to control surgical bleeding without requiring subsequent removal. Granules and patches currently occupy the largest volume positions, with granules penetrating trauma and orthopedic applications where conformability to irregular wound beds matters, while patches dominate cardiothoracic procedures demanding uniform compression surfaces. Sponges represent the fastest-expanding format as surgeons adopt pre-shaped configurations for laparoscopic and endoscopic delivery channels where manual shaping proves impractical.
FDA 510(k) clearance requirements and ISO 10993 biocompatibility standards govern commercial entry, with FDA scrutiny intensifying around immunogenicity claims for novel marine-derived polysaccharides. The EU Medical Device Regulation imposes additional clinical evidence burdens through PMCF studies that extend validation timelines for CE-marked hemostatic products. Stakeholders must monitor evolving reimbursement thresholds for hemostatic adjuncts under CMS hospital outpatient prospective payment systems, where incremental technology add-on payments determine whether novel formulations displace established mechanical methods.
Market Dynamics
Centralized procurement by integrated delivery networks is compressing vendor margins and forcing polysaccharide hemostatic suppliers to demonstrate measurable blood-loss reduction metrics to retain hospital contracts.
Growth Catalysts
- Trauma surgery expansion:Tertiary hospitals in the United States are outfitting new hybrid operating suites with absorbable hemostatic matrices as standard equipment for damage-control laparotomy.
- FDA 510(k) streamlining:The premarket notification pathway for Class II hemostatic devices is accelerating commercial entry timelines for novel oxidized cellulose and chitosan formulations.
- Fermentation capacity buildout:Domestic production of chitosan precursors through microbial fermentation is reducing import dependency for marine-derived raw materials in East Asian manufacturing clusters.
Market Restraints
- Chitosan supply concentration:Overreliance on crustacean harvesting regions exposes processors to seasonal biomass volatility and shellfish disease outbreaks.
- EU MDR clinical burdens:Post-market clinical follow-up requirements for CE-marked hemostatic products are extending validation timelines and inflating regulatory compliance costs.
- Mechanical hemostasis persistence:Electrocautery and topical thrombin remain entrenched in cost-sensitive ambulatory surgical centers, limiting polysaccharide penetration in outpatient settings.
Strategic Opportunities
- Laparoscopic sponge formats:Pre-shaped hemostatic sponges designed for trocar delivery are capturing procedural volume as minimally invasive surgery expands in German and Japanese hospital systems.
- Marine biotechnology convergence:Synthetic biology platforms for engineered polysaccharide production are opening supply pathways independent of agricultural or fishery feedstocks.
- CMS technology add-on payments:Incremental reimbursement codes for hemostatic adjuncts in hospital outpatient prospective payment systems are creating financial headroom for premium absorbable matrices.
Industry Challenges
- Cross-linking chemistry expertise:Formulation scientists capable of tuning absorption profiles between 24 hours and 14 days remain scarce relative to expansion plans of matrix manufacturers.
- ISO 10993 biocompatibility validation:Extended cytotoxicity and sensitization testing for novel marine-derived polysaccharides is delaying product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polysaccharide Hemostatic System Market |
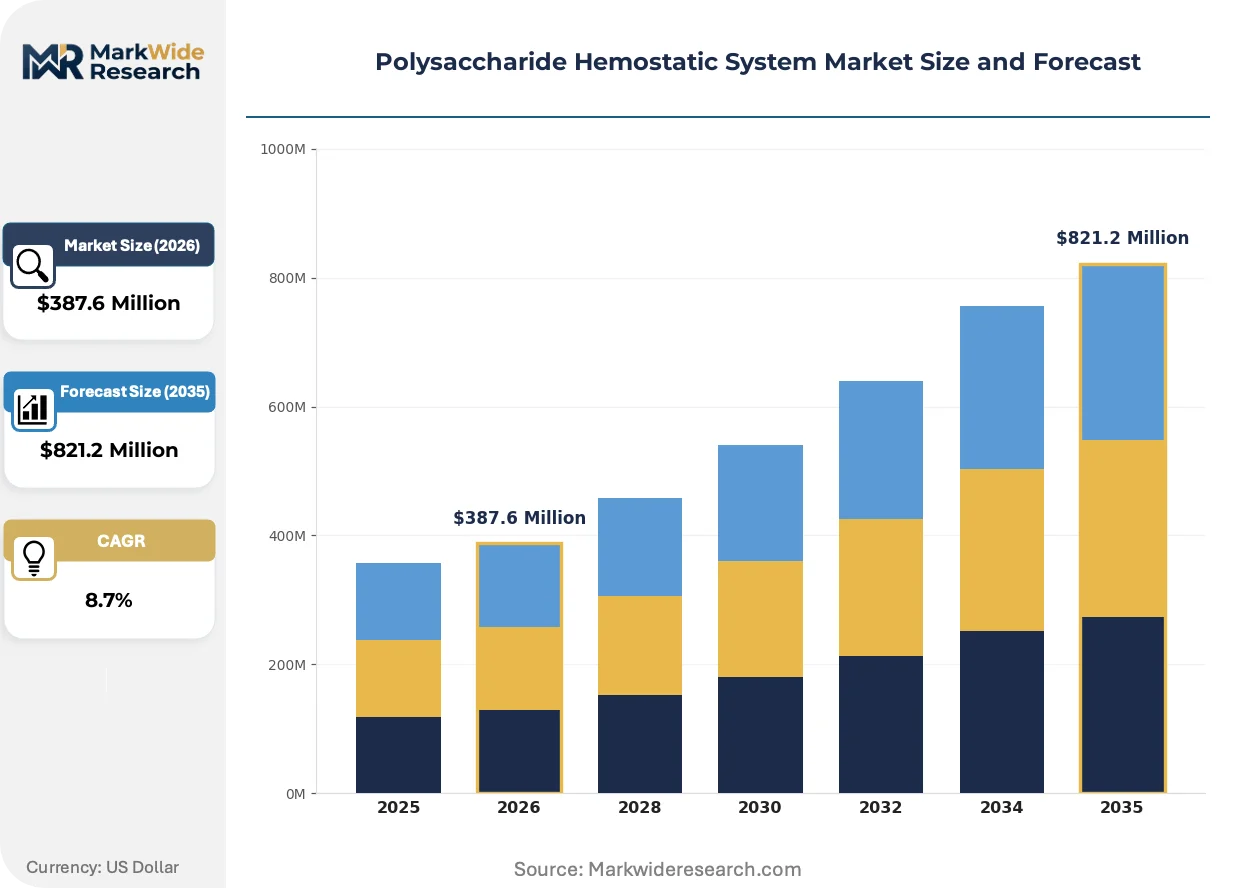
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Sponges, Patches, Sheets Application: Trauma Surgery, General Surgery, Orthopedic Surgery, Cardiothoracic Surgery Delivery Mode: Topical, Injectable, Surgical, Endoscopic End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions |
| Companies Covered | Baxter International Inc., Medtronic plc., Johnson & Johnson Services, Inc., 3M Company, Teleflex, Ethicon, Becton Dickinson and Company, Olympus Corporation, Integra LifeSciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polysaccharide Hemostatic System Market Evolving Landscape
Recombinant production methods and intelligent pore architectures are redefining performance benchmarks for absorbable hemostatics, while regulatory frameworks on both sides of the Atlantic recalibrate evidence requirements for clinical claims.
Lyophilized chitosan-calcium matrices with engineered nanofiber structures are rendering obsolete conventional granular formats in orthopedic trauma applications. Surgeons in level-I trauma centers are adopting these configurations for complex pelvic fractures where conformability and rapid factor activation prove decisive. The shift is compressing demand for oxidized regenerated cellulose granules in high-bleeding-risk procedures.
The EU Medical Device Regulation's post-market surveillance mandates are intensifying documentation burdens for hemostatic device manufacturers seeking CE marking renewal. Companies must now maintain active implant registries and periodic safety update reports that extend beyond legacy vigilance requirements. High-bleeding-risk cardiovascular applications face the steepest compliance escalation, with notified bodies demanding procedure-specific clinical evidence.
Hospital value analysis committees are consolidating hemostatic purchasing decisions at integrated delivery network headquarters rather than individual facility materials management. This concentration is displacing distributor-centric selling models that relied on surgeon preference cards and local rep relationships. The United States exhibits the most pronounced centralization, with three national IDNs controlling access to over forty percent of tertiary surgical volume.
Polysaccharide Hemostatic System Market Segmentation
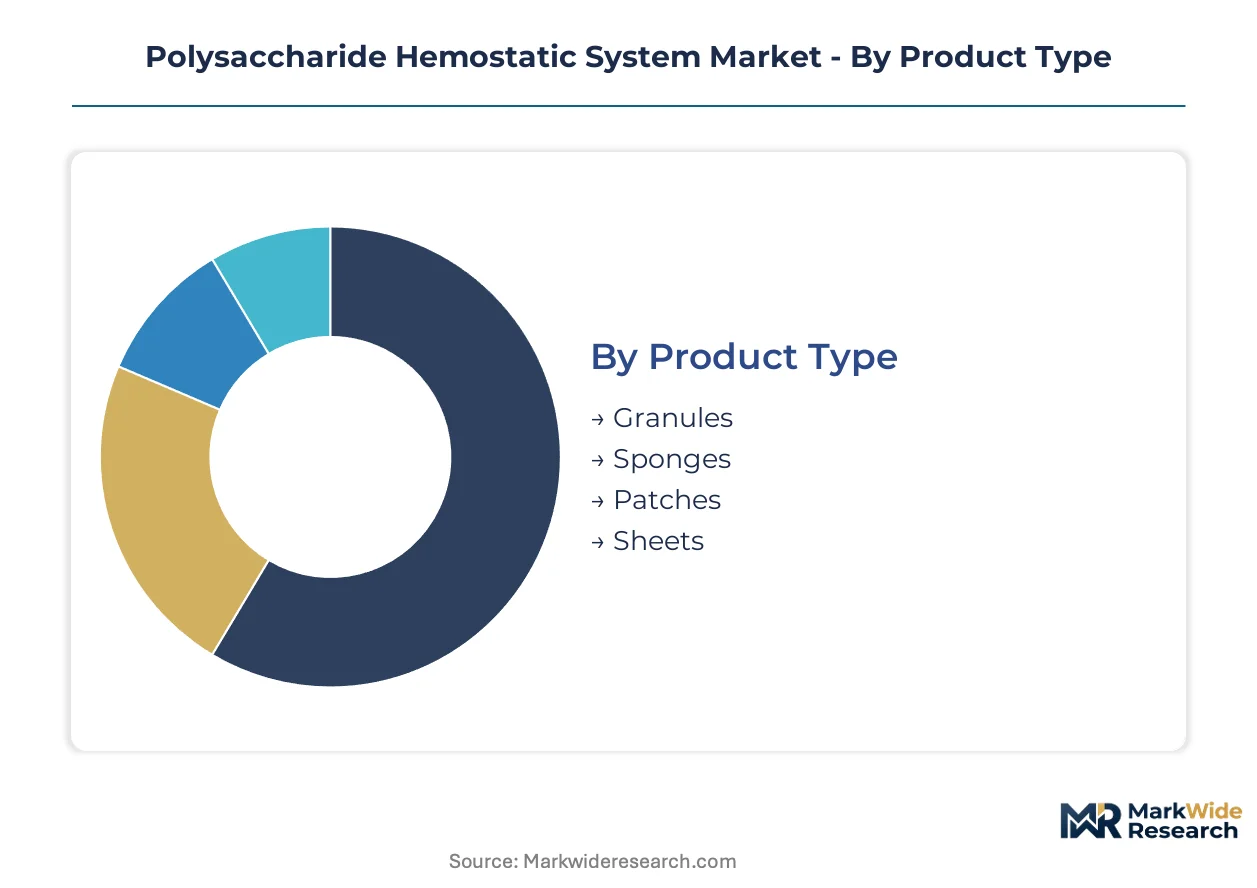
Polysaccharide hemostatic systems fragment across four distinct classification axes that determine procurement workflows, reimbursement coding, and clinical training requirements. Product geometry dictates handling protocols in sterile fields. Application specialization drives regulatory evidence burdens and pricing tier placement.
Product Type:
Absorption cycle times vary dramatically across formats, with some configurations clearing wound beds within 24 hours while others maintain structural integrity for two weeks, directly impacting inventory turnover and shelf-life management.
- Granules:Free-flowing oxidized cellulose or starch particulates engineered for rapid deployment into irregular wound cavities. Trauma bays in United States level-I centers favor granules for penetrating abdominal injuries where conformability to tissue planes outweighs compression uniformity. Shelf-life degradation accelerates turnover cycles relative to sheet formats.
- Sponges:Pre-shaped lyophilized matrices with defined pore architectures designed for trocar delivery in laparoscopic channels. German and Japanese hospital systems are expanding sponge adoption as minimally invasive procedural volumes climb, compressing demand for manually configurable alternatives. Manufacturing lead times extend replenishment cycles versus granule production.
- Patches:Uniform compression surfaces with calibrated thickness for cardiothoracic applications requiring hemostasis under direct visualization.
- Sheets:Large-format matrices cut to specification in sterile fields, carrying the longest inventory cycles due to customizable deployment.
Granules anchor the volume base while sponges gain share at the steepest rate.
Application:
Procedure complexity and bleeding risk stratification determine which polysaccharide formats penetrate each surgical domain, with high-acuity settings commanding premium absorption profiles and extended structural integrity.
- Trauma Surgery:Damage-control laparotomy and emergency thoracotomy procedures requiring immediate hemostasis under resuscitation conditions. United States tertiary hospitals outfit hybrid operating suites with absorbable matrices as standard equipment, with procurement concentrated through integrated delivery network headquarters rather than individual facility purchasing.
- General Surgery:Elective abdominal and soft-tissue procedures where blood loss remains modest and mechanical methods compete effectively. Ambulatory surgical centers in cost-sensitive markets limit polysaccharide uptake here, constraining segment expansion relative to trauma applications.
- Orthopedic Surgery:Complex pelvic fracture repair and joint reconstruction demanding conformability to irregular bone surfaces.
- Cardiothoracic Surgery:Sternotomy and thoracotomy sites requiring uniform compression under positive-pressure ventilation.
Trauma surgery commands the highest per-procedure consumption intensity while general surgery contributes the broadest case volume base.
Delivery Mode:
Channel access requirements and sterile field protocols segment the market by deployment mechanism, with minimally invasive expansion reshaping format preferences.
- Topical:Direct surface application for accessible bleeding sites in open procedures, dominating current volume through simplicity and clinician familiarity.
- Injectable:Flowable formulations delivered through catheters for deep or non-compressible hemorrhage.
- Surgical:Open-field deployment with manual compression, the established default in trauma and orthopedic settings.
- Endoscopic:Trocar-compatible formats gaining traction as laparoscopic volumes expand in German and Japanese hospital systems.
Topical delivery maintains the installed base while endoscopic formats expand most quickly through minimally invasive procedural adoption.
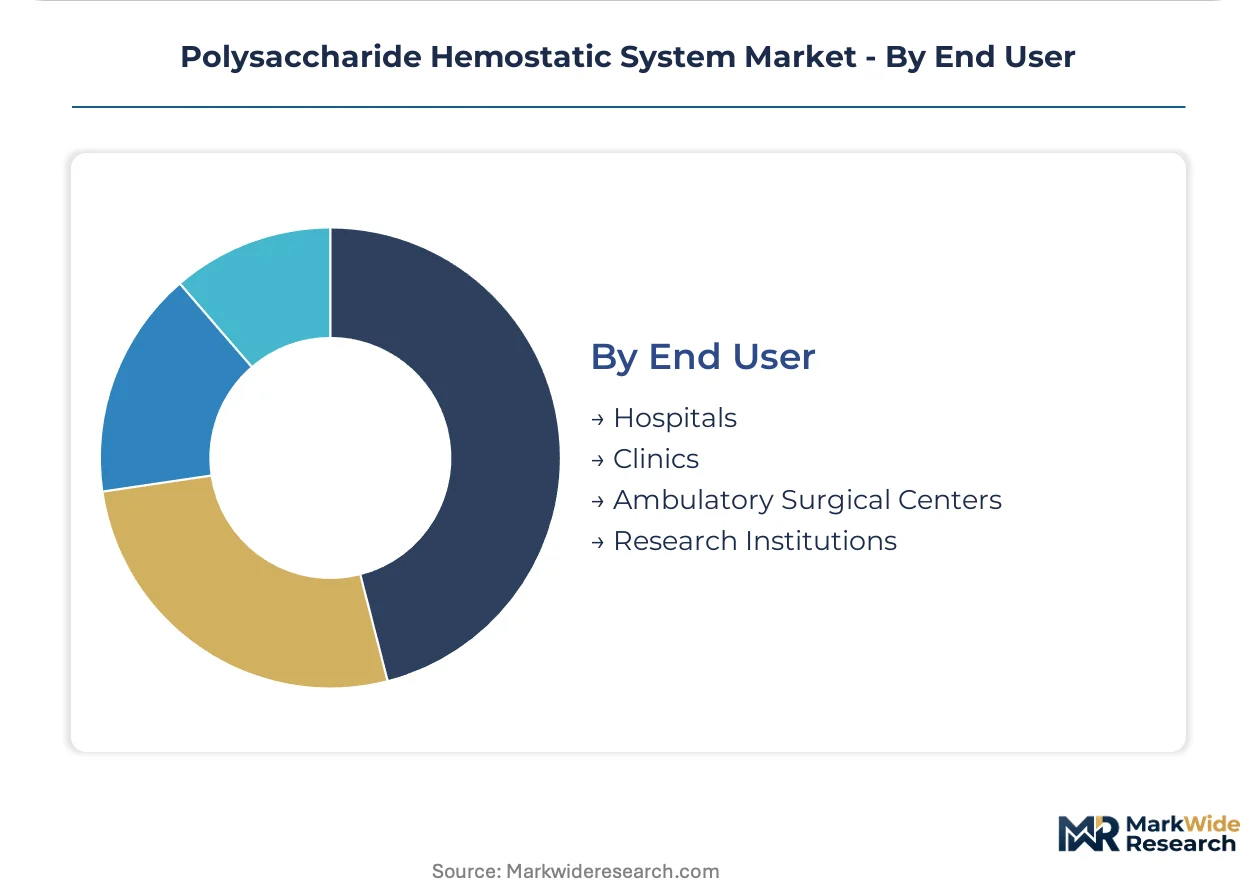
End User:
Purchasing concentration and reimbursement sophistication determine addressable market structure across care settings.
- Hospitals:Tertiary and community facilities where value analysis committees centralize hemostatic procurement decisions. Three United States integrated delivery networks control access to over forty percent of tertiary surgical volume, compressing vendor margins and demanding measurable blood-loss reduction metrics.
- Clinics:Outpatient settings with limited surgical infrastructure and price-sensitive procurement patterns.
- Ambulatory Surgical Centers:Elective procedure hubs where mechanical hemostasis and topical thrombin retain cost advantages, limiting polysaccharide penetration.
- Research Institutions:Academic medical centers driving clinical evidence generation for novel marine-derived formulations under FDA and EU MDR scrutiny.
Hospitals concentrate purchasing power while ambulatory surgical centers present the steepest access barriers due to mechanical method entrenchment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polysaccharide hemostatic manufacturing clusters in the United States, Germany, China, Japan, and Switzerland concentrate the bulk of fermentation capacity and cross-linking chemistry expertise. FDA 510(k) pathways and EU MDR frameworks create divergent commercial entry timelines across these jurisdictions. Procurement centralization through integrated delivery networks is reshaping distribution economics in North American and European hospital systems.
United States
Hybrid trauma surgery suites in level-I centers drive absorbable matrix consumption as standard equipment for damage-control laparotomy. FDA premarket notification pathways for Class II hemostatic devices accelerate commercial entry timelines for novel oxidized cellulose formulations. Boston and Minneapolis medical device corridors host formulation scientists specializing in 24-hour to 14-day absorption profile tuning.
Germany
Minimally invasive procedural volumes in German hospital systems expand demand for pre-shaped hemostatic sponges designed for trocar delivery. EU Medical Device Regulation post-market clinical follow-up requirements extend validation timelines for CE-marked products seeking renewal. The Baden-Württemberg industrial cluster sustains expertise in engineered nanofiber structures for lyophilized matrices.
China
Domestic fermentation capacity additions for chitosan and oxidized cellulose precursors narrow import dependency in East Asian manufacturing. NMPA regulatory frameworks govern commercial entry for novel marine-derived polysaccharides with intensified immunogenicity scrutiny. Yangtze River Delta biotech corridors scale microbial production platforms independent of crustacean harvesting cycles.
Japan
PMDA biocompatibility standards and ISO 10993 validation requirements shape product launch schedules for absorbable hemostatic matrices. METI industrial policy supports synthetic biology platforms for engineered polysaccharide production. The Kansai region around Osaka concentrates surgical device distribution networks serving laparoscopic procedural expansion.
Switzerland
Swissmedic regulatory frameworks align with EU MDR clinical evidence burdens for hemostatic device manufacturers seeking European market access. Precision fermentation expertise in the Basel-Zürich corridor enables recombinant production methods for carbohydrate-based matrices. Alpine biotechnology clusters develop supply pathways independent of agricultural or fishery feedstocks.
Polysaccharide Hemostatic System Market Competitive Landscape
Integrated multinationals and specialized hemostatic device manufacturers split the market between scale-driven procurement consolidation and technology-differentiated niche positioning. Three strategic archetypes dominate: diversified medical technology conglomerates with backward integration into polysaccharide raw material supply, mid-cap surgical device specialists with proprietary cross-linking chemistries, and regional fermentation-based producers leveraging domestic chitosan capacity. Competitive moves concentrate on M&A activity targeting formulation expertise and strategic partnerships securing marine biotechnology feedstocks.
Among diversified medical technology conglomerates, Baxter International Inc. and Medtronic plc. occupy positions exemplifying backward integration archetypes, while Johnson & Johnson Services, Inc. anchors brand-recognition positioning in trauma bay procurement workflows. These three entities represent distinct competitive vectors: captive supply chain control, proprietary chemistry differentiation, and clinician familiarity driving repeat hospital purchasing decisions.
| Leading Market Players |
|---|
| Baxter International Inc. |
| Medtronic plc. |
| Johnson & Johnson Services, Inc. |
| 3M Company |
| Teleflex |
| Ethicon |
| Becton Dickinson and Company |
| Olympus Corporation |
| Integra LifeSciences Corporation |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta fermentation corridor anchors global chitosan precursor capacity, with microbial production scale directly determining margin headroom for downstream absorbable matrix manufacturers bidding into hospital IDN contracts.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across polysaccharide hemostatic systems, separating premium cross-linked formulations with 14-day absorption profiles from standard 24-48 hour matrices and economy-grade oxidized cellulose alternatives. Price differentiation rests on ISO 10993 biocompatibility certification levels and proprietary nanofiber engineering, with German and Japanese hospital systems paying premiums for trocar-compatible sponge formats. Cost compression in standard-tier granules is intensifying because integrated delivery networks demand measurable blood-loss reduction metrics, while ambulatory surgical centers remain the most price-sensitive buyers due to mechanical hemostasis entrenchment.
Supply Chain Analysis
Crustacean biomass and microbial fermentation feedstocks determine upstream cost structures for chitosan production, with supply concentrating in China, Vietnam, and Indonesia for marine-derived raw materials while Switzerland and Germany host recombinant precision fermentation platforms. Raw material dependencies span chitosan precursors, oxidized regenerated cellulose, and specialized cross-linking reagents, with single-source vulnerability concentrated in seasonal shellfish harvesting cycles. Distribution runs through integrated delivery network headquarters in the United States and hospital system procurement consortia in Germany and Japan, displacing distributor-centric models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polysaccharide hemostatic procurement is consolidating onto platform economics as hospital value analysis committees standardize around interoperable absorption profiles and centralized vendor qualification systems.
For Market Incumbents: Harden cross-linking chemistry expertise through captive R&D investment in Boston and Minneapolis medical device corridors, insulating proprietary 24-hour to 14-day absorption tuning capabilities from formulation scientist scarcity. Deepen backward integration into fermentation capacity for chitosan precursors, neutralizing crustacean biomass volatility threats from Southeast Asian supply regions. For New Entrants and Emerging Players: Ambulatory surgical centers in cost-sensitive United States markets present the most penetrable white-space target, where mechanical hemostasis and topical thrombin retain entrenched positions due to price sensitivity rather than clinical superiority. Synthetic biology platforms for engineered polysaccharide production offer a go-to-market angle independent of fishery feedstock constraints, with marine biotechnology convergence enabling supply pathway differentiation. For Investors and Strategic Acquirers: Long-term, this sits as a capability-capture play because cross-linking chemistry expertise and proprietary absorption profile tuning remain scarce relative to matrix manufacturer expansion plans, creating durable moats for specialized formulation assets. Target mid-cap surgical device specialists with FDA-cleared 510(k) portfolios and demonstrated hospital IDN contract traction. Monitor CMS technology add-on payment decisions for hemostatic adjuncts as the inflection signal indicating reimbursement headroom expansion for premium absorbable matrices.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates commercial entry timelines for novel oxidized cellulose and chitosan formulations in United States trauma centers. |
| CE Marking Renewal Strategy | Addresses EU MDR post-market clinical follow-up burdens through active implant registries and periodic safety update reports. |
| Hospital System Partnership | Secures centralized procurement contracts with integrated delivery networks controlling forty percent of tertiary surgical volume. |
| Reimbursement Strategy | Positions premium absorbable matrices for CMS technology add-on payments in hospital outpatient prospective payment systems. |
| Backward Integration into Fermentation | Sustains margin stability across hospital purchasing cycles through captive supply of chitosan and oxidized cellulose precursors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across this analysis, combining primary interviews with trauma surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 10993 biocompatibility standards. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Calibration across the analysis window employed procedure volume projections, absorption format adoption curves, and regulatory approval timelines to derive growth trajectories. Segmentation dimensions modeled include product geometry, application specialization, delivery mode, and end-user purchasing concentration, with CAGRs reflecting hospital IDN consolidation rates and minimally invasive procedural expansion patterns.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles, CMS reimbursement policy, or crustacean biomass harvest yields would shift the trajectory for fermentation-dependent supply chains. Cross-checking against hospital procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
Nerve Repair Biomaterials Market
Biomaterials
Self-Healing Materials Market
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
Bone and Joints Ingredients Market
Biomaterials
Flowable Hemostats Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Bone Substitutes Market
Biomaterials
Crocodile Peptide Market
Biomaterials
Biomaterial Wound Dressing Market
Biomaterials
Scaffold Materials Market
Biomaterials
Global Biomaterials Market
Biomaterials
US Heparin Market
Biomaterials
Global Hydroxyapatite Market
Biomaterials
Biodegradable Bone Graft Polymers Market