
 Hydrogel Market | 2026-2036
Hydrogel Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogel Market Intelligence
Application-specific formulation support for complex medical devices is restructuring the commercial model beyond bulk material sales. This shift favors suppliers who can provide deep technical collaboration. Smith & Nephew leverages its specialized knowledge in advanced wound care to develop proprietary hydrogel dressings. B. Braun Melsungen competes by offering integrated solutions that combine its hydrogels with drug delivery systems for clinical applications.
A hydrogel is a three-dimensional network of hydrophilic polymer chains, capable of holding large amounts of water while maintaining its structure due to chemical or physical cross-linking. Its primary commercial purpose is to provide controlled release, high absorbency, and biocompatible scaffolding in medical and consumer applications. Within applications, wound care and drug delivery constitute the largest value pools, driven by clinical needs in chronic care. Injectable and microparticle forms are gaining share over traditional sheet hydrogels, enabling minimally invasive procedures and targeted therapies.
Market access is governed by stringent regulatory approvals from bodies like the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA). In China, compliance with NMPA standards for medical materials is critical for manufacturers seeking to enter its healthcare market. Future competitive advantage will depend on navigating these diverse regulatory pathways while innovating in biodegradable and stimuli-responsive materials.
Market Dynamics
The central force restructuring the hydrogel market is the shift from commodity polymer sales to collaborative, application-specific formulation services. This transition is driven by the increasing complexity of medical devices and clinical demands for functional, integrated materials.
Growth Catalysts
- Chronic Disease Management:Demand for advanced dressings to treat diabetic ulcers and pressure sores is a primary catalyst in regions with aging populations.
- Injectable Formulations:The rise of injectable hydrogels enables minimally invasive procedures in drug delivery and tissue engineering, expanding the addressable market.
- Regulatory Harmonization:IMDRF initiatives to align standards for medical devices ease cross-border market access for hydrogel-based products.
Market Restraints
- Raw Material Costs:Prices for synthetic hydrophilic polymers are tied to volatile petrochemical markets, creating margin pressure for manufacturers.
- Sterilization Challenges:Many hydrogels are incompatible with cost-effective sterilization like gamma irradiation, requiring expensive alternatives that raise product cost.
- Substitution Risk:In less critical applications, lower-cost alternatives like traditional gauze and foam dressings limit hydrogel adoption.
Strategic Opportunities
- 3D Bioprinting Integration:Using hydrogels as bio-inks for printing tissue scaffolds and organoids opens new frontiers in regenerative medicine research.
- Veterinary Medicine:The underpenetrated market for advanced wound care in companion and livestock animals presents a significant growth opportunity.
- Stimuli-Responsive Polymers:Hydrogels that react to pH or temperature create potential for targeted drug delivery and smart diagnostic systems.
Industry Challenges
- Lengthy Clinical Validation:Demonstrating safety and efficacy to meet stringent requirements from regulators like the FDA and under the EU's MDR is a time-consuming and costly process.
- Manufacturing Scale-Up:Consistently reproducing complex hydrogel properties from lab-scale batches to large-volume industrial production remains a significant chemical engineering hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogel Market |
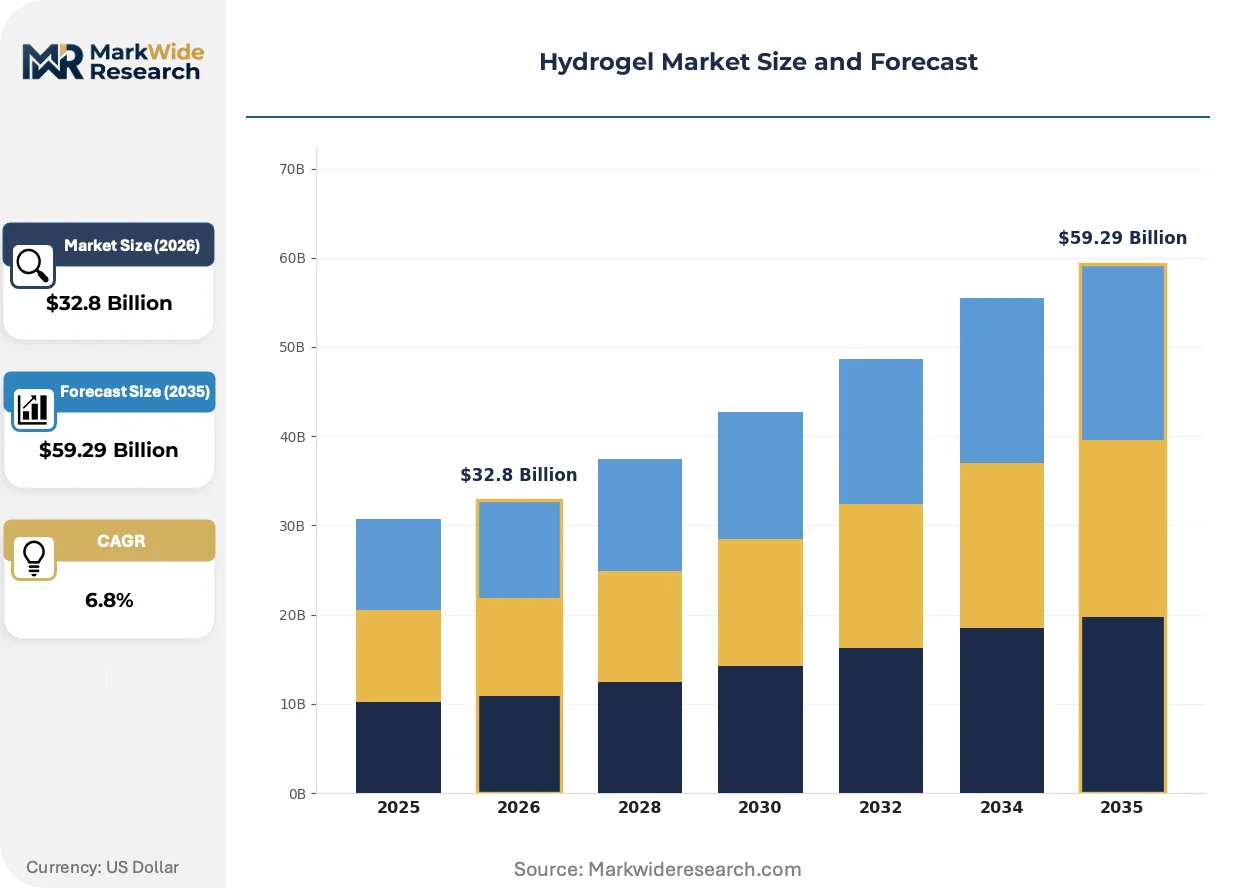
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $59.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic Acid, Polyvinyl Alcohol, Polyacrylamide, Natural Hydrogels Application: Wound Care, Drug Delivery, Contact Lenses, Tissue Engineering End User: Pharmaceutical Manufacturers, Medical Device Companies, Research Institutes, Cosmetic Producers Form: Sheet, Granules, Microparticles, Injectable |
| Companies Covered | Smith & Nephew, Convatec, Johnson & Johnson, Ashland, B. Braun Melsungen, 3M Company, Coloplast, Royal DSM, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogel Market Strategic Shifts & Innovations
Material intelligence is fundamentally altering the hydrogel value proposition. Products are evolving from passive, water-absorbent matrices into active, functional components of sophisticated therapeutic and diagnostic systems, demanding deeper integration with device engineering and clinical workflows.
Smart hydrogels integrated with micro-sensors represent a key technological evolution. These materials monitor wound-site metrics like pH, temperature, or bacterial load. Advanced wound care clinics are the primary adopters, and this technology is automating clinical data collection, reducing the need for invasive inspections.
The European Union's Medical Device Regulation (MDR) intensifies scrutiny on material biocompatibility and clinical evidence. This regulation forces manufacturers to provide extensive data on long-term safety and performance. Device makers using hydrogels in implantable applications are reformulating products and investing heavily in new clinical trials.
A distinct behavioral shift sees healthcare providers moving from purchasing bulk hydrogels to procuring complete therapeutic systems. This change disrupts the model for traditional polymer suppliers, pushing them toward partnerships with device firms. The trend is pronounced in oncology, where integrated drug-eluting injectables offer superior clinical outcomes.
Hydrogel Market Segmentation
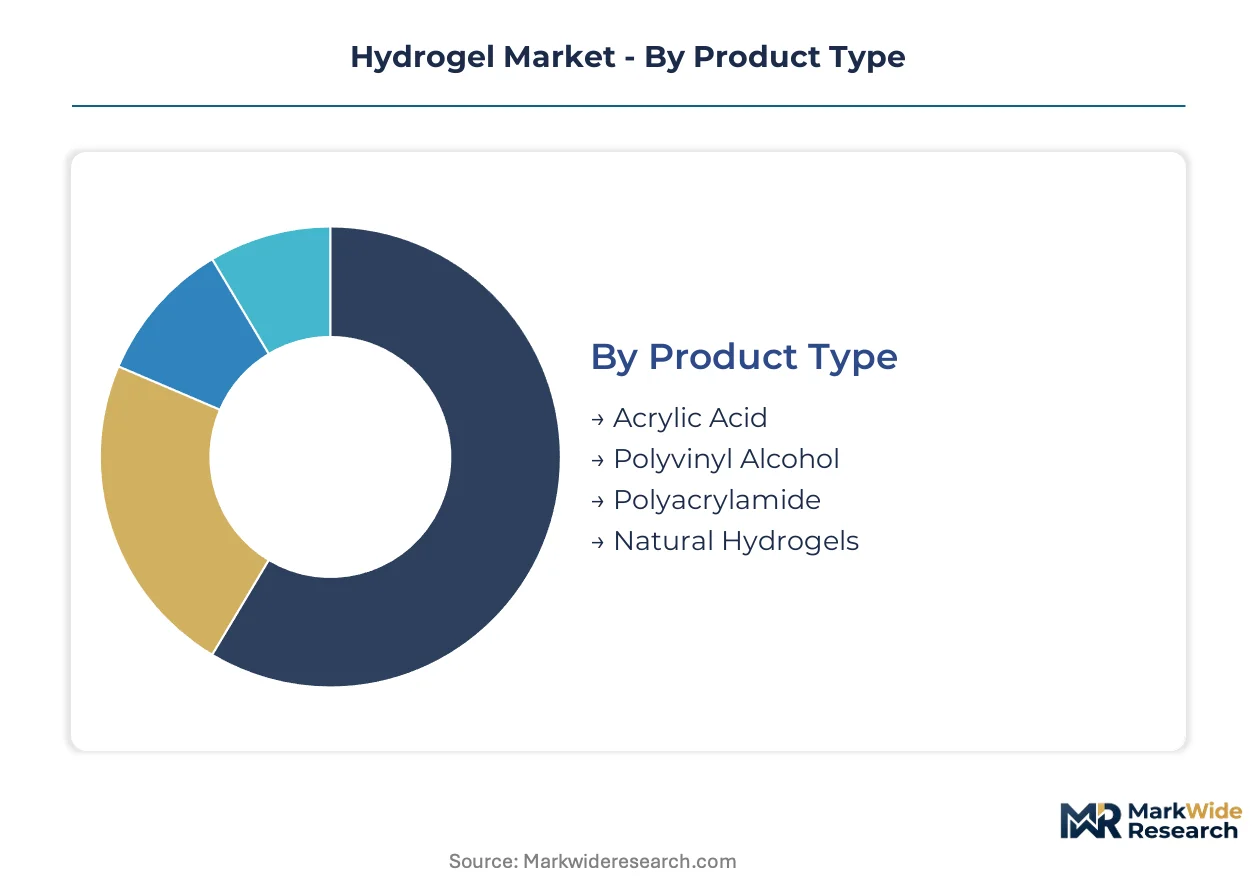
The hydrogel market exhibits diverse characteristics across its various segments, reflecting specialized material compositions and targeted functionalities. Understanding these distinctions is crucial for identifying areas of concentrated demand and emerging growth opportunities. Material innovation directly influences segment performance across therapeutic and diagnostic applications.
Product Type:
Hydrogel product types range from standalone material sales to highly integrated components within complex medical devices.
- Natural Hydrogels:Natural hydrogels, derived from biopolymers like alginate or chitosan, offer superior biocompatibility and biodegradability. Demand is concentrating in advanced wound care and tissue engineering, driven by clinical needs for non-toxic, resorbable materials.
- Acrylic Acid:Acrylic acid-based hydrogels are synthetic polymers known for their high absorbency and mechanical strength. Their demand is strong in diaper manufacturing and certain wound dressings, where cost-effectiveness and performance are critical factors.
- Polyvinyl Alcohol:Polyvinyl alcohol hydrogels provide good elasticity and transparency, finding use in contact lenses and drug delivery systems.
- Polyacrylamide:Polyacrylamide hydrogels are utilized for their chemical stability and swelling properties, often employed in electrophoresis gels and some medical implants.
Volume placements concentrate in Acrylic Acid; the faster expansion belongs to Natural Hydrogels.
Application:
The hydrogel market applications are defined by specific clinical needs and functional requirements across diverse medical fields.
- Wound Care:Hydrogels in wound care provide a moist healing environment, debridement, and pain reduction for chronic wounds. Demand is high in Germany, driven by an aging population and stringent requirements for advanced dressings under EU MDR.
- Drug Delivery:Hydrogels serve as matrices for controlled drug release, enabling targeted and sustained therapeutic effects. This application sees significant demand in oncology, where integrated drug-eluting injectables offer superior clinical outcomes.
- Contact Lenses:Hydrogels form the primary material for soft contact lenses, valued for their oxygen permeability and comfort.
- Tissue Engineering:In tissue engineering, hydrogels act as biocompatible scaffolds, supporting cell growth and differentiation for regenerative medicine.
Clinical impact is highest in Wound Care; Tissue Engineering offers significant future potential for regenerative therapies.
End User:
End-user segments for hydrogels reflect varied procurement strategies and integration levels within their respective industries.
- Medical Device Companies:Medical device companies integrate hydrogels into advanced wound dressings, implants, and diagnostic tools. Their procurement patterns prioritize technical collaboration and application-specific formulation support from suppliers.
- Pharmaceutical Manufacturers:Pharmaceutical manufacturers utilize hydrogels for controlled release drug delivery systems and specialized formulations. Regulatory approval from bodies like the FDA and EMA for combination products significantly influences their material selection.
- Research Institutes:Research institutes use hydrogels for fundamental studies in biomaterials, tissue engineering, and drug discovery.
- Cosmetic Producers:Cosmetic producers incorporate hydrogels into skincare products for hydration, texture, and active ingredient delivery.
The largest value pool resides with Medical Device Companies; Research Institutes are expanding their hydrogel consumption for novel applications.
Form:
Hydrogel forms dictate the delivery mechanism and suitability for various clinical and consumer applications.
- Injectable:Injectable hydrogels enable minimally invasive procedures for drug delivery, tissue augmentation, and localized therapies. This form is gaining share due to patient comfort and precise anatomical targeting.
- Microparticles:Hydrogel microparticles offer targeted drug delivery and enhanced bioavailability by encapsulating active compounds. Their use is expanding in oncology and ophthalmology for controlled release at specific sites.
- Sheet:Sheet hydrogels are traditional forms used primarily in wound dressings, providing a moist healing environment.
- Granules:Hydrogel granules are employed in superabsorbent applications and some wound fillers for their high fluid uptake capacity.
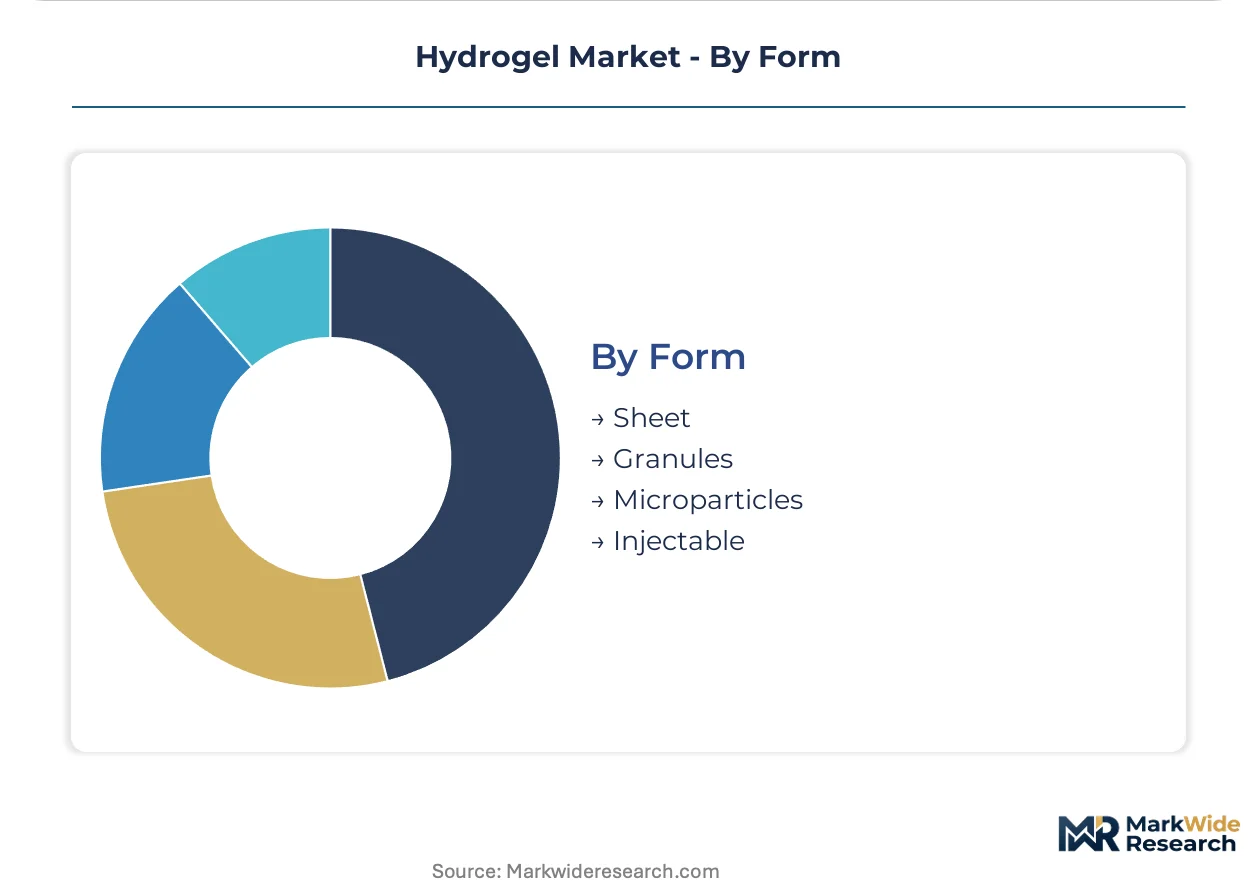
Traditional demand centers on Sheet forms; Injectable hydrogels are seeing accelerated adoption for advanced clinical procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hydrogel market exhibits a distinct geographic split between advanced material production and high-volume application consumption. Production capabilities for specialized polymers are concentrated in developed economies, while significant demand for end-use products like wound care dressings spans global healthcare systems. This creates complex trade flows and localized manufacturing strategies.
United States
Demand for hydrogels in the United States is driven by its large chronic wound patient population and extensive pharmaceutical research. FDA regulations mandate rigorous clinical trials for new hydrogel-based medical devices and drug delivery systems. The Boston-Cambridge biotech cluster actively develops novel hydrogel applications for regenerative medicine.
Germany
Germany's market for hydrogels is propelled by its robust medical technology sector and the need for sophisticated wound care products. The EU Medical Device Regulation (MDR) significantly influences material selection and clinical evidence requirements. Bavarian medical technology clusters focus on integrated solutions combining hydrogels with drug delivery systems.
China
Expanding healthcare infrastructure in China fuels significant demand for hydrogels, particularly in advanced wound care and drug delivery. Compliance with NMPA standards is essential for manufacturers introducing hydrogel-based products. Shanghai's rapidly growing medical device manufacturing base integrates hydrogels into various therapeutic and diagnostic tools.
Japan
Japan's demand for hydrogels stems from its aging demographic and strong emphasis on minimally invasive medical procedures. PMDA guidelines ensure the safety and efficacy of hydrogel-based medical devices and regenerative medicine applications. Research institutions in Tokyo pioneer novel stimuli-responsive hydrogels for smart diagnostic and therapeutic systems.
India
India exhibits growing demand for hydrogels, driven by its large population and increasing incidence of chronic diseases like diabetes. The CDSCO regulates approval for hydrogel-containing medical devices and pharmaceutical products within the country. Hyderabad's pharmaceutical and biotechnology sector explores hydrogel applications for controlled drug release.
Hydrogel Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the hydrogel market, creating a tiered competitive structure. The market spans large chemical conglomerates supplying bulk polymers and specialized medical device firms integrating hydrogels into complex therapeutic systems. Key archetypes include raw material suppliers, integrated solution providers, and niche innovators focusing on advanced biomaterials. Strategic partnerships between material science companies and device manufacturers are common, alongside targeted portfolio diversification into high-value applications.
Specialists in advanced wound care technology, such as Smith & Nephew, exemplify firms leveraging deep application knowledge to develop proprietary hydrogel dressings. B. Braun Melsungen AG represents another archetype, offering integrated solutions that combine hydrogels with advanced drug delivery systems for clinical use. These companies focus on high-value, clinically driven applications requiring extensive technical collaboration and regulatory expertise. Material science companies like Royal DSM, a Netherlands-based corporation, anchor the supply chain by providing specialized polymer components. These players navigate stringent regulatory pathways while innovating in biodegradable and stimuli-responsive materials.
| Leading Market Players |
|---|
| Smith & Nephew |
| Convatec |
| Johnson & Johnson |
| Ashland |
| B. Braun Melsungen |
| 3M Company |
| Coloplast |
| Royal DSM |
| Cardinal Health |
| Others |
Cost & Logistics Intelligence
A clear performance gap between highly specialized hydrogels for implantable devices and commodity hydrogels for wound dressings creates a bifurcated pricing structure, influencing sourcing strategies across the supply chain.
Pricing Analysis
Margin compression in commodity hydrogels stems from volatile petrochemical input costs and competition from lower-cost alternatives like traditional gauze. The dominant pricing model is per-unit transactional, with long-term contracts for bulk suppliers. Price differentiation derives from material biocompatibility certifications and customization for specific medical device integration. Medical device companies integrating hydrogels into complex systems are less price-sensitive than consumer product manufacturers.
Supply Chain Analysis
Single-source vulnerability sits with specialized polymer manufacturers for high-purity, medical-grade hydrophilic polymers. Geographic supply concentration for key raw materials like acrylic acid and polyvinyl alcohol centers on China and Germany. Raw material costs, tied to volatile petrochemical markets, present a significant supply chain risk. Distribution runs through a mix of direct sales to large device manufacturers and specialized chemical distributors for smaller players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
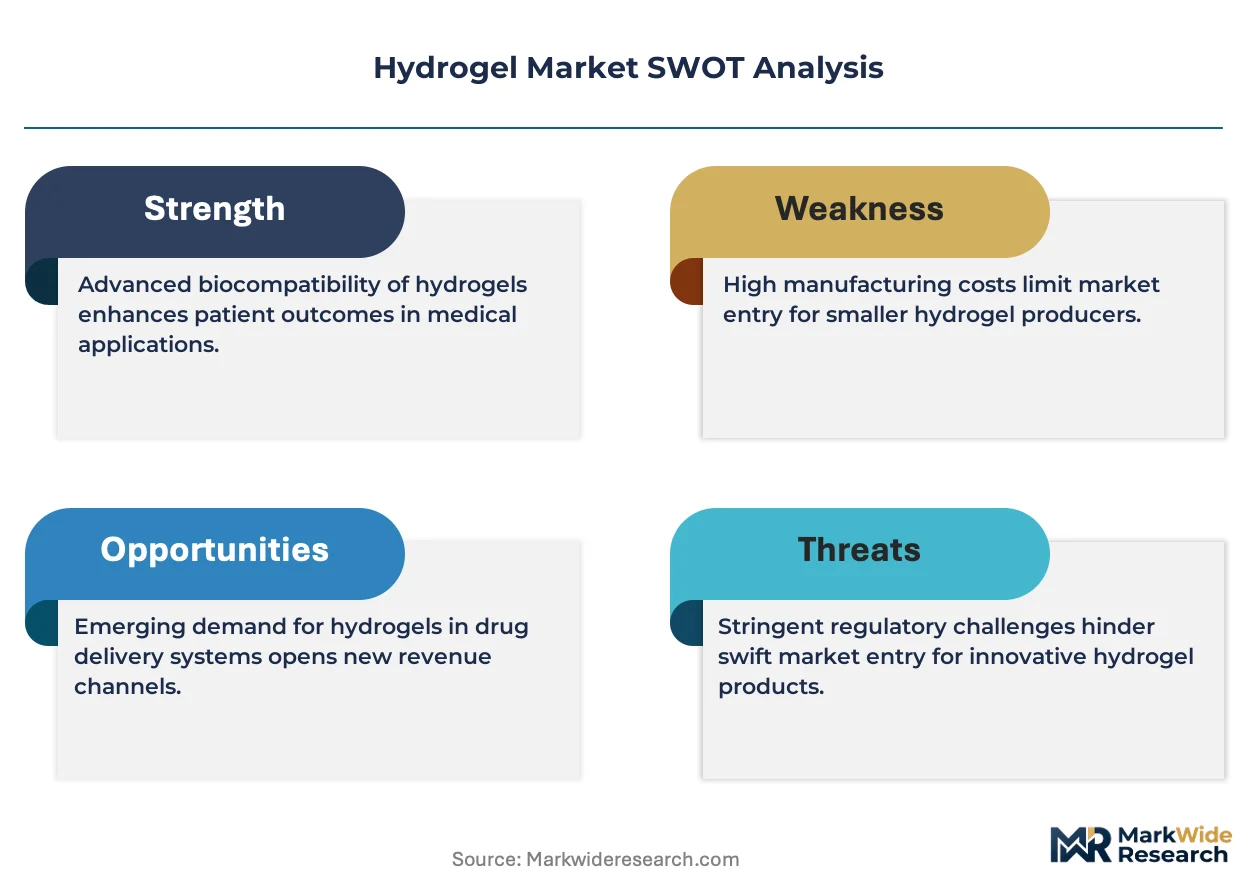
The hydrogel market is consolidating, driven by stringent regulatory requirements under the EU MDR that disproportionately burden smaller, less capitalized firms.
For Market Incumbents: Deepen technical collaboration with medical device companies to co-develop application-specific hydrogel formulations. This mitigates the threat from emerging niche innovators focusing solely on material science. Invest in advanced manufacturing capabilities for stimuli-responsive and biodegradable materials, leveraging certification investment to maintain market leadership against regulatory shifts.
For New Entrants and Emerging Players: A significant price-point gap exists between premium, custom-formulated hydrogels and standard, off-the-shelf options. Target underpenetrated applications in veterinary medicine or specialized diagnostic systems, offering cost-effective, high-performance alternatives. Focus on novel biodegradable materials with a streamlined regulatory pathway as a go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by large pharmaceutical or medical device conglomerates seeking advanced material capabilities. Long-term viability hinges on companies demonstrating robust intellectual property in next-generation hydrogel technologies. Watch for successful clinical trial outcomes for injectable or smart hydrogel applications as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Application-Specific Formulation Services | Increases value capture by moving beyond bulk material sales for medical device companies. |
| Invest in Biodegradable Polymer R&D | Addresses regulatory pressure for sustainable materials and opens new clinical applications. |
| Secure Long-Term Raw Material Contracts | Mitigates margin pressure from volatile petrochemical markets for manufacturers. |
| Pursue Regulatory Approvals in China | Unlocks access to a rapidly expanding healthcare market for hydrogel products. |
| Develop Integrated Drug-Eluting Systems | Enhances clinical outcomes in oncology and differentiates offerings for pharmaceutical manufacturers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews engaged R&D directors, procurement leads at medical device firms, regulatory affairs specialists, and clinicians specializing in wound care. This blend of qualitative insights and quantitative data informed both top-down market sizing and bottom-up segment validation.
Reconciling diverse data streams across the analysis window established the foundational market figures. Segmentation dimensions modeled included product type, application, end-user, form, and specific material composition. Compound annual growth rates were derived from historical trends and projected future demand drivers like chronic disease prevalence and regulatory approval timelines for novel therapies. Regulatory changes formed a key forecast input.
Inputs from industry reports and company disclosures were available through the study window; gaps in emerging technology adoption rates introduce uncertainty bands. Forecasts reflect assumptions regarding clinical acceptance and R&D success. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Hydroxyapatite Market
Biomaterials
Orthopedic Bone Defect Repair Materials Market
Biomaterials
Chitosan Films Market
Biomaterials
Bone Distractors Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Crocodile Peptide Market
Biomaterials
Bone and Joints Ingredients Market
Biomaterials
Global Collagen Meniscus Implants Market
Biomaterials
Self-Healing Materials Market
Biomaterials
United Kingdom Collagen Market
Biomaterials
Chitosan Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Scaffold Materials Market
Biomaterials
Brazil Bone Graft and Substitutes Market