
 Bone and Joints Ingredients Market | 2026-2036
Bone and Joints Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Bone and Joints Ingredients Market Outlook
European collagen peptide production is hardening as a supply anchor for the bone and joints ingredients sector. DSM-Firmenich AG leverages its fermentation-derived glucosamine platforms to secure pharmaceutical-grade supply chains. BASF SE anchors its position through synthetic chondroitin sulfate capacity at Ludwigshafen. Glanbia plc competes via its dairy-derived bioactive portfolio and sports nutrition channel dominance.
Bone and joints ingredients comprise bioactive compounds including glucosamine, chondroitin, methylsulfonylmethane, and collagen peptides that support cartilage integrity, synovial fluid viscosity, and bone mineral density through oral administration at standardized dosages typically ranging from 500 to 1500 milligrams per serving. These ingredients serve nutraceutical manufacturers, pharmaceutical formulators, and functional food developers targeting musculoskeletal health maintenance and osteoarthritis symptom management. Collagen segments lead value capture due to cross-category expansion into beauty and sports nutrition, while glucosamine maintains volume dominance through decades of clinical validation and pharmacy channel presence. The supplements application category generates the fastest growth trajectory as direct-to-consumer brands bypass traditional retail intermediaries.
The FDA's New Dietary Ingredient notification requirements and cGMP enforcement for dietary supplements determine market access timelines and compliance costs for US-bound products. EFSA health claim assessments under the EU Nutrition and Health Claims Regulation constrain permissible marketing language for glucosamine and chondroitin products across member states. China's NMPA and SAMR oversight of health food registrations creates a dual-track system where blue-hat certification separates compliant from non-compliant entrants. Stakeholders must monitor evolving substantiation standards as regulators tighten the evidentiary threshold for structure-function claims.
Market Dynamics
Collagen peptide fermentation technology is compressing production timelines and eroding the cost advantage of traditional animal-extraction methods, forcing established glucosamine suppliers to defend margin positions through pharmaceutical-grade certification upgrades.
Growth Catalysts
- Aging demographics in developed economies:The United States and Japan exhibit expanding 65-plus populations with elevated osteoarthritis prevalence, driving pharmacy-channel demand for chondroitin and methylsulfonylmethane formulations.
- FDA's New Dietary Ingredient notification pathway:Structured pre-market consultation is accelerating compliant ingredient commercialization timelines for US-bound collagen and glucosamine entrants.
- Sports nutrition channel expansion:Fitness culture penetration across Germany and Australia is pulling hydrolyzed collagen into recovery-positioned powders and ready-to-drink formats.
Market Restraints
- Marine collagen supply concentration:Wild-caught fish skin and scale sourcing clusters in Southeast Asian coastal zones, exposing formulators to seasonal catch variability and sustainability audit failures.
- EFSA health claim substantiation thresholds:The EU Nutrition and Health Claims Regulation demands randomized controlled trial evidence for glucosamine structure-function statements, elevating marketing compliance costs.
- Plant-based collagen mimetic substitution:Silica-boosted and amino acid-fortified vegan alternatives are capturing ethical-consumer segments in Netherlands and UK retail channels.
Strategic Opportunities
- Direct-to-consumer subscription models:US-based wellness platforms are bypassing pharmacy intermediaries with personalized joint health stacks combining collagen, vitamin D3, and turmeric extracts.
- China's blue-hat health food registration:NMPA and SAMR dual-track certification creates first-mover advantages for foreign glucosamine suppliers achieving functional food status.
- Beauty-nutrition convergence:Oral collagen positioning for skin elasticity is opening pharmacy and prestige retail placement in France and South Korea beyond traditional joint health aisles.
Industry Challenges
- Pharmaceutical-grade certification timelines:USP and EP monograph compliance for chondroitin sulfate requires 18-to-24-month validation cycles, delaying contract manufacturing transitions.
- Fermentation scale-up talent scarcity:Microbial glucosamine production demands hybrid skill sets spanning industrial biotechnology and GMP facility management, constraining European capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone and Joints Ingredients Market |
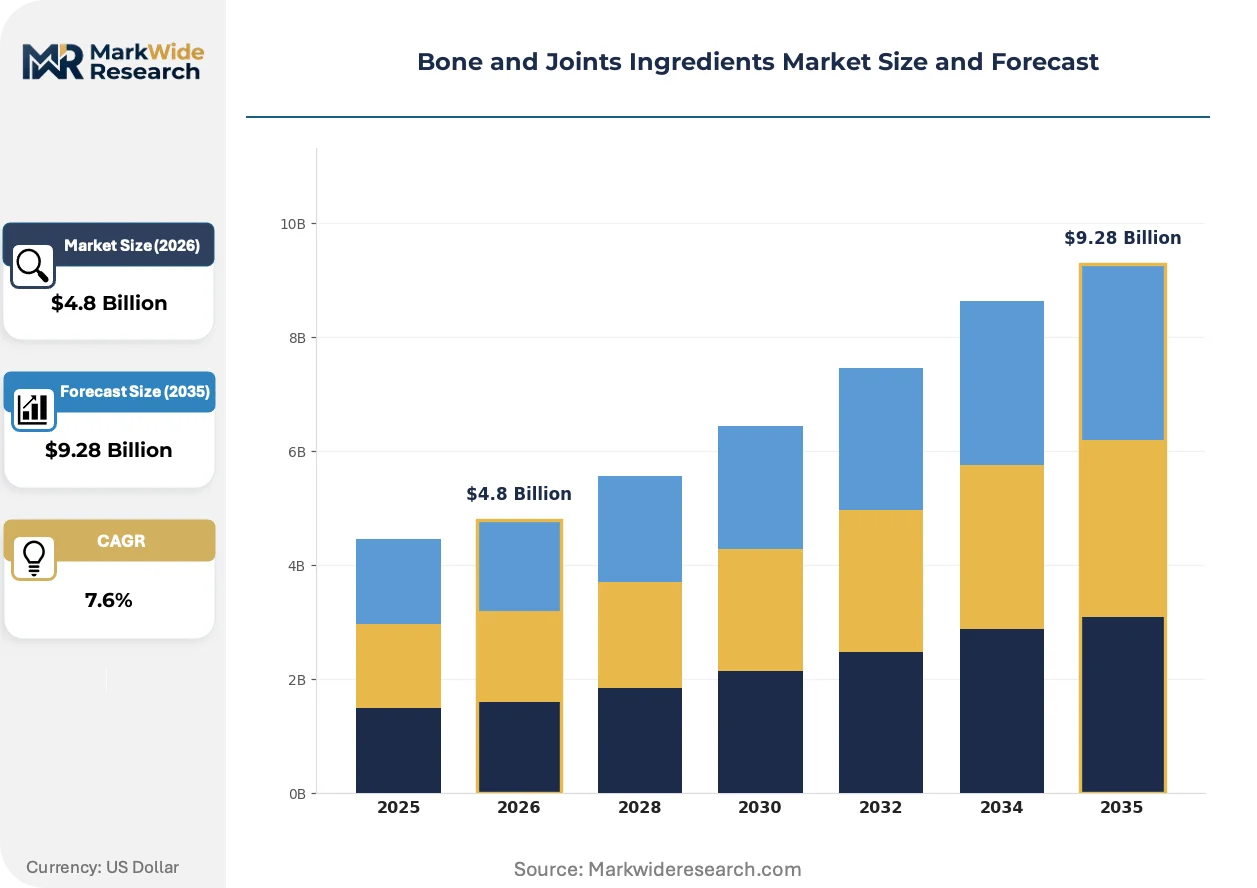
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucosamine, Chondroitin, MSM, Collagen Application: Supplements, Nutraceuticals, Functional Foods, Pharmaceuticals End User: Adults, Athletes, Elderly, Pets Formulation: Capsule, Powder, Liquid, Chewable |
| Companies Covered | DSM-Firmenich AG, BASF SE, Archer Daniels Midland Company, Glanbia plc, Cargill Incorporated, Gelita AG, Rousselot BV, Bioiberica S.A.U, Koninklijke DSM NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone and Joints Ingredients Market Strategic Shifts
Bioprocess engineering and regulatory data requirements are simultaneously compressing production economics and elevating evidentiary standards for market access, bifurcating competitive advantage between technology-led and compliance-led suppliers.
Precision fermentation of collagen peptides is automating the shift from slaughterhouse-derived inputs to recombinant microbial platforms. Nutraceutical contract manufacturers in Netherlands and Denmark are adopting these systems at pilot scale. The technology is automating batch-to-batch consistency improvements that animal-extraction methods cannot replicate, enabling pharmaceutical-grade output without supply chain traceability risks.
REACH registration requirements for novel collagen extraction solvents are tightening toxicological data obligations across EU member states. ECHA substance evaluation is extending dossier preparation timelines for hydrolyzed collagen producers using non-traditional enzymatic processes. German and French formulators are responding by consolidating supplier relationships with established registrants possessing complete Annex XV data packages.
Subscription-based replenishment models are displacing pharmacy-led repurchase cycles for bone and joint supplements. US direct-to-consumer brands are capturing recurring revenue through personalized dosage algorithms and auto-ship collagen formats. This behavioral shift is most visible in California and Texas metropolitan markets where telehealth-integrated wellness platforms bundle musculoskeletal screening with ingredient recommendations.
Bone and Joints Ingredients Market Segmentation
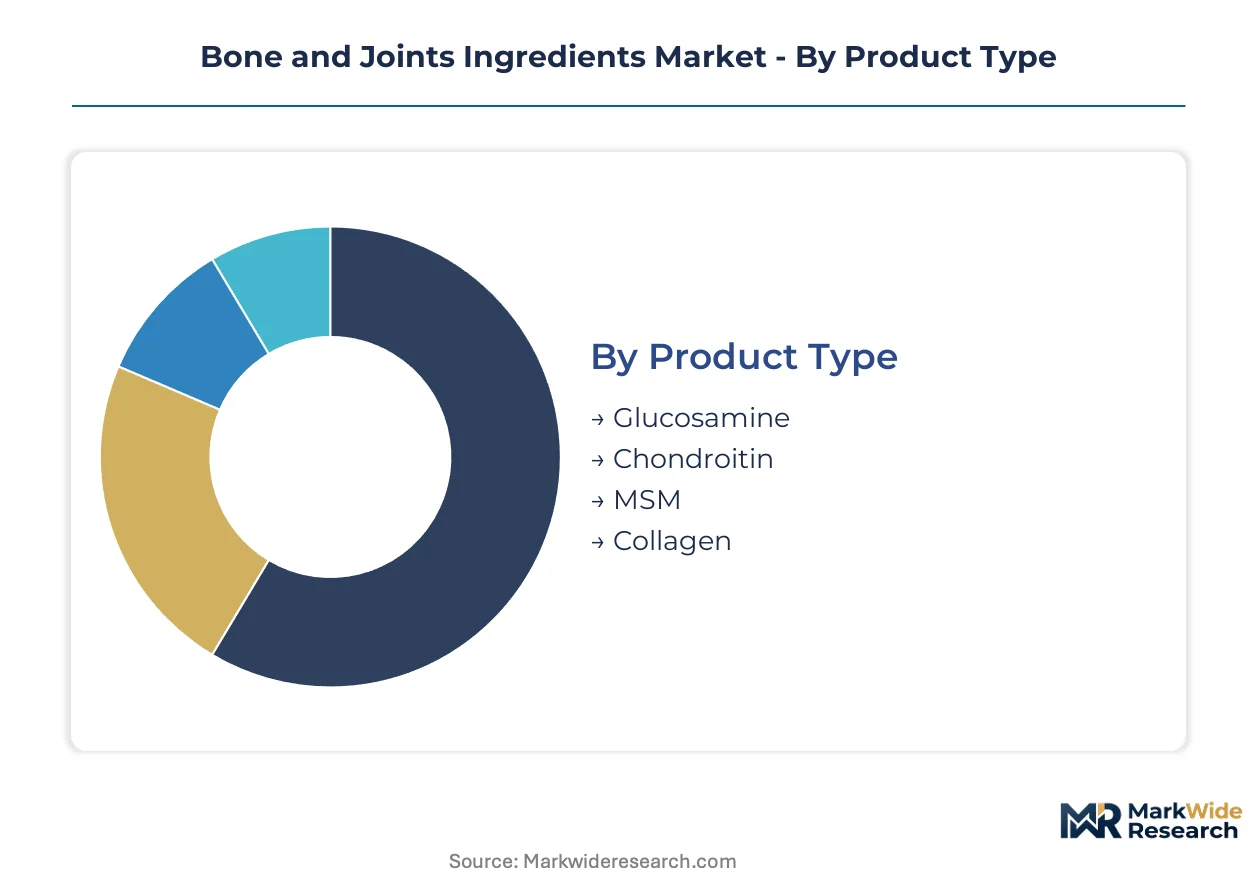
Ingredient specification and delivery format determine margin capture and regulatory pathway for bone and joint formulations. Manufacturers must align product architecture with end-user compliance preferences and channel requirements.
Product Type:
Structural composition defines bioavailability profiles and clinical substantiation requirements across the category.
- Collagen:Hydrolyzed peptide chains deliver type II collagen for cartilage matrix support. Sports nutrition brands in Germany and Australia are pulling hydrolyzed collagen into recovery-positioned powders, driven by fitness culture penetration and cross-category beauty positioning.
- Glucosamine:Amino sugar derived from shellfish or fermentation platforms supports glycosaminoglycan synthesis. Pharmacy-channel demand concentrates in the United States and Japan where aging demographics elevate osteoarthritis management protocols.
- Chondroitin:Sulfated glycosaminoglycan maintains synovial fluid viscosity and cartilage elasticity. BASF SE anchors synthetic production capacity at Ludwigshafen to secure pharmaceutical-grade supply chains.
- MSM:Organic sulfur compound methylsulfonylmethane addresses inflammation pathways and connective tissue repair. Direct-to-consumer brands combine MSM with turmeric extracts in personalized joint health stacks.
Collagen leads on scale; MSM leads on momentum.
Application:
Regulatory classification and distribution channel determine formulation investment and claim substantiation burden.
- Supplements:Dietary supplement formats operate under FDA NDI notification and cGMP enforcement, accelerating compliant commercialization timelines for US-bound entrants.
- Pharmaceuticals:Prescription-grade formulations require USP and EP monograph compliance with 18-to-24-month validation cycles, delaying contract manufacturing transitions.
- Nutraceuticals:Functional food positioning demands EFSA health claim assessments under EU Nutrition and Health Claims Regulation, elevating marketing compliance costs.
- Functional Foods:Fortified beverage and bar formats target China's blue-hat health food registration, creating first-mover advantages for foreign suppliers achieving functional food status.
Supplements dominate volume; pharmaceuticals command premium pricing tiers.
End User:
Demographic targeting shapes dosage architecture, packaging design, and channel placement strategy.
- Adults:General wellness consumers seeking preventive musculoskeletal maintenance drive subscription-based replenishment models through telehealth-integrated platforms.
- Elderly:Osteoarthritis symptom management concentrates pharmacy-channel repurchase cycles in the United States and Japan where 65-plus population expansion elevates demand.
- Athletes:Recovery and injury prevention positioning pulls collagen into ready-to-drink formats across metropolitan markets in California and Texas.
- Pets:Companion animal joint health represents emerging category expansion, with veterinary channel formulations mirroring human supplement architectures.
Elderly users anchor pharmacy revenue; athletes drive format innovation.
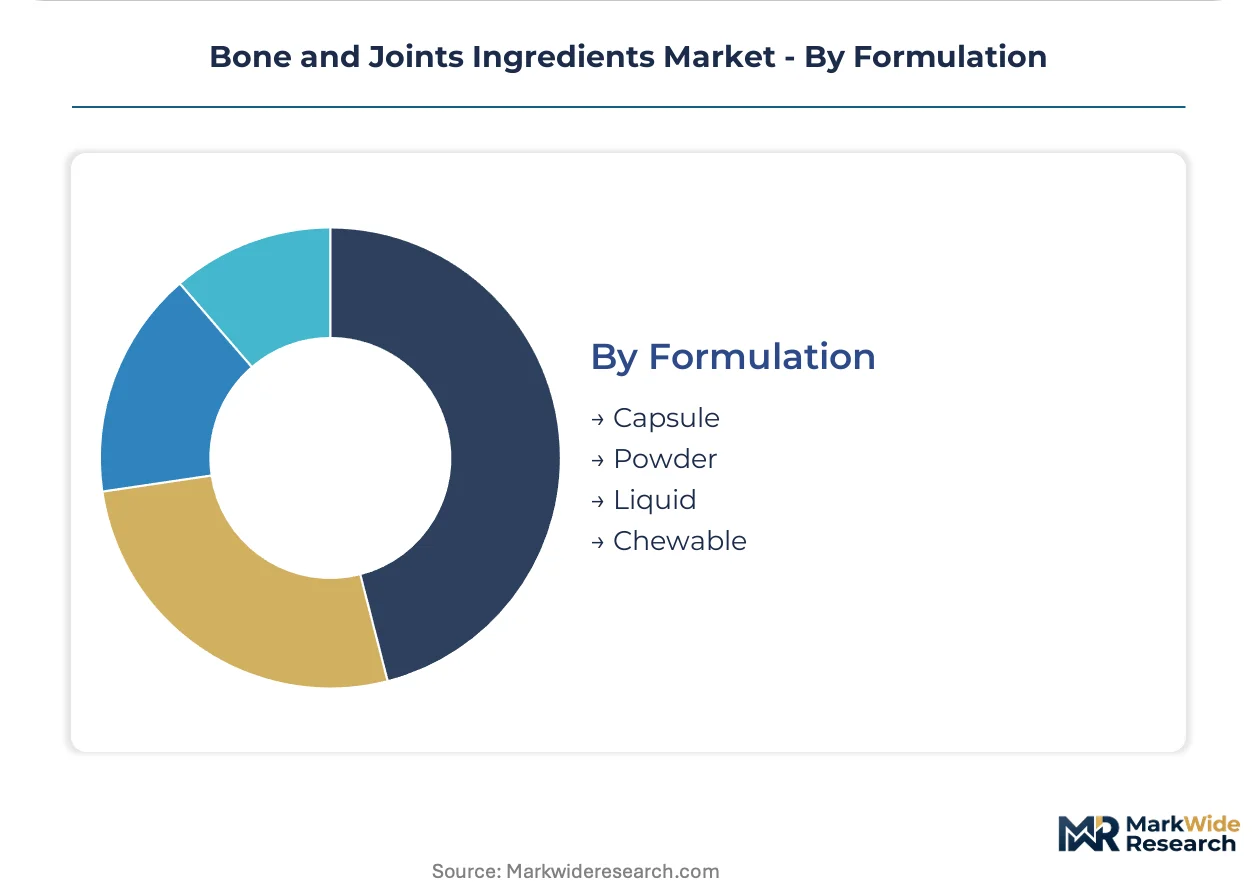
Formulation:
Delivery mechanism determines manufacturing capital requirements, stability testing protocols, and consumer compliance rates.
- Powder:Bulk hydrolyzed collagen enables sports nutrition stacking and personalized dosing, favored by direct-to-consumer subscription platforms.
- Capsule:Standardized dosing and portability sustain pharmacy-channel dominance for glucosamine and chondroitin combinations.
- Liquid:Ready-to-drink formats target convenience-seeking athletes and elderly users with swallowing difficulties.
- Chewable:Palatability-focused formats address pet compliance and pediatric-adjacent adult preferences in European retail channels.
Capsules maintain channel share; powders are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers migrate toward jurisdictions with streamlined health claim pathways and lower certification costs. The United States and European Union maintain stringent substantiation standards that elevate compliance investments, while China and Southeast Asian markets offer accelerated registration timelines for functional food positioning.
United States
Aging demographics and fitness culture convergence drive pharmacy and direct-to-consumer channel expansion for collagen and glucosamine formulations. FDA's New Dietary Ingredient notification pathway and cGMP enforcement determine market access timelines for domestic and foreign entrants. California and Texas metropolitan markets host telehealth-integrated wellness platforms bundling musculoskeletal screening with personalized joint health recommendations.
Germany
Sports nutrition channel penetration pulls hydrolyzed collagen into recovery-positioned powders across metropolitan fitness markets. EFSA health claim assessments under EU Nutrition and Health Claims Regulation constrain permissible marketing language for glucosamine products, elevating compliance costs. BASF SE anchors synthetic chondroitin sulfate capacity at Ludwigshafen, securing pharmaceutical-grade supply chains for European formulators.
China
Blue-hat health food registration under NMPA and SAMR oversight creates first-mover advantages for foreign suppliers achieving functional food status. Dual-track certification separates compliant from non-compliant entrants in retail and pharmacy channels. Yangtze River Delta and Pearl River Delta industrial clusters concentrate contract manufacturing capacity for both domestic consumption and export-oriented production.
Japan
Expanding 65-plus population elevates osteoarthritis management protocols and pharmacy-channel repurchase cycles for chondroitin and methylsulfonylmethane formulations. METI and PMDA oversight maintains stringent quality standards for imported and domestically produced ingredients. Kanto and Kansai regions concentrate nutraceutical formulation facilities serving aging consumer segments.
Netherlands
Plant-based collagen mimetic substitution captures ethical-consumer segments in retail channels, pressuring traditional animal-extracted ingredient positioning. REACH registration requirements for novel collagen extraction solvents tighten toxicological data obligations under ECHA substance evaluation. Nutraceutical contract manufacturers in Randstad and Brabant regions adopt precision fermentation systems at pilot scale.
Bone and Joints Ingredients Market Competitive Environment
European producers anchor the pharmaceutical-grade tier through synthetic and fermentation-derived platforms; Asian specialists hold cost-optimized extraction capacity. The vendor base stratifies across three tiers: integrated chemical conglomerates with multi-ingredient portfolios, dedicated collagen peptide houses with beauty-nutrition crossover positioning, and regional fermentation specialists serving contract manufacturing demand. Competitive moves concentrate on pharmaceutical-grade certification upgrades and precision fermentation technology licensing to defend margin positions against eroding animal-extraction economics.
Within the integrated chemical tier, DSM-Firmenich AG and BASF SE exemplify European conglomerates leveraging fermentation and synthetic platforms to secure supply chain control. Glanbia plc occupies a position bridging dairy-derived bioactives and sports nutrition channel dominance. These three entities represent divergent strategic archetypes: biotechnology-led pharmaceutical-grade positioning, petrochemical-rooted synthetic capacity, and nutrition-specialized vertical integration into upstream dairy processing.
| Leading Market Players |
|---|
| DSM-Firmenich AG |
| BASF SE |
| Archer Daniels Midland Company |
| Glanbia plc |
| Cargill Incorporated |
| Gelita AG |
| Rousselot BV |
| Bioiberica S.A.U |
| Koninklijke DSM NV |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up collagen peptide specialists have consolidated European extraction capacity, tightening pricing discipline while funneling margin capture toward pharmaceutical-grade certification tiers and away from commodity animal-derived inputs.
Pricing Analysis
Distributor margin layers compress as direct-to-consumer platforms disintermediate pharmacy intermediaries in the United States and Germany. Pricing stratifies across pharmaceutical-grade, food-grade, and feed-grade tiers, with USP and EP monograph compliance commanding substantial premia over uncertified alternatives. Cost compression in marine collagen runs through Southeast Asian wild-catch supply variability and sustainability audit failures. Institutional buyers in pharmaceutical formulation remain least price-sensitive, while sports nutrition brands exhibit highest elasticity to peptide yield specifications.
Supply Chain Analysis
China's blue-hat health food registration and domestic-content preferences for functional food manufacturing are reshaping sourcing patterns for foreign glucosamine suppliers. Raw material extraction concentrates in Indonesia and Vietnam for marine collagen, the Netherlands and Denmark for precision fermentation platforms, and Germany for synthetic chondroitin sulfate. Production draws from shellfish harvesting, recombinant microbial biomass, and petrochemical feedstocks. Single-source vulnerability clusters in Southeast Asian coastal zones expose formulators to seasonal catch disruption. Distribution runs through nutraceutical contract manufacturers, pharmacy wholesalers, and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bone and joints ingredients market reads as a late-cycle quality story, with demand shifting decisively toward pharmaceutical-grade specifications and fermentation-derived provenance as animal-extraction economics erode.
For Market Incumbents: Extend pharmaceutical-grade certification coverage across glucosamine and chondroitin portfolios to defend margin positions against precision fermentation substitution. BASF SE and DSM-Firmenich AG should deepen backward integration into recombinant microbial platforms while locking long-term supply agreements with direct-to-consumer wellness platforms in California and Texas metropolitan markets.
For New Entrants and Emerging Players: Begin with white-space targeting in China's blue-hat functional food registration pathway, where foreign first-movers capture retail placement advantages before domestic competition intensifies. Plant-based collagen mimetic formulations for ethical-consumer segments in the Netherlands and United Kingdom offer the most penetrable entry vector, with silica-boosted and amino acid-fortified positioning as the optimal go-to-market angle.
For Investors and Strategic Acquirers: Nutraceutical contract manufacturers with pilot-scale precision fermentation capabilities are the most active acquirer targets in this space, as capacity scarcity constrains European expansion. The acquisition archetype centers on Netherlands-based and Denmark-based facilities with hybrid industrial biotechnology and GMP facility management talent pools. Watch for NMPA and SAMR accelerated registration timelines as the inflection signal indicating China demand pull-through.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Recombinant microbial platforms displace animal-extraction methods, securing pharmaceutical-grade output without traceability risks. |
| Pharmaceutical-Grade Certification Investment | USP and EP monograph compliance creates 18-to-24-month validation barriers that entrench incumbent positioning. |
| Direct-to-Consumer Channel Expansion | Subscription-based replenishment models in California and Texas bypass pharmacy intermediaries and capture recurring revenue. |
| Blue-Hat Registration Achievement | NMPA and SAMR functional food status separates compliant from non-compliant entrants in China's retail channels. |
| Beauty-Nutrition Crossover Positioning | Oral collagen for skin elasticity opens pharmacy and prestige retail placement in France and South Korea beyond joint health aisles. |
Study Parameters
Coverage spans the United States, Germany, China, Japan, and the Netherlands, with primary inputs from each market combined with secondary validation across regulatory filings and trade databases. Interviews with nutraceutical contract manufacturing executives, pharmaceutical formulation procurement leads, regulatory affairs specialists at FDA and EFSA, and sports nutrition brand managers informed demand-side assumptions. Secondary sources include FDA New Dietary Ingredient notifications, EFSA health claim assessments, NMPA blue-hat registration databases, customs and trade flow data, and SEC filings from listed ingredient suppliers. Bottom-up volume modeling and top-down value triangulation anchored market size estimates.
Granularity extends to ingredient type, application category, end-user demographic, and formulation format, with geographic regulatory clusters modeled separately. CAGRs were derived from regression analysis of historical volume trajectories and projected demand elasticities across aging demographic curves and fitness culture penetration rates. Forecast inputs incorporated EFSA substantiation threshold evolution, precision fermentation technology diffusion curves, and direct-to-consumer channel share assumptions.
Several conditions sit outside the modeled scope, including unforeseen regulatory reclassifications of collagen peptides as novel foods, abrupt marine ecosystem disruptions affecting Southeast Asian supply, and macroeconomic shocks altering consumer discretionary spending on preventive supplements. Forecasts reflect documented assumptions about technology adoption timelines and channel migration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Chitosan Supplements Market
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Calcium Phosphate Market
Biomaterials
Chitosan Oligosaccharides Market
Biomaterials
North America Chitosan Market
Biomaterials
Global Medical Engineered Materials Market
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Self-Healing Hydrogels Market
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
Hydrogel Market
Biomaterials
Scaffold Materials Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Europe Collagen Market