
 Chitosan Market | 2026-2036
Chitosan Market Size, Share, and Industry Trends Forecast 2026-2036
Chitosan Market Intelligence
Direct sales channels between Asian chitosan producers and European pharmaceutical formulators is rewriting procurement geography for high-purity grades. Primex ehf leverages its Icelandic marine sourcing to sustain premium positioning in EU biomedical supply chains. KitoZyme SA anchors its competitive stance through enzymatic deacetylation technology that meets EMA excipient standards. Golden-Shell Pharmaceutical Co. Ltd. dominates bulk powder exports to food preservatives manufacturers across Southeast Asia.
Chitosan is a linear polysaccharide derived from chitin deacetylation, typically containing 70-95% deacetylated glucosamine units with molecular weights ranging from 50 to 2,000 kDa depending on processing conditions. Manufacturers produce it through chemical or enzymatic treatment of crustacean shells for applications spanning flocculation, film formation, and controlled drug release. Chitosan powder leads volume shipments due to its versatility across water treatment and agricultural additive formulations, while biomedical applications command the highest purity premiums and fastest value growth. Food preservation demand for chitosan flakes is maturing in established Asian markets, whereas chitosan granules for controlled-release agricultural formulations represent an emerging margin pool.
FDA GRAS notifications and EMA excipient monographs shape pharmaceutical-grade chitosan specifications, while REACH registration requirements govern chemical imports into European Union manufacturing facilities. EPA effluent guidelines in the United States indirectly boost chitosan demand as municipalities adopt bio-based flocculants for heavy metal removal. Stakeholders must monitor regulatory divergence between FDA and EMA purity standards when designing single-source manufacturing strategies.
Market Dynamics
Enzymatic deacetylation is displacing chemical processing as the dominant production pathway for pharmaceutical-grade material, compressing batch-to-batch variability while elevating EMA compliance rates among European formulators.
Growth Catalysts
- EU Green Deal biopolymer mandates:Brussels-based procurement directives now specify bio-based flocculants for municipal water treatment, redirecting volume toward crustacean-derived alternatives.
- Japan METI biopolymer initiatives:Domestic production subsidies for high-purity grades are capturing value that previously flowed to Chinese bulk exporters.
- Controlled-release agricultural formulations:Granular chitosan coatings for nitrogen stabilization are penetrating specialty fertilizer portfolios across Southeast Asian plantation agriculture.
Market Restraints
- Shellstock supply concentration:Antarctic krill and North Atlantic shrimp processing geography locks raw material access to Iceland, Norway, and Argentina landing zones.
- Seasonal crustacean harvest cycles:Fishing quota fluctuations in the Barents Sea and Gulf of Maine create six-month input price volatility windows.
- Protein-based flocculant substitution:Cationic polyacrylamide retains cost advantage in bulk industrial water treatment despite inferior biodegradability profiles.
Strategic Opportunities
- Brazilian aquaculture expansion:Farmed shrimp waste streams in Ceará and Rio Grande do Norte remain unexploited for chitin extraction despite processing infrastructure proximity.
- EMA excipient monograph harmonization:Pending updates to pharmaceutical purity standards create first-mover advantage for producers pre-certifying enzymatic grades.
- Direct-to-formulator digital platforms:Asian producers are bypassing European distributors to capture premium margins in wound care and drug delivery segments.
Industry Challenges
- Enzymatic process engineering talent scarcity:Biocatalysis PhD pipelines in Vietnam and Indonesia lag behind commercial scale-up requirements.
- Dual FDA-EMA certification timelines:Divergent heavy metal and endotoxin testing protocols force parallel validation studies for single-source strategies.
- Legacy chemical deacetylation asset stranding:Caustic soda-based plants face retrofit costs exceeding greenfield enzymatic facility investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chitosan Market |
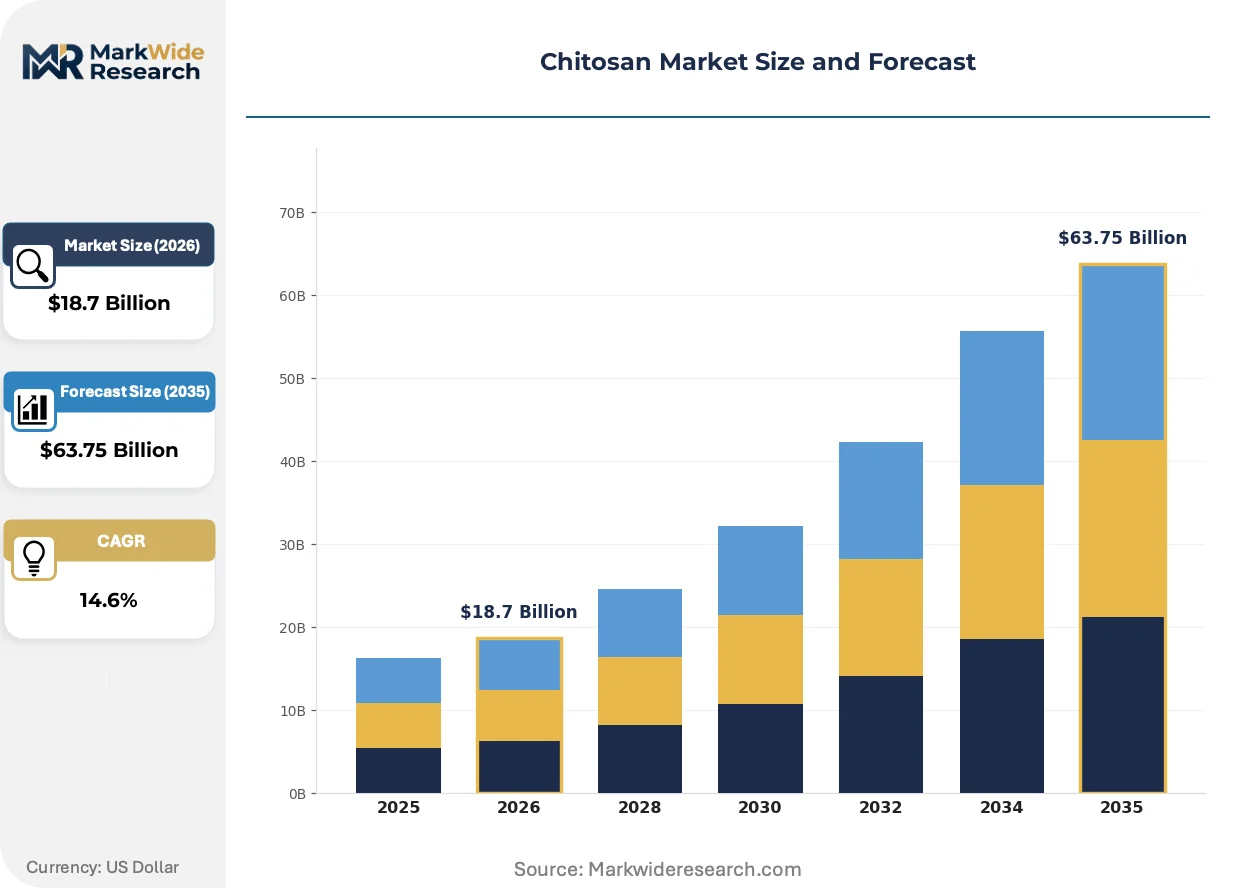
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chitosan Flakes, Chitosan Powder, Chitosan Granules, Chitosan Pellets Application: Food Preservation, Water Treatment, Agricultural Additive, Biomedical End User: Food Industry, Pharmaceuticals, Cosmetics, Agriculture Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Advanced Biopolymers AS, Meron Group, Primex ehf, Mahtani Chitosan Private Limited, FMC Corporation, Heppe Medical Chitosan GmbH, Golden-Shell Pharmaceutical Co. Ltd., Panvo Organics Pvt. Ltd., KitoZyme SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chitosan Market Strategic Shifts & Innovations
Production technology, regulatory stringency, and procurement geography are simultaneously rewiring competitive position in chitosan supply chains. These forces favor specialized producers with marine sourcing control and enzymatic capability.
Enzymatic deacetylation using chitin deacetylase enzymes is digitizing quality control through real-time molecular weight monitoring during batch processing. Pharmaceutical formulators in Germany and Switzerland are specifying enzyme-derived grades exclusively. This technology is digitizing specification compliance, compressing certificate-of-analysis turnaround from weeks to hours.
REACH registration requirements for polymer imports are tightening purity documentation for non-EU producers. ECHA substance evaluation protocols now demand batch-level heavy metal traceability. Biomedical-grade shipments into Rotterdam and Hamburg are responding with blockchain-anchored supply chain verification systems.
Long-term offtake agreements are replacing spot market purchases among European water treatment utilities. Municipal procurement departments in Denmark and the Netherlands are consolidating annual volume into single-source contracts with Icelandic and Norwegian producers. This pattern concentrates supplier relationships and compresses price negotiation frequency.
Chitosan Market Segmentation
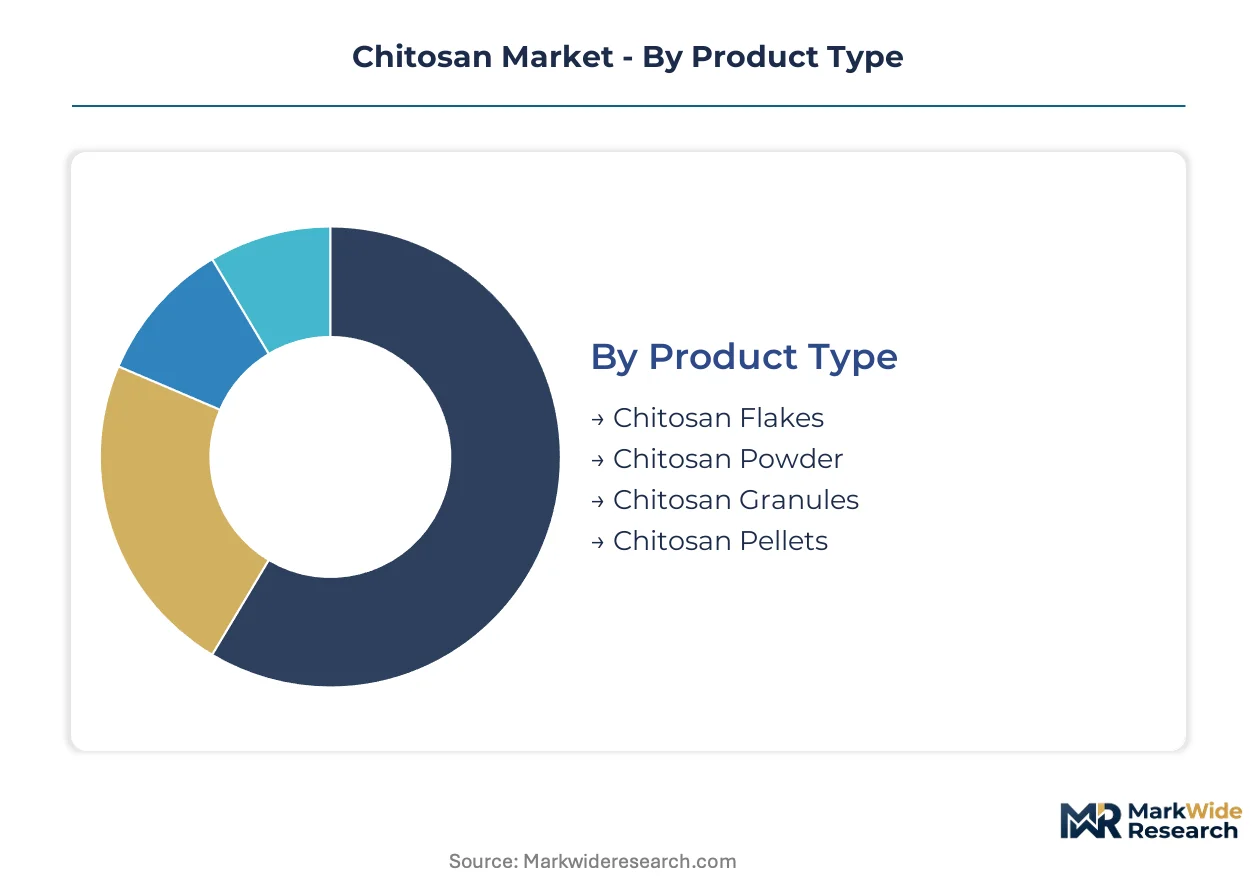
Chitosan specifications diverge sharply across end-use requirements, with pharmaceutical purity standards commanding tenfold price premiums over industrial grades. Procurement channels and physical form factors further stratify supplier relationships and margin capture.
Product Type:
The use-case spectrum spans bulk industrial flocculation to precision drug delivery, with physical form determining handling economics and dissolution kinetics.
- Chitosan Powder:Fine particulate morphology with molecular weights tunable from 50 to 2,000 kDa enables rapid hydration in aqueous systems. Water treatment utilities in Denmark and the Netherlands specify powder grades for municipal heavy metal removal, though seasonal shellstock supply from Iceland and Norway creates six-month price volatility windows.
- Chitosan Flakes:Intermediate surface-area-to-volume ratio supports controlled dissolution in acidic food matrices. Southeast Asian food preservatives manufacturers in Thailand and Vietnam anchor procurement around flake specifications, with demand maturing as regional seafood processing infrastructure saturates.
- Chitosan Granules:Dense agglomerated structure enables slow-release nitrogen stabilization in plantation agriculture. Cargill and Wilmar International trial granular coatings for oil palm and rubber applications across Indonesia and Malaysia.
- Chitosan Pellets:Compressed spherical form factors suit automated dosing in continuous-flow bioreactors. German pharmaceutical formulators specify pelletized excipients for tablet compression lines.
Established volume favors powder; emerging adoption favors granules.
Application:
Cost tiers separate commodity flocculants from certified biomedical grades, with regulatory burden determining margin structure.
- Biomedical:EMA excipient monographs and FDA GRAS notifications mandate endotoxin limits below 0.25 EU/g and heavy metal traceability to batch level. Swiss and German wound care formulators specify enzymatic-derived grades exclusively, with blockchain-anchored supply chain verification now standard for Rotterdam and Hamburg shipments.
- Water Treatment:EU Green Deal biopolymer mandates redirect municipal procurement toward crustacean-derived alternatives. Danish utilities consolidate annual volume into single-source contracts with Icelandic producers, compressing price negotiation frequency.
- Food Preservation:Antimicrobial film coatings for fresh seafood and meat products dominate Japanese and Korean applications. FSSAI and MFDS standards converge on deacetylation degree minimums of 85%.
- Agricultural Additive:Controlled-release formulations for nitrogen stabilization penetrate Southeast Asian plantation agriculture. Granular chitosan coatings command specialty fertilizer premiums in Indonesia and Malaysia.
Regulatory intensity concentrates margin in biomedical; policy tailwinds accelerate water treatment.
End User:
Customer type dictates specification stringency, with pharmaceutical and cosmetic buyers enforcing certificate-of-analysis protocols that industrial purchasers waive.
- Pharmaceuticals:EMA and FDA dual certification timelines force parallel validation studies for single-source manufacturing strategies. German, Swiss, and Danish formulators drive enzymatic deacetylation adoption.
- Food Industry:GRAS self-affirmation pathways in the United States contrast with EFSA novel food authorization requirements in Europe. Thai and Vietnamese seafood processors dominate flake consumption.
- Agriculture:Plantation operators in Indonesia and Malaysia trial granular formulations for oil palm productivity enhancement. Yara International and Sime Darby evaluate long-term offtake structures.
- Cosmetics:Moisturizing and antimicrobial claims in Korean and Japanese skincare formulations specify low-molecular-weight hydrolysates. Amorepacific and Shiseido qualify suppliers against JIS and MFDS cosmetic ingredient standards.
Certification burden stratifies pricing most sharply between pharmaceuticals and agriculture.
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, with direct relationships displacing intermediaries in premium segments.
- Direct Sales:Asian producers bypass European distributors to capture wound care and drug delivery margins. Primex ehf leverages Icelandic marine sourcing for premium positioning in EU biomedical supply chains.
- Distributors:Regional chemical distributors aggregate small-lot purchases for water treatment and agricultural buyers. Brenntag and Univar Solutions dominate European chitosan logistics.
- Online:Alibaba and specialty chemical marketplaces serve research-grade and pilot-scale buyers. Certificate-of-analysis documentation varies widely.
- Retail:Limited to nutraceutical capsules and cosmetic finished goods. Amazon and iHerb channels capture consumer-direct volumes.
Relationship depth favors direct sales; transaction efficiency favors distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI-backed biopolymer initiatives in Japan anchor the dominant geography for high-purity chitosan production, while regulatory divergence between FDA and EMA standards shapes procurement patterns across North America and Europe.
Japan
Domestic production subsidies for pharmaceutical-grade material capture value previously flowing to Chinese bulk exporters. METI biopolymer programs prioritize enzymatic deacetylation capacity for wound healing applications. Tokyo-Osaka pharmaceutical clusters drive specification stringency for biomedical-grade imports.
Germany
Swiss and German formulators specify enzyme-derived grades exclusively for tablet compression and drug delivery systems. EMA excipient monographs mandate endotoxin limits below 0.25 EU/g with batch-level heavy metal traceability. Hamburg-Rotterdam logistics corridors anchor blockchain-verified supply chain verification for biomedical shipments.
United States
EPA effluent guidelines indirectly boost demand as municipalities adopt bio-based flocculants for heavy metal removal. FDA GRAS notifications shape food preservation specifications, contrasting with EFSA novel food pathways. Massachusetts and New Jersey pharmaceutical clusters enforce dual certification timelines for single-source strategies.
Iceland
Antarctic krill and North Atlantic shrimp processing geography locks premium raw material access to Reykjanes Peninsula landing zones. Primex ehf leverages marine sourcing control for EU biomedical supply chain positioning. Seasonal fishing quota fluctuations in adjacent Norwegian waters create six-month input price volatility windows.
Brazil
Farmed shrimp waste streams in Ceará and Rio Grande do Norte remain unexploited for chitin extraction despite processing infrastructure proximity. ANVISA pharmaceutical regulations lag EMA stringency, creating export-focused production incentives. Northeastern aquaculture expansion offers backward integration opportunities for enzymatic facility investment.
Chitosan Market Key Industry Players
Marine-sourced specialists and enzymatic technology holders split the market between premium biomedical grades and bulk industrial volumes. The vendor base concentrates around crustacean processing geography in Iceland, Norway, and Argentina, with Asian producers dominating powder exports for water treatment and agricultural applications. Three archetypes define competitive position: vertically integrated marine processors, enzymatic technology licensors, and regional bulk distributors. Capacity expansion and direct-to-formulator digital platforms represent the dominant competitive moves compressing distributor margins.
Among marine-sourced processors, Primex ehf and Golden-Shell Pharmaceutical Co. Ltd. exemplify geographic anchoring strategies, while KitoZyme SA occupies a position within the enzymatic technology tier. These three entities represent the spectrum from raw material control through processing technology to regional volume leadership, with each archetype capturing margin at different specification thresholds across biomedical, food preservation, and agricultural end uses.
| Leading Market Players |
|---|
| Advanced Biopolymers AS |
| Meron Group |
| Primex ehf |
| Mahtani Chitosan Private Limited |
| FMC Corporation |
| Heppe Medical Chitosan GmbH |
| Golden-Shell Pharmaceutical Co. Ltd. |
| Panvo Organics Pvt. Ltd. |
| KitoZyme SA |
| Others |
Cost & Logistics Intelligence
Reykjanes Peninsula processing clusters anchor premium biomedical-grade supply, with Antarctic krill landing volumes directly determining downstream pricing power for EMA-certified shipments into Rotterdam and Hamburg. Seasonal quota fluctuations in adjacent Norwegian waters compress margin windows for producers lacking long-term shellstock contracts.
Pricing Analysis
Price spreads between Icelandic enzymatic grades and Chinese chemically processed powder now exceed threefold at the Rotterdam port gate. Pricing stratifies across pharmaceutical excipient, food-grade flake, and industrial powder tiers, with certification burden and molecular weight precision as primary differentiation drivers. Cost compression in bulk water treatment grades intensifies as cationic polyacrylamide substitutes erode volume commitments. Municipal procurement departments demonstrate highest price sensitivity, while Swiss and German pharmaceutical formulators absorb premiums for blockchain-verified endotoxin documentation.
Supply Chain Analysis
Contract manufacturing concentrates with Primex ehf in Iceland, KitoZyme SA in Belgium, and Golden-Shell Pharmaceutical in Zhejiang Province holding enzymatic capacity. Raw material sourcing draws from Antarctic krill, North Atlantic shrimp shellstock, and emerging Brazilian farmed shrimp waste streams. Single-source vulnerability concentrates in Barents Sea fishing quota allocations. Distribution runs through direct sales channels for biomedical grades and Brenntag-Univar regional networks for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic deacetylation biocatalysis expertise functions as the binding constraint on pharmaceutical-grade expansion, with fewer than twelve facilities globally capable of EMA-compliant batch certification. This scarcity dynamic rewards early movers in talent acquisition and process patenting.
For Market Incumbents: Harden supply security through backward integration into shellstock processing or captive long-term offtake agreements with Icelandic and Norwegian landing operations. Invest in parallel FDA-EMA validation infrastructure to preempt regulatory divergence risks. Threat substitution from protein-based flocculants demands premium positioning reinforcement in biomedical segments least vulnerable to cost-based switching. For New Entrants and Emerging Players: Pursue unexploited Brazilian aquaculture waste streams in Ceará and Rio Grande do Norte for greenfield enzymatic facility siting. Plantation agriculture granular formulations in Indonesia and Malaysia offer the most penetrable demand pool with limited incumbent specialization. Go-to-market execution should anchor on direct digital platform relationships with Southeast Asian fertilizer blenders bypassing distributor markups. For Investors and Strategic Acquirers: Long-term, this sits as a specialty biopolymer infrastructure play because regulatory moats around pharmaceutical-grade certification compound returns to enzymatic technology holders. Acquisition focus should target marine-sourced processors with existing EMA documentation and unexploited capacity expansion rights. Signal to monitor: METI subsidy expansion or contraction as predictor of Japanese domestic production substitution effects.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Capacity Expansion | Belgian and Icelandic producers capture EMA pre-certification advantages before monograph harmonization. |
| Backward Integration into Shellstock | Reykjanes Peninsula landing zone control secures input cost stability against Barents Sea quota volatility. |
| Blockchain Supply Chain Verification | Rotterdam and Hamburg pharmaceutical shipments now require batch-level heavy metal traceability documentation. |
| Direct-to-Formulator Digital Platform | Asian producers bypass Brenntag-Univar margins in wound care and drug delivery segments. |
| Brazilian Aquaculture Waste Stream Development | Ceará and Rio Grande do Norte shrimp processing proximity enables first-mover enzymatic facility economics. |
Research Approach
A spread of perspectives from enzymatic process engineers, pharmaceutical procurement managers at German and Swiss formulators, shellstock landing operators in Iceland and Norway, and EMA regulatory affairs specialists converged on the working assumptions. Primary field engagement combined with secondary validation against REACH registration databases, ECHA substance evaluation protocols, FDA GRAS notification filings, and Japanese METI biopolymer program disclosures. Bottom-up volume modeling from facility capacity declarations triangulated against top-down demand aggregation across water treatment utility procurement records.
Demand-supply balance dynamics shaped the analytical framework across the analysis window, with segmentation dimensions spanning physical form factor, deacetylation degree tier, end-use application intensity, and regional regulatory cluster. CAGRs derived from weighted least-squares fitting to historical trade flow data and projected capacity expansion timelines. Forecast inputs incorporated seasonal shellstock harvest cycles, enzymatic technology adoption curves, and municipal procurement contract renewal patterns.
Sensitivities concentrate around Barents Sea fishing quota revisions, EMA excipient monograph update timing, and METI subsidy program continuity. Forecasts reflect documented assumptions regarding technology diffusion rates and regulatory harmonization progress. Quarterly review of Rotterdam port pharmaceutical-grade import volumes, Icelandic landing zone quota allocations, and enzymatic facility patent filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Flowable Hemostats Market
Biomaterials
South America Collagen Market
Biomaterials
Biomimetic Materials Market
Biomaterials
Polysaccharide Hemostatic System Market
Biomaterials
North America Chitosan Market
Biomaterials
Chitosan-Based Biomaterials Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
Nerve Repair Biomaterials Market
Biomaterials
Bone Distractors Market
Biomaterials
Bone Substitutes Market
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
Europe Collagen Market
Biomaterials
Crocodile Peptide Market