
 Penicillin Intermediate Market | 2026-2036
Penicillin Intermediate Market Size, Share, and Industry Trends Forecast 2026-2036
Penicillin Intermediate Market Insights
Enzymatic biocatalysis is realigning traditional chemical synthesis routes for penicillin intermediates, compressing conversion costs and waste streams. Pfizer Inc. leverages captive fermentation infrastructure across North American sites to secure upstream supply of 6-aminopenicillanic acid. Aurobindo Pharma Ltd. anchors its intermediate strategy on backward integration into penicillin G potassium fermentation in Telangana. Centrient Pharmaceuticals specializes in enzymatic routes to side-chain precursors, differentiating its offering from acid-cleavage competitors.
Penicillin intermediates comprise semi-synthetic beta-lactam precursors—principally 6-APA, 7-ACA, and 7-ADCA—manufactured via fermentation-derived penicillin G or V followed by enzymatic or chemical deacylation, with purity thresholds typically exceeding 99% for pharmaceutical-grade material. These intermediates serve as the structural backbone for amoxicillin, ampicillin, and cephalexin production across human and veterinary medicine. Among product types, 6-aminopenicillanic acid dominates volume throughput owing to its centrality in oral penicillin manufacturing, while phenoxymethylpenicillin intermediates occupy narrower, higher-margin niches in European markets with specific formulary preferences. By application, antibiotics production absorbs the bulk of intermediate flows, though research laboratories represent the fastest-growing demand pocket as novel beta-lactamase inhibitor combinations advance through clinical pipelines.
FDA's Current Good Manufacturing Practice enforcement for active pharmaceutical ingredients, EMA's revised penicillin residue limits under veterinary regulation, and India's BIS certification requirements for bulk drug exports collectively elevate compliance costs for intermediate suppliers while restricting market access for uncertified producers. These regulatory layers favor manufacturers with validated quality management systems and documented supply chain traceability. Stakeholders must monitor evolving pharmacopoeial monograph revisions and antibiotic stewardship policies that could redirect intermediate demand toward narrower-spectrum derivatives.
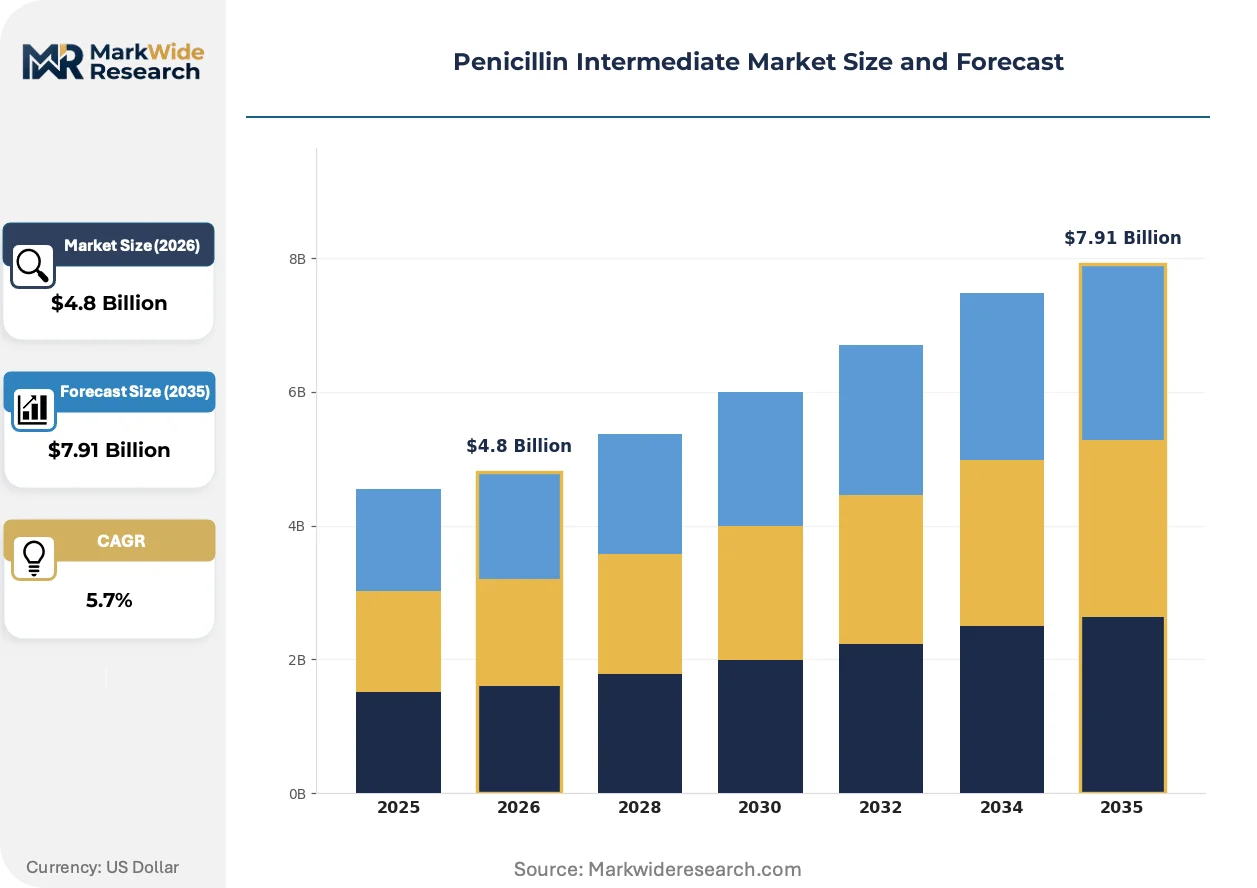
Market Dynamics
Enzymatic biocatalysis is compressing conversion costs and waste streams while FDA and EMA purity standards reshape supplier qualification protocols across the penicillin intermediate supply base.
Growth Catalysts
- Enzymatic Deacylation:Fermentation-derived penicillin G conversion via enzymatic routes cuts solvent use and environmental discharge compared to acid-cleavage methods.
- India's PLI Scheme:Production-linked incentives for bulk drug manufacturing accelerate backward integration into penicillin G potassium fermentation among domestic API producers.
- Beta-Lactamase Inhibitor Pipelines:Novel combination therapies advancing through clinical trials expand demand for high-purity 6-APA and 7-ACA derivatives in research laboratory settings.
Market Restraints
- Corn Steep Liquor Volatility:Fermentation media costs fluctuate with agricultural commodity cycles, squeezing margins for penicillin G producers without long-term supply contracts.
- Shandong Corridor Concentration:Overreliance on fermentation capacity in China's eastern provinces exposes buyers to regional environmental enforcement actions and production halts.
- EMA Veterinary Residue Limits:Revised penicillin residue thresholds under EU veterinary regulations restrict intermediate sourcing to certified suppliers with documented impurity profiles.
Strategic Opportunities
- Southeast Asia Expansion:Vietnam and Indonesia offer underexploited fermentation infrastructure and lower labor costs for greenfield penicillin intermediate facilities.
- Continuous Manufacturing:Integration of flow chemistry with enzymatic biocatalysis enables real-time quality monitoring and reduced batch-to-batch variability for pharmaceutical-grade material.
- Antibiotic Stewardship Tailwinds:Narrow-spectrum penicillin formulations gaining formulary preference in European markets expand addressable demand for phenoxymethylpenicillin intermediates.
Industry Challenges
- Fermentation Specialist Scarcity:Industrial microbiology and downstream processing expertise gaps constrain capacity expansion timelines for new market entrants.
- Multi-Pharmacopoeia Certification:Simultaneous compliance with USP, EP, and IP monographs extends validation timelines and raises documentation burdens for export-oriented suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Penicillin Intermediate Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 6-Aminopenicillanic Acid, Benzylpenicillin, Phenoxymethylpenicillin, Others Application: Pharmaceuticals, Antibiotics Production, Research Laboratories, Veterinary Medicine End User: Hospitals, Contract Manufacturing Organizations, Pharmaceutical Companies, Academic Institutions Distribution Channel: Online Sales, Direct Sales, Distributors, Retail Pharmacies |
| Companies Covered | Pfizer Inc., Aurobindo Pharma Ltd., Centrient Pharmaceuticals, GlaxoSmithKline plc, Sandoz, Cipla Ltd., Dr. Reddy's Laboratories, Sun Pharmaceutical Industries Ltd., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Penicillin Intermediate Market Trends and Innovations
Biocatalytic process intensification and regulatory harmonization pressures are reconfiguring how penicillin intermediates are manufactured, certified, and procured across human and veterinary medicine supply chains.
Immobilized enzyme technology is absorbing fixed-cost investments from traditional chemical synthesis infrastructure. Generic antibiotic manufacturers in India and China are retrofitting existing acid-cleavage plants with enzyme-based conversion systems. The structural consequence is a compression of capital recovery periods for fermentation-to-intermediate facilities as enzymatic routes achieve comparable yields at lower operating temperatures.
REACH registration requirements for chemical intermediates are tightening substance identity documentation and impurity disclosure obligations for European market access. Bulk drug exporters must now submit analytical data packages covering all penicillin derivative metabolites. Suppliers with validated quality management systems are capturing preferential qualification status while uncertified producers face exclusion from EMA-inspected supply chains.
Long-term offtake agreements are displacing spot-market purchasing for 6-APA and 7-ACA derivatives. Maharashtra's bulk drug clusters are negotiating multi-year supply contracts directly with formulation manufacturers, bypassing traditional distributor networks. This consolidation is most visible among veterinary antibiotic producers seeking price stability amid agricultural commodity volatility.
Penicillin Intermediate Market Segmentation
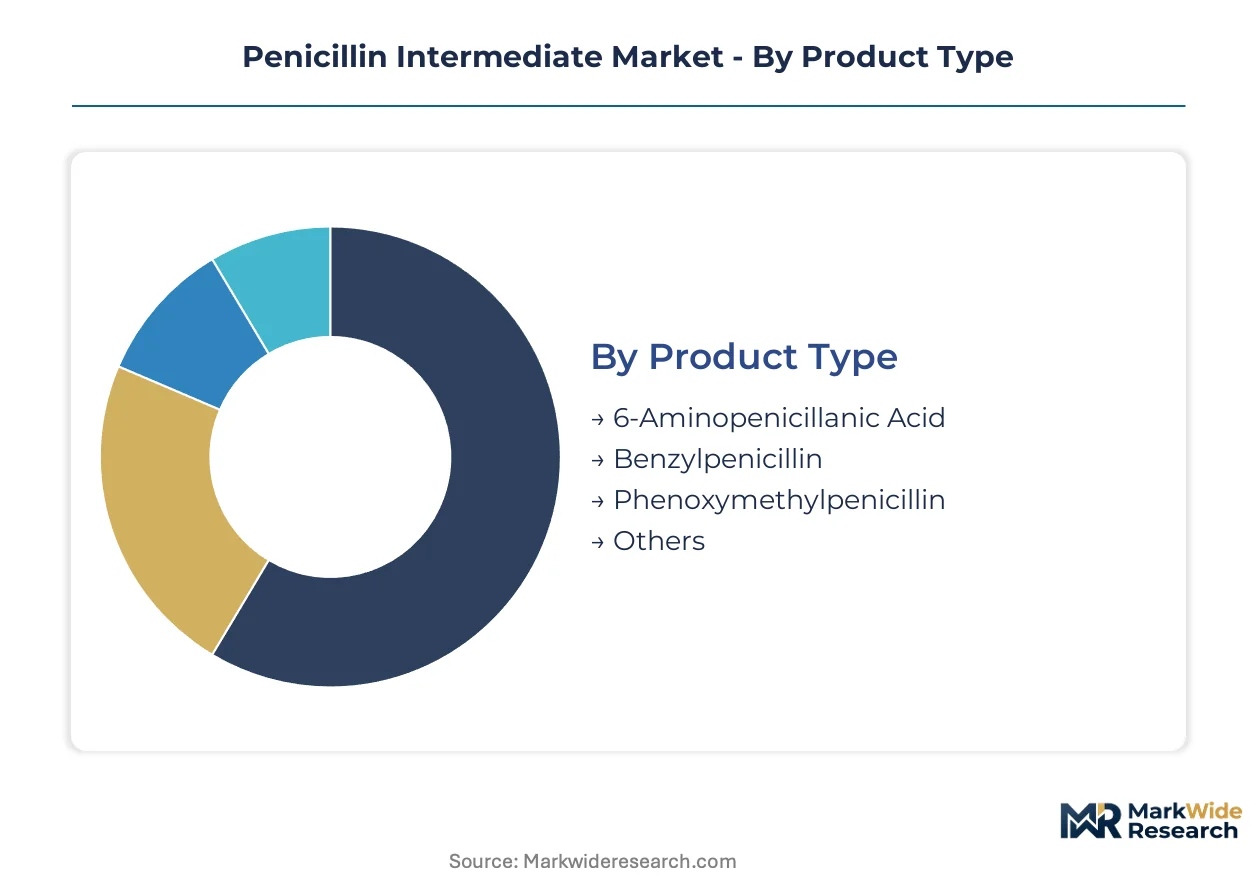
Penicillin intermediate procurement splits across four dimensions that determine regulatory burden, margin structure, and supply chain configuration. Certification requirements vary sharply by product grade and end-use destination.
Product Type:
FDA and EMA enforce distinct purity thresholds across intermediate grades, with pharmaceutical-grade material demanding documented impurity profiles that generic-grade product escapes.
- 6-Aminopenicillanic Acid:The core beta-lactam nucleus serves as precursor for amoxicillin and ampicillin synthesis via enzymatic deacylation of penicillin G. Maharashtra's bulk drug clusters absorb the majority of volume as Indian generic manufacturers pursue backward integration into fermentation.
- Benzylpenicillin:Natural penicillin G potassium salt undergoes direct conversion to 6-APA or enters parenteral formulation streams. Shandong Province's fermentation corridors concentrate production capacity, exposing buyers to regional environmental enforcement risks.
- Phenoxymethylpenicillin:Oral penicillin V derivative occupies narrower European formulary niches with higher margin profiles.
- Others:Includes 7-ACA and 7-ADCA cephalosporin precursors manufactured via chemical or enzymatic ring expansion.
Leading the category by volume: 6-Aminopenicillanic Acid. Growing fastest: Phenoxymethylpenicillin.
Application:
End-use destination dictates pharmacopoeial compliance tier and documentation depth for batch release.
- Pharmaceuticals:Human medicine formulations require USP, EP, and IP monograph compliance with full supply chain traceability.
- Antibiotics Production:Bulk active pharmaceutical ingredient manufacturing consumes the majority of intermediate throughput across oral and injectable penicillin categories.
- Research Laboratories:Novel beta-lactamase inhibitor combinations in clinical pipelines drive demand for high-purity 6-APA and 7-ACA derivatives with specialized analytical certificates.
- Veterinary Medicine:EMA residue limits restrict sourcing to certified suppliers with documented metabolite profiles for food animal applications.
Dominant volume share: Antibiotics Production. Steepest expansion trajectory: Research Laboratories.
End User:
Customer scale and integration depth determine procurement modality and contract structure.
- Pharmaceutical Companies:Integrated manufacturers like Pfizer leverage captive fermentation infrastructure for upstream 6-APA supply security.
- Contract Manufacturing Organizations:CDMOs serving multinational clients require multi-pharmacopoeia certification and validated quality management systems.
- Hospitals:Institutional procurement of compounded formulations represents a minor direct channel for intermediate offtake.
- Academic Institutions:Research universities source gram-scale quantities for medicinal chemistry programs with reduced documentation requirements.
Largest procurement scale: Pharmaceutical Companies. Fastest contract growth: Contract Manufacturing Organizations.
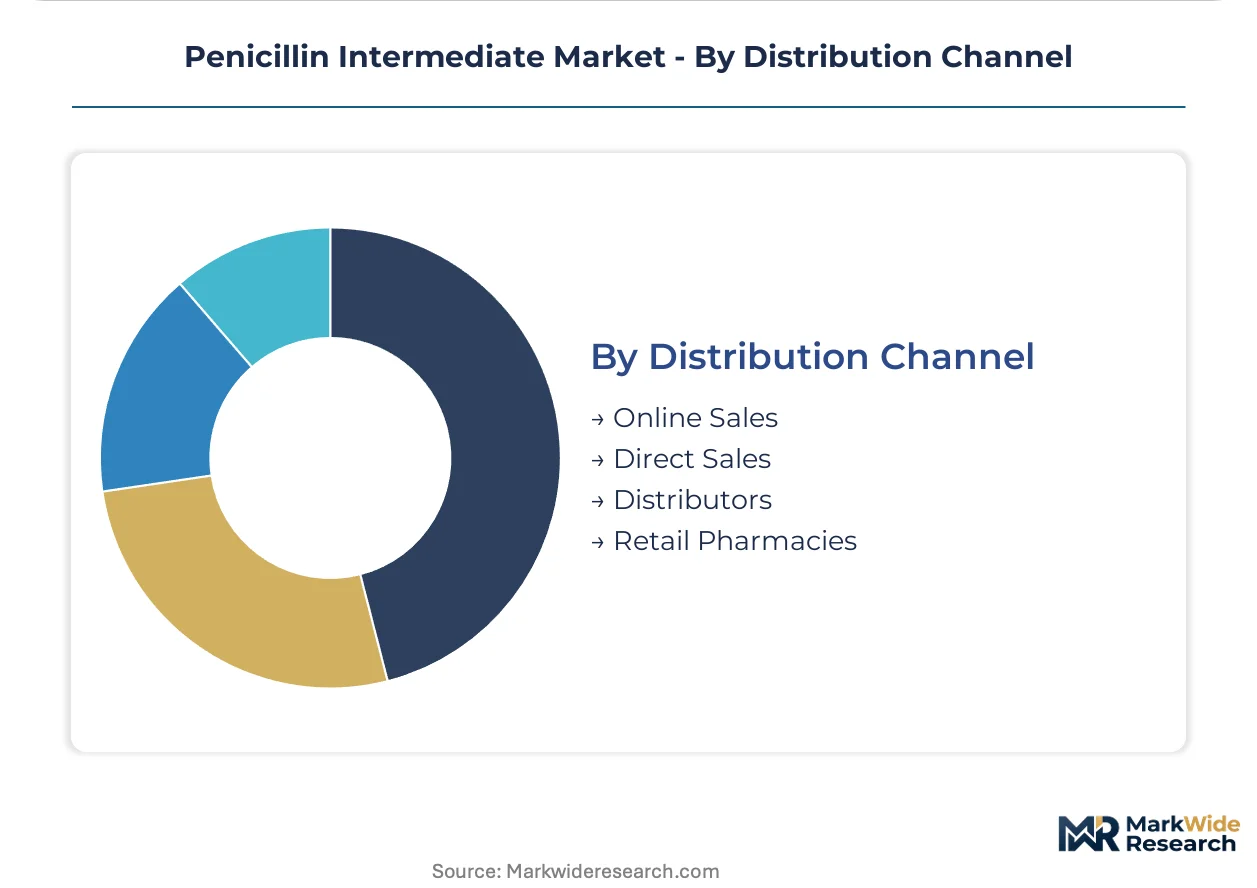
Distribution Channel:
Channel selection reflects order size, urgency, and regulatory documentation needs.
- Direct Sales:Long-term offtake agreements between fermentation producers and formulation manufacturers displace spot-market purchasing across Maharashtra and Shandong clusters.
- Distributors:Traditional bulk drug traders face margin compression as manufacturers bypass intermediary networks for volume accounts.
- Online Sales:E-procurement platforms gain traction for catalog-grade research quantities with standardized specifications.
- Retail Pharmacies:Minimal intermediate flow; channel serves only specialized compounding pharmacies with regulatory exemptions.
Primary volume channel: Direct Sales. Fastest digital adoption: Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Penicillin intermediate demand concentrates in fermentation corridors spanning India, China, and select European manufacturing hubs. FDA and EMA purity standards reshape supplier qualification protocols across these geographies. Local regulatory frameworks and industrial clustering patterns determine competitive positioning within each national market.
India
Maharashtra's bulk drug clusters absorb the majority of 6-APA volume as domestic generic manufacturers pursue backward integration into penicillin G potassium fermentation. The country's PLI scheme for bulk drug manufacturing accelerates capital deployment into fermentation capacity. Telangana anchors Aurobindo Pharma's integrated intermediate strategy with captive fermentation infrastructure.
China
Shandong Province's fermentation corridors concentrate global production capacity for benzylpenicillin and 6-APA derivatives. The Ministry of Ecology and Environment enforces discharge standards that periodically trigger production halts and supply disruptions. NMPA certification requirements for active pharmaceutical ingredients restrict market access for uncertified producers.
United States
Pfizer leverages captive fermentation infrastructure across North American sites to secure upstream supply of 6-aminopenicillanic acid for internal antibiotic manufacturing. FDA Current Good Manufacturing Practice enforcement elevates compliance costs for intermediate suppliers serving the US market. The domestic market exhibits limited fermentation capacity expansion due to capital intensity and regulatory burden.
Switzerland
Swissmedic's stringent pharmacopoeial requirements favor suppliers with validated quality management systems and documented supply chain traceability. Novartis and Sandoz operations anchor demand for high-purity 7-ACA and 7-ADCA cephalosporin precursors. The country's pharmaceutical manufacturing base sources intermediates through long-term offtake agreements rather than spot-market purchasing.
Netherlands
Centrient Pharmaceuticals specializes in enzymatic routes to penicillin side-chain precursors from Dutch manufacturing locations. EMA revised penicillin residue limits under veterinary regulation restrict intermediate sourcing to certified suppliers with documented impurity profiles. The Randstad region hosts formulation manufacturers that demand multi-pharmacopoeia certification for research laboratory and human medicine applications.
Penicillin Intermediate Market Competitive Landscape
Backward integration into fermentation infrastructure dominates the current competitive landscape as manufacturers seek supply security amid regulatory tightening. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates with captive fermentation, specialized API producers with enzymatic conversion capabilities, and commodity bulk drug suppliers competing on scale. Strategic archetypes include quality-certified specialists serving regulated markets and cost-optimized producers targeting generic antibiotic manufacturers. Capacity expansion and enzymatic technology licensing represent the dominant competitive moves as players reposition away from acid-cleavage methods.
Within the integrated pharmaceutical tier, Pfizer Inc. exemplifies the captive fermentation archetype with North American upstream infrastructure securing 6-APA supply. Among India-based specialists, Aurobindo Pharma Ltd. and Dr. Reddy's Laboratories occupy positions emphasizing backward integration into penicillin G potassium fermentation. Centrient Pharmaceuticals represents the enzymatic biocatalysis specialist archetype, differentiating through enzymatic routes rather than traditional chemical synthesis. These three companies anchor distinct strategic positions without overlapping competitive territory.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Aurobindo Pharma Ltd. |
| Centrient Pharmaceuticals |
| GlaxoSmithKline plc |
| Sandoz |
| Cipla Ltd. |
| Dr. Reddy's Laboratories |
| Sun Pharmaceutical Industries Ltd. |
| Novartis AG |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals and discharge standards under the Ministry of Ecology and Environment gate qualified supply for premium-tier penicillin intermediate access. Buyers seeking pharmaceutical-grade material with documented impurity profiles face restricted supplier pools as environmental enforcement actions periodically shutter Shandong Province fermentation corridors, compressing availability for certified product and widening price spreads against generic-grade alternatives.
Pricing Analysis
Volume throughput concentrates in standard-grade 6-APA for oral antibiotic manufacturing while premium-tier phenoxymethylpenicillin intermediates command wider margins in European formulary niches. Pricing stratifies across pharmaceutical-grade, veterinary-grade, and research-grade certification tiers with FDA and EMA monograph compliance as the primary differentiation driver. Cost compression in standard-grade material is intensifying as Indian generic manufacturers scale backward integration into penicillin G potassium fermentation under the PLI scheme. Contract manufacturing organizations exhibit the least price sensitivity given multi-pharmacopoeia certification requirements, while commodity bulk drug traders face acute margin pressure from direct offtake agreements.
Supply Chain Analysis
India's PLI scheme and domestic-content incentives for bulk drug manufacturing are reshaping sourcing patterns toward Maharashtra's bulk drug clusters and Telangana's integrated fermentation facilities. Raw material flows draw from corn steep liquor fermentation media, specialized enzyme preparations for biocatalytic conversion, and penicillium chrysogenum culture strains. Single-source vulnerability concentrates in Shandong Province's environmental enforcement exposure, where regional discharge standard violations trigger unplanned production halts. Distribution runs through long-term offtake agreements between fermentation producers and formulation manufacturers, displacing traditional bulk drug distributor networks across both Asian supply corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The penicillin intermediate market functions as a vertical-integration race where upstream fermentation capacity and enzymatic conversion technology determine supply security. Players are pursuing captive control over penicillin G potassium feedstock as the decisive lever against raw material volatility and regulatory qualification bottlenecks.
For Market Incumbents: Hedge against Shandong corridor concentration risk by diversifying fermentation sourcing into Maharashtra's expanding bulk drug clusters under India's PLI scheme. Secure multi-year enzyme supply contracts with biocatalysis specialists to defend enzymatic conversion yields against acid-cleavage competitors. Certification investment in simultaneous USP, EP, and IP monograph compliance creates switching costs for formulation manufacturer customers. For New Entrants and Emerging Players: Enter via Southeast Asia's underexploited fermentation infrastructure in Vietnam and Indonesia, where lower labor costs and greenfield facility eligibility offer cost positioning advantages. Target research laboratory demand for high-purity 6-APA and 7-ACA derivatives as the most penetrable segment, leveraging simplified documentation requirements against pharmaceutical-grade certification barriers. Pursue technology licensing partnerships with established enzymatic biocatalysis providers rather than greenfield acid-cleavage plant construction. For Investors and Strategic Acquirers: NMPA certification upgrades among Chinese fermentation producers is the leading indicator that supply consolidation and premium-tier pricing power are shifting toward quality-validated suppliers. Position acquisition screening around mid-cap API producers with documented impurity profiling capabilities and existing multi-pharmacopoeia certification, avoiding commodity bulk drug suppliers without validated quality management systems. Watch for EMA veterinary residue limit enforcement actions as the signal that regulatory compliance moats are widening against uncertified competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation | Captive penicillin G potassium supply secures upstream margin control against corn steep liquor volatility. |
| Enzymatic Biocatalysis Licensing | Technology transfer agreements compress conversion costs and environmental discharge versus acid-cleavage routes. |
| Multi-Pharmacopoeia Certification Investment | Simultaneous USP, EP, and IP compliance opens EMA-inspected supply chains for European formulation manufacturers. |
| Southeast Asia Capacity Expansion | Greenfield fermentation facilities in Vietnam exploit lower labor costs and distance from Shandong environmental enforcement. |
| Long-term Offtake Agreement Structuring | Direct manufacturer-to-formulator contracts displace distributor networks and stabilize pricing across agricultural commodity cycles. |
Research Methodology
Document review covered FDA Current Good Manufacturing Practice enforcement records, EMA veterinary residue limit revisions, and India's BIS certification requirements for bulk drug exports, complemented by interviews with fermentation plant managers, API procurement leads at generic antibiotic manufacturers, regulatory affairs specialists, and distribution channel partners. Secondary validation drew from customs trade data, SEC 10-K filings of integrated pharmaceutical conglomerates, and pharmacopoeial monograph revision notices. Bottom-up capacity assessments across Maharashtra and Shandong fermentation corridors were triangulated against top-down demand modeling from formulation manufacturer procurement disclosures.
Historical production volume trajectories were cross-referenced against panel input from industry stakeholders to construct the analytical framework across the projection horizon. Segmentation modeling incorporated product type, application destination, end-user scale, and distribution channel structure alongside regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation adjusted for enzymatic technology adoption curves and PLI scheme capacity deployment timelines. Forecast inputs included fermentation yield improvements, environmental enforcement probability distributions, and antibiotic stewardship policy directional signals.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt environmental enforcement escalations in Shandong Province or accelerated enzymatic biocatalysis patent expirations. The analytical envelope assumes continued regulatory harmonization pressure from FDA and EMA without fundamental pharmacopoeial monograph restructuring. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Potassium Benzoate Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Montelukast Intermediate Market
Chemical Intermediates
Global Etoricoxib Intermediate Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Leather Chemicals Market
Chemical Intermediates
Tertiary Amines Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Pigment Intermediates Market
Chemical Intermediates
Acetoacetanilide Market
Chemical Intermediates
Isosafrole Market
Chemical Intermediates
9-Decanoic Acid Methyl Ester Market
Chemical Intermediates
Potential Hydrogen (Ph) Adjusters Market
Chemical Intermediates
Thioesters Market
Chemical Intermediates
3-Chloropropionyl Chloride Market