
 Global Collagen Meniscus Implants Market | 2026-2036
Global Collagen Meniscus Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Collagen Meniscus Implants Market Intelligence
The divergence in capital access for extensive clinical trials is collapsing the competitive space between specialized innovators and established medtech firms. Stryker Corporation leverages its extensive global distribution network to reach a broad base of orthopedic clinics. In contrast, specialists like Orthonika differentiate through focused innovation in next-generation scaffold-based implant designs. Johnson & Johnson competes by integrating these implants within its broader portfolio of joint reconstruction solutions.
Collagen meniscus implants are bioresorbable medical devices engineered to serve as a scaffold for meniscal tissue regeneration following injury or partial meniscectomy. These implants are typically composed of highly purified Type I collagen, processed into a porous, three-dimensional structure that encourages cellular infiltration and tissue regrowth. Sports injury repair applications constitute the largest source of procedures, particularly among younger, active patient populations. While specialized hospitals currently represent the primary end-user channel, procedures are increasingly shifting towards more cost-effective ambulatory surgical centers.
Market access for collagen meniscus implants is contingent on stringent pre-market approvals from bodies like the US FDA and the European Medicines Agency (EMA). These regulations, along with standards from China's NMPA, mandate extensive clinical data to prove both safety and efficacy, setting a high barrier to entry. Future commercial success will depend on securing favorable reimbursement policies from payers and generating long-term clinical evidence to support broader adoption.
Market Dynamics
The central structural force shaping the market is the high-stakes friction between the pace of material science innovation and the rigorous, capital-intensive demands of global regulatory approval pathways, creating a competitive divide between specialized firms and large medtech corporations.
Growth Catalysts
- Material Science Advancement:Innovations in cross-linked Type I collagen processing are improving the mechanical strength and resorption profiles of implants, enhancing their durability and biocompatibility for sports injury repair applications.
- Active Aging Demographics:An increasing number of procedures among younger and middle-aged active individuals seeking to preserve joint function after meniscal injury provides a consistent source of demand for regenerative solutions.
- Healthcare Infrastructure:The expansion of specialized orthopedic clinics and sports medicine centers in developed economies, particularly the United States, creates concentrated points of care for advanced meniscal repair procedures.
Market Restraints
- Stringent Regulatory Hurdles:Pre-market approval processes, such as those mandated by the US FDA and the EU's EMA, require extensive and costly clinical trials to demonstrate safety and efficacy, setting a high barrier to entry.
- Reimbursement Uncertainty:Securing favorable and consistent reimbursement codes and payment levels from public and private payers is a significant hurdle, limiting patient access and slowing broader clinical adoption.
- Limited Long-Term Data:The relative novelty of collagen meniscus implants means there is a smaller body of long-term clinical evidence compared to traditional meniscectomy, making some clinicians hesitant to adopt the technology.
Strategic Opportunities
- Channel Expansion into ASCs:The procedural shift towards ambulatory surgical centers offers an opportunity for manufacturers to develop specific sales models and product bundles tailored to the cost and efficiency needs of these outpatient facilities.
- Targeting Underpenetrated Geographies:Markets in Western Europe and Japan with advanced healthcare systems, aging but active populations, and high rates of sports participation represent significant growth opportunities beyond the US.
- Biologic Augmentation:There is a clear opportunity to develop next-generation implants that integrate biologic agents, such as growth factors or stem cells, to accelerate and improve the quality of tissue regeneration.
Industry Challenges
- Clinical Trial Execution:The high cost and operational complexity of conducting large-scale, multi-year clinical trials required for regulatory approval is a major challenge, particularly for smaller, innovation-focused companies with limited capital access.
- Specialized Surgeon Training:Ensuring consistent and positive patient outcomes requires specialized training for orthopedic surgeons on the specific techniques for implant sizing and fixation, which can slow the rate of adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Collagen Meniscus Implants Market |
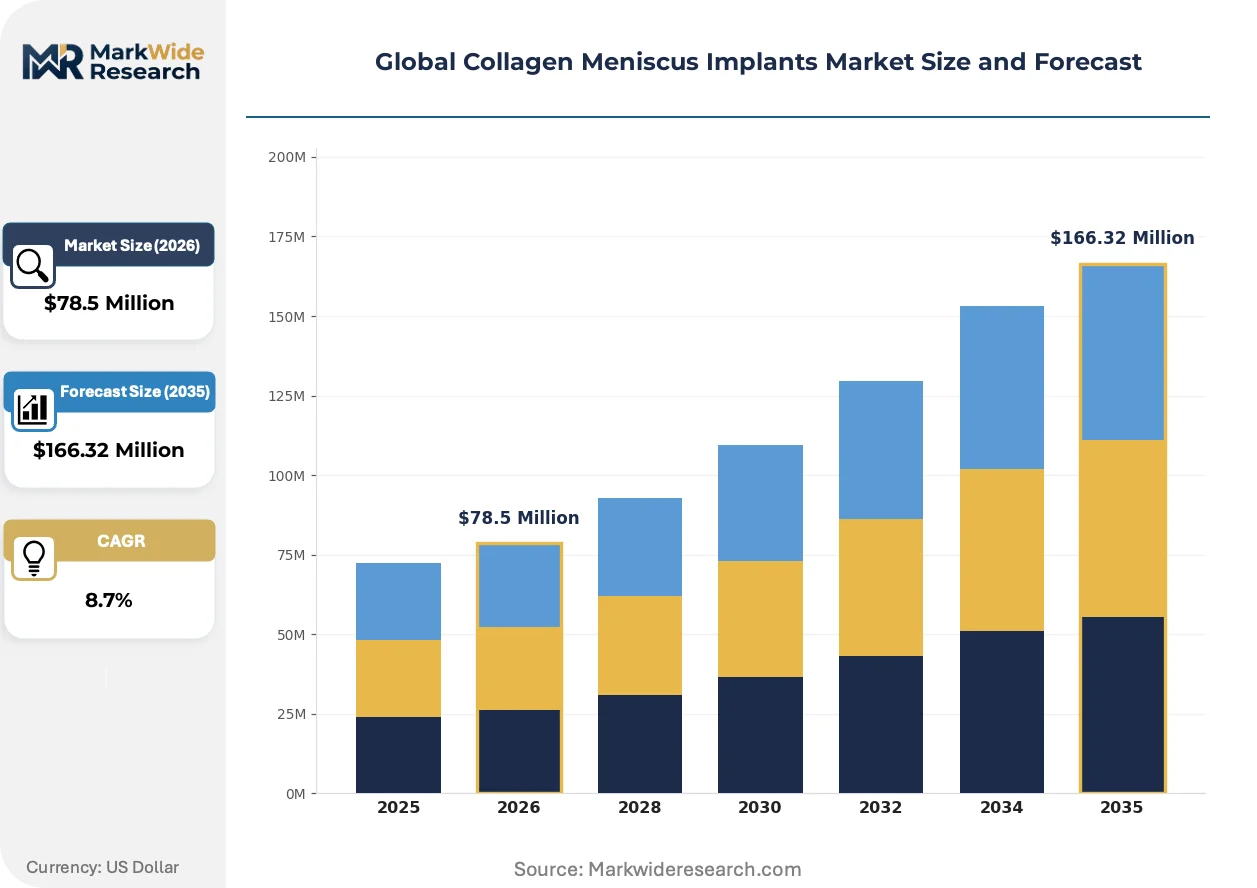
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $166.32 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Partial Implants, Total Implants, Scaffold-Based Implants, Multi-Layer Implants Material Composition: Type I Collagen, Type II Collagen, Synthetic Polymers, Hydrogel Blends, Cross-Linked Collagen Application: Sports Injury Repair, Degenerative Meniscal Tear, Post-Traumatic Reconstruction, Cartilage Preservation End User: Orthopedic Clinics, Ambulatory Surgical Centers, Rehabilitation Centers, Specialized Hospitals |
| Companies Covered | Smith & Nephew plc, Johnson & Johnson, Stryker Corporation, Active Implants LLC, Medtronic plc, Zimmer Biomet Holdings, Inc., Bioventus Inc., Orthonika, RTI Surgical Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Collagen Meniscus Implants Market Strategic Shifts & Innovations
Material science is driving a fundamental shift in implant design, moving toward scaffolds that more accurately mimic native tissue architecture and degradation kinetics. This evolution is occurring within a tightening global regulatory environment that prioritizes long-term patient safety and clinical evidence.
Next-generation bioresorbable scaffolds are engineered from highly purified, cross-linked collagen to create a porous structure that facilitates cellular infiltration. Orthopedic surgeons in specialized sports medicine centers are the primary adopters, using these implants to treat complex meniscal tears in younger patients. The predictable resorption profile of the material is decomposing the traditional boundary between a permanent implant and a temporary regenerative aid.
The European Union’s Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence and post-market surveillance. This regulation increases the time and cost to obtain and maintain a CE marking, directly impacting product development timelines. Manufacturers of Class III devices like collagen implants are most affected, forcing them to rationalize portfolios and prioritize investments in products with robust clinical data.
A significant shift in procedure location is underway, moving from traditional inpatient hospital settings to outpatient ambulatory surgical centers (ASCs). This trend disrupts established hospital-centric sales models, creating an advantage for vendors with flexible logistics and device pricing suitable for a cost-conscious environment. This pattern is most pronounced in the United States, where payer policies actively incentivize procedures in lower-cost outpatient settings.
Global Collagen Meniscus Implants Market Segmentation
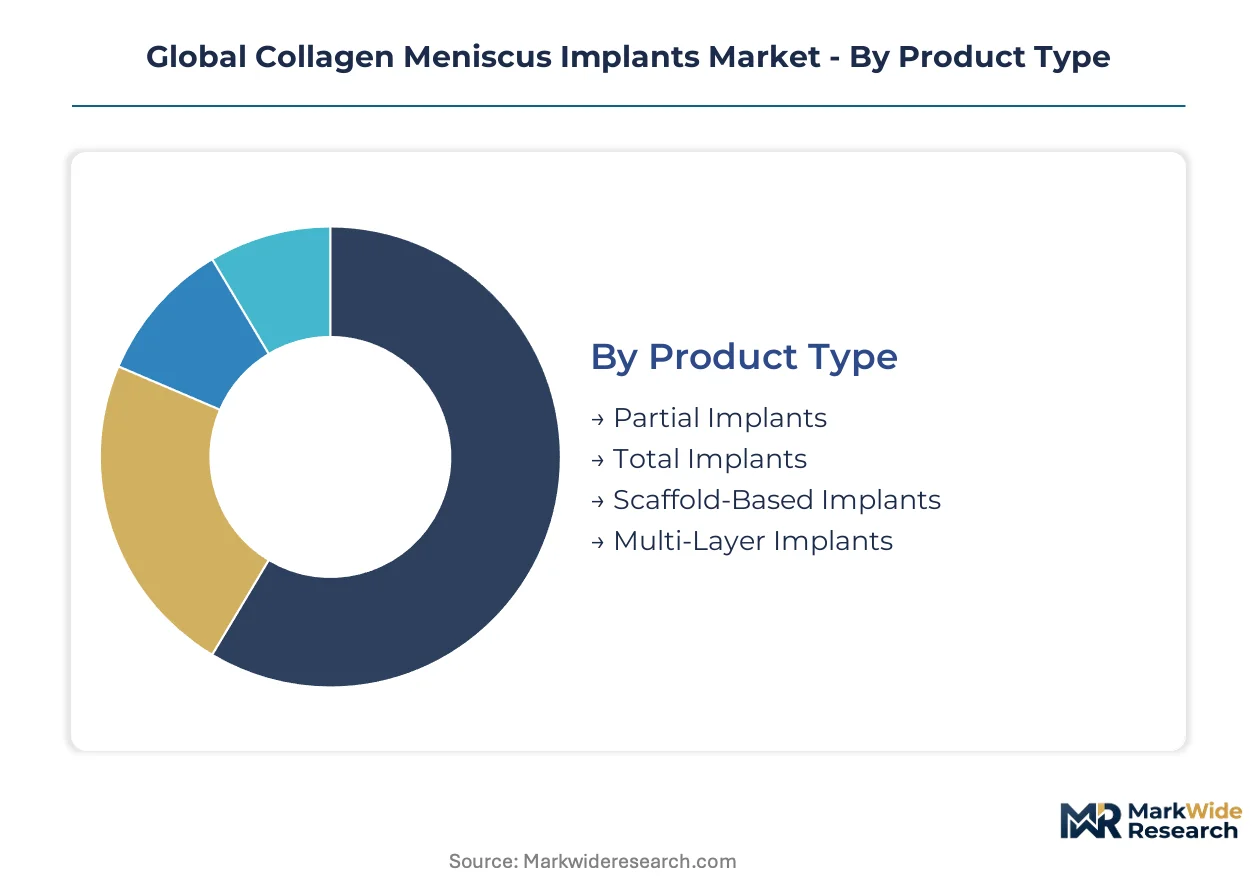
Market segmentation for collagen meniscus implants illuminates the intricate interplay between product innovation, material science, clinical applications, and diverse end-user preferences. This detailed breakdown helps stakeholders understand specific demand pockets and the strategic pathways for market penetration across different healthcare settings.
End User:
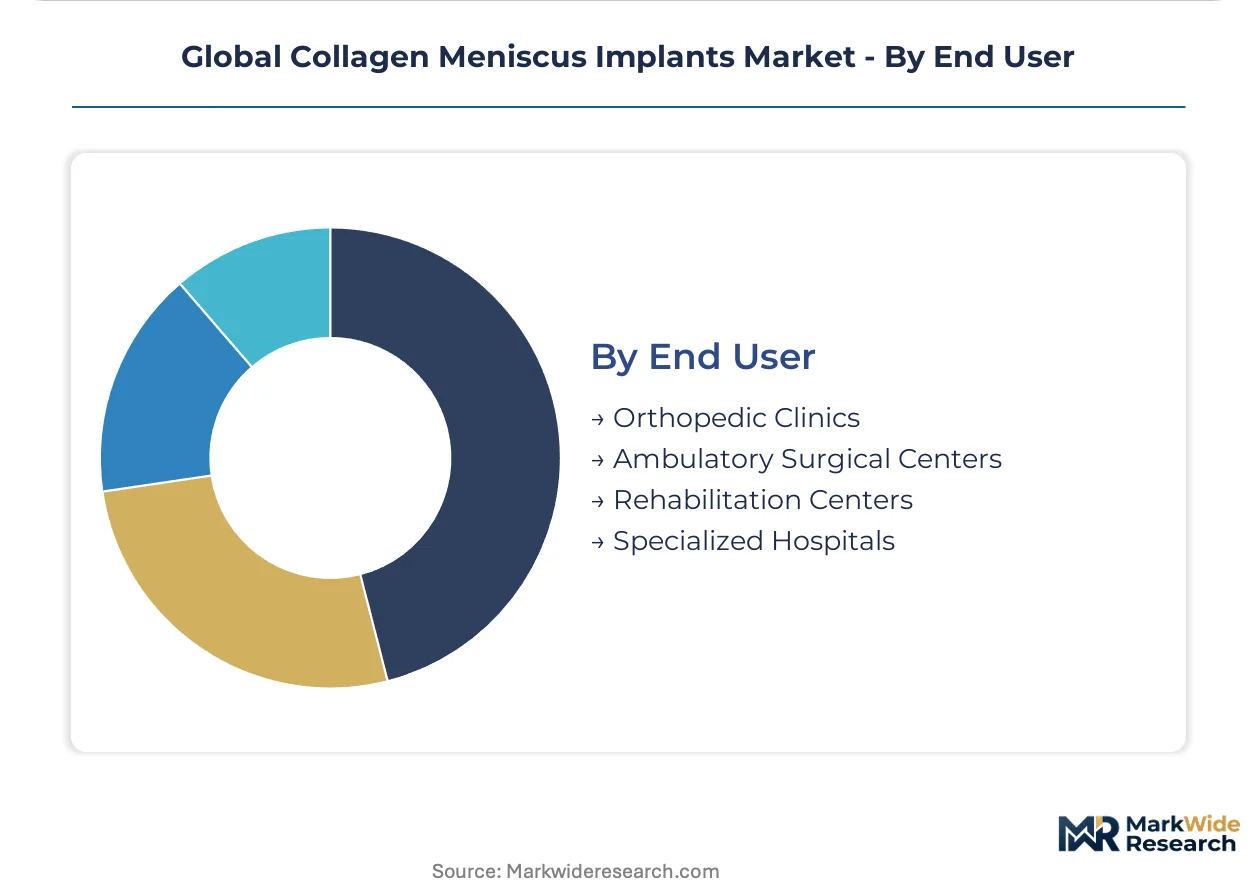
The distribution of collagen meniscus implant procedures across various end-user channels dictates market access and operational strategies for manufacturers.
- Specialized Hospitals:These facilities offer comprehensive orthopedic care, including complex surgical procedures and post-operative rehabilitation, catering to severe meniscal injuries requiring extensive medical oversight. Demand concentrates here due to the established infrastructure for advanced surgical interventions and the presence of highly skilled orthopedic surgeons globally.
- Ambulatory Surgical Centers:ASCs provide a cost-effective outpatient setting for less complex meniscal repair procedures, appealing to payers and patients seeking efficiency. Demand is accelerating in the United States, driven by payer incentives and a focus on reducing healthcare costs.
- Orthopedic Clinics:These clinics serve as primary points of patient consultation and follow-up, often referring patients to surgical centers for implant procedures.
- Rehabilitation Centers:Post-surgical rehabilitation is critical for patient recovery, though these centers do not directly perform implant procedures.
Specialized Hospitals dominate the current installed base for complex collagen meniscus implant procedures. Ambulatory Surgical Centers are where procedural expansion concentrates for routine cases.
Product Type:
Product type segmentation highlights the technological evolution of collagen meniscus implants, from foundational designs to advanced regenerative scaffolds.
- Scaffold-Based Implants:These devices provide a porous, three-dimensional matrix, typically from Type I collagen, designed to encourage cellular infiltration and natural tissue regeneration. Demand is high for younger, active patients in developed economies seeking long-term joint preservation.
- Partial Implants:Designed to replace only a damaged portion of the meniscus, these implants preserve more native tissue and are often used in less severe or localized tears. Demand for these solutions is consistent across various global orthopedic practices.
- Total Implants:These larger devices replace the entire meniscus, used in cases of extensive damage where partial repair is not feasible.
- Multi-Layer Implants:Featuring varied structural properties across layers, these implants aim to mimic the biomechanical complexity of the native meniscus more closely.
Innovations in scaffold-based designs are driving the next generation of collagen meniscus implants. Partial implants maintain a steady clinical presence.
Material Composition:
The material composition of collagen meniscus implants directly influences their biomechanical properties, biocompatibility, and degradation profiles, impacting clinical outcomes.
- Cross-Linked Collagen:This material variant enhances the mechanical strength and extends the degradation time of Type I collagen implants, improving durability and integration within the knee joint. Demand for cross-linked options is strong in sports medicine for active patient populations.
- Type I Collagen:Derived primarily from bovine or porcine sources, this highly purified protein forms the foundational biomaterial for most commercially available meniscus scaffolds due to its excellent biocompatibility. It finds widespread use in various meniscal repair procedures globally.
- Type II Collagen:Less common in current implants, Type II collagen is typically found in articular cartilage and offers different biomechanical properties.
- Synthetic Polymers:Materials like polyurethanes or polycaprolactone are explored for their tunable mechanical properties and controlled degradation rates.
- Hydrogel Blends:These composite materials combine collagen with other polymers to achieve specific elasticity and cellular interaction characteristics.
Cross-linked collagen formulations are advancing implant performance. Type I collagen remains the industry standard for bioresorbable scaffolds.
Application:
Application segments delineate the specific clinical conditions and patient demographics addressed by collagen meniscus implants, reflecting diverse surgical needs.
- Sports Injury Repair:This application addresses acute meniscal tears common in athletes and physically active individuals, aiming to restore joint function and prevent long-term degeneration. Demand is particularly high in the United States and Western Europe, driven by high sports participation rates.
- Degenerative Meniscal Tear:Targeting tears resulting from age-related wear and tear, these implants aim to alleviate pain and improve mobility in older patient cohorts. This application provides a steady volume of procedures as populations age globally.
- Post-Traumatic Reconstruction:Implants are used to reconstruct meniscal tissue following significant trauma, often in conjunction with other knee ligament repairs.
- Cartilage Preservation:This application focuses on using implants to protect adjacent articular cartilage by restoring meniscal function, thereby delaying the onset of osteoarthritis.
Sports injury repair represents the primary demand driver for collagen meniscus implants. Degenerative meniscal tears also contribute a substantial volume of procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for collagen meniscus implants varies significantly across global markets. In highly developed economies with robust private insurance, patient populations exhibit lower price sensitivity for advanced regenerative solutions. Conversely, markets dominated by public healthcare systems often prioritize cost-effectiveness, influencing product adoption rates.
United States
The United States represents the largest market, driven by a high incidence of sports injuries and advanced orthopedic infrastructure. The US FDA's stringent pre-market approval process mandates extensive clinical data. Major orthopedic hubs like Boston, Massachusetts, foster innovation and specialized surgical practices.
Germany
Germany exhibits strong demand, fueled by its well-developed healthcare system and active population. The European Medical Device Regulation (MDR) imposes rigorous requirements for CE marking. Munich and Berlin serve as key centers for orthopedic research and advanced surgical techniques.
Japan
Japan presents a substantial opportunity, characterized by an aging yet active demographic and focus on quality-of-life improvements. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees device approvals, emphasizing long-term safety. Tokyo and Osaka host leading medical institutions driving meniscal repair advancements.
China
China's market is expanding, propelled by increasing sports participation and a growing middle class seeking advanced treatments. The National Medical Products Administration (NMPA) sets comprehensive standards for medical device registration. Shanghai and Beijing are emerging as significant centers for orthopedic surgery and implant distribution.
United Kingdom
The United Kingdom shows consistent demand, supported by a strong sports culture and commitment to regenerative medicine. The Medicines and Healthcare products Regulatory Agency (MHRA) ensures medical device safety and performance. London and Manchester are prominent locations for specialized sports medicine clinics and surgical training.
Global Collagen Meniscus Implants Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the collagen meniscus implants market. The competitive landscape is characterized by a tiered structure, where established medtech corporations coexist with specialized innovators and emerging start-ups. Strategic archetypes include diversified orthopedic giants, niche regenerative medicine developers, and material science-focused innovators. Dominant competitive moves involve strategic partnerships for market access, continuous portfolio diversification, and targeted M&A activities.
Among the diversified orthopedic giants, Johnson & Johnson exemplifies a player integrating collagen meniscus implants within a broader joint reconstruction solutions portfolio to offer comprehensive care. Stryker Corporation, another major medical technology firm, represents an archetype leveraging extensive global distribution networks to effectively reach orthopedic clinics worldwide. Orthonika, in contrast, sits within the specialized innovator tier, focusing on next-generation scaffold-based implant designs that differentiate through material science advancements. These archetypes highlight the varied approaches to market penetration and product development.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| Johnson & Johnson |
| Stryker Corporation |
| Active Implants LLC |
| Medtronic plc |
| Zimmer Biomet Holdings, Inc. |
| Bioventus Inc. |
| Orthonika |
| RTI Surgical Holdings, Inc. |
| Others |
Cost & Logistics Intelligence
The substitution of traditional meniscectomy with advanced bioresorbable collagen implants reshapes manufacturing locations and the value-based pricing models accepted by global payers. This shift influences where specialized materials are sourced and how costs are distributed through the supply chain.
Pricing Analysis
Post-implantation rehabilitation and follow-up care represent a crucial after-sales revenue tier for the collagen meniscus implant market, driving long-term patient engagement and value. The dominant pricing model remains per-unit transactional, influenced by regulatory approval tiers and brand premiums associated with established medtech firms. Price differentiation stems from the implant's material composition, such as cross-linked collagen, and the specific FDA/EMA certification level. Pricing softness stems from increasing pressure from payers to reduce overall healthcare costs, making ambulatory surgical centers highly price-sensitive compared to specialized hospitals.
Supply Chain Analysis
Rising inbound logistics costs, particularly for specialized biological raw materials, impact the global collagen meniscus implant supply chain, which draws from bovine or porcine sources processed in the United States and Western Europe. Key raw material dependencies include medical-grade collagen and biocompatible cross-linking agents. A structural risk involves single-source vulnerability for specialized biomaterial suppliers, necessitating robust supplier diversification strategies. Distribution runs through established medical device channels, primarily to orthopedic clinics and surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collagen meniscus implants market presents a significant fragmentation opportunity driven by the demand-side shift towards cost-effective outpatient procedures in ambulatory surgical centers. This creates distinct niches for specialized product offerings and sales models.
For Market Incumbents: Compound existing distribution network advantages by strategically partnering with ambulatory surgical centers to offer tailored product bundles and logistics solutions. Reinforce market leadership against specialized innovators by investing heavily in next-generation biologic augmentation to accelerate tissue regeneration. This counters the threat from niche players offering advanced scaffold designs. Focus R&D on long-term clinical evidence generation to support broader reimbursement.
For New Entrants and Emerging Players: Expedited regulatory certification pathways in specific regional markets like Japan or Western Europe offer a fast-track for specialized innovators. Target underpenetrated geographies and patient segments, such as older, active individuals with degenerative tears, where existing solutions are less optimized. A focused go-to-market angle emphasizing superior material science and predictable resorption profiles can differentiate offerings. Developing next-generation scaffold designs with integrated growth factors represents a key white-space target.
For Investors and Strategic Acquirers: The market sits at an early-growth phase that favors specialized innovators with robust clinical data and clear regulatory pathways. Long-term viability hinges on securing favorable reimbursement policies and demonstrating superior patient outcomes over traditional meniscectomy. Acquisition target archetypes include niche regenerative medicine developers with proprietary material science or advanced scaffold designs. The signal to watch is the expansion of favorable reimbursement codes across major developed economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand ASC-specific product lines | Tailored implant sizes and cost-effective bundles will capture procedural volume shifting to outpatient settings. |
| Invest in biologic augmentation R&D | Integrating growth factors or stem cells will accelerate tissue regeneration and improve long-term patient outcomes. |
| Pursue PMDA/EMA approvals | Gaining regulatory clearances in Japan and Western Europe unlocks significant underpenetrated market opportunities. |
| Generate long-term clinical evidence | Robust data demonstrating durability and efficacy is crucial for securing broader payer reimbursement and clinical adoption. |
| Strategic partnerships with specialized clinics | Collaborations with leading sports medicine centers drive surgeon adoption and refine surgical techniques. |
Research Approach
Initial hypotheses were tested against primary input from orthopedic surgeons, hospital procurement managers, medical device engineers, and regulatory affairs specialists, and refined through iterative analysis. This approach combined in-depth interviews with secondary validation from sources such as US FDA filings, EMA submissions, and orthopedic society publications. Both bottom-up and top-down triangulation methods were employed to ensure data consistency.
Variance decomposition identified key drivers impacting market growth across the analysis window, including material science advancements and active aging demographics. The analytical framework modeled market dynamics by segmenting across end-user channels, product types, and application areas. Compound annual growth rates were derived from historical trends and projected adoption rates, incorporating inputs like procedure volume forecasts and material cost trajectories.
The analysis sits within stated boundaries; outcomes outside significant shifts in regulatory frameworks or unexpected material science breakthroughs would require recalibration. Forecasts reflect assumptions regarding healthcare spending trends and the pace of clinical evidence accumulation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Chitosan Oligosaccharides Market
Biomaterials
US Heparin Market
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
Global Medical Engineered Materials Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Atelocollagen Market
Biomaterials
Heparin Market
Biomaterials
Europe Collagen Market
Biomaterials
Biodegradable Bone Graft Polymers Market
Biomaterials
Chitosan Films Market
Biomaterials
Global Biomaterials Market
Biomaterials
Chitosan-Based Biomaterials Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
Bone Substitutes Market