
 Global Hydroxyapatite Market | 2026-2036
Global Hydroxyapatite Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydroxyapatite Market Foresight
The hydroxyapatite supply base is restructuring around a sharp split between premium nanocrystalline grades for orthopedic coatings and commodity powder for dental fillers. Zimmer Biomet dominates implant-grade formulations through captive manufacturing and FDA master file control. Fluidinova leverages spray-drying technology to sustain European supply of spherical granules for 3D-printed bone scaffolds.
Hydroxyapatite is a calcium phosphate ceramic with the formula Ca₁₀(PO₄)₆(OH)₂, possessing a calcium-to-phosphorus molar ratio of 1.67 that matches natural bone mineral and enables direct osteoconduction when implanted. Synthetic powder forms the volume core of the market but carries thin margins, while nanocrystalline variants command premium pricing in orthopedic coatings due to superior surface area and dissolution kinetics. Orthopedic implants represent the fastest-growing application segment as hospitals shift toward hydroxyapatite-coated titanium stems to reduce aseptic loosening revisions. Tissue engineering scaffolds remain nascent but attract R&D investment from biomedical firms seeking off-the-shelf graft substitutes.
FDA 510(k) pathways and the EU Medical Device Regulation shape market access timelines for new hydroxyapatite formulations, with notified bodies demanding extensive biocompatibility ISO 10993 testing for permanent implant classifications. Japan's PMDA adds another compliance layer through its QMS ordinance for custom-made bone prosthetics. Stakeholders must monitor evolving reimbursement codes for synthetic bone substitutes as health technology assessment bodies in Germany and France weigh cost-effectiveness against autograft standards.
Market Dynamics
The hydroxyapatite market pivots on orthopedic manufacturers' migration from plasma-sprayed coatings to electrochemically deposited nanocrystalline layers, a shift compressing formulation margins while elevating biocompatibility certification barriers.
Growth Catalysts
- EU Medical Device Regulation:Stricter biocompatibility ISO 10993 testing mandates for permanent implant classifications are filtering out substandard suppliers and consolidating demand around certified producers.
- Japan's aging demographic:Joint replacement volumes in Japanese hospitals are accelerating consumption of hydroxyapatite-coated titanium stems for hip and knee arthroplasty.
- Spray-drying technology:Advanced spherical granule production is enabling 3D-printed bone scaffold manufacturing with superior packing density and flow characteristics.
Market Restraints
- Phosphate rock volatility:Feedstock cost instability from Moroccan and Chinese supply concentration squeezes synthetic powder margins.
- FDA 510(k) pathway friction:Extended review timelines for novel hydroxyapatite formulations delay commercialization by 12-18 months versus predicate devices.
- Demineralized bone matrix substitution:Allograft alternatives with established reimbursement codes capture price-sensitive dental and spinal fusion segments.
Strategic Opportunities
- India's orthopedic expansion:Domestic joint replacement procedure growth outpaces local hydroxyapatite coating capacity, creating import substitution potential.
- Tissue engineering convergence:Integration of hydroxyapatite with collagen and polycaprolactone biopolymers is opening off-the-shelf graft substitute development.
- US IRA manufacturing incentives:Domestic production tax credits for critical medical materials are attracting greenfield investment in nanocrystalline synthesis.
Industry Challenges
- Biomaterials PhD scarcity:Specialized expertise in calcium phosphate crystallization and surface functionalization commands premium compensation and constrains R&D scaling.
- Cleanroom capex intensity:ISO 14644 Class 7 production environments for implant-grade powder require $15-25 million facility investments.
- PMDA QMS ordinance compliance:Japan's quality management system for custom-made bone prosthetics demands documented traceability from raw phosphate to finished coating.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydroxyapatite Market |
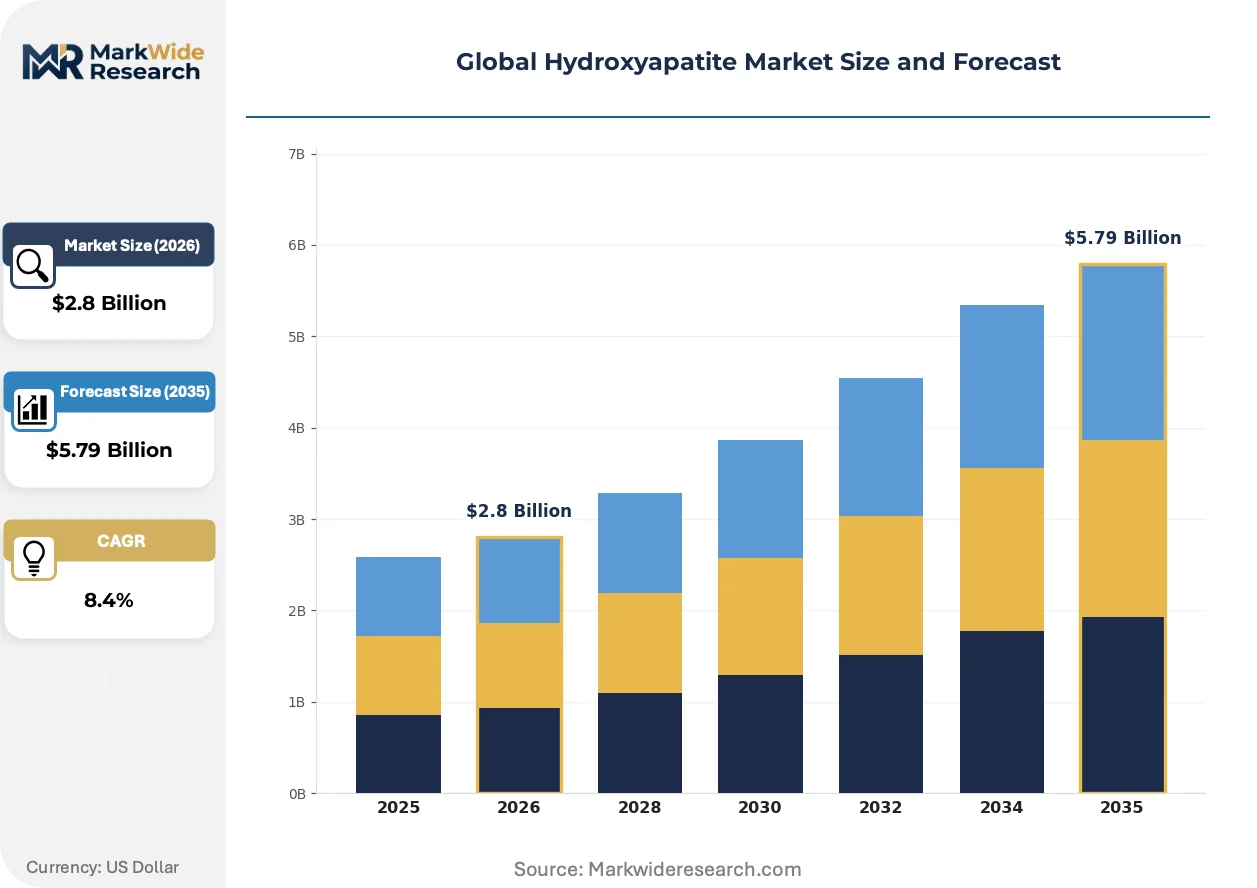
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Coatings, Blocks, Scaffolds Application: Bone Grafting, Dental Fillers, Drug Delivery, Tissue Engineering, Orthopedic Implants End User: Dental Laboratories, Research Institutes, Prosthetic Manufacturers, Biomedical Firms, Pharmacies Form: Synthetic, Natural, Nanocrystalline, Composite, Microcrystalline |
| Companies Covered | Bio-Rad Laboratories Inc., The Lubrizol Corporation, Zimmer Biomet, Taihei Chemical Industrial Co. Ltd, SigmaGraft Biomaterials, Fluidinova, CGbio, APS Materials Inc., Berkeley Advanced Biomaterials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydroxyapatite Market Shifts & Advancements
Electrochemical deposition and biomaterial hybridization are compressing traditional coating supply chains while regulatory convergence around ISO standards is harmonizing quality benchmarks across previously fragmented national frameworks.
Sol-gel synthesis of nanocrystalline hydroxyapatite is decentralizing coating production away from centralized plasma spray facilities. Mid-sized orthopedic implant manufacturers in Germany and the United States are adopting benchtop electrochemical cells to deposit conformal layers in-house. This technology is decentralizing the historical supplier-buyer power balance that favored large coating houses with captive thermal spray infrastructure.
EU MDR's tightened biocompatibility certification requirements for synthetic bone substitutes are extending notified body review cycles. Manufacturers must now submit comprehensive biological evaluation plans covering genotoxicity, carcinogenicity, and reproductive toxicity endpoints. Implant-grade nanocrystalline formulations face the steepest compliance burden, driving consolidation toward producers with established FDA master files and CE technical documentation libraries.
Japanese university hospitals are consolidating procurement through centralized purchasing cooperatives for orthopedic biomaterials. These buying groups negotiate multi-year supply agreements with coating providers, displacing fragmented hospital-level contracting. Germany's hospital procurement landscape is witnessing comparable concentration, with regional purchasing alliances standardizing hydroxyapatite specifications across member institutions.
Global Hydroxyapatite Market Segmentation
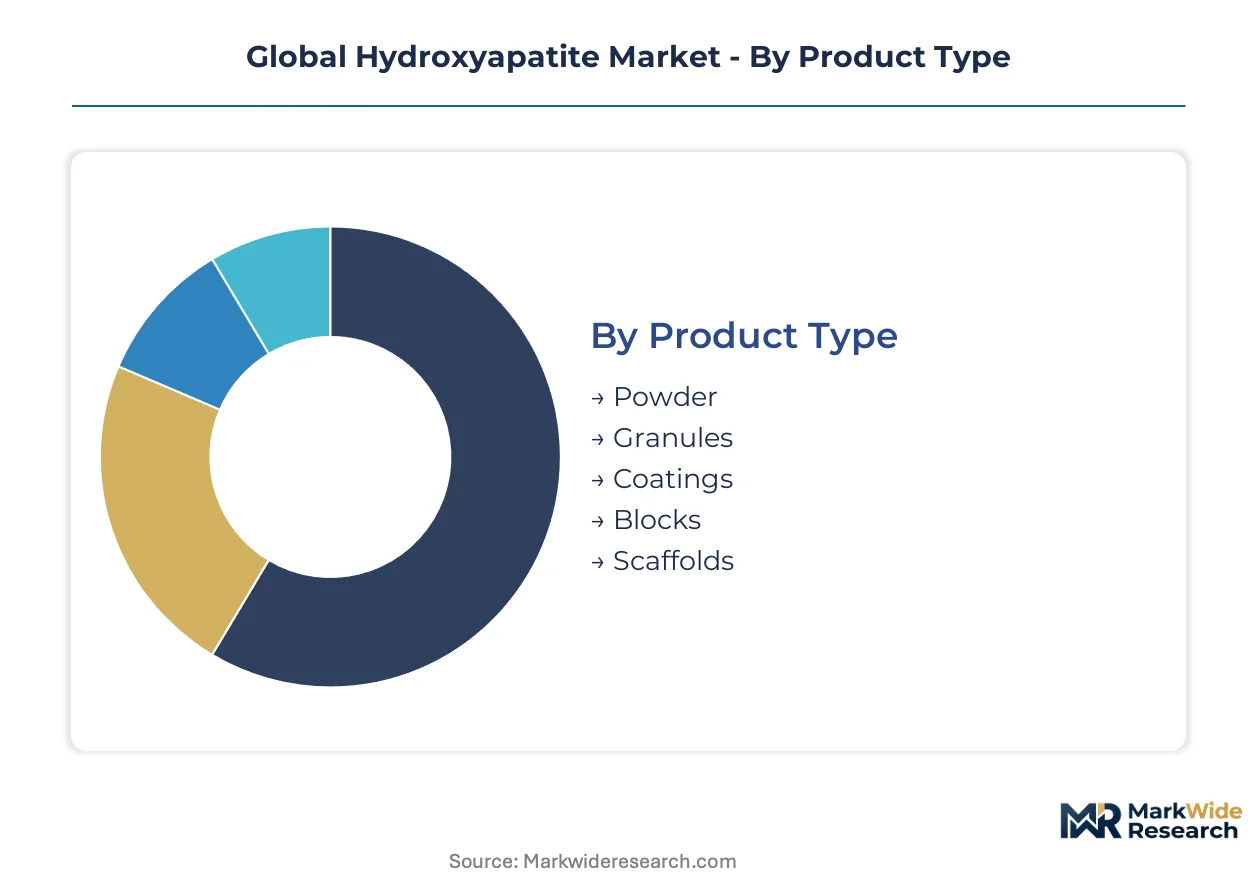
Hydroxyapatite segmentation tracks a fundamental split between commodity feedstock and functionalized medical grades. Product form and crystalline structure determine pricing power, regulatory pathway, and end-use eligibility across orthopedic, dental, and research applications.
Product Type:
Buyers differentiate by processing stage and functional integration, with raw powder serving bulk applications while advanced formats command premium positioning in implant manufacturing.
- Powder:Unprocessed calcium phosphate ceramic requiring downstream sintering or compaction. Demand concentrates in China and Morocco for phosphate rock conversion into synthetic hydroxyapatite feedstock, squeezed by volatile raw material costs from concentrated Moroccan supply.
- Coatings:Electrochemically deposited or plasma-sprayed layers applied to titanium stems for hip and knee arthroplasty. Japanese hospitals and German implant manufacturers are accelerating procurement of nanocrystalline variants to reduce aseptic loosening revisions.
- Granules:Spherical particles produced via spray-drying for dental fillers and bone void packing. Fluidinova's European supply serves 3D-printed scaffold manufacturers seeking superior flow characteristics.
- Blocks:Pre-formed dense ceramic for maxillofacial reconstruction and spinal fusion. Compression-molded formats suit load-bearing applications where structural integrity outweighs porosity requirements.
- Scaffolds:Architected porous structures for tissue engineering and custom bone regeneration. R&D investment from biomedical firms targets off-the-shelf graft substitutes integrating collagen and polycaprolactone.
Powder leads volumes today; coatings are gaining share fastest.
Application:
End-use concentration follows procedure reimbursement codes and surgical volume demographics across mature healthcare systems.
- Orthopedic Implants:Hydroxyapatite-coated titanium stems for hip and knee arthroplasty. United States hospitals are shifting procurement toward electrochemically deposited nanocrystalline layers, compressing margins while elevating FDA 510(k) certification barriers.
- Bone Grafting:Synthetic substitutes for autograft and allograft replacement in spinal fusion and trauma. Demineralized bone matrix alternatives with established reimbursement codes capture price-sensitive segments in France and Germany.
- Dental Fillers:Granules and cement formulations for periodontal defects and extraction socket preservation. Japanese dental clinics standardize on synthetic powder over bovine-derived alternatives amid religious and safety concerns.
- Tissue Engineering:Scaffold substrates for cell seeding and bioreactor cultivation. Academic medical centers in Germany and the United States drive experimental consumption ahead of commercial translation.
- Drug Delivery:Ceramic carriers for controlled release of antibiotics, growth factors, or bisphosphonates. Local delivery applications in osteomyelitis treatment remain niche relative to systemic alternatives.
Bone grafting anchors revenue today; orthopedic implants are climbing the fastest.
End User:
Procurement sophistication varies from centralized hospital purchasing cooperatives to fragmented laboratory supply chains.
- Prosthetic Manufacturers:Captive coating operations and outsourced thermal spray services for implant finishing. Zimmer Biomet maintains internal nanocrystalline synthesis capabilities with FDA master file control.
- Biomedical Firms:R&D-stage consumption for scaffold development and biopolymer hybridization. Venture-funded startups in Boston and Berlin drive experimental demand for composite formulations.
- Dental Laboratories:Millable blocks and injectable cements for crown foundations and ridge augmentation. Independent labs in Japan consolidate purchasing through regional dental associations.
- Research Institutes:Standard-grade powder for crystallization studies and comparative biomaterials research. University procurement favors catalog distributors over direct manufacturer relationships.
- Pharmacies:Over-the-counter dental repair cements and topical remineralization products. Retail channels in Germany and France stock consumer-grade hydroxyapatite toothpaste additives.
Prosthetic manufacturers dominate procurement volumes; biomedical firms show the steepest expansion trajectory.
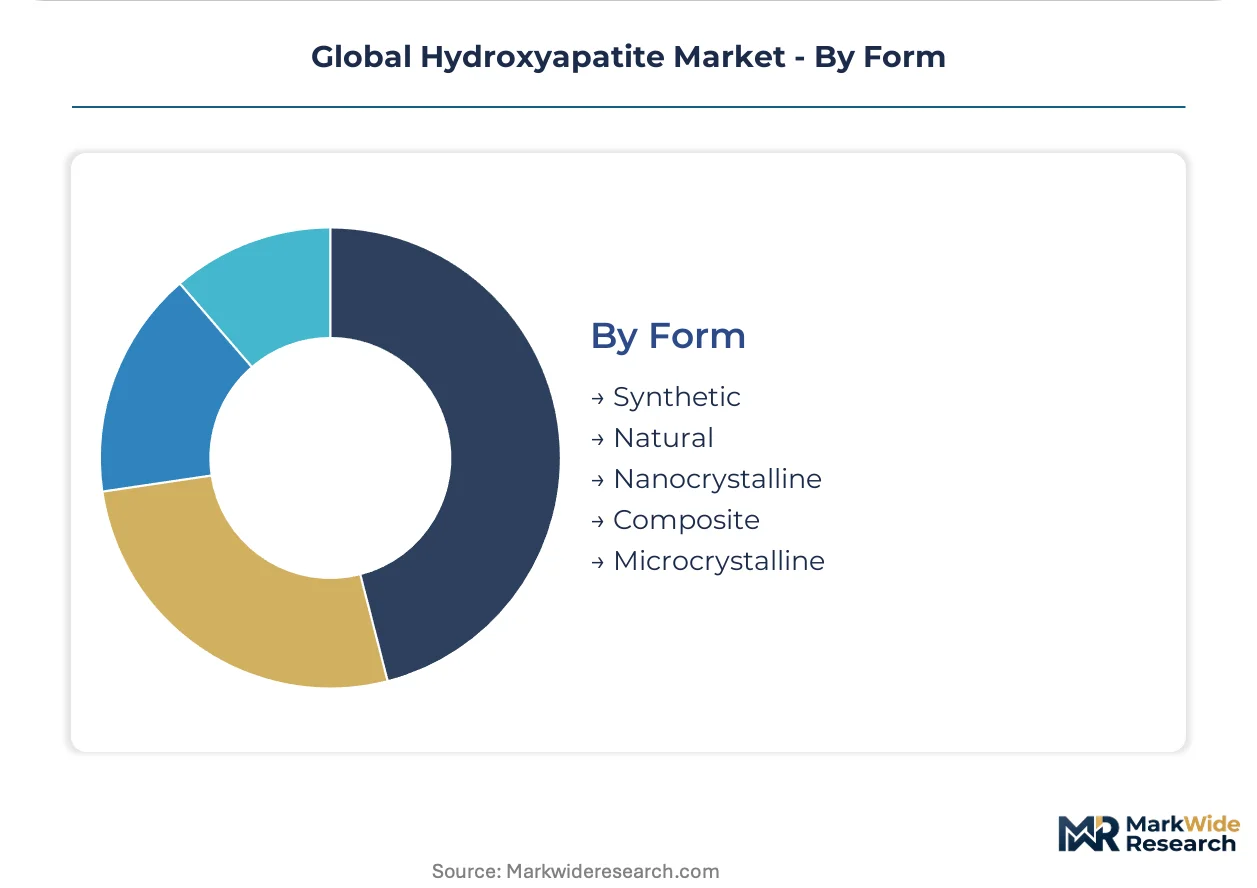
Form:
Crystalline architecture determines dissolution kinetics, surface area, and regulatory classification for permanent implant use.
- Nanocrystalline:Sub-100nm crystal domains with elevated surface area and accelerated osteoconduction. Implant-grade formulations face the steepest EU MDR biocompatibility certification burden, consolidating supply around producers with established technical documentation libraries.
- Synthetic:Chemically precipitated calcium phosphate from phosphate rock and calcium salts. Commodity powder production margins compress under feedstock volatility from Moroccan and Chinese supply concentration.
- Natural:Derived from bovine bone, coral, or eggshell sources. Religious dietary restrictions and transmissible spongiform encephalopathy concerns limit adoption in Middle Eastern and Japanese markets.
- Composite:Blended with collagen, polycaprolactone, or bioactive glass for tunable mechanical properties. Tissue engineering applications favor hybrid scaffolds over monolithic ceramic.
- Microcrystalline:Intermediate crystal size for dental fillers and non-load-bearing bone void fillers. Standard-grade specifications suit cost-sensitive applications where nanoscale precision is unnecessary.
Synthetic forms dominate tonnage today; nanocrystalline grades are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized biomaterials PhD concentrations in Boston, Stuttgart, and Osaka anchor geographic demand for hydroxyapatite. Orthopedic implant clusters concentrate near university hospital networks with active arthroplasty programs. Regulatory convergence around ISO 10993 standards is harmonizing quality benchmarks across previously fragmented national frameworks.
United States
Joint replacement volumes at Mayo Clinic and Hospital for Special Surgery drive consumption of nanocrystalline-coated titanium stems. FDA 510(k) review timelines for novel hydroxyapatite formulations extend commercialization cycles by 12-18 months versus predicate devices. Greater Boston hosts venture-funded biomedical startups pursuing scaffold hybridization with collagen and polycaprolactone.
Germany
Regional purchasing alliances in Bavaria and North Rhine-Westphalia standardize hydroxyapatite specifications across member hospitals. EU MDR notified bodies demand comprehensive ISO 10993 biological evaluation plans covering genotoxicity and carcinogenicity endpoints. Stuttgart's industrial corridor concentrates electrochemical deposition equipment suppliers serving mid-sized orthopedic manufacturers.
Japan
Tokyo and Osaka university hospitals consolidate procurement through centralized purchasing cooperatives negotiating multi-year supply agreements. PMDA QMS ordinance mandates documented traceability from raw phosphate to finished coating for custom-made bone prosthetics. Kobe's medical device cluster specializes in nanocrystalline synthesis for domestic implant manufacturers.
China
Phosphate rock conversion capacity concentrates in Guizhou and Yunnan provinces, feeding synthetic powder production for dental filler exports. NMPA biocompatibility requirements for permanent implant classifications are tightening documentation standards. Shanghai's Zhangjiang Hi-Tech Park attracts R&D investment from multinational orthopedic firms seeking localized coating supply.
India
Domestic joint replacement procedure growth at Apollo and Fortis hospital networks outpaces local hydroxyapatite coating capacity. CDSCO medical device rules are aligning with ISO 13485 quality management standards for imported orthopedic biomaterials. Hyderabad's medical technology corridor incubates startups targeting import substitution in nanocrystalline synthesis.
Global Hydroxyapatite Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the hydroxyapatite supply base. Captive manufacturing operations at major orthopedic OEMs contrast with independent coating houses and specialized powder suppliers. Three archetypes dominate: integrated implant manufacturers with internal synthesis capabilities, independent thermal spray service providers, and research-grade material suppliers serving academic markets. Consolidation pressures favor backward integration into nanocrystalline production and strategic partnerships with 3D-printed scaffold developers.
Among US-based diversified healthcare conglomerates, Zimmer Biomet exemplifies the integrated manufacturer archetype with FDA master file control over implant-grade formulations. Fluidinova represents European specialist positioning in spherical granule production through spray-drying technology. Taihei Chemical Industrial Co. Ltd anchors Japanese supply of synthetic powder for domestic dental and orthopedic applications. These three occupy positions spanning the value chain from commodity feedstock to functionalized medical grades.
| Leading Market Players |
|---|
| Bio-Rad Laboratories Inc. |
| The Lubrizol Corporation |
| Zimmer Biomet |
| Taihei Chemical Industrial Co. Ltd |
| SigmaGraft Biomaterials |
| Fluidinova |
| CGbio |
| APS Materials Inc. |
| Berkeley Advanced Biomaterials |
| Others |
Supply & Pricing Matrix
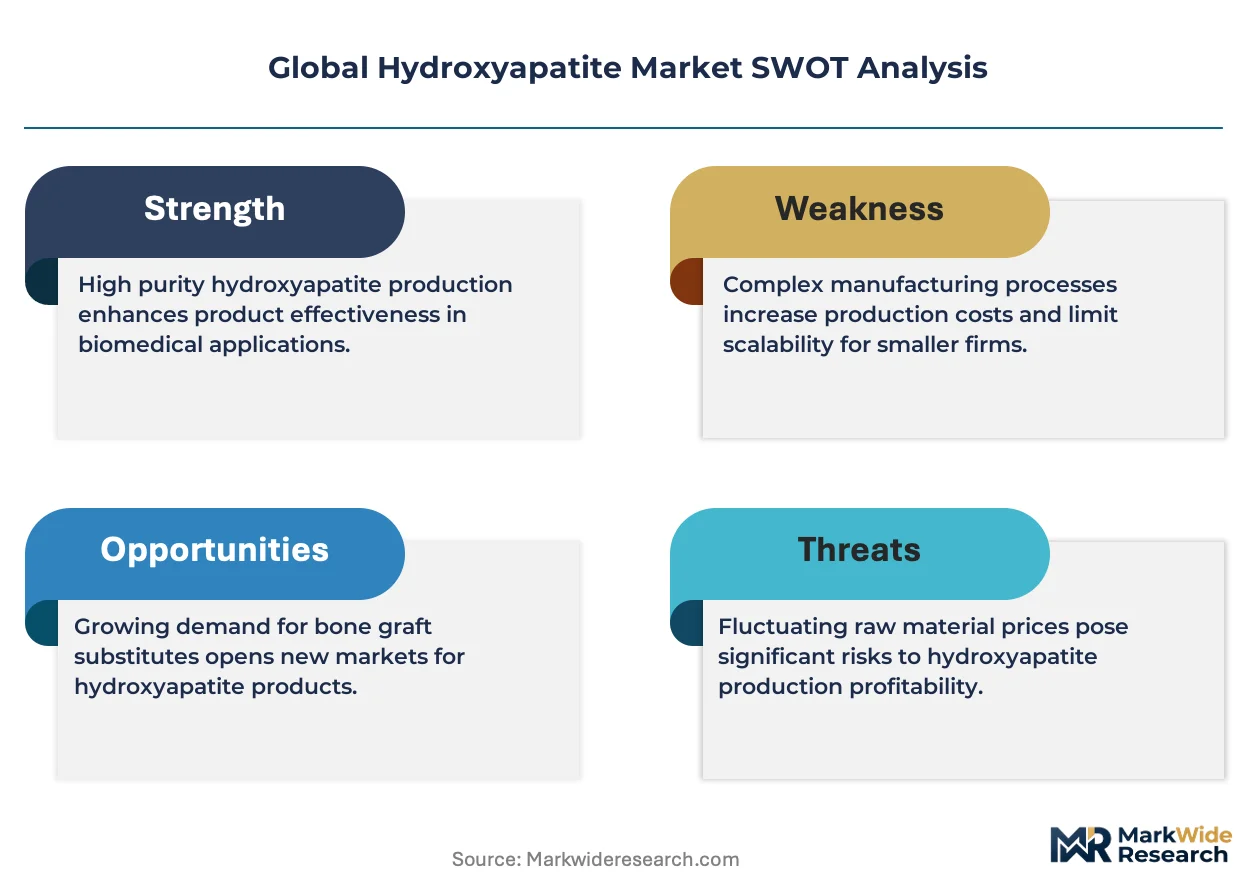
Moroccan phosphate rock export pricing cascades through synthetic hydroxyapatite production into three distinct tiers: nanocrystalline coatings for orthopedic OEMs, spherical granules for dental manufacturers, and commodity powder for research supply. Feedstock volatility from concentrated North African supply compresses margins at the base while premium grades capture pricing power through FDA master file control and EU MDR certification barriers.
Pricing Analysis
Bundled coating services versus unbundled powder supply splits pricing architecture across the value chain. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and crystalline architecture differentiation. Price differentiation stems from ISO 10993 biocompatibility tier and volume scale commitments in multi-year hospital purchasing agreements. Cost compression in synthetic powder intensifies because Moroccan phosphate rock volatility feeds directly into feedstock costs. Dental laboratories and research institutes exhibit highest price sensitivity, while orthopedic OEMs with captive coating operations demonstrate lowest sensitivity due to quality-locked specifications.
Supply Chain Analysis
Domestic-content mandates under the US IRA manufacturing incentives and India's PLI scheme for medical devices are reshaping sourcing patterns toward localized nanocrystalline synthesis. Supply concentrates in Morocco for phosphate rock, China for synthetic powder conversion, and Japan for implant-grade coating formulation. Raw material dependencies rest on phosphate rock, calcium carbonate precursors, and specialized spray-drying equipment. Single-source vulnerability runs through Moroccan phosphate rock concentration given OCP's global market position. Distribution runs through regional hospital purchasing cooperatives in Germany and Japan, consolidated GPO contracts in the United States, and fragmented dental laboratory networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydroxyapatite market represents a late-cycle quality story as orthopedic manufacturers shift procurement toward electrochemically deposited nanocrystalline specifications with superior osseointegration performance. This specification upgrade favors producers with established FDA master files and EU MDR technical documentation libraries.
For Market Incumbents: Lock in supply security through backward integration into phosphate rock conversion or captive nanocrystalline synthesis capacity. Defend against electrochemical deposition technology decentralization by deepening hospital purchasing cooperative relationships and accelerating ISO 10993 certification investments for next-generation coating formulations. For New Entrants and Emerging Players: Electrochemical deposition equipment-as-a-service models offer a technology-first wedge into mid-sized orthopedic manufacturers in Germany and the United States seeking in-house coating capabilities. Target India's underpenetrated joint replacement market where domestic coating capacity lags procedure growth at Apollo and Fortis networks. Pursue scaffold hybridization partnerships with Boston and Berlin biomedical startups as the go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with nanocrystalline synthesis specialists possessing established FDA master files and EU MDR certification libraries. Long-term viability centers on producers capable of spanning orthopedic, dental, and tissue engineering applications through formulation flexibility. Watch PMDA QMS ordinance enforcement patterns in Japan as the inflection indicator for regulatory compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Master File Expansion | Accelerates 510(k) pathway access for orthopedic OEM partners seeking predicate device alignment. |
| EU MDR Certification Investment | Extends notified body review cycles but filters substandard competitors from permanent implant classifications. |
| Electrochemical Deposition Scale-Up | Decentralizes coating production away from centralized plasma spray facilities toward mid-tier manufacturers. |
| Phosphate Rock Backward Integration | Insulates margin structures from Moroccan supply concentration and feedstock price volatility. |
| Hospital Purchasing Cooperative Partnership | Secures multi-year supply agreements through consolidated procurement in Germany and Japan. |
Research Methodology
Direct dialogue with orthopedic implant procurement directors, biomedical R&D leads, dental laboratory purchasing managers, and regulatory affairs specialists at notified bodies grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EMA CE marking databases, Japanese PMDA QMS ordinance guidance, hospital GPO contract disclosures, and phosphate rock trade flow records. Bottom-up and top-down triangulation cross-checked volume estimates against capacity disclosures and procedure volume demographics.
Bottom-up modeling of nanocrystalline coating consumption per joint replacement procedure converged with top-down phosphate rock conversion capacity analysis across the projection horizon. Segmentation dimensions spanned product form, crystalline architecture, application, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories, reimbursement code evolution, and technology substitution curves for coating deposition methods. Forecast inputs incorporated EU MDR implementation pace and IRA domestic production incentive uptake.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to phosphate rock price volatility, PMDA enforcement stringency, and electrochemical deposition technology diffusion rates. Forecasts reflect documented assumptions regarding procedure volume growth, regulatory compliance cost trajectories, and technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
US Heparin Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Calcium Phosphate Market
Biomaterials
Polysaccharide Hemostatic System Market
Biomaterials
Global Extracellular Matrix Patches Market
Biomaterials
Global Collagen Meniscus Implants Market
Biomaterials
Global Biomaterials Market
Biomaterials
Chitosan Oligosaccharides Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Bone Distractors Market
Biomaterials
North America Chitosan Market
Biomaterials
Global Bioactive Materials Market
Biomaterials
Bone and Joints Ingredients Market