
 Biomaterial in Surgical Mesh Market | 2026-2036
Biomaterial in Surgical Mesh Market Size, Share, and Industry Trends Forecast 2026-2036
Biomaterial in Surgical Mesh Market Outlook
Biomaterials engineering talent is bifurcating between polymer synthesis specialists and regenerative-mesh designers, creating divergent R&D pipelines across the industry. Medtronic leverages its integrated surgical ecosystem to sustain high-volume polypropylene mesh supply chains. W. L. Gore & Associates differentiates through expanded polytetrafluoroethylene composites that dominate soft-tissue reconstruction niches. B. Braun Melsungen AG anchors European hospital procurement networks with standardized hernia repair kits.
Biomaterial in surgical mesh refers to implantable scaffolds—woven, knitted, or non-woven structures typically 0.3–1.5 mm thick—engineered from synthetic polymers or biological substrates to reinforce fascial defects and promote tissue ingrowth while maintaining tensile strength exceeding 16 N/cm. Polypropylene meshes currently occupy the largest volume share due to cost efficiency and decades of clinical validation, though composite constructions integrating absorbable layers are capturing margin pools in premium pelvic floor repair. Electrospinning technology leads manufacturing innovation by producing nanofiber architectures with pore sizes below 50 μm that accelerate cellular colonization.
FDA 510(k) premarket notifications and EU MDR Class III implant requirements enforce biocompatibility testing under ISO 10993 protocols, elevating compliance costs but filtering substandard entrants from hospital tender processes. The EPA monitors perfluorinated compound emissions from expanded PTFE manufacturing, pressuring Gore and similar suppliers toward closed-loop solvent recovery systems. Stakeholders must monitor how FDA breakthrough device designations for biofabricated meshes reshape reimbursement thresholds and competitive entry barriers.
Market Dynamics
EU MDR Class III implant documentation requirements are compressing the supplier base for permanent surgical meshes, forcing manufacturers to consolidate biocompatibility testing capabilities or exit European hospital tenders entirely.
Growth Catalysts
- Minimally invasive hernia protocols:General surgery departments in tertiary hospitals are standardizing laparoscopic mesh placement, expanding addressable procedure volumes across the United States, Germany, and China.
- FDA 510(k) pathway clarity:Streamlined premarket notification frameworks for polypropylene-based devices accelerate time-to-market for incremental mesh iterations.
- ISO 10993-18 chemical characterization:Updated biocompatibility testing standards create competitive moats for laboratories with advanced extractables-leachables capabilities.
Market Restraints
- Perfluorinated compound input costs:EPA emissions monitoring of expanded PTFE manufacturing elevates solvent recovery capital expenditure for Gore-type composite suppliers.
- Single-source electrospinning equipment:Nanofiber architecture production depends on concentrated European and Japanese precision machinery vendors.
- Permanent implant liability exposure:Long-term biocompatibility litigation risk constrains insurer appetite for novel biomaterial platforms.
Strategic Opportunities
- Pelvic floor reconstruction underpenetration:Absorbable-layer composite meshes capture premium positioning in urogynecological applications where polypropylene alone faces clinical skepticism.
- Biofabricated mesh breakthrough designation:FDA breakthrough device pathways for cell-seeded scaffolds reshape reimbursement thresholds and competitive entry barriers.
- Closed-loop solvent recovery:Environmental compliance technology convergence creates differentiation for PTFE manufacturers facing EPA enforcement.
Industry Challenges
- Polymer synthesis-regenerative design talent bifurcation:R&D teams struggle to recruit hybrid specialists bridging traditional materials engineering with tissue engineering protocols.
- EU MDR technical documentation timelines:Class III implant certification cycles extend 18-24 months, compressing product refresh cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomaterial in Surgical Mesh Market |
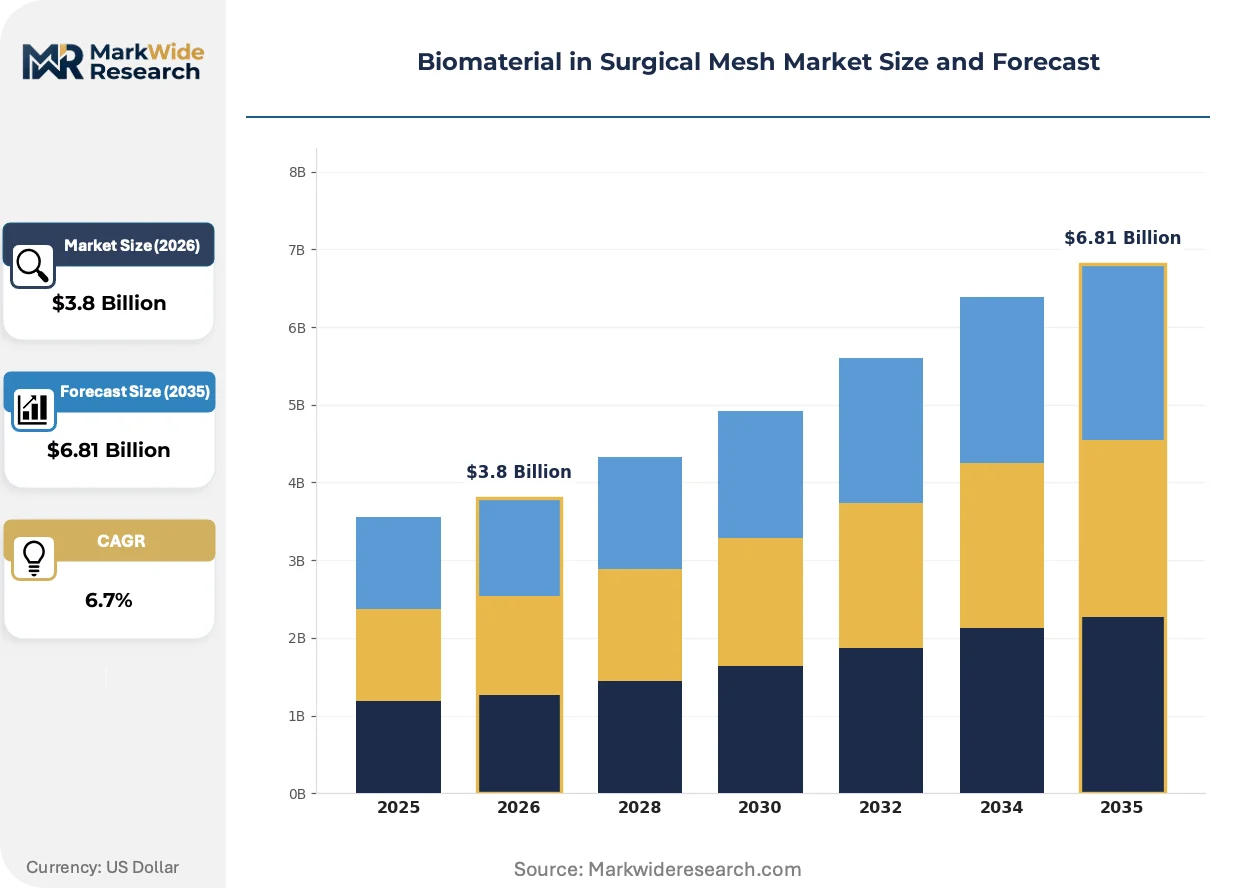
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyglycolic Acid, Polyethylene, Composite End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: Hernia Repair, Pelvic Floor Repair, Tissue Reconstruction, General Surgery Technology: 3D Printing, Electrospinning, Coating Techniques, Biofabrication |
| Companies Covered | Medtronic, Ethicon, B. Braun Melsungen AG, W. L. Gore & Associates, LifeCell Corporation, Cook Medical Inc, Atrium Medical, Baxter International Inc, Integra LifeSciences Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomaterial in Surgical Mesh Market Strategic Shifts
Electrospinning nanofiber architectures and bioabsorbable composite layers are actively displacing monofilament polypropylene in premium surgical applications, while regulatory documentation burdens reshape which manufacturers can sustain European market access.
Nanofiber meshes produced via electrospinning technology feature pore architectures below 50 μm that accelerate cellular colonization and tissue integration. Pelvic floor reconstruction specialists and soft-tissue hernia repair centers are adopting these platforms for complex cases. This material transition is displacing conventional woven polypropylene in high-margin reconstructive niches where accelerated healing commands price premiums.
EU MDR technical documentation requirements for Class III permanent implants mandate expanded biocompatibility testing under ISO 10993 protocols. Manufacturers must submit comprehensive chemical characterization and biological evaluation reports that exceed previous CE-marking thresholds. Mid-tier mesh suppliers without captive testing laboratories are withdrawing from German and French hospital procurement networks rather than absorbing compliance cost escalation.
Hospital purchasing consortia are consolidating vendor panels around integrated surgical ecosystem suppliers. Standardized hernia repair kits bundling mesh, fixation devices, and instrumentation displace standalone mesh tenders. This concentration is most visible in United States IDN procurement and German hospital group purchasing, where procurement teams prioritize supply chain simplification over material innovation.
Biomaterial in Surgical Mesh Market Segmentation
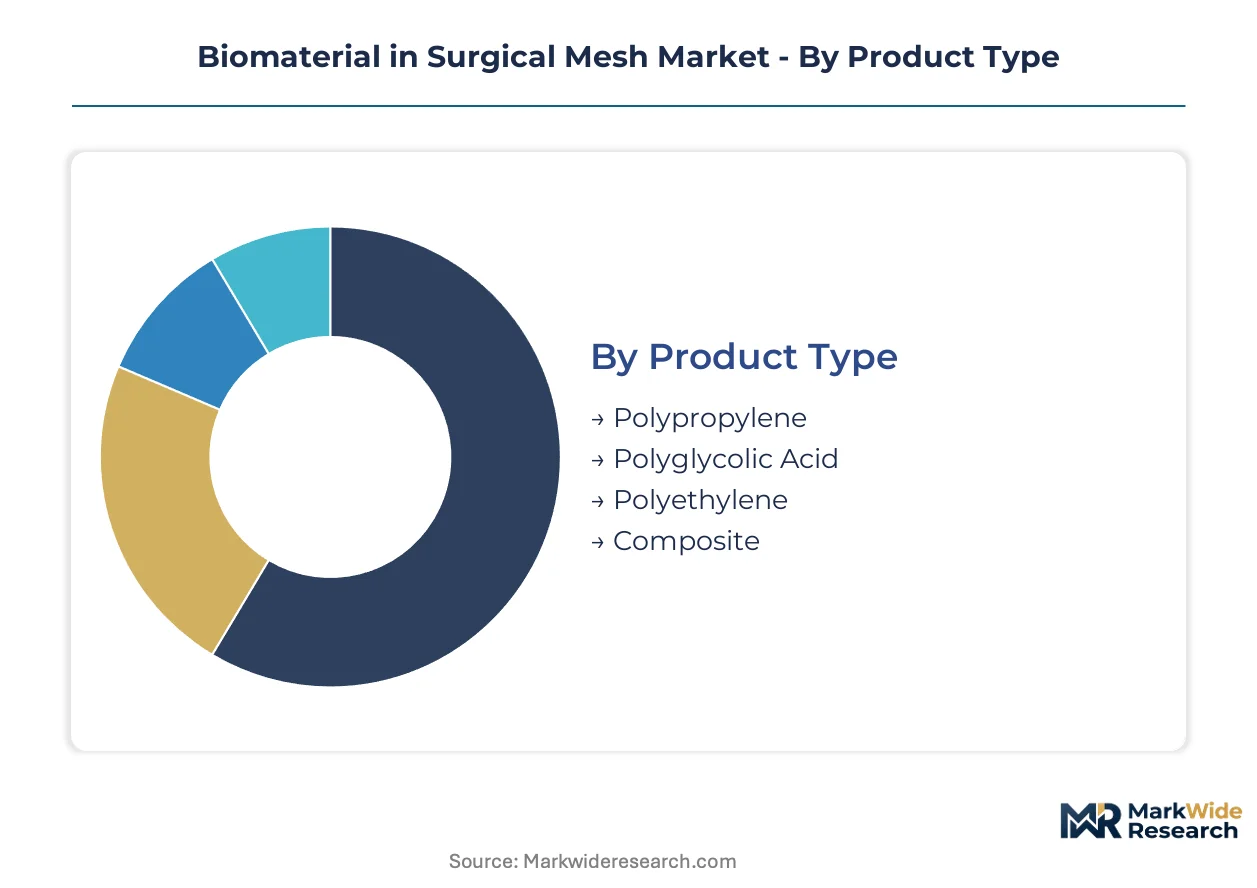
Surgical mesh segmentation reveals how material chemistry, manufacturing technology, and care setting economics create distinct competitive battlegrounds. Manufacturers must align R&D investment with the specific substitution pressures each segment faces from alternative repair modalities and emerging biomaterial platforms.
Product Type:
Polypropylene faces the most acute substitution pressure from bioabsorbable alternatives in pelvic floor applications, while composite constructions command premium positioning where permanent reinforcement conflicts with long-term biocompatibility concerns.
- Polypropylene:Woven or knitted monofilament structures deliver tensile strength exceeding 16 N/cm at the lowest per-unit cost. Demand concentrates in United States general surgery departments performing high-volume hernia repairs where decades of clinical validation offset material innovation pressure.
- Composite:Multi-layer architectures combine permanent synthetic substrates with absorbable coatings that modulate inflammatory response. German and French hospital procurement networks favor these platforms for complex pelvic floor reconstruction where polypropylene alone faces clinical skepticism.
- Polyglycolic Acid:Fully absorbable scaffolds eliminate permanent foreign body risk in pediatric and fertility-preserving applications.
- Polyethylene:High-density formulations offer intermediate strength-to-weight ratios for soft-tissue reinforcement niches.
Polypropylene anchors the volume base while composite constructions gain share at the steepest rate.
End User:
Cost tier stratification across care settings determines pricing power and kit bundling strategy, with hospital procurement consolidation squeezing standalone mesh margins.
- Hospitals:Tertiary medical centers in the United States, Germany, and China drive procedure volume through standardized laparoscopic protocols. IDN purchasing consortia bundle mesh with fixation devices and instrumentation, favoring suppliers with integrated surgical ecosystem capabilities.
- Ambulatory Surgical Centers:Same-day discharge requirements favor lightweight, macroporous meshes that minimize postoperative pain and accelerate return to activity. These facilities prioritize inventory efficiency over material innovation.
- Specialty Clinics:Urogynecology and hernia-focused practices seek differentiated products for complex revision cases.
- Research Institutions:Academic medical centers pilot biofabricated and patient-specific mesh architectures under FDA breakthrough device pathways.
Hospitals dominate absolute consumption while ambulatory surgical centers expand most quickly as procedure migration accelerates.
Application:
Volume concentration in hernia repair creates scale economies that subsidize development of higher-margin reconstructive specialties.
- Hernia Repair:Inguinal, ventral, and incisional hernia procedures constitute the dominant procedural category. Laparoscopic technique standardization in United States tertiary centers and Chinese provincial hospitals sustains demand for lightweight, large-pore polypropylene configurations.
- Pelvic Floor Repair:Urogynecological applications including stress urinary incontinence slings and prolapse meshes command premium pricing. Absorbable-layer composites displace pure polypropylene in this segment due to chronic pain litigation exposure.
- Tissue Reconstruction:Abdominal wall and chest wall defect repair requires customized mesh sizing and fixation approaches.
- General Surgery:Trauma and emergency applications prioritize immediate availability over material optimization.
Hernia repair anchors the volume base while pelvic floor repair commands the steepest margin expansion trajectory.
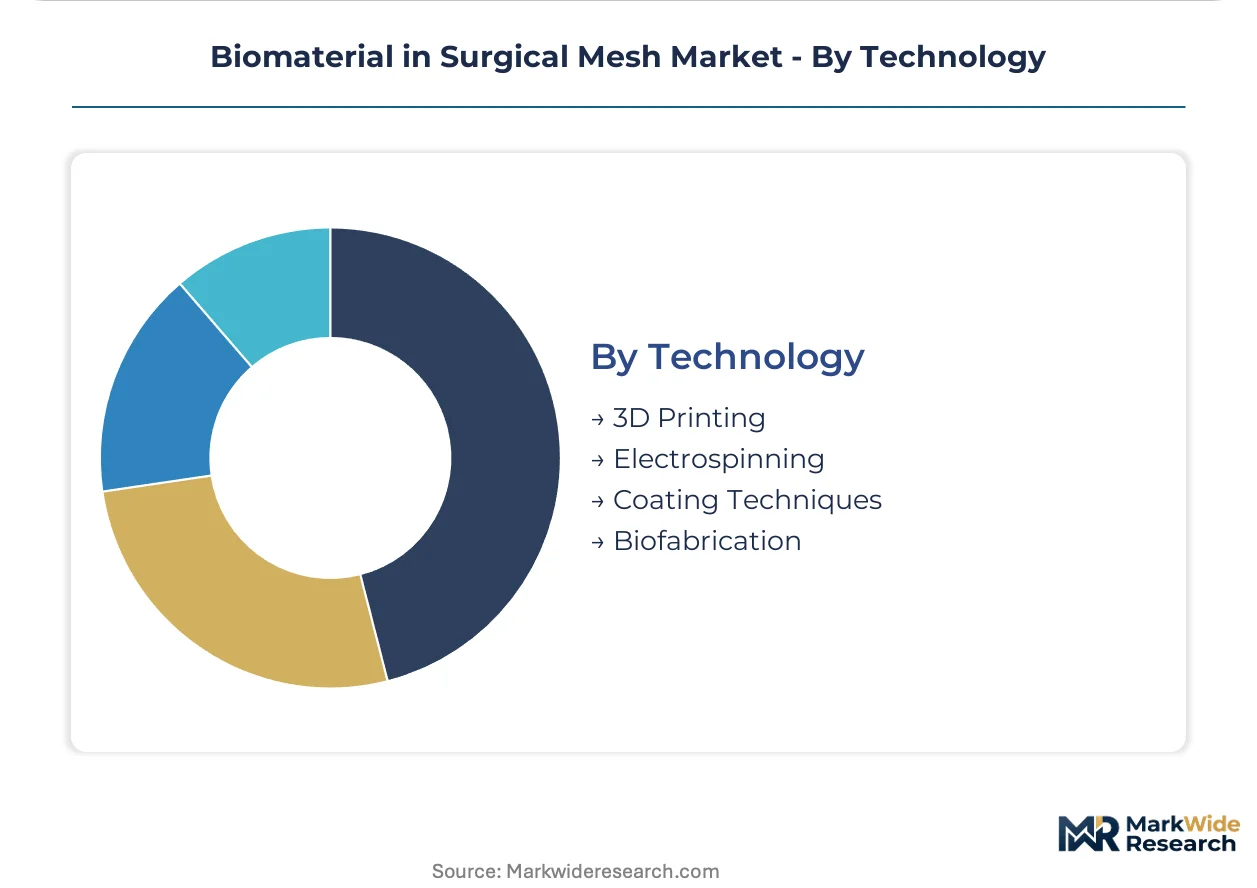
Technology:
Manufacturing process selection determines pore architecture precision, production scalability, and regulatory pathway complexity.
- Electrospinning:Nanofiber production achieves pore sizes below 50 μm that accelerate cellular colonization and tissue integration. Japanese and European precision machinery vendors control critical equipment supply, constraining capacity expansion for new entrants.
- 3D Printing:Patient-specific mesh geometries and gradient porosity architectures enable anatomical customization. Research institutions in the United States and Germany pilot these platforms for complex defect reconstruction.
- Coating Techniques:Surface modification with absorbable polymers or bioactive agents modulates tissue response without altering structural substrate.
- Biofabrication:Cell-seeded and decellularized extracellular matrix scaffolds represent the frontier of regenerative mesh design.
Electrospinning anchors current production volume while biofabrication climbs the fastest as FDA breakthrough designations reshape reimbursement thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes surgical mesh primarily through high-volume laparoscopic hernia protocols, while Germany and China concentrate demand in pelvic floor reconstruction and provincial hospital expansion respectively. This tripartite demand split shapes divergent procurement specifications and regulatory compliance investments across major markets.
United States
Integrated delivery networks in Texas and California drive consolidated purchasing of standardized hernia repair kits bundling mesh with fixation devices. FDA 510(k) premarket notification pathways streamline incremental polypropylene mesh iterations, compressing time-to-market for established suppliers. Minneapolis and Boston medical device clusters anchor electrospinning equipment distribution networks serving tertiary hospital systems.
Germany
Hospital group purchasing organizations in North Rhine-Westphalia and Bavaria prioritize composite mesh constructions for complex pelvic floor reconstruction cases. EU MDR Class III implant documentation requirements enforce ISO 10993 biocompatibility testing standards that filter mid-tier suppliers from tender processes. Tübingen and Aachen university hospitals pilot biofabricated scaffold architectures under breakthrough device pathways.
China
Provincial hospital networks in Jiangsu and Guangdong provinces scale minimally invasive surgical volumes through centralized procurement of lightweight polypropylene configurations. NMPA medical device registration requirements align with international biocompatibility standards while maintaining distinct clinical trial protocols for permanent implants. Shanghai and Suzhou manufacturing clusters supply electrospinning machinery to domestic mesh fabricators.
Japan
Metropolitan Tokyo and Osaka medical centers adopt nanofiber mesh platforms for soft-tissue reconstruction requiring accelerated cellular colonization. PMDA pharmaceutical and medical device agency reviews emphasize long-term biocompatility surveillance data for permanent implant approvals. Nagoya precision machinery vendors control critical electrospinning equipment supply constraining regional capacity expansion.
France
Paris and Lyon university hospital networks concentrate demand for absorbable-layer composite meshes in urogynecological applications. ANSM national drug safety agency monitors chronic pain litigation exposure from permanent polypropylene implants, shifting procurement toward bioabsorbable alternatives. Strasbourg medical technology clusters coordinate EU MDR technical documentation preparation for cross-border hospital tenders.
Biomaterial in Surgical Mesh Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with hospital procurement consolidation rewarding suppliers offering bundled surgical ecosystems. The upper tier commands integrated delivery network contracts through comprehensive fixation-and-mesh portfolios, while mid-cap specialists compete on material innovation in pelvic floor niches. Two strategic archetypes dominate: polymer synthesis majors leveraging scale economies in polypropylene supply, and regenerative-mesh designers capturing premium positioning in bioabsorbable composites. Competitive moves concentrate on backward integration into electrospinning equipment partnerships and geographic expansion through EU MDR certification acquisitions.
Within the integrated surgical ecosystem tier, Medtronic and Ethicon exemplify scale-driven hospital procurement consolidation through bundled kit offerings. W. L. Gore & Associates occupies a distinct position among composite material specialists, representing the expanded polytetrafluoroethylene architecture archetype that dominates soft-tissue reconstruction premium segments. These three anchors illustrate how divergent R&D pipelines—polymer synthesis versus regenerative design—create non-overlapping competitive territories within the same procedural categories.
| Leading Market Players |
|---|
| Medtronic |
| Ethicon |
| B. Braun Melsungen AG |
| W. L. Gore & Associates |
| LifeCell Corporation |
| Cook Medical Inc |
| Atrium Medical |
| Baxter International Inc |
| Integra LifeSciences Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance pathways and EU MDR Class III implant documentation simultaneously gate supply qualification and stratify price tiers across polypropylene, composite, and biofabricated mesh categories. Hospital procurement consortia exploit this dual filtering mechanism to compress margins on standardized hernia repair kits while absorbing premium pricing for nanofiber architectures with breakthrough device designations.
Pricing Analysis
Long-term offtake contracts dominate United States IDN procurement, with standardized hernia repair kits bundling mesh and fixation devices at volume-discounted rates. Price differentiation separates ISO 10993-certified composite constructions from commodity polypropylene tiers, with German and French hospital networks absorbing steeper premiums for absorbable-layer pelvic floor meshes. Cost compression in the polypropylene tier intensifies as Chinese provincial hospitals scale centralized purchasing, while specialty clinics demonstrate lowest price sensitivity for patient-specific 3D-printed architectures.
Supply Chain Analysis
Inventory lead times for electrospinning equipment extend 12-18 months due to concentrated supply from Japanese and German precision machinery vendors. Raw material sourcing draws from Saudi petrochemical feedstocks for polypropylene resin, Chinese fluoropolymer production for PTFE precursors, and Indian textile-grade polymer suppliers. Single-source vulnerability concentrates in European electrospinning equipment vendors, while distribution runs through hospital group purchasing organizations in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biofabricated mesh breakthrough device designations signal high-growth disruption, with FDA regulatory inflections reshaping reimbursement thresholds and competitive entry barriers across regenerative scaffold platforms.
For Market Incumbents: Shield core polypropylene volume positions by deepening backward integration into Saudi and Chinese resin supply chains. Anchor hospital procurement consolidation through captive ISO 10993 testing laboratories that accelerate EU MDR documentation cycles. Defend against nanofiber substitution by acquiring electrospinning equipment partnerships with Nagoya and Tübingen precision machinery vendors. For New Entrants and Emerging Players: FDA breakthrough device fast-track pathways for cell-seeded scaffolds offer the most penetrable regulatory entry point. Target underpenetrated pelvic floor reconstruction segments in French and German urogynecology networks where absorbable-layer composites command price premiums. Establish go-to-market positioning through academic medical center pilot programs rather than competing directly for IDN bundled kit contracts. For Investors and Strategic Acquirers: EU MDR Class III implant certification reshapes the acquisition landscape by elevating mid-tier suppliers with captive biocompatibility testing capabilities. Long-term viability centers on five-to-ten year regulatory compliance moats rather than near-term material innovation. Watch FDA reimbursement threshold decisions for biofabricated meshes as the primary inflection signal for portfolio rebalancing toward regenerative scaffold platforms.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Testing Laboratory Acquisition | EU MDR Class III documentation requirements filter competitors without captive biocompatibility capabilities from German hospital tenders. |
| Electrospinning Equipment Partnership | Nagoya and Tübingen precision machinery vendors control critical nanofiber production capacity expansion for soft-tissue reconstruction niches. |
| FDA Breakthrough Device Submission | Cell-seeded scaffold designations reshape reimbursement thresholds and competitive entry barriers in pelvic floor reconstruction segments. |
| Hospital System Partnership | United States IDN procurement consolidation rewards suppliers with integrated surgical ecosystems bundling mesh and fixation devices. |
| Closed-Loop Solvent Recovery Investment | EPA emissions monitoring of expanded PTFE manufacturing elevates environmental compliance differentiation for Gore-type composite suppliers. |
Study Parameters
Operator-level perspectives from hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and regulatory affairs leads anchored the qualitative base. Primary interview data triangulated against FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement contract registries, and CMS Medicare reimbursement schedules. Secondary validation drew from SEC 10-K medical device segment disclosures and ISO 10993 testing laboratory certification records. Bottom-up procedure volume estimates and top-down manufacturer revenue reconciliation converged across the analysis window.
Sensitivity analysis framed volume and value outputs across the projection horizon, modeling surgical mesh demand by material chemistry, manufacturing technology, care setting economics, and regional regulatory cluster. Segmentation dimensions spanned polypropylene versus composite versus biofabricated product types, hernia repair versus pelvic floor reconstruction versus tissue reconstruction applications, and tertiary hospital versus ambulatory surgical center versus specialty clinic end users. CAGRs derived from procedure migration trends, minimally invasive surgical volume scaling, and biomaterial substitution elasticity coefficients.
The analysis sits within stated boundaries; outcomes outside FDA breakthrough device reimbursement decisions, EU MDR enforcement intensity, or electrospinning equipment capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding biocompatibility litigation exposure, perfluorinated compound input cost trajectories, and hospital procurement consolidation velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Global Bioactive Materials Market
Biomaterials
Spine Surgery Gels Market
Biomaterials
US Heparin Market
Biomaterials
Global Extracellular Matrix Patches Market
Biomaterials
North America Chitosan Market
Biomaterials
Mushroom Materials Market
Biomaterials
United Kingdom Collagen Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Bone and Joints Ingredients Market
Biomaterials
Chitosan Oligosaccharides and Glucosamine Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Atelocollagen Market
Biomaterials
Pulp Cells Market
Biomaterials
Biomimetic Materials Market
Biomaterials
Scaffold Materials Market