
 Self-Healing Materials Market | 2026-2036
Self-Healing Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Healing Materials Market Intelligence
Aftermarket service revenue from structural repair and component overhaul is narrowing as embedded self-healing functionality displaces traditional maintenance cycles in high-value equipment. BASF SE anchors its position through captive supply of polymer precursors and catalyst systems. Evonik Industries AG differentiates via R&D intensity in microencapsulation chemistry. Covestro AG leverages its polyurethane expertise to dominate shape-memory polymer formulations for automotive applications.
Self-healing materials are engineered substances capable of autonomously repairing physical damage through embedded vascular networks, reversible chemical bonds, or microencapsulated healing agents triggered by mechanical stress or thermal activation. These materials typically achieve recovery efficiencies exceeding 80% of original tensile strength and serve primarily to extend operational lifespan while reducing scheduled maintenance in critical infrastructure. Polymer-based systems currently occupy the largest margin pool due to established processing infrastructure and tunable molecular architectures. Microcapsule technology leads commercial deployment, while conductive network approaches are gaining fastest in electronics applications where circuit continuity restoration commands premium pricing. The construction sector presents concentrated demand for concrete and coating systems, though aerospace qualification timelines slow adoption despite superior performance benchmarks.
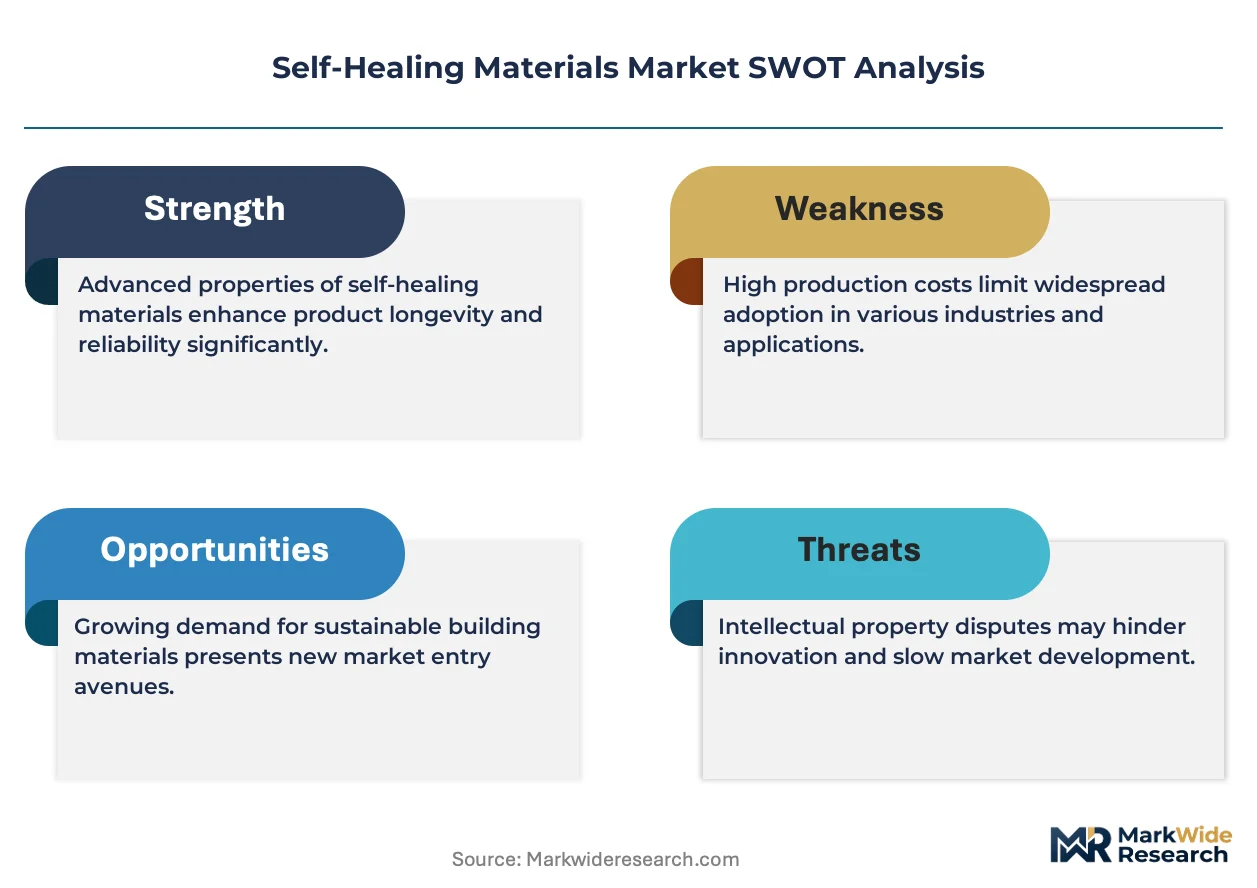
The EPA regulates volatile organic compound emissions from coating applications, pushing manufacturers toward solvent-free self-healing formulations. REACH compliance in Europe mandates extensive substance safety documentation, creating barriers for novel healing agent chemistries. FAA airworthiness standards govern incorporation of self-healing composites into commercial aircraft structures, requiring extensive fatigue testing protocols. Stakeholders must weigh certification investment against payback periods from reduced lifecycle maintenance as regulatory frameworks mature across jurisdictions.
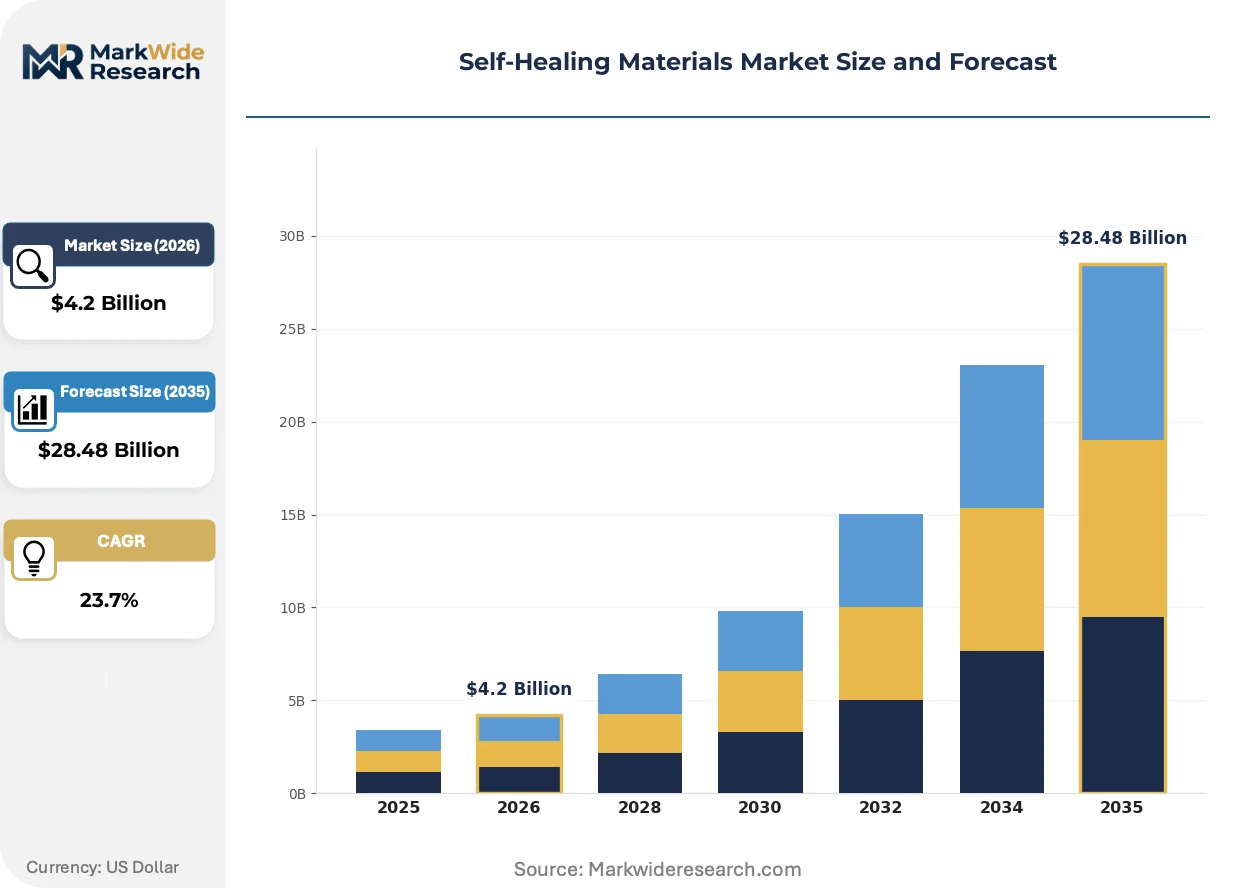
Market Dynamics
Aerospace qualification protocols compress supplier margins while embedding self-healing functionality into structural composites, forcing chemical conglomerates to absorb extended certification timelines before capturing commercial aircraft procurement cycles.
Growth Catalysts
- EU F-Gas Regulation:Tightening durability mandates for energy-intensive applications accelerate substitution toward self-healing coating systems in industrial refrigeration and HVAC infrastructure across Germany and France.
- Microencapsulation chemistry:Advances in shell-wall engineering enable controlled release of healing agents under mechanical stress, unlocking deployment in automotive underbody coatings and wind turbine blade leading edges.
- Cologne-Leverkusen corridor:Dense clustering of automotive OEMs and polymer precursor suppliers creates captive demand pull for shape-memory polyurethane systems in structural components.
Market Restraints
- Epoxy resin price volatility:Feedstock benzene and propylene cost swings destabilize margin structures for thermoset-based healing systems, particularly affecting small-batch specialty formulators.
- Catalyst supply concentration:Ruthenium and palladium sourcing dependence on South African and Russian mining operations exposes polymer producers to geopolitical supply interruptions.
- FAA fatigue testing protocols:Extensive airworthiness certification requirements for self-healing composites impose 4-7 year validation timelines that deter mid-cap suppliers from commercial aviation entry.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced materials manufacturing attract greenfield investment in self-healing concrete admixtures for infrastructure megaprojects in Gujarat and Maharashtra.
- Conductive network restoration:Integration of self-healing functionality into flexible electronics circuits addresses failure modes in wearable medical devices and foldable display interconnects.
- Japan METI carbon neutrality roadmap:Public procurement preferences for extended-lifecycle materials drive adoption of autonomously repairing coatings in offshore wind foundations and bridge superstructures.
Industry Challenges
- Multiphysics simulation expertise:Scarcity of computational chemists capable of modeling crack propagation and healing kinetics simultaneously slows formulation optimization cycles.
- Legacy coating infrastructure retrofit:Solvent-free self-healing formulations require capital-intensive conversion of existing spray application lines, straining mid-tier applicator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Healing Materials Market |
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $28.48 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polymer, Metal, Composite, Ceramic Application Sector: Automotive, Aerospace, Electronics, Construction End Use: Consumer Goods, Industrial Equipment, Healthcare Devices, Packaging Technology: Microcapsules, Conductive Networks, Shape Memory Polymers, Bio-inspired Systems |
| Companies Covered | Autonomic Materials Inc., Evonik Industries AG, BASF SE, Arkema S.A., The Goodyear Tire and Rubber Company, Covestro AG, NEI Corporation, AkzoNobel N.V., Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Healing Materials Market Strategic Shifts & Innovations
Digital twin integration and autonomous material response systems are compressing the feedback loop between damage detection and repair activation, shifting competitive advantage toward data-fluent chemical suppliers.
Vascular network self-healing architectures are virtualizing the traditional maintenance paradigm in critical infrastructure. Embedded hollow channels circulate liquid healing agents to damage sites under capillary or pump-driven flow. Civil engineering contractors in seismic zones adopt these systems for bridge column confinement. The technology is virtualizing scheduled inspection cycles into continuous autonomous monitoring regimes.
REACH substance safety documentation requirements are forcing reformulation of amine-based healing agents toward bio-derived alternatives. ECHA registration dossiers for novel microencapsulated chemistries demand extensive toxicological endpoint data. European coating formulators accelerate partnerships with biotechnology firms to secure compliant feedstock pipelines before 2027 substance evaluation deadlines.
Asset operators now specify total lifecycle cost rather than unit price in procurement tenders for protective systems. Engineering-procurement-construction firms unbundle coating application from material supply, inserting specialist self-healing integrators into project delivery chains. This restructuring concentrates most visibly in German automotive paint shops and Dutch offshore fabrication yards.
Self-Healing Materials Market Segmentation
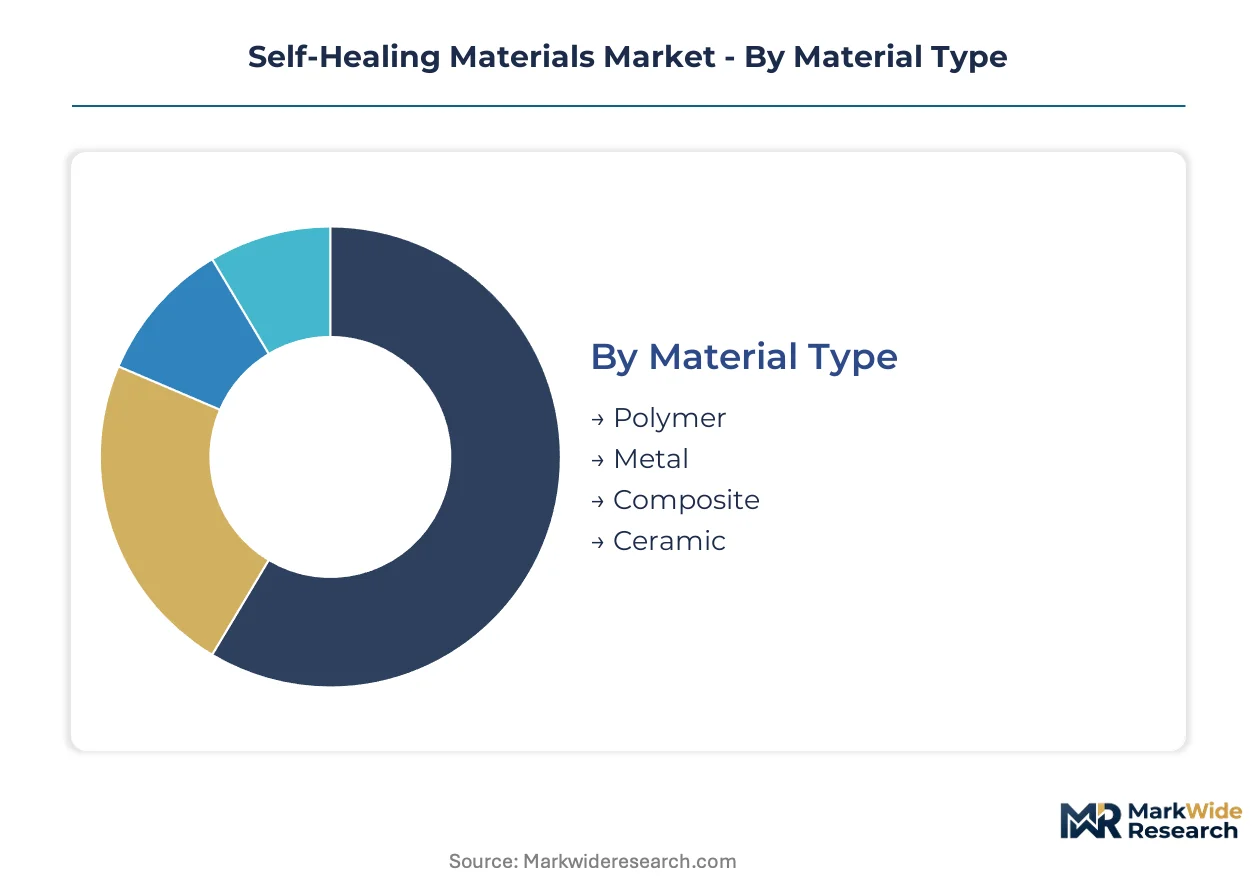
Segmentation in self-healing materials reveals distinct commercial rhythms. Polymer systems and microcapsule technologies command established revenue streams, while conductive networks and bio-inspired architectures compress development cycles for electronics and medical applications.
Material Type:
Cycle times vary dramatically across material classes, with polymer systems turning inventory fastest and ceramic formulations requiring longest qualification periods.
- Polymer:Tunable molecular architectures enable reversible chemical bonds and microencapsulated healing agents. BASF SE and Covestro AG concentrate production around Cologne and Leverkusen, feeding automotive OEM demand for shape-memory polyurethane structural components under EU Green Deal durability mandates.
- Composite:Self-healing carbon fiber and glass fiber systems embed vascular networks for aerospace structural airframe applications. FAA fatigue testing protocols impose extended validation timelines that compress supplier margins despite superior performance benchmarks in commercial aircraft procurement.
- Metal:Autonomous repair in aluminum and magnesium alloys relies on precipitation-hardening mechanisms triggered by thermal cycling.
- Ceramic:High-temperature oxide and carbide systems target turbine blade coatings and refractory linings with slowest commercialization trajectories.
Polymer anchors the volume base while composite gains share at the steepest rate.
Application Sector:
Cost tier separation distinguishes premium qualification-heavy sectors from high-volume standardized applications.
- Automotive:Underbody coatings and structural adhesives deploy microencapsulated healing agents for scratch and corrosion resistance. German OEM procurement concentrates in the Cologne-Leverkusen corridor, where chemical conglomerates cluster to minimize logistics costs for just-in-time paint shop delivery.
- Construction:Self-healing concrete admixtures and protective coatings address crack remediation in bridge superstructures and offshore wind foundations. Japan METI carbon neutrality procurement preferences accelerate adoption for extended-lifecycle infrastructure materials.
- Aerospace:Structural composite qualification demands intensive fatigue testing under FAA airworthiness standards.
- Electronics:Flexible circuit interconnects and wearable device housings exploit conductive network restoration for failure mode mitigation.
Construction commands the broadest installed base while electronics climbs the fastest as foldable display and medical wearable markets expand.
End Use:
Customer type fragmentation separates specification-driven industrial procurement from price-sensitive consumer markets.
- Industrial Equipment:Wind turbine blade leading edges and HVAC heat exchangers utilize vascular network architectures for continuous damage repair. EU F-Gas Regulation tightening drives substitution toward self-healing coating systems in energy-intensive refrigeration infrastructure across Germany and France.
- Healthcare Devices:Implantable sensors and drug delivery systems integrate bio-compatible microcapsules for autonomous material response. REACH compliance mandates extensive substance safety documentation, forcing partnerships with biotechnology firms for amine-free healing agent feedstocks.
- Consumer Goods:Scratch-resistant smartphone housings and athletic footwear midsoles target premium pricing tiers.
- Packaging:Barrier film integrity restoration addresses food and pharmaceutical shelf-life extension requirements.
Industrial equipment generates the most concentrated contract value while healthcare devices show the steepest expansion trajectory on regulatory tailwinds.
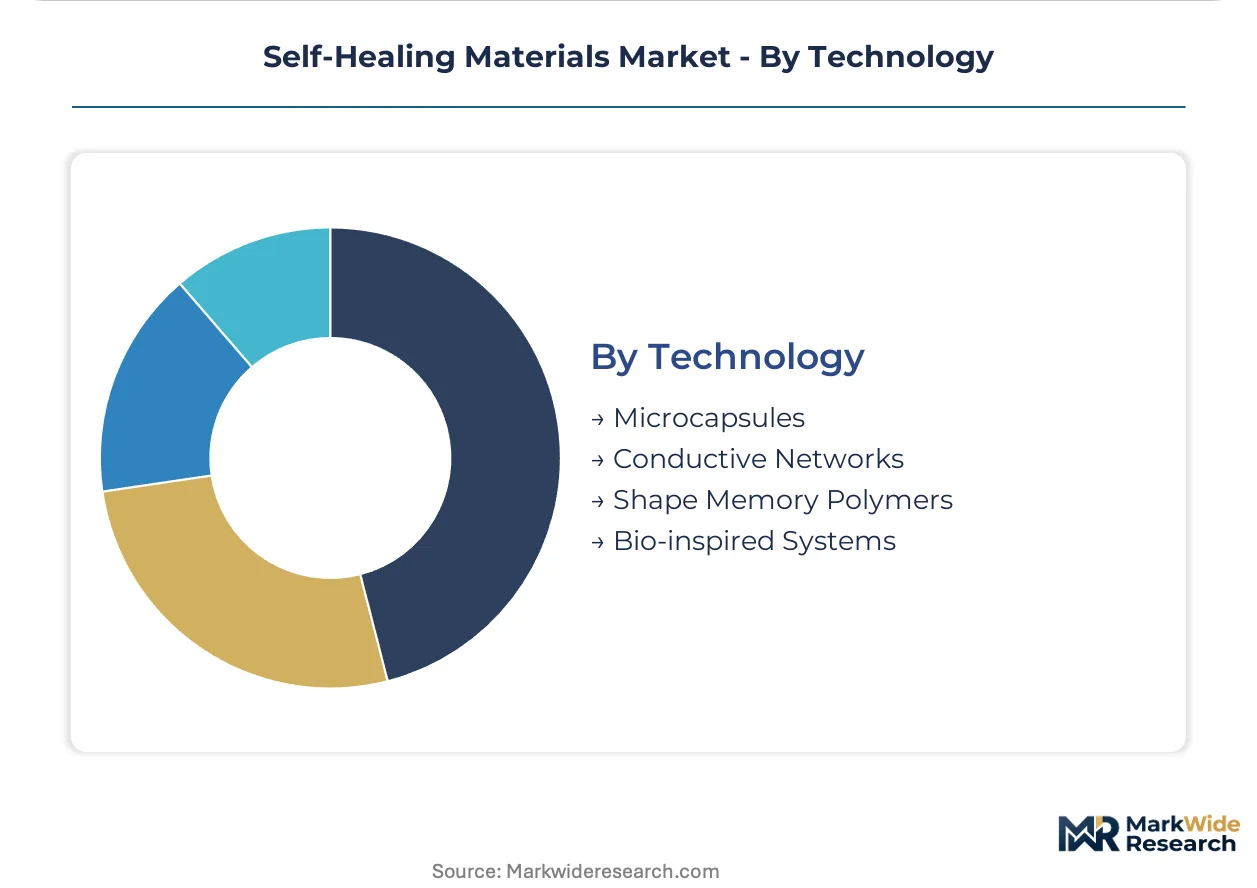
Technology:
Supply concentration varies sharply, with microcapsule production scaling through established chemical infrastructure and bio-inspired systems remaining captive to specialized R&D facilities.
- Microcapsules:Shell-wall engineering advances enable controlled release of epoxy and amine healing agents under mechanical stress. Evonik Industries AG differentiates through R&D intensity in microencapsulation chemistry, supplying automotive underbody and wind turbine blade coating formulators.
- Conductive Networks:Self-restoring circuit pathways in silver nanowire and carbon nanotube composites address interconnect failure in foldable displays. Premium pricing for electronics continuity restoration attracts materials suppliers with multiphysics simulation capabilities.
- Shape Memory Polymers:Polyurethane formulations dominate automotive structural applications through thermally activated recovery.
- Bio-inspired Systems:Bacterial spore and enzyme-embedded matrices target concrete crack healing with longest development timelines.
Microcapsules retain the dominant revenue position while conductive networks expand most quickly on electronics miniaturization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Germany concentrates procurement in automotive structural applications under EU Green Deal mandates. Japan prioritizes infrastructure longevity for seismic resilience. The United States drives aerospace qualification timelines. India channels investment toward construction megaprojects through production-linked incentives.
Germany
Automotive OEMs and chemical conglomerates cluster around Cologne and Leverkusen for just-in-time paint shop delivery of shape-memory polyurethane systems. EU F-Gas Regulation tightening accelerates substitution toward self-healing coating systems in industrial refrigeration infrastructure. BASF SE and Covestro AG anchor captive supply chains for polymer precursors and catalyst systems serving structural component manufacturers.
United States
Aerospace manufacturers expand procurement of self-healing composites for structural airframe components despite extended validation timelines. FAA fatigue testing protocols impose 4-7 year airworthiness certification requirements that compress supplier margins. The EPA regulates volatile organic compound emissions from coating applications, pushing manufacturers toward solvent-free formulations.
Japan
METI carbon neutrality procurement preferences drive adoption of autonomously repairing coatings in offshore wind foundations and bridge superstructures. Engineering-procurement-construction firms unbundle coating application from material supply, inserting specialist integrators into project delivery chains. Asset operators specify total lifecycle cost rather than unit price in infrastructure tenders.
India
Production-linked incentives for advanced materials manufacturing attract greenfield investment in self-healing concrete admixtures for infrastructure megaprojects in Gujarat and Maharashtra. The national PLI scheme channels public capital toward extended-lifecycle materials for energy-intensive applications. Civil engineering contractors adopt vascular network architectures for seismic zone bridge column confinement.
France
Industrial refrigeration and HVAC infrastructure operators substitute toward self-healing coating systems under EU F-Gas Regulation durability mandates. ECHA registration dossiers for novel microencapsulated chemistries demand extensive toxicological endpoint data. Coating formulators accelerate partnerships with biotechnology firms to secure REACH-compliant feedstock pipelines before substance evaluation deadlines.
Self-Healing Materials Market Key Industry Players
Capability concentration sits with R&D-intensive specialists; scale advantage sits with diversified chemical conglomerates. The market structures around three tiers: global diversifieds with captive precursor supply, mid-cap technology licensors, and application-specific integrators. Two competitive moves dominate: backward integration into polymer precursor production and strategic partnerships with biotechnology firms for REACH-compliant healing agent feedstocks.
Among Germany-based chemical conglomerates, BASF SE, Evonik Industries AG, and Covestro AG occupy distinct archetype positions. BASF SE anchors the diversified precursor supply tier through captive production of polymer feedstocks and catalyst systems. Evonik Industries AG exemplifies the R&D-intensive specialist model with concentration in microencapsulation chemistry. Covestro AG represents the polyurethane formulation leader leveraging shape-memory polymer expertise for automotive structural applications.
| Leading Market Players |
|---|
| Autonomic Materials Inc. |
| Evonik Industries AG |
| BASF SE |
| Arkema S.A. |
| The Goodyear Tire and Rubber Company |
| Covestro AG |
| NEI Corporation |
| AkzoNobel N.V. |
| Dow Inc. |
| Others |
Cost & Logistics Intelligence
The Cologne-Leverkusen corridor concentrates polymer precursor production capacity, feeding captive supply chains that lock in pricing power for automotive OEM procurement of shape-memory polyurethane systems under EU Green Deal durability mandates.
Pricing Analysis
Long-term offtake agreements dominate aerospace composite procurement, while spot purchasing persists for construction-grade concrete admixtures. Price differentiation separates FAA-certified structural systems from uncertified industrial coatings. Cost compression in thermoset-based healing systems intensifies due to benzene and propylene feedstock volatility. Small-batch specialty formulators exhibit highest price sensitivity; aerospace OEMs demonstrate lowest sensitivity given lifecycle cost specifications.
Supply Chain Analysis
Contract manufacturing for microencapsulated healing agents concentrates at Evonik Industries AG facilities in Germany and Arkema S.A. operations in France. Raw material sourcing draws from South African ruthenium mines and Russian palladium operations for catalyst systems, alongside German benzene crackers for polymer feedstocks. Geopolitical supply interruption risk sits with precious metal concentration. Distribution runs through captive direct supply to automotive paint shops and specialist integrators for infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Self-healing materials face substitution pressure from extended-warranty service contracts and predictive maintenance analytics that extend equipment lifecycles without embedded repair functionality. Incumbents must navigate this threat through capability deepening.
For Market Incumbents: Build regulatory certification moats by accelerating FAA airworthiness validation timelines before mid-cap suppliers achieve entry. Backward integration into polymer precursor production secures margin control against benzene price swings. Threat from bio-derived healing agent substitutes demands partnerships with biotechnology firms for REACH-compliant feedstock pipelines.
For New Entrants and Emerging Players: Pursue white-space opportunities in conductive network restoration for foldable electronics and wearable medical devices where circuit continuity commands premium positioning. India's PLI scheme for advanced materials manufacturing offers most penetrable geographic entry with public capital backing. Go-to-market angle should target specialist integrators unbundled from EPC delivery chains in Japanese offshore wind and bridge superstructure projects.
For Investors and Strategic Acquirers: Long-term, this sits as a materials-science consolidation play because R&D-intensive microencapsulation specialists face acquisition pressure from diversified chemical conglomerates seeking captive technology. Acquisition target archetype: mid-cap technology licensors with multiphysics simulation capabilities and existing FAA fatigue testing data packages. Signal to watch is aerospace procurement cycle inflection as extended validation timelines compress and commercial aircraft orders accelerate.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Production | In-house ruthenium and palladium processing reduces exposure to South African and Russian supply interruptions. |
| Long-term Supply Agreement with Automotive OEMs | Captive offtake from Cologne-Leverkusen corridor paint shops locks in volume for shape-memory polyurethane systems. |
| Joint Venture with Biotechnology Firms | Partnerships secure amine-free healing agent feedstocks ahead of ECHA substance evaluation deadlines. |
| Capacity Expansion in India | Greenfield investment in Gujarat and Maharashtra captures PLI scheme incentives for infrastructure megaproject supply. |
| Technology Licensing to Electronics Manufacturers | Silver nanowire and carbon nanotube composite patents monetize conductive network restoration demand. |
Research Approach
Desk research of customs trade data, SEC 10-K filings from chemical conglomerates, and ECHA registration dossiers preceded structured interviews with plant managers at polymer precursor facilities, procurement leads at automotive OEMs, technical R&D directors in microencapsulation chemistry, and aftermarket service heads at aerospace MRO providers. Bottom-up volume estimates from application-level consumption data triangulated against top-down market sizing from producer revenue disclosures.
Assumptions held fixed include current EU F-Gas Regulation durability mandates, FAA fatigue testing protocol timelines, and REACH substance safety documentation requirements; variables included benzene and propylene feedstock price trajectories, aerospace procurement cycle timing, and electronics miniaturization rates. The analytical framework modeled segmentation across material type, application sector, end-use category, and technology platform. CAGRs derived from logistic curve fitting to historical adoption patterns, with inputs from polymer processing capacity expansion schedules and infrastructure investment pipelines.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles, automotive production volumes, or precious metal mining output would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and certification timeline continuity. Quarterly review of ECHA substance evaluation progress, FAA airworthiness directive issuance, and automotive OEM paint shop procurement schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
North America Chitosan Market
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
Scaffold Materials Market
Biomaterials
Orthopedic Bone Defect Repair Materials Market
Biomaterials
Polysaccharide Hemostatic System Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Bone Substitutes Market
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Chitosan Market
Biomaterials
Global Hydroxyapatite Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Biomimetic Peptides Market
Biomaterials
Biomimetic Materials Market
Biomaterials
Europe Collagen Market
Biomaterials
Crocodile Peptide Market