
 Automated Lubrication Systems Market | 2026-2036
Automated Lubrication Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Lubrication Systems Market Insights
Buyer concentration among heavy equipment dealers and process equipment operators is restructuring procurement patterns across the Automated Lubrication Systems landscape. SKF Group leverages its bearing-service integration to capture bundled maintenance contracts in Nordic mining districts. Graco Inc. anchors North American market presence through channel control in construction machinery distribution. The Timken Company differentiates via R&D intensity in condition-monitoring-enabled lubrication architectures.
Automated lubrication systems are electromechanical or pneumatic networks that meter precise lubricant volumes to multiple friction points through progressive divider valves or dual-line manifolds, typically operating at pressures between 1,500 and 5,000 psi to prevent bearing wear and thermal seizure in continuous-duty machinery. Their primary commercial purpose is eliminating manual greasing labor while extending component life in inaccessible or hazardous equipment locations. Progressive systems dominate installed base volumes due to simpler architecture and lower fault-recovery complexity, while wireless control technology represents the fastest-expanding segment as remote diagnostics reduce field service costs. Dual line systems retain premium positioning in steel mill and cement kiln applications where line rupture tolerance justifies higher capital outlay.
OSHA lockout-tagout enforcement and EPA spill prevention requirements shape US product specifications toward sealed reservoir designs and leak detection integration. REACH chemical restrictions and EU F-Gas Regulation phase-down timelines compel European OEM manufacturers to validate biodegradable grease compatibility and eliminate pneumatic venting in food processing equipment. Machinery maintenance stakeholders must monitor evolving carbon border adjustment mechanisms and battery-operated system certification standards to avoid stranded capital in retrofit programs.
Market Dynamics
Wireless condition-monitoring integration is compressing maintenance cycles across heavy equipment fleets, forcing suppliers to bundle predictive analytics with hardware or surrender margin to third-party IoT platforms.
Growth Catalysts
- OSHA lockout-tagout enforcement:US manufacturing plants face escalating penalties for manual lubrication exposure incidents, accelerating capital approval for sealed automated systems in food processing and chemical handling facilities.
- Copper concentrate throughput expansion:Chilean and Australian mining operators are standardizing fleet-wide dual-line installations to eliminate unplanned crusher and conveyor downtime during 24-hour extraction cycles.
- Biodegradable grease formulation advances:European OEMs under REACH chemical restrictions are qualifying plant-based lubricants for progressive systems, opening food-grade and marine applications previously blocked by mineral oil contamination risks.
Market Restraints
- Specialized polymer seal input concentration:Fluoroelastomer O-ring supply concentrates among Japanese and German chemical processors, exposing system assemblers to 12-18 month order backlogs during raw material allocation shocks.
- Pneumatic system retrofit incompatibility:Legacy compressed-air infrastructure in aging US Midwest metalworking plants cannot support closed-loop grease circuits without compressor upgrades that double project capital intensity.
- Manual greasing labor substitution threshold:Small-scale Brazilian and Indonesian construction fleets operating below 40-unit thresholds cannot amortize automated system hardware costs against diesel mechanic wage differentials.
Strategic Opportunities
- Indian cement kiln underpenetration:Domestic producers running 5,000+ tpd clinker lines operate fewer than 15% of friction points on automated lubrication, presenting retrofit volume comparable to 1990s China expansion.
- EU F-Gas Regulation phase-down:Pneumatic venting elimination mandates in dairy and beverage processing create forced upgrade cycles for air-operated grease pumps, favoring electromechanical alternatives with integrated leak detection.
- Battery-electric construction equipment convergence:OEMs integrating lubrication controllers with electric drivetrain battery management systems can capture sole-source positions on next-generation excavator and loader platforms.
Industry Challenges
- Mechatronics technician scarcity:Progressive divider valve diagnostics require combined mechanical and PLC troubleshooting skills that vocational programs in Poland, Mexico, and Vietnam have not scaled to match installation growth.
- ISO 4406 cleanliness certification timelines:Hydraulic lubrication system suppliers face 14-18 month validation cycles for new reservoir designs, delaying revenue recognition on mining and wind turbine contracts.
- Legacy SCADA integration complexity:Brownfield steel mills and paper plants operate proprietary 1990s control architectures that resist standard Modbus or OPC-UA connectivity without middleware development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Lubrication Systems Market |
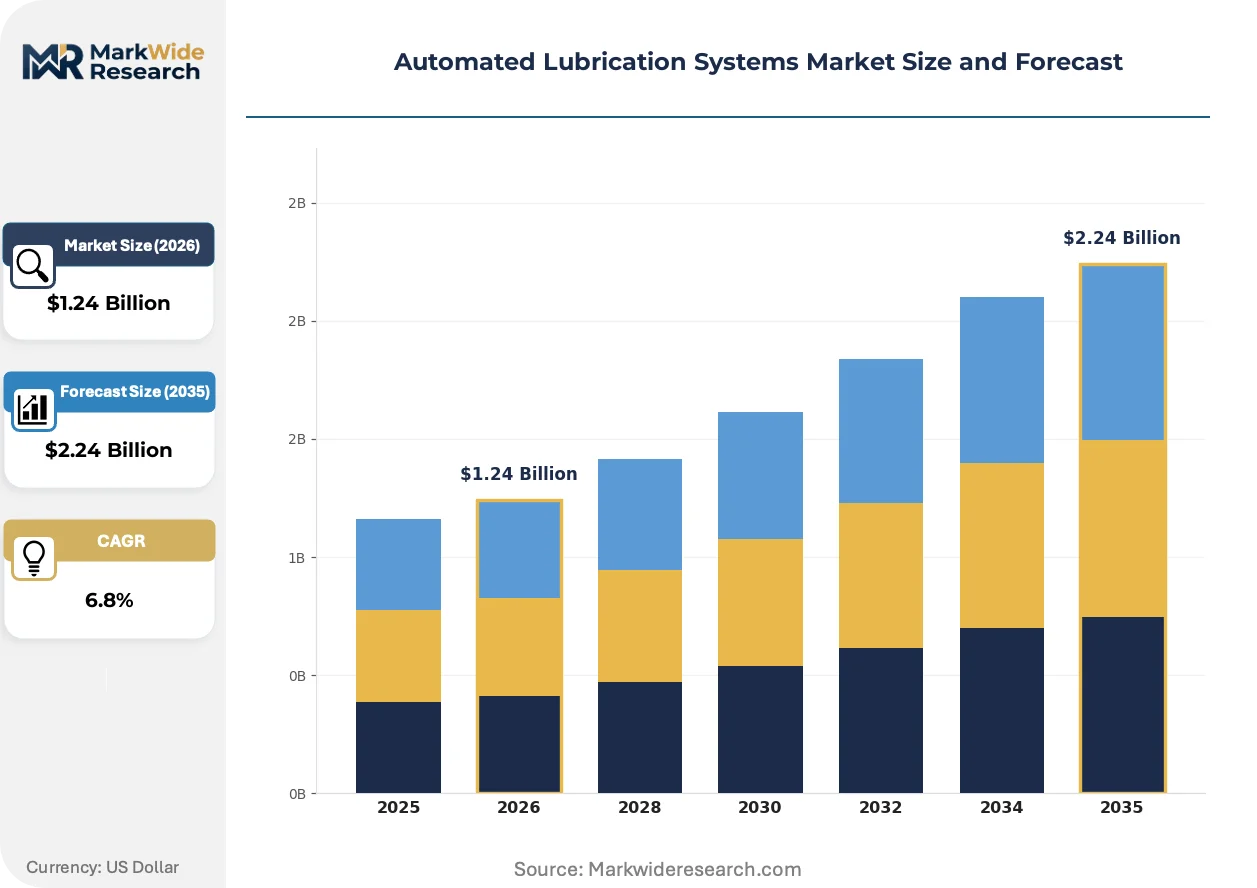
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Line Systems, Dual Line Systems, Progressive Systems, Multi-Point Systems, Automatic Grease Systems Technology: Electro-Mechanical, Pneumatic, Hydraulic, Battery Operated, Wireless Control Application: Construction Machinery, Food Processing Equipment, Textile Machinery, Mining Equipment, Metalworking Machines End User: OEM Manufacturers, Machinery Maintenance, Industrial Plants, Process Equipment Operators, Heavy Equipment Dealers |
| Companies Covered | SKF Group, Graco Inc., The Timken Company, Bijur Delimon International, Lincoln Industrial Corporation, Groeneveld-BEKA, DropsA S.p.A., Cenlub Systems, Trico Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Lubrication Systems Market Trends and Innovations
Sensor-enabled predictive maintenance architectures are displacing scheduled-interval lubrication protocols across capital-intensive process industries, compressing the value capture window for pure hardware suppliers.
Cloud-connected vibration-temperature hybrid sensors are expanding into progressive system manifolds, enabling real-time bearing health scoring that mining operators in Western Australia now specify as standard on new haul truck orders. SKF and Graco channel partners report retrofit attachment rates climbing fastest on equipment older than eight years where manual inspection intervals had lapsed. The technology is expanding into mid-tier construction equipment previously priced out of condition-monitoring coverage, compressing the addressable market for basic timer-based controllers.
EU F-Gas Regulation phase-down timelines are compelling pneumatic system redesigns across German dairy processing and Dutch cold-chain logistics facilities, eliminating vented air-operated pumps in favor of sealed electromechanical alternatives with integrated pressure transducers. ECHA enforcement of biodegradable grease compatibility is forcing lubricant suppliers to recertify entire product lines for progressive system compatibility, extending new product introduction cycles by 8-12 months. Food processing OEMs in Denmark and Italy are responding by consolidating supplier panels to those with in-house REACH compliance laboratories.
Maintenance outsourcing contracts are unbundling lubrication system ownership from equipment procurement, with German automotive stamping plants and US Gulf Coast petrochemical operators now leasing automated grease circuits on per-friction-point monthly fees. Equipment finance subsidiaries of bearing manufacturers are displacing traditional distributor credit terms, capturing decade-long service relationships through bundled hardware-fluids-diagnostics subscriptions. The shift is most visible in automotive component manufacturing corridors where just-in-time production tolerances leave no margin for unplanned spindle downtime.
Automated Lubrication Systems Market Segmentation
Automated lubrication system procurement hinges on friction point density, environmental exposure severity, and maintenance labor cost structures. Segment boundaries blur as wireless retrofit kits penetrate legacy electromechanical installations and food-grade specifications reshape hardware material selection.
Product Type:
Capital intensity and line rupture tolerance drive buyer selection between architectures, with mining operators prioritizing fault isolation over initial hardware cost.
- Progressive Systems:Sequential divider valves meter grease through interconnected metering pistons that stall the entire circuit if any point blocks, demanding simpler fault diagnosis than dual-line alternatives. Australian iron ore haul truck fleets specify these for conveyor bearings where single-point failure visibility outweighs redundancy needs.
- Dual Line Systems:Parallel supply and return lines enable isolated section shutoff during line breaks, justifying 40-60% higher capital outlay in steel mill continuous casters where thermal cycling risks hose rupture. Chilean copper concentrators mandate these for crusher main bearings operating under 24-hour extraction cycles.
- Single Line Systems:Direct pump-to-point architecture suits low-friction-count machinery in Indonesian palm oil processing where installation simplicity trumps precision metering.
- Multi-Point Systems:Centralized reservoir designs with spider distribution networks serve Polish automotive stamping presses with 50+ lubrication points per press line.
- Automatic Grease Systems:Self-contained cartridge units dominate Brazilian construction equipment retrofit where air compressor availability is unreliable.
Volume sits with Progressive Systems; growth tilts toward Dual Line Systems.
Technology:
Power source selection reflects infrastructure maturity and regulatory pressure on pneumatic venting, with electromechanical architectures displacing compressed-air alternatives in European food processing.
- Wireless Control:Battery-powered sensor nodes transmit pressure and flow data via LoRaWAN or cellular protocols, eliminating conduit installation in remote mining installations. Western Australian iron ore operators now specify these as standard on haul trucks older than eight years where manual inspection intervals had lapsed.
- Electro-Mechanical:Motor-driven piston pumps with programmable controllers deliver precise volume dosing independent of shop air quality, capturing German dairy processing upgrades under EU F-Gas Regulation phase-down mandates.
- Pneumatic:Compressed-air-driven diaphragm pumps retain cost advantage in US Midwest metalworking plants with legacy compressor infrastructure, though retrofit incompatibility limits expansion.
- Hydraulic:High-pressure circuits operating above 3,000 psi serve cement kiln support rollers in Indian clinker production where thermal expansion demands forceful grease penetration.
- Battery Operated:Portable units with rechargeable lithium-ion packs enable construction crane lubrication in Vietnamese port terminals without electrical infrastructure.
Electro-Mechanical dominates current procurement volumes; Wireless Control is expanding most quickly as remote diagnostics compress field service costs.
Application:
Equipment duty cycle severity and accessibility constraints determine specification grade, with continuous-process machinery commanding premium architectures over intermittent-use construction fleets.
- Mining Equipment:Gyratory crushers, rope shovels, and overland conveyors operate in abrasive dust environments that accelerate bearing wear without continuous lubrication. Australian and Chilean operators standardize fleet-wide automated systems to eliminate unplanned downtime during extraction peaks.
- Construction Machinery:Excavator booms, loader articulation joints, and crane slewing rings face intermittent duty cycles that complicate automated system payback calculations, limiting penetration to fleet operators above 40-unit thresholds.
- Food Processing Equipment:Mixers, conveyors, and packaging lines in Danish dairy plants require stainless steel construction and biodegradable grease compatibility under REACH chemical restrictions.
- Metalworking Machines:CNC machining center spindles and press brake pivot points in German automotive component corridors demand ISO 4406 cleanliness certification to maintain tolerance precision.
- Textile Machinery:High-speed spinning frames and knitting machines in Vietnamese fabric mills use low-viscosity oil mist systems distinct from grease-based heavy equipment architectures.
Mining Equipment captures the highest per-unit system value; Food Processing Equipment is gaining share fastest as regulatory compliance mandates accelerate replacement cycles.
End User:
Procurement authority fragmentation between equipment financiers, maintenance contractors, and operating plants is restructuring contract structures toward subscription-based lubrication service models.
- Industrial Plants:Petrochemical refineries along the US Gulf Coast and automotive stamping facilities in Germany's manufacturing corridor bundle automated lubrication into integrated maintenance contracts with decade-long service relationships.
- Process Equipment Operators:Cement producers running 5,000+ tpd clinker lines in India operate fewer than 15% of friction points on automated systems, presenting retrofit volume comparable to 1990s Chinese expansion.
- OEM Manufacturers:Construction equipment builders in Japan and South Korea integrate lubrication controllers with electric drivetrain battery management systems for next-generation excavator platforms.
- Machinery Maintenance:Outsourced service providers in Poland and Mexico face mechatronics technician scarcity that limits installation growth despite hardware availability.
- Heavy Equipment Dealers:Nordic mining districts and Australian iron ore regions see SKF Group and Graco Inc. channel partners capturing bundled bearing-service-lubrication contracts.
Industrial Plants anchor current revenue; Process Equipment Operators offer the steepest expansion trajectory as underpenetrated emerging market assets modernize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heavy equipment operators in Australia and Chile concentrate fleet-level procurement, while German automotive corridors and US Gulf Coast petrochemical hubs anchor industrial plant demand for sealed automated grease systems.
Australia
Iron ore haul truck fleets in Western Australia's Pilbara region specify wireless-enabled progressive systems for conveyor bearings older than eight years. TGA-equivalent mining safety enforcement mandates continuous lubrication on rope shovels and overland conveyors. Perth-based maintenance contractors bundle predictive diagnostics with hardware to capture decade-long service relationships.
Germany
Automotive stamping plants in Bavaria and Baden-Württemberg lease automated grease circuits on per-friction-point monthly fees under just-in-time production tolerances. EU F-Gas Regulation phase-down compels dairy processors to eliminate pneumatic venting in favor of sealed electromechanical pumps. Stuttgart's manufacturing corridor sees bearing manufacturers displacing distributor credit terms through equipment finance subsidiaries.
United States
Gulf Coast petrochemical refineries integrate automated lubrication into bundled maintenance contracts spanning ten-year horizons. OSHA lockout-tagout enforcement escalates penalties for manual lubrication exposure in food processing and chemical handling facilities. Houston's process equipment hub concentrates procurement authority among outsourced maintenance contractors.
Chile
Copper concentrators mandate dual-line installations for crusher main bearings operating under 24-hour extraction cycles. National mining regulators align with international machinery safety standards to eliminate unplanned downtime during throughput peaks. Antofagasta's extraction districts standardize fleet-wide automated systems across gyratory crushers and conveyor networks.
India
Cement producers running 5,000+ tpd clinker lines operate fewer than 15% of friction points on automated systems, presenting retrofit volume comparable to 1990s Chinese expansion. BIS machinery safety standards increasingly reference ISO 4406 cleanliness certification for hydraulic lubrication systems. Gujarat's cement belt and Maharashtra's industrial corridors concentrate underpenetrated process equipment assets.
Automated Lubrication Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wireless retrofit kits and condition-monitoring integration. The vendor base stratifies across three tiers: bearing-service integrators capturing bundled maintenance contracts, pump and fluid handling specialists controlling distribution channels, and component manufacturers differentiating through R&D intensity in sensor-enabled architectures. Consolidation pressure concentrates among mid-scale system assemblers facing fluoroelastomer supply constraints. Dominant competitive moves include backward integration into seal manufacturing and strategic partnerships with electric drivetrain OEMs.
Within the bearing-service integrator tier, SKF Group exemplifies bundled contract capture in Nordic mining districts. Graco Inc. anchors North American channel control in construction machinery distribution. The Timken Company occupies a position among R&D-intensive specialists developing condition-monitoring-enabled lubrication architectures. These three represent distinct strategic archetypes rather than overlapping competitive positions.
| Leading Market Players |
|---|
| SKF Group |
| Graco Inc. |
| The Timken Company |
| Bijur Delimon International |
| Lincoln Industrial Corporation |
| Groeneveld-BEKA |
| DropsA S.p.A. |
| Cenlub Systems |
| Trico Corporation |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap seal manufacturers in Germany and Japan anchor fluoroelastomer O-ring supply, creating 12-18 month order backlogs that prop pricing discipline for system assemblers during raw material allocation shocks. Equipment finance subsidiaries of bearing manufacturers now bundle hardware-fluids-diagnostics subscriptions, compressing distributor margins while capturing decade-long service relationships.
Pricing Analysis
Volume concentrates in progressive system hardware sold on per-unit transactional terms, while margin accrues to predictive analytics subscriptions and aftermarket service contracts. Three-tier pricing structure across premium, standard, and economy levels separates ISO 4406-certified mining architectures from basic timer-based controllers for construction fleets. Cost compression in pneumatic system tiers is intensifying because EU F-Gas Regulation phase-downs force electromechanical retrofits. Small-scale Brazilian and Indonesian construction operators below 40-unit fleet thresholds exhibit highest price sensitivity; German automotive stamping plants under just-in-time tolerances show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Australian iron ore fleets and Chilean copper concentrators, while construction machinery distribution runs through Graco-controlled North American dealer networks. Fluoroelastomer O-ring production draws from Japan and Germany; progressive divider valve machining centers on Poland and Mexico; stainless steel reservoir fabrication rests on Italian and Danish food-grade specialists. Single-source vulnerability concentrates in Japanese chemical processors during semiconductor industry raw material allocation cycles. Authorized distributor networks with captive service technicians dominate downstream structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluoroelastomer seal supply constraints prop pricing power, as 12-18 month order backlogs prevent rapid capacity response to demand surges.
For Market Incumbents: Hedge against wireless retrofit kit disruption by backward integration into sensor manufacturing or exclusive partnerships with IoT platform providers. SKF-style bundled maintenance contracts defend share against pure hardware commoditization. Captive seal production in Germany or Japan insulates margin from raw material allocation shocks. For New Entrants and Emerging Players: Capture Indian cement kiln retrofit volume where fewer than 15% of friction points run automated systems. Vietnamese and Indonesian construction fleets without air compressor infrastructure present battery-operated system white space. Lease-per-point financing models bypass upfront capital barriers for small-scale operators. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale system assemblers with stranded pneumatic inventory in EU dairy processing corridors. Long-term viability hinges on electromechanical architecture transition completion and REACH compliance laboratory accreditation. Watch fluoroelastomer order backlog duration as inflection signal for pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Manufacturing | Captive fluoroelastomer supply insulates SKF and Graco from Japanese chemical processor allocation shocks. |
| Wireless Retrofit Kit Development | LoRaWAN-enabled sensor nodes capture Western Australian haul truck aftermarket from timer-based controller incumbents. |
| REACH Compliance Laboratory Investment | In-house biodegradable grease validation accelerates European food-grade OEM qualification timelines. |
| Battery-Electric OEM Partnership | Lubrication controller integration with electric drivetrain BMS secures sole-source positions on next-generation excavators. |
| Per-Friction-Point Subscription Launch | Equipment finance subsidiaries displace distributor credit terms in German automotive stamping corridors. |
Research Methodology
SEC 10-K filings, EU F-Gas Regulation enforcement databases, and Australian TGA mining safety directives formed the secondary backbone, cross-referenced with primary interviews across maintenance directors at Chilean copper concentrators, plant engineers at German automotive stamping facilities, aftermarket service heads at Nordic bearing distributors, and OEM procurement teams at Japanese construction equipment builders. Bottom-up installation unit estimates triangulated against top-down industrial automation spend data.
Historical trendline analysis tracked progressive versus dual-line system mix shifts across mining and cement end uses. Segmentation dimensions modeled include product architecture, power source technology, equipment application, and end-user procurement authority. CAGRs derived from elasticity-adjusted replacement cycles and regulatory mandate acceleration effects. Forecast inputs incorporated REACH chemical restriction timelines and battery-electric construction equipment platform launch cadence.
The model holds under stable fluoroelastomer supply allocation and OSHA enforcement continuity; deviation in raw material shock severity or EU F-Gas phase-down acceleration would shift retrofit timing assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
China Automotive Actuators Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Global Automotive Sun Visor Market
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
Active Suspension Damper Actuator Systems Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Automotive Engine Connecting Rods Market
Automotive Components
Automotive Filters Market
Automotive Components
Automotive Stabilizer Bar Link Market
Automotive Components
United States Automotive Pneumatic Actuators Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Polyamide in E-Mobility Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
Europe Torque Vectoring Market