
 Luxury Electric Vehicle Market | 2026-2036
Luxury Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Electric Vehicle Market Outlook
Software-defined feature subscriptions is consolidating around recurring revenue models that transform one-time vehicle sales into lifetime customer relationships. BMW leverages its operating system layer to sustain aftermarket monetization across infotainment and autonomous functions. Lucid Motors anchors its position through proprietary drivetrain efficiency and over-the-air performance upgrades. Mercedes-Benz differentiates via integrated energy management services that extend beyond the vehicle to home and grid connectivity.
A luxury electric vehicle denotes a premium-priced battery electric automobile engineered with superior performance parameters, refined cabin materials, and advanced driver assistance systems, typically achieving acceleration from zero to sixty miles per hour in under four seconds while delivering ranges exceeding three hundred miles per charge. These vehicles serve affluent consumers and corporate fleets seeking zero-emission transportation without compromising comfort, status, or driving dynamics. Sedans occupy the established margin pool where brand heritage and aerodynamic efficiency command pricing power, while SUVs capture expanding demand from buyers prioritizing cabin space and commanding road presence. Solid-state battery technology represents the fastest-growing segment within battery chemistry, promising energy density improvements that could reshape range expectations and thermal management architectures across the competitive set.
The US EPA tailpipe emission standards and California Air Resources Board zero-emission vehicle mandates collectively compress the available market for internal combustion alternatives, directly enlarging the addressable base for battery-electric luxury offerings. China's MIIT new energy vehicle credit system and dual carbon goals impose production quotas that manufacturers must satisfy through premium electric lineups, accelerating localization of R&D and assembly capacity. The EU Green Deal transport decarbonization pathway and forthcoming Euro 7 standards tighten the regulatory noose on conventional powertrains across member states. Stakeholders must monitor how battery mineral supply agreements and charging infrastructure buildout timelines in key metropolitan corridors influence production scaling decisions and regional allocation strategies.
Market Dynamics
Solid-state battery chemistry is compressing charging cycles and extending range thresholds, forcing incumbents to reconfigure thermal management architectures and assembly lines ahead of mass production readiness.
Growth Catalysts
- EPA tailpipe emission standards:The US Environmental Protection Agency's tightening emission rules eliminate internal combustion alternatives in premium segments, directly enlarging the addressable base for battery-electric luxury offerings.
- Fleet electrification mandates:Corporate transport operators in Shenzhen, Shanghai, and Beijing are expanding procurement of premium electric sedans for executive mobility, creating concentrated demand from institutional buyers.
- Silicon-anode integration:Advanced anode materials are boosting energy density in existing lithium-ion architectures, bridging performance gaps while solid-state technologies mature.
Market Restraints
- Lithium supply concentration:Processing capacity and raw material extraction concentrate in limited geographic corridors, exposing manufacturers to price volatility and geopolitical supply disruptions.
- Charging infrastructure gaps:Metropolitan corridor buildout timelines lag production scaling decisions, creating regional allocation friction and demand suppression outside core urban clusters.
- Thermal runaway risks:Current-generation battery packs require complex cooling systems that add weight and cost, constraining packaging flexibility and vehicle architecture optimization.
Strategic Opportunities
- Software-defined subscriptions:Recurring revenue models transform one-time vehicle sales into lifetime customer relationships through over-the-air feature activation and autonomous function monetization.
- Vehicle-to-grid integration:Bi-directional charging capabilities position luxury EVs as distributed energy assets, opening revenue streams beyond mobility into home and grid connectivity services.
- Second-life battery applications:Degraded automotive battery packs retain substantial capacity for stationary storage, creating circular economy value recovery before recycling.
Industry Challenges
- Solid-state manufacturing scale-up:Dry electrode coating and ceramic electrolyte processing require entirely new capital equipment and process control expertise absent from incumbent lithium-ion operations.
- Software-hardware integration complexity:Autonomous driving stacks and infotainment operating systems demand talent pools spanning automotive embedded systems and consumer electronics development cultures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Electric Vehicle Market |
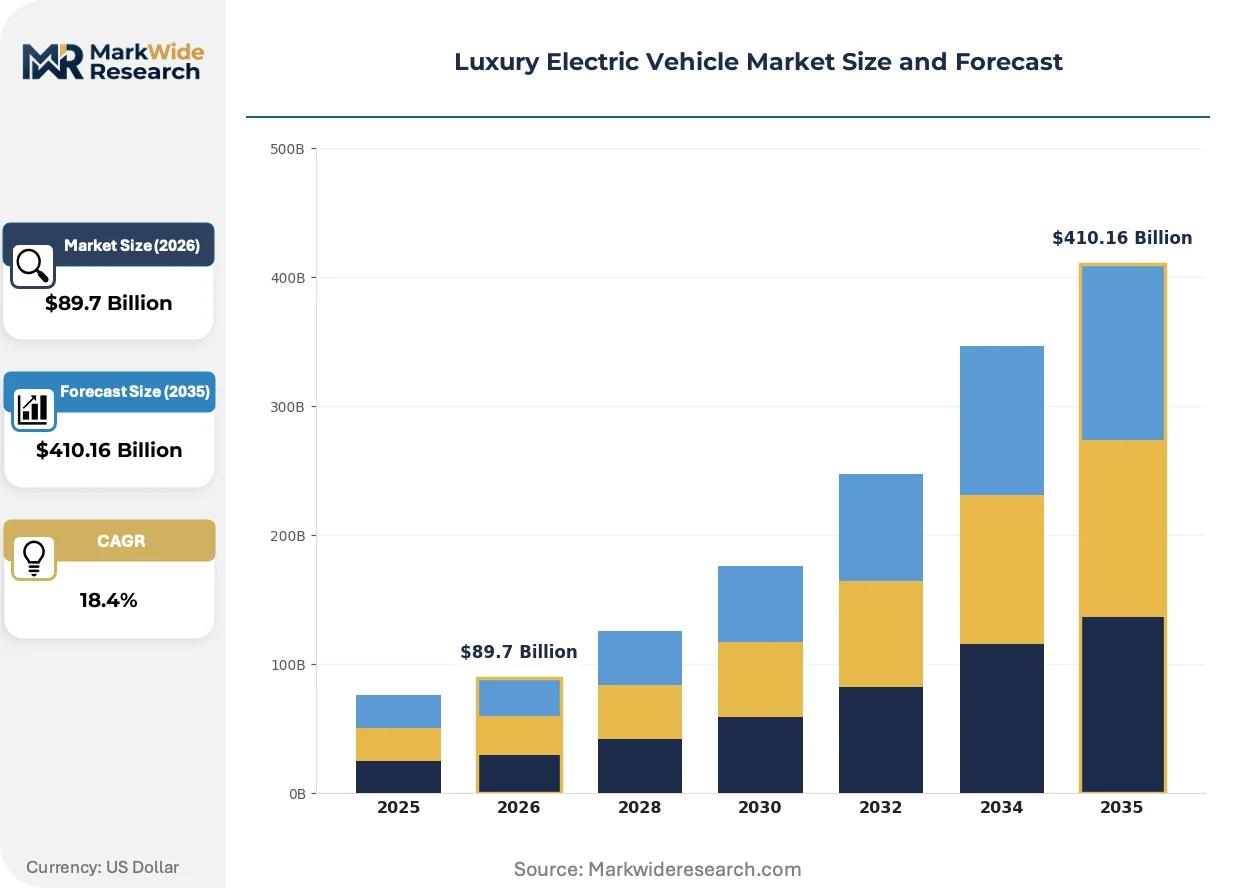
| Market Size in 2026 | $89.7 Billion |
| Market Size in 2035 | $410.16 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sedans, SUVs, Coupes, Convertibles Battery Technology: Lithium-Ion, Solid State, Nickel-Metal Hydride, Lithium Polymer Charging Infrastructure: Fast Charging Stations, Home Chargers, Superchargers, Wireless Charging End User: Individual Consumers, Fleet Operators, Rental Services, Corporate Users |
| Companies Covered | Audi, Lucid Motors, Porsche, Cadillac, Rolls-Royce, BMW, Volvo, NIO, Mercedes-Benz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Electric Vehicle Market Strategic Shifts
Battery platform architectures are fragmenting into cell-to-pack and cell-to-chassis configurations that eliminate module housings and compress bill-of-materials costs while enabling vehicle structural innovation.
Cell-to-chassis battery integration is modularizing vehicle underbody structures by eliminating dedicated pack enclosures and mounting hardware. Premium manufacturers are adopting this approach for flagship sedans and SUVs, enabling floor pan stiffness improvements and cabin space expansion. The technology is compressing traditional tiered supplier relationships as OEMs bring structural battery engineering in-house.
The EU Green Deal transport decarbonization pathway tightens the regulatory noose on conventional powertrains across member states. Euro 7 standards impose stricter emission limits that accelerate powertrain electrification timelines for luxury manufacturers serving European markets. Premium brands are responding by front-loading battery-electric model launches and localizing R&D capacity within the trading bloc.
Direct-to-consumer sales channels are displacing traditional franchised dealer networks in affluent urban markets. Tesla's retail model has forced legacy marques to experiment with agency contracts and online configuration tools in Germany, Norway, and the Netherlands. This channel shift is most visible in metropolitan corridors where digital-native buyers prioritize transparent pricing and seamless delivery experiences over negotiation rituals.
Luxury Electric Vehicle Market Segmentation
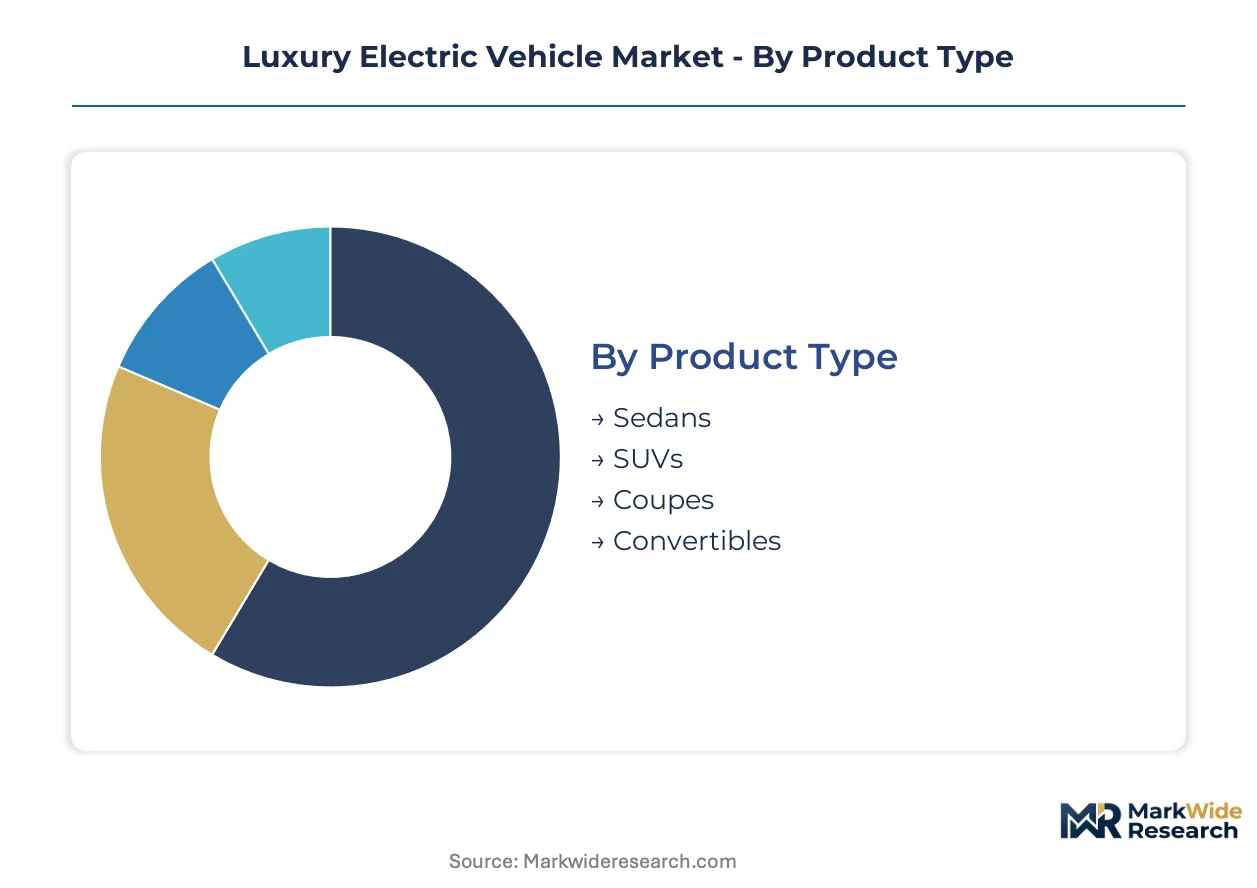
Segmentation in luxury electric vehicles reveals divergent engineering priorities and purchasing logics that manufacturers must reconcile. Product architecture, energy storage chemistry, charging modality, and buyer identity each create distinct margin profiles and competitive battlegrounds.
Product Type:
Body style selection signals buyer priorities around aerodynamic efficiency versus cabin volume and road presence.
- Sedans:Low drag coefficients and optimized weight distribution maximize range per kilowatt-hour. Demand concentrates among executive fleet operators in Shenzhen and corporate transport buyers seeking understated prestige with minimal environmental footprint.
- SUVs:Elevated seating positions and expanded cargo capacity command pricing premiums despite aerodynamic penalties. Affluent families in Shanghai and Beijing prioritize cabin space and commanding visibility, accepting moderate range trade-offs.
- Coupes:Two-door configurations with swept rooflines target driving enthusiasts seeking performance-oriented chassis tuning and exclusive styling.
- Convertibles:Retractable roof mechanisms add weight and structural complexity, limiting electric range but capturing status-conscious buyers in temperate coastal markets.
SUVs lead volumes today; sedans are gaining share fastest among institutional procurement channels.
Battery Technology:
Chemistry selection determines thermal management requirements, manufacturing capital intensity, and vehicle packaging constraints.
- Lithium-Ion:Mature cell-to-pack architectures dominate current production with established supply chains and recycling pathways. Silicon-anode integration is boosting energy density while solid-state alternatives mature.
- Solid State:Ceramic electrolytes eliminate flammable liquid components and enable higher voltage operation. Dry electrode coating processes demand entirely new capital equipment absent from incumbent operations.
- Nickel-Metal Hydride:Lower energy density relegates this chemistry to hybrid auxiliary applications and emerging market cost-sensitive segments.
- Lithium Polymer:Flexible form factors suit limited-volume specialty vehicles where packaging geometry overrides cost optimization.
Lithium-ion leads volumes today; solid-state is expanding most quickly as pilot production lines achieve yield targets.
Charging Infrastructure:
Charging modality shapes daily use patterns, infrastructure investment requirements, and aftermarket revenue opportunities.
- Fast Charging Stations:DC rapid chargers delivering 150-350 kW compress long-distance travel stops to 20-30 minutes. Highway corridor buildout in Germany and Norway is accelerating fleet electrification timelines.
- Home Chargers:Level 2 residential installations provide overnight replenishment for suburban owners with dedicated parking. Bi-directional capabilities are opening vehicle-to-grid revenue streams.
- Superchargers:Proprietary high-speed networks create ecosystem lock-in and subscription monetization opportunities.
- Wireless Charging:Inductive pad systems eliminate connector wear and enable automated fleet depot operations.
Home chargers lead volumes today; fast charging stations are climbing the fastest as highway infrastructure gaps close.
End User:
Buyer category determines fleet sizing, financing structures, and feature prioritization across software and hardware specifications.
- Individual Consumers:Private owners prioritize brand heritage, infotainment integration, and over-the-air upgrade pathways. Direct-to-consumer sales channels are displacing traditional dealer networks in affluent urban corridors.
- Fleet Operators:Corporate and ride-hail fleets emphasize total cost of ownership, residual value predictability, and centralized telematics management. Procurement concentrates in metropolitan clusters with reliable charging density.
- Rental Services:Short-term mobility providers demand rapid turnaround capability and standardized vehicle configurations for operational simplicity.
- Corporate Users:Executive transport programs require premium cabin materials and autonomous driving features for productivity during transit.
Individual consumers lead volumes today; fleet operators are gaining share fastest as electrification mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands volume leadership through concentrated urban demand clusters, whereas Germany channels engineering heritage into premium electrification platforms that command sustained pricing power across European corridors.
China
Domestic marques and foreign premium brands compete intensely for affluent buyers in Shenzhen, Shanghai, and Beijing. MIIT new energy vehicle credit systems impose production quotas that accelerate localization of R&D and assembly capacity. The Pearl River Delta manufacturing corridor hosts expanding battery platform engineering centers serving Asia-Pacific export markets.
Germany
Luxury manufacturers leverage century-old brand equity to justify premium positioning in battery-electric segments. The EU Green Deal transport decarbonization pathway and forthcoming Euro 7 standards tighten regulatory pressure on conventional powertrains. Bavaria and Baden-Württemberg host concentrated R&D campuses where solid-state pilot production lines achieve yield targets.
United States
Corporate fleet operators in California and the Northeast corridor expand procurement of premium electric sedans for executive transport programs. EPA tailpipe emission standards and California Air Resources Board zero-emission vehicle mandates collectively compress available market space for internal combustion alternatives. Silicon Valley engineering clusters attract autonomous driving talent pools spanning automotive embedded systems and consumer electronics development cultures.
Norway
Policy-driven electrification has created the world's highest per-capita luxury EV penetration rate among private consumers. National tax exemptions and toll waivers for zero-emission vehicles sustain demand concentration in Oslo and surrounding metropolitan corridors. Highway fast-charging infrastructure buildout eliminates range anxiety for long-distance travel across Scandinavian routes.
United Kingdom
London's ultra-low emission zone and expanding clean air regulations drive replacement demand among executive transport operators. The national ban on new internal combustion vehicle sales from 2030 front-loads electrification timelines for premium manufacturers. Midlands manufacturing regions transition battery assembly capacity from hybrid systems toward full-electric platforms.
Luxury Electric Vehicle Market Competitive Environment
Top-tier vendors anchor heritage-driven positioning, while emerging specialists challenge through drivetrain efficiency and software-native architectures. The competitive set fragments across three strategic tiers: established luxury marques with century-old brand equity, technology-forward entrants leveraging clean-sheet engineering, and Chinese domestic champions capturing localized demand clusters. Dominant competitive moves include vertical integration into battery cell manufacturing and exclusive charging network deployment.
Within the heritage tier, BMW and Mercedes-Benz exemplify incumbent adaptation strategies through operating system monetization and integrated energy management services. Lucid Motors occupies a position among engineering-focused specialists emphasizing proprietary drivetrain efficiency and over-the-air performance upgrades. These three entities represent divergent archetypes for sustaining margin structures as software-defined vehicles reshape revenue composition.
| Leading Market Players |
|---|
| Audi |
| Lucid Motors |
| Porsche |
| Cadillac |
| Rolls-Royce |
| BMW |
| Volvo |
| NIO |
| Mercedes-Benz |
| Others |
Value Chain & Pricing Dynamics
Cell engineering talent concentration in Bavaria and Baden-Württemberg widens labor-cost spreads between German premium marques and Asian manufacturing hubs, compressing margin structures for entrants lacking captive R&D scale while sustaining three-tier pricing stratification across flagship, volume, and entry-luxury segments.
Pricing Analysis
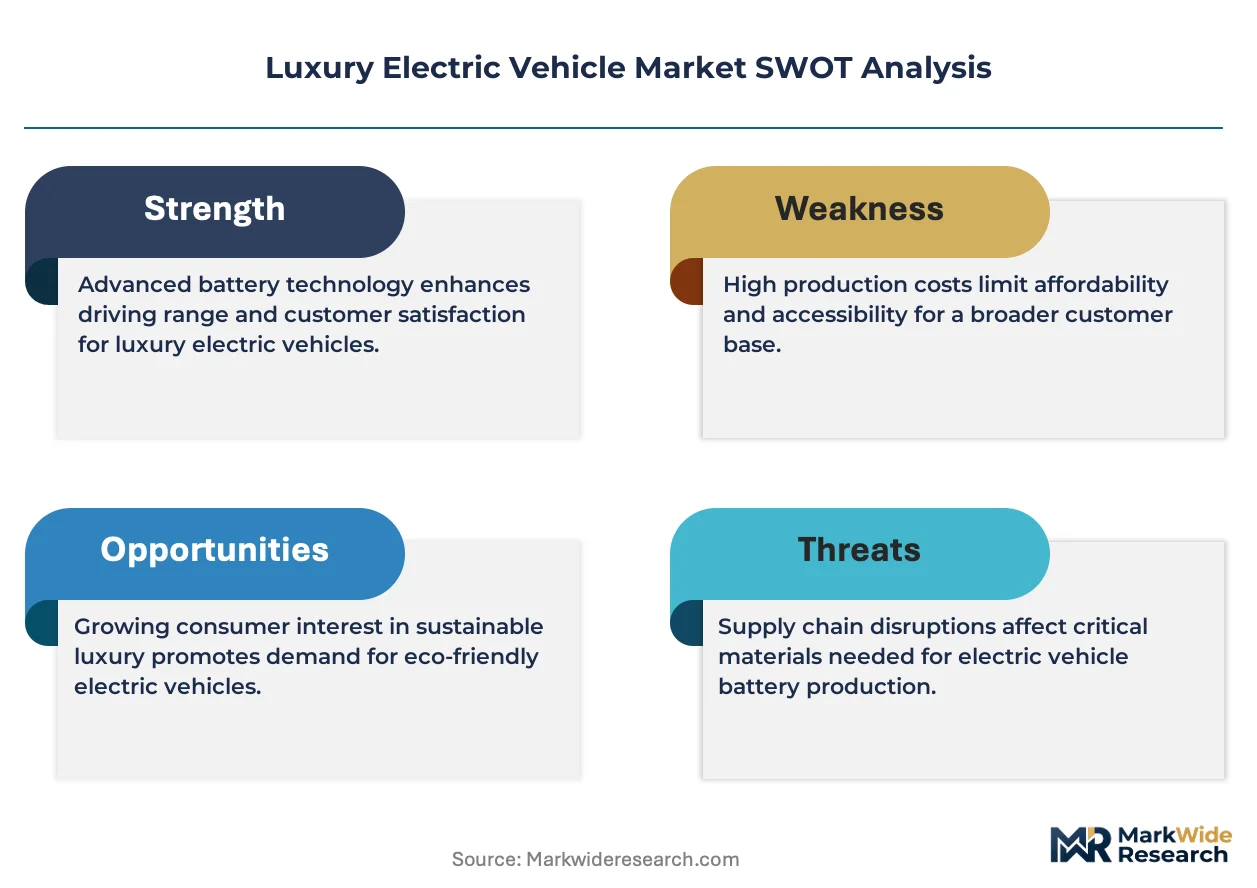
Capacity additions in South Korea and China are reshaping price floors for lithium-ion cell supply, forcing European incumbents to absorb cost compression or surrender share. Pricing stratifies across heritage-flagship, technology-forward, and domestic-champion tiers, with brand equity and software subscription attach rates commanding 15-40 point spreads. Pricing pressure stems from silicon-anode integration costs and solid-state pilot production yields. Fleet operators exhibit highest price sensitivity; individual collectors of limited editions show lowest.
Supply Chain Analysis
Second-life battery refurbishment flows from European and North American markets back to stationary storage integrators in China are creating circular revenue streams that offset raw material exposure. Cathode active material production concentrates in China, South Korea, and Japan; lithium extraction draws from Australia, Chile, and Argentina. The supply chain rests on cobalt and nickel price volatility from single-source concentration in the DRC and Indonesia. Distribution runs through direct-to-consumer agency contracts in affluent urban corridors and fleet procurement desks in metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state manufacturing yield improvements and software-defined subscription attach rates are expanding service-margin pools, transforming hardware-centric economics toward recurring-revenue models that reward platform control over unit sales velocity.
For Market Incumbents: Lock in cell-to-chassis engineering talent and solid-state pilot production capacity before yield curves flatten. Defend against Chinese domestic champions by localizing operating system development for MIIT compliance and accelerating over-the-air monetization pathways. Prioritize captive battery supply agreements to secure cathode precursor access. For New Entrants and Emerging Players: Enter via fleet procurement channels in Shenzhen and Shanghai where electrification mandates concentrate institutional demand with lower brand-heritage barriers. Target second-life battery integration services for grid-scale storage operators. Pursue vehicle-to-grid certification as a differentiated hardware-software bundle. For Investors and Strategic Acquirers: Valuations sit cheapest among engineering-focused specialists with solid-state pilot lines and autonomous driving stack integration. Long-term viability favors entities controlling proprietary thermal management architectures and bi-directional charging IP. Monitor solid-state ceramic electrolyte yield announcements as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term offtake contracts with CATL or LG Energy Solution secure cathode capacity for platform scaling. |
| Software-Defined Vehicle Investment | Operating system layer development enables recurring revenue from autonomous function subscriptions. |
| Charging Infrastructure Partnership | Proprietary high-speed network deployment creates ecosystem lock-in and grid-services monetization. |
| Geographic Manufacturing Footprint | Localization in Pearl River Delta corridors satisfies MIIT credit quotas and reduces tariff exposure. |
| Platform Standardization | Cell-to-chassis architectures compress bill-of-materials costs while enabling structural innovation. |
Study Parameters
Bottom-up fleet procurement and individual consumer demand modeling reconciled against top-down battery production and vehicle registration tracking forms the analytical core. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, charging infrastructure operators, and fleet telematics managers combined with secondary validation from MIIT production databases, EPA certification filings, IHS Markit registration data, and EU Green Deal implementation trackers. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Input-output matrices map propulsion architecture, vehicle class, and regional production cluster dimensions across the projection horizon. CAGRs derive from segment-level adoption curves weighted by regulatory mandate timelines and infrastructure buildout trajectories. Forecast inputs incorporate solid-state yield improvement schedules and software subscription attach rate assumptions by buyer archetype.
Inputs from OEM production plans and MIIT credit disclosures were available through the study window; gaps in solid-state pilot yield data and charging infrastructure deployment timelines introduce uncertainty bands. Practitioners should monitor ceramic electrolyte processing announcements and highway corridor fast-charging commissioning for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
Vietnam Electric Vehicle Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market
Electric Vehicles
Middle-East and Africa Electric Vehicle (EV) Fluids Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
Three Wheel E-Scooter Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
Train Battery Market
Electric Vehicles
Mexico E-Bike Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Russia Electric Cars Market
Electric Vehicles
France Solar E-Bike Market