
 Automotive Air Lift Jack Market | 2026-2036
Automotive Air Lift Jack Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Air Lift Jack Market Outlook
Skilled technician availability across North American heavy-duty repair shops is collapsing, forcing fleet maintenance departments to prioritize speed-rated lifting equipment that reduces bay occupancy time. Sunex Tools, Inc. leverages extensive distributor partnerships across the United States to sustain aftermarket parts availability. Gray Manufacturing Co. Inc. anchors its position through specialized hydraulic cylinder production integrated into its jack assemblies. Astro Pneumatic Tool Co. competes aggressively on portable pneumatic configurations targeting mobile service applications.
An automotive air lift jack is a compressed-air-actuated or hydraulically powered lifting device designed to raise vehicles for undercarriage access, typically operating at pressures between 90 and 150 PSI and constructed from heat-treated steel alloy frames rated for repetitive load cycles. Pneumatic variants dominate high-volume commercial settings where rapid lift cycles matter most, while hydraulic units retain margin concentration in precision alignment shops requiring controlled descent rates. Fleet operators represent the fastest-expanding end-user category as logistics companies internalize maintenance capacity to control vehicle uptime.
OSHA standards governing portable lifting equipment and the EU Machinery Directive with its CE marking requirements shape product design thresholds and market access conditions on both sides of the Atlantic. Germany's KBA enforces periodic inspection protocols that directly influence replacement demand for certified lifting equipment in commercial garages. Stakeholders must weigh whether to deepen pneumatic automation or defend hydraulic precision positions as electrification trends alter vehicle weight distributions and lifting point geometries.
Market Dynamics
Fleet operators are internalizing maintenance capacity to control vehicle uptime, compressing replacement cycles for lifting equipment and forcing manufacturers to prioritize speed-rated pneumatic systems over legacy hydraulic configurations.
Growth Catalysts
- OSHA Workplace Safety Mandates:United States enforcement of portable lifting equipment standards is elevating certification requirements for pneumatic and hydraulic systems in commercial garages.
- Commercial Vehicle Production Scaling:China's domestic truck and bus manufacturing expansion is driving aftermarket service network buildout and associated lifting equipment procurement.
- Heat-Treated Steel Alloy Advances:Improved frame metallurgy is extending load cycle ratings and reducing equipment replacement frequency in high-volume fleet maintenance bays.
Market Restraints
- Steel Input Cost Volatility:Heat-treated alloy pricing fluctuations compress margin stability for frame manufacturers dependent on commodity steel markets.
- Certification Inspection Protocols:Germany's KBA periodic inspection requirements create regulatory friction that slows replacement demand timing in commercial garages.
- Precision Hydraulic Substitution Threat:Controlled descent rate advantages in alignment shops limit pneumatic penetration in precision maintenance segments.
Strategic Opportunities
- Mobile Service Channel Expansion:Portable pneumatic configurations are capturing fleet maintenance departments deploying roadside and depot-adjacent service units.
- Electrification Geometry Adaptation:Battery-electric vehicle weight distribution shifts and altered lifting point configurations are creating specification gaps for redesigned jack assemblies.
- EU Machinery Directive Tailwind:CE marking requirements for pneumatic lifting systems are consolidating supplier bases and creating certification-barrier advantages for compliant manufacturers.
Industry Challenges
- Technician Availability Collapse:Skilled heavy-duty repair labor scarcity across North American shops is forcing equipment specification toward reduced-complexity pneumatic systems.
- Integration Complexity with Legacy Bays:Existing hydraulic infrastructure in established commercial garages creates retrofit friction for pneumatic system conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Air Lift Jack Market |
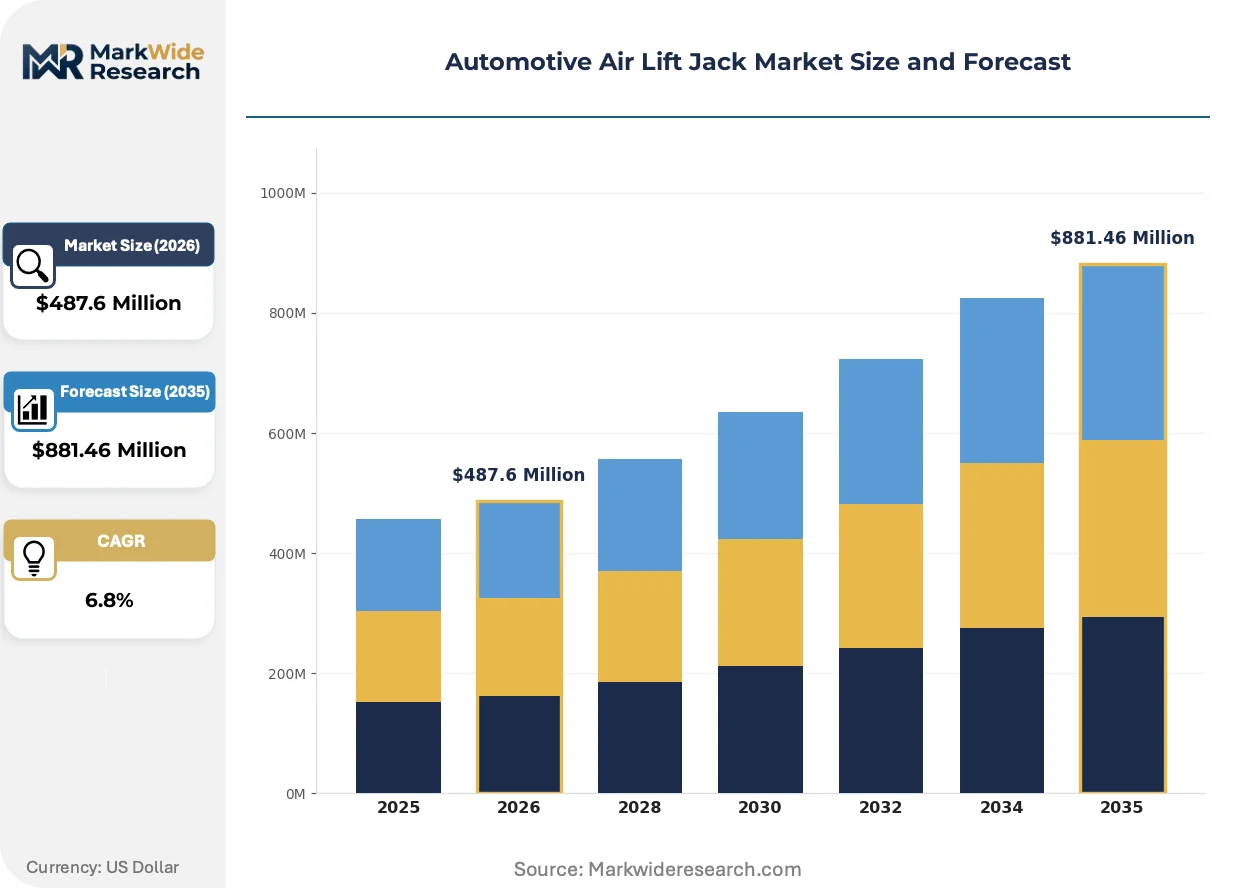
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
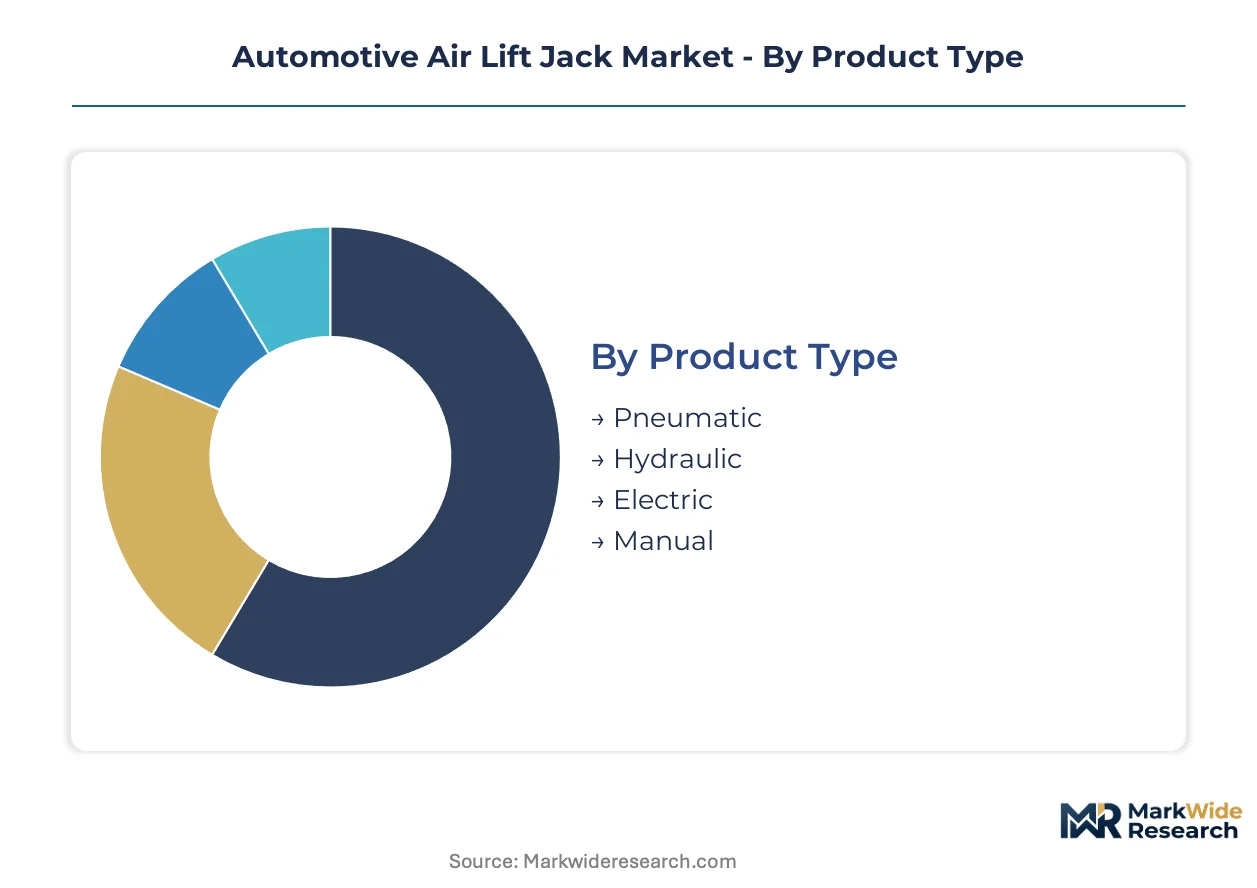
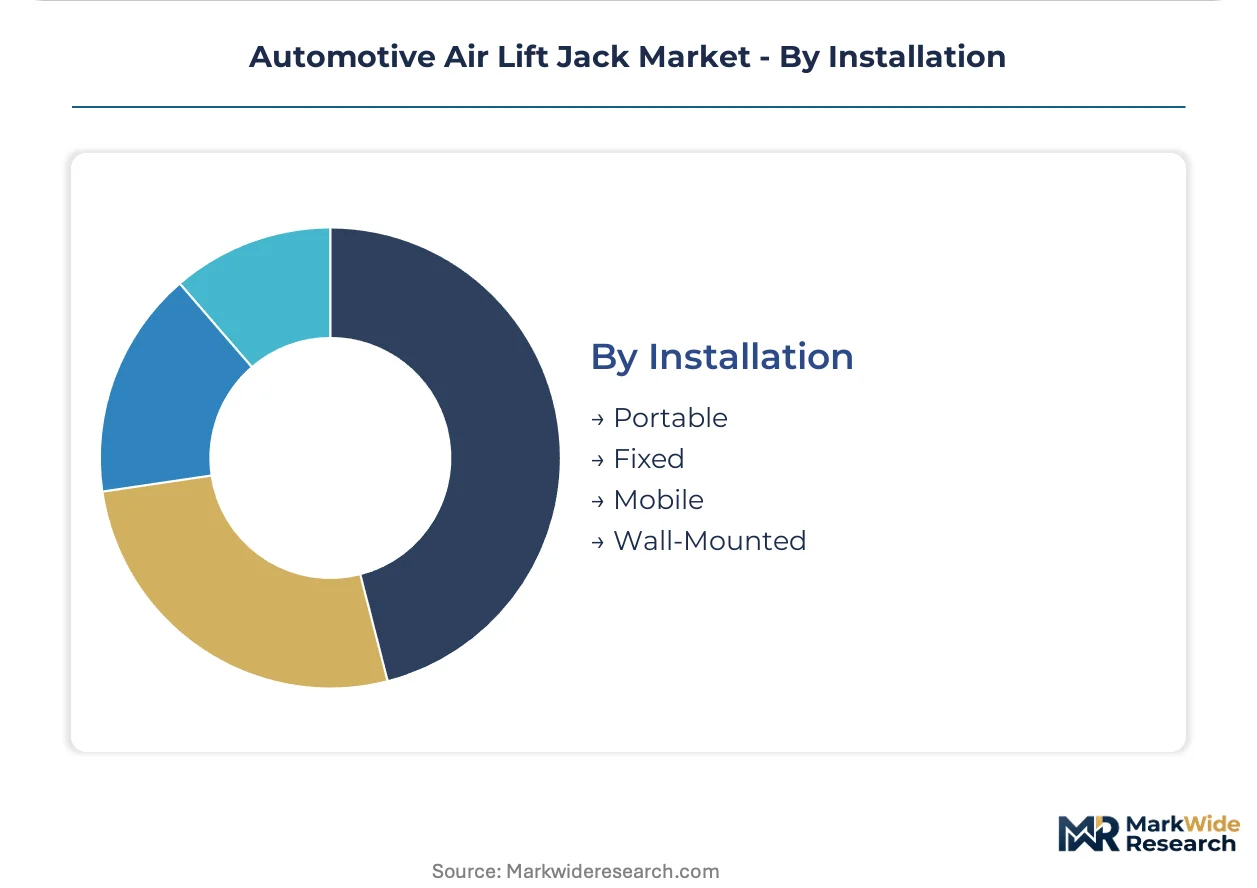
| Segmentation | Product Type: Pneumatic, Hydraulic, Electric, Manual End User: Mechanics, DIY Enthusiasts, Fleet Operators, Car Dealerships Capacity: 1 Ton, 2 Ton, 3 Ton, 4 Ton Installation: Portable, Fixed, Mobile, Wall-Mounted |
| Companies Covered | Astro Pneumatic Tool Co., Sunex Tools, Inc., Norco Industries Inc., ATD Tools, Inc., Gray Manufacturing Co. Inc., JET Equipment & Tools Ltd., Shinn Fu Company of America Inc., Emerson Manufacturing Corp., Jack Sealey Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Air Lift Jack Market Strategic Shifts
Compressed-air actuation is displacing hydraulic precision in commercial settings as fleet operators prioritize lift speed over descent control, while regulatory certification requirements reshape product development priorities across manufacturing bases.
Aluminum-magnesium alloy framing is decomposing traditional heat-treated steel dominance in portable pneumatic jack construction. Mobile service fleet operators are specifying these lighter configurations for roadside deployment applications. The technology is decomposing established supplier hierarchies by enabling new entrants to bypass capital-intensive steel forging infrastructure.
EU Machinery Directive CE marking enforcement is tightening conformity assessment procedures for pneumatic lifting equipment exported into European commercial garage markets. Manufacturers must now maintain notified body relationships and technical documentation systems that smaller competitors cannot sustain. German commercial vehicle service networks are responding by consolidating supplier relationships toward established certification-holding producers.
Bay occupancy time has displaced equipment purchase price as the primary procurement criterion for fleet maintenance departments managing high vehicle throughput. Traditional distributor-led sales channels are losing share to direct manufacturer relationships that bundle training and rapid parts availability. This behavioral shift concentrates most acutely in United States logistics hubs where driver detention costs exceed equipment capital outlays.
Automotive Air Lift Jack Market Segmentation
Automotive air lift jack procurement channels diverge sharply by operational intensity. Fleet maintenance departments source through direct manufacturer relationships, while independent repair shops rely on distributor networks for aftermarket support.
Product Type:
Distributor partnerships favor pneumatic and hydraulic variants with established parts availability, while electric configurations penetrate through specialized industrial supply channels.
- Pneumatic:Compressed-air systems operating at 90-150 PSI dominate high-volume commercial bays where lift speed compresses bay occupancy. Fleet operators in United States logistics hubs specify these for roadside service units.
- Hydraulic:Precision-controlled descent rates retain preference in alignment shops requiring load stability. Germany's KBA inspection protocols reinforce specification continuity in certified commercial garages.
- Electric:Battery-powered units eliminate compressor dependency for mobile deployment.
- Manual:Foot-pump mechanisms persist in low-frequency DIY applications.
By volume, pneumatic leads. By growth pace, electric is ahead.
End User:
Procurement authority concentrates with fleet maintenance departments internalizing service capacity, while DIY channels fragment across retail and e-commerce.
- Fleet Operators:Logistics companies with captive maintenance infrastructure specify speed-rated equipment to minimize driver detention costs. Direct manufacturer relationships displace traditional distributor channels.
- Mechanics:Independent repair shops prioritize equipment with rapid parts availability through established distributor networks like Sunex Tools.
- Car Dealerships:OEM-affiliated service centers require CE-marked equipment for warranty compliance.
- DIY Enthusiasts:Price-sensitive consumers drive portable manual and small-capacity pneumatic sales through retail channels.
Fleet operators command the steepest expansion trajectory. Mechanics retain the largest installed base.
Capacity:
Margin structure tightens at lower capacity tiers where commoditization pressures concentrate, while heavy-duty specifications command specification premiums.
- 3 Ton:The commercial fleet standard for medium-duty trucks and buses. Heat-treated steel alloy framing extends load cycle ratings in high-throughput maintenance bays.
- 4 Ton:Heavy-duty configurations serve commercial vehicle production facilities and specialized recovery operations. China's truck manufacturing expansion drives specification demand.
- 2 Ton:Light commercial and passenger vehicle applications.
- 1 Ton:Compact portable units for roadside emergency use.
Three-ton specifications dominate revenue contribution. Four-ton configurations are gaining share fastest.
Installation:
Channel economics favor portable configurations for mobile service expansion, while fixed installations anchor established commercial garage infrastructure.
- Portable:Aluminum-magnesium alloy framing reduces weight for technician transport. Mobile fleet operators specify these for depot-adjacent and roadside deployment.
- Mobile:Wheeled configurations with integrated air reservoirs serve multi-bay commercial facilities requiring equipment repositioning.
- Fixed:Pit-mounted and in-ground systems maximize bay density in permanent facilities.
- Wall-Mounted:Space-constrained urban garages utilize vertical storage integration.
Portable leads by deployment volume. Mobile is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety mandates in the United States anchor the regulatory framework shaping pneumatic lifting equipment certification requirements across commercial garage networks. Fleet maintenance departments in logistics hubs drive specification intensity for speed-rated systems that compress bay occupancy.
United States
Logistics companies with captive maintenance infrastructure in Chicago and Dallas-Fort Worth are internalizing service capacity to control driver detention costs. OSHA enforcement of portable lifting equipment standards elevates certification thresholds for pneumatic and hydraulic systems in commercial garages. Gray Manufacturing Co. Inc. anchors its position through specialized hydraulic cylinder production integrated into jack assemblies serving these high-throughput markets.
Germany
The KBA enforces periodic inspection protocols that directly influence replacement demand timing for certified lifting equipment in commercial vehicle service networks. EU Machinery Directive CE marking requirements shape product design thresholds and market access conditions for pneumatic systems exported into European markets. Stuttgart and Munich industrial clusters concentrate precision alignment shops requiring controlled descent rate hydraulic configurations.
China
Domestic commercial vehicle production scaling in the Yangtze River Delta drives aftermarket service network buildout and associated lifting equipment procurement. GB standards and SAMR oversight govern machinery safety certification for pneumatic lifting systems deployed in manufacturing facilities. Shanghai and Wuhan production hubs generate specification demand for heavy-duty 4-ton configurations serving truck and bus manufacturing expansion.
India
Fleet operators in Maharashtra and Gujarat are expanding procurement of heavy-duty lifting equipment as commercial vehicle maintenance cycles intensify across logistics corridors. BIS certification requirements and the PLI scheme for manufacturing infrastructure shape equipment import and local production decisions. Pune and Ahmedabad industrial zones concentrate aftermarket service network development supporting domestic commercial vehicle production growth.
Japan
METI industrial standards and JIS certification protocols govern pneumatic lifting equipment specifications for commercial garage networks serving precision maintenance segments. Nagoya and Osaka manufacturing clusters retain preference for hydraulic configurations requiring controlled descent rates in alignment applications. Domestic automotive production quality standards reinforce specification continuity for certified lifting equipment in OEM-affiliated service centers.
Automotive Air Lift Jack Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around manufacturers possessing captive forging capacity and established certification relationships with notified bodies. The mid-tier fragments across regional fabricators serving distributor networks with standardized pneumatic configurations. Two strategic archetypes dominate: integrated metallurgy-to-assembly producers commanding heavy-duty specifications, and portable equipment specialists capturing mobile service channel expansion. Competitive moves concentrate on geographic distributor partnerships and aluminum-magnesium alloy framing technology licensing.
Among United States-based manufacturers, Sunex Tools, Inc. and Gray Manufacturing Co. Inc. exemplify the integrated production archetype, with the former leveraging extensive distributor partnerships to sustain aftermarket parts availability and the latter anchoring position through specialized hydraulic cylinder production. Astro Pneumatic Tool Co. occupies the portable configuration specialist tier, competing aggressively on pneumatic systems targeting mobile service applications where aluminum-magnesium alloy framing reduces technician transport burden.
| Leading Market Players |
|---|
| Astro Pneumatic Tool Co. |
| Sunex Tools, Inc. |
| Norco Industries Inc. |
| ATD Tools, Inc. |
| Gray Manufacturing Co. Inc. |
| JET Equipment & Tools Ltd. |
| Shinn Fu Company of America Inc. |
| Emerson Manufacturing Corp. |
| Jack Sealey Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between fleet operators and pneumatic equipment manufacturers lock in both heat-treated steel alloy supply access and price visibility across multi-year maintenance contracts. These arrangements insulate procurement departments from commodity volatility while compressing margin flexibility for frame fabricators locked into fixed-price commitments.
Pricing Analysis
United States-Germany price spreads for 3-ton pneumatic configurations reflect divergent certification cost burdens, with CE-marked units commanding premiums over OSHA-compliant equivalents. Pricing stratifies across certification grade, volume scale, after-sales service bundling, and geographic delivery cost. Cost compression in portable aluminum-magnesium alloy tiers is intensifying because new entrants bypass capital-intensive forging infrastructure. Fleet operators exhibit lowest price sensitivity, prioritizing bay occupancy reduction over capital outlay, while DIY enthusiasts drive commoditization at sub-2-ton capacity tiers.
Supply Chain Analysis
Heat-treated steel alloy forging capacity concentrates in China, Germany, and the United States, creating single-source vulnerability for specialized frame manufacturers without captive metallurgy operations. Production draws from chromium-molybdenum steel billets, precision-machined hydraulic cylinders, and pneumatic valve assemblies. Tariff exposure on Chinese alloy imports disrupts cost structures for North American assemblers. Distribution runs through manufacturer-direct channels for fleet accounts and established distributor networks serving independent repair shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across United States logistics corridors is shifting procurement leverage toward volume buyers capable of dictating specification standards. This buyer-power concentration fragments pricing power among equipment manufacturers competing for multi-unit maintenance contracts.
For Market Incumbents: Compound certification barrier advantages by deepening notified body relationships for EU Machinery Directive compliance, while accelerating aluminum-magnesium alloy framing R&D to defend against lightweighting substitution threats from portable equipment specialists. Prioritize captive forging capacity expansion in Germany to secure KBA-inspection-compliant supply continuity. For New Entrants and Emerging Players: CE marking fast-track partnerships with established conformity assessment bodies enable rapid European market access without multi-year technical documentation buildout. Target mobile service fleet deployments in United States logistics hubs where speed-rated pneumatic specifications outrank brand loyalty. Pursue direct manufacturer relationships bypassing legacy distributor markups. For Investors and Strategic Acquirers: Portable configuration specialists with aluminum-magnesium alloy framing IP offer asymmetric upside as mobile service channels expand. Long-term viability hinges on electrification geometry adaptation capabilities rather than legacy hydraulic precision positioning. Monitor battery-electric vehicle lifting point standardization announcements as inflection indicators for specification obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum-Magnesium Alloy Framing Scale-Up | Reduces technician transport burden for mobile fleet operators deploying roadside service units. |
| CE Marking Conformity Partnership | Consolidates supplier relationships in German commercial vehicle service networks toward certified producers. |
| Direct Fleet Procurement Channel | Bypasses distributor markups while bundling training and rapid parts availability for high-throughput bays. |
| Electrification Geometry R&D Program | Addresses battery-electric vehicle weight distribution shifts and altered lifting point configurations. |
| Heat-Treated Steel Forging Expansion | Secures captive supply of chromium-molybdenum alloy frames for 4-ton heavy-duty specifications. |
Study Parameters
The analysis maps pneumatic, hydraulic, electric, and manual product sub-sectors, each validated through maintenance directors, fleet procurement officers, aftermarket distributor principals, and OEM platform engineers. Primary interview data triangulates against customs/trade records, SEC 10-K filings, OSHA enforcement databases, and vehicle production statistics. Bottom-up equipment shipment estimates reconcile with top-down commercial vehicle fleet size projections.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework models capacity tier, actuation technology, installation type, and end-user procurement authority. CAGRs derive from segment-level growth rate synthesis. Forecast inputs incorporate GB standards evolution in China, KBA inspection protocol changes, and fleet internalization rates for captive maintenance infrastructure.
Decision-makers should treat outputs as directional under stable steel alloy pricing and unchanged OSHA enforcement intensity; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as battery-electric vehicle weight distributions and lifting point geometries evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Car Refrigerator Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
Rear Spoiler Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
Saudi Arabia Vehicle Exhaust Hose Market
Automotive Parts
North America Automotive Foams Market
Automotive Parts
Tow Bar Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Crankshaft Materials Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Motorcycle Battery Chargers Market