
 Off-Road Hoses Market | 2026-2036
Off-Road Hoses Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Road Hoses Market Analytics
A shift from single-source to multi-source procurement is rebalancing supply chain risk across the off-road hoses sector. Parker Hannifin Corporation leverages its fluid power portfolio to sustain specification-grade relationships with OEMs. Gates Corporation anchors North American aftermarket channels through extensive distributor networks. Continental AG competes on material science leadership in thermoplastic hose constructions.
Off-road hoses are reinforced, flexible conduits engineered to transmit hydraulic fluid, compressed air, fuel, or coolant under pressure ratings typically spanning 3,000 to 6,000 psi, constructed from synthetic rubber compounds, thermoplastic elastomers, or polyurethane with braided wire or textile reinforcement. These assemblies prevent catastrophic fluid loss in construction equipment, agricultural machinery, all-terrain vehicles, and utility vehicles operating in abrasive, high-vibration environments. Hydraulic hoses command the largest product category share due to pervasive power-transmission requirements in heavy equipment, while polyurethane materials are displacing rubber in weight-sensitive ATV applications where flexibility and abrasion resistance converge. Air hose demand concentrates in construction equipment pneumatic systems, whereas fuel hoses face material-transition pressures from biofuel compatibility mandates.
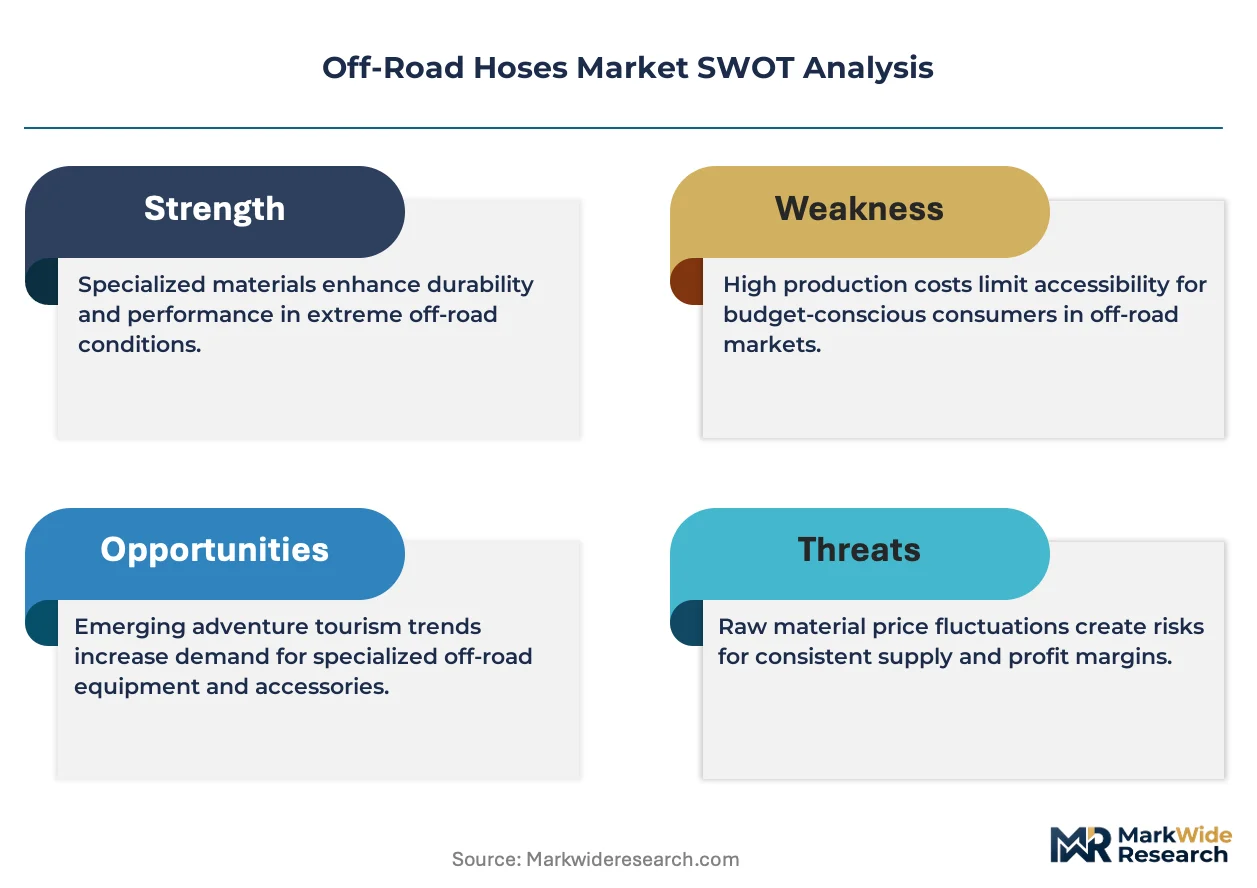
The EPA enforces emissions and fuel-system integrity standards that dictate hose permeation limits and material specifications for equipment sold in the United States. REACH and RoHS frameworks in Europe restrict phthalate plasticizers and heavy-metal additives in PVC and rubber compounds, compelling reformulation of hose constructions. The EU Green Deal's machinery decarbonization timeline is accelerating electric-hydraulic hybrid designs that alter hose pressure and thermal profiles. Stakeholders must monitor how electrification shifts thermal management requirements and whether existing hose specifications accommodate coolant loops in battery-powered off-road platforms.
Market Dynamics
Electrification of off-road equipment is redrawing thermal management specifications, forcing hose manufacturers to validate materials against coolant chemistries and pulse pressures that differ fundamentally from legacy hydraulic architectures.
Growth Catalysts
- EU Green Deal machinery decarbonization:The timeline accelerates electric-hydraulic hybrid designs, creating demand for hoses rated to new thermal and pressure profiles in German and French precision farming equipment.
- Agricultural fleet expansion:Machinery replacement cycles in the European Union are shortening as emissions compliance deadlines tighten, pulling forward hose replacement demand across tractor and harvester applications.
- Polyurethane material substitution:Weight-sensitive ATV and UTV manufacturers are specifying thermoplastic elastomer constructions to reduce unsprung mass while maintaining abrasion resistance in rocky terrain.
Market Restraints
- Synthetic rubber feedstock volatility:Styrene-butadiene and nitrile rubber prices track petrochemical indices, compressing margin visibility for compounders serving the construction equipment aftermarket.
- REACH formulation compliance:ECHA restrictions on phthalate plasticizers and heavy-metal additives force costly reformulation of PVC and rubber hose constructions, extending R&D timelines.
- Steel wire reinforcement concentration:Braided wire supply clusters in East Asian metallurgy centers expose OEMs to logistics disruptions and tariff exposure on critical reinforcement materials.
Strategic Opportunities
- India agricultural mechanization:PLI scheme incentives for farm equipment manufacturing are drawing Deere and Mahindra capacity expansions, creating localized hose specification opportunities.
- Biofuel-compatible fuel hose retrofit:FAME and HVO mandates across European markets require material transitions in legacy machinery, opening aftermarket conversion kits for ethanol and biodiesel permeation resistance.
- Telematics-integrated predictive replacement:IoT pressure and temperature monitoring in rental fleet management is enabling condition-based hose replacement contracts, shifting revenue from transactional to recurring models.
Industry Challenges
- Electrification thermal validation:Battery coolant loop specifications lack harmonized SAE or ISO test protocols, forcing manufacturers to conduct parallel validation programs for each OEM platform.
- Multi-material bonding expertise:Thermoplastic-to-rubber transition joints in hybrid hose constructions require polymer scientists and process engineers in short supply across the supplier base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Road Hoses Market |
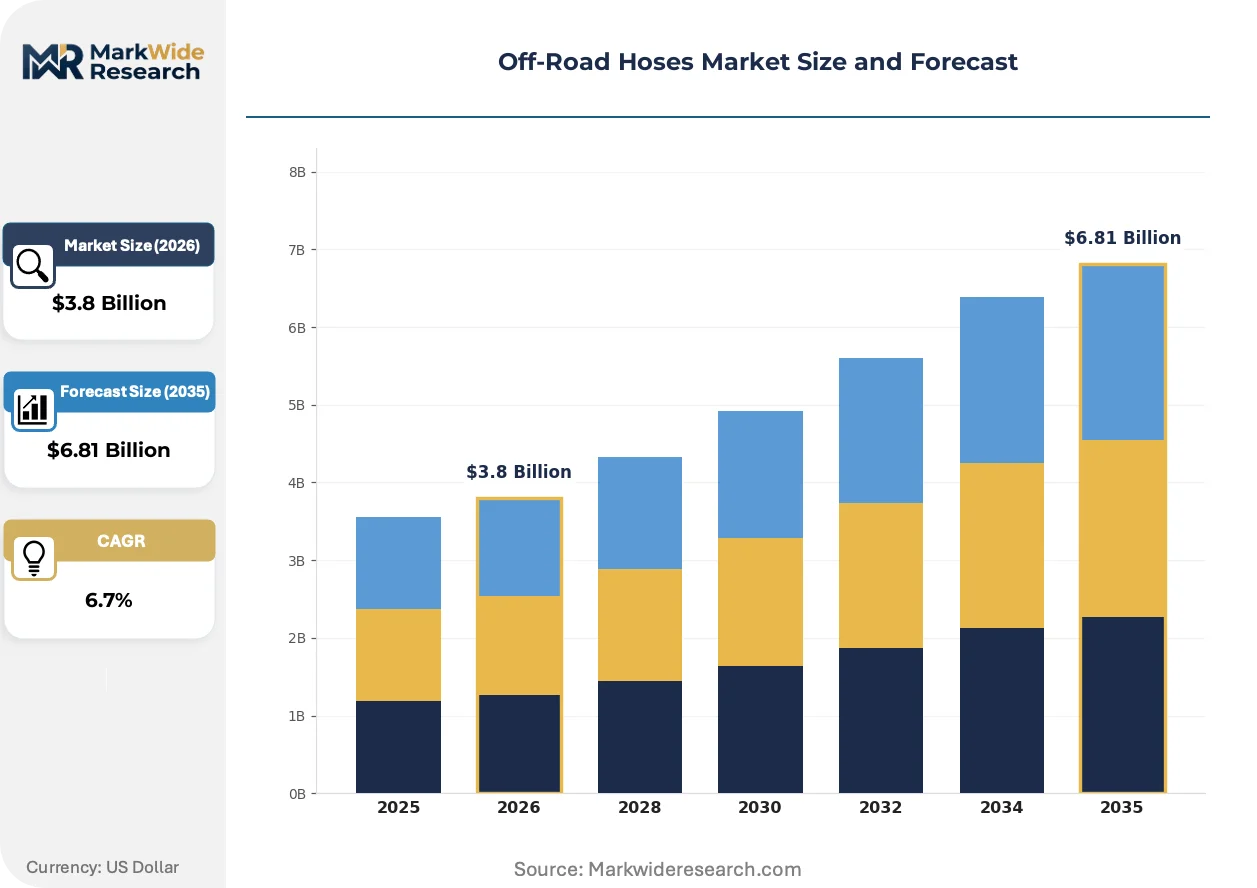
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Hoses, Air Hoses, Fuel Hoses, Water Hoses Material: Rubber, PVC, Nylon, Polyurethane Application: Construction Equipment, Agricultural Machinery, All-Terrain Vehicles, Utility Vehicles End User: OEMs, Aftermarket Providers, Distributors, Fleet Operators |
| Companies Covered | OffRoadhose, Speedflate, JACO, MORRFlate, MAXTRAX, Parker Hannifin Corporation, Gates Corporation, Eaton Corporation, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Road Hoses Market Evolving Landscape
Material science convergence with digital manufacturing is collapsing development cycles for application-specific hose geometries. Specification-grade suppliers now compete on validated performance data rather than commodity catalog breadth.
Thermoplastic polyurethane (TPU) hydraulic assemblies are expanding into German precision farming equipment where weight reduction and kink resistance outweigh premium pricing. OEMs specify TPU for articulated steering circuits and implement hydraulics on high-horsepower tractors. The material is expanding into adjacent construction equipment categories as operators report reduced fatigue failure in cold-start conditions.
REACH and RoHS frameworks are compelling systematic elimination of phthalate plasticizers from PVC and nitrile rubber compounds. Compounders must reformulate to maintain flexibility and ozone resistance without restricted additives. German agricultural machinery manufacturers are accelerating supplier audits to verify compliance ahead of 2027 enforcement milestones.
Fleet operators are consolidating hose procurement through integrated maintenance contracts rather than spot aftermarket purchases. Construction equipment rental companies in the United States are bundling hose replacement into total cost of ownership agreements. The shift compresses distributor margins while rewarding manufacturers with direct OEM and fleet specification relationships.
Off-Road Hoses Market Segmentation
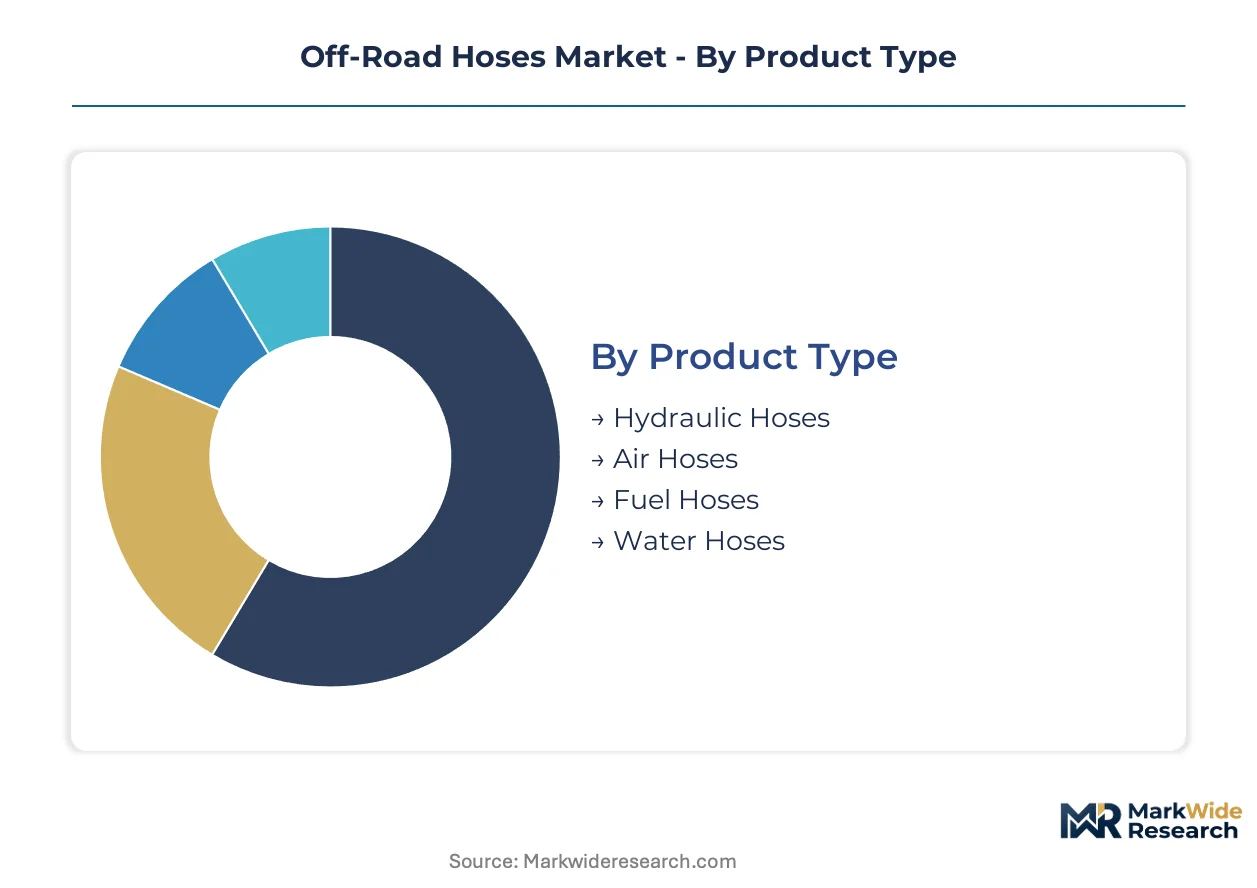
Off-road hose specifications diverge sharply between standalone replacement demand and embedded OEM systems, with procurement cycles, margin structures, and technical validation requirements differing fundamentally across these integration contexts. Understanding where each segment sits on this spectrum clarifies why hydraulic assemblies command specification-grade relationships while aftermarket channels compete on availability and price.
Product Type:
Standalone replacement demand dominates aftermarket procurement for wear-prone categories, while embedded hydraulic systems require upfront co-development with equipment manufacturers.
- Hydraulic Hoses:These assemblies transmit pressurized fluid at 3,000–6,000 psi through synthetic rubber or thermoplastic constructions with braided wire reinforcement. Demand concentrates in German and French precision farming equipment where electric-hydraulic hybrid designs are altering thermal profiles and pressure ratings. OEM specification relationships here lock in multi-year supply agreements.
- Air Hoses:Flexible conduits deliver compressed air to pneumatic systems in construction equipment, typically constructed from PVC or polyurethane with textile reinforcement. Fleet operators in the United States specify these for rental equipment maintenance contracts, shifting procurement from transactional spot purchases to integrated service agreements.
- Fuel Hoses:Barrier-layer constructions prevent permeation of hydrocarbons and biofuel blends in engine feed lines. REACH and RoHS frameworks in Europe are forcing material transitions away from phthalate plasticizers.
- Water Hoses:Coolant circulation assemblies manage thermal loads in engine and battery systems, with electrification expanding demand for battery coolant loop specifications.
Hydraulic hoses lead volumes today; water hoses are gaining share fastest as electrification proliferates.
Material:
Cost tiers separate specification-grade compounds validated for OEM integration from commodity substitutes acceptable in aftermarket replacement.
- Rubber:Nitrile and styrene-butadiene compounds dominate legacy hydraulic applications with proven compatibility across petroleum-based fluids. Synthetic rubber feedstock volatility tied to petrochemical indices compresses margin visibility for compounders serving construction equipment aftermarket channels.
- Polyurethane:Thermoplastic elastomer constructions reduce weight while maintaining abrasion resistance in rocky terrain. ATV and UTV manufacturers in Germany specify TPU for articulated steering circuits where kink resistance outweighs premium pricing.
- PVC:Cost-effective constructions for low-pressure air and water applications face reformulation pressures from ECHA restrictions on phthalate plasticizers.
- Nylon:Semi-crystalline thermoplastic structures offer chemical resistance in fuel system applications with tight permeation limits.
Rubber maintains volume leadership; polyurethane is climbing the fastest on weight-reduction priorities.
Application:
Customer type determines whether hoses ship as embedded components or standalone replacement units, with fleet operators consolidating procurement differently than individual owner-operators.
- Construction Equipment:Excavators, loaders, and cranes require hydraulic assemblies rated for impulse fatigue and abrasion. Rental fleet operators in the United States are bundling hose replacement into total cost of ownership agreements.
- Agricultural Machinery:Tractors and harvesters demand hoses validated for biofuel compatibility and precision farming hydraulics. EU emissions compliance deadlines are shortening replacement cycles across European Union machinery fleets.
- All-Terrain Vehicles:Weight-sensitive applications specify polyurethane to reduce unsprung mass without sacrificing flexibility in suspension and steering circuits.
- Utility Vehicles:Work-site transport platforms require balanced specifications across hydraulic, air, and coolant systems with moderate duty cycles.
Construction equipment leads volumes today; agricultural machinery is expanding most quickly on fleet renewal timelines.
End User:
Supply concentration varies sharply between OEM direct relationships and fragmented aftermarket distribution, with margin structures reflecting these channel economics.
- OEMs:Original equipment manufacturers specify hoses during platform development, requiring extensive validation testing and multi-year supply commitments. German agricultural machinery manufacturers are accelerating supplier audits to verify REACH compliance ahead of enforcement milestones.
- Aftermarket Providers:Independent distributors and jobbers serve owner-operators and small fleets through catalog breadth and availability. Margin compression intensifies as fleet operators consolidate procurement through direct manufacturer relationships.
- Distributors:Channel intermediaries stock inventory across multiple brands, with extensive networks anchoring North American aftermarket access.
- Fleet Operators:Large rental and construction companies negotiate integrated maintenance contracts, shifting revenue from transactional replacement to recurring service models with condition-based monitoring.
OEMs lead volumes today; fleet operators are gaining share fastest on procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision farming equipment corridor concentrates specification-grade demand for thermoplastic hydraulic assemblies. Agricultural machinery manufacturers in Baden-Württemberg and Lower Saxony are accelerating hose replacement cycles ahead of EU emissions deadlines.
United States
Construction equipment rental fleets in Texas and the Midwest are consolidating hose procurement through integrated maintenance contracts. EPA emissions standards dictate fuel-system permeation limits for equipment sold domestically. Oklahoma-based distributors anchor aftermarket channel access for owner-operators and regional contractors.
Germany
Precision farming OEMs in Stuttgart and Munich specify polyurethane hydraulic hoses for articulated steering circuits on high-horsepower tractors. REACH and RoHS frameworks compel reformulation of PVC and rubber compounds ahead of 2027 enforcement milestones. The Mannheim-Ludwigshafen chemical cluster supplies compliant plasticizer alternatives to compounders serving agricultural machinery builders.
India
PLI scheme incentives for farm equipment manufacturing are drawing capacity expansions from Deere and Mahindra, creating localized hose specification opportunities. BIS standards govern pressure ratings and material compatibility for domestic equipment sales. Tamil Nadu and Maharashtra industrial zones are emerging as fabrication hubs for tractor hydraulic systems.
China
Dual carbon goals and agricultural mechanization policies are expanding demand for durable hydraulic assemblies in combine harvesters and irrigation equipment. MIIT regulations coordinate with GB standards for pressure equipment safety. Shandong Province manufacturers supply reinforced hose constructions to domestic construction equipment assemblers.
Brazil
Soybean and sugarcane mechanization is extending replacement cycles for hydraulic hoses in harvester fleets operating across Mato Grosso and São Paulo. ANVISA oversees chemical safety in rubber compound formulations. Campinas-based agricultural machinery distributors stock nitrile rubber assemblies for the aftermarket.
Off-Road Hoses Market Competitive Landscape
Global majors compete with regional champions across specification-grade and aftermarket channels. The market structures around three tiers: multinational fluid power conglomerates with OEM validation capabilities, specialized hose fabricators serving regional equipment builders, and catalog distributors competing on availability. Consolidation pressures intensify as fleet operators bypass intermediaries for direct manufacturer relationships. Capacity expansion and REACH-compliant material reformulation represent the dominant competitive vectors.
Within the multinational tier, Parker Hannifin Corporation and Gates Corporation exemplify specification-grade positioning through fluid power portfolios and aftermarket network scale. Eaton Corporation occupies a complementary position across electrical and hydraulic system integration. Continental AG anchors European material science leadership in thermoplastic constructions. These entities represent divergent strategic archetypes: one emphasizing integrated fluid power systems, another prioritizing distribution density, and the third competing on polymer innovation.
| Leading Market Players |
|---|
| OffRoadhose |
| Speedflate |
| JACO |
| MORRFlate |
| MAXTRAX |
| Parker Hannifin Corporation |
| Gates Corporation |
| Eaton Corporation |
| Continental AG |
| Others |
Value Network & Pricing Analysis
Polymer compounding expertise concentrates in Germany's Mannheim-Ludwigshafen chemical cluster, where REACH-compliant formulation specialists command wage premiums that propagate through specification-grade hose pricing tiers.
Pricing Analysis
Input-cost pass-through from synthetic rubber and steel wire reinforcement feeds directly into OEM contract negotiations and aftermarket catalog pricing. Three-tier pricing structure across specification-grade, validated-performance, and commodity-replacement levels separates multi-year OEM agreements from spot aftermarket purchases. Cost compression in the construction equipment aftermarket intensifies as rental fleet operators consolidate procurement through direct manufacturer relationships. Owner-operators and small contractors exhibit highest price sensitivity, while German precision farming OEMs prioritize thermal validation and kink resistance over unit economics.
Supply Chain Analysis
Freight cost volatility on steel wire reinforcement shipments from East Asian metallurgy centers exposes compounders to margin erosion on long-haul procurement. Manufacturing concentrates in Germany, China, and the United States, with compounding operations drawing from nitrile rubber, thermoplastic polyurethane, and phthalate-free plasticizer feedstocks. Single-source vulnerability in braided wire supply creates tariff exposure and logistics disruption risk. Distribution runs through OEM direct specification channels, integrated fleet maintenance contracts, and independent aftermarket distributors serving owner-operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Off-Road Hoses Market functions as a stable compounder, with agricultural fleet renewal timelines and emissions compliance deadlines generating predictable replacement demand across multiple equipment categories.
For Market Incumbents: Lock in specification-grade relationships with German and French precision farming OEMs by accelerating REACH-compliant material validation ahead of enforcement milestones. Defend against margin compression from synthetic rubber feedstock volatility through backward integration into compounding operations or long-term offtake agreements with petrochemical suppliers. For New Entrants and Emerging Players: Launch via telematics-integrated predictive replacement contracts targeting United States construction equipment rental fleets seeking to shift from transactional procurement to recurring service models. India's PLI scheme incentives for farm equipment manufacturing present the most penetrable geography, with localized hose specification opportunities emerging around Deere and Mahindra capacity expansions in Tamil Nadu and Maharashtra. For Investors and Strategic Acquirers: Fluid power conglomerates with integrated electrical-hydraulic system portfolios are the most active acquirers in this space, seeking specification-grade validation capabilities to anchor electrification-era thermal management platforms. Target mid-cap compounders with proven multi-material bonding expertise and established OEM audit relationships. Monitor battery coolant loop specification harmonization efforts by SAE and ISO working groups as the critical inflection signal for platform standardization timing.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | ECHA restrictions on phthalate plasticizers force systematic compound redevelopment across European supply bases. |
| Telematics-Integrated Predictive Replacement | IoT pressure monitoring enables condition-based maintenance contracts with United States rental fleet operators. |
| India Localization Partnership | PLI scheme incentives draw Deere and Mahindra expansions, creating specification opportunities for domestic compounders. |
| Biofuel-Compatible Fuel Hose Retrofit | FAME and HVO mandates across European markets require aftermarket conversion kits for legacy machinery permeation resistance. |
| Multi-Material Bonding Capability Investment | Thermoplastic-to-rubber transition joints in hybrid constructions require polymer scientists in short supply. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM procurement directors, aftermarket distribution managers, fleet maintenance heads, and polymer compounding R&D leads with secondary validation against customs trade data, SEC filings from listed fluid power conglomerates, EPA emissions enforcement records, and ECHA regulatory guidance documents. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Segment-weighting approaches distributed forecast mass across product type, material construction, application equipment category, and end-user channel dimensions throughout the projection horizon. CAGRs derived from equipment fleet renewal timelines, emissions compliance deadline clustering, and electrification penetration curves for battery thermal management applications. Industry-specific inputs included synthetic rubber price indices, agricultural machinery production forecasts, and rental fleet telematics adoption rates.
Several conditions sit outside the modeled scope, including abrupt tariff regime shifts on steel wire reinforcement, unanticipated REACH substance restrictions beyond phthalates, and rapid solid-state battery thermal management architectures that eliminate liquid coolant loops. Forecasts reflect documented assumptions about OEM specification lock-in durations and fleet operator procurement consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Argentina Automotive Parts Aluminium Die Casting Market
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
Automotive Roller Bearing Market
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
Gasoline Direct Injection Market
Automotive Parts
Automotive Hoses Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Automotive Weatherstrips Market
Automotive Parts
Brazil Automotive Hydraulic Actuators Market
Automotive Parts
Brake Shoe Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Leaf Spring Shackle Side Bar Market
Automotive Parts
Automotive Air Lift Jack Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
Africa Passenger Vehicles Lubricants Market