
 Mobile Emission Catalysts Market | 2026-2036
Mobile Emission Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Emission Catalysts Market Intelligence
The classic model separating Original Equipment Manufacturers from Aftermarket Suppliers is collapsing as OEMs demand longer-lasting, integrated systems. This shift favors suppliers with deep R&D and manufacturing scale. BASF SE leverages its extensive chemical expertise to develop next-generation catalyst formulations. Umicore dominates the precious metals recycling loop, providing a crucial hedge against material price volatility for its catalyst products.
Mobile emission catalysts are devices that convert toxic pollutants from internal combustion engine exhaust into less harmful substances through chemical reactions. These systems typically utilize a ceramic substrate coated with a washcoat containing precious metals like platinum, palladium, and rhodium. The market's product portfolio is defined by application, with Three-Way Catalysts remaining the standard for gasoline passenger cars. In contrast, Selective Catalytic Reduction systems are essential for diesel commercial vehicles to meet NOx emission limits.
The regulatory framework is the primary demand driver, with agencies like the US EPA and standards such as the EU's Euro 7 and China's GB standards setting progressively lower emission ceilings. These regulations directly influence catalyst design, loading of precious metals, and durability requirements for all vehicle types. Stakeholders must now navigate the challenge of developing higher-performance catalysts while managing the cost and supply chain risks associated with critical raw materials.
Market Dynamics
The primary structural force shaping the mobile emission catalysts market is the global regulatory mandate for near-zero tailpipe emissions. This pressure, exemplified by the EU's Euro 7 and China's GB standards, compels innovation in catalyst durability and efficiency, directly influencing material science and system design.
Growth Catalysts
- Stringent Emission Standards:Regulations like the EU's Euro 7 introduce stricter limits on pollutants such as NOx and non-methane hydrocarbons, compelling the adoption of more advanced and higher-value catalyst systems across all vehicle types.
- Commercial Vehicle Expansion:Growth in logistics and freight, particularly in markets like China and India, drives demand for heavy-duty vehicles equipped with Selective Catalytic Reduction (SCR) systems to comply with national emission norms.
- Integrated Aftertreatment Systems:The increasing use of Gasoline Particulate Filters (GPFs) in direct-injection gasoline engines necessitates their integration with Three-Way Catalysts, creating demand for more complex and sophisticated single-canister solutions.
Market Restraints
- Precious Metal Price Volatility:The market is highly exposed to price fluctuations and supply uncertainties for precious group metals like rhodium, palladium, and platinum, which are critical active materials in catalyst formulations.
- BEV Substitution Threat:The accelerating transition to battery electric vehicles (BEVs) represents a fundamental long-term restraint, as BEVs do not have exhaust systems and therefore require no emission catalysts.
- Technical Durability Hurdles:Engineering catalysts to maintain performance over the extended full useful life periods mandated by regulators like the US EPA presents a significant technical and cost challenge for manufacturers.
Strategic Opportunities
- Alternative Fuel Catalysis:Developing specialized catalysts for emerging powertrains, such as hydrogen internal combustion engines (H2-ICE) and engines running on e-fuels, opens a new, high-performance market segment.
- Non-Road Mobile Machinery:Expanding emission regulations for agricultural and construction equipment in developing nations provides an opportunity to adapt existing catalyst technologies for the off-highway vehicle sector.
- Advanced PGM Recycling:Investing in closed-loop recycling technologies to recover higher yields of precious metals from end-of-life catalysts offers a hedge against raw material costs and a sustainable supply source.
Industry Challenges
- Global Certification Complexity:The need to validate and certify catalyst systems against a patchwork of different regional standards, including those from the EPA, ECHA, and China's MEE, creates significant administrative and testing overhead.
- System Integration with On-Board Diagnostics:Ensuring flawless communication and performance between the catalyst system and the vehicle's engine control unit (ECU) and OBD systems is a major integration challenge that can impact development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Emission Catalysts Market |
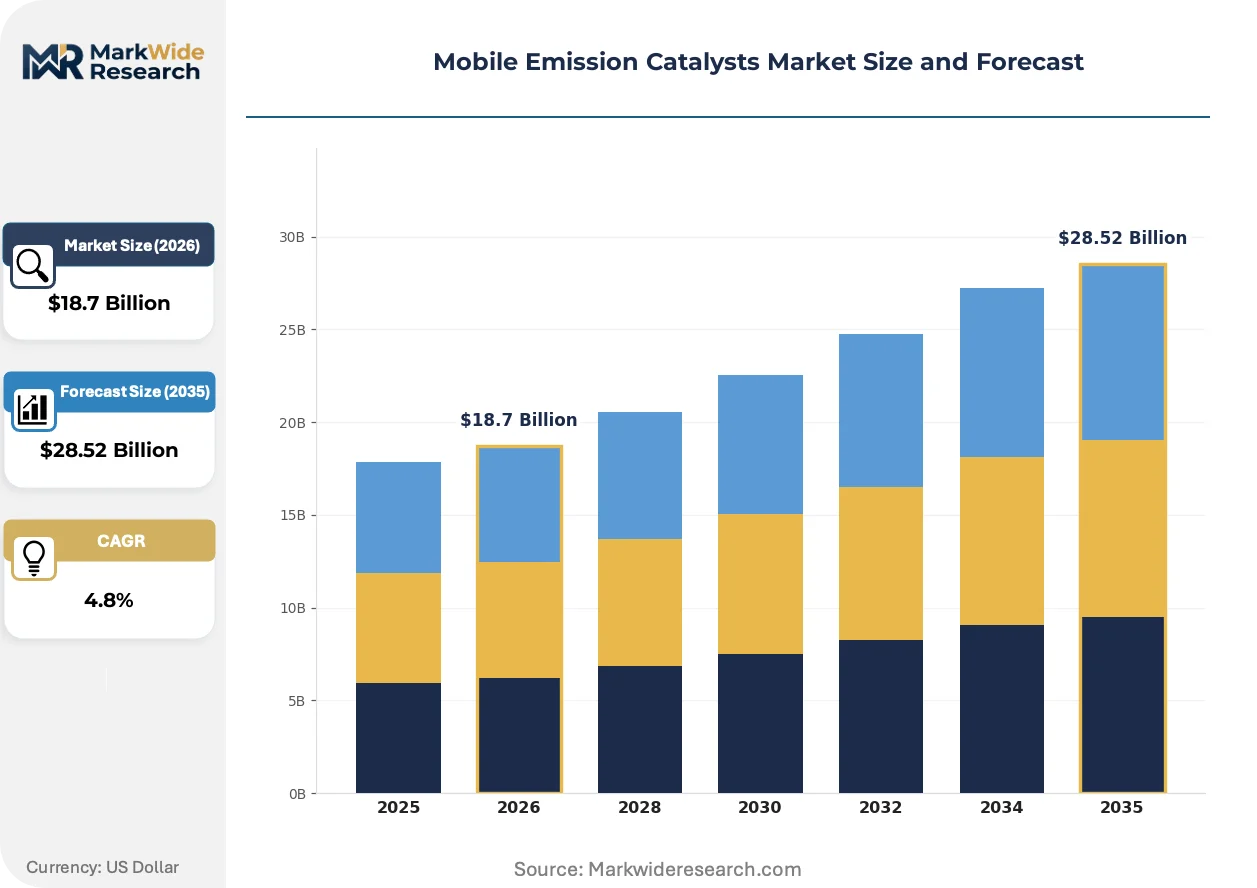
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Three-Way Catalysts, Diesel Oxidation Catalysts, Lean NOx Traps, Selective Catalytic Reduction, Soot Filters Application: Passenger Cars, Commercial Vehicles, Off-Highway Equipment, Two-Wheelers, Light-Duty Trucks Technology: Platinum-Based, Palladium-Based, Rhodium-Based, Ceramic Substrate, Metal Substrate End User: Original Equipment Manufacturers, Aftermarket Suppliers, Fleet Operators, Vehicle Assemblers, Parts Distributors |
| Companies Covered | Johnson Matthey, BASF SE, Umicore, Clariant, Cataler Corporation, Heraeus Holding, Corning Incorporated, Tenneco Inc., N.E. CHEMCAT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Emission Catalysts Market Strategic Shifts & Innovations
Innovation in the mobile emission catalysts market is driven by the dual pressures of meeting stricter regulatory targets while mitigating exposure to volatile precious metal supply chains. This is forcing a shift towards more efficient material use and integrated system design.
Advanced catalyst formulations using significantly lower loads of precious group metals (PGMs) are gaining traction. These systems employ novel washcoat chemistries and substrate designs to maximize the reactive surface area. Automotive OEMs are actively evaluating these low-PGM solutions for next-generation platforms, and this development is displacing the long-standing industry reliance on high-cost, high-loading catalyst designs.
The US EPA's Clean Trucks Plan is a pivotal regulatory development that is reshaping the heavy-duty vehicle segment. The rule mandates substantial reductions in NOx emissions and extends the required durability of aftertreatment systems. This directly impacts the North American commercial vehicle market, forcing engine and truck manufacturers to invest in higher-performance SCR catalysts and more robust diagnostic systems.
A clear shift in OEM sourcing strategy is altering the competitive landscape. Automakers are moving away from purchasing individual components and are instead procuring fully integrated and pre-validated exhaust aftertreatment modules from a smaller set of Tier 1 suppliers. This trend is most pronounced in the European passenger car market, where system complexity and warranty risk are major considerations.
Mobile Emission Catalysts Market Segmentation
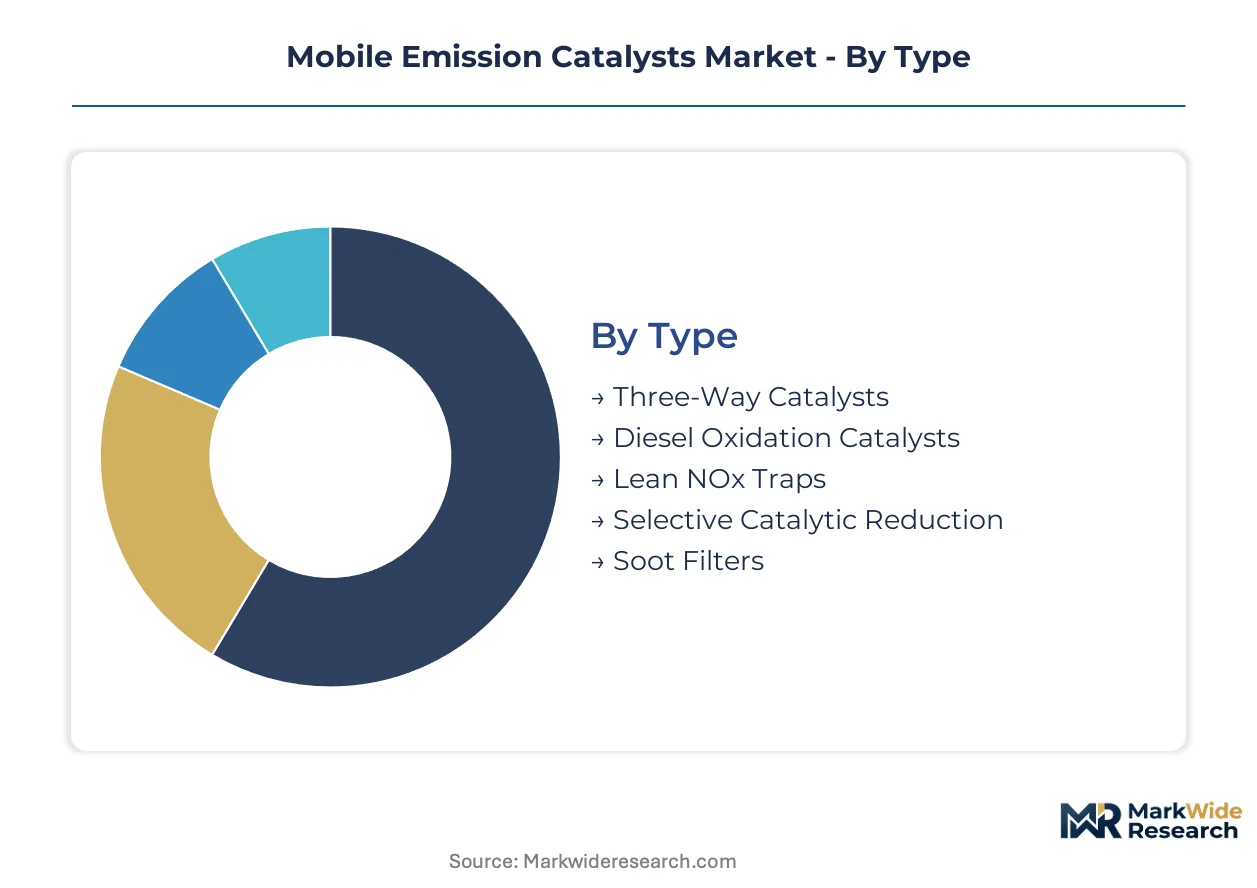
Understanding the segmentation of the mobile emission catalysts market is crucial for identifying areas of concentrated demand, technological differentiation, and strategic investment. This analysis highlights how distinct product types, applications, technologies, and end-user requirements shape the competitive landscape and drive innovation across the industry.
Type:
The distribution of catalyst types to end-users reflects distinct vehicle platforms and regulatory requirements, influencing the material science and system integration demands for each segment.
- Three-Way Catalysts:These systems are the standard for gasoline passenger cars, converting carbon monoxide, unburnt hydrocarbons, and nitrogen oxides into less harmful substances. Demand concentrates in high-volume automotive production markets like China, driven by the stringent GB standards for light-duty vehicles.
- Selective Catalytic Reduction:Essential for diesel commercial vehicles, these systems reduce nitrogen oxide emissions by injecting a reductant like urea into the exhaust stream. Growth in logistics and freight, particularly in India and Europe, drives demand for these advanced systems.
- Diesel Oxidation Catalysts:These catalysts oxidize carbon monoxide and hydrocarbons into less harmful substances for diesel engines, often forming part of a larger aftertreatment system.
- Lean NOx Traps:These systems adsorb nitrogen oxides under lean exhaust conditions and then release them for reduction during brief rich regeneration phases, typically in some diesel applications.
- Soot Filters:Also known as Diesel Particulate Filters, these devices capture particulate matter from diesel engine exhaust, requiring periodic regeneration to burn off accumulated soot.
Three-Way Catalysts dominate the installed base for light-duty vehicles. Selective Catalytic Reduction is where expansion concentrates for heavy-duty applications.
Application:
Volume demand for mobile emission catalysts varies significantly across vehicle applications, driven by production scales and emission compliance needs for each segment.
- Passenger Cars:This segment represents the largest volume of catalyst consumption, primarily utilizing Three-Way Catalysts for gasoline engines. Stricter EU Euro 7 and US EPA standards compel advanced catalyst designs for these high-volume vehicles.
- Commercial Vehicles:This segment includes heavy-duty trucks and buses, predominantly using Selective Catalytic Reduction systems to meet NOx emission limits. Expansion in global logistics, particularly in China, drives demand for these systems to comply with national emission norms.
- Off-Highway Equipment:Catalysts for agricultural and construction machinery face expanding emission regulations in developing nations, adapting existing technologies for robust operating conditions.
- Light-Duty Trucks:These vehicles often share catalyst technologies with passenger cars but require robust solutions tailored for their varied duty cycles and load capacities.
- Two-Wheelers:This segment uses simpler catalytic converters, with demand significantly influenced by tightening emission standards in dense urban markets across Asia, such as India.
Passenger Cars maintain the largest share of catalyst consumption. Commercial Vehicles are climbing the fastest due to increasing freight movement.
Technology:
Catalyst technology selection often involves a trade-off between performance efficacy and raw material cost, particularly concerning precious metals, impacting market adoption.
- Palladium-Based:These catalysts often serve as primary active components in Three-Way Catalysts for gasoline engines due to their cost-effectiveness relative to rhodium. Automotive OEMs in Europe are increasingly evaluating these solutions for next-generation platforms to manage PGM exposure.
- Ceramic Substrate:These substrates provide high surface area and thermal stability, forming the structural backbone for most catalytic converters. Their widespread adoption in high-volume production is due to their cost efficiency and robust performance under diverse operating conditions.
- Platinum-Based:Primarily used in diesel oxidation catalysts and some three-way catalyst formulations, platinum offers high activity for carbon monoxide and hydrocarbon oxidation.
- Rhodium-Based:Critical for nitrogen oxide reduction in three-way catalysts, rhodium's price volatility makes its efficient utilization a key design challenge for manufacturers.
- Metal Substrate:Offering lower thermal inertia and higher mechanical strength, metal substrates find application in specific high-performance or compact catalyst designs where space is limited.
Ceramic Substrate technologies remain foundational for catalyst production. Palladium-Based systems are gaining share fastest due to cost-performance balance.
End User:
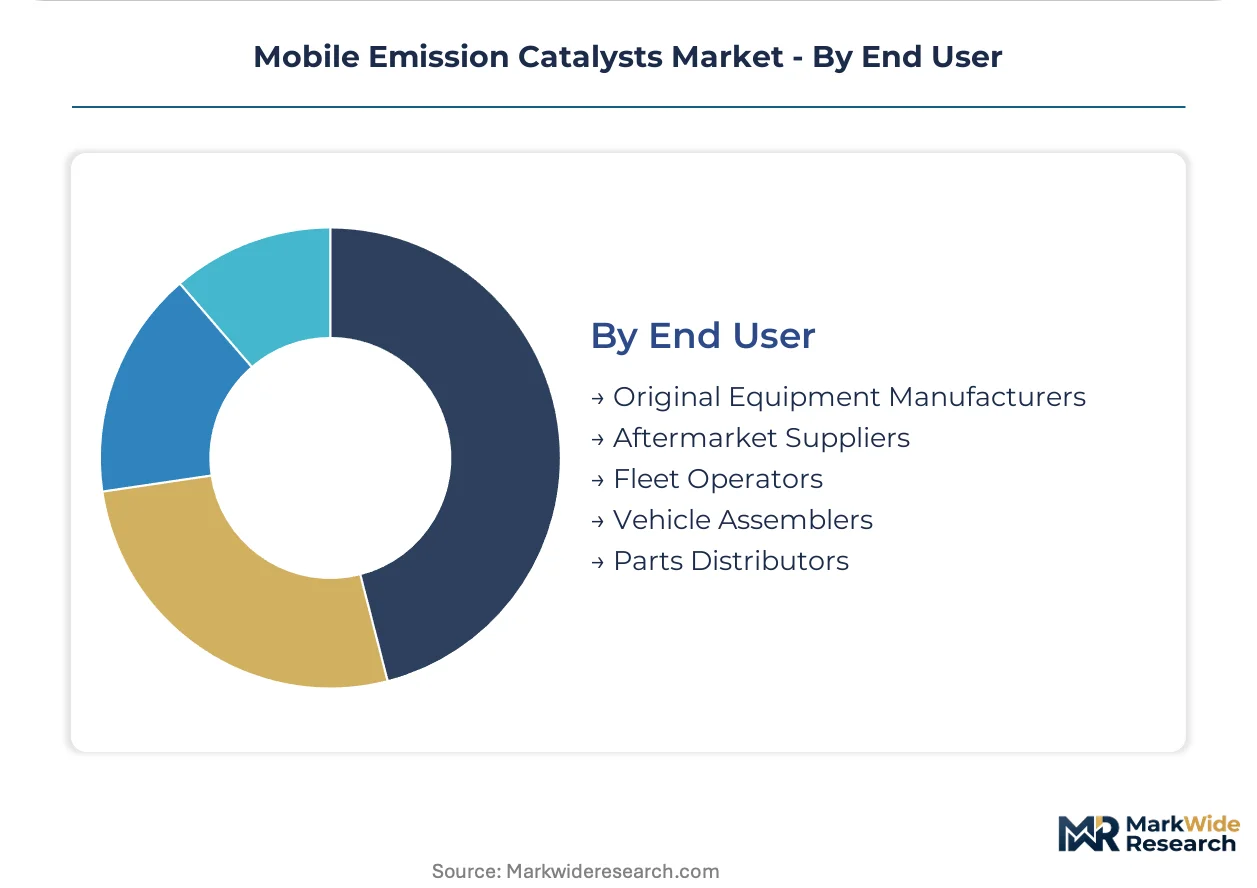
The customer type dictates procurement patterns and integration requirements for mobile emission catalysts, ranging from direct manufacturing supply to replacement parts distribution.
- Original Equipment Manufacturers:These entities integrate catalysts directly into new vehicle production lines, demanding highly customized and validated systems with long durability. Automakers in Germany are increasingly procuring fully integrated exhaust aftertreatment modules from Tier 1 suppliers.
- Aftermarket Suppliers:These companies provide replacement catalyst units for vehicles already in operation, focusing on standardized fitment and compliance with local emission regulations. Demand for these products in the US is influenced by vehicle longevity and repair cycles.
- Fleet Operators:These entities often procure catalysts as part of comprehensive maintenance programs, prioritizing durability and cost-efficiency for their large vehicle inventories.
- Vehicle Assemblers:These organizations integrate catalyst systems into the final vehicle assembly process, requiring just-in-time delivery and stringent quality assurance from suppliers.
- Parts Distributors:These companies supply a wide range of catalyst components to repair shops and individual consumers, focusing on inventory management and efficient logistics networks.
Original Equipment Manufacturers represent the largest purchasing segment. Fleet Operators show the steepest expansion trajectory for replacement parts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive manufacturing infrastructure, particularly assembly lines and trade routes, underwrites the demand for mobile emission catalysts across major production hubs. Stricter environmental regulations globally compel advanced catalyst technologies for vehicle exhaust systems. This drives innovation and adoption in key automotive markets worldwide.
China
China's massive automotive production volume and expanding commercial vehicle fleet drive significant catalyst demand. The country's stringent GB standards, including GB 6b, mandate advanced aftertreatment systems for both light and heavy-duty vehicles. Manufacturing clusters in the Yangtze River Delta, like Shanghai, actively develop and produce these compliant catalyst systems.
United States
The large passenger car market and heavy-duty truck segment in the United States create substantial demand for emission catalysts. The US EPA's Clean Trucks Plan and Tier 3 emission standards impose rigorous requirements for NOx and particulate matter reduction. Automotive manufacturing regions such as Michigan's Detroit area integrate advanced catalyst technologies into new vehicle platforms.
Germany
Premium automotive manufacturing and a strong focus on diesel commercial vehicles sustain catalyst demand in Germany. EU's Euro 7 standards enforce stringent limits on pollutants, pushing for higher-performance catalyst designs across the vehicle fleet. The Rhine-Main region, with its automotive R&D centers, leads in developing next-generation catalyst formulations.
India
India's rapidly expanding vehicle market, especially for two-wheelers and commercial vehicles, fuels the need for emission catalysts. The Bharat Stage (BS) VI emission norms require advanced catalytic converters for all new vehicle registrations. Automotive hubs like Chennai and Pune are increasing local production capabilities for these compliant aftertreatment systems.
Japan
Advanced automotive manufacturing and a focus on fuel efficiency contribute to steady demand for mobile emission catalysts in Japan. The country's own stringent emission regulations, aligned with global standards, necessitate continuous innovation in catalyst technology. Regions like Aichi Prefecture, a major automotive production center, focus on integrated exhaust system development.
Mobile Emission Catalysts Market Key Industry Players
Concentration sits with large, integrated chemical and materials science companies that possess extensive R&D capabilities. The market structure exhibits a tiered consolidation, with a few global Tier 1 suppliers dominating the OEM segment. Strategic archetypes include diversified chemical giants, specialized precious metal refiners, and integrated exhaust system providers. Dominant competitive moves involve strategic partnerships for system integration and continuous R&D investment in low-PGM formulations.
Within the specialized chemical manufacturing tier, Johnson Matthey and BASF SE exemplify companies leveraging deep material science expertise to develop advanced catalyst formulations. Johnson Matthey, a UK-based sustainable technologies company, focuses on innovative PGM-based and PGM-free catalyst solutions. BASF SE, a German chemical giant, contributes through its extensive chemical portfolio and global manufacturing footprint. Umicore, a Belgian-based materials technology group, occupies a crucial position in the precious metals recycling loop, providing a sustainable supply chain for critical raw materials and enhancing circularity. These entities anchor the market's innovation trajectory through their extensive research and development efforts.
| Leading Market Players |
|---|
| Johnson Matthey |
| BASF SE |
| Umicore |
| Clariant |
| Cataler Corporation |
| Heraeus Holding |
| Corning Incorporated |
| Tenneco Inc. |
| N.E. CHEMCAT |
| Others |
Cost & Logistics Intelligence
Extended lead times for advanced catalyst formulations directly influence pricing power, especially for systems requiring high PGM content. This duration reflects the complex material sourcing and specialized manufacturing processes inherent in the supply chain.
Pricing Analysis
Volume-based discount structures characterize pricing in the mobile emission catalysts market, particularly for large OEM contracts. The dominant pricing model is contract-based long-term offtake, reflecting the high upfront R&D investment and customized integration required. Price differentiation stems from the volume scale of orders and the customization level for integrated aftertreatment modules. Pricing pressure originates from the accelerating BEV substitution threat and the inherent PGM price volatility. Aftermarket suppliers exhibit the highest price sensitivity, contrasting with OEMs who prioritize validated performance and durability for new vehicle platforms.
Supply Chain Analysis
China, Germany, and Japan anchor the global manufacturing and advanced R&D for mobile emission catalysts. The supply chain draws from critical raw material dependencies including platinum, palladium, and rhodium, primarily sourced from South Africa and Russia. A significant structural risk is the inherent commodity price volatility of precious group metals, impacting manufacturing costs and long-term planning. Downstream distribution runs predominantly direct-to-OEM for new vehicle production, while the aftermarket relies on a multi-tier network of parts distributors and specialized suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile emission catalysts market is defined by a scarcity of advanced material science expertise required for low-PGM formulations. This gap compels strategic positioning around R&D and integrated system development.
For Market Incumbents:Compound investments in advanced PGM recycling technologies to mitigate precious metal price volatility and secure sustainable supply. Deepen R&D into next-generation PGM-free or ultra-low PGM catalyst formulations to counter the long-term BEV substitution threat. Strategic partnerships with automotive OEMs for integrated aftertreatment module development will reinforce market position against emerging component suppliers. This proactive approach ensures relevance in a rapidly evolving regulatory and technological landscape.
For New Entrants and Emerging Players:Specialized catalysis for hydrogen internal combustion engines represents a service-layer gap where incumbents are under-serving. Target the expanding non-road mobile machinery segment in developing nations by adapting existing robust catalyst technologies. Focus on developing unique solutions for alternative fuels, leveraging agility to address specific performance requirements. A go-to-market angle emphasizing rapid customization and certification for niche applications will differentiate offerings.
For Investors and Strategic Acquirers:Long-term, this sits as a compliance-driven technology play because stringent emission regulations will persist for internal combustion engines for decades. Identify mid-cap specialists with proprietary PGM-reduction technologies or advanced precious metal recycling capabilities as prime acquisition targets. Prioritize companies demonstrating strong intellectual property in novel washcoat chemistries and substrate designs. The commercialization success of PGM-free catalyst solutions will serve as a critical inflection signal for future valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced PGM Recycling Investment | Secures critical raw material supply and mitigates price volatility for catalyst manufacturers. |
| Low-PGM Catalyst R&D Acceleration | Reduces manufacturing costs and enhances competitiveness against BEV substitution threat. |
| Integrated Aftertreatment Module Partnerships | Aligns with OEM sourcing strategy for pre-validated, complex exhaust systems. |
| Non-Road Emissions Solution Development | Expands market reach into agricultural and construction equipment sectors. |
| Alternative Fuel Catalysis Expertise | Positions for emerging powertrains like hydrogen ICE and e-fuels, creating new revenue streams. |
Research Approach
A spread of perspectives from catalyst R&D directors, OEM procurement leads, regulatory compliance officers, and aftermarket distributors converged on the working assumptions for this analysis. The methodology integrated primary interviews with robust secondary research, drawing from US EPA reports, EU Euro standards documentation, China GB standards, and global automotive production statistics. Bottom-up and top-down triangulation validated volume and value estimates.
Product type, application, technology, end-user, and regional regulatory compliance constituted the core segmentation dimensions modeled across the analysis window. The analytical framework projected market evolution based on historical data and anticipated shifts in vehicle electrification and emission standards. Compound annual growth rates were derived from a detailed assessment of these factors. Key industry-specific inputs included global vehicle production forecasts and specific emission regulation timelines.
Forecasts assume regulatory continuity in the US EPA, EU, and China GB regimes; material policy shifts would require re-modeling. Unforeseen acceleration in BEV adoption or significant precious metal supply disruptions represent key risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Japan Ceramic Ball Bearings Market
Automotive Parts
Engine Oil Pan Market
Automotive Parts
Engine Oil Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
Global All Wheel Drive Market
Automotive Parts
Smart Adaptive Headlights Market
Automotive Parts
Engine Piston Ring Set Market
Automotive Parts
Ball Bearing Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Global Automotive Gas Charged Shock Absorbers Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Automotive Crankcase Additives Market
Automotive Parts
Automotive Axle and Propeller Shaft Market
Automotive Parts
Germany Automotive Hydraulic Actuators Market
Automotive Parts
Global Climate Control System for Commercial Vehicle Market