
 Global Bevel Gearbox Market | 2026-2036
Global Bevel Gearbox Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bevel Gearbox Market Analysis
OEM-direct procurement channels for heavy-gear systems is reconfiguring as mill operators and turbine builders consolidate supplier lists. Gleason Corporation leverages its cutter and testing equipment ecosystem to sustain captive demand for precision-ground spiral bevel sets. Bonfiglioli Riduttori S.p.A. anchors European industrial machinery lines with modular vertical installations. SEW-EURODRIVE GmbH & Co KG competes through integrated motor-gearbox packages that dominate conveyor and bulk-material handling specifications.
A bevel gearbox transmits rotational power between intersecting shafts, typically at 90 degrees, using conical gear teeth machined to AGMA or DIN quality grades with surface hardness exceeding 58 HRC after carburizing. Its primary purpose is to redirect torque in confined drivetrain envelopes while preserving mechanical efficiency above 97 percent in spiral bevel architectures. Spiral bevel configurations command the widest application footprint across aerospace and marine propulsion systems where load distribution and noise suppression justify premium positioning. Straight bevel designs retain cost-sensitive volume in agricultural and light industrial machinery where intermittent duty cycles predominate. Hypoid variants are displacing conventional spiral sets in automotive axle applications due to their offset pinion geometry enabling lower driveshaft tunnels.
ISO 1328 gear accuracy standards, AGMA 2001-D04 bending and pitting resistance ratings, and EU machinery directive 2006/42/EC collectively dictate tooth geometry tolerances, safety enclosure requirements, and CE market access protocols for power-transmission equipment sold into European industrial installations. China's GB/T 10095 national gear standard and Japan's JIS B 1702 create parallel compliance tracks that shape export qualification costs for non-domestic suppliers. Stakeholders must monitor evolving carbon-border adjustment mechanisms and regional content thresholds that threaten to fragment previously unified gearbox sourcing strategies.
Market Dynamics
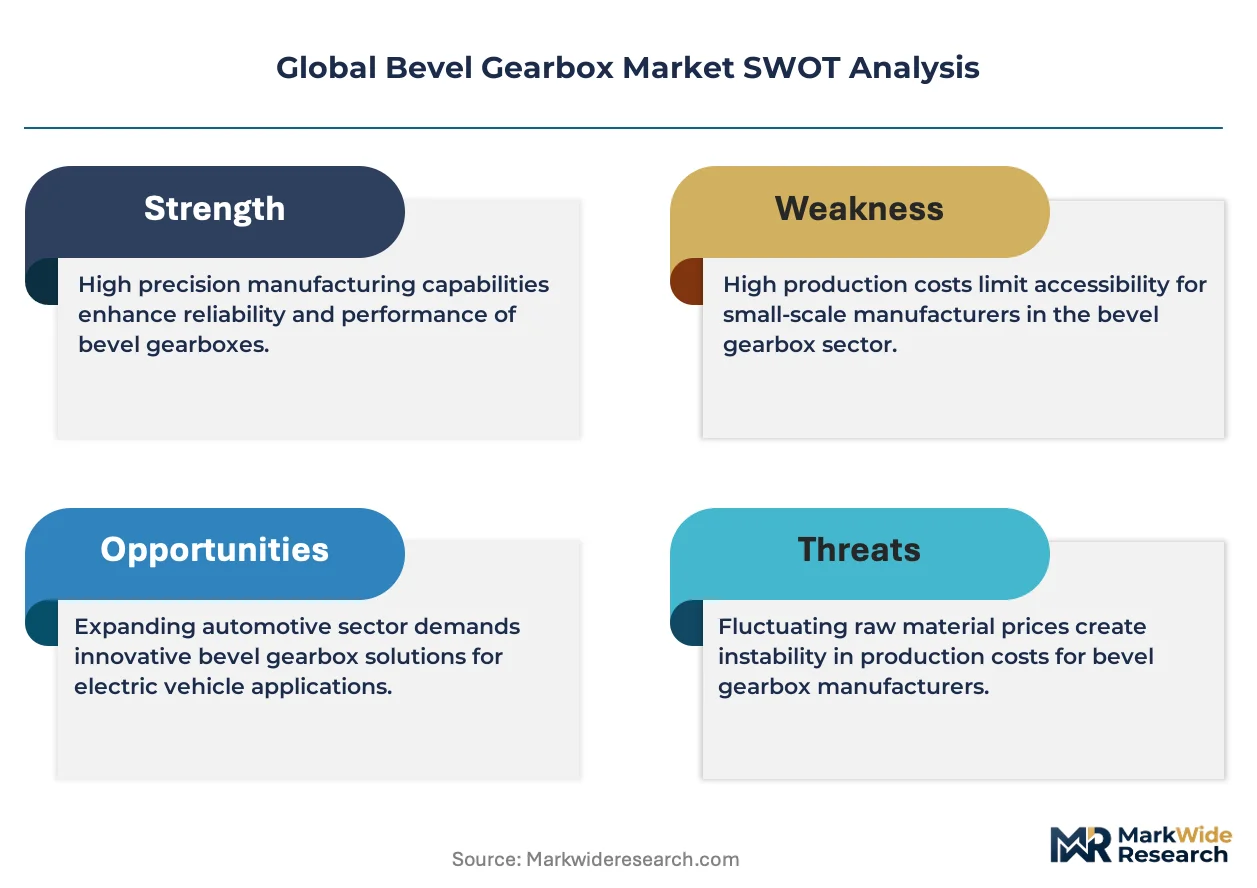
ISO 1328 gear accuracy standards and tightening AGMA quality grades are forcing manufacturers to retool grinding and hard-finishing capabilities, consolidating procurement around suppliers with captive metrology and cutter ecosystems.
Growth Catalysts
- Wind-turbine drivetrain retrofits:Coastal manufacturing clusters across China are concentrating demand for spiral bevel configurations rated for 20-year service life in offshore environments.
- EU machinery directive 2006/42/EC:CE marking requirements for safety enclosures and emergency-stop integration are filtering out uncertified suppliers from European industrial installations.
- Carburizing process advances:Vacuum low-pressure carburizing with high-pressure gas quenching is extending surface hardness consistency above 58 HRC for aerospace landing-gear applications.
Market Restraints
- Alloy steel price volatility:Nickel and molybdenum input costs for case-hardening grades fluctuate with mining output from Indonesian and Philippine concentrate suppliers.
- Grinding wheel supply concentration:Precision vitrified CBN wheels for spiral bevel finishing depend on Japanese and German abrasive manufacturers with 18-month order backlogs.
- Dimensional substitution:Compact planetary and cycloidal drives are capturing light-load redirect applications below 50 kW where bevel efficiency advantages diminish.
Strategic Opportunities
- India industrial corridor expansion:BIS certification alignment with ISO 1328 is opening qualification pathways for precision-ground sets in cement and steel mill upgrades.
- Digital twin integration:Convergence of finite element tooth-contact analysis with IoT vibration monitoring is enabling predictive maintenance contracts for marine propulsion systems.
- US Inflation Reduction Act:Domestic content bonuses for wind-energy components are incentivizing localized spiral bevel production for nacelle drivetrains.
Industry Challenges
- Gleason cutter programming expertise:Spiral bevel tooth geometry optimization requires specialized CAM operators with 5+ years of machine-specific training.
- Multi-standard certification timelines:Simultaneous AGMA 2001-D04, DIN 3991, and JIS B 1702 qualification extends product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bevel Gearbox Market |
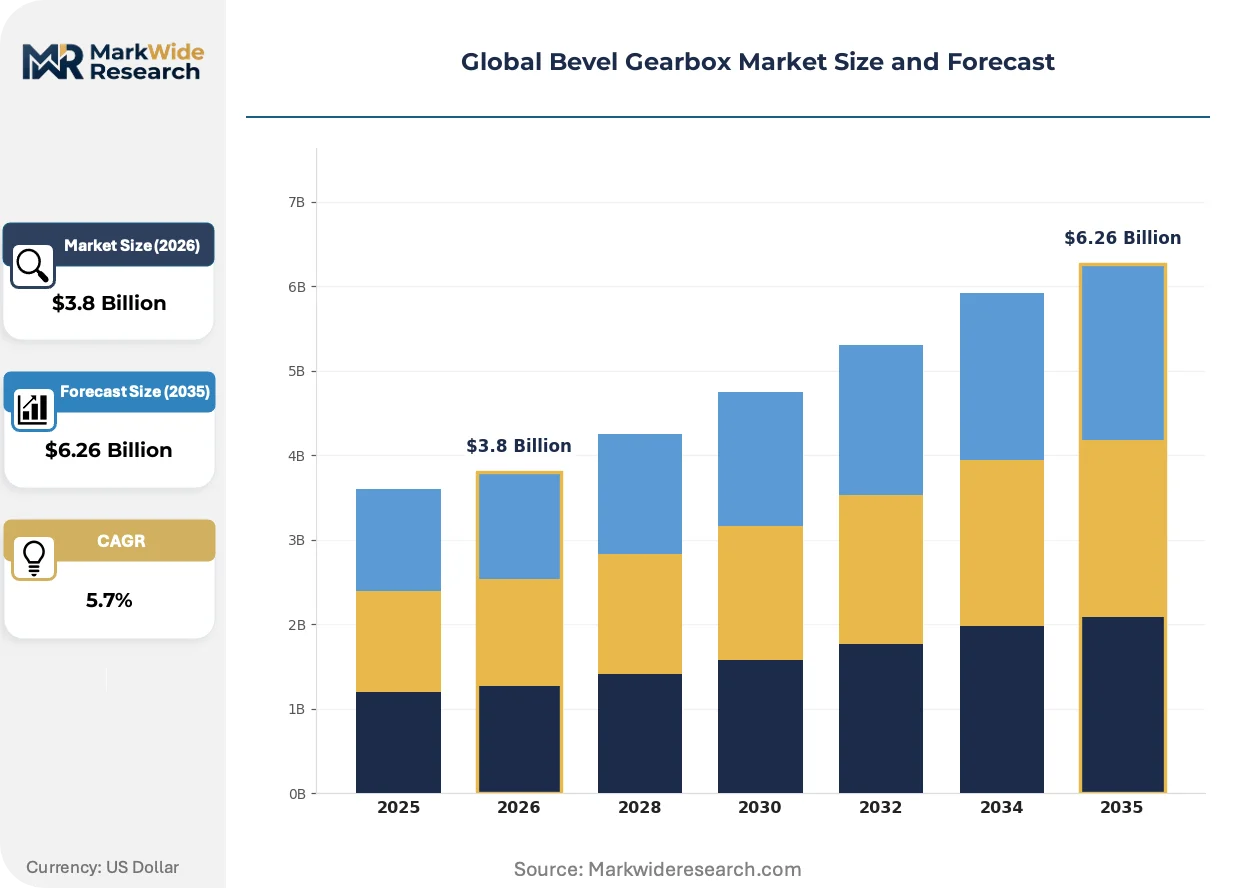
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hypoid, Straight Bevel, Spiral Bevel, Miter Application: Aerospace, Automotive, Industrial Machinery, Marine End User: Manufacturers, OEMs, System Integrators, Repair Shops Installation Type: Horizontal, Vertical, Compact, Custom |
| Companies Covered | Gleason Corporation, Bonfiglioli Riduttori S.p.A., SEW-EURODRIVE GmbH & Co KG, Boston Gear LLC, Nord Drivesystems, Klingelnberg Group, David Brown Santasalo, Apex Dynamics, Inc., Regal Rexnord Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bevel Gearbox Market Emerging Trajectories
Virtual simulation and closed-loop manufacturing are compressing prototype-to-production cycles while regulatory carbon accounting and buyer consolidation are rewriting supplier qualification protocols.
Digital twin platforms for bevel gear tooth contact analysis are virtualizing physical test-stand validation for spiral bevel sets. Aerospace drivetrain engineers at Boeing and Airbus suppliers now iterate 30+ load scenarios in silico before cutting first prototypes. This capability is collapsing development timelines from 18 months to under 9 months for new ratio configurations.
REACH restrictions on chromium(VI) post-treatment coatings are mandating trivalent chrome and thin-film dense chrome alternatives for corrosion protection in marine and offshore applications. German gearbox manufacturers serving North Sea wind farms must reformulate surface finishing lines by 2026. The shift is elevating qualification costs for smaller European suppliers without captive plating capacity.
Mill operators and turbine builders are consolidating approved vendor lists from 12-15 suppliers to 3-5 strategic partners with full-service capabilities. Direct OEM procurement teams now require integrated motor-gearbox packages, predictive maintenance APIs, and 15-year spare-part guarantees. This concentration is most visible in German automotive supplier parks and Chinese coastal wind-energy manufacturing clusters.
Global Bevel Gearbox Market Segmentation
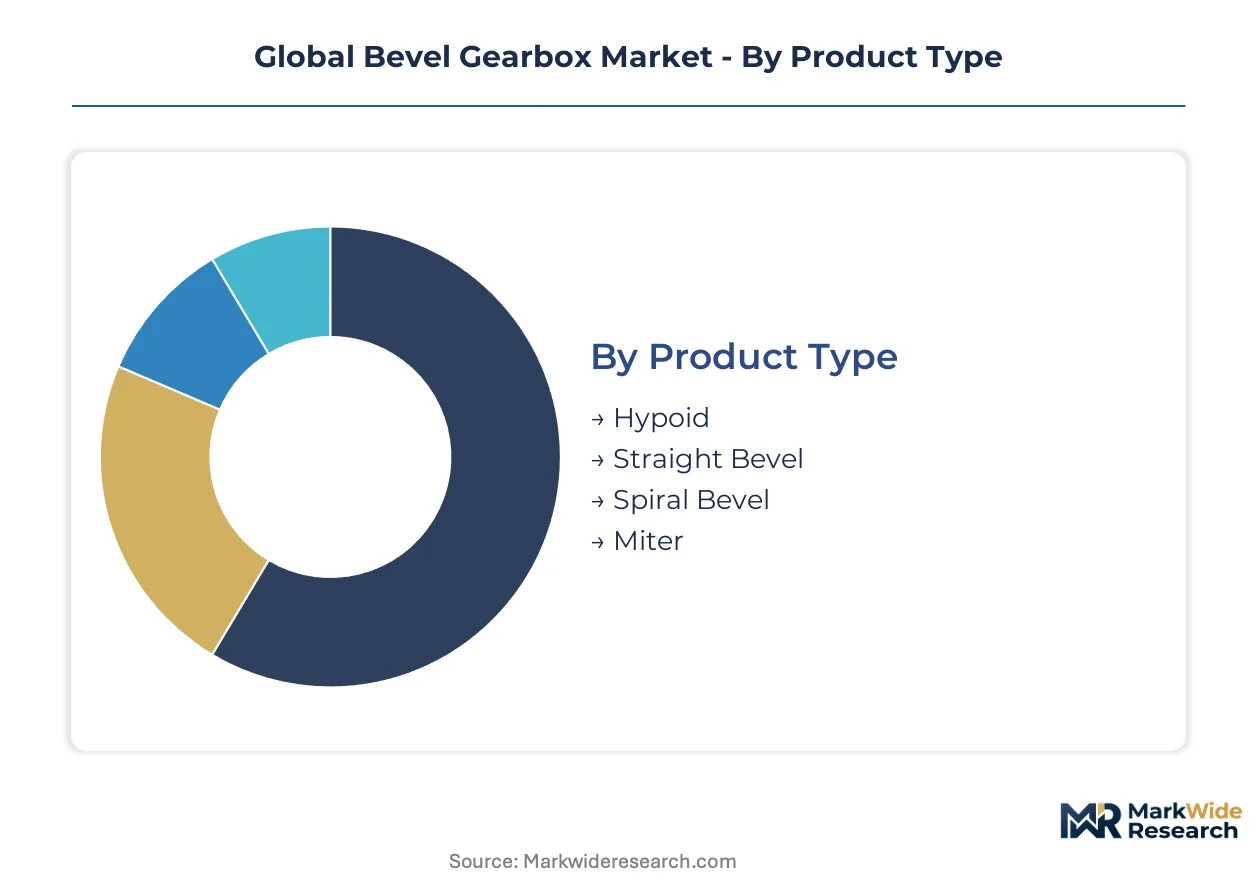
Bevel gearbox procurement patterns diverge sharply across product architectures and end-use requirements. Aerospace drivetrain engineers prioritize spiral bevel precision for noise suppression, while automotive axle manufacturers migrate toward hypoid geometries for packaging efficiency.
Product Type:
Use-case spectrum spans from intermittent-duty agricultural equipment to continuous-load marine propulsion systems requiring 20-year service intervals.
- Spiral Bevel:Curved tooth geometry distributes contact across multiple teeth simultaneously, achieving mechanical efficiency above 97 percent. Wind-turbine drivetrain retrofits in China's coastal manufacturing clusters concentrate demand for hardened sets rated to AGMA 14/ISO 1328 Grade 4 accuracy.
- Hypoid:Offset pinion positioning enables lower driveshaft tunnels in passenger vehicle architectures. Automotive axle applications in Germany and Japan are displacing conventional spiral sets as NVH thresholds tighten and cabin packaging constraints intensify.
- Straight Bevel:Simple conical tooth geometry suits cost-sensitive intermittent duty cycles. Agricultural implement manufacturers in India's industrial corridors specify these for seasonal harvest equipment where capital recovery periods dominate lifecycle economics.
- Miter:1:1 ratio conical pairs redirect power at 90 degrees without speed change. Conveyor system builders specify compact miter boxes for tight envelope material handling installations where space claims preclude alternative architectures.
The dominant share belongs to Spiral Bevel, while Hypoid is closing the gap fastest.
Application:
Customer investment intensity separates continuous-process industries from intermittent-duty equipment purchasers.
- Industrial Machinery:Cement mills and steel rolling operations specify heavy-duty spiral bevel sets with 15-year spare-part guarantees. German machinery OEMs consolidate approved vendor lists around suppliers offering integrated motor-gearbox packages and predictive maintenance APIs.
- Aerospace:Landing-gear actuation and flight-control surface mechanisms demand vacuum low-pressure carburizing with surface hardness consistency exceeding 58 HRC. Boeing and Airbus suppliers now iterate 30-plus load scenarios in digital twin environments before prototype cutting.
- Automotive:Axle and differential applications drive volume demand for precision-ground hypoid sets. Japanese tier-1 suppliers face REACH-mandated surface finishing line reformulation by 2026, elevating qualification barriers for chromium(VI)-dependent processes.
- Marine:Offshore propulsion and dynamic positioning systems require corrosion-resistant coatings compliant with trivalent chrome alternatives. North Sea wind-farm service vessels specify sealed spiral bevel drivetrains with IoT vibration monitoring for predictive maintenance contracting.
Industrial Machinery commands the largest installed base, though Aerospace exhibits the steepest expansion trajectory.
End User:
Procurement sophistication varies from specification-driven OEM engineering teams to price-sensitive aftermarket repair operations.
- OEMs:Direct engineering engagement with gearbox suppliers enables custom ratio optimization and integrated motor-gearbox packaging. Wind-turbine nacelle builders in the United States leverage domestic content bonuses under the Inflation Reduction Act to localize spiral bevel sourcing.
- System Integrators:Turnkey drivetrain contractors require multi-standard certification alignment across AGMA, DIN, and JIS protocols. Simultaneous qualification extends product launch cycles by 14-18 months, filtering out suppliers without captive metrology capabilities.
- Manufacturers:In-house production equipment builders prioritize modular vertical installations with standardized mounting interfaces. Bonfiglioli Riduttori anchors European industrial lines with configurable bevel-helical combinations for material handling specifications.
- Repair Shops:Aftermarket replacement demand concentrates on legacy straight bevel sets for agricultural and light industrial equipment. Inventory carrying costs favor suppliers with regional distribution hubs near Midwestern US farming corridors and India's cement belt.
OEMs retain specification authority, while System Integrators are gaining procurement influence fastest.
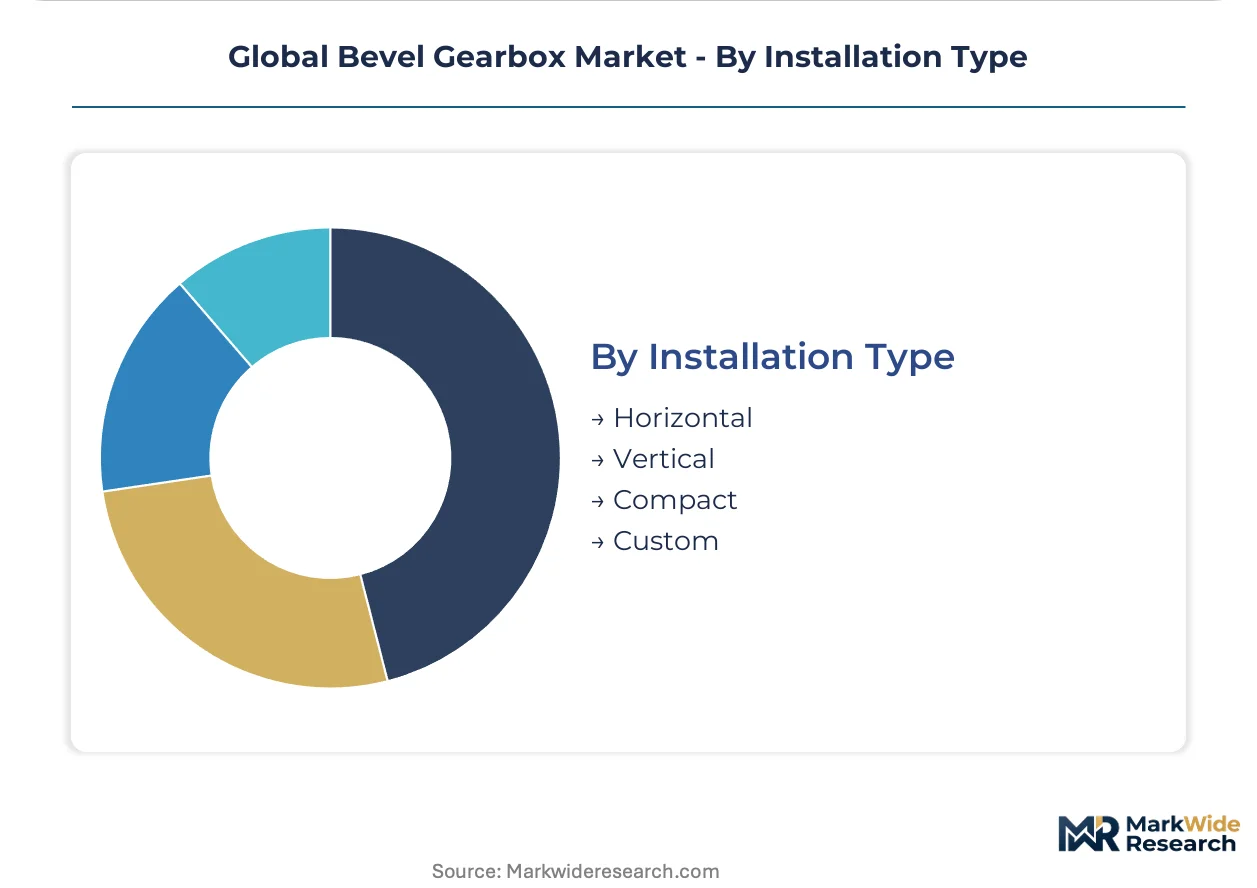
Installation Type:
Physical mounting constraints and thermal management requirements shape enclosure design and lubrication system selection.
- Vertical:Downward-facing output shafts demand enhanced sealing against contamination ingress. Modular vertical configurations from European suppliers dominate bulk-material handling conveyor specifications where floor-space optimization drives layout decisions.
- Compact:Reduced center-distance designs substitute for planetary drives in light-load redirect applications below 50 kW. Cycloidal alternatives capture share where bevel efficiency advantages diminish at smaller torque ratings.
- Horizontal:Standard foot-mounted configurations suit majority of industrial machinery applications with accessible maintenance access. SEW-EURODRIVE's integrated motor-gearbox packages dominate this specification tier through conveyor and bulk-handling verticals.
- Custom:Non-standard shaft orientations and envelope constraints require Gleason cutter programming expertise with 5-plus years of machine-specific training. Specialized CAM operators optimize spiral bevel tooth geometry for aerospace and marine propulsion applications.
Horizontal installations maintain the dominant share, while Compact configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates with German and Japanese precision-ground spiral bevel suppliers, while Chinese coastal manufacturers compete on volume for wind-turbine retrofit contracts. This asymmetry shapes procurement consolidation patterns across industrial machinery and renewable energy verticals.
United States
Wind-turbine nacelle builders source spiral bevel sets under Inflation Reduction Act domestic content bonuses. The FAA certifies aerospace landing-gear actuation systems with surface hardness requirements exceeding 58 HRC. Manufacturing clusters in the Pacific Northwest and Midwest concentrate drivetrain assembly for export markets.
Germany
Cement mill and steel rolling operations specify heavy-duty spiral bevel configurations with 15-year spare-part guarantees. REACH mandates trivalent chrome alternatives for corrosion protection by 2026, elevating qualification barriers. Industrial machinery OEMs in Bavaria and North Rhine-Westphalia consolidate approved vendor lists around integrated motor-gearbox packages.
China
Coastal manufacturing clusters in Jiangsu and Guangdong concentrate demand for 20-year service life spiral bevel sets in offshore wind applications. GB/T 10095 national gear standards create parallel compliance tracks shaping export qualification costs. MIIT industrial policy accelerates localization of precision grinding capabilities for aerospace suppliers.
Japan
Automotive tier-1 suppliers face JIS B 1702 alignment with tightening NVH thresholds in passenger vehicle axle applications. METI supports vacuum low-pressure carburizing process advances for aerospace drivetrain components. Nagoya and Osaka industrial corridors host captive metrology ecosystems for AGMA 14/ISO 1328 Grade 4 accuracy qualification.
India
BIS certification alignment with ISO 1328 opens qualification pathways for cement and steel mill upgrades in Maharashtra and Gujarat. CEA power sector mandates drive wind-turbine drivetrain retrofit demand. The PLI scheme incentivizes precision gear manufacturing capacity in industrial corridor expansions.
Global Bevel Gearbox Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in cutter and testing equipment ecosystems. The supplier base organizes around three strategic tiers: precision-ground spiral bevel manufacturers with captive metrology, modular vertical installation providers for bulk-material handling, and integrated motor-gearbox packagers dominating conveyor specifications. Consolidation pressures favor full-service capabilities over single-product vendors. Two dominant competitive moves reshape positioning: direct OEM procurement channel expansion and predictive maintenance API integration.
Among precision-ground spiral bevel specialists, Gleason Corporation anchors the cutter and testing equipment ecosystem, while Bonfiglioli Riduttori S.p.A. occupies a position within modular vertical installation architectures. SEW-EURODRIVE GmbH & Co KG exemplifies the integrated motor-gearbox packaging tier. These three entities represent distinct competitive archetypes rather than overlapping market positions, with each commanding specification authority in discrete application verticals through differentiated capability configurations.
| Leading Market Players |
|---|
| Gleason Corporation |
| Bonfiglioli Riduttori S.p.A. |
| SEW-EURODRIVE GmbH & Co KG |
| Boston Gear LLC |
| Nord Drivesystems |
| Klingelnberg Group |
| David Brown Santasalo |
| Apex Dynamics, Inc. |
| Regal Rexnord Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese precision grinding capacity is pressuring spiral bevel set pricing while simultaneously compressing margins for European and Japanese suppliers maintaining AGMA 14 certification tiers. This utilization asymmetry rewards buyers consolidating vendor lists around full-service providers with captive metrology and hard-finishing capabilities.
Pricing Analysis
The customization-premium spread between configured-to-order spiral bevel sets and standard catalog configurations spans three distinct pricing tiers tied to ISO 1328 accuracy grades and carburizing process specifications. Project-based pricing dominates heavy industrial machinery applications requiring 15-year spare-part guarantees, while per-unit transactional structures govern agricultural and light industrial straight bevel procurement. Price differentiation rests on certification level and geographic delivery cost, with REACH-compliant trivalent chrome finishing commanding substantial premiums over legacy chromium(VI) alternatives. Cost compression in standard-grade configurations is intensifying because of cycloidal drive substitution below 50 kW ratings. Aftermarket repair shops exhibit highest price sensitivity, while aerospace landing-gear OEMs prioritize surface hardness consistency above 58 HRC regardless of cost.
Supply Chain Analysis
Contract manufacturing concentration for precision spiral bevel finishing rests with Japanese and German abrasive specialists holding 18-month backlogs on vitrified CBN grinding wheels. Geographic supply concentration centers on Germany, Japan, and China for hardened gear production, with India emerging as a secondary hub for cement and steel mill retrofit demand. Raw material dependencies draw from Indonesian and Philippine nickel-molybdenum concentrate suppliers for case-hardening alloy grades. Single-source vulnerability in precision cutter ecosystems threatens production continuity for Gleason-programmed tooth geometries. Distribution runs through direct OEM procurement channels consolidating around integrated motor-gearbox packagers with predictive maintenance API capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts for marine propulsion and wind-turbine drivetrain applications are expanding faster than hardware-only revenue streams, transforming bevel gearbox procurement into a service-attach opportunity with recurring telemetry-based revenue layers.
For Market Incumbents: Insulate spiral bevel pricing power by deepening captive metrology investments and hard-finishing capacity in Germany and Japan, where AGMA 14/ISO 1328 Grade 4 qualification creates defendable moats against Chinese volume competitors. Accelerate digital twin integration with IoT vibration monitoring to capture predictive maintenance contracts before system integrators consolidate vendor lists to 3-5 strategic partners. Cycloidal drive substitution below 50 kW represents the most immediate substitution threat requiring portfolio response. For New Entrants and Emerging Players: India's industrial corridor expansion in Maharashtra and Gujarat offers the most penetrable geographic entry point, where BIS certification alignment with ISO 1328 is opening qualification pathways for precision-ground sets in cement and steel mill upgrades. Target repair shop aftermarket demand for legacy straight bevel configurations in Midwestern US farming corridors, where inventory carrying costs favor regional distribution hubs over incumbent centralized logistics. A go-to-market angle anchored to 15-year spare-part guarantees with modular vertical installation configurations can bypass entrenched integrated motor-gearbox packagers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across vacuum low-pressure carburizing process lines, as aerospace landing-gear applications demand surface hardness consistency exceeding 58 HRC. Long-term viability over the next decade favors precision-ground spiral bevel specialists with captive cutter programming expertise and Gleason ecosystem integration. Acquisition targets should exhibit demonstrated multi-standard certification capabilities spanning AGMA, DIN, and JIS protocols. The signal to watch is consolidation velocity in approved vendor lists from 12-15 suppliers toward 3-5 strategic partners, which will determine which mid-cap specialists achieve scale escape velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance API Integration | Enables IoT vibration monitoring contracts for North Sea wind-farm service vessels. |
| Multi-Standard Certification Investment | AGMA 2001-D04, DIN 3991, and JIS B 1702 alignment filters out uncertified competitors from European industrial installations. |
| Backward Integration into Cutter Programming | Captive Gleason CAM operators with 5-plus years of machine-specific training secure spiral bevel tooth geometry optimization. |
| Domestic Content Localization | US Inflation Reduction Act bonuses incentivize spiral bevel production for wind-turbine nacelle drivetrains. |
| REACH-Compliant Surface Finishing Transition | Trivalent chrome alternatives reformulate plating lines for German North Sea wind-farm suppliers by 2026. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from listed industrial equipment manufacturers, AGMA technical standards documentation, and IHS Markit industrial production databases. Primary interviews engaged maintenance directors at cement and steel mills, OEM procurement teams specifying integrated motor-gearbox packages, aftermarket service heads managing spare-part inventory, and plant engineers overseeing drivetrain retrofits. Bottom-up triangulation across facility-level demand and top-down validation through national industrial output statistics ensures cross-verified market sizing.
Forecast inputs include product type segmentation across spiral, hypoid, straight bevel, and miter configurations; application splits between industrial machinery, aerospace, automotive, and marine verticals; end-user differentiation among OEMs, system integrators, manufacturers, and repair shops; and installation type variation across vertical, compact, horizontal, and custom mounting arrangements. CAGRs were derived through regression analysis of historical procurement patterns against capacity expansion announcements and regulatory compliance timelines. Industry-specific inputs incorporate wind-turbine drivetrain retrofit pipelines, REACH-mandated surface finishing transitions, and MIIT industrial policy localization targets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese coastal manufacturers scaling precision grinding capacity or cycloidal drive specialists expanding above 50 kW ratings would shift outcomes. Quarterly review of vendor list consolidation velocity, grinding wheel order backlogs, and alloy steel price volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Global Automotive Engine Valves Market
Automotive Parts
Automotive Suspension System Market
Automotive Parts
UAE Automotive Lubricants Market
Automotive Parts
Automotive Parking Heater Market
Automotive Parts
Auxiliary Oil Cooler Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
North America Automotive Airfilters Market
Automotive Parts
Automotive Control Arms Market
Automotive Parts
Automotive Belts and Hoses Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
North America Automotive AHSS Market
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Passenger Car Motor Oil Market