
 Isopentane Market | 2026-2036
Isopentane Market Size, Share, and Industry Trends Forecast 2026-2036
Isopentane Market Outlook
Gulf Coast petrochemical producers is pivoting toward lighter feedstock slates to capture isopentane yields from natural gas liquids fractionation. Chevron Phillips Chemical Company leverages its Cedar Bayou complex to sustain high-purity isopentane output for domestic polymer customers. ExxonMobil Chemical anchors North American supply through integrated Beaumont refining and chemical operations. Shell Chemicals competes on global logistics reach across Asian and European derivative markets.
Isopentane is a branched-chain alkane with molecular formula C₅H₁₂ and boiling point near 28°C, produced via fractional distillation of natural gasoline or catalytic isomerization of n-pentane, serving primarily as a physical blowing agent and non-polar solvent. The chemical intermediate segment dominates value capture due to downstream integration into specialty rubber and adhesive formulations. Solvent-grade isopentane differentiates through ultra-low aromatic specifications demanded by pharmaceutical extraction protocols. Refrigerant applications are concentrating in European markets where F-Gas Regulation phase-downs favor hydrocarbon alternatives with negligible global warming potential.
EPA SNAP approvals and EU F-Gas Regulation constrain hydrofluorocarbon alternatives while elevating hydrocarbon blowing agent status across construction and appliance sectors. China's GB standards and MEE enforcement on volatile organic compound emissions shape product purity thresholds for domestic chemical processors. Stakeholders must monitor feedstock cost spreads between NGL-derived and refinery-stream isopentane as cracker feedslate economics shift with regional natural gas pricing.
Market Dynamics
Feedstock slates at Gulf Coast fractionators are tilting toward lighter natural gas liquids to maximize isopentane yields, compressing supply elasticity as cracker operators compete for the same NGL streams.
Growth Catalysts
- EPA SNAP Program:Mandated phase-out of HCFC-based blowing agents in US polyurethane foam manufacturing is redirecting formulation demand toward hydrocarbon alternatives with negligible ozone depletion potential.
- EU F-Gas Regulation:Progressive hydrofluorocarbon phase-down schedules are elevating hydrocarbon refrigerant status across European commercial refrigeration and heat pump installations.
- Polymerization chemistry:Specialty rubber manufacturers are expanding isopentane-derived intermediate consumption for high-performance adhesive and sealant formulations serving automotive lightweighting programs.
Market Restraints
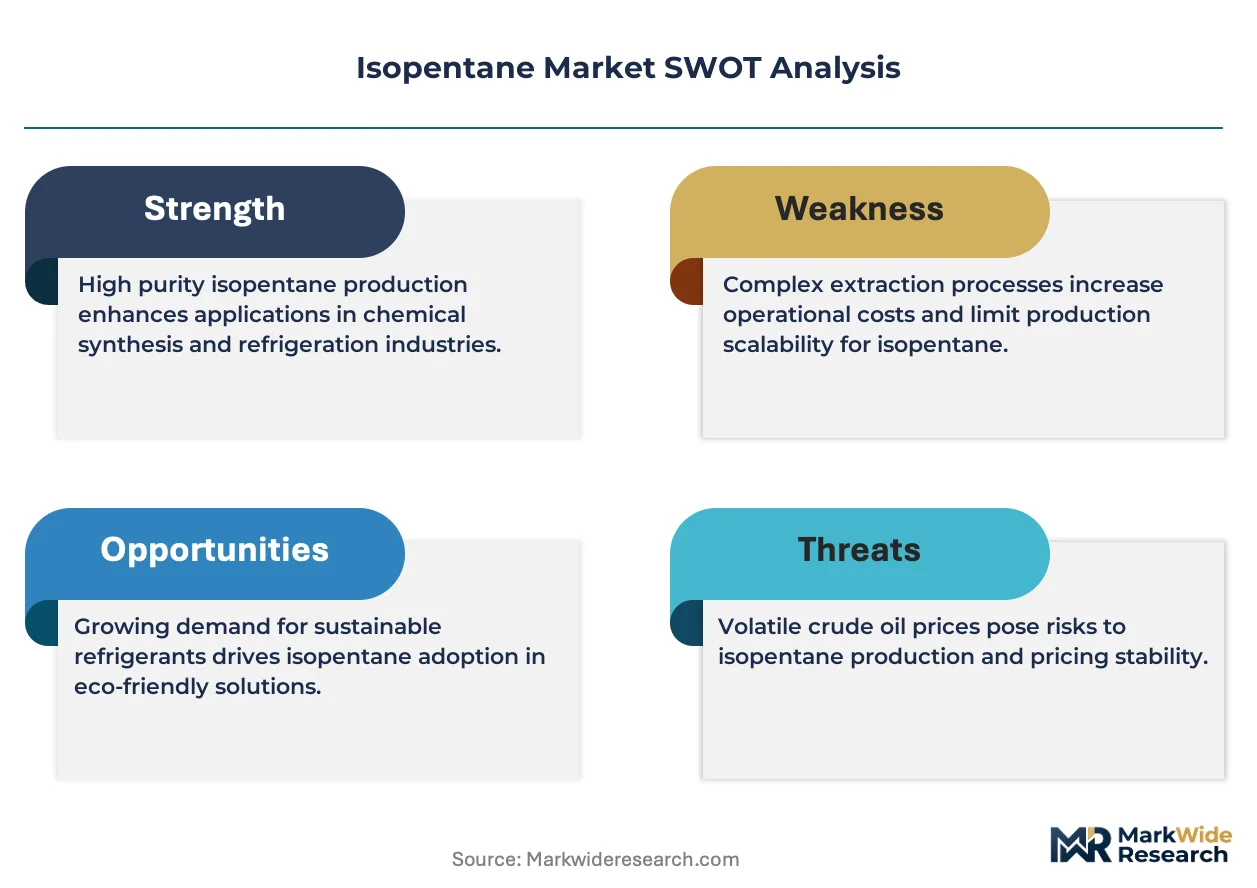
- NGL price volatility:Feedstock cost spreads between natural gas liquids and refinery-stream pentanes fluctuate with Henry Hub pricing, squeezing fractionator margins during winter heating demand spikes.
- Concentrated supply geography:High-purity isopentane production clusters along the US Gulf Coast and select Chinese petrochemical corridors, exposing buyers to hurricane and logistics disruption risks.
- Aromatic contamination thresholds:Pharmaceutical extraction protocols demand ultra-low benzene specifications below 10 ppm, requiring capital-intensive purification infrastructure that limits new entrant participation.
Strategic Opportunities
- Indian chemical processing:BIS standards evolution and PLI scheme incentives for domestic specialty chemical manufacturing are creating first-mover advantages for blowing agent suppliers establishing local technical service capabilities.
- Electronics cleaning applications:Semiconductor fabs are evaluating hydrocarbon solvent alternatives to perfluorinated compounds for wafer cleaning processes, opening specification development partnerships with solvent-grade producers.
- Japanese refrigerant transition:METI carbon neutrality roadmaps and revised fluorocarbon emission control laws are accelerating hydrocarbon adoption in commercial cold chain infrastructure ahead of regulatory deadlines.
Industry Challenges
- Specialized fractionation engineering:Separating isopentane from mixed C5 streams with pharmaceutical-grade purity requires cryogenic distillation expertise that remains concentrated among a limited contractor base.
- Cross-border certification timelines:REACH registration dossiers and EPA PMN notifications for new isopentane supply sources extend 18-36 months, delaying market entry for emerging producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isopentane Market |
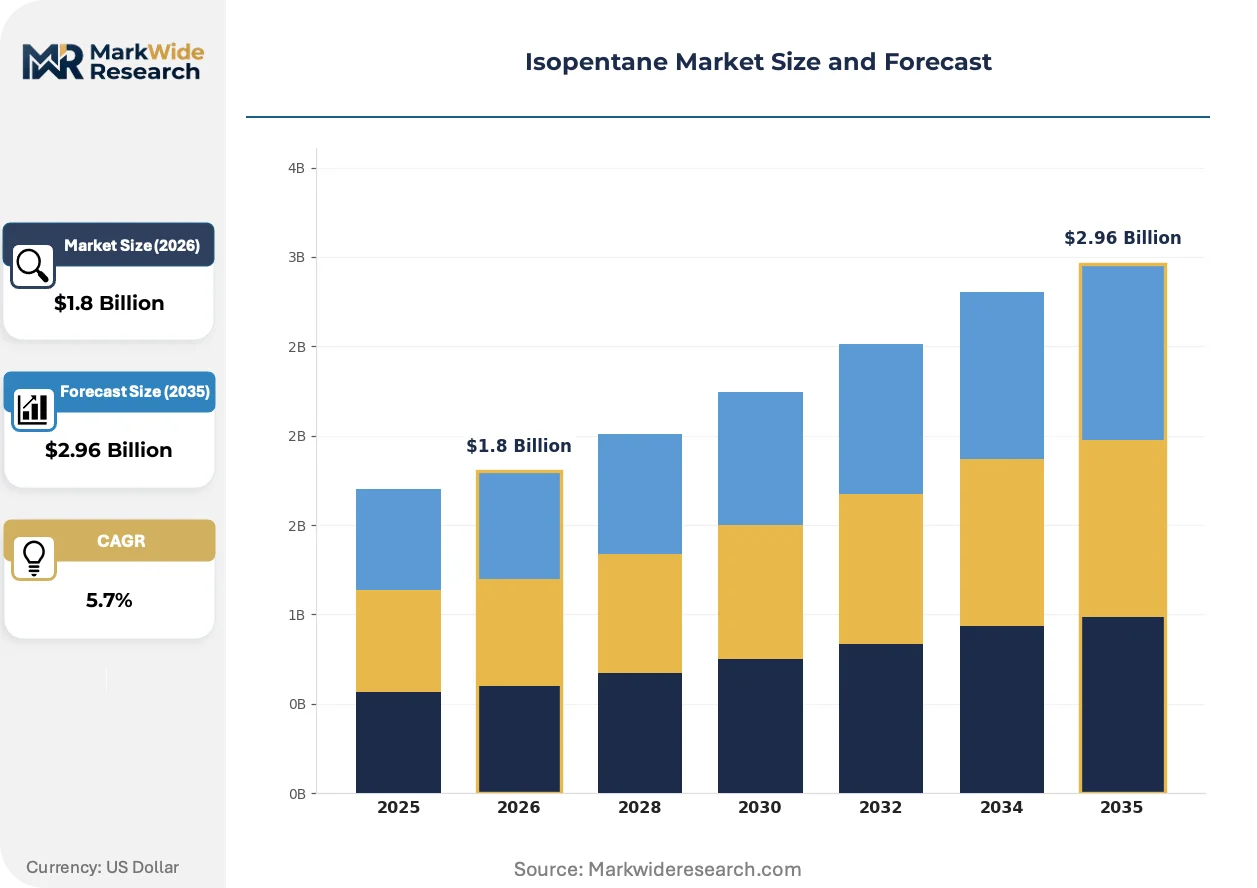
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isomer, Chemical Intermediate, Solvent, Refrigerant Application: Blowing Agent, Fuel Additive, Laboratory Solvent, Specialty Chemical End User: Pharmaceuticals, Petrochemicals, FMCG, Research Institutions Distribution Channel: Direct Sales, Distributors, Online Retailers, Bulk Suppliers |
| Companies Covered | Chevron Phillips Chemical Company, Aeropres Corporation, ExxonMobil Chemical, HCS Group, South Hampton Resources, Shell Chemicals, Junyuan Petroleum Group, Linde Group, Phillips 66, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isopentane Market Strategic Shifts
Process intensification and regulatory chemistry are compressing product development cycles while reshaping how buyers evaluate total cost of ownership across blowing agent and solvent applications.
Advanced adsorptive separation technology using metal-organic frameworks is unifying purification and recovery operations at integrated petrochemical sites. Polymer foam manufacturers in Germany and the Netherlands are piloting these systems to eliminate aromatic contamination without multi-stage distillation. The technology is compressing capital requirements for pharmaceutical-grade production while tightening purity specifications industry-wide.
EU F-Gas Regulation phase-down mechanics are forcing refrigerant formulators toward hydrocarbon blends with lower global warming potential. Commercial refrigeration OEMs serving supermarket chains are redesigning system architectures to accommodate flammable refrigerant charge limits. Italian and Spanish cold chain operators are accelerating retrofit timelines ahead of 2030 quota reductions.
Specification-driven procurement now dominates blowing agent selection for construction insulation. Building envelope contractors are consolidating supplier relationships around technical service capabilities rather than spot pricing. This pattern concentrates procurement volume among fractionators offering formulation support and regulatory documentation packages, particularly visible in French and German passive house construction markets.
Isopentane Market Segmentation
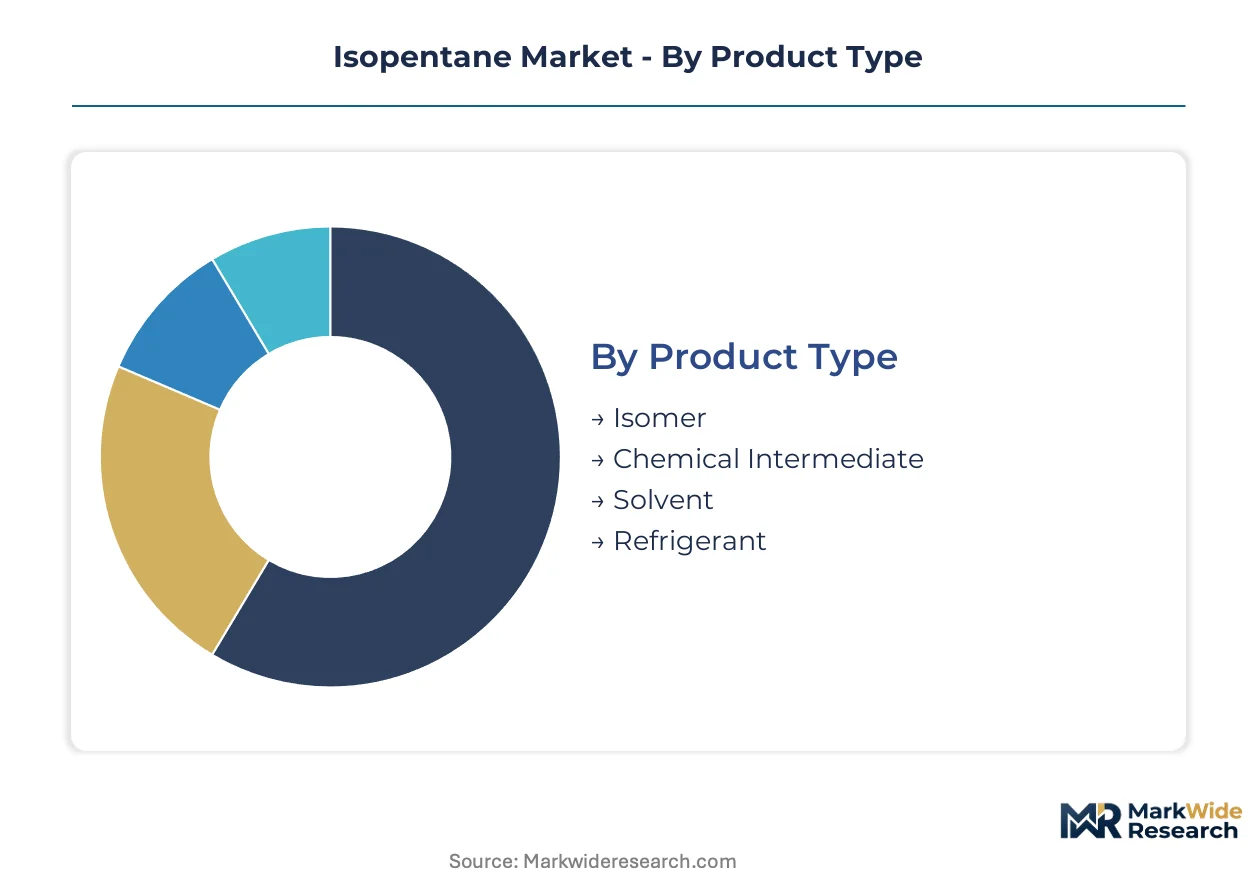
Isopentane demand fragments across specification tiers that command radically different margin profiles. Technical purity thresholds determine whether material captures pharmaceutical extraction premiums or competes as commodity blowing agent feedstock.
Product Type:
Specification chemistry separates commodity-grade from pharmaceutical-grade economics, with purification intensity defining competitive moats.
- Isomer:Branched C5 alkane produced via catalytic isomerization of n-pentane or direct fractionation of natural gasoline. Polyurethane foam manufacturers in the US and Germany concentrate procurement here for EPA SNAP and EU F-Gas compliant blowing agent formulations.
- Chemical Intermediate:Feedstock for specialty rubber polymerization and high-performance adhesive synthesis. Demand clusters in Jiangsu and Shandong provinces where integrated petrochemical complexes achieve backward integration into downstream rubber formulations.
- Solvent:Ultra-low aromatic grade required for pharmaceutical extraction protocols. Purity thresholds below 10 ppm benzene restrict supply to cryogenic distillation specialists with capital-intensive purification infrastructure.
- Refrigerant:Hydrocarbon alternative with negligible global warming potential. European commercial refrigeration OEMs redesign system architectures around flammable charge limits mandated by EU F-Gas Regulation phase-down schedules.
Isomer leads on scale; refrigerant leads on momentum.
Application:
End-use functionality dictates procurement patterns, with regulatory chemistry accelerating segment divergence.
- Blowing Agent:Physical foaming agent replacing HCFC systems in construction insulation and appliance manufacturing. US EPA SNAP mandates compress formulation windows, concentrating volume among fractionators offering regulatory documentation packages.
- Fuel Additive:Octane enhancement component and gasoline volatility modifier. Refinery integration determines supply economics, with Gulf Coast producers leveraging NGL fractionation proximity.
- Laboratory Solvent:Non-polar medium for chromatography and extraction procedures. Research institutions specify ultra-high purity grades with batch certification requirements that extend procurement cycles.
- Specialty Chemical:Precursor for agrochemical and fragrance synthesis. Contract manufacturers in India evaluate local technical service capabilities under evolving BIS standards.
Blowing agent dominates volume capture; specialty chemical climbs fastest.
End User:
Customer sophistication varies dramatically, with certification requirements filtering supplier eligibility.
- Pharmaceuticals:cGMP-compliant manufacturers demand solvent-grade material with comprehensive CoA documentation and audit trails. Regulatory scrutiny from FDA and EMA elevates supplier qualification timelines.
- Petrochemicals:Integrated producers consume isopentane as internal intermediate for rubber and adhesive derivatives. Gulf Coast and Chinese corridor operators achieve margin capture through downstream integration.
- FMCG:Aerosol propellant and packaging applications. Procurement emphasizes supply security over specification intensity, favoring bulk suppliers with logistics reliability.
- Research Institutions:Fragmented demand across academic and government laboratories. Small-lot flexibility and technical support outweigh unit cost considerations.
Petrochemicals anchor volume; pharmaceuticals command premium pricing power.
Distribution Channel:
Channel selection reflects customer scale and specification complexity, with service intensity inversely correlating to transaction size.
- Direct Sales:Dedicated account management for polymer foam manufacturers and pharmaceutical formulators. Technical service teams co-develop formulation solutions and regulatory submission packages.
- Distributors:Regional inventory positioning for mid-volume chemical processors. Stocking locations in Rotterdam, Singapore, and Houston compress lead times for spot demand.
- Online Retailers:Small-package fulfillment for research laboratories and educational institutions. Limited to standard-grade material with straightforward specifications.
- Bulk Suppliers:Tanker and railcar delivery for refinery and petrochemical consumers. Economies of scale in logistics favor high-volume, low-frequency procurement patterns.
Direct sales leads on margin contribution; distributors lead on geographic reach expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping isopentane production geography as EPA SNAP compliance costs in the United States diverge from EU F-Gas enforcement intensity. Producers are optimizing fractionation asset placement around these cost-of-compliance gaps.
United States
EPA SNAP mandates on HCFC phase-out are concentrating polyurethane foam formulation demand along the Gulf Coast. The Cedar Bayou complex and Beaumont refining corridor anchor high-purity fractionation capacity for domestic polymer customers. Hurricane exposure remains the persistent supply risk.
Germany
EU F-Gas Regulation quota reductions are accelerating hydrocarbon refrigerant adoption in commercial cold chain infrastructure. Passive house construction standards in Bavaria and Baden-Württemberg are consolidating procurement around suppliers offering technical documentation packages.
China
GB standards and MEE enforcement on volatile organic compound emissions are tightening purity thresholds for chemical processors. Petrochemical expansion corridors in Jiangsu and Shandong provinces are integrating backward into specialty rubber and adhesive derivatives.
India
BIS standards evolution and PLI scheme incentives for specialty chemical manufacturing are creating first-mover opportunities for blowing agent suppliers. Domestic technical service capabilities are becoming the qualification barrier for contract manufacturers in Gujarat and Maharashtra.
Japan
METI carbon neutrality roadmaps and revised fluorocarbon emission control laws are accelerating hydrocarbon adoption ahead of regulatory deadlines. Commercial refrigeration OEMs in the Kansai region are redesigning system architectures around flammable refrigerant charge limits.
Isopentane Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade purification and electronics solvent specifications. The vendor base stratifies between integrated petrochemical majors with captive NGL feedstock access and specialized fractionators serving specification-intensive end-uses. Three archetypes dominate: Gulf Coast-integrated refiners with NGL fractionation proximity, European solvent specialists with cryogenic distillation expertise, and Asian petrochemical conglomerates with downstream rubber integration. Competitive moves concentrate on capacity expansion in high-purity grades and strategic partnerships with refrigerant formulators seeking regulatory documentation support.
Within the integrated refiner archetype, Chevron Phillips Chemical Company and ExxonMobil Chemical exemplify Gulf Coast-integrated producers leveraging NGL fractionation proximity. Shell Chemicals occupies a position bridging standard and specialty tiers through global logistics reach. Among Chinese petrochemical conglomerates, Junyuan Petroleum Group represents the downstream-integrated model with captive demand from rubber and adhesive derivatives. These anchors illustrate how feedstock access and purification capability define competitive positioning.
| Leading Market Players |
|---|
| Chevron Phillips Chemical Company |
| Aeropres Corporation |
| ExxonMobil Chemical |
| HCS Group |
| South Hampton Resources |
| Shell Chemicals |
| Junyuan Petroleum Group |
| Linde Group |
| Phillips 66 |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed Chinese petrochemical conglomerates and Gulf Coast-integrated refiners anchor supply concentration, translating captive NGL access into pricing discipline across pharmaceutical-grade and commodity blowing agent tiers.
Pricing Analysis
Distributor margins compress at 8-12% for bulk commodity grades while direct-to-OEM channels command 15-20% premiums on pharmaceutical-grade material with CoA documentation. Three-tier pricing structure across pharmaceutical, solvent, and technical grades reflects purification intensity and certification overhead. Pricing pressure stems from Henry Hub volatility feeding into NGL feedstock costs, squeezing fractionator margins during winter demand spikes. Polyurethane foam manufacturers exhibit highest price sensitivity due to formulation cost pressures, while pharmaceutical extractors prioritize purity thresholds over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical formulators and refrigerant OEMs mandate multi-supplier qualification across the United States, Germany, and China. Feedstock draws from natural gas liquids fractionation at Gulf Coast complexes, catalytic isomerization units in Shandong province, and refinery streams at Rotterdam and Singapore hubs. Single-source vulnerability concentrates in cryogenic distillation expertise for sub-10 ppm benzene grades, with qualified contractors limited to HCS Group and select Chinese specialists. Distribution runs through regional tanker networks for bulk petrochemical consumers, complemented by drum and tote fulfillment for mid-volume chemical processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isopentane market represents a late-cycle quality story as EPA SNAP and EU F-Gas Regulation phase-outs redirect formulation demand toward hydrocarbon alternatives with stringent purity documentation.
For Market Incumbents: Lock in long-term offtake agreements with polyurethane foam manufacturers ahead of HCFC phase-out deadlines. Chevron Phillips Chemical Company and ExxonMobil Chemical should expand cryogenic distillation capacity at Cedar Bayou and Beaumont to capture pharmaceutical-grade premiums before Chinese competitors achieve comparable purity thresholds. Backward integration into NGL fractionation secures feedstock cost advantage against refinery-stream dependent rivals. For New Entrants and Emerging Players: E-commerce channels for research-grade isopentane offer the most penetrable entry vector, serving fragmented academic and government laboratory demand with small-lot flexibility. Target Indian contract manufacturers under evolving BIS standards and PLI scheme incentives, where domestic technical service capabilities remain the primary qualification barrier. Specification development partnerships with semiconductor fabs evaluating hydrocarbon cleaning solvents provide a second white-space avenue. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap solvent specialists with cryogenic distillation expertise but limited downstream integration. The five-to-ten year viability window favors acquisition targets possessing both pharmaceutical-grade certification infrastructure and refrigerant formulator relationships. Watch EPA SNAP enforcement intensity and EU F-Gas quota reduction schedules as inflection indicators for hydrocarbon blowing agent demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Cedar Bayou and Shandong corridor additions capture EPA SNAP-driven demand from US polyurethane foam manufacturers. |
| Backward Integration | NGL fractionation proximity at Gulf Coast complexes insulates margin structure from Henry Hub volatility spikes. |
| Green Manufacturing Transition | Metal-organic framework adsorptive separation reduces multi-stage distillation energy intensity for pharmaceutical grades. |
| Long-term Supply Agreement | Refrigerant OEM partnerships with European supermarket chains secure volume ahead of EU F-Gas quota reductions. |
| Joint Venture | Indian technical service joint ventures establish BIS-compliant local capabilities for PLI scheme beneficiaries. |
Study Parameters
Bottom-up blowing agent and solvent demand modeling reconciled against top-down NGL fractionation capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Gulf Coast and Chinese petrochemical complexes, procurement leads at polyurethane foam manufacturers, refrigerant formulator technical directors, and pharmaceutical extraction specialists combined with secondary validation from customs and trade data, ACC and Cefic industry reports, EPA SNAP program filings, and EU F-Gas Regulation implementation documents. The approach triangulates consumption estimates against production capacity and inventory positioning across Rotterdam, Singapore, and Houston distribution hubs.
Historical trendline analysis of isopentane price spreads against n-pentane and natural gasoline benchmarks informed elasticity assumptions across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use application, regional production hub, and customer certification requirement intensity. CAGRs derive from slope analysis of demand drivers including regulatory phase-out schedules, polymer chemistry adoption curves, and refrigerant transition timelines. Forecast inputs incorporate cracker feedslate economics shifting with regional natural gas pricing and pharmaceutical extraction protocol evolution.
The model assumes a particular technology adoption path for metal-organic framework purification; alternative pathways for cryogenic distillation efficiency gains would alter the outlook for capital requirements and new entrant participation. Forecasts reflect assumptions on EPA SNAP enforcement consistency, EU F-Gas quota allocation mechanics, and Chinese MEE volatile organic compound emission threshold stringency. Deviation in regulatory implementation timelines or feedstock cost spread volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Phosphorus and Derivatives Market
Bulk Chemicals
Malathion Market
Bulk Chemicals
Tertiary Butylhydroquinone Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Nitric Acid Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
Global Ethylene Market
Bulk Chemicals
Global Bulk Ferroalloys Market
Bulk Chemicals
India Iodine Market
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
Rubidium Bromide Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Europe Lithium Chloride Market
Bulk Chemicals
Potassium Chloride Market