
 Potassium Schoenite Market | 2026-2036
Potassium Schoenite Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Schoenite Market Insights
ISO 9001 quality management certification is reorganizing supplier hierarchies in the potassium schoenite sector, filtering out sub-scale producers from premium fertilizer supply chains. K+S AG leverages its vertical integration from German potash mines to finished granular products, sustaining captive sulfur sourcing that insulates margin pools. Compass Minerals International Inc. anchors North American distribution through controlled bulk terminal access, while Arab Potash Company competes on Dead Sea brine economics that differentiate its cost position.
Potassium schoenite is a double salt of potassium sulfate and magnesium sulfate with the chemical formula K2SO4·MgSO4·6H2O, typically manufactured through controlled crystallization from brine solutions or synthetic processing of potassium and magnesium sources, and serves primarily as a chloride-free fertilizer providing both potassium and magnesium nutrients without soil salinity risk. Granular formulations dominate volume flows into mechanized broadcasting equipment, while crystalline grades command premium positioning in greenhouse and hydroponic systems where solubility specifications determine nutrient delivery precision. Powder variants occupy a narrowing mid-tier as blending operations consolidate toward either fluid fertilizer integration or direct-application granules.
REACH registration requirements in Europe and India's FSSAI nutrient labeling mandates for packaged fertilizers create divergent compliance burdens that reshape export-oriented production configurations. The EPA's water quality standards for nutrient runoff in the United States further constrain application practices, redirecting formulation innovation toward controlled-release coatings and precision dosing systems. Stakeholders must monitor how evolving carbon border adjustment mechanisms and national fertilizer security strategies recalibrate sourcing priorities across production geographies.
Market Dynamics
Precision agriculture protocols and chloride-free fertilizer mandates are compressing traditional potassium sulfate supply chains while elevating double-salt formulations into premium nutrient tiers. Specialty crop growers now specify solubility grades that filter out commodity producers from qualified supplier pools.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for synthetic fertilizers are redirecting greenhouse operators toward naturally crystallized potassium schoenite with lower carbon intensity certification.
- Hydroponic nutrient delivery systems:Controlled-environment agriculture in the Netherlands and Spain requires crystalline grades with sub-50 micron particle specifications for drip-irrigation compatibility.
- India PLI scheme:Domestic manufacturing incentives for specialty fertilizers are accelerating backward integration into Dead Sea and German brine processing corridors.
Market Restraints
- Sulfur input volatility:Refinery byproduct sulfur prices fluctuate with maritime fuel regulation changes, compressing margin pools for non-integrated crystallizers.
- Dead Sea supply concentration:Israeli and Jordanian evaporation pond operations control 40% of global magnesium sulfate feedstock, creating single-source vulnerability for Asian blenders.
- REACH registration costs:ECHA data requirements for imported fertilizer salts impose six-figure compliance burdens that exclude sub-scale exporters from EU premium tiers.
Strategic Opportunities
- Saudi Arabia specialty crop expansion:Neom and Qiddom greenhouse clusters require chloride-free potassium sources for desert soil remediation, opening import substitution pathways.
- Controlled-release coating convergence:Polymer-schoenite composite granules integrate with precision dosing hardware to command 3x pricing over uncoated crystalline grades.
- Brazil ANVISA organic certification:New input allowances for natural double-salt fertilizers are displacing synthetic potassium chloride in organic soybean and coffee supply chains.
Industry Challenges
- ISO 9001 certification timelines:Eighteen-month audit cycles delay new entrants from accessing European distributor qualified vendor lists.
- Brine chemistry expertise scarcity:Evaporation pond optimization and impurity control require process engineers with Dead Sea or Stassfurt operational experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Schoenite Market |
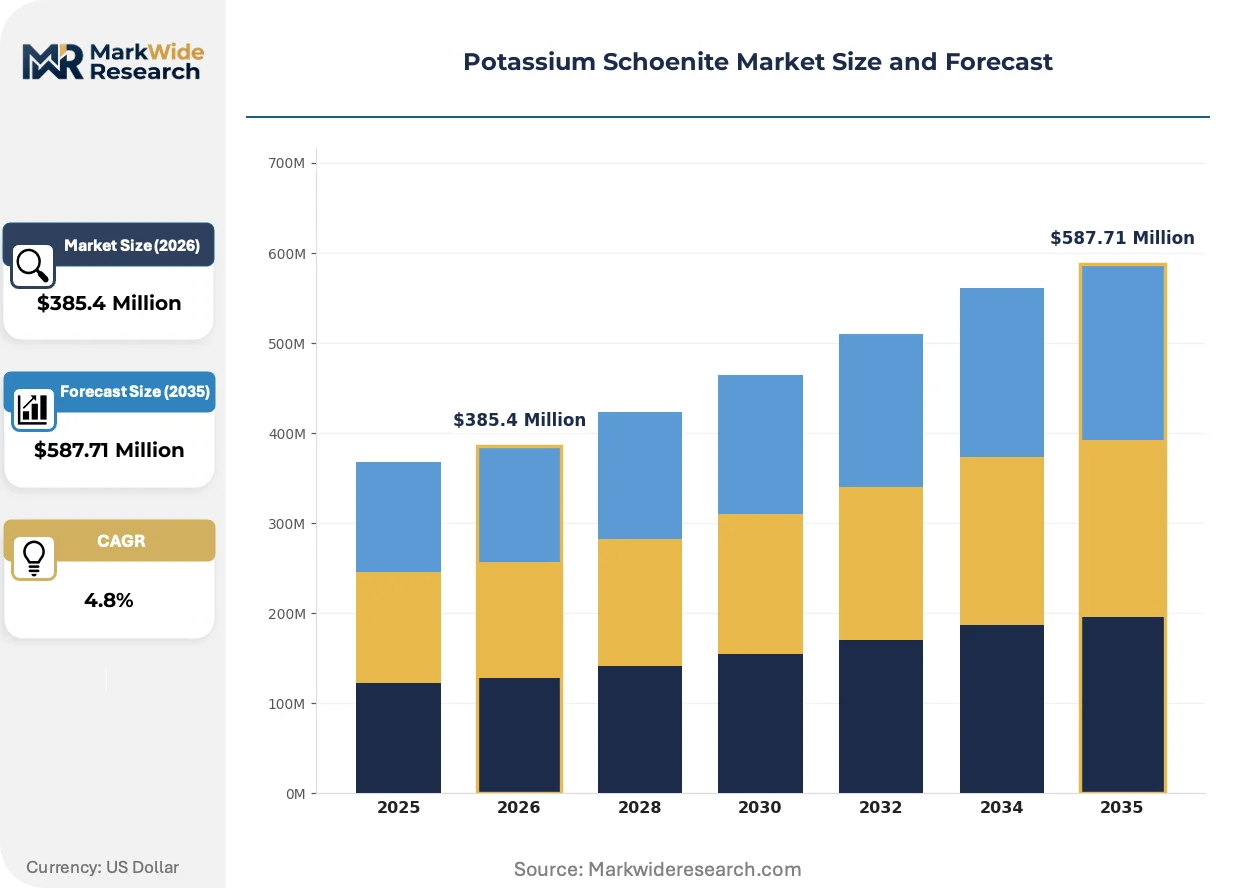
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Crystalline, Liquid Application: Agriculture, Fertilizers, Pharmaceuticals, Chemical Manufacturing End User: Farmers, Manufacturers, Research Institutions, Retailers Packaging Type: Bags, Drums, Bulk, Pouches |
| Companies Covered | K+S AG, Yara International ASA, Compass Minerals International Inc., Arab Potash Company (APC), Eurochem Group AG, Nutrien Ltd., Israel Chemicals Ltd. (ICL Group), JSC Uralkali, Mosaic Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Schoenite Market Trends and Innovations
Formulation science and application hardware are converging to create performance-differentiated potassium schoenite tiers that reward solubility precision over commodity volume. Regulatory carbon accounting and nutrient stewardship mandates are accelerating this bifurcation.
Solubility-engineered crystalline grades are fragmenting the traditional granular-dominated application landscape. Dutch greenhouse operators and Spanish berry cooperatives now specify sub-100 micron crystals for fertigation systems, compressing demand for standard broadcasting granules. This particle-size specialization is enabling premium pricing tiers that commodity sulfate producers cannot access.
REACH registration and EU Green Deal carbon border adjustments are forcing reformulation transparency across fertilizer supply chains. ECHA substance data requirements now extend to upstream brine sourcing, compelling Dead Sea and German producers to document evaporation energy intensity. Containerized crystalline shipments to Rotterdam and Hamburg face new documentation burdens that favor vertically integrated suppliers with captive carbon accounting.
Buyer consolidation among European distributor cooperatives is compressing supplier negotiation leverage while expanding technical service requirements. German and French agricultural purchasing groups now mandate application training and soil testing support as contract conditions, displacing spot-market crystalline transactions. This bundled service model favors producers with regional agronomy teams over pure commodity exporters.
Potassium Schoenite Market Segmentation
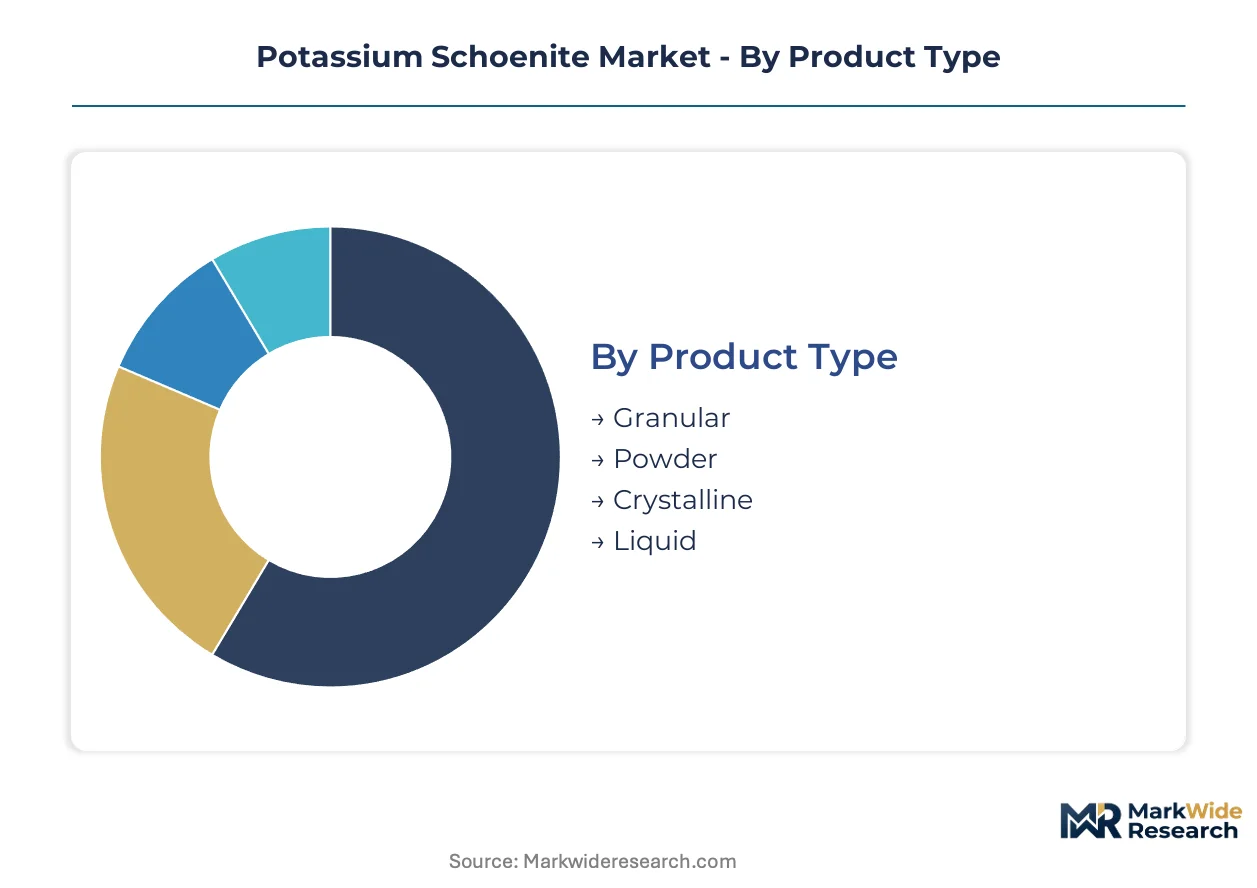
Potassium schoenite segmentation reflects divergent margin capture between commodity bulk fertilizers and precision-grade crystalline inputs. Product form and packaging configuration determine access to premium pricing tiers, while end-user sophistication filters supplier qualification requirements.
Product Type:
Margin pools concentrate in crystalline grades where solubility specifications command triple-digit price premiums over bulk granules.
- Granular:Spherical agglomerates sized 2-4mm for mechanized broadcasting equipment dominate volume flows into broad-acre agriculture. Indian fertilizer cooperatives and Brazilian soybean operations specify this grade for dry-spreader compatibility, though margin compression intensifies as blending operations consolidate.
- Crystalline:Sub-100 micron crystals engineered for drip-irrigation solubility capture premium positioning in Dutch greenhouse clusters and Spanish berry cooperatives. REACH documentation requirements and ECHA carbon intensity disclosures favor vertically integrated producers with captive brine sourcing.
- Powder:Intermediate particle sizes serve fluid fertilizer integration and specialty blending operations, occupying a narrowing mid-tier as demand polarizes toward granules or crystals.
- Liquid:Dissolved formulations for fertigation systems require stabilized solution chemistry, gaining traction in Saudi Arabian desert greenhouse remediation projects.
Granular holds installed capacity. Crystalline is rotating up the share rankings.
Application:
Volume concentrates in agriculture, though pharmaceutical purity grades sustain the steepest margin structures.
- Agriculture:Chloride-free potassium and magnesium delivery for salinity-sensitive soils drives the dominant demand channel, with Indian PLI scheme incentives accelerating domestic manufacturing scale.
- Fertilizers:Compound NPK blending operations in Indonesia and Vietnam specify schoenite as a sulfate carrier, constrained by sulfur input volatility from maritime fuel regulation shifts.
- Pharmaceuticals:USP-grade crystalline material for magnesium replenishment therapies commands 5-10x agricultural pricing, filtered by FDA cGMP facility audits and USP monograph compliance.
- Chemical Manufacturing:Precursor applications in potassium salt synthesis and laboratory reagents occupy a stable niche with long-term supply contracts to institutional purchasers.
Fertilizers anchor volume throughput. Pharmaceuticals is climbing the fastest.
End User:
Procurement sophistication stratifies across farmer cooperatives, industrial manufacturers, and institutional purchasers with divergent technical service demands.
- Farmers:Precision agriculture adopters in California's Central Valley and Almeria's greenhouse belt specify crystalline grades with soil-testing support bundled into supply contracts.
- Manufacturers:Fertilizer blenders and chemical processors negotiate multi-year offtake agreements, prioritizing sulfur cost pass-through mechanisms and ISO 9001 certification status.
- Research Institutions:Agricultural universities and soil science laboratories purchase analytical-grade material for field trial calibration, requiring lot-specific purity documentation.
- Retailers:Agricultural supply cooperatives in Germany and France consolidate purchasing power while mandating application training and agronomy support services.
Manufacturers lock in contracted volumes. Farmers are gaining procurement sophistication fastest.
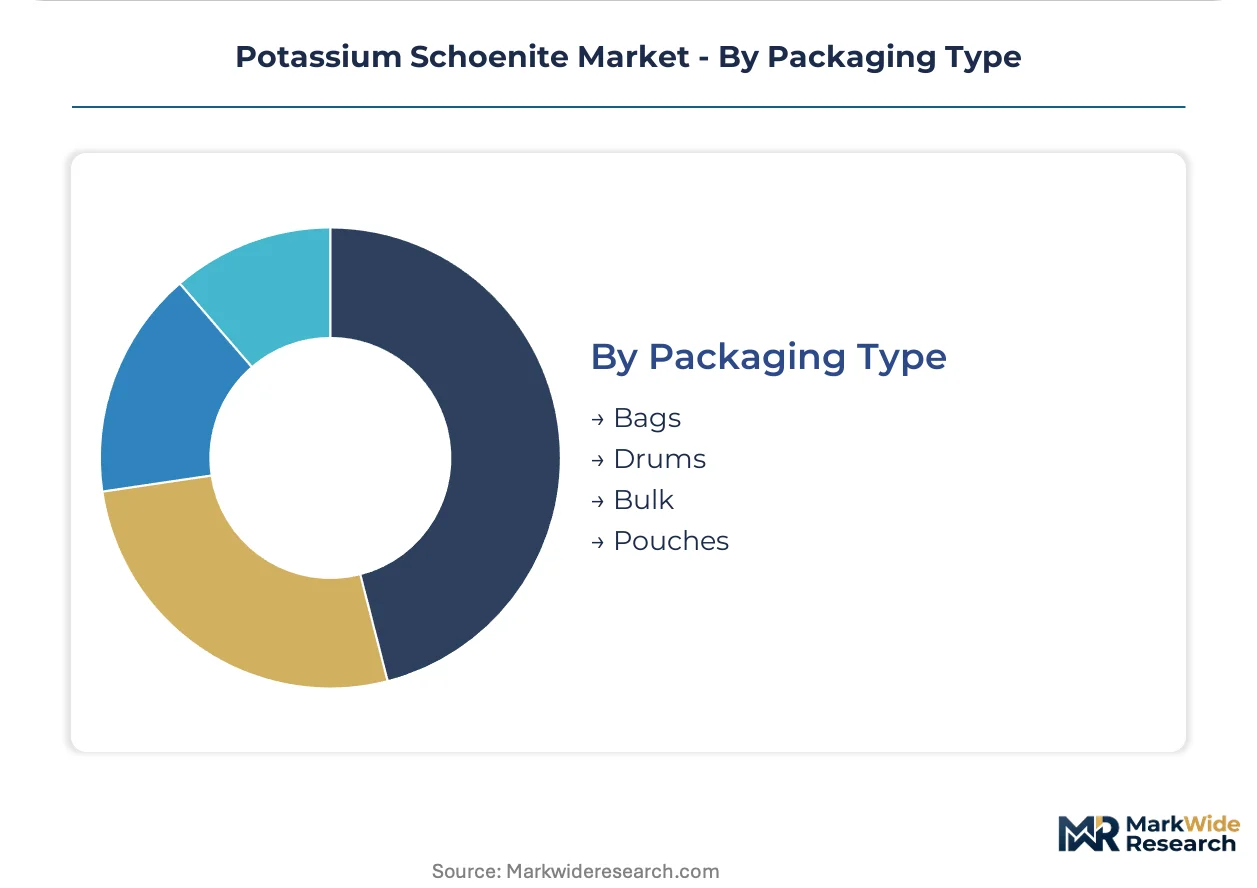
Packaging Type:
Logistics configuration determines market access, with bulk terminal relationships filtering supplier participation in coastal import markets.
- Bulk:Unpackaged granular flows through controlled terminal access at Rotterdam, Hamburg, and Mumbai ports, favoring producers with dedicated storage infrastructure.
- Bags:25-50kg woven polypropylene units serve smallholder distribution networks in India and Southeast Asia, constrained by FSSAI nutrient labeling mandate compliance costs.
- Drums:Fiber or steel containment for crystalline pharmaceutical grades ensures moisture protection through multi-modal transport to FDA-registered facilities.
- Pouches:Retail-scale packaging for garden and specialty crop segments, expanding in European home gardening channels with organic certification labeling.
Bulk commands throughput scale. Pouches are expanding most quickly in premium consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for domestic nutrient manufacturing is redirecting procurement flows toward domestic crystallizers. German brine processors leverage REACH carbon documentation to capture EU greenhouse premiums. Dead Sea evaporation economics continue filtering Asian blender supplier pools.
India
Fertilizer corridor blenders in Gujarat and Maharashtra specify chloride-free potassium sources for salinity-sensitive cash crops. FSSAI nutrient labeling mandates for packaged fertilizers impose documentation burdens that favor organized producers with laboratory infrastructure. The PLI scheme accelerates backward integration into brine processing at Mundra and Hazira port complexes.
Germany
Stassfurt potash mines feed crystallization circuits producing REACH-registered grades for Dutch greenhouse cooperatives. ECHA carbon intensity disclosures favor vertically integrated suppliers with captive sulfur sourcing from domestic refinery networks. K+S AG anchors premium positioning through controlled bulk terminal access at Hamburg.
Israel
Dead Sea evaporation ponds supply magnesium sulfate feedstock commanding 40% of global crystallizer input requirements. Single-source vulnerability concentrates in Israeli and Jordanian pond operations, constraining Asian blender procurement flexibility. ICL Group leverages brine chemistry expertise at Sodom and Ein Bokek production clusters.
Netherlands
Westland greenhouse operators specify sub-50 micron crystalline grades for drip-irrigation compatibility in precision tomato and pepper cultivation. EU F-Gas Regulation phase-down schedules redirect demand toward naturally crystallized potassium schoenite with lower carbon intensity certification. Rotterdam bulk terminal relationships filter supplier participation in coastal import markets.
Brazil
ANVISA organic certification allowances for natural double-salt fertilizers displace synthetic potassium chloride in Mato Grosso soybean and Minas Gerais coffee supply chains. Sulfur input volatility from maritime fuel regulation changes compresses margin pools for non-integrated crystallizers. Santos port infrastructure constraints favor producers with dedicated storage partnerships.
Potassium Schoenite Market Competitive Landscape
Player mix skews toward integrated mining-chemical conglomerates with captive brine access and regional fertilizer distributors with terminal control. Structure concentrates around three strategic archetypes: vertically integrated potash miners crystallizing from captive brine, regional blenders sourcing merchant sulfate feedstock, and specialty chemical houses serving pharmaceutical purity tiers. Dominant competitive moves include backward integration into sulfur sourcing and geographic expansion through controlled-release coating partnerships.
Among German-integrated mining houses, K+S AG exemplifies the captive brine-to-granule archetype with Stassfurt-derived supply chains. Compass Minerals International Inc. anchors North American distribution infrastructure. Arab Potash Company occupies a position reflecting Dead Sea brine economics that differentiate cost positioning for Asian blender procurement.
| Leading Market Players |
|---|
| K+S AG |
| Yara International ASA |
| Compass Minerals International Inc. |
| Arab Potash Company (APC) |
| Eurochem Group AG |
| Nutrien Ltd. |
| Israel Chemicals Ltd. (ICL Group) |
| JSC Uralkali |
| Mosaic Company |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Dead Sea producers and Indian fertilizer blenders lock in sulfur cost pass-through mechanisms while anchoring price visibility across volatile maritime fuel regulation cycles. These arrangements concentrate procurement leverage among vertically integrated suppliers with captive brine access, compressing spot-market participation to sub-scale crystallizers lacking ISO 9001 certification.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade crystalline material and agricultural granules, with REACH-registered Dead Sea output commanding substantial premiums over non-registered alternatives. Three-tier pricing structure separates USP-grade pharmaceutical crystals from greenhouse-certified crystalline grades from bulk broadcasting granules, with sulfur input volatility from IMO maritime fuel standards pressuring mid-tier powder formulations most acutely. Indian fertilizer cooperatives exhibit highest price sensitivity due to PLI scheme domestic manufacturing incentives, while Dutch greenhouse operators prioritize solubility specifications over unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites magnesium sulfate feedstock flows from Israeli and Jordanian evaporation ponds to Asian blending operations, exposing crystallizers to geopolitical logistics disruption. Production concentrates in Israel, Germany, and India, with Dead Sea brine chemistry and Stassfurt potash mines feeding distinct processing corridors. Sulfur refinery byproducts, magnesium chloride brine, and crystallization energy constitute critical input dependencies. Single-source vulnerability runs through Israeli-Jordanian pond concentration. Distribution runs through controlled bulk terminals at Rotterdam, Hamburg, and Mumbai ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brine chemistry expertise scarcity constrains new crystallizer entry, as evaporation pond optimization and impurity control require process engineers with Dead Sea or Stassfurt operational experience that cannot be replicated through textbook training.
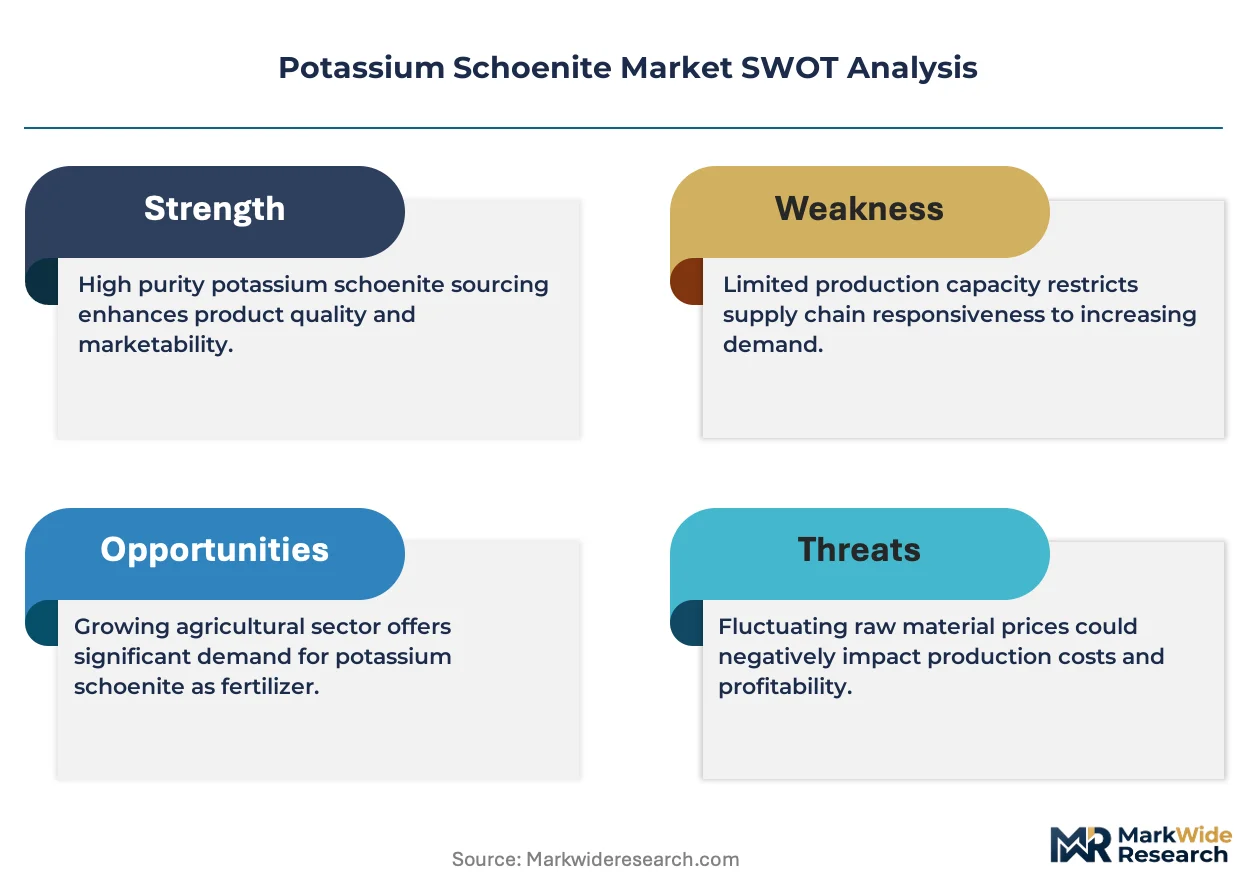
For Market Incumbents: Secure captive sulfur sourcing through refinery partnership agreements to insulate margin pools from IMO maritime fuel regulation volatility. Invest in REACH carbon intensity documentation infrastructure to defend Dutch greenhouse premium positioning against emerging German competitors. Priority lever rests on backward integration into Dead Sea or domestic brine processing corridors. For New Entrants and Emerging Players: Differentiate on sub-50 micron crystalline grades for Saudi Arabian Neom greenhouse clusters, where chloride-free potassium demand for desert soil remediation outpaces qualified supplier availability. Target Brazilian organic soybean supply chains through ANVISA natural fertilizer certification pathways. White-space entry runs through technical agronomy service bundling that incumbent commodity exporters cannot match. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated brine-to-crystal producers with existing ISO 9001 certification and REACH registration infrastructure, as regulatory compliance timelines extend competitive moats beyond capital availability alone. Long-term viability favors assets with captive sulfur sourcing and controlled terminal access. Signal to monitor: Dead Sea evaporation pond yield degradation or Jordanian-Israeli supply corridor disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Sourcing | Captive refinery byproduct access insulates K+S AG and ICL Group from IMO fuel regulation volatility. |
| REACH Carbon Documentation Investment | ECHA-compliant producers capture Dutch greenhouse premium tiers inaccessible to non-registered competitors. |
| Controlled-Release Coating Partnership | Polymer-schoenite composite granules integrate with precision dosing hardware to triple pricing power. |
| Dead Sea Brine Capacity Expansion | APC and ICL Group pond optimization addresses 40% global magnesium sulfate feedstock concentration risk. |
| India PLI Scheme Manufacturing Scale-Up | Domestic crystallizers at Mundra and Hazira secure FSSAI-compliant packaged fertilizer market share. |
Research Methodology
A standing panel of fertilizer blend procurement managers, Dead Sea process engineers, Dutch greenhouse operations directors, and REACH compliance consultants provided ongoing calibration against secondary validation from customs trade data, FSSAI regulatory filings, ECHA substance registrations, and SEC 10-K disclosures from listed potash producers. Primary interviews with Indian fertilizer cooperative purchasing committees and German agricultural supply cooperative category managers combined with bottom-up crystallizer capacity assessments and top-down nutrient demand modeling.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning product form, application purity tier, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to PLI scheme incentive trajectories, EU F-Gas Regulation phase-down schedules, and Dead Sea evaporation pond yield projections. Industry-specific inputs included sulfur refinery byproduct price indices and greenhouse cultivation area expansion in the Netherlands and Saudi Arabia.
Material uncertainties — sulfur price volatility from maritime fuel regulation shifts, Dead Sea supply corridor disruption, and carbon border adjustment mechanism implementation timelines — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and brine chemistry yield continuity that practitioners should keep alternative scenarios live as EU Green Deal enforcement and Indian domestic manufacturing incentive evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Snowflake Salt Market
Industrial Minerals
China Feed Minerals Market
Industrial Minerals
Calcined Anthracite Market
Industrial Minerals
Europe Limestone Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Unexpanded Perlite Market
Industrial Minerals
Global Feed Minerals Market
Industrial Minerals
Talc Market
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Boron Minerals and Chemicals Market
Industrial Minerals
Inorganic Salts Market
Industrial Minerals
Solar Salt Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
Barite Mining Market
Industrial Minerals
Strategic Mineral Materials Market
Industrial Minerals
Global and US Inorganic Salt Market