
 Triisobutyl Phosphate Market | 2026-2036
Triisobutyl Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Triisobutyl Phosphate Market Analytics
Oilfield chemicals is hardening as the dominant demand vertical for triisobutyl phosphate, displacing traditional construction adhesive applications in priority. LANXESS leverages its integrated phosphate ester portfolio to supply specialty extractants for hydrometallurgy. BASF anchors European supply through Ludwigshafen-based batch production optimized for high-purity solvent grades. Zhangjiagang Xinya competes on cost-advantaged continuous processing serving Asian paint and coatings formulators.
Triisobutyl phosphate is a triester of phosphoric acid and isobutanol, typically specified at minimum purity levels and characterized by low water solubility with strong affinity for metal ions, produced through controlled esterification followed by vacuum distillation to remove residual alcohol and acidic byproducts. It functions primarily as a selective liquid extractant in hydrometallurgical separations, a coalescing solvent in paint systems, and a rheology modifier in oilfield drilling fluids. Plasticizers represent the most mature product type with stable but slower expansion, while liquid extractants capture the fastest growth trajectory driven by cobalt and rare earth recovery circuits. Solvent applications for paints and coatings concentrate margin pools in formulated systems rather than commodity supply.
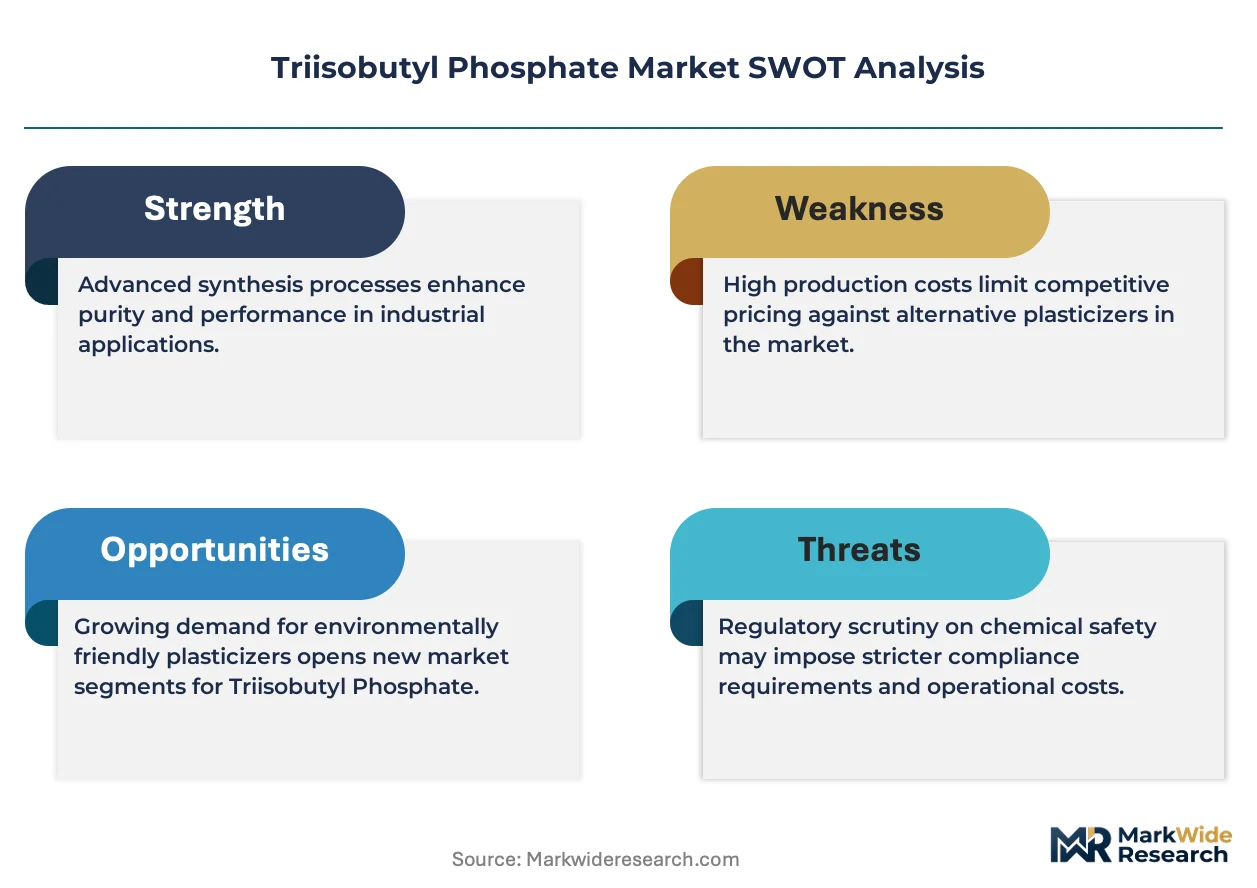
REACH registration requirements in Europe and EPA Toxic Substances Control Act oversight in the United States shape product specifications, testing burdens, and market access conditions for triisobutyl phosphate manufacturers and importers. China's MEE environmental compliance framework is tightening wastewater discharge standards for phosphorus-containing chemical processes, raising capital requirements for domestic producers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation adjustments or dedicated supply chain configurations offer superior returns.
Market Dynamics
REACH compliance in Europe is compressing supplier margins by mandating higher purity specifications for phosphate esters, while simultaneously oilfield drilling intensity in North American shale basins is pulling demand toward specialty solvent grades that command formulation premiums.
Growth Catalysts
- Shale basin drilling intensity:Permian and Bakken operators are expanding horizontal well completions, driving consumption of triisobutyl phosphate as a rheology modifier in synthetic-based drilling fluids.
- REACH registration thresholds:ECHA's tightened substance evaluation protocols are disqualifying low-purity imports, creating protected market space for compliant European producers.
- Hydrometallurgical circuit expansion:Cobalt and rare earth solvent extraction facilities in Central Africa and Southeast Asia are specifying technical-grade phosphate esters for metal separation processes.
Market Restraints
- Isobutanol feedstock volatility:Propylene derivative pricing swings directly compress esterification margins, particularly for batch producers without long-term alcohol supply agreements.
- Supply concentration in East China:Jiangsu and Zhejiang provinces host over 60 percent of global nameplate capacity, exposing buyers to concentrated logistics disruption risk.
- Phosphorus discharge limits:China's MEE wastewater standards are forcing capital-intensive scrubber retrofits on legacy continuous plants, raising breakeven thresholds for marginal producers.
Strategic Opportunities
- Underpenetrated Latin American oilfield services:Brazilian pre-salt development and Argentine Vaca Muerta shale projects lack established local phosphate ester supply chains.
- Battery recycling extractant demand:Spent lithium-ion cell processing facilities in Germany and South Korea are piloting triisobutyl phosphate for cobalt-nickel separation from black mass.
- EU Green Deal industrial chemistry incentives:Horizon Europe funding streams are supporting bio-based alcohol feedstock research for lower-carbon phosphate ester production pathways.
Industry Challenges
- Specialized chemical engineering talent scarcity:Vacuum distillation expertise for high-purity solvent production is concentrated among retiring workforce cohorts in European chemical clusters.
- Multi-jurisdiction certification timelines:Simultaneous EPA TSCA pre-manufacture notifications and REACH dossier updates extend product launch cycles by 18-24 months.
- Legacy batch reactor integration:Ludwigshafen and Antwerp facilities face mechanical constraints retrofitting continuous processing equipment without extended shutdown windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triisobutyl Phosphate Market |
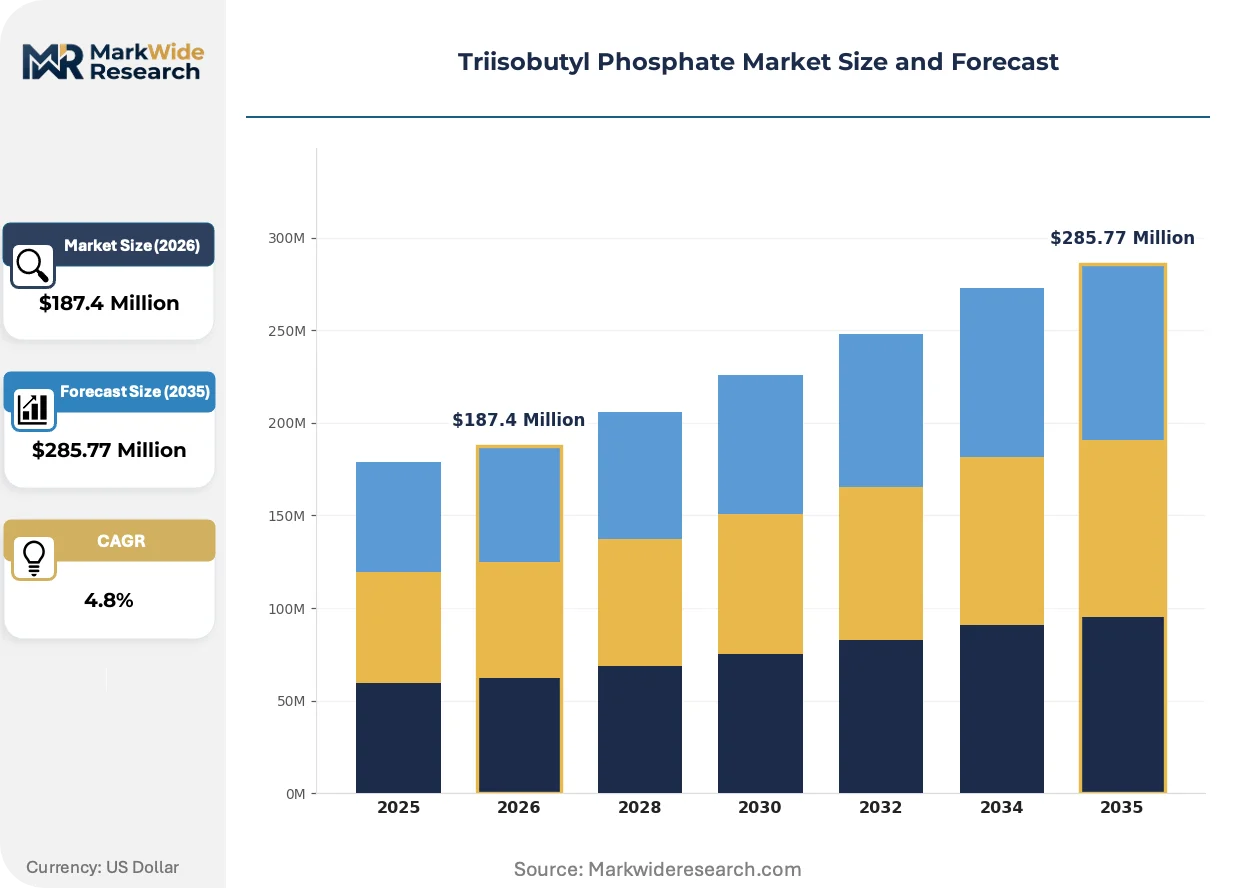
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Solvents, Liquid Extractants, Intermediate Chemicals Application: Adhesives, Paints & Coatings, Oilfield Chemicals, Metalworking Fluids End User: Chemical Manufacturing, Oil & Gas, Construction, Automotive Components Technology: Batch Processing, Continuous Processing, Advanced Separation, Distillation |
| Companies Covered | LANXESS, Clariant, BASF, Evonik Industries, Solvay, Arkema, Dow Chemical Company, Eastman Chemical Company, Zhangjiagang Xinya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triisobutyl Phosphate Market Evolving Landscape
Continuous processing technology is displacing traditional batch esterification in phosphate ester manufacturing, while regulatory chemistry is tightening purity specifications faster than incumbent purification methods can adapt.
Membrane-assisted vacuum distillation is consolidating the competitive position of producers serving hydrometallurgy and electronics-grade solvent markets. BASF and LANXESS have retrofitted Ludwigshafen and Leverkusen facilities with ceramic membrane pre-concentration stages that reduce residual alcohol content below 50 ppm. This purification intensity is compressing the addressable market for commodity-grade suppliers who lack capital access for similar upgrades.
REACH substance evaluation under the 2024-2026 rolling action plan is forcing reformulation of industrial solvent blends containing phosphate esters. ECHA's persistent, bioaccumulative and toxic screening criteria are triggering additional ecotoxicology testing burdens for importers. Specialty chemical distributors in Rotterdam and Hamburg are responding by consolidating supply relationships with dossier-holding manufacturers who can provide extended safety data sheets.
Direct mill supply contracts are displacing merchant distribution for oilfield chemical applications. Major drilling fluid service providers in Texas and Oklahoma are negotiating multi-year offtake agreements with phosphate ester producers, bypassing traditional chemical distribution intermediaries. This channel compression is most visible in the Permian Basin, where integrated service companies seek volume certainty and specification control over rheology modifier supply.
Triisobutyl Phosphate Market Segmentation
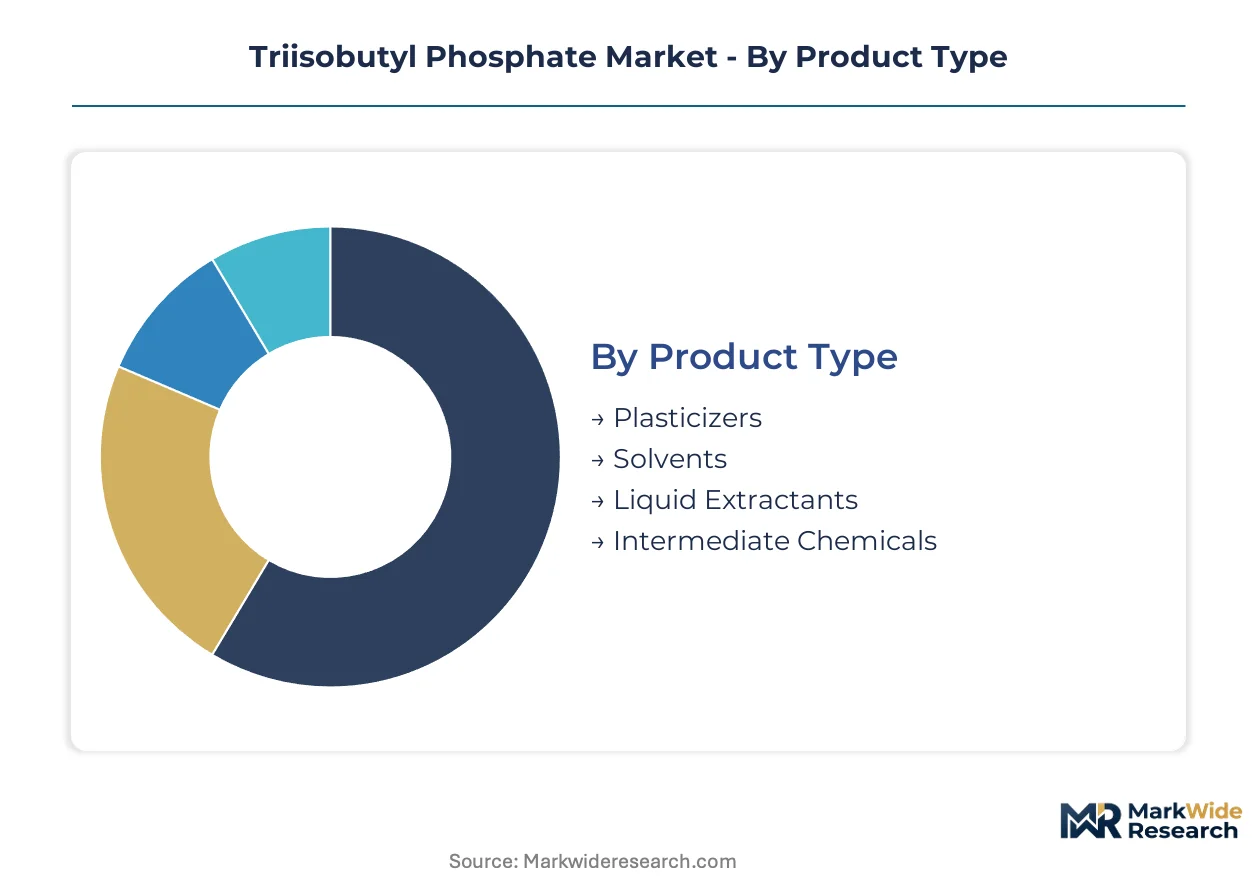
Triisobutyl phosphate exhibits divergent margin profiles across product grades and processing intensities. Capital deployment varies sharply between commodity-scale solvent production and pharmaceutical-grade purification infrastructure. Understanding segment-specific investment thresholds illuminates where incumbent producers hold structural advantages versus where new entrants can challenge established supply positions.
Product Type:
Continuous vacuum distillation systems demand the heaviest upfront capital outlays, while batch esterification units require lower fixed investment but sacrifice unit economics at scale.
- Liquid Extractants:Technical-grade phosphate esters specified for cobalt, rare earth, and nickel separation circuits require residual alcohol content below 100 ppm. Hydrometallurgy facilities in Central Africa and Southeast Asia are scaling solvent extraction train capacity faster than traditional industrial applications.
- Solvents:Paint and coatings formulators specify triisobutyl phosphate as a coalescing aid in waterborne systems. Demand from Asian architectural coatings producers is hardening as VOC regulations tighten formulation requirements across China and South Korea.
- Plasticizers:Mature product category serving stable polymer compounding demand.
- Intermediate Chemicals:Feedstock for downstream phosphate ester synthesis and specialty surfactant manufacturing.
Most installed capacity flows through Solvents. Expansion is steepest in Liquid Extractants.
Application:
Customer procurement patterns split between direct mill contracts for high-volume oilfield buyers and distributor-mediated purchasing for fragmented construction adhesives demand.
- Oilfield Chemicals:Synthetic-based drilling fluid systems deploy triisobutyl phosphate as a rheology modifier to stabilize emulsion characteristics across temperature gradients. Permian and Bakken operators are negotiating multi-year offtake agreements that bypass traditional chemical distribution channels.
- Paints & Coatings:Waterborne architectural and industrial coatings incorporate phosphate esters to improve film formation and substrate wetting. REACH substance evaluation protocols are forcing reformulation of legacy solvent blends across European manufacturing facilities.
- Adhesives:Construction-grade adhesive formulations leverage plasticizer functionality.
- Metalworking Fluids:Extreme-pressure additives and corrosion inhibitors in machining operations.
Volume concentrates in Paints & Coatings. Value capture is climbing fastest in Oilfield Chemicals.
End User:
Asset specificity requirements range from commodity chemical handling infrastructure to explosion-proof processing equipment for hydrocarbon extraction environments.
- Oil & Gas:Drilling fluid service providers in Texas, Oklahoma, and North Dakota specify certified solvent grades with guaranteed supply continuity. Direct supply relationships are displacing merchant distribution as operators seek specification control over rheology modifier inputs.
- Chemical Manufacturing:Hydrometallurgical processors and specialty chemical synthesizers constitute the most technically demanding customer segment. Battery recycling facilities in Germany and South Korea are piloting triisobutyl phosphate for cobalt-nickel separation from spent lithium-ion cell black mass.
- Construction:Adhesive and sealant compounders with price-sensitive procurement.
- Automotive Components:Underhood plastics and interior trim applications.
Revenue tilts toward Oil & Gas. Technical specification intensity peaks in Chemical Manufacturing.
Technology:
Process selection locks in product purity ceilings and determines regulatory compliance capabilities across jurisdictions.
- Advanced Separation:Ceramic membrane pre-concentration stages reduce residual alcohol below 50 ppm, enabling electronics-grade and pharmaceutical-grade supply positions. BASF and LANXESS have retrofitted Ludwigshafen and Leverkusen facilities with this infrastructure to defend premium market tiers.
- Continuous Processing:Cost-advantaged production serving Asian paint and coatings markets with commodity solvent grades. Zhangjiagang Xinya operates continuous lines that sacrifice flexibility for throughput economics.
- Batch Processing:Legacy European infrastructure optimized for multi-product flexibility.
- Distillation:Final purification stage common across all production configurations.
Capital deployment favors Continuous Processing. Technical differentiation accumulates in Advanced Separation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting phosphate ester production toward jurisdictions with lower compliance burdens, even as end-use demand clusters in high-standard markets. Producers weigh REACH certification costs in Europe against wastewater discharge enforcement in China.
United States
Permian Basin drilling activity drives solvent-grade consumption for synthetic-based drilling fluids. EPA TSCA oversight requires pre-manufacture notifications for new chemical introductions, extending product launch timelines. Houston and Midland chemical distribution hubs are consolidating direct mill contracts that bypass traditional merchant channels.
China
Jiangsu and Zhejiang provinces concentrate over sixty percent of global nameplate capacity for commodity solvent production. MEE wastewater discharge standards are forcing capital-intensive scrubber retrofits on legacy continuous plants. Zhangjiagang chemical clusters serve Asian paint and coatings formulators with cost-advantaged processing.
Germany
Ludwigshafen and Leverkusen facilities anchor European supply for high-purity extractant grades. ECHA substance evaluation protocols under the rolling action plan are disqualifying low-purity imports from non-compliant sources. BASF and LANXESS operations defend premium market tiers through ceramic membrane purification infrastructure.
South Korea
Battery recycling facilities in industrial zones near Seoul are piloting phosphate esters for cobalt-nickel separation from spent lithium-ion black mass. MFDS chemical substance registration requirements parallel REACH frameworks for industrial solvent imports. Ulsan petrochemical complexes provide integrated feedstock access for domestic esterification.
Brazil
Pre-salt development and Vaca Muerta shale projects lack established local phosphate ester supply chains, creating import-dependent procurement. ANVISA industrial chemical regulations govern solvent specifications for oilfield applications. Rio de Janeiro and São Paulo distribution networks currently route supply through North American intermediaries.
Triisobutyl Phosphate Market Competitive Landscape
Capacity expansion dominates the current landscape as producers retrofit purification infrastructure to meet tightening purity specifications. The vendor base splits between integrated multinational chemical conglomerates and regional continuous processors. Two strategic archetypes have emerged: integrated phosphate ester portfolio holders leveraging backward control over phosphorus supply, and cost-optimized Asian fabricators maximizing throughput on commodity solvent grades. Competitive moves center on ceramic membrane distillation upgrades and direct mill supply contract capture in oilfield chemicals.
Among European integrated producers, LANXESS, BASF, and Evonik Industries occupy positions anchored by REACH-compliant manufacturing infrastructure. LANXESS represents the specialty extractant archetype with portfolio breadth across hydrometallurgy applications. BASF exemplifies scale-driven solvent production optimized for formulation-grade supply. Evonik Industries sits within the high-purity chemical segment serving technically demanding customer specifications. Zhangjiagang Xinya anchors the cost-competitive Asian fabrication tier.
| Leading Market Players |
|---|
| LANXESS |
| Clariant |
| BASF |
| Evonik Industries |
| Solvay |
| Arkema |
| Dow Chemical Company |
| Eastman Chemical Company |
| Zhangjiagang Xinya |
| Others |
Value Network & Pricing Analysis
China's MEE wastewater discharge mandates gate qualified supply and premium-tier pricing access, forcing capital-intensive scrubber retrofits that bifurcate the market between compliant high-purity producers and cost-optimized commodity suppliers. Buyers face escalating procurement complexity as regulatory divergence between REACH-certified European supply and Asian continuous processing creates divergent qualification pathways.
Pricing Analysis
Distributor margins compress as direct mill contracts displace merchant channels in oilfield chemicals. Three-tier pricing structure across premium, standard, and economy levels separates ceramic membrane-purified extractants from commodity solvent grades and unrefined intermediates. Pricing pressure stems from isobutanol feedstock volatility linked to propylene derivative swings. Small-batch construction adhesive compounders exhibit highest price sensitivity; hydrometallurgy processors demonstrate lowest sensitivity due to specification-locked procurement.
Supply Chain Analysis
Refurbishment flows remain negligible given phosphate ester stability and single-use application profiles in drilling fluids and metal extraction. Supply concentrates in China, Germany, and the United States, with Jiangsu and Zhejiang provinces hosting dominant continuous processing capacity. Production draws from isobutanol, phosphoric acid, and specialized catalyst inputs. Single-source vulnerability concentrates in East China logistics corridors. Distribution runs through Rotterdam and Houston chemical hubs for formulated systems, with direct rail and barge links serving Permian Basin operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in high-purity extractant tiers where REACH compliance and ceramic membrane infrastructure create defendable pricing power against commodity substitution.
For Market Incumbents: Anchor premium positioning through ceramic membrane distillation retrofits at Ludwigshafen and Leverkusen facilities before low-purity imports regain dossier compliance. Defend against Zhangjiagang Xinya's cost-advantaged continuous processing by locking multi-year offtake agreements with Permian drilling fluid service providers. Prioritize backward integration into phosphorus supply to buffer against phosphate rock price volatility. For New Entrants and Emerging Players: Brazilian pre-salt drilling contractors represent an underserved buyer archetype lacking established local phosphate ester supply chains. Argentine Vaca Muerta shale developers and Central African hydrometallurgy facilities offer parallel white-space entry points. Pursue toll manufacturing arrangements with underutilized European batch reactors to bypass capital-intensive greenfield construction. For Investors and Strategic Acquirers: Roll-up economics work for regional solvent distributors because direct mill contracting trends compress merchant channel viability and create distressed acquisition targets. Five-to-ten year viability hinges on purification technology access rather than commodity scale. Monitor ECHA substance evaluation rulings under the rolling action plan for disqualification triggers that would reshape import-competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Membrane Retrofit | BASF and LANXESS deployments at Ludwigshafen defend premium extractant tiers against commodity erosion. |
| Direct Mill Supply Agreement | Permian Basin operators bypass Rotterdam and Houston distribution hubs for specification-controlled rheology modifier access. |
| Backward Integration | Captive phosphorus supply buffers European producers against phosphate rock volatility and import dependency. |
| Battery Recycling Partnership | German and South Korean black mass processors pilot cobalt-nickel separation using technical-grade phosphate esters. |
| Latin American Distribution Buildout | Rio de Janeiro and São Paulo networks reduce import lag for Brazilian pre-salt and Argentine shale development. |
Research Methodology
Coverage spans the United States, China, Germany, South Korea, and Brazil, with primary inputs from each market cluster combined with secondary validation. Plant managers at Jiangsu and Zhejiang continuous processing facilities, procurement leads at Permian drilling fluid service providers, distribution channel partners in Rotterdam and Houston, and technical R&D directors at Leverkusen and Ludwigshafen sites contributed field intelligence. Secondary sources include customs and trade data, ECHA substance evaluation dossiers, SEC 10-K filings from listed chemical conglomerates, and MEE wastewater discharge compliance records. Bottom-up capacity and consumption modeling triangulates against top-down macroeconomic drivers.
Granularity-level modeling distinguishes liquid extractant, solvent, plasticizer, and intermediate chemical grades across oilfield chemicals, paints and coatings, adhesives, and metalworking fluid applications. Technology segmentation captures batch processing, continuous processing, advanced membrane separation, and conventional distillation configurations. CAGRs derive from segment-specific volume trajectories and value-per-unit trends across the projection horizon. Forecast inputs incorporate shale drilling intensity indices, hydrometallurgy capacity expansion pipelines, and REACH registration timeline assumptions.
Underlying measurement precision varies by segment; liquid extractants and oilfield chemicals carry tighter precision than construction adhesives given concentrated buyer visibility. Forecasts reflect documented assumptions regarding regulatory enforcement intensity, feedstock price correlation stability, and technology adoption curves. Practitioners should monitor ECHA rolling action plan substance evaluations, MEE wastewater standard implementation timelines, and Permian Basin drilling permit trajectories for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Chemical Synthesizer Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Global Chemical Intermediates Market
Chemical Intermediates
Acid Chlorides Market
Chemical Intermediates
Global Electrophoresis Reagents Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
Metal Alkyls Market
Chemical Intermediates
Dye Intermediates Market
Chemical Intermediates
Grignard Reagents Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Montelukast Intermediate Market